
 Asia Pacific Acrylic Teeth Market | 2026-2036
Asia Pacific Acrylic Teeth Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Acrylic Teeth Market Analysis
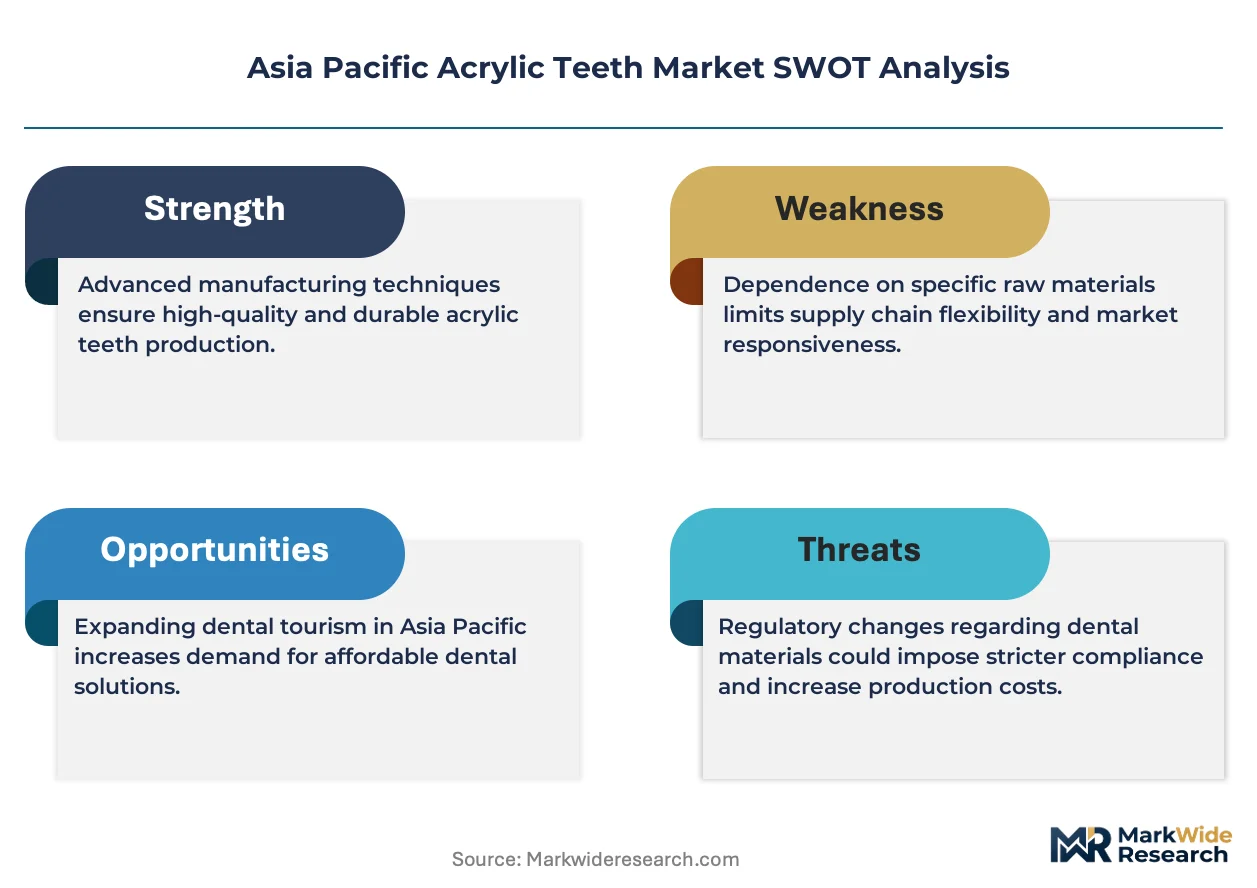
Subscription-based digital shade-matching software is decoupling color calibration from physical tooth libraries, altering how dental laboratories procure acrylic teeth. Ivoclar Vivadent AG leverages its proprietary digital workflow platforms to sustain premium positioning across Japanese and Australian dental clinics. Shanghai Pigeon Dental Mfg Co Ltd anchors cost-competitive complete denture supply through direct distribution into Southeast Asian dental laboratories. GC Corporation differentiates via biocompatible acrylic formulations that navigate Japan's stringent material safety protocols.
Asia Pacific acrylic teeth are polymethyl methacrylate-based prosthetic devices manufactured through heat-cured or cold-cured polymerization processes, with flexural strength typically ranging from 65 to 95 MPa, designed to replicate natural dentition in removable and fixed prosthodontic applications. Complete dentures command the largest product type share due to aging demographics across Japan and South Korea, while customized teeth represent the fastest-growing segment as intraoral scanning penetration rises in Chinese urban dental clinics. Heat-cured acrylic dominates material demand for its superior dimensional stability, though biocompatible acrylic captures expanding margin pools in premium Australian and Japanese restorative dentistry channels.
Japan's PMDA enforces biocompatibility testing under ISO 10993 frameworks, compelling manufacturers to validate cytotoxicity and sensitization profiles before market entry. Australia's TGA and China's NMPA maintain divergent acrylic resin purity standards, fragmenting compliance costs for regional suppliers seeking cross-border sales. India's CDSCO dental device classification rules create additional registration hurdles for imported temporary teeth. Stakeholders must monitor harmonization efforts between ASEAN medical device directives and national pharmacopoeia updates to anticipate shifts in market access requirements.
Market Dynamics
Digital CAD/CAM workflows are compressing conventional molding cycles across Asia Pacific dental laboratories, forcing acrylic teeth suppliers to recalibrate production formats and distribution logistics around intraoral scanning penetration.
Growth Catalysts
- Japan's PMDA biocompatibility frameworks:Manufacturers validating cytotoxicity profiles under ISO 10993 gain preferential access to premium restorative dentistry channels, creating compliance-based market segmentation.
- Guangdong manufacturing clusters:Domestic heat-cured acrylic producers achieve scale economies that lower unit costs for complete denture exports into Southeast Asian dental laboratories.
- Intraoral scanning adoption:Chinese urban clinics deploying chairside digital impression systems generate demand for customized tooth geometries that conventional mold libraries cannot fulfill.
Market Restraints
- Methyl methacrylate price volatility:Petrochemical feedstock fluctuations compress margins for cold-cured acrylic producers serving price-sensitive Indian dental laboratories.
- Supply concentration in Zhejiang:Three domestic manufacturers control majority heat-cured output, creating vulnerability to regional logistics disruptions or environmental compliance shutdowns.
- Dimensional stability limitations:Cold-cured acrylic exhibits higher water sorption rates that disqualify it from Australia's TGA material safety certifications for long-term prosthodontic use.
Strategic Opportunities
- Vietnam dental laboratory expansion:Underpenetrated prosthodontic service capacity creates first-mover advantage for direct distribution networks bypassing traditional importer channels.
- ASEAN medical device directive harmonization:Converging regulatory standards between Thailand, Indonesia, and Malaysia reduce redundant certification costs for regional suppliers.
- Biocompatible acrylic-nanoceramic convergence:Hybrid formulations combining PMMA matrices with zirconia nanoparticles address flexural strength gaps in premium Japanese restorative applications.
Industry Challenges
- CAD/CAM technician scarcity:Dental laboratories across India and Southeast Asia face acute shortages of operators capable of calibrating digital shade-matching software to physical tooth outputs.
- Legacy mold inventory stranding:Laboratories holding extensive conventional tooth libraries face write-down pressure as subscription-based digital libraries decouple color calibration from physical stock.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Acrylic Teeth Market |
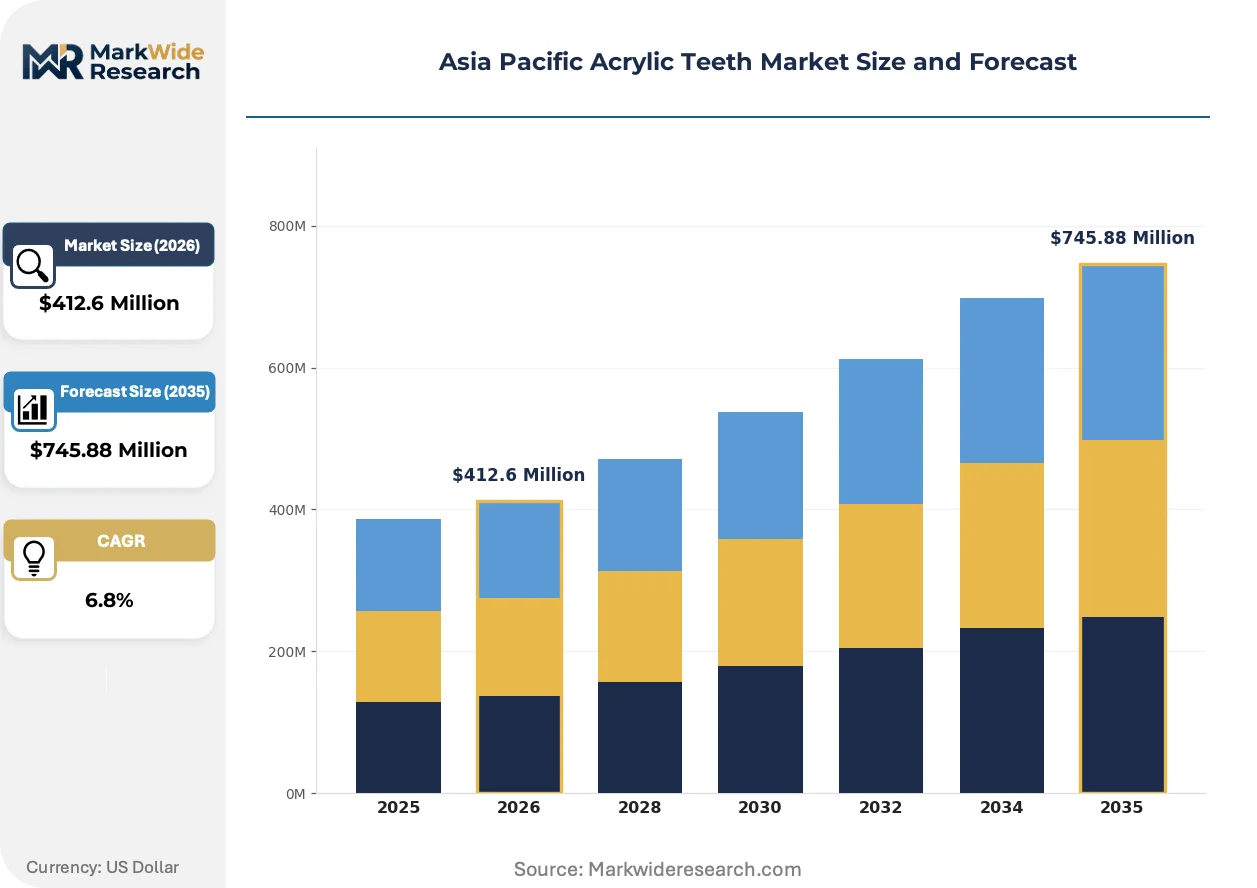
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Partial Dentures, Complete Dentures, Customized Teeth, Temporary Teeth End User: Dental Clinics, Hospitals, Laboratories, Dental Supply Companies Application: Cosmetic Dentistry, Restorative Dentistry, Prosthodontics, Orthodontics Material: Heat-Cured Acrylic, Cold-Cured Acrylic, High-Impact Acrylic, Biocompatible Acrylic |
| Companies Covered | Dentsply Sirona Inc, Ivoclar Vivadent AG, Kulzer GmbH, VITA Zahnfabrik, SHOFU Inc., Shanghai Pigeon Dental Mfg Co Ltd, Yamahachi Dental MFG Co, Shandong Huge Dental Material Corporation, GC Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Acrylic Teeth Market Emerging Trajectories
Acrylic teeth production is bifurcating between commodity heat-cured output for complete dentures and precision-manufactured biocompatible grades for premium restorative work, with digital workflows determining which path laboratories pursue.
Cloud-based shade-matching platforms are unifying color libraries across dispersed dental laboratory networks, eliminating physical tooth sample shipping between facilities. Japanese and Australian laboratories with multi-site operations adopt these systems fastest, compressing turnaround times for cross-border denture cases from weeks to days. The technology is unifying quality control standards that previously varied significantly between metropolitan and regional laboratory locations.
China's NMPA tightened acrylic resin purity standards for dental device registrations, requiring heavy metal content documentation that cold-cured formulations struggle to satisfy. Domestic manufacturers in Guangdong and Zhejiang are reconfiguring polymerization protocols to meet these specifications ahead of anticipated enforcement waves. Heat-cured acrylic lines with validated supply chain documentation capture expanding share in premium Chinese urban clinic channels.
Direct procurement from manufacturer digital portals is displacing distributor-mediated ordering for standardized complete denture teeth. Southeast Asian dental laboratories with predictable volume requirements negotiate subscription pricing that locks material costs across quarterly planning cycles. Vietnam and Indonesia show the fastest channel migration, where laboratory consolidation creates buyer concentration sufficient to bypass traditional dental supply intermediaries.
Asia Pacific Acrylic Teeth Market Segmentation
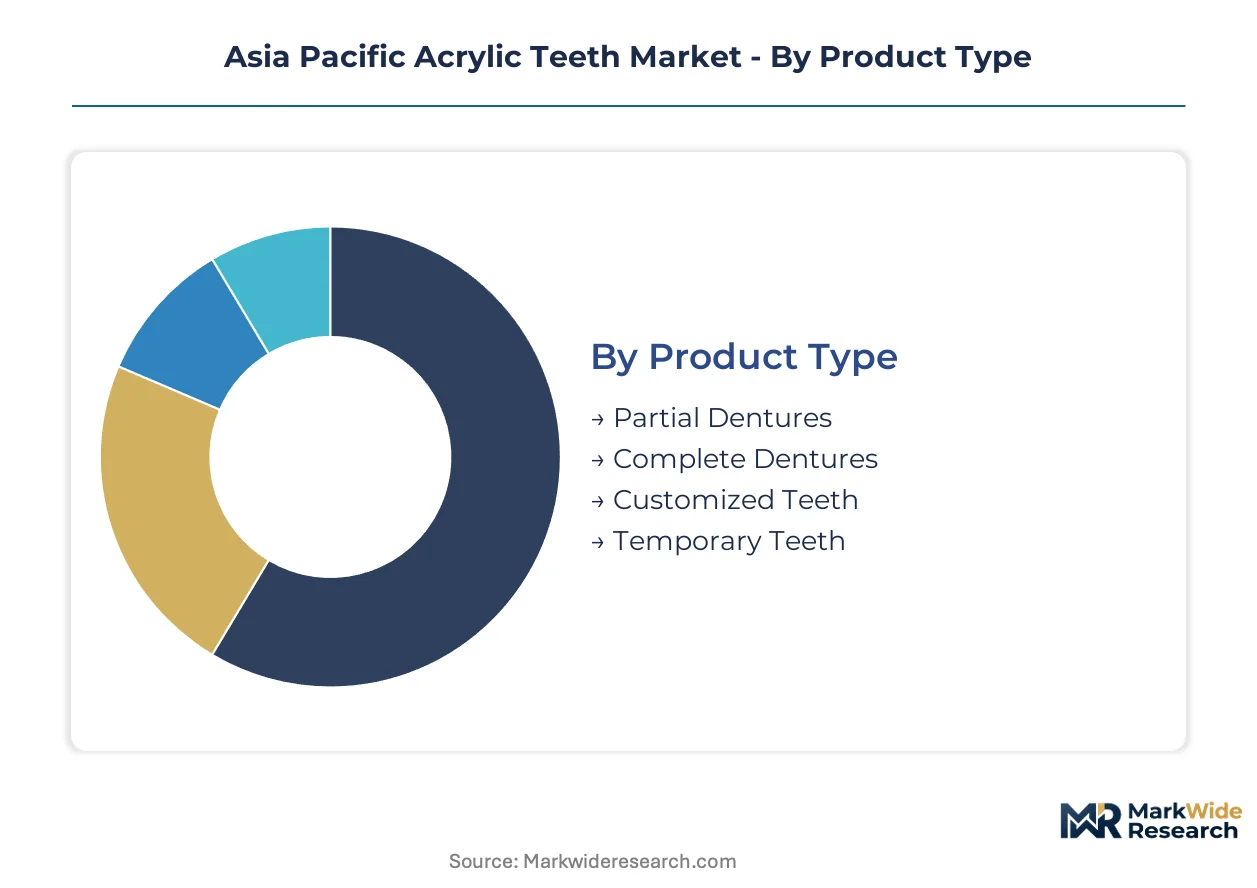
Acrylic teeth manufacturers must align production configurations with divergent technical requirements across prosthodontic applications. Capital deployment decisions hinge on whether facilities serve high-volume complete denture fabrication or precision-driven restorative workflows.
Product Type:
Heat-cured polymerization lines demand the heaviest upfront investment, with autoclave systems and climate-controlled curing chambers dominating capital allocation for manufacturers serving complete denture demand.
- Complete Dentures:Full-arch prosthetic sets fabricated from polymethyl methacrylate matrices requiring 72-hour heat-cured cycles for dimensional stability. Demand concentrates in China's Guangdong manufacturing clusters, where domestic producers scale output for Southeast Asian dental laboratory exports.
- Customized Teeth:CAD/CAM-milled or 3D-printed geometries matched to intraoral scan data, bypassing conventional mold libraries entirely. Chinese urban clinics deploying chairside digital impression systems generate specifications that conventional molding cannot fulfill.
- Partial Dentures:Segment-specific tooth sets designed for removable frameworks with metal or acrylic saddles.
- Temporary Teeth:Short-term prosthetic solutions pending permanent restoration, subject to India's CDSCO device classification rules.
Most installed capacity flows through Complete Dentures. Expansion is steepest in Customized Teeth.
End User:
Laboratory procurement volumes determine margin structure, with direct manufacturer relationships replacing distributor intermediaries where consolidation creates sufficient buyer concentration.
- Dental Laboratories:Primary fabrication sites for removable prosthetics, with Vietnam and Indonesia showing fastest channel migration toward direct digital procurement portals.
- Dental Clinics:Chairside providers generating demand for immediate-load temporary solutions and shade-matched restorations.
- Hospitals:Institutional purchasers with centralized procurement protocols for maxillofacial reconstruction cases.
- Dental Supply Companies:Traditional intermediaries facing displacement where laboratory consolidation enables subscription-based manufacturer relationships.
Laboratories absorb the majority of heat-cured acrylic volume. Clinic direct procurement is climbing the fastest.
Application:
Prosthodontic applications command premium pricing tiers where biocompatibility certifications differentiate supplier positioning in Japanese and Australian channels.
- Prosthodontics:Full and partial removable restoration, with Japan's PMDA biocompatibility frameworks compelling ISO 10993 validation for premium channel access.
- Restorative Dentistry:Permanent and semi-permanent tooth replacement, where Australia's TGA material safety rules disqualify cold-cured formulations for long-term use.
- Cosmetic Dentistry:Aesthetic-focused procedures requiring precise shade matching and translucency calibration.
- Orthodontics:Temporary tooth replacement during active orthodontic treatment phases.
Prosthodontics retains the deepest supplier relationships. Restorative Dentistry is gaining share fastest on digital workflow penetration.
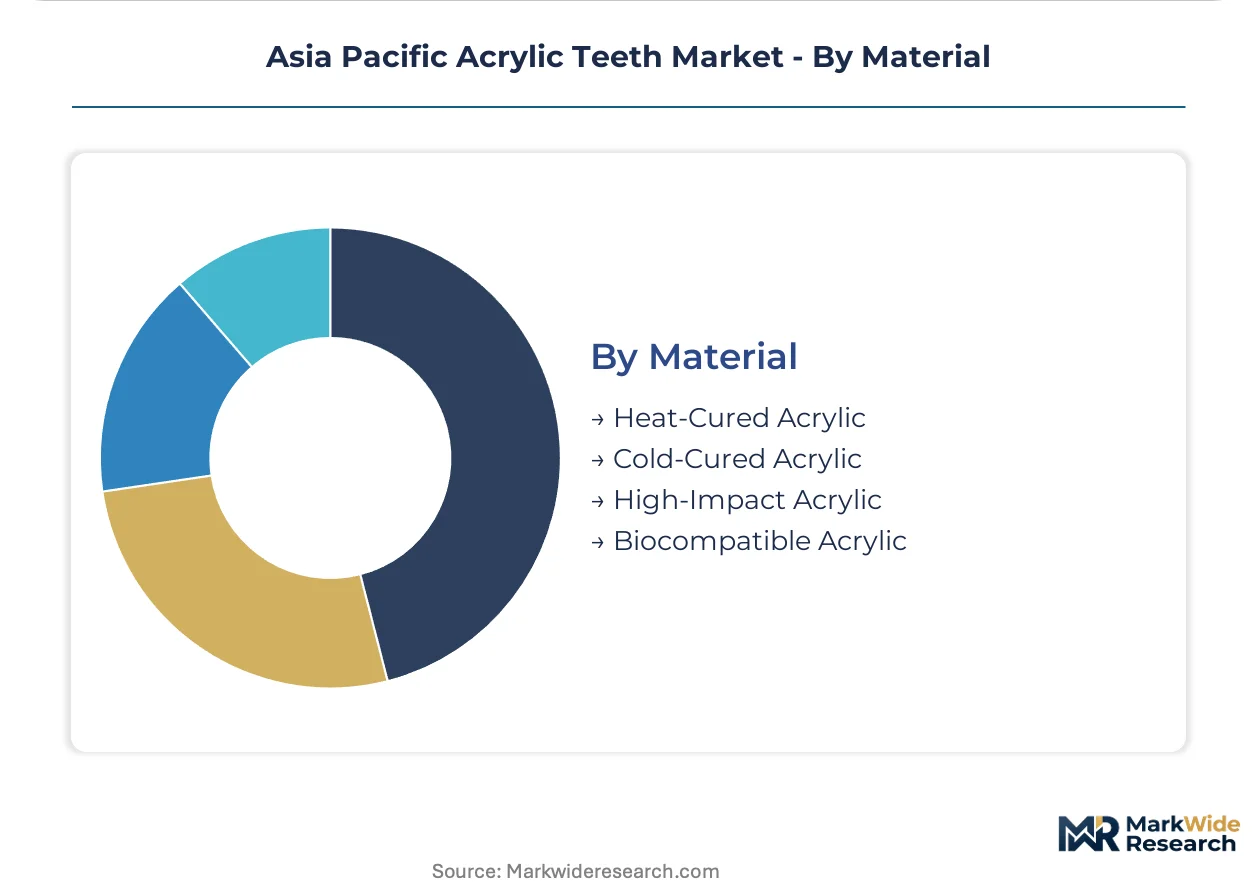
Material:
Polymerization protocol selection locks manufacturers into distinct cost structures, with heat-cured lines requiring validated supply chain documentation that cold-cured alternatives cannot readily obtain.
- Heat-Cured Acrylic:Autoclave-processed PMMA achieving 90-95 MPa flexural strength with minimal water sorption. Zhejiang manufacturing clusters concentrate majority regional output, creating vulnerability to environmental compliance shutdowns.
- Biocompatible Acrylic:Formulations engineered for cytotoxicity and sensitization compliance under Japan's PMDA and Australia's TGA protocols. GC Corporation and Ivoclar Vivadent AG dominate premium positioning through validated biocompatibility profiles.
- Cold-Cured Acrylic:Room-temperature polymerized resins with faster processing cycles but elevated water sorption rates.
- High-Impact Acrylic:Rubber-modified PMMA matrices engineered for fracture resistance in high-stress posterior applications.
Heat-Cured Acrylic carries the broadest installed base. Biocompatible Acrylic shows the steepest expansion trajectory on regulatory premium capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands the largest installed base of heat-cured acrylic production lines, while Japan's PMDA certification requirements filter premium channel access for biocompatible formulations. Australia's TGA material safety protocols and India's CDSCO device classification rules create divergent compliance pathways that reshape supplier positioning across the region.
China
Guangdong and Zhejiang manufacturing clusters concentrate domestic heat-cured acrylic capacity for complete denture exports. The NMPA tightened resin purity standards requiring heavy metal content documentation ahead of enforcement waves. Zhejiang-based producers are reconfiguring polymerization protocols to satisfy these specifications and capture premium urban clinic channels.
Japan
Aging demographics sustain demand for full-arch prosthetic sets across metropolitan dental laboratories. The PMDA enforces ISO 10993 biocompatibility testing frameworks compelling cytotoxicity and sensitization validation. Kanto and Kansai laboratory networks adopt cloud-based shade-matching platforms fastest, compressing cross-border denture case turnaround times.
India
Price-sensitive dental laboratories in Mumbai and Delhi-NCR drive cold-cured acrylic consumption despite feedstock volatility. The CDSCO dental device classification rules create registration hurdles for imported temporary teeth. Domestic manufacturers in Gujarat and Maharashtra scale direct distribution to bypass traditional supply intermediaries.
Australia
Multi-site laboratory operations in Sydney and Melbourne deploy subscription-based digital portals for standardized tooth procurement. The TGA material safety certifications disqualify cold-cured formulations for long-term prosthodontic use. Queensland and Victoria clinics generate demand for biocompatible grades that navigate these stringent protocols.
Vietnam
Underpenetrated prosthodontic service capacity in Ho Chi Minh City and Hanoi creates first-mover advantage for direct manufacturer relationships. The country's national pharmaceutical regulator maintains device registration requirements aligned with ASEAN harmonization efforts. Dental laboratories in the Mekong Delta region show fastest channel migration toward subscription pricing models.
Asia Pacific Acrylic Teeth Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium restorative channels consolidating around validated biocompatibility profiles while commodity complete denture supply fragments among domestic fabricators. Three domestic manufacturers control majority heat-cured output in Zhejiang, creating vulnerability to regional logistics disruptions. Strategic archetypes include PMDA-certified premium specialists, Guangdong-based scale producers, and digital workflow platform operators. Competitive moves center on direct procurement portal deployment and biocompatible formulation R&D partnerships.
Among Swiss and Liechtenstein-based specialists, Ivoclar Vivadent AG occupies a position exemplifying premium-tier digital workflow integration. Japanese fabricators SHOFU Inc. and Yamahachi Dental MFG Co represent the PMDA-compliant archetype serving domestic restorative channels. Shanghai Pigeon Dental Mfg Co Ltd anchors the cost-competitive complete denture segment through direct distribution into Southeast Asian laboratories. GC Corporation sits within the biocompatible formulation tier navigating Japan's material safety protocols.
| Leading Market Players |
|---|
| Dentsply Sirona Inc |
| Ivoclar Vivadent AG |
| Kulzer GmbH |
| VITA Zahnfabrik |
| SHOFU Inc. |
| Shanghai Pigeon Dental Mfg Co Ltd |
| Yamahachi Dental MFG Co |
| Shandong Huge Dental Material Corporation |
| GC Corporation |
| Others |
Supply Flow & Price Mechanics
Digital CAD/CAM workflow adoption across Guangdong and Zhejiang manufacturing clusters compresses conventional molding economics while concentrating production capacity among heat-cured acrylic specialists with validated supply chain documentation. This technology transition simultaneously elevates biocompatible formulation premiums in Japanese and Australian channels and erodes cold-cured margins serving price-sensitive Indian dental laboratories.
Pricing Analysis
Capacity additions in Guangdong manufacturing clusters are reshaping price floors for complete denture exports into Southeast Asian dental laboratories. Three-tier pricing structure across premium, standard, and economy levels separates PMDA-certified biocompatible grades from heat-cured commodity output and cold-cured temporary solutions. Price differentiation rests on certification level under Japan's ISO 10993 frameworks and volume scale in direct procurement portals. Cost compression in cold-cured tiers is intensifying because methyl methacrylate feedstock volatility squeezes producers serving Mumbai and Delhi-NCR price-sensitive buyers.
Supply Chain Analysis
Skilled polymerization technicians in Zhejiang and Guangdong provinces anchor regional heat-cured acrylic output capacity. Geographic supply concentrates in China, India, and Vietnam for PMMA resin processing and complete denture fabrication. Raw material dependencies draw from petrochemical feedstocks, zirconia nanoparticles for hybrid formulations, and colorant libraries for shade-matching systems. Single-source vulnerability runs through three domestic manufacturers controlling majority Zhejiang heat-cured output. Distribution runs through direct manufacturer portals displacing traditional dental supply intermediaries in Vietnam and Indonesia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in biocompatible acrylic tiers where regulatory certification creates defendable premium positioning, while cost-down potential emerges from direct digital procurement bypassing distributor layers.
For Market Incumbents: Anchor PMDA-certified production lines with validated ISO 10993 cytotoxicity documentation to defend against emerging biocompatible specialists from South Korea. Deepen backward integration into PMMA resin supply through captive Guangdong polymerization capacity. Prioritize cloud-based shade-matching platform deployment to lock multi-site laboratory networks before subscription-based competitors consolidate channel control. For New Entrants and Emerging Players: Dental laboratory consolidation in Vietnam's Mekong Delta region offers lowest customer acquisition costs for direct portal relationships bypassing traditional importer markups. Target underpenetrated prosthodontic service capacity in Ho Chi Minh City and Hanoi with subscription pricing models that lock material costs across quarterly planning cycles. Lead with biocompatible-nanoceramic hybrid formulations addressing flexural strength gaps in premium Japanese restorative applications. For Investors and Strategic Acquirers: Valuations sit cheapest among cold-cured acrylic producers facing margin compression from feedstock volatility and regulatory exclusion from long-term prosthodontic channels. Long-term viability favors acquisition targets with PMDA-validated biocompatibility profiles and direct digital procurement infrastructure. Watch ASEAN medical device directive harmonization progress as the inflection signal for reduced cross-border certification costs enabling regional scale.| Strategic Initiative | Industry Significance |
|---|---|
| Biocompatibility Certification Investment | PMDA ISO 10993 validation unlocks premium Japanese and Australian restorative dentistry channels. |
| Direct Digital Procurement Portal Deployment | Subscription-based manufacturer relationships bypass distributor intermediaries in Vietnam and Indonesia. |
| Heat-Cured Capacity Expansion | Guangdong and Zhejiang autoclave lines capture NMPA-compliant resin purity documentation requirements. |
| Hybrid Formulation R&D Partnership | PMMA-zirconia nanoparticle convergence addresses flexural strength demands in Japanese premium applications. |
| Cloud-Based Shade-Matching Platform Integration | Multi-site laboratory networks in Kanto and Kansai compress cross-border denture case turnaround times. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with dental laboratory procurement managers, polymerization technicians, regulatory affairs specialists at NMPA and PMDA, and GPO contracts managers with secondary validation against customs records, hospital procurement databases, SEC filings from listed dental material suppliers, and ASEAN medical device directive harmonization documentation. Bottom-up segment sizing and top-down macro constraint triangulation anchored volume and value estimates.
Segment-weighting approaches distributed value across product type, material grade tier, end-user channel, and application intensity dimensions throughout the forecast period. CAGRs derived from fitted growth curves applied to base-year validated segments, with cross-referencing to intraoral scanning penetration rates, aging demographic trajectories in Japan and South Korea, and regulatory enforcement wave timing for NMPA resin purity standards.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to methyl methacrylate feedstock volatility, ASEAN harmonization implementation delays, and CAD/CAM technician scarcity constraints in Indian and Southeast Asian dental laboratories. Forecasts reflect documented assumptions regarding digital workflow adoption curves and regulatory enforcement intensity. Material deviation in petrochemical input costs or PMDA biocompatibility validation timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Dental Suction Systems Market
Dental Devices
China Dental Devices Market
Dental Devices
Sleep Apnea Oral Appliances Market
Dental Devices
Dental Composite Resin Filling Market
Dental Devices
Intraoral Dental Sensors Market
Dental Devices
Dental Inlays and Onlays Market
Dental Devices
Latin America Dental Devices Market
Dental Devices
3D Printing Dental Device Market
Dental Devices
Root Canal Market
Dental Devices
Dental Devices and Consumables Market
Dental Devices
Global Veterinary Dentistry Instruments and Equipment Market
Dental Devices
Dental Autoclave Market
Dental Devices
Dental Splints Market
Dental Devices
Europe CBCT Dental Imaging Market
Dental Devices
United States Dental Implants Market
Dental Devices
Dental Floss Market