
 Electronic Pediatric Nebulizer Market | 2026-2036
Electronic Pediatric Nebulizer Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Pediatric Nebulizer Market Insights
A capital-intensity divergence between dedicated respiratory device manufacturers and diversified healthcare conglomerates is redrawing competitive boundaries in pediatric aerosol delivery. PARI GmbH leverages decades of German engineering heritage in high-precision mesh technology to sustain premium positioning across European hospital networks. Yuwell anchors volume production through integrated manufacturing in China, competing aggressively on cost in emerging markets. Aerogen differentiates via vibrating mesh innovation optimized for low tidal-volume pediatric patients, occupying a narrow but defensible clinical niche.
An electronic pediatric nebulizer converts liquid medication into respirable aerosol particles typically sized between one and five microns for direct lung deposition in children, employing electromechanical or pneumatic mechanisms with flow rates calibrated to infant and toddler breathing patterns. Mesh nebulizers lead the product type landscape due to silent operation and reduced medication waste, while Bluetooth-enabled technology is gaining fastest as remote monitoring integration reshapes homecare protocols. Pediatric clinics and hospitals retain the largest end-user value pools, though homecare settings are expanding most rapidly as reimbursement frameworks shift toward outpatient chronic disease management.
FDA 510(k) clearance pathways and CE marking under the EU Medical Device Regulation shape product development timelines and market access requirements for electronic pediatric nebulizers, with ISO 18562 biocompatibility testing increasingly demanded for polymer components in infant-facing devices. Japan's PMDA enforces additional clinical validation standards that filter out lower-tier competitors. Stakeholders must monitor evolving connectivity security mandates and pediatric-specific human-factors guidelines as regulatory scope broadens beyond pure mechanical performance.
Market Dynamics
Mesh nebulizer technology is bifurcating the competitive landscape between premium vibrating-mesh systems and cost-optimized passive-mesh alternatives, compressing margins for mid-tier pneumatic competitors while expanding addressable volume in homecare channels.
Growth Catalysts
- Bluetooth-enabled remote monitoring:Homecare protocols in Germany and Japan now reimburse connected devices that transmit adherence data to pediatric pulmonologists, accelerating replacement cycles for legacy compressor units.
- ISO 18562 biocompatibility mandates:Infant-facing polymer testing requirements under EU MDR are filtering out unqualified suppliers, concentrating procurement among certified manufacturers with in-house toxicology capabilities.
- Pediatric asthma prevalence clusters:Urban air quality deterioration in the United States and Japan sustains chronic disease management demand, with Medicaid expansion in several US states extending device coverage to underserved populations.
Market Restraints
- Piezoelectric ceramic supply concentration:Vibrating-mesh actuators depend on rare-earth processing facilities concentrated in China, exposing manufacturers to export quota volatility and forced technology transfer requirements.
- Compressor nebulizer substitution:Low-cost pneumatic systems retain reimbursement parity in emerging markets, delaying mesh technology penetration where out-of-pocket payment dominates.
- PMDA clinical validation timelines:Japan's pharmaceutical and medical device agency requires pediatric-specific efficacy studies that extend market entry by 18-24 months versus FDA 510(k) pathways.
Strategic Opportunities
- Underpenetrated Indian homecare:Ayushman Bharat insurance expansion creates first-time reimbursement for respiratory devices in tier-2 cities, opening volume potential for cost-optimized mesh systems with local manufacturing partnerships.
- AI-actuated dosing algorithms:Convergence of flow-sensor arrays with machine learning enables real-time pediatric breathing pattern adaptation, differentiating premium offerings in European hospital networks.
- Direct-to-patient subscription channels:Pharmacy benefit managers in the United States are piloting nebulizer-as-a-service models that bundle device, consumables, and telehealth monitoring for chronic asthma households.
Industry Challenges
- Pediatric human-factors engineering talent:Specialized industrial designers capable of infant-safe form-factor development command premium compensation, constraining product refresh cadence for mid-tier manufacturers.
- CE-MDR technical documentation burden:European notified body backlogs extend conformity assessment timelines, freezing working capital in inventory awaiting market release authorization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Pediatric Nebulizer Market |
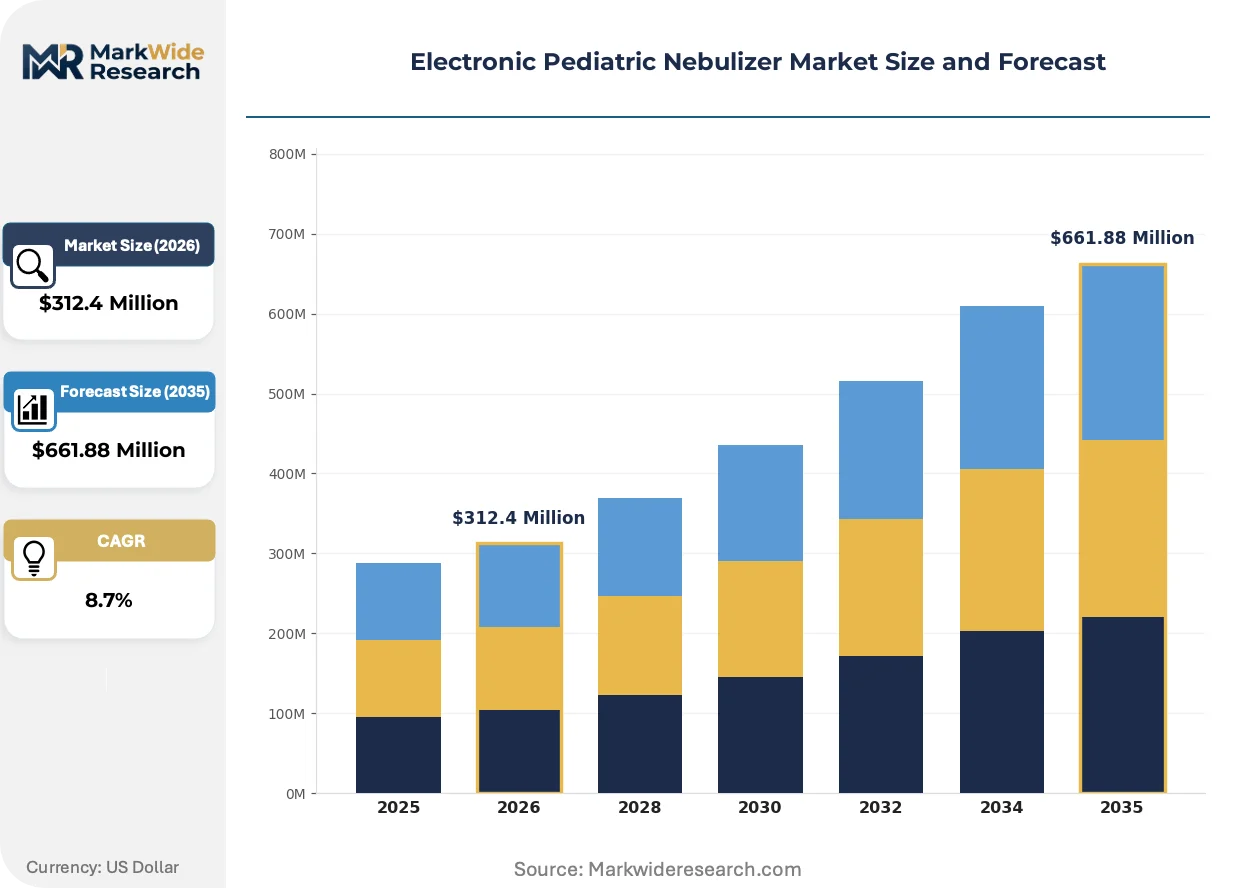
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mesh Nebulizers, Compressor Nebulizers, Ultrasonic Nebulizers, Portable Nebulizers End User: Pediatric Clinics, Hospitals, Homecare Settings, Emergency Rooms Technology: Electromechanical, Pneumatic, Bluetooth-enabled, Microcontroller-based Distribution Channel: Pharmacies, Online Retail, Medical Supply Stores, Direct Sales |
| Companies Covered | Koninklijke Philips N.V., PARI GmbH, Omron Corporation, Drive DeVilbiss Healthcare, Microlife Corporation, Aerogen, GE Healthcare, Yuwell, Medel International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Pediatric Nebulizer Market Trends and Innovations
Connectivity integration and miniaturization are compressing device form factors while expanding clinical data capture, fundamentally altering how pediatric respiratory therapy is prescribed, monitored, and reimbursed across ambulatory settings.
Vibrating mesh technology is bifurcating the product architecture landscape between hospital-grade precision systems and disposable homecare units. German engineering clusters dominate the former with sub-2-micron particle consistency for cystic fibrosis protocols, while Chinese manufacturing ecosystems drive the latter toward sub-$50 price points for asthma maintenance. This split is compressing R&D investment in legacy compressor platforms as procurement committees in France and Italy mandate silent operation standards incompatible with pneumatic mechanisms.
EU Medical Device Regulation biocompatibility testing is extending development timelines for polymer-intensive infant-facing components. ISO 18562-1 through -4 evaluation requirements now govern all gas-pathway materials, forcing reformulation of polycarbonate housings and silicone gaskets. Japanese manufacturers with pre-existing toxicology databases are capturing accelerated approval advantages, while smaller European specialists outsource testing to contract laboratories, diluting margin structures.
Parental adherence anxiety is displacing clinical-site purchasing authority in chronic disease management decisions. United States Medicaid programs in California and New York now authorize homecare durable medical equipment based on caregiver-reported quality-of-life metrics rather than physician preference alone. Pharmacy chains are responding with staffed respiratory therapy consultations, capturing device selection influence from hospital discharge planners and pulmonology practices.
Electronic Pediatric Nebulizer Market Segmentation
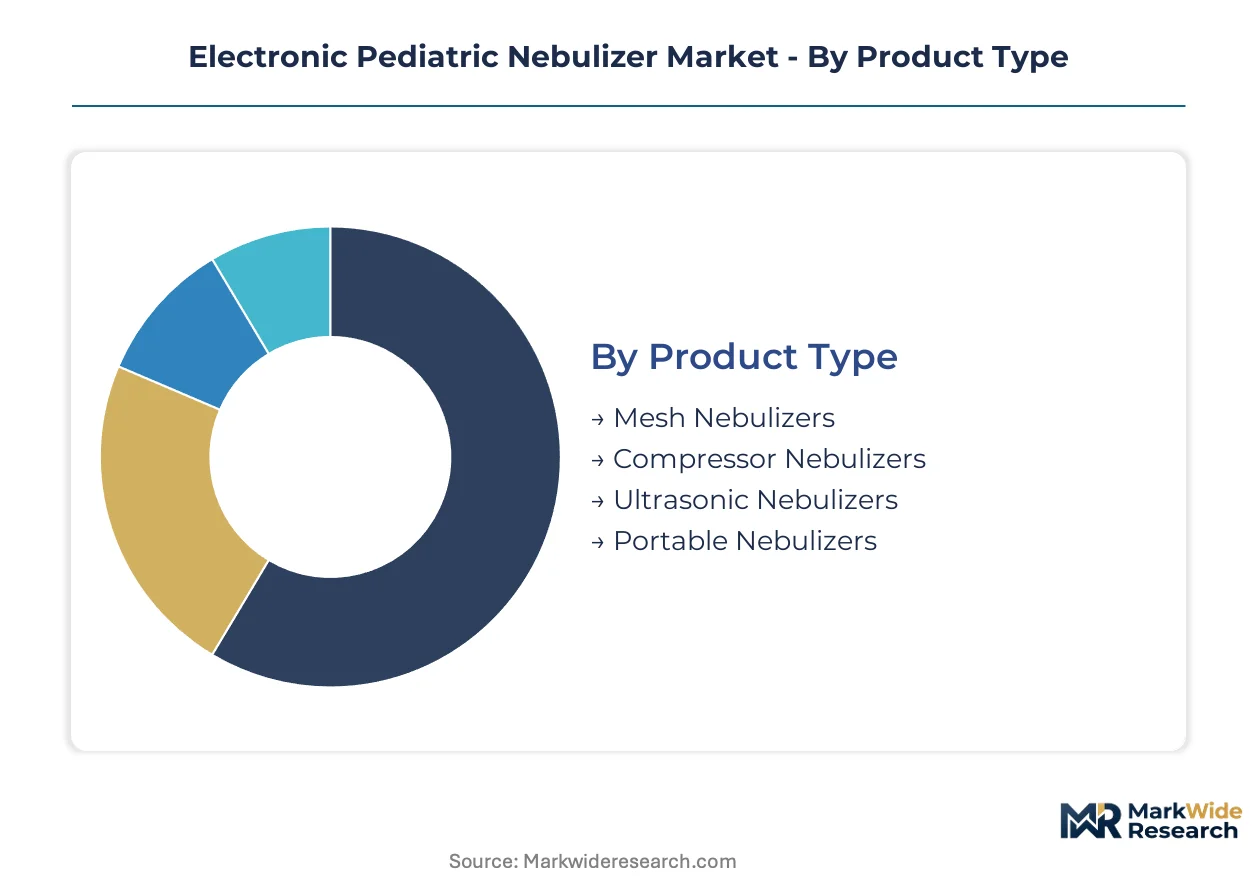
Channel mix and reimbursement pathways determine which pediatric nebulizer configurations capture volume versus margin. Manufacturers must align product architecture with specific procurement hierarchies across hospital systems, retail pharmacies, and direct-to-patient platforms.
Product Type:
Hospital procurement committees and homecare reimbursement tiers split demand across electromechanical architectures with distinct noise profiles and particle consistency specifications.
- Mesh Nebulizers:Vibrating-mesh actuators generate sub-3-micron aerosol distributions with near-silent operation below 30 decibels. German hospital networks and Japanese cystic fibrosis centers specify these for overnight infant dosing protocols where noise disrupts sleep architecture.
- Compressor Nebulizers:Piston-driven pneumatic systems deliver higher flow rates through disposable tubing sets at acquisition costs one-third of mesh equivalents. Medicaid programs in Texas and Florida retain reimbursement parity for these units, sustaining volume in price-sensitive homecare segments despite noise levels exceeding 55 decibels.
- Ultrasonic Nebulizers:Piezoelectric crystal arrays produce aerosol through high-frequency liquid surface disruption.
- Portable Nebulizers:Battery-optimized miniaturized units target travel-dependent families and school-based asthma action plans.
By volume, compressor nebulizers lead. By growth pace, mesh systems are gaining share fastest.
End User:
Purchasing authority and reimbursement coding complexity create four distinct customer types with diverging technical requirements and contract negotiation dynamics.
- Pediatric Clinics:Ambulatory pulmonology practices in the United States and Germany prioritize rapid patient turnaround with disposable medication cups and 90-second treatment protocols. These settings drive demand for dual-voltage compressor units compatible with examination room infrastructure.
- Hospitals:Inpatient pediatric wards and respiratory therapy departments require ISO 18562-certified gas-pathway materials and centralized oxygen compatibility. French and Italian procurement frameworks now mandate silent operation standards that disqualify legacy pneumatic platforms from new equipment tenders.
- Homecare Settings:Caregiver-operated devices for chronic asthma and bronchiolitis management.
- Emergency Rooms:Triage-optimized disposable nebulizer systems for acute bronchospasm episodes.
By installed base, hospitals dominate. By expansion trajectory, homecare settings are climbing the fastest as outpatient chronic disease management frameworks mature.
Technology:
Component cost tiers and regulatory validation burden separate mature electromechanical platforms from emerging connected architectures with data security compliance requirements.
- Bluetooth-enabled:Wireless adherence monitoring transmits treatment timestamps and inhalation flow profiles to pediatric pulmonology dashboards. Germany's DiGA framework and Japan's MHLW reimbursement codes now cover connected respiratory devices, accelerating replacement of analog compressor units in insured populations.
- Electromechanical:Proven vibrating-mesh and piston-compressor architectures with established FDA 510(k) predicate device pathways. These platforms minimize regulatory risk for manufacturers but lack differentiation in procurement evaluations where connectivity is becoming a scored criterion.
- Pneumatic:Compressed gas or piston-driven aerosol generation without electronic control systems.
- Microcontroller-based:Embedded sensor arrays enabling dose tracking and fault detection without full wireless connectivity.
By shipment volume, electromechanical platforms lead. By development pipeline investment, Bluetooth-enabled systems show the steepest expansion trajectory.
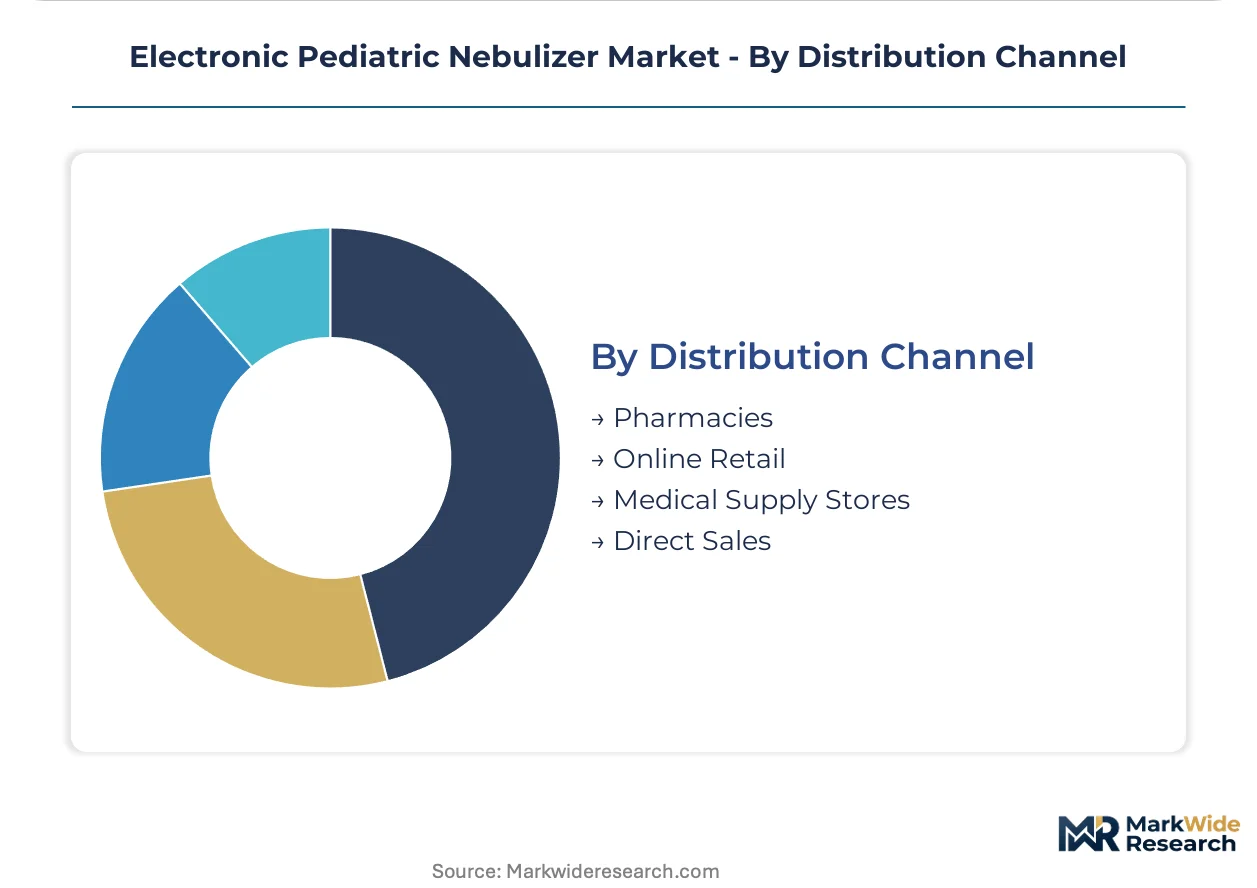
Distribution Channel:
Patient journey stage and reimbursement processing complexity determine whether devices flow through staffed retail, digital self-service, institutional contracting, or manufacturer-direct pathways.
- Pharmacies:United States retail chains including CVS and Walgreens now employ respiratory therapists for nebulizer counseling, capturing device selection influence from hospital discharge planners. Medicare Part B durable medical equipment billing through pharmacy networks simplifies caregiver access compared to home medical equipment dealers.
- Online Retail:Direct-to-consumer platforms bypass prescription requirements in markets with less stringent medical device classification. Indian e-commerce marketplaces and Amazon's US marketplace drive price transparency and comparison shopping for replacement mesh heads and medication cups.
- Medical Supply Stores:Specialized durable medical equipment dealers with insurance pre-authorization expertise.
- Direct Sales:Manufacturer field representatives negotiating hospital system and managed care organization contracts.
By transaction volume, pharmacies lead. By channel margin expansion, online retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. United States and Japanese buyers prioritize clinical efficacy and connectivity over acquisition cost, while Indian and Brazilian markets remain acutely price-sensitive, compressing margins for premium mesh systems.
United States
Medicaid expansion in California and New York has extended device coverage to previously underserved pediatric populations. FDA 510(k) clearance pathways maintain shorter market entry timelines than Japanese or European equivalents. Hospital procurement committees in Boston and New York Metro increasingly mandate Bluetooth-enabled adherence monitoring for chronic asthma management.
Germany
The DiGA framework now reimburses connected respiratory devices that transmit treatment data to pediatric pulmonologists. CE marking under EU MDR enforces ISO 18562 biocompatibility testing for all gas-pathway polymers. Engineering clusters in Bavaria and North Rhine-Westphalia concentrate vibrating-mesh manufacturing for hospital-grade precision systems.
Japan
Pediatric asthma prevalence in urban corridors sustains chronic disease management demand. PMDA requires pediatric-specific efficacy studies that extend market entry by 18-24 months versus FDA pathways. Tokyo and Osaka-based manufacturers leverage pre-existing toxicology databases to capture accelerated approval advantages under tightened biocompatibility standards.
India
Ayushman Bharat insurance expansion creates first-time reimbursement for respiratory devices in tier-2 cities. CDSCO medical device regulations are tightening quality benchmarks for imported electronics. Manufacturing partnerships in Gujarat and Maharashtra enable cost-optimized mesh production for price-sensitive homecare segments.
China
Domestic volume production anchors global supply for cost-optimized passive-mesh alternatives. NMPA medical device registration requirements filter out lower-tier competitors. Yangtze River Delta manufacturing ecosystems drive unit economics toward sub-$50 price points for emerging market export.
Electronic Pediatric Nebulizer Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the former commanding hospital procurement contracts and the latter capturing homecare volume through cost engineering. The competitive terrain separates into three archetypes: diversified healthcare conglomerates with respiratory divisions, dedicated aerosol delivery specialists, and integrated manufacturing platforms from East Asia. Dominant competitive moves include vertical integration into piezoelectric actuator supply chains and strategic partnerships with pharmacy benefit managers for subscription-based device distribution.
Among dedicated specialists, PARI GmbH exemplifies the premium engineering archetype with German heritage in precision mesh technology, while Yuwell anchors the volume-production tier through integrated Chinese manufacturing. Aerogen occupies a narrow clinical niche with vibrating-mesh innovation calibrated for low tidal-volume pediatric applications. These three represent distinct competitive vectors: heritage engineering, manufacturing scale, and clinical specialization.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| PARI GmbH |
| Omron Corporation |
| Drive DeVilbiss Healthcare |
| Microlife Corporation |
| Aerogen |
| GE Healthcare |
| Yuwell |
| Medel International |
| Others |
Pricing and Supply Chain Analysis
Ninety-day inventory cycles for piezoelectric actuators concentrate procurement leverage among German and Japanese manufacturers, compressing margin structures for mid-tier competitors while amplifying pricing power for vertically integrated mesh-technology specialists with captive ceramic sourcing.
Pricing Analysis
After-sales revenue from replacement mesh heads and medication cups drives lifetime value, with consumable attachment rates determining profitability more than device acquisition cost. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared hospital systems from CE-marked homecare units and unregulated direct-to-consumer imports. Pricing pressure stems from Medicaid reimbursement compression in Texas and Florida, where compressor nebulizers retain parity despite inferior clinical performance. Homecare caregivers exhibit highest price sensitivity, while Japanese cystic fibrosis centers prioritize particle consistency over acquisition cost.
Supply Chain Analysis
China dominates passive-mesh manufacturing and rare-earth ceramic processing, while Germany and Japan anchor precision vibrating-mesh production for hospital-grade systems. Raw material flows draw from zirconium oxide deposits, medical-grade polycarbonate resins, and platinum-coated electrode assemblies. Single-source vulnerability concentrates in piezoelectric ceramic supply, where export quota volatility from Yangtze River Delta processors disrupts actuator availability. Distribution runs through pharmacy benefit managers in the United States, hospital procurement consortiums in France and Italy, and direct-to-patient platforms in Indian tier-2 cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
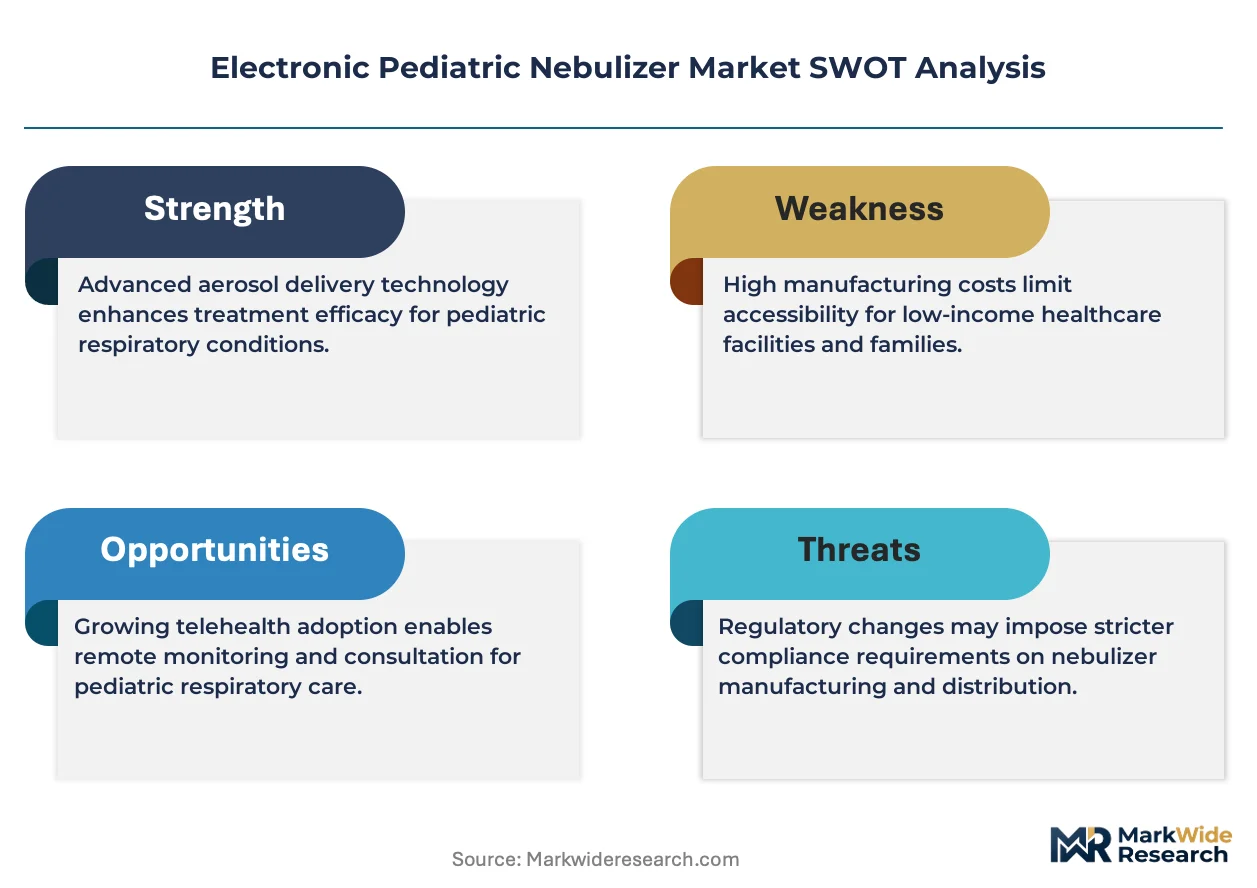
Fragmentation opportunity emerges as connectivity mandates and biocompatibility testing bifurcate the vendor base, creating specialist niches for certified manufacturers while filtering out undifferentiated compressor suppliers.
For Market Incumbents: Consolidate control over piezoelectric ceramic supply chains through backward integration or long-term offtake agreements with Yangtze River Delta processors. Deepen hospital system partnerships in Germany and Japan where DiGA and MHLW reimbursement codes favor connected devices, defending against cost-optimized Chinese entrants in emerging markets. For New Entrants and Emerging Players: Lead with AI-actuated dosing algorithms targeting European hospital networks where breathing-pattern adaptation commands premium positioning. Capture underpenetrated Indian homecare through Ayushman Bharat reimbursement partnerships with Gujarat and Maharashtra manufacturing joint ventures, bypassing established distribution through direct pulmonologist engagement. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified healthcare conglomerates with underinvested respiratory divisions lacking ISO 18562 certification capabilities. Five-to-ten year viability hinges on connectivity integration and toxicology database depth; monitor PMDA approval timelines as inflection signal for Japanese market access competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR biocompatibility testing filters out unqualified polymer suppliers from infant-facing device markets. |
| Hospital System Partnership | French and Italian procurement frameworks now mandate silent operation standards incompatible with pneumatic platforms. |
| Software Companion Development | Bluetooth-enabled adherence monitoring qualifies for Germany's DiGA reimbursement and Japan's MHLW connected device codes. |
| Reimbursement Strategy | Medicaid expansion in California and New York extends coverage to underserved pediatric asthma populations. |
| FDA Submission | 510(k) predicate pathways maintain shorter market entry timelines than PMDA pediatric-specific efficacy requirements. |
Research Methodology
Initial hypotheses were tested against primary input from pediatric pulmonologists, hospital biomedical engineers, GPO contracts managers, and pharmacy benefit manager formulary directors and refined through secondary validation against FDA 510(k) filings, CE marking databases under EU MDR, Japanese PMDA approval records, and CMS Medicare durable medical equipment claims. Bottom-up shipment estimates from manufacturer disclosures triangulated against top-down demand modeling from asthma prevalence databases and reimbursement expansion schedules.
Variance decomposition across product type, end-user setting, technology tier, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation with macro healthcare expenditure trajectories and pediatric respiratory disease epidemiology. Forecast inputs incorporated piezoelectric ceramic supply constraints, notified body backlog timelines, and connectivity security mandate evolution.
The analysis sits within stated boundaries; outcomes outside sustained Medicaid expansion, stable rare-earth export flows, or accelerated PMDA review timelines would require recalibration. Forecasts reflect documented assumptions regarding reimbursement parity shifts and biocompatibility standard enforcement. Recalibration cycles align with material shifts in regulatory approval timelines, supply quota announcements, and connectivity mandate effective dates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Needle-Free Drug Delivery Devices Market
Medical Devices
Global Urinary Incontinence Treatment Devices Market
Medical Devices
Elderly and Disabled Assistive Devices Market
Medical Devices
North America and Europe Medical Technology Market
Medical Devices
GCC Biopsy Devices Market
Medical Devices
Myopia Management Lenses Market
Medical Devices
Global Pacemakers Market
Medical Devices
APAC AMH Market
Medical Devices
Global Next Generation Surgical Robotics Market
Medical Devices
Latin America Breast Biopsy Needle Market
Medical Devices
Europe Urinary Catheters Market
Medical Devices
US Nurse Call Systems Market
Medical Devices
North America Electroencephalography Devices Market
Medical Devices
Bionic Devices Market
Medical Devices
Eye Examination Equipment Market
Medical Devices
Lung Preservation Systems Market