
 Bowel Irrigation System Market | 2026-2036
Bowel Irrigation System Market Size, Share, and Industry Trends Forecast 2026-2036
Bowel Irrigation System Market Analytics
REACH compliance is pivoting the cost-of-entry calculus for European manufacturers of bowel irrigation systems. Coloplast leverages its captive polymer compounding capabilities to navigate evolving biocompatibility mandates without supplier dependency. Becton, Dickinson and Company anchors its position through sterile kit automation lines that sustain batch consistency under tighter chemical safety thresholds. ConvaTec Group plc differentiates via hydrophilic coating technologies that preempt regulatory scrutiny on surface-leachable substances.
Bowel irrigation systems are closed-loop fluid delivery devices designed to introduce controlled water volumes into the lower colon through rectal or transanal catheters, typically operating at pressures below 100 mmHg and temperatures between 36°C and 38°C to prevent mucosal injury; their primary purpose is to restore predictable defecation patterns in patients with neurogenic bowel dysfunction or chronic constipation. Automated systems command the dominant revenue share due to programmable flow-rate controls that reduce caregiver burden, while disposable kits represent the fastest-growing product category as infection-control protocols harden against reusable component cross-contamination. Home care end users now absorb the majority of unit volume, though margin pools remain deeper in specialized centers where clinical oversight justifies premium pricing for integrated telemetry features.
FDA 510(k) pathways govern US market access for bowel irrigation devices, while the EU MDR and ISO 13485 quality management standards shape conformity assessment across European distribution channels. Japan's PMDA enforces additional sterilization validation requirements that filter out lower-capability assemblers. Stakeholders must monitor how reimbursement code expansions in home care settings interact with regulatory demands for real-world evidence on long-term catheter safety.
Market Dynamics
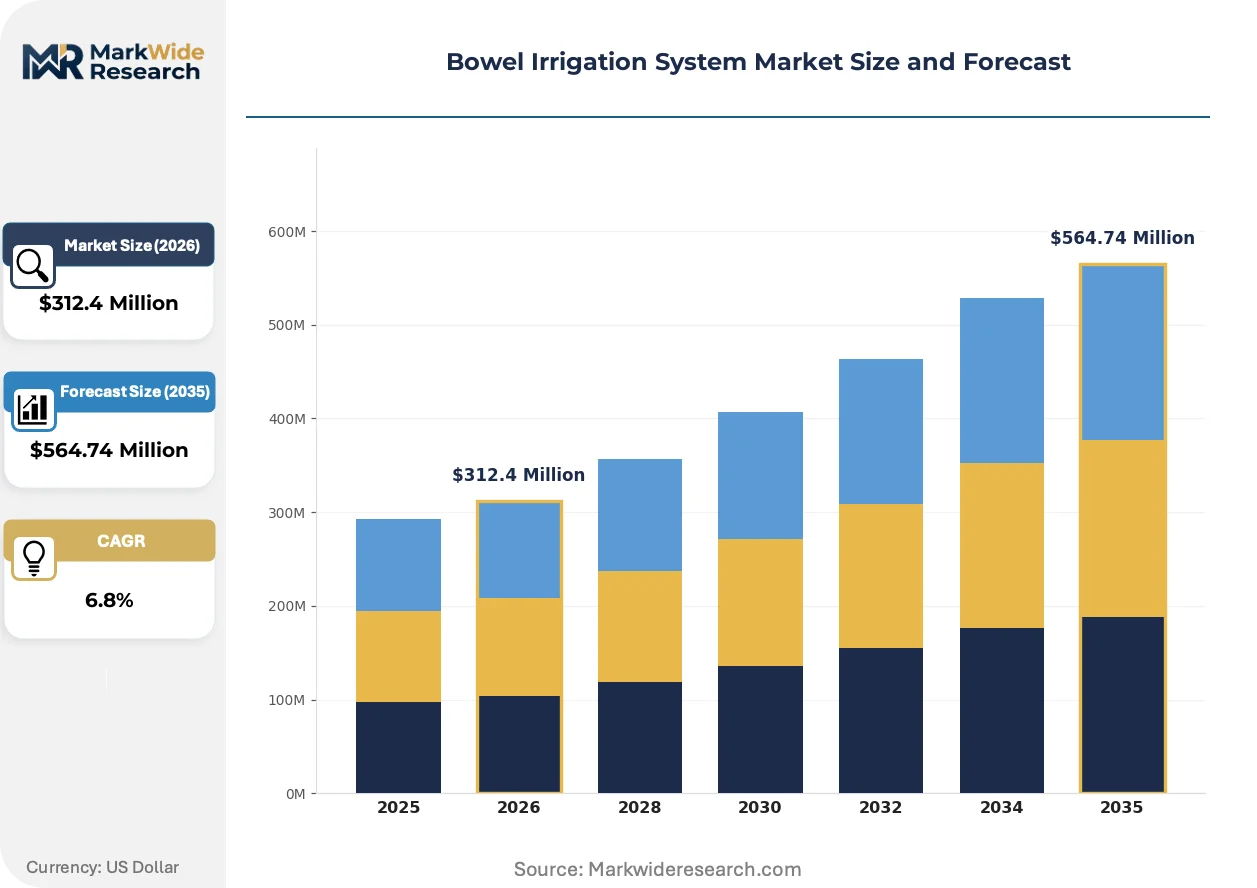
The EU Medical Device Regulation is compressing product development timelines as manufacturers redesign rectal catheter materials to meet tightened biocompatibility testing protocols, while home care reimbursement expansions in Germany pull volume away from institutional channels.
Growth Catalysts
- Statutory health insurance frameworks:Germany's expanded reimbursement codes for transanal irrigation procedures accelerate patient migration from hospital-based care to domestic settings.
- Catheter-free bowel management:Patient preference for non-invasive home protocols drives demand for closed-loop fluid delivery systems with programmable controls.
- Polymer compounding capabilities:Captive material science competencies allow manufacturers to iterate rapidly on REACH-compliant formulations without supplier bottlenecks.
Market Restraints
- Biocompatibility testing costs:EU MDR mandates for rectal delivery component validation inflate pre-market expenditure for mid-tier assemblers lacking in-house toxicology labs.
- Sterilization validation barriers:Japan's PMDA requirements filter out lower-capability manufacturers, concentrating supply among firms with validated gamma or ethylene oxide protocols.
- Reusable component liability:Infection-control protocols hardening against cross-contamination compress margins on capital equipment sales in favor of disposable kit economics.
Strategic Opportunities
- Telemetry-enabled systems:Integrated flow-rate monitoring and remote compliance tracking create premium positioning in specialized centers where clinical oversight justifies higher pricing.
- Hydrophilic coating technologies:Surface engineering that preempts regulatory scrutiny on leachable substances opens differentiation in European distribution channels.
- Automated sterile kit production:Robotics-based assembly lines that sustain batch consistency under tightening chemical safety thresholds capture share from manual assemblers.
Industry Challenges
- ISO 13485 quality management implementation:Smaller manufacturers face extended certification timelines as notified bodies prioritize MDR conformity assessments over legacy quality system renewals.
- Real-world evidence collection:Payers and regulators demand longitudinal catheter safety data that home care settings struggle to document systematically without integrated digital infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bowel Irrigation System Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Systems, Automated Systems, Disposable Kits, Reusable Kits End User: Hospitals, Clinics, Home Care, Specialized Centers Application: Constipation Treatment, Bowel Preparation, Fecal Incontinence, Colorectal Surgery Delivery Mode: Oral, Rectal, Transanal, Enema |
| Companies Covered | Coloplast, Becton, Dickinson and Company, ConvaTec Group plc, Qufora A/S, B. Braun Melsungen AG, Consure Medical, ProSys International Ltd, Renew Medical Inc, Aquaflush Medical Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bowel Irrigation System Market Evolving Landscape
Closed-loop fluid delivery architectures are displacing gravity-dependent systems as pressure-controlled pumps enable precise volumetric administration without caregiver supervision, reshaping competitive requirements across both institutional and domestic channels.
Programmable micro-pump mechanisms are integrating flow-rate sensors and thermal regulation modules to maintain irrigation temperatures between 36°C and 38°C automatically. Home care patients and their caregivers adopt these systems fastest where statutory reimbursement reduces out-of-pocket exposure. The technology is integrating predictive maintenance algorithms that flag catheter degradation before mucosal injury risk escalates, compressing liability exposure for manufacturers.
REACH enforcement through ECHA is mandating full material disclosure for all polymer components contacting rectal mucosa, eliminating legacy phthalate-based softeners from supply chains. Industrial consequence includes forced reformulation of catheter durometers and bonding adhesives. German and French notified bodies are processing technical documentation most aggressively, creating first-mover advantage for firms with pre-submitted dossiers.
Patient-administered irrigation protocols are displacing nurse-dependent bowel management in spinal cord injury and multiple sclerosis populations. Specialist continence nurses in the Netherlands and Scandinavia now train home users on transanal irrigation during single-session discharges, replacing recurring outpatient visits. This behavioral pivot concentrates volume in disposable kit categories while eroding rental revenue from reusable system deployments.
Bowel Irrigation System Market Segmentation
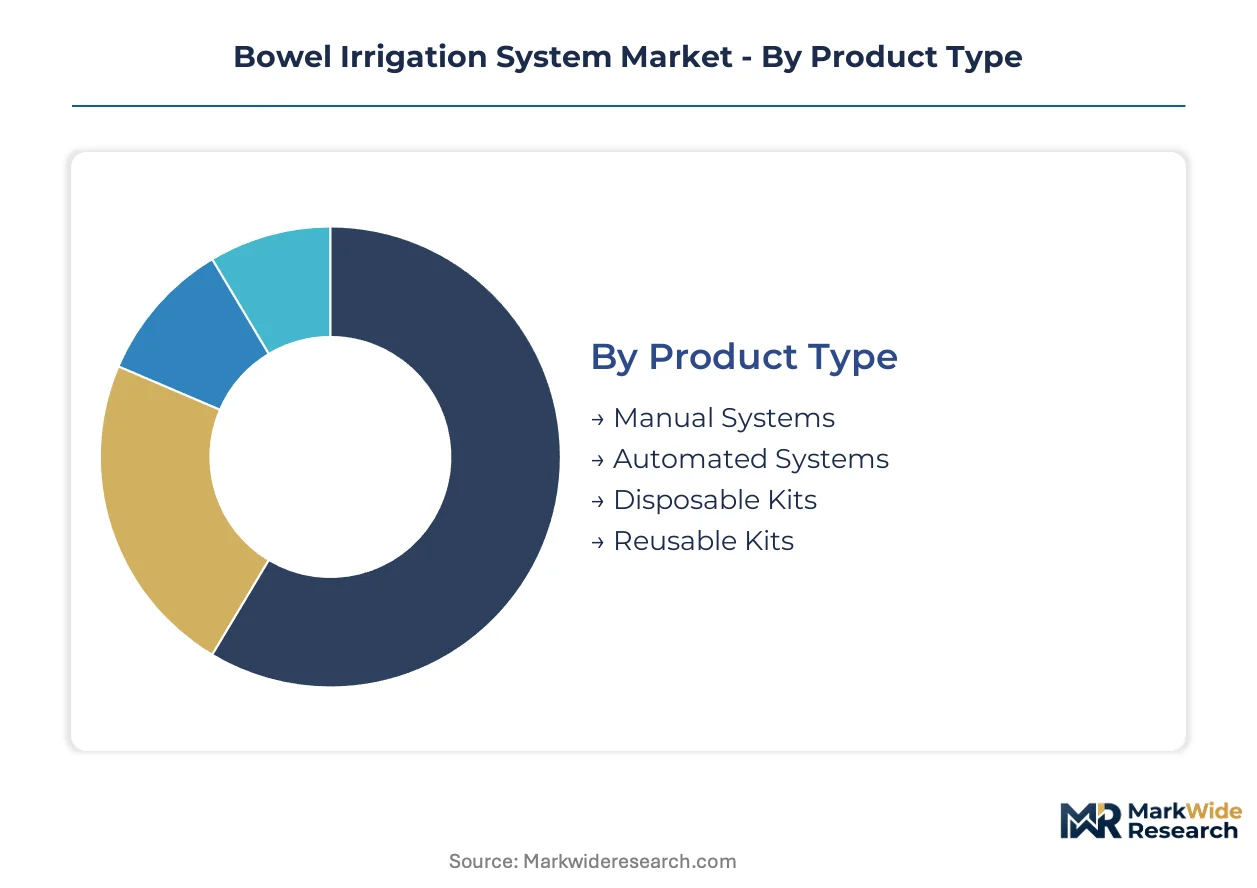
Bowel irrigation system segmentation reveals how procurement authority and reimbursement pathways fragment demand across institutional and domestic channels. Technical specifications diverge sharply between caregiver-supervised installations and patient-administered home protocols.
Product Type:
Cost tiers separate capital equipment purchasers from recurring consumable buyers across reimbursement frameworks.
- Automated Systems:Programmable pressure pumps maintain irrigation temperatures between 36°C and 38°C through integrated thermal regulation modules. Hospitals in Germany absorb the majority of unit volume where statutory reimbursement codes justify premium capital expenditure.
- Disposable Kits:Single-use catheter assemblies with pre-filled saline reservoirs eliminate cross-contamination liability. Home care settings in the Netherlands and Scandinavia are expanding most quickly as specialist continence nurses train patients on transanal irrigation during single-session discharges.
- Manual Systems:Gravity-dependent bags with hand-controlled flow valves serve price-sensitive institutional buyers.
- Reusable Kits:Silicon catheter sets with sterilizable components face margin compression from hardening infection-control protocols.
Volume sits with Automated Systems; growth tilts toward Disposable Kits.
End User:
Clinical oversight requirements determine feature bundling and pricing architecture across patient touchpoints.
- Home Care:Patient-administered protocols for spinal cord injury and multiple sclerosis populations demand closed-loop fluid delivery with remote compliance tracking. Germany's expanded statutory health insurance frameworks accelerate migration from hospital-based care to domestic settings.
- Specialized Centers:Integrated telemetry features justify premium pricing where clinical oversight mandates real-time flow-rate monitoring.
- Hospitals:Acute care procurement prioritizes batch-consistent sterile kits under tighter EU MDR chemical safety thresholds.
- Clinics:Outpatient facilities concentrate reusable system rentals where nurse-dependent bowel management persists.
Unit volume concentrates in Home Care; margin pools remain deepest in Specialized Centers.
Application:
Physiological indication dictates catheter specification and irrigation pressure parameters.
- Constipation Treatment:Chronic idiopathic constipation and opioid-induced bowel dysfunction drive demand for low-pressure transanal irrigation below 100 mmHg.
- Fecal Incontinence:Neurogenic bowel dysfunction in spinal cord injury patients requires predictable defecation pattern restoration through programmable volumetric administration.
- Bowel Preparation:Pre-operative colon cleansing protocols favor rapid-fill systems with higher flow rates.
- Colorectal Surgery:Post-anastomotic irrigation demands sterile single-use assemblies to prevent surgical site infection.
Procedure volume clusters around Constipation Treatment; steepest expansion trajectory appears in Fecal Incontinence management.
Delivery Mode:
Anatomical entry point determines regulatory classification and biocompatibility testing burden.
- Transanal:Catheter-based delivery through the anal canal into the rectosigmoid colon represents the dominant revenue channel. REACH compliance through ECHA mandates full material disclosure for all polymer components contacting rectal mucosa.
- Rectal:Enema-style bulb or bag systems serve short-term bowel preparation with lower device classification requirements.
- Oral:Pharmacological bowel preparation competes indirectly on patient preference for non-invasive protocols.
- Enema:Traditional phosphate or saline enemas retain share in acute constipation relief despite irrigation system displacement.
Revenue concentrates in Transanal delivery; regulatory scrutiny intensifies fastest for Rectal component classifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's statutory health insurance zones for home medical equipment create the densest reimbursement infrastructure for bowel irrigation systems in Europe. Patient migration from hospital-based care to domestic settings concentrates demand in cities with established continence nursing networks.
Germany
Statutory health insurance frameworks for transanal irrigation procedures accelerate patient discharge protocols. The EU Medical Device Regulation drives notified bodies in Berlin and Munich to process technical documentation aggressively for catheter material reformulations. Manufacturing clusters in Baden-Württemberg iterate rapidly on REACH-compliant polymer formulations.
United States
Spinal cord injury rehabilitation centers in major metropolitan corridors drive institutional procurement of programmable irrigation systems. FDA 510(k) pathways govern market access with emphasis on sterile kit validation. Production capabilities concentrate in medical device corridors where contract manufacturers serve multiple catheter-based therapy segments.
Netherlands
Specialist continence nurses train home users on transanal irrigation during single-session hospital discharges. The country's national healthcare regulator enforces infection-control protocols that favor disposable kit economics over reusable system rentals. Medical technology distribution hubs in Utrecht and Eindhoven coordinate logistics for Benelux home care channels.
Japan
PMDA sterilization validation requirements filter out lower-capability assemblers, concentrating supply among firms with validated gamma protocols. Aging demographics expand the addressable patient base for neurogenic bowel dysfunction management. Industrial clusters in the Kansai region maintain precision polymer processing capabilities for medical catheter production.
United Kingdom
National Health Service procurement frameworks prioritize batch-consistent sterile kits under tightening chemical safety thresholds. Continence service networks in England drive patient-administered protocol adoption for multiple sclerosis populations. Regulatory alignment with EU MDR standards persists post-Brexit, maintaining biocompatibility testing burdens for rectal delivery components.
Bowel Irrigation System Market Competitive Landscape
European producers anchor the premium-tier supply base; North American specialists hold positions in automated system engineering. Market structure tilts toward consolidated control among firms with captive polymer compounding capabilities, though mid-tier assemblers persist in regional distribution channels. Strategic archetypes include integrated material science operators, sterile kit automation specialists, and hydrophilic coating technology developers. Competitive moves center on M&A for regulatory dossier portfolios and capacity expansion in REACH-compliant polymer lines.
Among Denmark-based operators, Coloplast occupies a position exemplifying integrated material science capabilities. Becton, Dickinson and Company anchors the sterile kit automation archetype through its instrumentation heritage. ConvaTec Group plc sits within the surface engineering tier, representing hydrophilic coating competencies that address leachable substance scrutiny.
| Leading Market Players |
|---|
| Coloplast |
| Becton, Dickinson and Company |
| ConvaTec Group plc |
| Qufora A/S |
| B. Braun Melsungen AG |
| Consure Medical |
| ProSys International Ltd |
| Renew Medical Inc |
| Aquaflush Medical Limited |
| Others |
Value Network & Pricing Analysis
Polymer resin costs for REACH-compliant catheter formulations cascade through three pricing tiers, with German compounders commanding premium spreads over Asian spot suppliers as EU MDR biocompatibility documentation requirements harden.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent separate emergency hospital procurement from scheduled home care kit replenishment. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with ISO 13485-validated manufacturers capturing margin above manual assemblers. Pricing pressure stems from mid-tier assemblers lacking captive toxicology labs as EU MDR testing mandates inflate pre-market expenditure. Home care patients exhibit highest price sensitivity where statutory reimbursement gaps expose out-of-pocket exposure, while specialized centers absorb premium telemetry features with limited negotiation leverage.
Supply Chain Analysis
Direct-to-hospital channels handle institutional volume through GPO contracts, while home care distribution runs through specialized medical equipment retailers and continence nursing networks. Manufacturing concentrates in Germany, Denmark, and the United States, with Baden-Württemberg polymer clusters and Copenhagen-area coating specialists anchoring European supply. Production draws from medical-grade silicone, thermoplastic elastomers, and hydrophilic coating precursors. Single-source vulnerability concentrates in gamma sterilization capacity, where validated ethylene oxide alternatives remain limited among mid-tier assemblers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR notified body backlogs constrain REACH-compliant polymer capacity, propping pricing power among manufacturers with pre-submitted technical dossiers.
For Market Incumbents: Lock in catheter material supply agreements with German compounders before REACH disclosure mandates eliminate legacy phthalate formulations. Secure gamma sterilization slot allocations to preempt mid-tier competitors from clearing Japan PMDA validation. Vertical integration into hydrophilic coating chemistry defends margin against surface-engineering specialists. For New Entrants and Emerging Players: Enter via disposable kit automation for Netherlands and Scandinavian home care channels where specialist nurse training protocols concentrate patient-administered volume. Target manual system displacement in price-sensitive Southern European clinics. Pursue white-label partnerships with established polymer compounders to bypass REACH formulation development timelines. For Investors and Strategic Acquirers: German statutory reimbursement code expansions for transanal irrigation are the leading indicator that home care volume migration will sustain premium pricing for telemetry-enabled systems. Acquisition candidates with captive polymer compounding and pre-validated EU MDR dossiers offer defensive positioning through regulatory capacity scarcity. Monitor Japan PMDA sterilization validation clearance rates as a signal for supply-side consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Dossier Pre-Submission | Early engagement with Berlin and Munich notified bodies secures priority review queues ahead of mid-tier competitors. |
| REACH-Compliant Polymer Backward Integration | Captive compounding capabilities in Baden-Württemberg eliminate supplier dependency for rectal delivery component reformulation. |
| Telemetry-Enabled System Development | Integrated flow-rate monitoring justifies premium positioning in specialized centers with clinical oversight mandates. |
| Single-Session Nurse Training Protocols | Dutch and Scandinavian continence nursing networks accelerate patient-administered protocol adoption in home care settings. |
| Gamma Sterilization Capacity Expansion | Validated protocols for catheter assemblies filter out lower-capability assemblers under Japan PMDA requirements. |
Research Methodology
Regulatory filing databases, hospital procurement records, and polymer trade flow data formed the secondary backbone, supplemented by primary interviews with biomedical engineers, GPO contracts managers, continence nursing specialists, and regulatory affairs leads at notified bodies. Bottom-up unit demand modeling across product type, end user, application, and delivery mode dimensions combined with top-down reimbursement framework analysis to triangulate market sizing.
Historical trendline analysis of statutory health insurance code expansions and catheter safety surveillance data informed growth trajectory projections across the analysis window. Segmentation modeling captured product type, end user channel, clinical application, and anatomical delivery mode variations. CAGR derivation incorporated reimbursement elasticity coefficients and regulatory approval timeline distributions specific to transanal irrigation devices.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU MDR notified body processing delays or REACH enforcement acceleration. Periodic stress-testing of base assumptions is recommended, particularly regarding polymer supply chain reconfiguration timelines and home care reimbursement code stability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
APAC Ablation Devices Market
Medical Devices
ECG Sensor Patch Market
Medical Devices
Dual Balloon Angioplasty Catheter Market
Medical Devices
US Mechanical Ventilator Market
Medical Devices
Wireless ECG Devices Market
Medical Devices
3D Printed Hip and Knee Implants Market
Medical Devices
Asia-Pacific Wearable Medical Devices Market
Medical Devices
Surgical Display Market
Medical Devices
Injectable Bulking Agents Market
Medical Devices
Air Oxygen Blender Market
Medical Devices
Global Limb Prosthetics Market
Medical Devices
Micro Balloon Catheter Market
Medical Devices
Medical Device Complaint Management Market
Medical Devices
Sharps Destruction Device Market
Medical Devices
Venous Device Market
Medical Devices
Asia-Pacific Smart Medical Devices Market