
 Global Oxygen Cylinders and Concentrators Market | 2026-2036
Global Oxygen Cylinders and Concentrators Market Size, Share, and Industry Trends Forecast 2026-2036
Global Oxygen Cylinders and Concentrators Market Foresight
Modular oxygen delivery systems that separate concentrator units from battery and cart accessories is realigning how home healthcare providers evaluate total cost of ownership. Koninklijke Philips N.V. leverages its sleep and respiratory therapy ecosystem to bundle software-enabled monitoring with hardware sales. Inogen, Inc. specializes in portable concentrator lightweighting, sustaining premium positioning through direct-to-consumer channels. CAIRE Inc. anchors its competitive stance with military and commercial aviation oxygen systems that extend into civilian medical applications.
Oxygen cylinders and concentrators are pressure vessels and electromechanical devices that generate, store, or purify medical-grade oxygen typically at concentrations exceeding 90% for therapeutic delivery to patients with respiratory insufficiency. Pressure swing adsorption technology dominates portable and stationary concentrator manufacturing due to its energy efficiency and reliability at scale. Among product configurations, portable oxygen concentrators represent the fastest-expanding segment as ambulatory patients prioritize mobility over stationary systems. Composite cylinders command margin concentration despite higher unit costs, since carbon-fiber wrapping reduces weight by 40-70% versus steel alternatives and supports emergency medical services deployment.
FDA 510(k) clearance requirements and EU MDR technical documentation obligations shape product development timelines and market access costs for oxygen device manufacturers. ISO 13485 quality management certification and IEC 60601-1-2 electromagnetic compatibility standards further constrain supplier qualification for hospital and clinic procurement. Stakeholders must monitor reimbursement rate adjustments by CMS and parallel national health technology assessment bodies, as payment policy shifts directly alter end-user affordability and replacement cycle velocity.
Market Dynamics
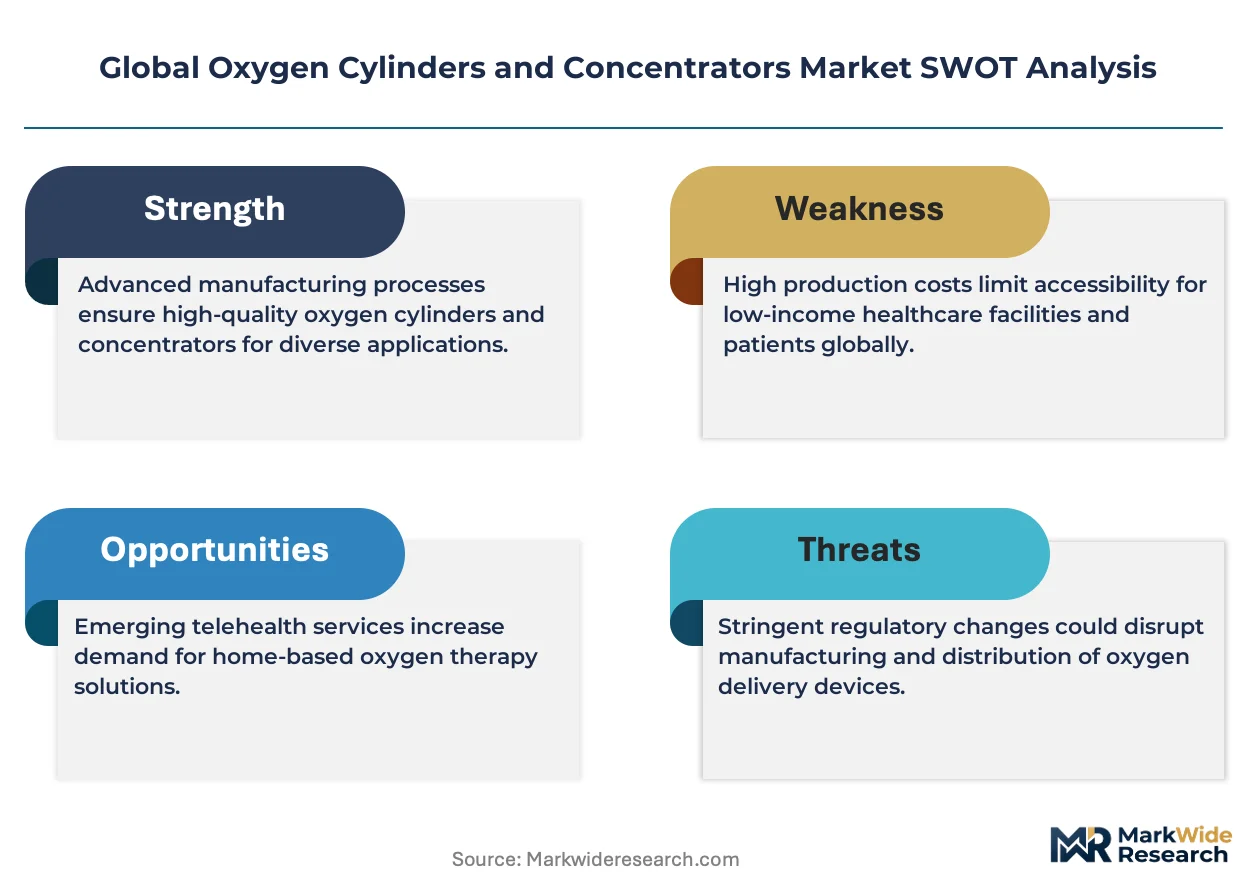
The oxygen device market restructures around decentralized post-acute care delivery, with home healthcare providers consolidating purchasing power and demanding modular, software-integrated systems that reduce total cost of ownership across replacement cycles.
Growth Catalysts
- EU MDR compliance deadlines:Manufacturers accelerating technical documentation completion to maintain CE marking access are simultaneously upgrading quality systems, creating demand for certified component suppliers and testing services.
- Carbon-fiber composite wrapping:Emergency medical services operators replacing steel cylinder fleets with 40-70% lighter alternatives are expanding procurement of high-pressure vessels for ambulance and helicopter deployment.
- Japan's super-aged society:METI reimbursement frameworks for home oxygen therapy sustain device utilization among COPD patients, with municipal governments subsidizing concentrator rentals for rural populations.
Market Restraints
- Zeolite molecular sieve supply concentration:Pressure swing adsorption concentrator production depends on specialized aluminosilicate materials sourced from limited chemical processing clusters in China and the United States.
- FDA 510(k) review timelines:Electromechanical device submissions face extended clearance periods as the agency prioritizes AI-enabled diagnostics, compressing revenue recognition for new portable concentrator launches.
- Stationary system substitution:Liquid oxygen delivery services retain cost advantages for high-flow, immobile patients in metropolitan areas with established distribution infrastructure.
Strategic Opportunities
- India's PLI scheme for medical devices:Domestic manufacturing incentives attract component assembly for portable concentrators targeting price-sensitive home healthcare segments in South Asia.
- Aviation-to-medical technology transfer:Military oxygen system engineering capabilities developed for hypoxia protection in fighter aircraft migrate to civilian pulse-dose delivery algorithms.
- Direct-to-consumer channel expansion:Online respiratory therapy platforms bypass durable medical equipment distributors, capturing margin compression from traditional procurement intermediaries.
Industry Challenges
- IEC 60601-1-2 electromagnetic compatibility testing:Portable concentrator manufacturers face repeated design iterations to achieve immunity certification against cellular and Wi-Fi interference in residential environments.
- Battery chemistry supply chain reconfiguration:Lithium-ion cell sourcing shifts from cylindrical to pouch formats for weight reduction, requiring thermal management system redesigns and supplier qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Oxygen Cylinders and Concentrators Market |
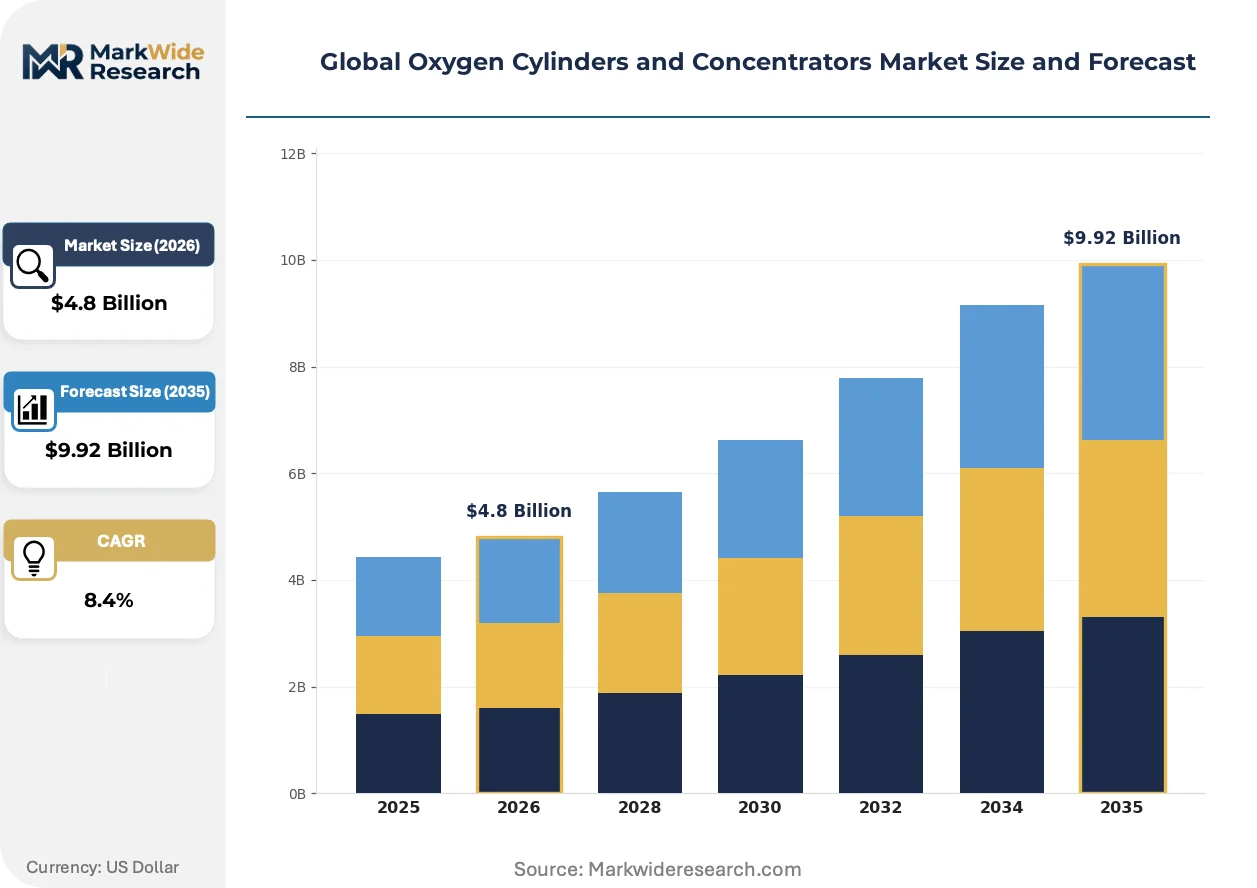
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.92 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Oxygen Concentrators, Stationary Oxygen Concentrators, Steel Cylinders, Aluminum Cylinders, Composite Cylinders Technology: Pressure Swing Adsorption, Membrane Separation, Cryogenic Distillation, Chemical Oxygen Generation Application: Home Oxygen Therapy, Emergency Medical Services, Chronic Obstructive Pulmonary Disease Treatment, Anesthesia Delivery, Veterinary Care End User: Hospitals, Clinics, Home Healthcare Providers, Ambulatory Surgery Centers, Long-Term Care Facilities |
| Companies Covered | Inogen, Inc., Koninklijke Philips N.V., CAIRE Inc., Chart Industries, Drive DeVilbiss Healthcare, ResMed, Invacare Corporation, Teijin Limited Company, Jiangsu Yuyue Medical Equipment & Supply Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Oxygen Cylinders and Concentrators Market Shifts & Advancements
Electrochemical oxygen generation and software-defined pulse dosing are compressing hardware differentiation cycles. Manufacturers now compete on algorithmic efficiency and remote monitoring integration rather than flow rate specifications alone.
Solid-state oxygen concentrator technology is electrifying portable device architectures by replacing compressor-driven pressure swing systems with ceramic ion transport membranes. Home healthcare agencies in Germany are piloting these units for nocturnal oxygen delivery, eliminating the acoustic footprint that drives patient non-compliance. The technology is electrifying competitive positioning by enabling overnight bedroom placement without sleep disruption, expanding addressable markets among ambulatory patients previously rejecting therapy.
EU MDR Article 10 technical documentation requirements are extending conformity assessment timelines for electromechanical respiratory devices. Manufacturers must now submit clinical evaluation reports with post-market surveillance data, elevating compliance costs for mid-tier suppliers. Stationary concentrator categories face the steepest documentation burden, with several firms withdrawing legacy models rather than completing gap analyses for renewed CE certificates.
Subscription-based oxygen service models are displacing capital equipment purchases among United States home healthcare networks. Regional providers in Texas and Florida are bundling device maintenance, remote monitoring, and consumable replenishment into per-patient monthly fees, transferring utilization risk to equipment lessors. This restructuring concentrates purchasing authority with national service platforms capable of underwriting inventory financing and predictive maintenance infrastructure.
Global Oxygen Cylinders and Concentrators Market Segmentation
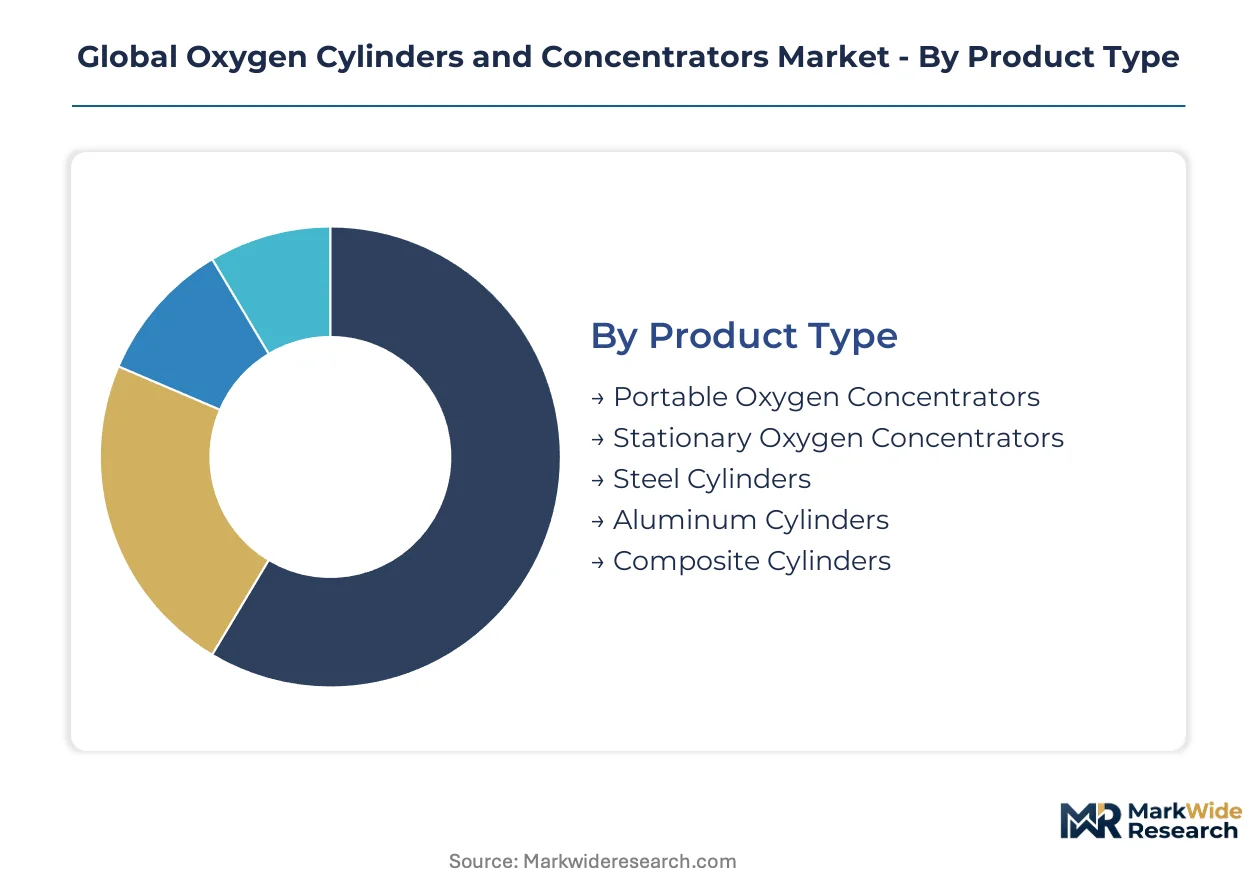
Segmentation in the oxygen device market reveals divergent capital requirements and margin profiles across hardware configurations. Procurement patterns vary sharply between institutional buyers optimizing for total cost of ownership and home healthcare providers prioritizing patient mobility and compliance.
Product Type:
Capital intensity escalates dramatically from metal cylinders to composite vessels and concentrator electronics, with pressure vessel certification and semiconductor-driven control systems demanding specialized manufacturing footprints.
- Portable Oxygen Concentrators:Battery-integrated electromechanical units employing pressure swing adsorption or emerging solid-state membranes. Demand concentrates among United States home healthcare providers as CMS reimbursement frameworks expand coverage for ambulatory COPD patients seeking mobility preservation.
- Composite Cylinders:Carbon-fiber wrapped aluminum liners rated for 300 bar service pressures. Emergency medical services operators in Germany and Japan are replacing steel fleets with 40-70% weight reductions, enabling helicopter hoist operations and stairway evacuations.
- Stationary Oxygen Concentrators:High-flow PSA systems for nocturnal and continuous delivery. METI-subsidized rental programs sustain installed base expansion across Japan's rural prefectures.
- Steel Cylinders:Legacy pressure vessels for institutional bulk storage and backup supply. Cost-sensitive clinics in India retain procurement preference despite weight penalties.
- Aluminum Cylinders:Intermediate-weight vessels for veterinary and intermediate-care applications. Moderate pressure ratings limit deployment to non-critical transport scenarios.
Stationary concentrators absorb the bulk of installed capacity; portable oxygen concentrators are expanding most quickly.
Technology:
Technology selection determines energy efficiency, purity thresholds, and scale economics, with membrane and cryogenic systems commanding premium positioning against dominant PSA architectures.
- Pressure Swing Adsorption:Zeolite molecular sieve systems cycling between adsorption and desorption beds. Dominates portable and stationary concentrator manufacturing due to proven reliability and moderate power consumption profiles.
- Cryogenic Distillation:Liquid oxygen production through fractional distillation of compressed air. Industrial gas majors leverage existing air separation infrastructure to supply high-volume hospital contracts.
- Membrane Separation:Polymeric hollow-fiber modules separating oxygen via differential permeability. Compact military aviation systems are migrating to civilian pulse-dose applications.
- Chemical Oxygen Generation:Sodium chlorate candles and potassium superoxide canisters. Aviation emergency systems and mine rescue kits sustain niche demand despite single-use economics.
Pressure swing adsorption retains dominant share; membrane separation is gaining share fastest in portable device architectures.
Application:
Application segmentation tracks reimbursement eligibility and clinical workflow integration, with chronic disease management programs driving recurring revenue against episodic emergency deployment.
- Home Oxygen Therapy:Long-term oxygen delivery for COPD, interstitial lung disease, and pulmonary hypertension. United States regional providers in Texas and Florida are consolidating into subscription service models bundling equipment and remote monitoring.
- Emergency Medical Services:Pre-hospital oxygen delivery for trauma, cardiac arrest, and respiratory failure. Carbon-fiber cylinder procurement accelerates as ambulance services seek weight reduction for paramedic ergonomics.
- Chronic Obstructive Pulmonary Disease Treatment:Disease-specific protocols emphasizing nocturnal and exertional oxygen supplementation. Germany's disease management programs integrate concentrator prescribing with pulmonary rehabilitation.
- Anesthesia Delivery:Operating room and procedural sedation oxygen sources. Hospital procurement favors centralized liquid oxygen piped systems for cost efficiency.
- Veterinary Care:Companion animal and livestock oxygen therapy. Small-animal emergency clinics drive portable concentrator adoption for transport ventilation.
Home oxygen therapy captures the largest addressable population; emergency medical services shows the steepest expansion trajectory for lightweight cylinder technologies.
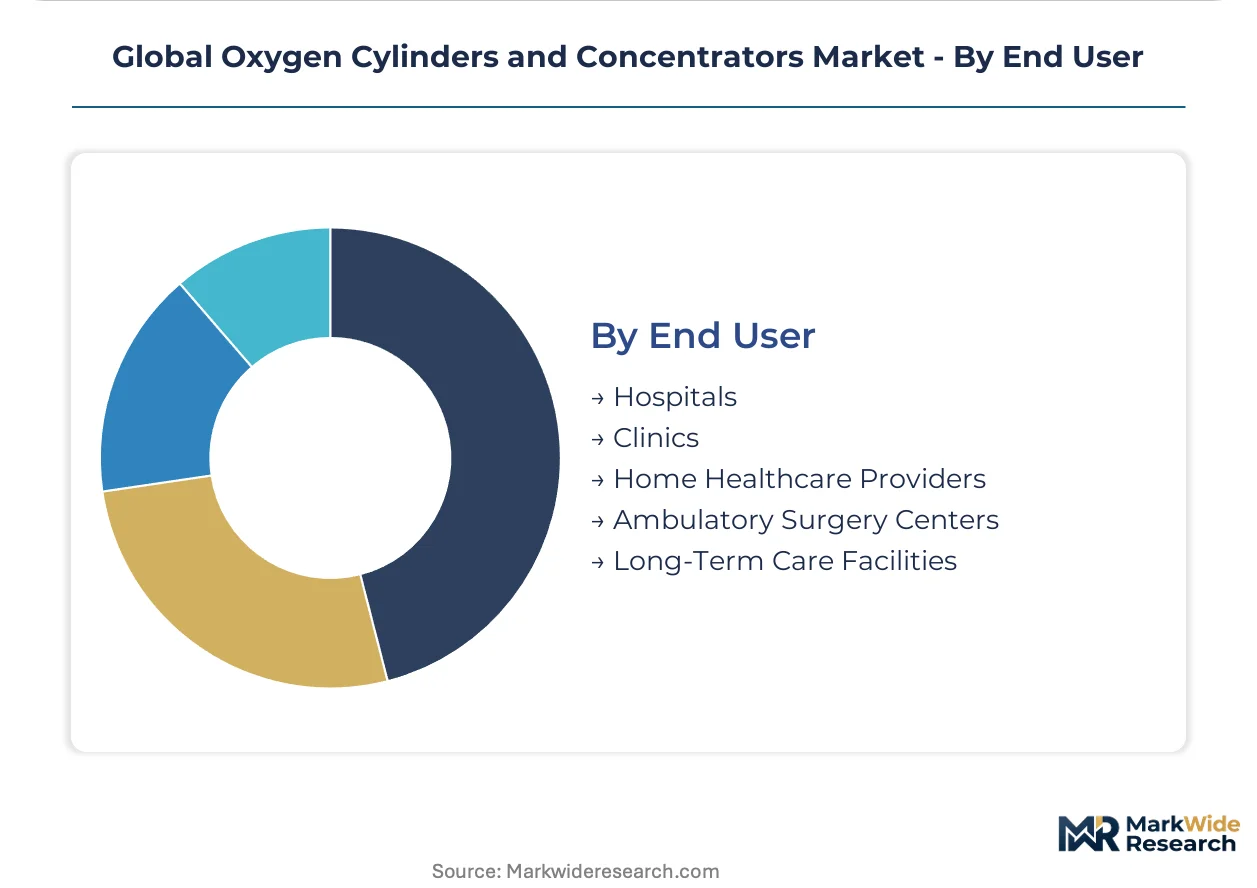
End User:
End-user concentration shapes sales channel economics, with hospital group purchasing organizations extracting volume discounts while home healthcare platforms invest in patient onboarding and compliance monitoring.
- Home Healthcare Providers:Decentralized post-acute care networks managing oxygen therapy outside institutional settings. United States platforms are capturing margin compression from traditional durable medical equipment distributors through direct-to-consumer channels.
- Hospitals:Acute care institutions with centralized oxygen infrastructure and emergency backup requirements. EU MDR compliance deadlines are extending procurement cycles for electromechanical respiratory devices.
- Clinics:Outpatient facilities with limited capital budgets and intermittent oxygen needs. India's PLI scheme for medical devices attracts component assembly targeting price-sensitive segments.
- Ambulatory Surgery Centers:Same-day procedure facilities requiring compact anesthesia and recovery oxygen systems. Rapid turnover demands favor portable concentrator rentals over fixed infrastructure.
- Long-Term Care Facilities:Skilled nursing and assisted living residences with aging resident populations. Staffing constraints drive preference for low-maintenance stationary concentrators over cylinder changeout protocols.
Hospitals retain the deepest installed base; home healthcare providers are climbing the fastest as reimbursement shifts toward decentralized delivery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shenzhen and Bangalore concentrate contract manufacturing for portable concentrator electronics, while FDA 510(k) clearance timelines and EU MDR technical documentation obligations reshape competitive access across major demand centers.
United States
CMS reimbursement frameworks for home oxygen therapy sustain device utilization among COPD patients, with regional providers in Texas and Florida consolidating into subscription service models. FDA 510(k) clearance timelines for electromechanical respiratory devices have extended as the agency prioritizes AI-enabled diagnostics. Goleta, California hosts engineering clusters developing pulse-dose delivery algorithms for ambulatory applications.
Germany
Disease management programs integrate concentrator prescribing with pulmonary rehabilitation, while emergency medical services operators replace steel cylinder fleets with carbon-fiber alternatives. EU MDR Article 10 technical documentation requirements extend conformity assessment timelines for electromechanical respiratory devices. North Rhine-Westphalia hosts industrial gas majors leveraging existing air separation infrastructure for hospital contracts.
Japan
METI reimbursement frameworks for home oxygen therapy sustain device utilization among COPD patients in the super-aged society, with municipal governments subsidizing concentrator rentals for rural populations. PMDA quality management requirements align with international standards for device registration. Osaka-Kobe manufacturing clusters produce zeolite molecular sieves for pressure swing adsorption systems.
India
Domestic manufacturing incentives under the PLI scheme for medical devices attract component assembly for portable concentrators targeting price-sensitive home healthcare segments. CDSCO medical device rules establish risk-based classification for oxygen delivery products. Karnataka's medical technology corridor near Bangalore concentrates contract electronics manufacturing for concentrator control systems.
China
NMPA medical device registration requirements and GB standards for oxygen equipment shape market access for domestic and imported concentrators. MIIT industrial policies support domestic production of pressure swing adsorption components. Shenzhen special economic zone hosts contract manufacturers supplying battery management systems for portable oxygen devices.
Global Oxygen Cylinders and Concentrators Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across technology tiers, with the market structure consolidating around respiratory therapy ecosystems and component supply chains. Strategic archetypes include diversified health technology conglomerates with sleep and respiratory portfolios, pure-play portable concentrator specialists with direct-to-consumer channels, and industrial gas majors with cryogenic infrastructure. Competitive moves center on M&A for patient monitoring software capabilities and vertical integration into zeolite molecular sieve supply.
Among diversified health technology conglomerates, Koninklijke Philips N.V. and ResMed exemplify archetypes bundling software-enabled monitoring with hardware platforms. Inogen, Inc. represents the pure-play specialist model focused on portable concentrator lightweighting through direct channels. CAIRE Inc. anchors a position spanning military aviation oxygen systems and civilian medical applications. These three companies illustrate the competitive spectrum from integrated health ecosystems to focused device engineering and dual-use technology migration.
| Leading Market Players |
|---|
| Inogen, Inc. |
| Koninklijke Philips N.V. |
| CAIRE Inc. |
| Chart Industries |
| Drive DeVilbiss Healthcare |
| ResMed |
| Invacare Corporation |
| Teijin Limited Company |
| Jiangsu Yuyue Medical Equipment & Supply Co., Ltd. |
| Others |
Supply & Pricing Matrix
Home healthcare provider consolidation into subscription service platforms concentrates procurement authority and anchors pricing around per-patient monthly fees rather than capital equipment transactions. This shift transfers utilization risk to equipment lessors while compressing margins for traditional durable medical equipment distributors.
Pricing Analysis
Short lead-time premiums apply to portable oxygen concentrator orders from United States regional providers facing CMS reimbursement deadlines, while spot inventory of legacy steel cylinders trades at discounts in India's price-sensitive clinic segment. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared portable units with remote monitoring from basic stationary concentrators and uncertified refurbished equipment. Price differentiation hinges on ISO 13485 certification tier and after-sales service bundling. Cost compression in the standard tier is intensifying because lithium-ion battery chemistry reconfiguration demands thermal management system redesigns. India's clinic segment exhibits highest price sensitivity; Japan's METI-subsidized rural rental programs show lowest.
Supply Chain Analysis
Regional distribution centers in Shenzhen and Bangalore concentrate contract manufacturing for portable concentrator electronics and battery management systems before hub-and-spoke deployment to United States and European home healthcare networks. Zeolite molecular sieve production clusters in China and the United States feed pressure swing adsorption concentrator assembly, while carbon-fiber prepeg for composite cylinders sources from Japan and Germany. Single-source vulnerability in specialized aluminosilicate materials creates chokepoint exposure. Distribution runs through national service platforms capable of underwriting inventory financing and predictive maintenance infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Zeolite molecular sieve supply concentration props pricing power for incumbent concentrator manufacturers while constraining capacity expansion for new entrants. This supply-constrained structure favors players with captive sieve supply or established supplier qualification.
For Market Incumbents: Lock in backward integration into zeolite molecular sieve supply or long-term offtake agreements with Osaka-Kobe and United States chemical processing clusters to defend against emerging solid-state membrane substitution threats. Prioritize IEC 60601-1-2 electromagnetic compatibility certification investment to maintain hospital procurement access as EU MDR deadlines extend conformity assessment timelines.
For New Entrants and Emerging Players: Solid-state oxygen concentrator technology offers a technology-first wedge into Germany's nocturnal oxygen therapy pilot programs where acoustic footprint elimination drives patient compliance. Target India's PLI-subsidized component assembly for portable concentrators as the most penetrable geography, leveraging Karnataka's medical technology corridor for control system manufacturing. Pursue direct-to-consumer channel partnerships with online respiratory therapy platforms to bypass distributor margin compression.
For Investors and Strategic Acquirers: The window for entry favors pure-play portable concentrator specialists with direct-to-consumer infrastructure and FDA 510(k) clearance track records. Long-term viability centers on software-enabled remote monitoring capabilities that bundle algorithmic efficiency with hardware sales. Watch for PMDA reimbursement rate adjustments as the inflection indicator for Japan's super-aged society demand trajectory.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Completion | CE marking retention opens continued access to German disease management programs and hospital procurement. |
| Zeolite Molecular Sieve Supply Agreement | Captive sieve sourcing secures pressure swing adsorption concentrator production against single-source vulnerability. |
| Solid-State Membrane Pilot Deployment | German nocturnal therapy trials validate acoustic elimination for bedroom placement expansion. |
| Direct-to-Consumer Platform Launch | Online respiratory therapy channels capture margin compression from traditional durable medical equipment distributors. |
| Battery Chemistry Format Transition | Pouch cell adoption enables portable concentrator lightweighting for emergency medical services procurement. |
Research Methodology
Document review covered FDA 510(k) filings, EU MDR technical documentation databases, CMS Medicare reimbursement schedules, and METI home oxygen therapy subsidy records, complemented by interviews with biomedical engineers, hospital GPO contracts managers, home healthcare procurement directors, and zeolite molecular sieve chemical processing executives. Secondary validation drew from ISO certification registries, IEC electromagnetic compatibility test reports, and PLI scheme beneficiary disclosures. Bottom-up concentrator shipment estimates triangulated against top-down healthcare expenditure allocations.
Cross-referencing historical reimbursement rate adjustments with panel input from pulmonary rehabilitation clinicians anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product configuration, technology architecture, application workflow, and end-user procurement authority. CAGRs derived from installed base replacement cycles and ambulatory patient mobility preference shifts. Forecast inputs incorporated CMS coverage expansion trajectories and carbon-fiber cylinder fleet conversion timelines.
Several conditions sit outside the modeled scope, including unannounced FDA guidance document revisions, geopolitical disruption to China-United States zeolite trade flows, and breakthrough solid-state oxygen generation commercialization. Forecasts reflect stated assumptions on reimbursement stability and certification timeline continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Keratoprosthesis (Kpro) Market
Medical Devices
Non-Invasive Intracranial Pressure Monitoring Device Market
Medical Devices
Genitourinary Prosthetics Market
Medical Devices
Global Cardiopulmonary Bypass Accessory Equipment Market
Medical Devices
Gel Implants Market
Medical Devices
United Arab Emirates Drug Delivery Devices Market
Medical Devices
Global Coagulation-Hemostasis Analyzer Market
Medical Devices
Spinal Thoracolumbar Implants Market
Medical Devices
United States Anesthesia Devices Market
Medical Devices
Global Medical Loupes Market
Medical Devices
Medical Manifolds Market
Medical Devices
Global Emerging Mental Health Devices and Platforms Market
Medical Devices
Breast Pump Flange Market
Medical Devices
Collateral Ligament Stabilizers Market
Medical Devices
Europe C-Arms Market
Medical Devices
Intraocular Lens (IOL) Market