
 Lung Preservation Systems Market | 2026-2036
Lung Preservation Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Lung Preservation Systems Market Analytics
Extracorporeal membrane oxygenation components are expanding their presence within integrated perfusion circuits, reducing reliance on static cold storage for marginal donor lungs. XVIVO Perfusion AB leverages its proprietary warm perfusion technology to dominate the European clinical landscape. Transmedics, Inc. sustains competitive intensity through its Organ Care System platform and direct hospital contracting. Paragonix Technologies differentiates via specialized cold storage devices with real-time temperature telemetry.
Lung preservation systems encompass devices, solutions, and biochemical agents designed to maintain donor organ viability during procurement, transport, and pre-implantation assessment, typically operating at hypothermic or normothermic temperatures with controlled oxygenation and perfusion flow rates to prevent ischemia-reperfusion injury. The primary commercial purpose centers on extending allowable preservation time while preserving graft function for successful transplantation. Machine perfusion systems command premium positioning due to their ability to assess and rehabilitate extended-criteria donor lungs that static methods would discard. Preservation solutions and biochemical agents occupy stable, recurring revenue positions tied to procedural volume rather than capital equipment cycles. Research institutions represent a faster-growing end-user segment as ex-vivo lung perfusion expands into therapeutic delivery and graft modification protocols.
FDA premarket notification requirements and ongoing IDE study obligations shape product development timelines and clinical evidence thresholds for US commercial entry. EMA medical device regulations and notified body conformity assessments govern European market access, with MDR transition intensifying documentation burdens for perfusion system manufacturers. ISO 14155 clinical investigation standards and WHO Guiding Principles on human cell, tissue, and organ transplantation provide additional compliance frameworks. Stakeholders must monitor evolving regulatory science around normothermic regional perfusion and the potential reclassification of ex-vivo perfusion as a therapeutic intervention rather than preservation.
Market Dynamics
Machine perfusion technology is compressing procurement timelines for marginal donor lungs while FDA clearance pathways accelerate commercialization velocity for novel preservation platforms.
Growth Catalysts
- Extended-criteria donor utilization:Machine perfusion systems rehabilitate lungs previously discarded under static cold storage protocols. Transplant centers in Germany deploy these platforms to expand viable donor pools.
- IDE study obligations:FDA investigational device exemption frameworks generate clinical evidence thresholds that validate product efficacy. This regulatory pathway accelerates US market entry for perfusion device manufacturers.
- Ex-vivo therapeutic delivery:Research institutions pioneer graft modification protocols during normothermic perfusion. This application expansion drives capital equipment demand beyond traditional preservation use cases.
Market Restraints
- Capital equipment intensity:Machine perfusion platforms require substantial upfront investment and dedicated perfusionist staffing. Smaller transplant centers face barriers to adoption.
- Supply concentration in proprietary consumables:Perfusion circuits and preservation solutions tie users to single-source suppliers. This dependency limits price negotiation leverage for hospital procurement departments.
- Technical limitation in warm perfusion duration:Current normothermic systems maintain viability windows that remain shorter than theoretical limits. Extended preservation beyond twelve hours risks graft dysfunction.
Strategic Opportunities
- Underpenetrated US transplant centers:Mid-volume programs in the United States lack machine perfusion capability. Direct hospital contracting models can capture this whitespace.
- EMA MDR transition tailwinds:Stricter European conformity assessments favor established manufacturers with robust quality systems. This regulatory burden disadvantages smaller competitors.
- Biochemical agent convergence:Preservation solutions incorporating targeted anti-inflammatory compounds integrate with perfusion hardware. This combination therapy approach commands premium positioning.
Industry Challenges
- Perfusionist workforce scarcity:Specialized clinical expertise required for normothermic system operation outpaces training program output. Transplant programs compete for limited qualified personnel.
- Legacy cold storage integration:Hybrid workflows combining static and perfusion methods create logistical complexity. Hospital organ procurement organizations must reconfigure transport protocols.
- ISO 14155 compliance timelines:Clinical investigation standards for perfusion device studies extend development cycles. Documentation burdens delay product iterations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lung Preservation Systems Market |
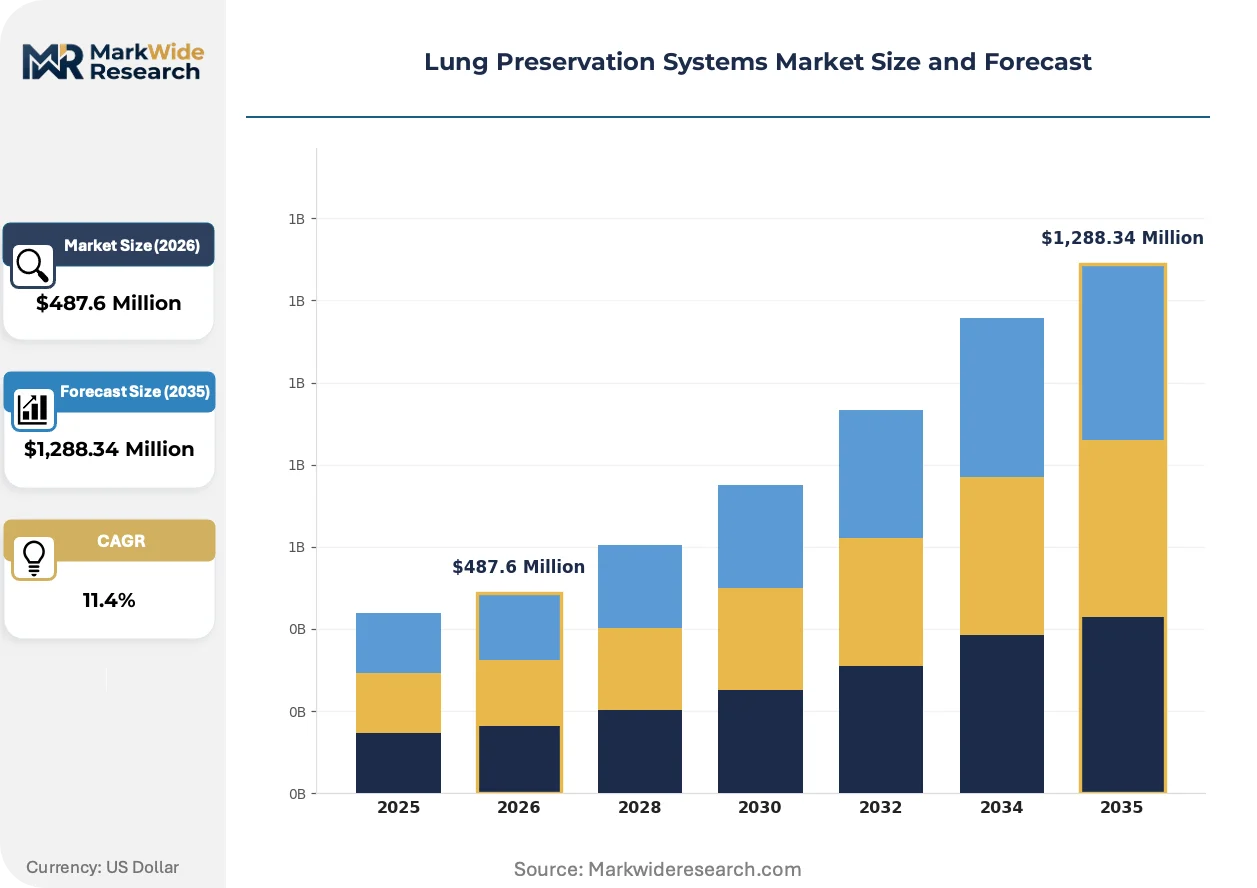
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cold Storage Solutions, Machine Perfusion Systems, Preservation Solutions, Biochemical Agents End User: Transplant Centers, Hospitals, Research Institutions, Biobanks Technology: Static Preservation, Dynamic Preservation, Oxygenation Techniques, Hypothermic Storage Application: Lung Transplants, Research & Development, Organ Logistics, Clinical Trials |
| Companies Covered | Transmedics, Inc., XVIVO Perfusion AB, Organ Recovery Systems, Paragonix Technologies, Dr. Franz Köhler Chemie GmbH, Waters Medical Systems LLC, Preservation Solutions, Inc., Bridge to Life Ltd., BioLife Solutions, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lung Preservation Systems Market Evolving Landscape
Integrated telemetry systems and biochemical sensor arrays are transforming how transplant teams assess graft viability during preservation. These innovations compress decision windows and reduce uncertainty.
Normothermic regional perfusion is electrifying procurement protocols for donation after circulatory death lungs. Organ procurement organizations in Spain and the Netherlands adopt this technique to expand donor pools. The approach enables functional assessment previously impossible under hypothermic conditions.
FDA premarket notification requirements for novel preservation devices are intensifying clinical evidence standards. Manufacturers must complete larger pivotal studies before commercial authorization. This regulatory elevation favors firms with established investigational infrastructure and hospital investigator networks.
Hospital procurement departments are unbundling after-sales service from capital equipment contracts. Transplant centers negotiate separate technical support agreements based on case volume. This purchasing pattern shift is most visible in United States academic medical centers with dedicated perfusion teams.
Lung Preservation Systems Market Segmentation
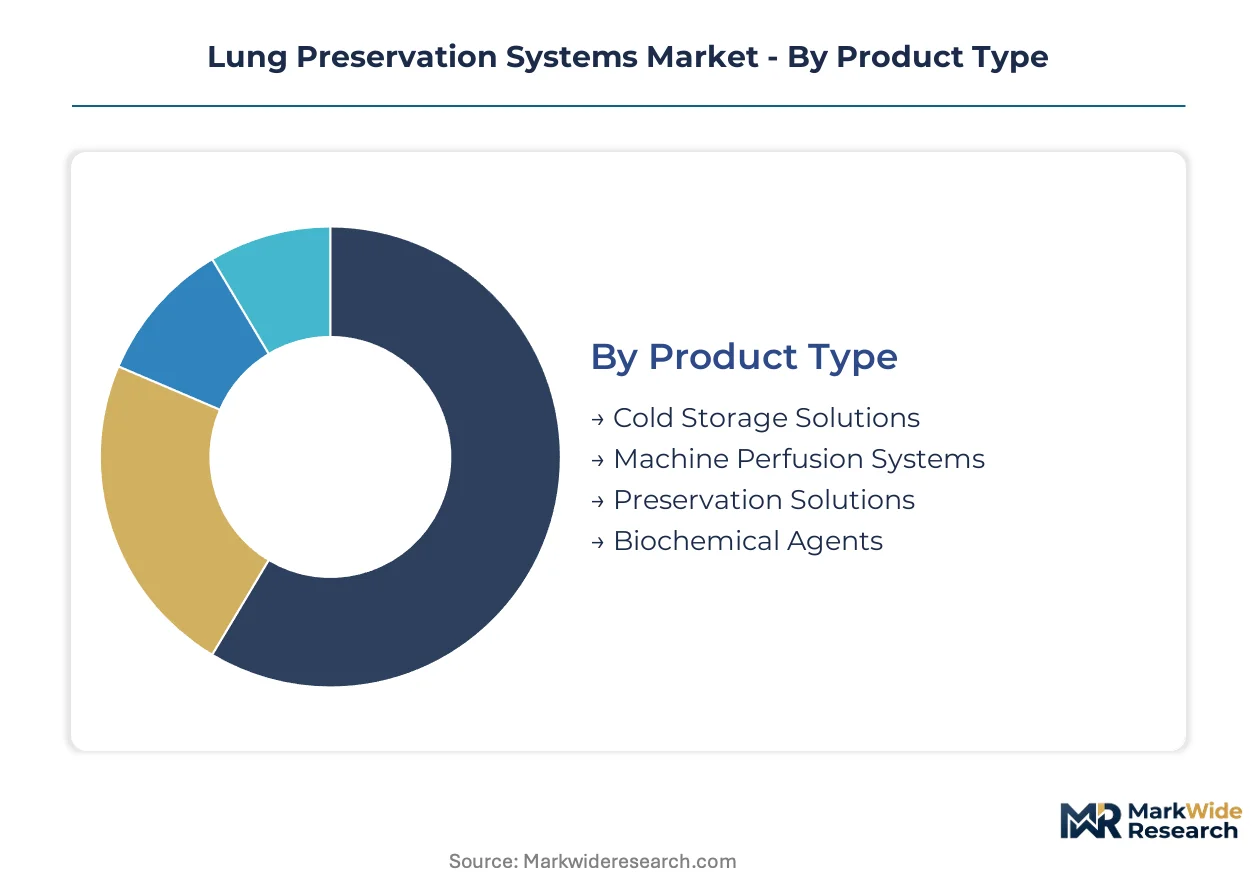
Segmentation in lung preservation systems reflects distinct procurement patterns across capital equipment, consumables, and service models. Transplant centers weight technology choices against case volume, while research institutions prioritize experimental flexibility over clinical throughput.
Product Type:
Standalone capital platforms dominate high-value procurement cycles, while embedded consumables generate recurring revenue streams tied to procedural volume.
- Machine Perfusion Systems:Integrated platforms combining pumps, oxygenators, and monitoring arrays enable normothermic preservation with real-time functional assessment. Demand concentrates in German transplant centers expanding extended-criteria donor programs; these systems command premium positioning through rehabilitation capabilities that static methods cannot replicate.
- Cold Storage Solutions:Specialized containers with integrated temperature telemetry maintain hypothermic conditions during transport. Procurement departments in United States academic medical centers favor these devices for standard-criteria donors where perfusion infrastructure remains uneconomical.
- Preservation Solutions:Proprietary buffer formulations prevent cellular edema and acidosis during ischemic intervals.
- Biochemical Agents:Targeted anti-inflammatory compounds and surfactant supplements address specific graft injury mechanisms.
Volume placements concentrate in Cold Storage Solutions; the faster expansion belongs to Machine Perfusion Systems.
End User:
Customer archetypes diverge sharply between clinical throughput maximizers and experimental protocol developers.
- Transplant Centers:High-volume surgical programs drive equipment standardization around perfusion platforms capable of marginal donor rehabilitation. United States centers with annual volumes exceeding fifty procedures justify dedicated perfusionist staffing and captive machine inventory.
- Research Institutions:Academic laboratories pioneer ex-vivo therapeutic delivery and graft modification protocols during normothermic perfusion. These users prioritize system flexibility over regulatory clearance speed, expanding applications beyond traditional preservation boundaries.
- Hospitals:General medical centers with occasional transplant activity rely on shared regional perfusion resources or third-party organ procurement organization services.
- Biobanks:Tissue repositories utilize specialized hypothermic storage for research specimen archiving rather than clinical transplantation.
Transplant Centers capture the dominant placement share; Research Institutions are climbing the fastest.
Technology:
Preservation modality selection hinges on donor quality, transport distance, and institutional technical capability.
- Dynamic Preservation:Continuous perfusion with nutrient-enriched solutions maintains cellular metabolism and enables functional assessment. German and Dutch procurement networks deploy these systems for donation after circulatory death lungs where warm ischemia demands active intervention.
- Static Preservation:Simple hypothermic immersion in preservation solution remains the default for standard-criteria donors with minimal ischemic time. Smaller United States transplant programs continue reliance on this approach due to capital constraints and perfusionist scarcity.
- Oxygenation Techniques:Membrane oxygenator configurations vary between extracorporeal membrane oxygenation circuits and integrated perfusion platforms.
- Hypothermic Storage:Temperature reduction to four to eight degrees Celsius slows metabolic demand without active perfusion support.
Static Preservation retains volume leadership; Dynamic Preservation shows the steepest expansion trajectory.
Application:
Use case segmentation separates revenue-stable clinical procedures from faster-growing experimental domains.
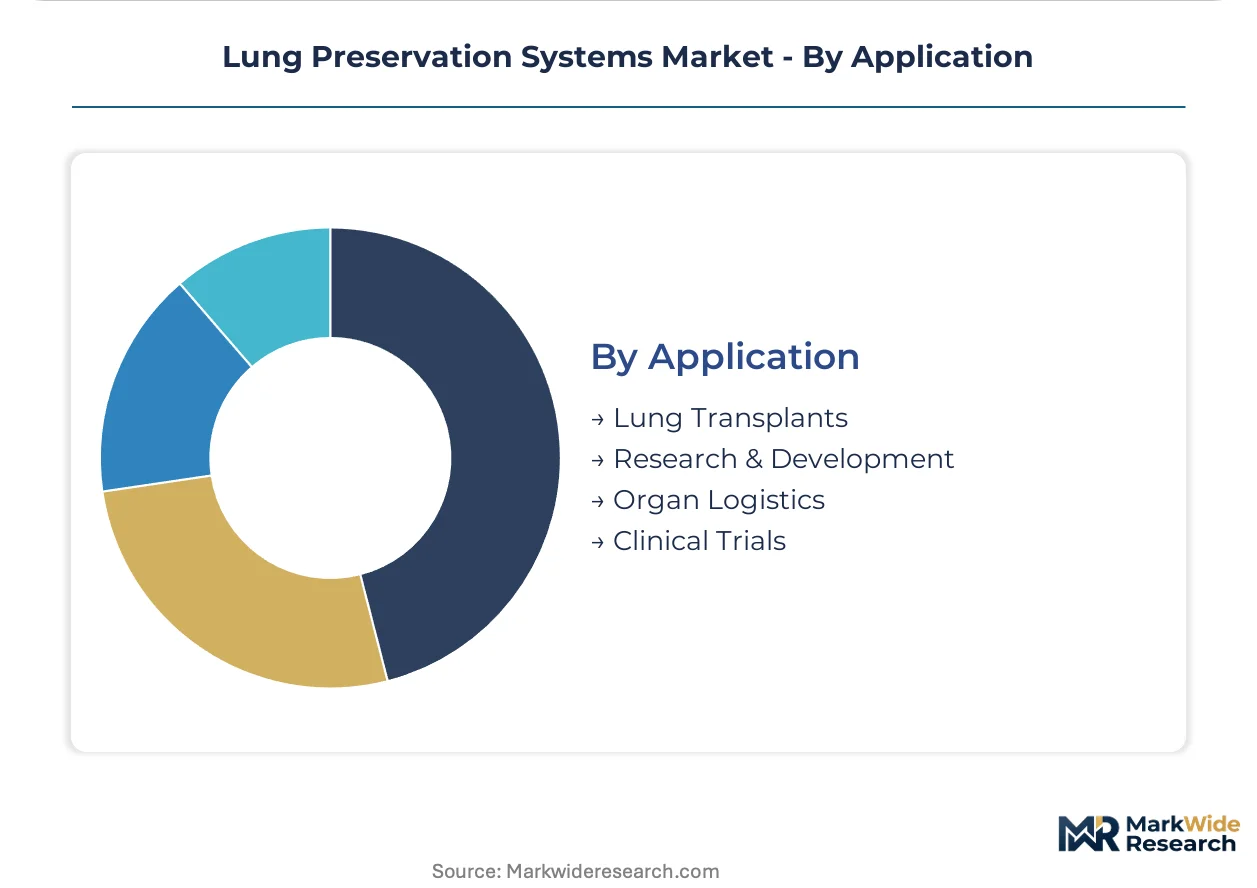
- Lung Transplants:Clinical transplantation generates recurring demand tied to donor availability and waiting list dynamics. German centers lead European adoption of perfusion-assisted procedures, while United States programs concentrate in academic medical centers with established thoracic surgery divisions.
- Research & Development:Ex-vivo platforms enable therapeutic delivery, gene editing, and immunomodulation studies on intact grafts. Research institutions in the Netherlands and Spain pioneer normothermic regional perfusion protocols that expand donor pool eligibility criteria.
- Organ Logistics:Transport and coordination services require portable preservation systems compatible with air and ground ambulance configurations.
- Clinical Trials:Investigational device exemption studies for novel perfusion platforms generate temporary demand spikes at qualified sites.
Lung Transplants anchor current volume; Research & Development is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized medical device tax incentives in the United States concentrate lung preservation technology development in established transplant corridors. German university hospitals anchor European adoption through integrated procurement networks. Japanese regulatory pathways for perfusion devices create distinct commercialization timelines.
United States
FDA investigational device exemption frameworks accelerate clinical validation for novel perfusion platforms. Academic medical centers in Massachusetts and North Carolina drive machine perfusion adoption through established thoracic surgery divisions. Transplant volume concentration in the Northeast Corridor justifies dedicated perfusionist staffing and captive equipment inventory.
Germany
High annual lung transplant volumes and established organ procurement networks concentrate demand for extended-criteria donor rehabilitation systems. EMA MDR transition intensifies conformity assessment documentation for perfusion device manufacturers. University hospitals in Bavaria and North Rhine-Westphalia deploy normothermic regional perfusion protocols for donation after circulatory death lungs.
Netherlands
Organ procurement organizations pioneer normothermic regional perfusion techniques to expand donor pool eligibility. Dutch transplant centers collaborate with Spanish counterparts on cross-border perfusion protocol standardization. Research institutions in Rotterdam and Amsterdam develop ex-vivo therapeutic delivery applications beyond traditional preservation boundaries.
Japan
PMDA medical device review pathways shape product development timelines for perfusion system manufacturers. Domestic transplant centers balance adoption of foreign platforms against national technology development priorities. Tokyo and Osaka metropolitan hospital networks concentrate specialized perfusionist training programs.
Spain
High donation rates and established organ procurement infrastructure create favorable conditions for advanced preservation technology deployment. Regional health authorities in Catalonia and Madrid coordinate multicenter perfusion protocol evaluations. Spanish transplant programs contribute clinical evidence to EMA regulatory science initiatives on normothermic preservation classification.
Lung Preservation Systems Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated platform developers commanding premium positioning against component suppliers. The vendor base organizes around three strategic archetypes: full-system perfusion platform developers, specialized cold storage device fabricators, and proprietary solution formulators. Consolidation pressures favor manufacturers with captive investigational infrastructure and established hospital investigator networks. Competitive moves concentrate on direct hospital contracting models and unbundled service agreements.
Among Swedish and US-based platform developers, XVIVO Perfusion AB and Transmedics, Inc. occupy positions exemplifying the integrated-system archetype, while Paragonix Technologies represents the specialized-device tier. These anchors illustrate how geographic origin and company structure correlate with strategic positioning: the Swedish entity leverages European clinical validation networks, the US corporation exploits FDA pathway familiarity, and the technology-focused firm targets procurement department preferences for telemetry-enabled transport solutions.
| Leading Market Players |
|---|
| Transmedics, Inc. |
| XVIVO Perfusion AB |
| Organ Recovery Systems |
| Paragonix Technologies |
| Dr. Franz Köhler Chemie GmbH |
| Waters Medical Systems LLC |
| Preservation Solutions, Inc. |
| Bridge to Life Ltd. |
| BioLife Solutions, Inc. |
| Others |
Value Network & Pricing Analysis
EU MDR conformity assessment requirements gate qualified supply access and premium-tier pricing power for perfusion device manufacturers, compressing margins for non-compliant vendors while elevating cleared platforms to premium positioning. Transplant centers in Germany and the Netherlands absorb these compliance costs through bundled service contracts that unbundle hardware from consumable pricing.
Pricing Analysis
Short lead-time premiums for perfusion circuit replenishment and spot-inventory discounts for standard preservation solutions structure transactional dynamics across procurement tiers. Three-tier pricing structure across premium, standard, and economy levels segments by FDA clearance status and ISO 14155 clinical validation depth. Price differentiation hinges on after-sales service bundling and perfusionist training inclusion. Pricing pressure stems from hospital procurement departments unbundling technical support from capital equipment. Mid-volume transplant centers in the United States exhibit highest price sensitivity; academic medical centers with captive perfusion teams demonstrate lowest.
Supply Chain Analysis
Regional distribution centers in Germany, the Netherlands, and Massachusetts anchor hub-and-spoke patterns for machine perfusion platforms and consumable replenishment. Component sourcing draws from Sweden for pump assemblies, the United States for membrane oxygenators, and Germany for sensor arrays. Single-source vulnerability concentrates in proprietary perfusion circuit suppliers. Distribution runs through hospital system GPO contracts and direct manufacturer agreements with transplant center procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where FDA IDE study infrastructure and EMA MDR quality systems create barrier-to-entry moats that favor capitalized incumbents over underfunded challengers.
For Market Incumbents: Acquire perfusionist training program assets and captive clinical investigation sites to lock hospital investigator networks. XVIVO Perfusion AB and Transmedics, Inc. should deepen backward integration into membrane oxygenator manufacturing to offset single-source supplier risk. Certification investment in ISO 14155-compliant study infrastructure defends against emerging platform developers with faster regulatory pathways. For New Entrants and Emerging Players: The premium-to-economy price-point gap in cold storage telemetry devices opens whitespace for mid-tier entrants with CE-marked alternatives to Paragonix Technologies. Target mid-volume United States transplant centers lacking dedicated perfusionist staffing as the most penetrable segment. Go-to-market through regional organ procurement organization service contracts bypasses direct hospital capital committee barriers. For Investors and Strategic Acquirers: FDA breakthrough device designation grants for normothermic regional perfusion platforms are the leading indicator that reimbursement pathways and commercial velocity will accelerate for compliant manufacturers. Long-term viability centers on ex-vivo therapeutic delivery expansion beyond preservation into graft modification. Acquisition target archetype: European perfusion device developers with EMA MDR technical documentation nearing completion. Watch for PMDA regulatory harmonization signals in Japan as inflection indicator for Asia-Pacific market opening.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Direct contracting with German university hospitals secures extended-criteria donor rehabilitation volume. |
| FDA Breakthrough Device Pathway | Accelerated review timelines compress commercialization cycles for normothermic perfusion platforms. |
| CE Marking Pathway Expansion | MDR technical documentation investment blocks smaller competitors from European market access. |
| Perfusionist Training Program Acquisition | Captive clinical expertise pipelines reduce staffing scarcity constraints for transplant centers. |
| Reimbursement Strategy Development | CPT code establishment for ex-vivo lung perfusion procedures unlocks hospital budget allocation. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with transplant surgeons, perfusionists, hospital procurement managers, and biomedical engineers. FDA 510(k) databases, EMA medical device registration systems, and hospital GPO contract repositories provided validation benchmarks. Bottom-up modeling of procedure volumes and equipment placements triangulated against top-down market sizing from capital equipment shipment records.
Granularity-level framing applied product-type segmentation at the SKU level for machine perfusion systems and preservation solutions, with end-user splits modeled at the institutional level for transplant centers versus research institutions. Technology modality and application use-case dimensions were projected across the analysis window using procedure-volume-linked CAGRs. Forecast inputs incorporated donor availability trends, waiting list dynamics, and regulatory approval velocity for novel perfusion platforms.
Inputs from FDA PMA and EMA CE marking databases were available through the study window; gaps in real-time hospital procurement transaction data introduce uncertainty bands around equipment placement timing. Forecasts reflect documented assumptions regarding regulatory pathway durations and reimbursement adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Zygomatic and Pterygoid Implants Market
Medical Devices
Light Therapy Beauty Devices Market
Medical Devices
Global Cast Saw Devices Market
Medical Devices
Actigraphy Sensors and Polysomnography Devices Market
Medical Devices
EMEA Surgical Microscopes Market
Medical Devices
Anesthesia Circuits Market
Medical Devices
Meniscal Rasps Market
Medical Devices
Europe Ambulatory Infusion Pumps Market
Medical Devices
Lower Limb Prosthetics Market
Medical Devices
Heat Therapy Units Market
Medical Devices
Interphalangeal Fusion Market
Medical Devices
Italy Ophthalmic Devices Market
Medical Devices
Medical Devices Clinical Trials Market
Medical Devices
Global Voice Prosthesis Devices Market
Medical Devices
Medical Oxygen Sensors Market
Medical Devices
Global Angioplasty Balloons Market