
 Outdoor Solar LED Market | 2026-2036
Outdoor Solar LED Market Size, Share, and Industry Trends Forecast 2026-2036
Outdoor Solar LED Market Intelligence
Chinese manufacturing dominance is decoupling the cost of polycrystalline panels from regional project economics and timelines. Signify Holding leverages its extensive distribution network for large-scale commercial deployments. SOKOYO Solar Lighting Co., Ltd. competes on high-volume production for global export markets. In contrast, Sunna Design specializes in intelligent and connected solar lighting systems for advanced smart city applications.
Outdoor solar LED systems integrate a photovoltaic panel, a rechargeable battery, and a light-emitting diode luminaire into a single autonomous unit. These systems are designed for off-grid operation, typically featuring dusk-to-dawn sensors and specific IP ratings for weather resistance. While street lamps constitute a major product type, garden and pathway lights represent the fastest-growing segment for residential applications. Monocrystalline technology leads in efficiency, commanding a premium, whereas polycrystalline options provide a cost-effective solution for large-scale municipal projects.
Government incentives and standards, including the EU Green Deal and China's dual carbon goals, mandate energy-efficient public infrastructure. Product safety and performance are governed by certifications like CE marking in Europe and compliance with GB standards in China. These frameworks directly influence component sourcing and market access for manufacturers. The key decision for end users now centers on balancing upfront capital investment against long-term operational savings and sustainability goals.
Market Dynamics
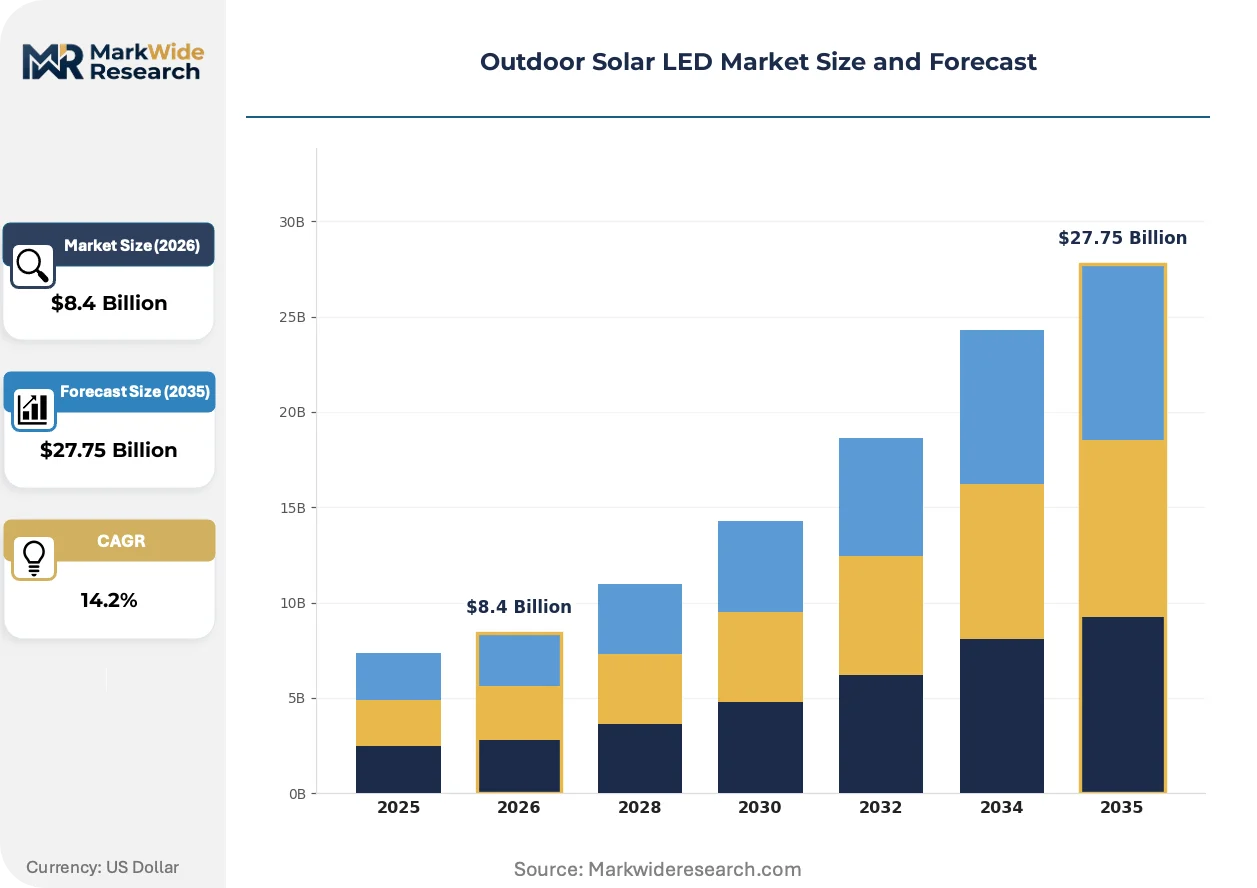
Demand from municipal authorities for energy-independent public lighting, especially for rural electrification, is the central force shaping the market. This creates a direct pull for autonomous, weather-resistant systems for public parks and streets.
Growth Catalysts
- Supportive Government Policies:The EU Green Deal and China's dual carbon goals mandate energy-efficient public infrastructure, creating direct demand for solar installations.
- Monocrystalline Panel Efficiency:Higher energy conversion rates from monocrystalline technology enable more powerful and reliable lighting, justifying their use in demanding applications.
- Rural Electrification:Projects in India and sub-Saharan Africa create concentrated demand for cost-effective systems to illuminate remote communities.
Market Restraints
- Upfront Capital Investment:The high initial purchase cost remains a primary barrier for municipalities with constrained budgets, despite long-term operational savings.
- Battery Performance Limitations:Limited battery cycle life and degradation in extreme temperatures increase total cost of ownership and affect long-term system reliability.
- Component Sourcing Dependence:Reliance on Chinese manufacturing for polycrystalline panels creates supply chain vulnerabilities for large-scale municipal projects.
Strategic Opportunities
- Smart City Integration:Combining solar LEDs with IoT sensors opens new service models in public safety and environmental monitoring for connected cities.
- Agricultural Applications:Specialized solar LED systems for nocturnal pest control and extending growing seasons represent an untapped market in off-grid farming.
- Latin American Infrastructure:Underpenetrated markets in Brazil and Colombia offer growth potential for street lighting as part of urbanization projects.
Industry Challenges
- Divergent Certification Standards:Manufacturers face complexity and cost in meeting disparate requirements like Europe's CE marking and China's GB standards for global market access.
- System Integration Complexity:Ensuring interoperability between autonomous solar lighting and legacy centralized grid management systems presents technical hurdles for hybrid smart city deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Outdoor Solar LED Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $27.75 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Garden Lights, Street Lamps, Floodlights, Wall Lights, Pathway Lights Technology: Monocrystalline, Polycrystalline, Thin-Film, Amorphous, Perovskite Application: Public Parks, Commercial Complexes, Parking Lots, Residential Gardens, Recreational Areas End User: Municipal Authorities, Hospitality Venues, Property Developers, Event Organizers, Educational Institutions |
| Companies Covered | Signify Holding, OSRAM GmbH, Greenshine New Energy, SOKOYO Solar Lighting Co., Ltd., SEPCO Solar Electric Power Company, Sunna Design, LEADSUN, Wipro Lighting, Bridgelux, Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Outdoor Solar LED Market Strategic Shifts & Innovations
System intelligence and autonomous operation are transitioning from premium features to baseline expectations. This evolution is driven by advancements in battery management and the growing demand for connected, data-generating infrastructure assets.
Integrated battery management systems (BMS) are a critical technology for optimizing charge cycles and extending battery life. Municipal end-users are adopting systems with advanced BMS to protect their long-term investments. This technology is expanding into even cost-sensitive, large-scale deployments to improve reliability and reduce lifetime operational costs.
China's dual carbon goals directly mandate the use of energy-efficient technologies in new public infrastructure projects. This policy accelerates the replacement of traditional street lamps with solar LED alternatives. The most significant impact is on provincial-level procurement specifications, which now frequently require solar solutions.
A shift towards lifecycle-cost-based procurement is altering purchasing decisions for public authorities. Instead of focusing solely on upfront capital expenditure, buyers now prioritize total cost of ownership, including battery replacement schedules. This behavior is most prominent in European municipal tenders, influencing product design towards modularity.
Outdoor Solar LED Market Segmentation
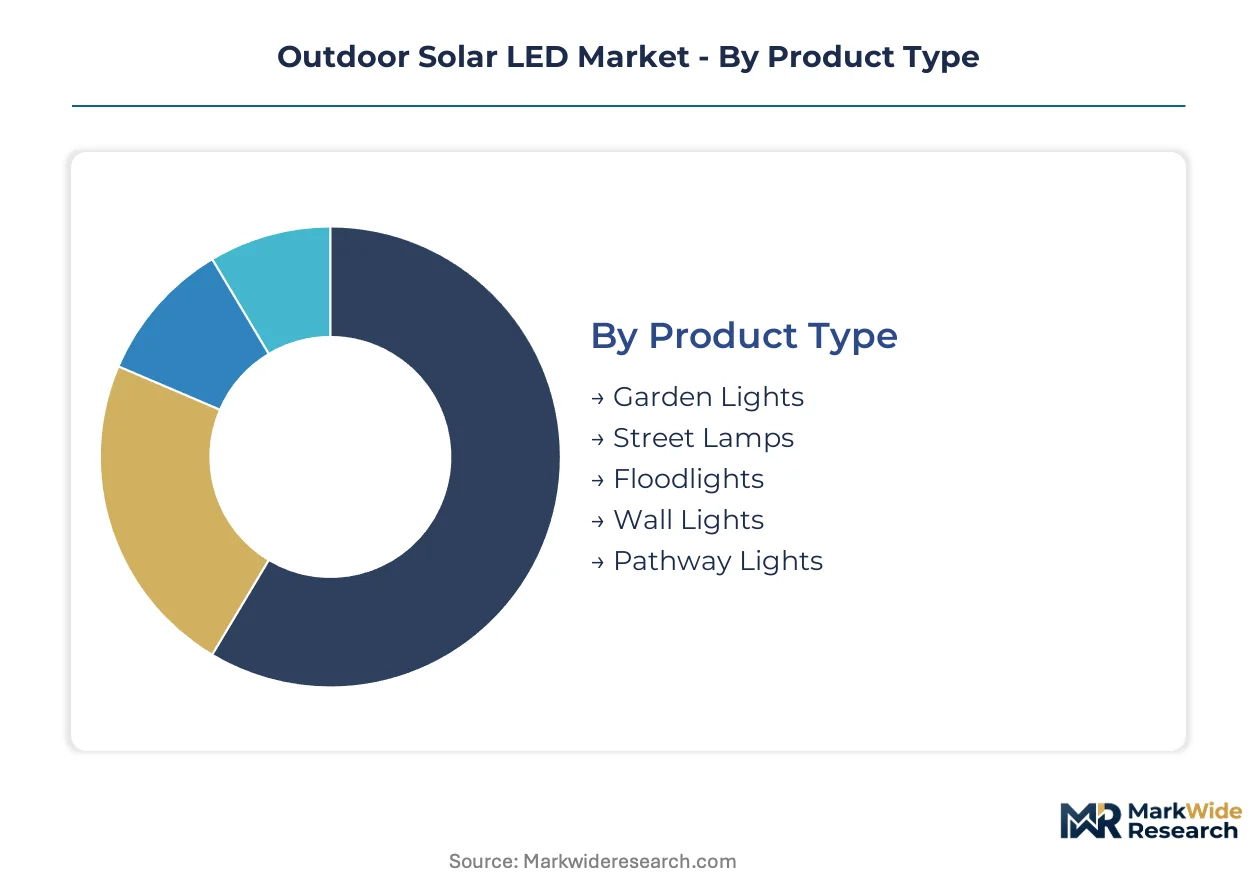
Understanding the segmentation of the outdoor solar LED market reveals critical distinctions in product requirements, technological preferences, and end-user demands. This detailed breakdown helps identify specific growth pockets and the varying economic drivers influencing different market sub-sectors.
Product Type:
The product type segmentation highlights the balance between highly standardized public infrastructure solutions and more customized residential or decorative lighting options.
- Garden Lights:These compact, aesthetic luminaires are designed for residential landscaping and outdoor décor, often integrating smaller solar panels and batteries for dusk-to-dawn operation in private settings. Demand concentrates in developed urban areas for home improvement and property value enhancement, driven by homeowner interest in sustainable living.
- Street Lamps:Large, robust fixtures are engineered for public illumination, providing high-intensity light output for roads, highways, and public squares, requiring significant power storage and advanced control systems. Demand from municipal authorities for public park and street lamp installations is a primary growth engine, especially for energy independence initiatives.
- Floodlights:Powerful, broad-beam lights provide extensive illumination for security, sports fields, or large outdoor areas, often featuring adjustable angles and higher wattage outputs.
- Wall Lights:Mounted directly onto exterior walls, these fixtures offer targeted lighting for building perimeters, entryways, and security, blending functional illumination with architectural aesthetics.
- Pathway Lights:Low-level luminaires guide pedestrians along walkways, driveways, and garden paths, prioritizing safety and subtle ambient lighting in both public and private spaces.
Most installed capacity flows through Street Lamps. Expansion is steepest in Garden Lights.
Technology:
Technology options present a clear differentiation based on cost efficiency and performance benchmarks for various project scales.
- Monocrystalline:These solar panels feature high purity silicon, offering superior efficiency and performance in limited space applications, making them suitable for premium or demanding installations. Higher energy conversion rates from monocrystalline technology enable more powerful and reliable lighting, justifying their use in demanding applications like smart city deployments.
- Polycrystalline:Composed of multiple silicon crystals, these panels offer a more cost-effective solution with slightly lower efficiency, commonly used in large-scale projects where space is not a primary constraint. Reliance on Chinese manufacturing for polycrystalline panels creates supply chain vulnerabilities for large-scale municipal projects due to concentrated production.
- Thin-Film:These flexible, lightweight panels use various materials deposited in thin layers, offering versatility in design and integration but generally lower efficiency compared to crystalline silicon.
- Amorphous:A type of thin-film technology, amorphous silicon panels are highly flexible and perform well in low-light conditions, though they typically have the lowest efficiency among solar panel types.
- Perovskite:An emerging technology, perovskite solar cells promise high efficiency and low manufacturing costs, with ongoing research focused on improving their stability and commercial viability for future applications.
Monocrystalline technology drives high-efficiency installations, with polycrystalline arrays providing economical alternatives for widespread deployment.
Application:
Application segments delineate where different customer groups prioritize autonomous lighting solutions for specific environmental needs.
- Public Parks:These areas require reliable, vandal-resistant lighting for safety and aesthetics during evening hours, often integrating with existing municipal infrastructure and control systems. Demand from municipal authorities for energy-independent public lighting creates a direct pull for autonomous, weather-resistant systems for public parks.
- Residential Gardens:Homeowners utilize these systems for decorative lighting, security, and pathway illumination around private properties, valuing ease of installation and low maintenance. Garden and pathway lights represent the fastest-growing segment for residential applications, driven by consumer interest in sustainable outdoor living.
- Commercial Complexes:Businesses deploy solar LED lighting for parking lots, building perimeters, and outdoor common areas to enhance security and reduce operational energy costs.
- Parking Lots:Large open spaces use solar LEDs for visibility and security, benefiting from off-grid operation to avoid extensive trenching and electrical infrastructure costs.
- Recreational Areas:Sports fields, trails, and outdoor event venues adopt solar lighting for extended usability and safety, often requiring robust, high-lumen output fixtures.
Public infrastructure projects drive significant volume, yet residential installations show substantial growth potential.
End User:
End-user categories reflect varied procurement scales, ranging from large public tenders to specialized requirements for specific commercial activities.
- Municipal Authorities:Government bodies procure solar LED systems for public infrastructure, including street lighting, parks, and rural electrification projects, often driven by energy efficiency mandates. The EU Green Deal and China's dual carbon goals mandate energy-efficient public infrastructure, creating direct demand for solar installations from these entities.
- Property Developers:These entities integrate solar LED lighting into new residential communities, commercial buildings, and planned urban developments, emphasizing sustainable design and reduced long-term operating costs. Underpenetrated markets in Brazil and Colombia offer growth potential for street lighting as part of urbanization projects led by developers.
- Hospitality Venues:Hotels, resorts, and restaurants use solar LEDs for outdoor ambiance, pathway lighting, and security, enhancing guest experience while lowering utility expenses.
- Event Organizers:Temporary lighting solutions for festivals, concerts, and outdoor gatherings benefit from portable, autonomous solar LED systems for flexible deployment without grid access.
- Educational Institutions:Schools and universities install solar lighting for campus pathways, parking areas, and outdoor sports facilities, aligning with sustainability goals and reducing operational budgets.
Municipal authorities shape the market through large-scale tenders, influencing product specifications and long-term service contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Outdoor Solar LED market exhibits a distinct regulatory arbitrage, as manufacturing cost differentials influence supply chain configurations. Procurement patterns are shifting towards lifecycle-cost-based models, impacting product design and sourcing decisions. This dynamic environment fosters varied growth trajectories across key geographies.
China
China's robust manufacturing base drives significant volume for polycrystalline panels, supporting large-scale municipal projects. The nation's dual carbon goals mandate energy-efficient public infrastructure, accelerating solar LED adoption. Cities like Shenzhen concentrate production and innovation for global export markets.
India
India's substantial rural electrification initiatives create a concentrated demand for cost-effective solar lighting solutions. Government schemes, including various PLI programs, support domestic manufacturing and deployment of solar technologies. Uttar Pradesh and Bihar are key states for large-scale rural lighting projects.
Germany
Germany's market prioritizes high-efficiency monocrystalline systems for smart city applications and demanding installations. The EU Green Deal mandates energy-efficient public infrastructure, driving demand for advanced solar LED solutions. Munich and Berlin are hubs for integrating intelligent lighting systems into urban planning.
Brazil
Brazil presents significant growth potential for street lighting as part of ongoing urbanization projects across its states. ANVISA regulations influence product safety standards for imported and domestically produced lighting systems. Sao Paulo and Rio de Janeiro lead in adopting solar LED solutions for public spaces.
South Africa
South Africa's rural communities require autonomous solar lighting for basic electrification and safety enhancements. The Department of Energy promotes renewable energy projects, including off-grid solar solutions for remote areas. Johannesburg and Cape Town are seeing increased adoption in commercial and public spaces.
Outdoor Solar LED Market Key Industry Players
Chinese producers anchor one tier, specializing in high-volume, cost-effective polycrystalline panels for global export. European and North American specialists hold another tier, focusing on premium, intelligent monocrystalline systems for advanced applications. The market fragments into large-scale manufacturers, niche technology providers, and regional distribution networks. Companies engage in capacity expansion and technology development to secure market share.
Within the premium and intelligent systems tier, Signify Holding leverages its extensive distribution network for large-scale commercial deployments. SOKOYO Solar Lighting Co., Ltd. exemplifies the high-volume production model, competing aggressively in global export markets. Sunna Design occupies a specialized position, focusing on intelligent and connected solar lighting systems tailored for smart city applications.
| Leading Market Players |
|---|
| Signify Holding |
| OSRAM GmbH |
| Greenshine New Energy |
| SOKOYO Solar Lighting Co., Ltd. |
| SEPCO Solar Electric Power Company |
| Sunna Design |
| LEADSUN |
| Wipro Lighting |
| Bridgelux, Inc |
| Others |
Cost & Logistics Intelligence
Polysilicon commodity prices directly influence the cost structure of solar panels, cascading through the supply chain into distinct pricing tiers for Outdoor Solar LED systems. This dynamic shapes procurement strategies for large-scale projects and premium installations.
Pricing Analysis
Distributor margins reflect the value addition for installation and after-sales service in the Outdoor Solar LED market. Pricing stratifies across premium, standard, and economy tiers, driven by panel efficiency (monocrystalline vs. polycrystalline) and certification level (CE marking, GB standards). Pricing pressure stems from the high-volume production of cost-effective polycrystalline panels from Chinese manufacturers. Municipal authorities with constrained budgets exhibit the highest price sensitivity for large-scale infrastructure projects.
Supply Chain Analysis
Multi-supplier qualification mandates are becoming more common for municipal tenders to mitigate supply risks. Geographic supply concentration centers on China for high-volume polycrystalline panel production, while specialized components draw from diverse global sources. The supply chain relies heavily on silicon for photovoltaic cells and lithium-ion for rechargeable batteries. Single-source vulnerability for specific components, particularly from concentrated manufacturing hubs, represents a structural risk. Distribution runs through established networks for large commercial deployments and global export channels for high-volume manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
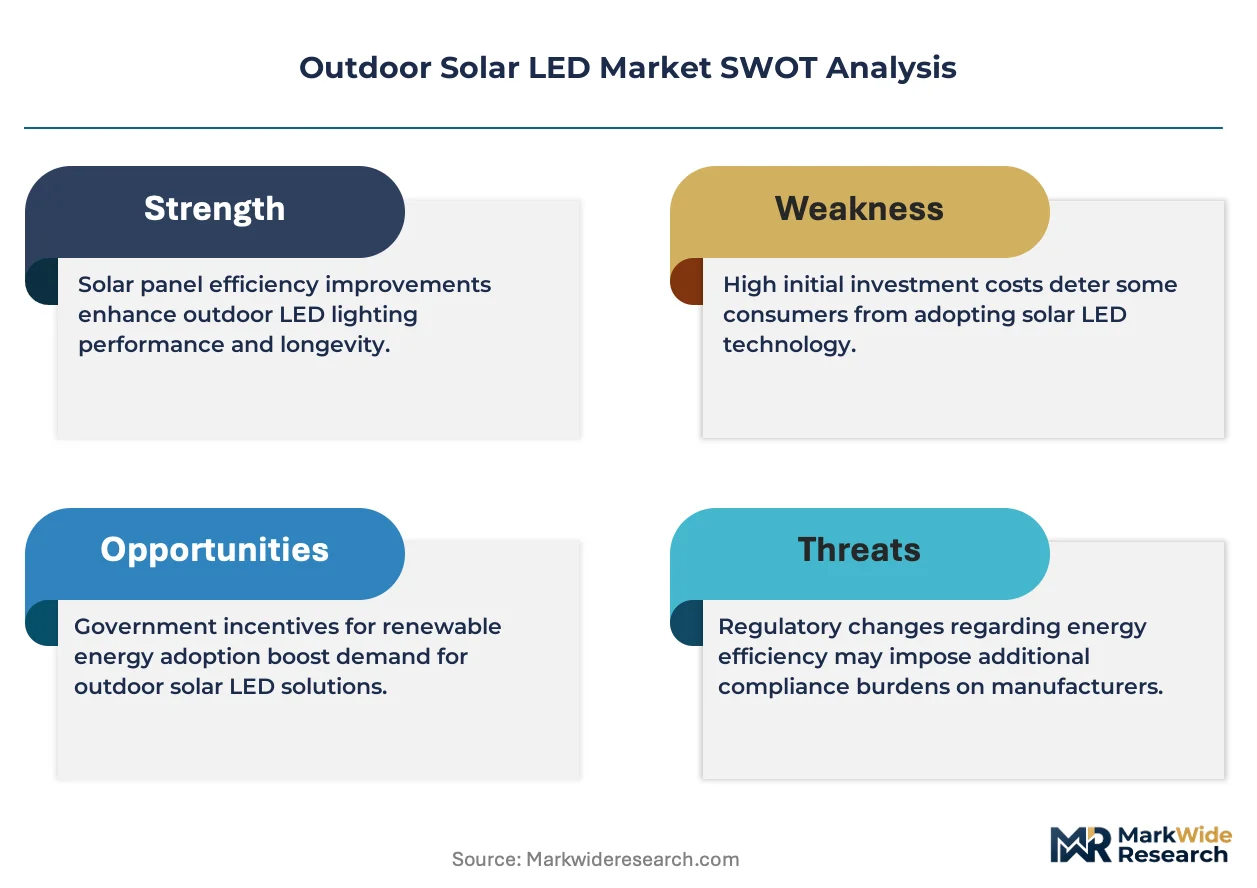
The Outdoor Solar LED market presents a margin-expansion story driven by the shift towards intelligent, connected systems and lifecycle-cost-based procurement.
For Market Incumbents:Lock in long-term municipal contracts by emphasizing total cost of ownership and advanced battery management systems. Invest in R&D for next-generation battery technologies to overcome current performance limitations and reduce long-term operational costs. Expand distribution networks in high-growth regions like India and sub-Saharan Africa to counter component sourcing dependence.
For New Entrants and Emerging Players:System integrators offer a path to market entry by focusing on specialized applications like agricultural lighting for nocturnal pest control. Target underpenetrated markets in Latin America, such as Brazil and Colombia, for urbanization-driven street lighting projects. Develop niche solutions with integrated IoT sensors for smart city applications, offering unique value propositions beyond basic illumination.
For Investors and Strategic Acquirers:Asymmetric upside sits with technology specialists focusing on intelligent solar lighting systems and advanced battery management. Monitor increased municipal tenders specifying lifecycle cost procurement and smart features as an inflection indicator. Long-term viability rests on the accelerating global transition to sustainable infrastructure and rural electrification initiatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Polycrystalline Panels | Supports high-volume demand for cost-effective municipal and rural electrification projects. |
| R&D in Advanced Battery Management Systems | Extends system reliability and reduces total cost of ownership for end-users. |
| Smart City Platform Integration | Creates new service models and data-generating infrastructure assets for urban environments. |
| Geographic Market Entry in Latin America | Capitalizes on urbanization projects and underpenetrated street lighting opportunities. |
| Certification Compliance Investment | Ensures market access and performance credibility in diverse global regulatory environments. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary insights with robust secondary validation. Primary data gathered from municipal procurement officers, property developers, lighting engineers, and R&D leads informed market dynamics. Secondary research leveraged government energy mandates like the EU Green Deal and China's dual carbon goals, trade association reports, and company financial filings, triangulating data through bottom-up and top-down analyses.
The forecast framework anchored the projection horizon to historical reference periods, modeling market evolution across key segmentation dimensions. These included product type (street lamps, garden lights), technology (monocrystalline, polycrystalline), application (public parks, residential gardens), end-user (municipal authorities, property developers), and regional adoption patterns. Compound annual growth rates were derived from historical growth trends and projected market dynamics, incorporating industry-specific forecast inputs such as rural electrification project pipelines and smart city investment plans.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to policy shifts and raw material price volatility. The analysis reflects assumptions regarding technological advancements and regulatory stability. Deviation in government subsidies or energy storage advancements would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Global Photovoltaic Market
Solar Power Systems
Non-Concentrating Solar Collector Market
Solar Power Systems
Solar Fuel Market
Solar Power Systems
Thin Film Photovoltaic Modules Market
Solar Power Systems
Slovakia Renewable Energy Market
Solar Power Systems
AR Photovoltaic Glass Market
Solar Power Systems
Asia Pacific Solar Inverter Market
Solar Power Systems
Switzerland Solar Energy Market
Solar Power Systems
Global Micro Solar Inverter Market
Solar Power Systems
Solar PV Panels Market
Solar Power Systems
Solar Updraft Tower Market
Solar Power Systems
Italy Distributed Solar Power Generation Market
Solar Power Systems
IBC Solar Cells Market
Solar Power Systems
Distributed Solar Power Generation System Market
Solar Power Systems
Solar PV Junction Box Market
Solar Power Systems
Bifacial Solar Panels Market