
 IBC Solar Cells Market | 2026-2036
IBC Solar Cells Market Size, Share, and Industry Trends Forecast 2026-2036
IBC Solar Cells Market Insights
Utility-scale solar deployment is consolidating share within the IBC solar cells end-use mix as developers prioritize module efficiency to reduce land and balance-of-system costs. LONGi Solar leverages its monocrystalline wafer scale to anchor cost positions across high-efficiency cell architectures. SunPower sustains premium positioning through proprietary interdigitated back-contact designs that maximize active cell area. Tongwei Solar competes aggressively on polysilicon-to-cell vertical integration, controlling upstream material flows that buffer margin volatility.
Interdigitated back-contact solar cells relocate all electrical contacts to the rear surface, eliminating front-side shading losses and enabling conversion efficiencies exceeding 26% in commercial production through precision laser-patterned doping and passivated emitter architectures. The cells serve utility and commercial segments where energy yield per square meter determines project economics. Monocrystalline cells dominate current output as silicon crystal quality supports the fine-line metallization that IBC architectures demand, while bifacial cells capture growing share as rear-side albedo harvesting improves system-level returns. Tandem cells represent the fastest-growing product category as perovskite-silicon stacks push theoretical efficiency limits beyond single-junction constraints.
China's MIIT enforces GB standards that mandate minimum conversion efficiencies for domestic photovoltaic products, directly shaping which cell technologies qualify for state-backed procurement. The EU Green Deal and F-Gas Regulation impose embodied carbon and process chemical constraints on modules sold into European markets, filtering market access by manufacturing cleanliness. The US IRA production tax credits reward domestic cell and module assembly, altering supply chain geography for North American project developers. Stakeholders must monitor how efficiency thresholds and carbon border adjustments redefine competitive advantage across manufacturing locations.
Market Dynamics
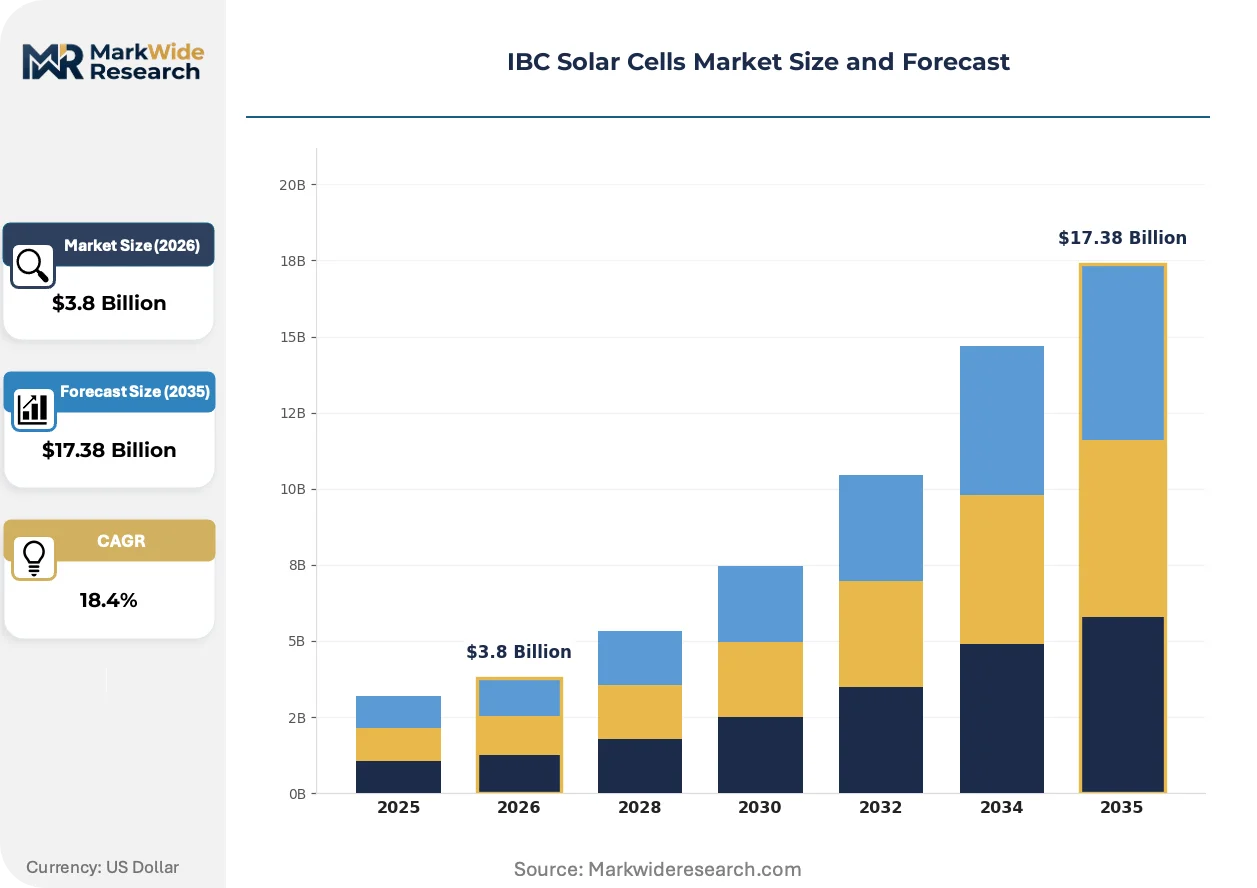
Utility-scale developers are consolidating procurement around high-efficiency architectures as land scarcity and balance-of-system costs dominate project economics. China's MIIT efficiency mandates and the US IRA domestic production incentives are bifurcating supply chain geography between policy-compliant and cost-optimized manufacturing clusters.
Growth Catalysts
- MIIT GB Standards:China's minimum efficiency thresholds disqualify legacy cell technologies from state-backed procurement, forcing manufacturing upgrades toward back-contact architectures.
- Utility-scale solar farms:Developers prioritize module efficiency to reduce land acquisition and cabling costs per megawatt installed.
- Perovskite-silicon tandem integration:Laboratory-validated stacks push theoretical efficiency beyond single-junction limits, attracting R&D capital toward commercialization.
Market Restraints
- Polysilicon price volatility:Upstream feedstock cost swings compress cell manufacturer margins during contract negotiation windows.
- Silver metallization dependency:Fine-line rear-contact patterning requires high-purity silver paste, exposing producers to precious metal supply concentration.
- Laser-patterning throughput limits:Precision doping equipment creates bottlenecks in scaling from pilot to mass production.
Strategic Opportunities
- US IRA production tax credits:Domestic cell and module assembly incentives attract capital toward North American manufacturing greenfield sites.
- Bifacial rear-side harvesting:Albedo capture in desert and snow-belt geographies improves system-level returns without front-side efficiency trade-offs.
- EU F-Gas Regulation compliance:Manufacturing cleanliness requirements filter market access, creating first-mover advantage for low-carbon process adopters.
Industry Challenges
- Passivated emitter process control:Atomic-layer deposition uniformity demands specialized technician training that outpaces workforce development.
- Cross-border carbon accounting:Embodied emissions verification for EU market entry requires supply chain documentation systems most producers lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IBC Solar Cells Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.38 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline Cells, Bifacial Cells, Tandem Cells, High-Efficiency Cells Application: Residential, Commercial, Utility-Scale, Off-Grid Technology: Thin-Film, Passivated Emitter, Laser Doping, PERC End User: OEMs, Installers, Distributors, Energy Providers |
| Companies Covered | Tongwei Solar, Aiko Solar, Jinko Solar, Canadian Solar, Trina Solar, LONGi Solar, SunPower, LG Corp, JA Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IBC Solar Cells Market Trends and Innovations
Back-contact cell architectures are converging with tandem stack designs and automated manufacturing controls, compressing the gap between laboratory efficiency records and commercial production yields. Three developments are restructuring competitive positioning.
Laser-patterned doping equipment is integrating with in-line metrology systems to enable real-time passivation quality feedback. Cell manufacturers in China and Germany are deploying these hybrid production lines to reduce yield drift during long production runs. The technology is integrating statistical process control methods from semiconductor fabrication, compressing defect rates and narrowing efficiency distributions between batches.
The EU F-Gas Regulation imposes process chemical constraints and embodied carbon thresholds on modules sold into European markets. Manufacturers must document fluorinated gas usage and supply chain emissions or face market exclusion. High-efficiency cell producers with certified low-carbon processes are capturing premium procurement slots from European utility developers.
Developers are unbundling module supply from engineering-procurement-construction contracts to negotiate cell efficiency guarantees separately. This disintermediation exposes cell manufacturers to direct performance liability while allowing project sponsors to optimize technology selection. The pattern is most visible in US utility-scale procurement where IRA domestic content bonuses create technology-specific sourcing requirements.
IBC Solar Cells Market Segmentation
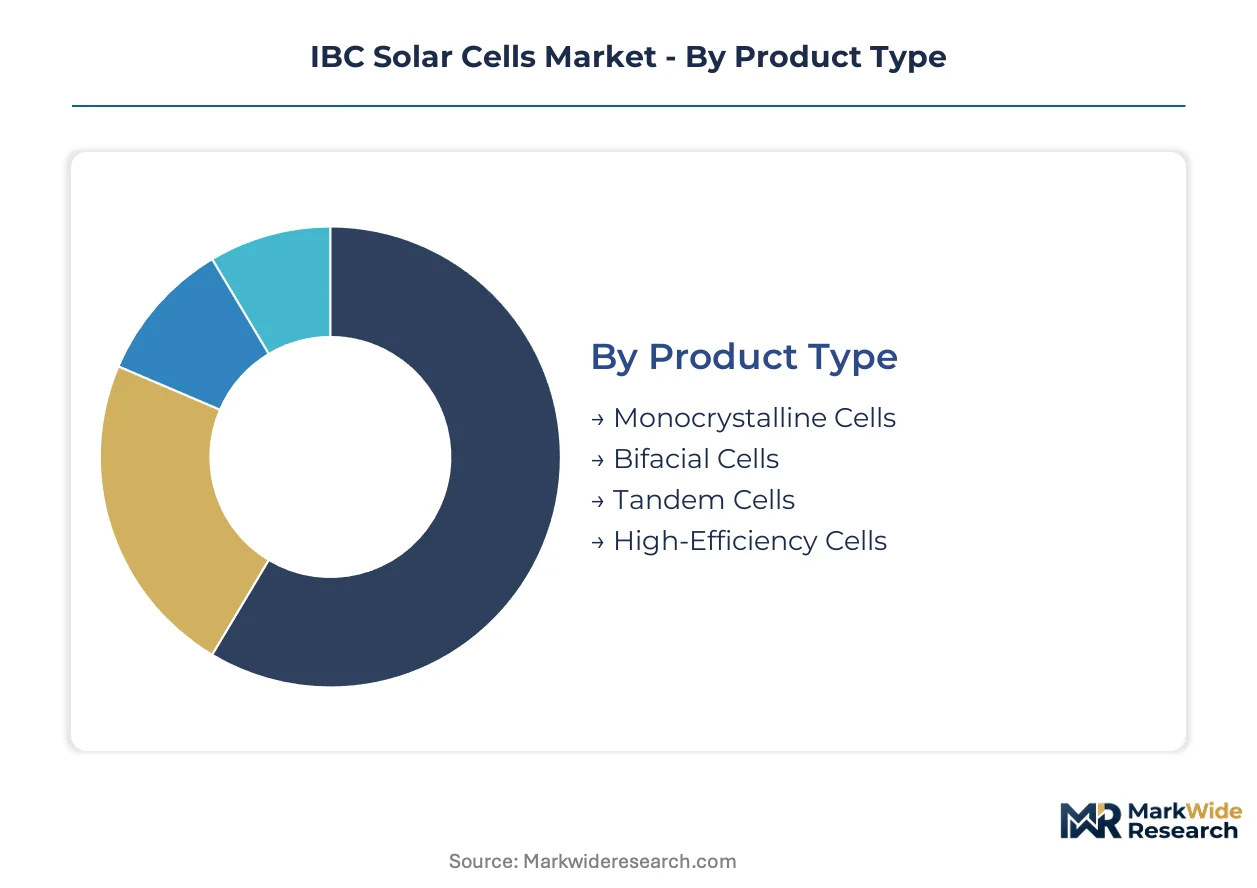
IBC solar cell procurement splits across multiple decision axes. Efficiency specifications dominate product selection for utility-scale developers, while installation scale determines channel economics and margin capture.
Product Type:
Buyers prioritize conversion efficiency thresholds over upfront module cost when selecting cell architectures for high-yield deployments.
- Monocrystalline Cells:Silicon ingot quality enables the fine-line rear-contact metallization that IBC architectures require. Utility-scale procurement in China and Germany concentrates here as developers seek bankable efficiency guarantees for long-term power purchase agreements.
- Tandem Cells:Perovskite-silicon stacks push theoretical efficiency beyond single-junction limits through stacked absorption layers. Laboratory-validated architectures are attracting R&D capital toward commercial production lines, with pilot deployments accelerating in German research clusters.
- Bifacial Cells:Rear-side albedo harvesting improves system-level returns without front-side efficiency trade-offs.
- High-Efficiency Cells:Premium architectures exceed 26% conversion efficiency in commercial production.
Monocrystalline cells lead on scale; tandem cells lead on momentum.
Application:
Installation scale determines balance-of-system cost allocation and land use intensity.
- Utility-Scale:Megawatt-scale solar farms prioritize module efficiency to reduce land acquisition, cabling, and mounting hardware per watt installed. Procurement concentrates in China, the United States, and Germany as developers optimize levelized cost of electricity under policy-backed offtake structures.
- Commercial:Rooftop and carport installations balance efficiency against structural load limits and interconnection capacity. Demand clusters in urban Germany and distributed solar markets across the United States where behind-the-meter economics drive technology selection.
- Residential:Homeowners prioritize aesthetics and warranty terms over absolute efficiency.
- Off-Grid:Remote power systems favor reliability and temperature coefficient performance.
Utility-scale deployment dominates procurement volume; commercial applications offer the steepest expansion trajectory.
Technology:
Manufacturing process selection determines yield rates, capital intensity, and regulatory compliance for export markets.
- Passivated Emitter:Atomic-layer deposition creates ultra-thin dielectric layers that reduce surface recombination losses. Chinese manufacturers are scaling these processes to meet MIIT GB efficiency mandates that disqualify legacy architectures from state-backed procurement.
- Laser Doping:Precision ablation enables localized phosphorus or boron introduction for interdigitated rear-contact patterning. Throughput constraints at scale create bottlenecks as producers expand from pilot to mass production lines.
- PERC:Passivated emitter and rear contact technology offers a bridge architecture for efficiency upgrades.
- Thin-Film:Alternative absorber materials compete on temperature coefficient and flexibility.
Passivated emitter processes anchor current manufacturing; laser doping systems are gaining share fastest.
End User:
Channel position determines pricing power, inventory risk, and technical support obligations.
- OEMs:Module assemblers source cells under long-term supply agreements that specify efficiency distributions and binning tolerances. Chinese vertical integrators dominate procurement volumes as they internalize cell production for captive module assembly.
- Installers:Engineering-procurement-construction contractors negotiate cell efficiency guarantees separately from module supply. US utility-scale procurement is disintermediating module supply from EPC contracts, exposing cell manufacturers to direct performance liability.
- Distributors:Inventory holders bridge supply timing mismatches for smaller-scale projects.
- Energy Providers:Utility and independent power producers specify technology requirements in request-for-proposal documents.
OEMs capture the largest procurement volume; installers are expanding their influence fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity migrates toward jurisdictions where production tax credits offset compliance costs for high-efficiency cell architectures. China's MIIT mandates, the US IRA domestic content bonuses, and the EU F-Gas Regulation create divergent cost-of-compliance landscapes that reshape facility location decisions.
China
Utility-scale developers in Xinjiang and Inner Mongolia drive procurement volumes for back-contact modules under state-backed power purchase agreements. MIIT GB standards enforce minimum conversion efficiency thresholds that disqualify legacy cell technologies from domestic procurement. The Yangtze River Delta anchors mass production scaling as Tongwei Solar and LONGi Solar expand passivated emitter process lines to meet mandate compliance.
United States
Independent power producers specify IBC cell efficiency guarantees in utility-scale RFPs to optimize land use intensity in California and Texas solar zones. The IRA production tax credits reward domestic cell and module assembly, attracting capital toward Southeast manufacturing greenfield sites. The Desert Southwest concentrates bifacial deployment projects where rear-side albedo harvesting improves system-level returns.
Germany
Commercial rooftop installers in Bavaria and North Rhine-Westphalia balance module efficiency against structural load limits for distributed solar economics. The EU F-Gas Regulation imposes embodied carbon thresholds and process chemical constraints on module market access. The Fraunhofer research clusters in Saxony pilot perovskite-silicon tandem integration toward commercial production validation.
Japan
Residential and commercial segments in Kanto and Kansai prioritize high-efficiency architectures where rooftop area constraints dominate project economics. METI efficiency programs and building-integrated photovoltaic standards shape technology selection for urban deployment. The Chubu region hosts precision manufacturing clusters supplying laser-patterning equipment for rear-contact cell production.
Australia
Utility-scale developers in Queensland and New South Wales optimize for temperature coefficient performance in high-irradiance desert geographies. The national renewable energy target and state-level feed-in tariff structures influence cell technology procurement. The Snowy Mountains region drives bifacial adoption where rear-side albedo from seasonal snow cover enhances energy yield calculations.
IBC Solar Cells Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers scale passivated emitter and laser-doping equipment to capture policy-backed procurement windows. The vendor base concentrates around three strategic tiers: Chinese vertical integrators controlling polysilicon-to-module supply chains, European technology licensors specializing in precision manufacturing equipment, and North American project developers disintermediating module supply from EPC contracts. Competitive moves bifurcate between geographic expansion toward IRA-compliant North American assembly and technology licensing to bypass capital-intensive process development.
Within the Chinese vertical integration tier, Tongwei Solar, LONGi Solar, and Aiko Solar exemplify the scale-driven archetype that anchors global cell production volumes. These entities occupy positions where captive polysilicon supply buffers margin volatility during feedstock price swings. SunPower represents the premium-tier specialist archetype through proprietary interdigitated back-contact designs that maximize active cell area for efficiency-focused project developers. The competitive dynamic situates Chinese scale players against premium-positioned technology specialists, with procurement patterns shifting based on domestic content requirements and carbon border compliance thresholds.
| Leading Market Players |
|---|
| Tongwei Solar |
| Aiko Solar |
| Jinko Solar |
| Canadian Solar |
| Trina Solar |
| LONGi Solar |
| SunPower |
| LG Corp |
| JA Solar |
| Others |
Pricing and Supply Chain Analysis
Utility-scale developers consolidating procurement around MIIT GB-compliant efficiency thresholds force Chinese manufacturers to absorb passivated emitter process upgrade costs, compressing margins on legacy capacity while premium-tier producers capture pricing power through certified low-carbon production lines.
Pricing Analysis
Distributor margins for IBC modules stratify across premium, standard, and economy tiers based on certification grade and volume scale. OEM direct contracts command steepest discounts for multi-gigawatt offtake commitments, while project developers negotiating separate cell efficiency guarantees face pricing premiums for documented carbon footprint compliance. Cost compression in standard-tier modules is intensifying as Tongwei Solar and LONGi Solar expand wafer-scale production, though silver metallization dependency limits downside price elasticity. Commercial rooftop installers in Germany exhibit highest price sensitivity due to structural load constraints limiting module size, whereas US utility-scale IPPs prioritize efficiency guarantees over unit cost.
Supply Chain Analysis
Container freight rates from Yangtze River Delta ports to Rotterdam and Long Beach dictate working capital cycles for European and North American project developers. Polysilicon feedstock concentrates in Xinjiang and Inner Mongolia, high-purity silver paste sources from Japanese and Korean refiners, and precision laser-patterning equipment ships from Chubu region manufacturers in Japan. Single-source vulnerability in atomic-layer deposition equipment creates bottlenecks as producers scale beyond pilot capacity. Distribution runs through captive vertical integrators in China, direct OEM relationships for US IRA-compliant procurement, and specialized distributors serving German commercial installers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell manufacturers face a geographic-arbitrage play between China's MIIT-mandated domestic efficiency floors and the US IRA's production tax credit differential for North American assembly, with the spread between compliance costs determining facility location economics.
For Market Incumbents: Hedge polysilicon price volatility through captive upstream supply or long-term feedstock offtake agreements with Xinjiang-based producers. Defend margin position by accelerating laser-patterning throughput upgrades before equipment bottlenecks constrain mass production scaling, and pursue EU F-Gas Regulation pre-certification to capture premium procurement slots from European utility developers ahead of carbon border enforcement.
For New Entrants and Emerging Players: Perovskite-silicon tandem pilot lines offer a technology-first wedge into German research clusters and US Department of Energy-backed demonstration projects where efficiency records attract strategic partnership capital. Target the Australian bifacial utility-scale segment where rear-side albedo harvesting specifications remain underspecified in current RFPs, and pursue licensing arrangements with established passivated emitter process holders to bypass multi-year R&D cycles.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale equipment suppliers specializing in in-line metrology integration for laser-patterned doping lines, as yield optimization becomes the binding constraint on commercial production scaling. Over a multi-year horizon, acquisition targets include laser-system specialists with semiconductor fabrication heritage and certified low-carbon process technology holders positioned for EU market access. Watch for MIIT efficiency threshold revisions as the signal for consolidation timing among legacy capacity holders.
| Strategic Initiative | Industry Significance |
|---|---|
| Passivated Emitter Capacity Buildout | MIIT GB compliance qualifies producers for state-backed procurement in China's utility-scale solar zones. |
| Perovskite-Silicon Tandem Licensing | Fraunhofer research partnerships accelerate commercial validation beyond single-junction efficiency limits. |
| US IRA-Compliant Manufacturing Footprint | Southeast greenfield sites capture production tax credits for domestic cell and module assembly. |
| EU F-Gas Pre-Certification Program | Documented low-carbon processes secure premium procurement from European IPPs under embodied carbon thresholds. |
| Laser-Patterning Equipment Joint Venture | Chubu precision manufacturers partner with Chinese producers to resolve throughput bottlenecks at mass production scale. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cell manufacturing executives, utility procurement officers, EPC contract managers, and laser-equipment engineering leads with secondary validation against MIIT policy filings, IRA implementation guidance, EU F-Gas Regulation technical documentation, and customs trade data for polysilicon and silver paste flows. Bottom-up capacity buildout models triangulated against top-down policy-backed procurement forecasts to anchor projection ranges.
Segment-weighting approaches applied differential growth assumptions across monocrystalline, tandem, and bifacial product categories, with technology adoption curves modeled separately for passivated emitter and laser-doping manufacturing processes. The analytical framework incorporated end-use splits between utility-scale, commercial, and residential installation scales, regional regulatory clusters spanning China, the United States, Germany, Japan, and Australia, and channel dynamics across OEM captive supply, direct installer relationships, and distributor inventory positions. CAGRs derived from policy-mandated procurement timelines, efficiency upgrade cycles, and equipment scaling trajectories.
The model holds under sustained MIIT efficiency enforcement and IRA credit continuity; deviation in polysilicon supply restrictions, silver price spikes, or carbon border adjustment timing would shift capacity location decisions and margin distribution across producer tiers. Stakeholders should weight assumptions against their own operating context and policy exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Power Tracker Market
Solar Power Systems
Southeast Asia Solar Energy Market
Solar Power Systems
GCC Solar Photovoltaic (PV) Market
Solar Power Systems
Solar Rack Market
Solar Power Systems
Indonesia Solar Energy Market
Solar Power Systems
Smart Solar Power Market
Solar Power Systems
Off-Grid Solar Power Market
Solar Power Systems
UV Solar Simulators Market
Solar Power Systems
PERC Solar Panels Market
Solar Power Systems
Global Airport Solar Power Market
Solar Power Systems
Crystalline Silicon Solar PV Market
Solar Power Systems
Solar Simulator Market
Solar Power Systems
Solar Panels for Home Market
Solar Power Systems
Europe Bifacial Solar Market
Solar Power Systems
Asia-Pacific Distributed Solar Power Generation Market
Solar Power Systems
Solar Cell Films Market