
 Asia Pacific Solar Inverter Market | 2026-2036
Asia Pacific Solar Inverter Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Solar Inverter Market Intelligence
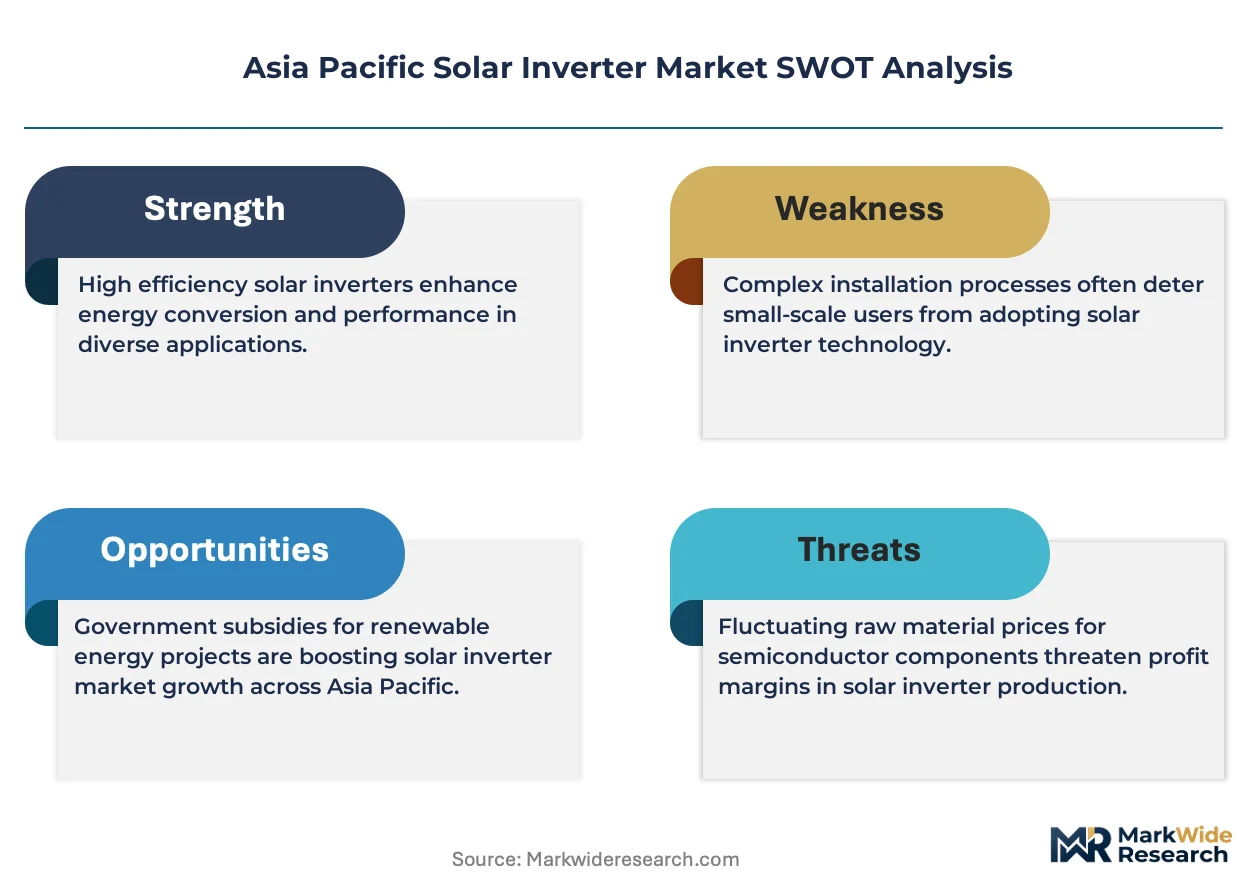
The shift toward utility-scale and large commercial projects is reorganizing procurement dynamics in the Asia Pacific solar inverter market. This moves focus away from smaller residential installations. Sungrow Power Supply leverages its massive manufacturing scale to serve these large-scale developments. Huawei Technologies competes on the basis of advanced digital and IoT integration features. SMA Solar Technology AG sustains its position through proven engineering reliability for complex grid-tied systems.
A solar inverter is a power electronics device converting direct current (DC) from photovoltaic panels into alternating current (AC) for grid use. This conversion must precisely manage voltage and frequency, with modern units achieving efficiencies above 98% to maximize energy harvest. String inverters are prevalent in residential and commercial applications due to design flexibility. The utility end-user segment, however, overwhelmingly prefers central inverters to achieve the lowest levelized cost of energy in large solar farms.
Regulatory frameworks across the Asia Pacific region shape product design and market entry. China's GB standards and India's Bureau of Indian Standards (BIS) certifications are mandatory for market access. Grid connection codes in countries like Australia and Japan impose strict requirements on inverter performance to ensure grid stability. Navigating these diverse and evolving national standards for grid integration remains a central challenge for all manufacturers.
Market Dynamics
The Asia Pacific solar inverter market's structure is defined by the tension between the massive, standardized demand from utility-scale projects and the fragmented, evolving grid codes of individual nations. This dynamic forces manufacturers to balance economies of scale with product customization for specific regulatory environments.
Growth Catalysts
- National Renewable Targets:Aggressive government mandates, such as Australia's renewable energy goals, directly stimulate the development of large-scale solar farms, creating predictable demand for high-capacity central and string inverters.
- Policy Incentives:Schemes like India's Production Linked Incentive (PLI) for solar manufacturing reduce capital costs and encourage domestic production, accelerating project pipelines and inverter deployment across the subcontinent.
- Falling System Costs:Continuous improvements in photovoltaic panel efficiency and manufacturing scale reduce the overall balance-of-system cost, making solar power generation more economically competitive and expanding the addressable market for inverters.
Market Restraints
- Component Supply Bottlenecks:The inverter supply chain's reliance on a concentrated number of global suppliers for critical power semiconductors, such as IGBTs and SiC modules, creates vulnerability to price volatility and shortages.
- Grid Infrastructure Limitations:In many developing economies within the region, aging or inadequate grid infrastructure limits the capacity to absorb large amounts of variable renewable energy, capping the scale of new solar projects.
- Regulatory Fragmentation:The high cost and long lead times associated with securing separate certifications for each country, such as BIS in India and compliance with Japan's grid codes, act as a significant barrier to entry and slow market penetration.
Strategic Opportunities
- Energy Storage Integration:The convergence of solar inverters with battery energy storage systems (BESS) creates a major opportunity for hybrid inverters that can manage both generation and storage, addressing grid stability concerns.
- Emerging Market Expansion:Underpenetrated markets in Southeast Asia, including Vietnam and the Philippines, offer significant growth potential as they begin to build out their renewable energy capacity to meet rising electricity demand.
- Green Hydrogen Production:The development of green hydrogen facilities powered by solar energy opens a new industrial end-use segment for high-capacity DC-DC converters and specialized inverter systems designed for electrolyzer loads.
Industry Challenges
- Rapidly Evolving Grid Codes:Manufacturers face a constant challenge to update firmware and hardware to comply with frequently revised grid connection standards, particularly advanced active power control requirements in markets like Australia.
- Skilled Labor Scarcity:A shortage of power electronics engineers and technicians with the specialized skills needed for commissioning, operating, and maintaining complex, grid-interactive inverter systems hampers project execution.
- Logistical Complexity:Transporting and installing multi-ton central inverters in remote, difficult-to-access locations for utility-scale solar farms presents significant logistical and operational hurdles for project developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Solar Inverter Market |
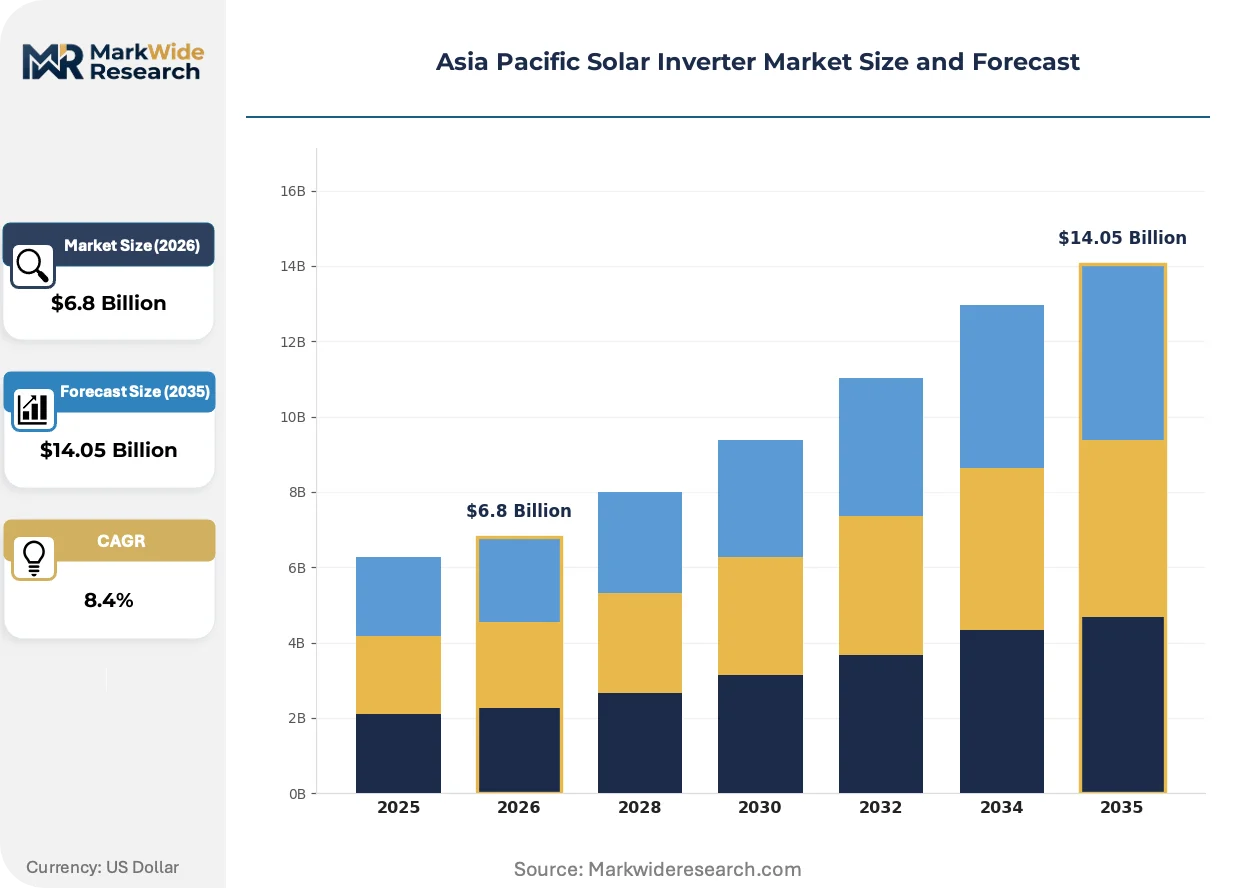
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: String Inverter, Micro Inverter, Central Inverter, Power Optimizer Installation Type: On-Grid, Off-Grid, Hybrid, BIPV End User: Residential, Commercial, Industrial, Utility Technology: Solar PV, Energy Storage, Smart Grid, IoT Integration |
| Companies Covered | Siemens AG, GoodWe, Huawei Technologies, Mitsubishi Electric Corporation, SMA Solar Technology AG, Sungrow Power Supply, Delta Energy Systems, Omron Corporation, Schneider Electric SE, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Solar Inverter Market Strategic Shifts & Innovations
Digitalization and advancing power electronics are transforming inverters from simple power conversion units into intelligent, grid-forming assets. This evolution is central to managing the increasing share of renewables on Asia Pacific grids, with a focus on enhanced control, reliability, and system intelligence.
Modular inverter architecture provides scalable power blocks that can be combined to meet specific capacity targets. Utility-scale developers are adopting this approach to improve system availability and simplify maintenance routines. This design philosophy is fragmenting the conventional, monolithic central inverter market by enabling more resilient and flexible power plant configurations.
Cybersecurity requirements are increasingly being embedded into national grid codes across the Asia Pacific region. This regulatory shift compels manufacturers to build robust security protocols and encrypted communications into their inverter control systems. The utility end-user segment is most impacted, as grid operators in countries like Australia mandate these features to protect critical energy infrastructure from digital threats.
Asset owners are increasingly demanding comprehensive long-term service agreements that guarantee inverter uptime and performance metrics. This behavior disrupts the traditional break-fix maintenance model, compelling inverter manufacturers to build out direct, sophisticated service networks. This trend is most visible among institutional investors and independent power producers in mature solar markets such as Japan and Australia.
Asia Pacific Solar Inverter Market Segmentation
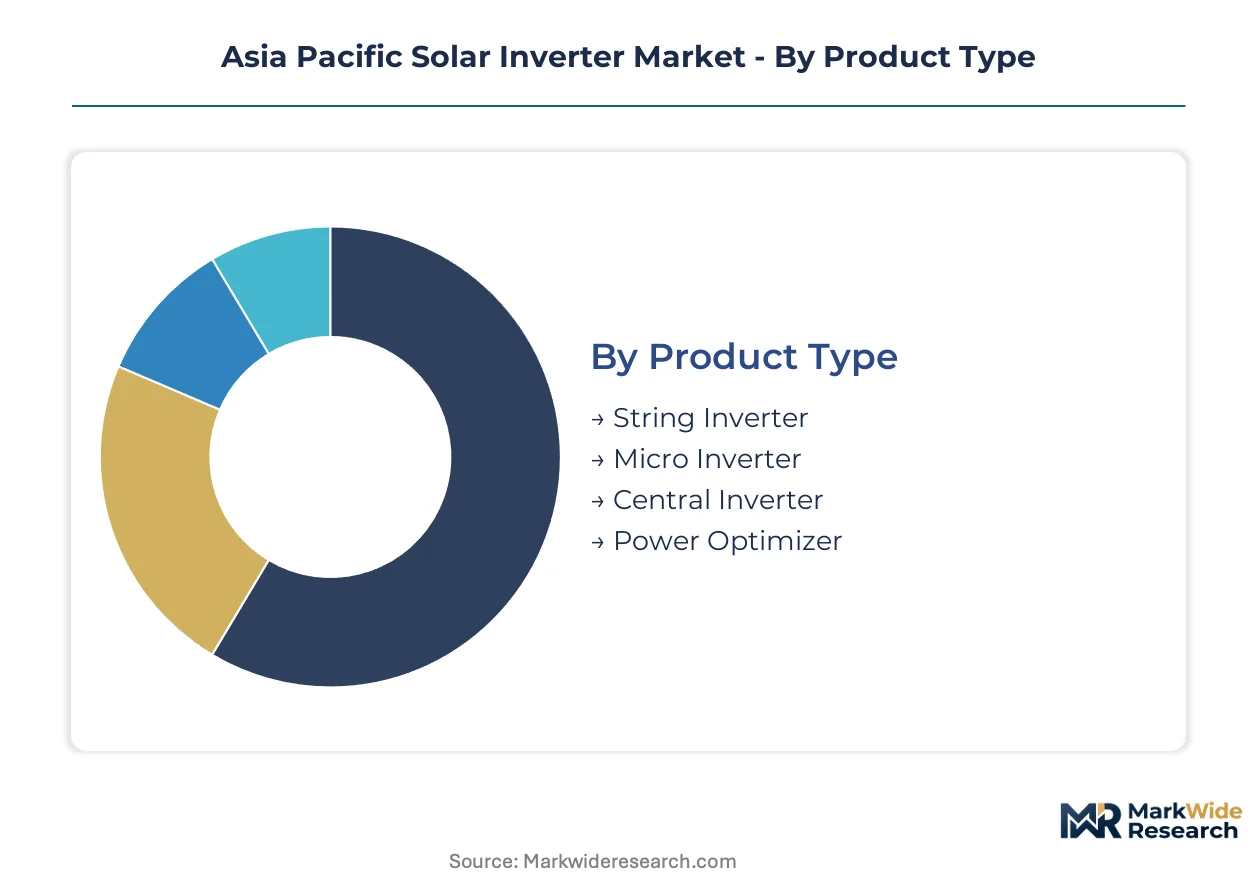
The Asia Pacific solar inverter market exhibits diverse requirements across its vast geography and varying stages of renewable energy development. Understanding these distinct segments is crucial for manufacturers to tailor product offerings, navigate regulatory frameworks, and optimize distribution channels effectively.
Product Type:
The geographic spread of solar inverter product types reflects regional preferences and project scales, with central inverters dominating utility-scale projects in resource-rich nations and string inverters finding broader acceptance in distributed generation across many countries.
- Central Inverter:These high-power devices convert DC electricity from large solar arrays into AC for grid injection, typically deployed in multi-megawatt installations. Demand concentrates in utility-scale solar farms across India and Australia, driven by the need for the lowest levelized cost of energy in large projects.
- String Inverter:Designed to handle DC power from multiple solar panels connected in series, string inverters offer flexibility and cost-effectiveness for smaller installations. These are widely adopted in residential and commercial applications in markets like Japan and Australia, benefiting from simpler design and maintenance.
- Micro Inverter:Micro inverters optimize power conversion at the individual solar panel level, enhancing energy harvest from shaded or mismatched modules.
- Power Optimizer:These module-level power electronics condition DC power from each panel before sending it to a central inverter, improving system performance under non-ideal conditions.
Central Inverter holds the largest share; momentum sits with String Inverter.
Installation Type:
Installation types are primarily differentiated by their connection to the electrical grid, influencing system design and the integration of energy storage solutions across the Asia Pacific region.
- On-Grid:These systems are directly connected to the public electricity grid, feeding excess solar power back into the utility network. On-grid installations represent the majority of solar deployments across China and India, driven by established grid infrastructure and net metering policies.
- Hybrid:Hybrid systems combine solar PV generation with battery energy storage and can operate both connected to the grid or independently. Demand for hybrid systems is strong in Australia and Japan, addressing grid stability concerns and providing energy resilience.
- Off-Grid:Off-grid systems operate independently of the utility grid, providing electricity to remote areas without access to centralized power.
- BIPV:Building-Integrated Photovoltaics (BIPV) involve solar inverters connected to PV modules that are integrated directly into building materials, serving both as power generators and structural components.
On-Grid installations dominate due to widespread grid connectivity, while hybrid systems are expanding most quickly.
End User:
End-user segments are distinguished by their energy consumption patterns, scale of deployment, and regulatory compliance requirements, shaping the demand for specific inverter capacities and features.
- Utility:This segment encompasses large-scale solar power plants designed to feed electricity directly into national grids, often requiring high-capacity central inverters. Utility-scale projects are prominent in India and Australia, supported by national renewable energy targets and competitive bidding processes.
- Commercial:Commercial end-users include businesses, offices, and industrial facilities that deploy solar systems for self-consumption and cost reduction, typically using string or medium-sized central inverters. This segment is expanding rapidly across Southeast Asia, driven by corporate sustainability goals and rising electricity prices.
- Residential:Residential end-users comprise individual homeowners installing solar panels on their properties, primarily utilizing string or micro inverters.
- Industrial:Industrial end-users are large energy consumers like manufacturing plants that integrate solar solutions to reduce operational costs and enhance energy independence.
The utility segment accounts for the largest inverter deployments, with industrial applications showing substantial growth.
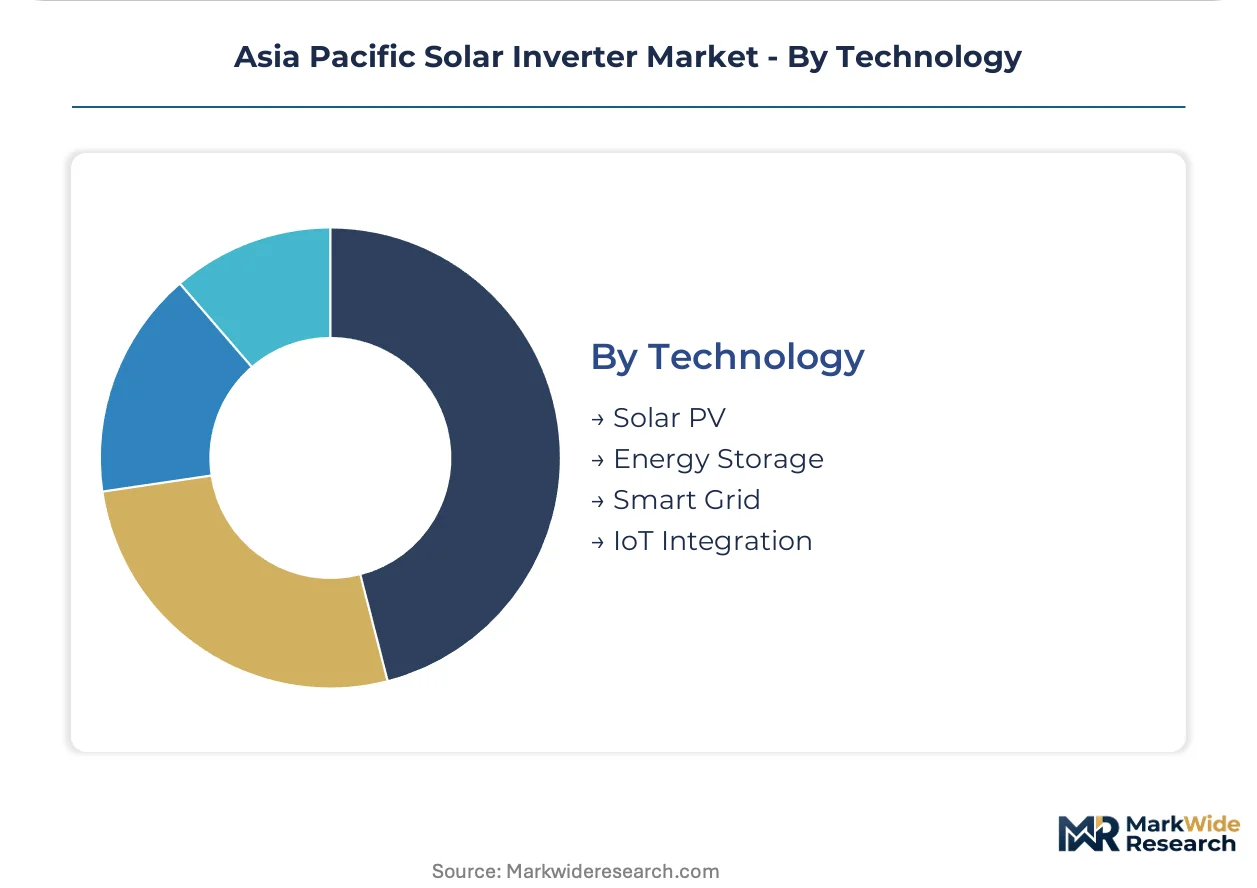
Technology:
Technological differentiation within the solar inverter market reflects the evolving capabilities of these devices, moving beyond simple power conversion to encompass advanced grid management and system intelligence.
- Solar PV:This core technology segment focuses on the fundamental DC-to-AC power conversion process essential for all photovoltaic installations. Solar PV technology underpins all inverter demand across the Asia Pacific region, representing the primary function of these devices.
- Energy Storage:This segment involves inverters designed to integrate and manage battery energy storage systems (BESS) alongside solar generation, enabling hybrid functionality. Demand for energy storage integration is increasing in Australia and Japan, driven by the need for peak shaving and grid stabilization.
- Smart Grid:Smart Grid technology in inverters includes advanced controls for grid-forming capabilities, frequency regulation, and voltage support to enhance overall grid stability.
- IoT Integration:IoT Integration incorporates communication protocols and sensors for remote monitoring, predictive maintenance, and data analytics of inverter performance.
Solar PV technology forms the market's foundation, while IoT integration is gaining share fastest as systems become more intelligent.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Asia Pacific region's expanding grid infrastructure underpins the growing demand for solar inverters. Significant investments in transmission and distribution networks across nations like India and Australia enable large-scale solar project integration. This infrastructure development supports the deployment of both central and string inverters.
India
Demand from utility-scale solar farms drives inverter deployment across India. The Production Linked Incentive (PLI) scheme encourages domestic manufacturing and project development. Rajasthan and Gujarat are becoming major hubs for solar park development, requiring high-capacity central inverters.
Australia
Aggressive renewable energy targets stimulate demand for both utility and hybrid solar inverter systems in Australia. Grid connection codes impose strict performance requirements to ensure grid stability. Queensland and New South Wales actively develop large-scale solar projects, focusing on grid-tied solutions.
China
China's dual carbon goals accelerate the deployment of massive solar projects, creating substantial inverter demand. GB standards mandate specific product certifications for market access and grid integration. Provinces like Xinjiang and Inner Mongolia host vast solar farms, utilizing advanced inverter technologies.
Japan
Demand for hybrid systems and residential applications drives inverter sales in Japan. METI regulations and JIS standards ensure strict performance and safety for grid-connected solar installations. The Kanto region, including Tokyo, sees high adoption of distributed generation and energy storage solutions.
Vietnam
Underpenetrated markets in Southeast Asia, such as Vietnam, offer growth potential as renewable energy capacity expands. The country's feed-in tariff policies previously spurred significant solar development. Provinces like Ninh Thuan and Binh Thuan are developing new solar power projects to meet rising electricity demand.
Asia Pacific Solar Inverter Market Key Industry Players
Listed leaders compete with private specialists across manufacturing scale and technological innovation. The Asia Pacific solar inverter market exhibits a tiered structure, with global conglomerates alongside regional players offering diverse solutions. Strategic archetypes include scale-driven manufacturers serving utility projects, technology innovators focusing on advanced digital integration, and established providers emphasizing engineering reliability for complex grid-tied systems. Dominant competitive moves involve rapid capacity expansion to meet utility-scale demand and strategic portfolio diversification into integrated energy storage solutions.
Within the scale-driven manufacturing archetype, Sungrow Power Supply Co., Ltd. exemplifies the ability to serve massive utility-scale developments across the region, leveraging its production capabilities. Huawei Technologies Co., Ltd. occupies a position among technology innovators, anchoring offerings around advanced digital and IoT integration features for grid-interactive solutions. SMA Solar Technology AG, a German-based company, represents established providers with proven engineering reliability for complex grid-tied systems, particularly in mature markets like Australia and Japan, where grid stability is paramount.
| Leading Market Players |
|---|
| Siemens AG |
| GoodWe |
| Huawei Technologies |
| Mitsubishi Electric Corporation |
| SMA Solar Technology AG |
| Sungrow Power Supply |
| Delta Energy Systems |
| Omron Corporation |
| Schneider Electric SE |
| Others |
Cost & Logistics Intelligence
Massive manufacturing scale in solar inverter production directly shapes both supply concentration and competitive price floors. This dynamic ensures that high-volume producers can offer more attractive pricing for large-scale utility projects, which in turn influences procurement decisions across the region.
Pricing Analysis
Volume-discount tiering structures characterize pricing across the Asia Pacific solar inverter market. Pricing stratifies across capacity tiers, with lower per-unit costs for high-volume central inverters compared to specialized micro inverters. Certification level, such as BIS in India or GB standards in China, and after-sales service bundles drive price differentiation. Pricing pressure stems from intense competition among large manufacturers like Sungrow Power Supply and Huawei Technologies. The utility segment consistently exhibits the highest price sensitivity, prioritizing the lowest levelized cost of energy.
Supply Chain Analysis
Strategic stockpiling for critical components balances just-in-time delivery for standard parts within the solar inverter supply chain. Supply concentration primarily resides in China, with key component manufacturing also occurring in South Korea and Japan. Critical raw material dependencies include power semiconductors, such as IGBTs and SiC modules, and specialized magnetic materials. Component supply bottlenecks and commodity price volatility represent a significant structural risk. Distribution runs through direct sales channels for utility-scale projects and a network of distributors for commercial and residential applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific solar inverter market is experiencing high-growth disruption, driven by the imperative for grid modernization and renewable energy integration.
For Market Incumbents:Secure long-term supply agreements for critical power semiconductors to mitigate component supply bottlenecks. Invest in advanced R&D for hybrid inverter systems that integrate energy storage, addressing grid stability concerns. Expand manufacturing capacity in strategic locations like India and Australia to comply with local content requirements and reduce logistical complexity. Build out robust service networks to meet asset owners' demands for guaranteed inverter uptime, countering competitive threats from new entrants focused on digital solutions.
For New Entrants and Emerging Players:Certification fast-tracks, such as specialized BIS certifications for specific inverter types, offer a market entry point. Target underpenetrated markets in Southeast Asia, focusing on commercial and industrial segments with rising electricity demand. Develop modular inverter architectures that simplify installation and maintenance for distributed generation projects. A go-to-market angle emphasizing advanced IoT integration and predictive maintenance features can differentiate offerings against established players in competitive markets.
For Investors and Strategic Acquirers:Mid-cycle technology positioning favors firms with strong intellectual property in advanced power electronics and grid-forming capabilities. Long-term viability remains strong, given the region's aggressive renewable energy targets over the coming decade. Acquisition targets should include specialized software firms enhancing inverter intelligence and cybersecurity, or manufacturers with strong localized service footprints. A signal to watch is the increasing standardization of grid connection codes across multiple Asia Pacific nations, indicating market maturation. Revision becomes warranted when grid infrastructure limitations significantly impede project pipelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand regional manufacturing capacity | Reduces logistics costs and improves compliance with local content regulations in India and Australia. |
| Invest in hybrid inverter R&D | Addresses growing demand for grid stability and energy resilience in Japan and Australia. |
| Strengthen cybersecurity protocols | Ensures compliance with evolving national grid codes and protects critical energy infrastructure. |
| Develop modular inverter solutions | Enhances system availability and simplifies maintenance for utility-scale solar farms. |
| Establish direct service networks | Meets asset owner demands for guaranteed uptime and performance metrics in mature markets. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through extensive primary interviews and validated with secondary research. This involved discussions with utility developers, EPC contractors, residential installers, grid operators, and inverter manufacturers. Secondary data sources included industry association reports, national renewable energy targets, government policy documents, and financial filings of public companies. A bottom-up approach to market sizing was triangulated with top-down validation.
The analytical framework projects market trajectories across the analysis window, considering historical trends and future growth drivers. Segmentation dimensions modeled included product type, installation type, end-user, technology, and regional regulatory compliance. Compound annual growth rates were derived from a comprehensive analysis of market drivers, restraints, opportunities, and industry challenges. Key forecast inputs included planned solar capacity additions and continuous improvements in inverter efficiency.
Underlying assumptions cover stable regulatory environments and continued technological advancements, with deviation risk concentrated in geopolitical shifts or unforeseen component shortages. Revision becomes warranted when policy incentives or grid infrastructure development significantly diverge from current projections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Rooftop Sales Market
Solar Power Systems
Solar Thermal Collector Market
Solar Power Systems
Frameless Solar Panel Market
Solar Power Systems
Colombia Solar Energy Market
Solar Power Systems
On-Site Photovoltaic Solar Power for Data Centers Market
Solar Power Systems
DSC Solar Technologies Market
Solar Power Systems
United Arab Emirates Solar Photovoltaic (PV) Market
Solar Power Systems
Utility Scale PV Inverter Market
Solar Power Systems
Bifacial Solar Module Market
Solar Power Systems
Mexico Rooftop Solar Market
Solar Power Systems
Solar PV Carport Market
Solar Power Systems
India Rooftop Solar Market
Solar Power Systems
Australia Rooftop Solar Market
Solar Power Systems
Solar Power Market
Solar Power Systems
Ghana Solar Energy Market
Solar Power Systems
India Solar Inverter Market