
 Advanced Lithium-Ion Batteries Market | 2026-2036
Advanced Lithium-Ion Batteries Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Lithium-Ion Batteries Market Analysis
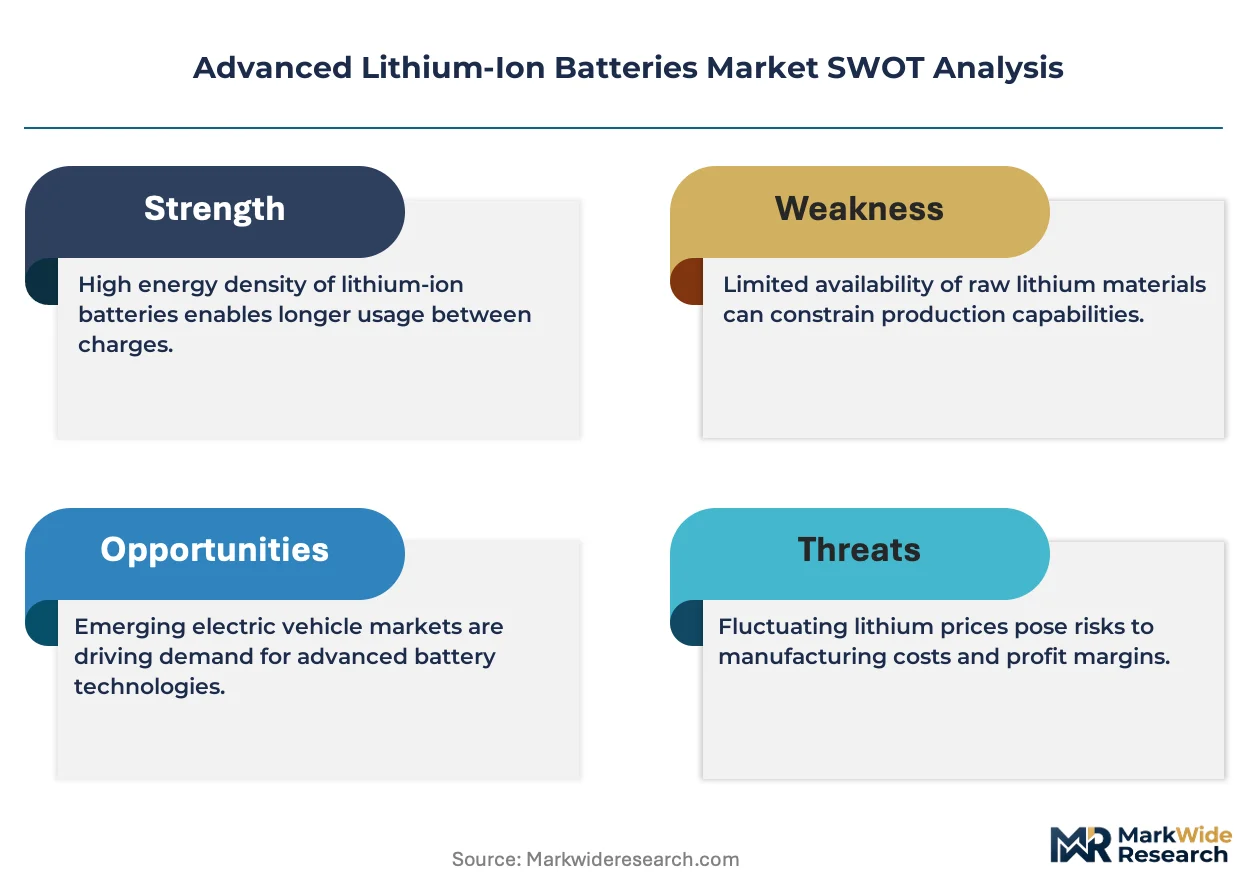
Silicon anode material is shifting from graphite-dominant architectures toward higher-capacity blends, reducing cobalt dependency while extending cycle life. CATL leverages integrated mining-to-cell verticality to secure precursor supply. LG Energy Solution anchors its position through cylindrical specialization for premium electric vehicle platforms. Samsung SDI differentiates via prismatic formats targeting industrial energy storage systems.
Advanced lithium-ion batteries are rechargeable electrochemical cells employing intercalation compounds, typically achieving energy densities above 250 Wh/kg through layered oxide cathodes paired with graphite or silicon composite anodes, manufactured via calendaring and electrolyte filling processes designed for high-rate cycling in mobility and grid applications. The electric vehicle application commands dominant volume as OEMs specify lithium nickel manganese cobalt formulations for range-critical platforms, while energy storage systems represent the fastest-expanding margin pool as lithium iron phosphate chemistry gains preference for stationary cycling durability. Pouch formats retain share in aerospace and healthcare end users where packaging flexibility outweighs structural rigidity requirements.
FDA device regulations and EPA hazardous material frameworks govern cell transport and medical device integration in the United States, while REACH and RoHS compliance in Europe restricts heavy metal content and mandates recycling accountability, directly shaping cathode chemistry selection and end-of-life collection infrastructure. China's SAMR enforces GB standards for cell safety testing that exporters must satisfy for market access. Stakeholders must monitor solid-state electrolyte patent landscapes and cathode precursor supply concentration to anticipate manufacturing cost trajectories and qualification timelines.
Market Dynamics
The transition from liquid electrolyte architectures toward solid-state configurations is compressing qualification timelines and forcing cathode precursor supply chains to reconfigure around sulfide and oxide electrolyte compatibility requirements.
Growth Catalysts
- China's dual carbon goals:Domestic NMPA accelerated approval pathways for solid-state pilot lines are compressing commercialization timelines by 18-24 months versus conventional liquid electrolyte qualification.
- High-nickel cathode chemistry:NMC 811 and 9½½ formulations are pulling demand from cobalt-heavy alternatives as OEMs specify 300+ Wh/kg pack targets for long-range electric vehicle platforms.
- Germany's automotive corridor clustering:Cell gigafactory siting near Wolfsburg, Stuttgart, and Munich assembly plants is reducing logistics costs and enabling just-in-time cathode active material delivery.
Market Restraints
- Nickel sulfate price volatility:Indonesian ore export restrictions and Philippine mining permit uncertainty are transmitting cost shocks through precursor supply chains.
- Graphite anode supply concentration:Synthetic and natural graphite processing capacity clusters in Shandong and Heilongjiang provinces, creating single-point vulnerability for non-Chinese cell manufacturers.
- Silicon anode expansion mechanics:Particle pulverization during lithiation cycles limits commercial blends to sub-10% silicon content, capping theoretical capacity gains.
Strategic Opportunities
- India's PLI scheme for ACC:Production-linked incentives for advanced chemistry cell manufacturing are attracting cathode precursor investments to Gujarat and Tamil Nadu.
- Aerospace pouch format demand:Satellite constellation operators and urban air mobility developers are specifying flexible packaging for non-cylindrical battery compartments.
- EU Battery Regulation due diligence:Mandatory carbon footprint declarations and recycled content quotas are creating first-mover advantage for European-sourced active materials.
Industry Challenges
- Solid-state electrolyte thin-film manufacturing:Sulfide handling protocols and moisture-free environments require cleanroom investments an order of magnitude beyond liquid electrolyte lines.
- UN 38.3 transport certification:Cell and pack-level testing for air freight compliance adds 4-6 months to product launch schedules for energy storage system integrators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Lithium-Ion Batteries Market |
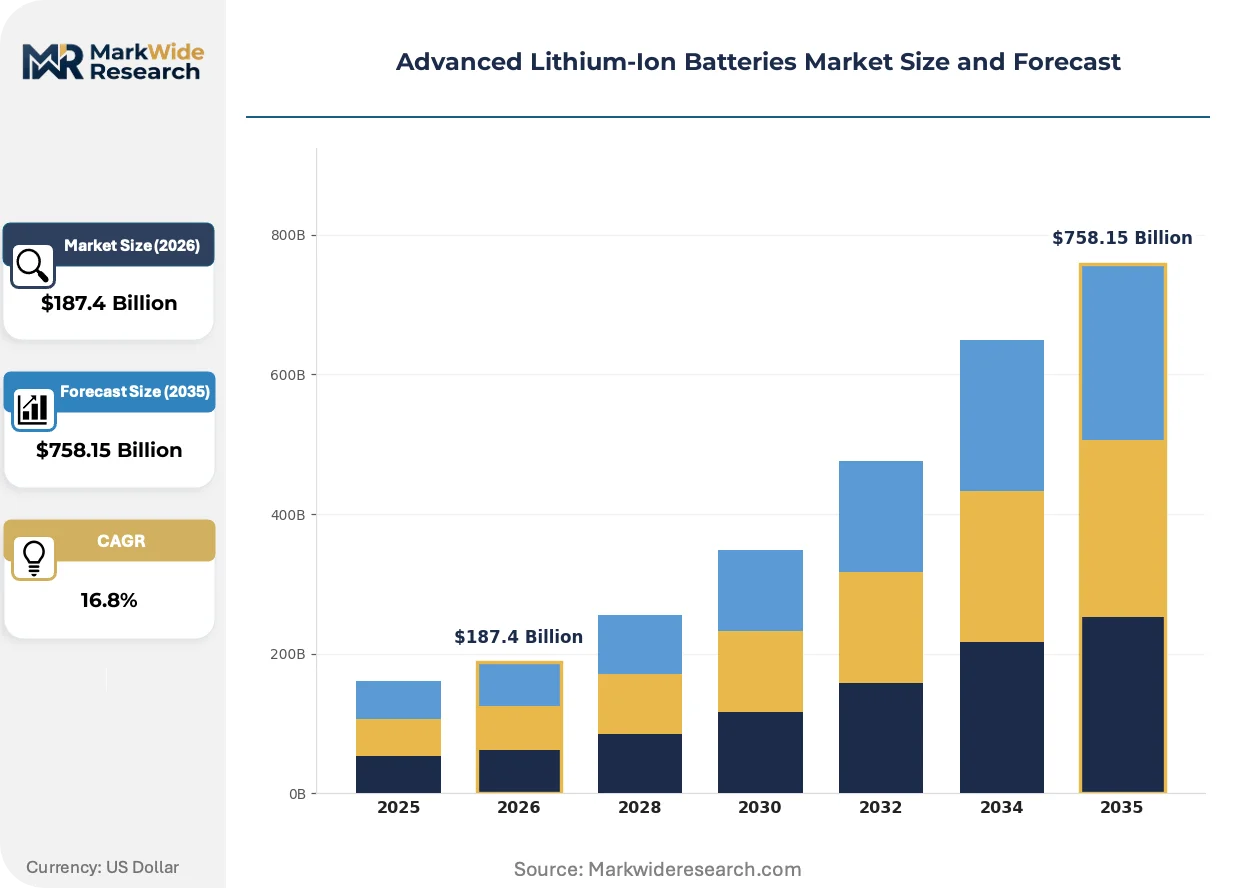
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $758.15 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cylindrical, Prismatic, Pouch, Coin Application: Consumer Electronics, Electric Vehicles, Energy Storage Systems, Power Tools Technology: Lithium Cobalt Oxide, Lithium Iron Phosphate, Lithium Manganese Oxide, Lithium Nickel Manganese Cobalt End User: Automotive, Healthcare, Aerospace, Industrial |
| Companies Covered | CATL, LG Energy Solution, Panasonic Holdings Corporation, BYD, Samsung SDI, A123 Systems, SK Innovation, Toshiba, Northvolt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Lithium-Ion Batteries Market Emerging Trajectories
Solid-state electrolyte commercialization is compressing the gap between laboratory energy density achievements and manufacturable cell formats. Three concurrent developments are determining which technical pathways reach volume production first.
Silicon composite anodes are electrifying the transition from graphite-dominant architectures. Cell manufacturers specify 5-10% silicon oxide blends for 2024-2025 electric vehicle platforms. The structural consequence is a 15-20% gravimetric energy density gain that enables smaller pack footprints without sacrificing range targets.
REACH substance restrictions and the EU Battery Regulation's carbon footprint methodology are forcing cathode chemistry selection toward lower-cobalt, European-sourced precursor options. Industrial consequence includes accelerated LFP qualification for stationary storage and NMC 622 persistence where 811 faces supply uncertainty. Germany's KBA type-approval processes are now incorporating end-of-life recycling accountability into homologation requirements.
Automotive OEMs are consolidating cell procurement around long-term offtake agreements with gigafactory operators, displacing spot-market purchasing. Tier-1 suppliers are responding by offering pack-level integration services rather than standalone module sales. This concentration is most visible in South Korea, where Hyundai-Kia and SK On have aligned cylindrical and prismatic sourcing across Ioniq and EV6 platforms.
Advanced Lithium-Ion Batteries Market Segmentation
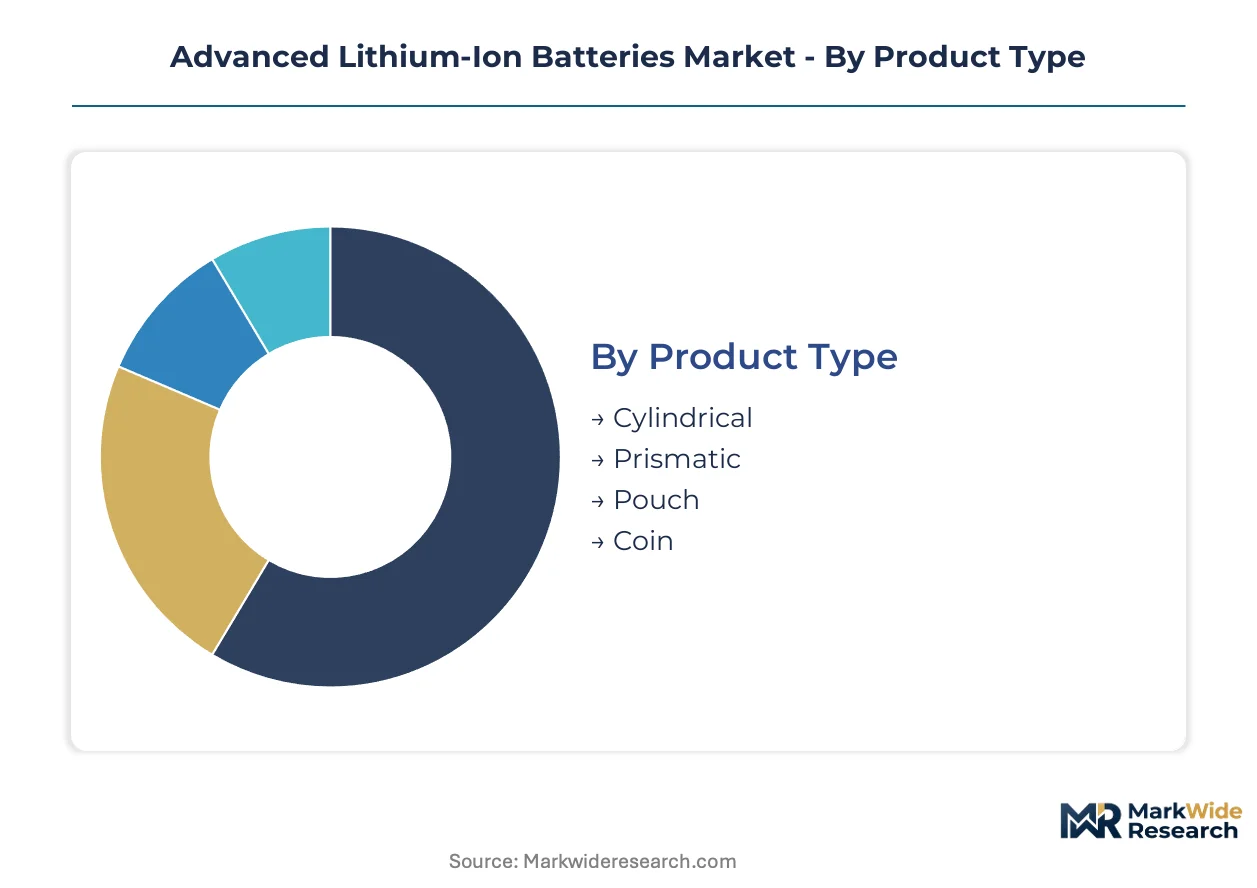
Cell format, chemistry, and end-use specifications create distinct manufacturing footprints and margin structures across the advanced lithium-ion battery value chain. Procurement patterns diverge sharply between automotive volume contracts and aerospace qualification timelines.
Product Type:
Standardized formats dominate high-volume automotive procurement, while custom dimensions persist in medical and satellite applications where packaging flexibility commands premium positioning.
- Cylindrical:2170 and 4680 formats achieve manufacturing scale through automated winding and laser welding. Tesla and BMW specify cylindrical cells for structural battery pack integration, where cell-to-pack architectures eliminate module-level costs.
- Prismatic:Aluminum-cased cells with stacked electrode configurations optimize volumetric efficiency for passenger vehicle platforms. CATL and BYD deploy prismatic formats with cell-to-pack designs that reduce component count.
- Pouch:Laminated polymer aluminum packaging enables non-rectangular geometries for space-constrained installations. Medical device manufacturers and satellite operators specify pouch cells where gram-level weight reduction justifies higher unit costs.
- Coin:Compact manganese dioxide chemistry serves hearing aids, wearables, and IoT sensors with sub-100mAh capacity requirements. Japanese manufacturers maintain specialized production lines for healthcare OEM qualification cycles.
Most installed capacity flows through Cylindrical formats. Expansion is steepest in Prismatic configurations.
Application:
Volume concentration versus margin capture splits this category between automotive scale and stationary storage durability requirements.
- Electric Vehicles:Long-range platforms specify nickel-rich cathodes exceeding 300 Wh/kg at cell level. OEMs consolidate procurement around multi-year offtake agreements with gigafactory operators to secure precursor supply.
- Energy Storage Systems:Lithium iron phosphate chemistry dominates grid-scale installations for cycle life exceeding 6,000 deep discharges. Utility procurement emphasizes 20-year operational warranties over energy density metrics.
- Consumer Electronics:Smartphones and laptops drive demand for cobalt-containing cathodes prioritizing volumetric density. Fast-charging protocols above 100W reshape thermal management specifications.
- Power Tools:High-discharge cylindrical cells enable cordless professional equipment with sustained 50A output. Milwaukee and DeWalt specify 2170 formats with nickel-manganese-cobalt chemistry for torque-intensive applications.
Revenue concentrates in Electric Vehicles. Stationary storage applications are expanding most quickly.
Technology:
Cathode chemistry selection trades energy density against thermal stability, raw material cost, and regulatory compliance across end-use segments.
- Lithium Nickel Manganese Cobalt:NMC 811 and 9½½ formulations deliver highest gravimetric density for premium electric vehicle platforms. Nickel sulfate supply concentration in Indonesia creates precursor procurement risk for European cell manufacturers.
- Lithium Iron Phosphate:Iron and phosphate precursors eliminate cobalt and nickel dependency. CATL and BYD dominate LFP production for Chinese domestic market buses and entry-level passenger vehicles.
- Lithium Cobalt Oxide:Layered oxide structure maximizes volumetric density for smartphone and laptop applications. Consumer electronics OEMs absorb cobalt price volatility through six-month supply contracts.
- Lithium Manganese Oxide:Spinel structure offers cost positioning for power tools and medical devices where moderate energy density suffices. Manganese ore supply from South Africa and Gabon shapes regional cost structures.
Manufacturing volume concentrates in Lithium Nickel Manganese Cobalt. Lithium Iron Phosphate is gaining share fastest.
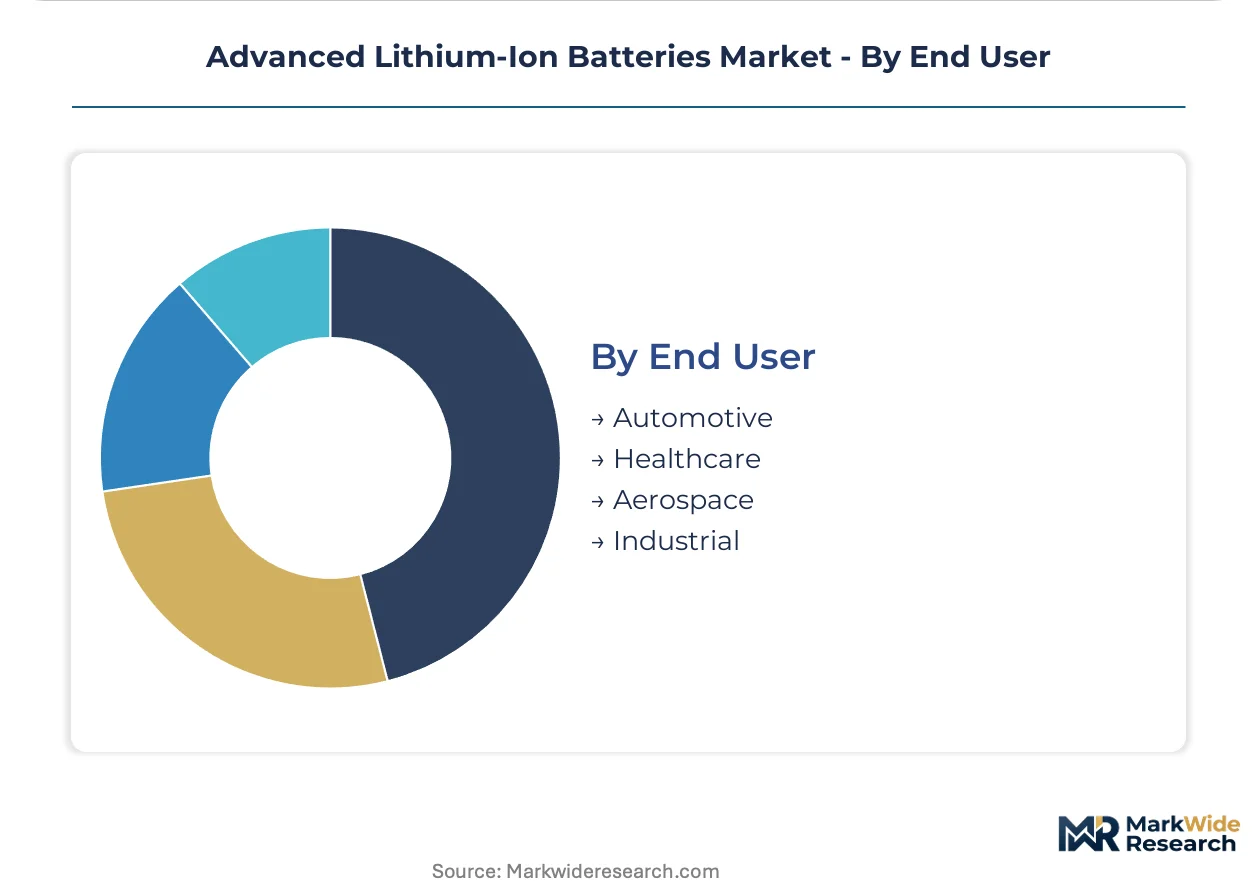
End User:
Qualification timelines and performance warranties create distinct customer archetypes with diverging procurement behaviors.
- Automotive:Cell suppliers undergo 24-36 month qualification cycles including abuse testing and thermal runaway propagation studies. OEMs specify traceability from mine to module for conflict mineral compliance.
- Industrial:Forklift and material handling equipment operators prioritize cycle life over energy density for multi-shift operations. Lead-acid replacement demand drives 48V and 80V pack configurations.
- Healthcare:FDA and EU MDR regulations govern implantable and external medical device batteries. Pacemaker manufacturers specify 10-year minimum service life with sub-microamp discharge profiles.
- Aerospace:Satellite operators and urban air mobility developers require UN 38.3 certification plus RTCA DO-311 qualification for aviation applications. Pouch formats dominate non-cylindrical battery compartments.
Procurement volume concentrates in Automotive. Qualification intensity peaks in Aerospace.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive corridor anchors the European cell manufacturing footprint, with gigafactory siting near Wolfsburg, Stuttgart, and Munich assembly plants compressing logistics costs for cathode active material delivery. The report identifies five countries where production gravity and regulatory frameworks are reshaping competitive positioning.
China
Ningde and Shenzhen host the dominant cathode precursor and cell manufacturing clusters. SAMR enforces GB standards for cell safety testing that exporters must satisfy for market access. The dual carbon goals and NMPA accelerated approval pathways are compressing solid-state commercialization timelines by 18-24 months.
Germany
KBA type-approval processes now incorporate end-of-life recycling accountability into homologation requirements for electric vehicle platforms. The EU Battery Regulation mandates carbon footprint declarations and recycled content quotas, creating first-mover advantage for European-sourced active materials. Northvolt's gigafactory in Heide anchors the northern European supply corridor.
United States
IRA production tax credits are pulling cathode precursor investments toward Texas and the Great Lakes manufacturing belt. FDA device regulations and EPA hazardous material frameworks govern cell transport and medical device integration. The Pacific Northwest hosts specialized facilities for aerospace pouch format qualification.
South Korea
Seoul Capital Area cell manufacturers anchor cylindrical and prismatic supply for premium electric vehicle platforms. MFDS oversees battery safety standards for medical device integration. SK On and LG Energy Solution operations in Ochang and Ochang Science Industrial Complex concentrate cylindrical specialization capacity.
India
PLI scheme incentives for advanced chemistry cell manufacturing are attracting cathode precursor investments to Gujarat and Tamil Nadu. BIS standards govern cell safety testing for domestic market access. The Delhi-Mumbai Industrial Corridor is emerging as a logistics hub for raw material import and cell assembly.
Advanced Lithium-Ion Batteries Market Vendor Landscape
Capacity expansion dominates the current landscape as manufacturers race to secure cathode precursor supply and solid-state electrolyte qualification timelines. The vendor base concentrates around Asian conglomerates with integrated mining-to-cell operations, European challengers building regional supply independence, and specialized format producers. Three archetypes define positioning: vertically integrated material-to-cell operators, format-specialized technology licensors, and regional pure-play gigafactory developers. M&A activity and long-term automotive offtake agreements are the dominant competitive vectors compressing spot-market participation.
Among Asian conglomerates, CATL, LG Energy Solution, and Samsung SDI occupy positions reflecting distinct format specialization strategies. CATL exemplifies the vertically integrated archetype through captive precursor supply and prismatic format dominance. LG Energy Solution represents cylindrical specialization for premium automotive platforms. Samsung SDI anchors the prismatic-industrial tier targeting energy storage system applications. These three entities collectively illustrate how geographic origin and format focus determine competitive positioning within the advanced lithium-ion battery value chain.
| Leading Market Players |
|---|
| CATL |
| LG Energy Solution |
| Panasonic Holdings Corporation |
| BYD |
| Samsung SDI |
| A123 Systems |
| SK Innovation |
| Toshiba |
| Northvolt |
| Others |
Supply Flow & Price Mechanics
Performance-grade divergence between automotive-grade cells and industrial storage units manifests in contract structures that tie cathode active material costs to nickel sulfate indices, while commodity LFP pricing anchors to iron phosphate spot markets with minimal volatility premium. This bifurcation concentrates margin capture in high-nickel formulations where precursor supply scarcity amplifies pricing power, whereas standardized LFP procurement runs through annual volume agreements with limited renegotiation flexibility.
Pricing Analysis
Input-cost pass-through from nickel sulfate and lithium carbonate volatility dominates contract renegotiation cycles for NMC 811 and 9½½ formulations. Pricing stratifies across premium cylindrical formats for structural battery packs, standard prismatic cells for passenger vehicles, and economy-tier LFP blocks for grid storage. Cost compression in high-nickel cathodes intensifies as Indonesian ore export restrictions tighten precursor availability. Automotive OEMs exhibit lowest price sensitivity due to qualification lock-in, while industrial forklift operators demand fixed-price five-year service agreements.
Supply Chain Analysis
Single-source vulnerability sits with synthetic graphite processing in Shandong and Heilongjiang provinces, where environmental compliance shutdowns disrupt anode supply for non-Chinese cell manufacturers. Cathode precursor production draws from Indonesia, China, and South Korea, with nickel sulfate refining anchored in Sulawesi and Morowali. Tariff exposure on Chinese cell imports into the United States and Europe is accelerating regional assembly investments. Distribution runs through gigafactory direct delivery to OEM assembly plants, bypassing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The advanced lithium-ion battery market functions as a stable compounder where electric vehicle platform electrification mandates create demand visibility across decade-long procurement horizons.
For Market Incumbents: Deepen captive precursor supply through backward integration into nickel sulfate refining and synthetic graphite processing to offset Indonesian export volatility. Secure multi-year offtake agreements with European automotive OEMs before EU Battery Regulation recycled content quotas harden qualification requirements. Expand prismatic format capacity in Germany's automotive corridor to exploit logistics cost advantages over Asian imports. For New Entrants and Emerging Players: India's PLI scheme for advanced chemistry cell manufacturing opens a window for LFP-focused producers to capture bus and two-wheeler electrification demand before domestic incumbents scale. Target Gujarat and Tamil Nadu for cathode precursor co-location with port access. Pursue technology licensing partnerships with established electrolyte suppliers rather than competing on proprietary chemistry development. For Investors and Strategic Acquirers: Consolidation pressure builds where solid-state electrolyte patent portfolios overlap with automotive qualification timelines, creating acquisition targets among thin-film processing specialists. Frame long-term viability around five-to-ten-year cathode chemistry transition windows rather than near-term format market share. Watch for NMPA solid-state pilot line approvals as the inflection signal for commercialization timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Cathode Precursor Backward Integration | Captive nickel sulfate supply from Indonesian operations insulates margin from export restriction volatility. |
| Solid-State Electrolyte Pilot Line Investment | NMPA accelerated approval pathways compress qualification timelines versus conventional liquid electrolyte routes. |
| Regional Gigafactory Siting | Proximity to Wolfsburg and Stuttgart assembly plants reduces cathode active material logistics costs. |
| LFP Chemistry Scale-Up | Iron phosphate qualification for grid storage captures utility procurement emphasizing 20-year operational warranties. |
| Automotive Offtake Agreement Structuring | Multi-year volume commitments with OEMs displace spot-market participation and secure precursor allocation priority. |
Methodological Framework
Bottom-up electric vehicle and energy storage system modeling reconciled against top-down cathode active material production tracking forms the analytical core. Primary interviews with cell manufacturing executives, automotive platform engineers, utility procurement officers, and precursor supply chain managers combined with secondary validation from SAMR GB standards filings, EPA hazardous material transport records, and EU Battery Regulation implementation guidance. Trade data from customs authorities and gigafactory construction permits triangulate capacity expansion timelines against demand projections.
Input-output matrices map cathode chemistry selection to end-use energy density requirements across cylindrical, prismatic, and pouch format demand. Segmentation dimensions include cell format, cathode chemistry tier, application intensity, and regional regulatory cluster. CAGRs derive from installed base replacement cycles and electric vehicle platform launch schedules. Forecast inputs incorporate nickel sulfate price trajectories and solid-state electrolyte manufacturing yield assumptions.
Revisions become necessary when Indonesian mining policy shifts, solid-state electrolyte manufacturing breakthroughs, or automotive OEM platform cancellations materialize. Forecasts reflect documented assumptions regarding cathode precursor supply concentration and qualification timeline compression. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Lithium-Ion (Li-Ion) Batteries Market
Lithium-ion Battery
Europe NMC Battery Pack Market
Lithium-ion Battery
Italy Electric Vehicle Battery Materials Market
Lithium-ion Battery
France Electric Vehicle Lithium-Ion Battery Separator Market
Lithium-ion Battery
Industrial Lithium-Ion Batteries Market
Lithium-ion Battery
France SLI Battery Market
Lithium-ion Battery
Global Lithium Ion Cell and Battery Pack Market
Lithium-ion Battery
UAV Lithium Battery Market
Lithium-ion Battery
Lithium Ion Energy Accumulator Market
Lithium-ion Battery
Germany SLI Battery Market
Lithium-ion Battery
Prismatic Lithium Cobalt Oxide (LiCoO2) Battery Market
Lithium-ion Battery
China SLI Battery Market
Lithium-ion Battery
France Electric Vehicle Battery Electrolyte Market
Lithium-ion Battery
Lithium Ion Battery Cathodes Market
Lithium-ion Battery
North America Lithium-Ion Battery Market
Lithium-ion Battery
HEV Li-Ion Battery Market