
 Solar Updraft Tower Market | 2026-2036
Solar Updraft Tower Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Updraft Tower Market Analytics
Chinese state-backed solar thermal developers is rebalancing upstream component sourcing for chimney and collector infrastructure. EnviroMission Limited anchors Australian project development through extended site control and thermal storage integration. BrightSource Energy leverages its concentrated solar power expertise to differentiate in hybrid tower configurations. Hanwha Q CELLS GmbH competes on module supply chain scale for collector field deployments.
A solar updraft tower functions as a thermal power plant using a greenhouse collector to heat air beneath a transparent canopy, driving turbines at the base of a central chimney typically exceeding 500 meters in height; the buoyancy differential generates continuous electricity regardless of direct beam availability. The technology serves baseload-compatible renewable generation for grid-stabilized desert and semi-arid zones. Thermal and hybrid technology segments lead current project pipelines, while electricity generation applications dominate operational installations. Rural installation types concentrate margin pools due to lower land acquisition friction and fewer aviation clearance constraints.
EPA guidelines on renewable energy siting influence US project permitting timelines, while EU Green Deal renewable targets and REACH material standards shape European collector component specifications. China's MIIT governs domestic turbine efficiency certifications under GB standards for grid-connected thermal plants. Stakeholders must monitor evolving national renewable auction designs that increasingly value dispatchable clean capacity over intermittent generation.
Market Dynamics
The EU Green Deal's renewable energy directives are compressing project development timelines as member states accelerate feasibility studies for dispatchable clean capacity, while China's MIIT turbine efficiency certifications under GB standards are reshaping equipment sourcing patterns for grid-connected thermal plants.
Growth Catalysts
- Utility-scale renewable procurement:Government-backed power purchasers in Spain's arid interior regions are expanding tender volumes where land availability and solar irradiance converge favorably for collector field deployments.
- EU Green Deal renewable targets:The directive's dispatchable capacity valuation mechanisms are accelerating project bankability assessments for baseload-compatible generation technologies.
- Thermal storage integration:Molten salt and concrete-based thermal mass systems are extending generation duration beyond daylight hours, improving capacity factor economics for grid stabilization contracts.
Market Restraints
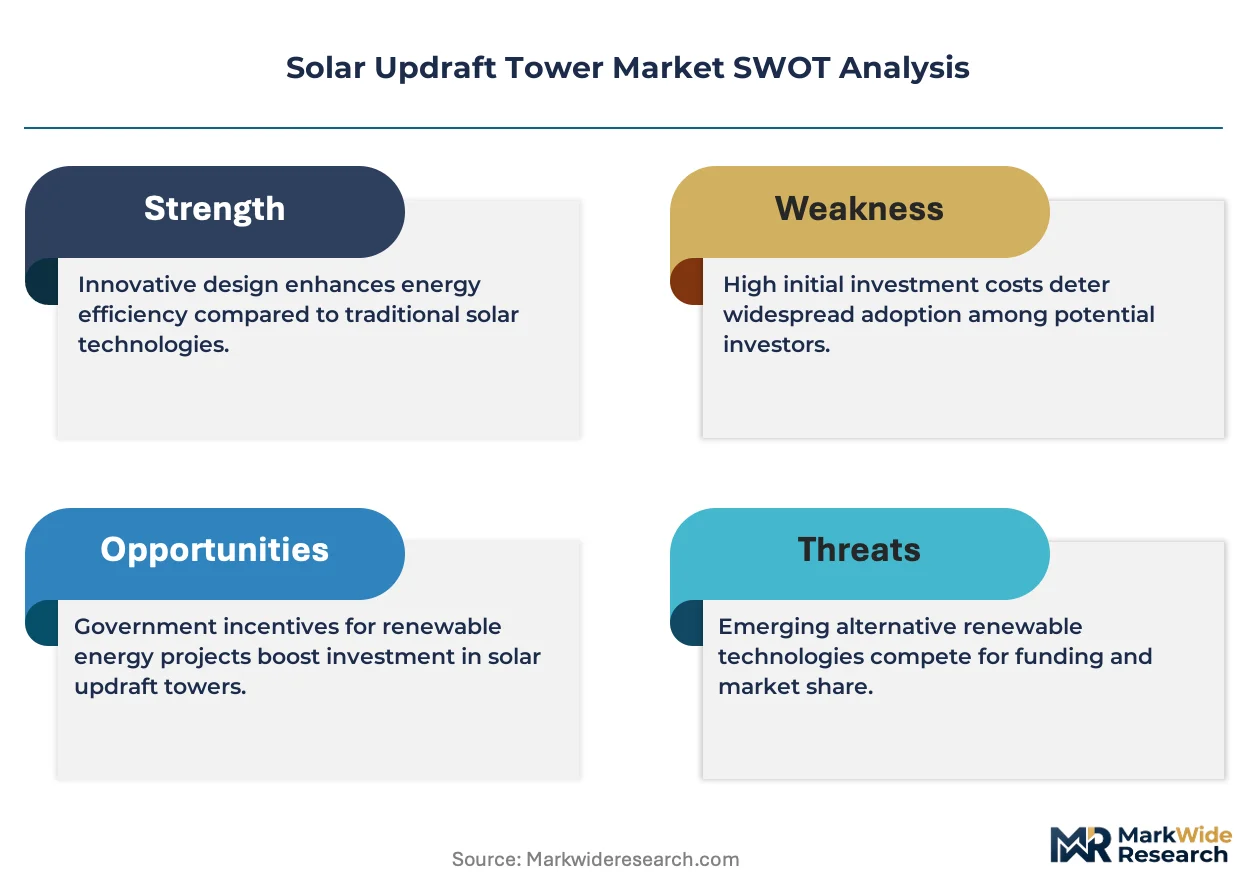
- Chimney construction cost volatility:Reinforced concrete and steel input prices fluctuate with regional cement supply constraints, compressing developer margins on fixed-price EPC contracts.
- Aviation clearance friction:Structures exceeding 500 meters trigger extended FAA and national civil aviation authority review timelines in proximity to flight corridors.
- Photovoltaic substitution pressure:Crystalline silicon module cost declines are diverting capital toward conventional solar farms with faster permitting cycles.
Strategic Opportunities
- Hybrid tower configurations:Concentrated solar power collectors integrated with updraft chimneys are absorbing developer interest for dispatchable renewable portfolios.
- Rural installation concentration:Lower land acquisition friction and reduced aviation constraints in Australia's interior regions are concentrating margin pools for early movers.
- REACH material standards compliance:EU collector component specifications are creating first-mover advantages for suppliers with pre-certified transparent canopy materials.
Industry Challenges
- Structural engineering specialization gap:Tall chimney aerodynamic modeling and seismic design expertise remains concentrated among a limited pool of infrastructure engineering consultancies.
- Grid interconnection certification timelines:GB standard turbine efficiency testing and grid code compliance procedures in China extend equipment qualification periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Updraft Tower Market |
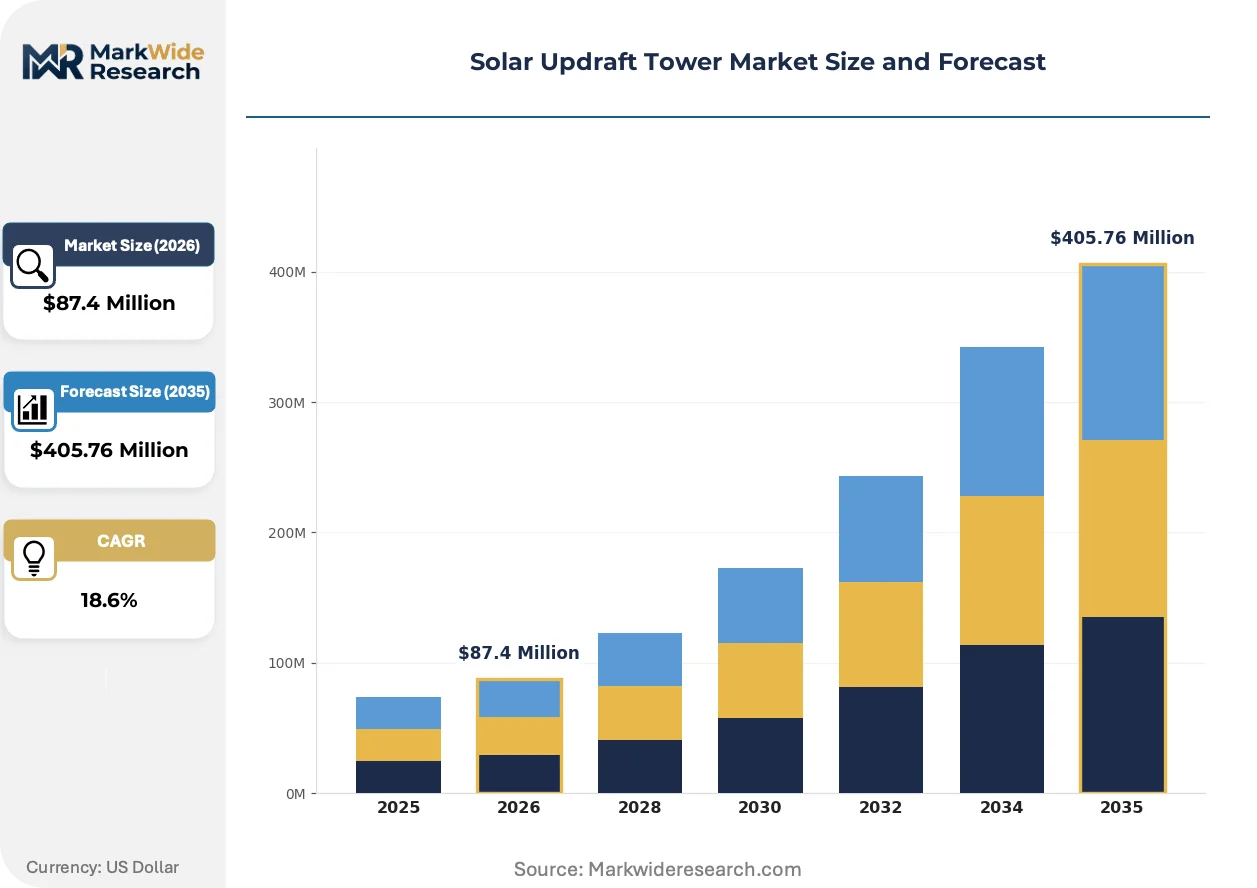
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $405.76 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Thermal, Hybrid, Solar Chimney, Turbine Application: Electricity Generation, Water Desalination, Industrial Heating, Environmental Cooling End User: Utilities, Government, Industrial Sectors, Commercial Buildings Installation Type: Onshore, Offshore, Urban, Rural |
| Companies Covered | SunCentral, SunPower Corporation, EnviroMission Limited, Pivot Energy Inc., BrightSource Energy, Enel Green Power, Atlantis Solar, Hanwha Q CELLS GmbH, Hyperion Solar Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Updraft Tower Market Evolving Landscape
Transparent polymer canopy materials are absorbing R&D investment as developers seek weight reductions and improved optical transmission, while regulatory frameworks across multiple geographies are recalibrating to value continuous renewable generation over intermittent alternatives.
Advanced polymer composite chimney liners are absorbing thermal cycling stresses more effectively than conventional concrete, enabling taller structures with reduced maintenance intervals. Spanish project developers are piloting these materials in collector field prototypes. The technology is absorbing capital from EPC contractors seeking to differentiate on structural longevity warranties.
EPA guidelines on renewable energy siting are extending US project permitting timelines as state-level implementation varies, while REACH material standards are mandating phthalate-free transparent canopy formulations in European supply chains. Collector component manufacturers are reformulating polymer specifications to maintain EU market access.
Power purchase agreement structures are compressing contract tenor preferences among utility offtakers, with fifteen-year terms displacing earlier twenty-five-year arrangements. Grid operators in semi-arid zones are prioritizing dispatchable capacity guarantees over energy-only pricing. This behavioral shift is most visible in Australian and Spanish procurement frameworks where baseload-compatible renewables command premium tariffs.
Solar Updraft Tower Market Segmentation
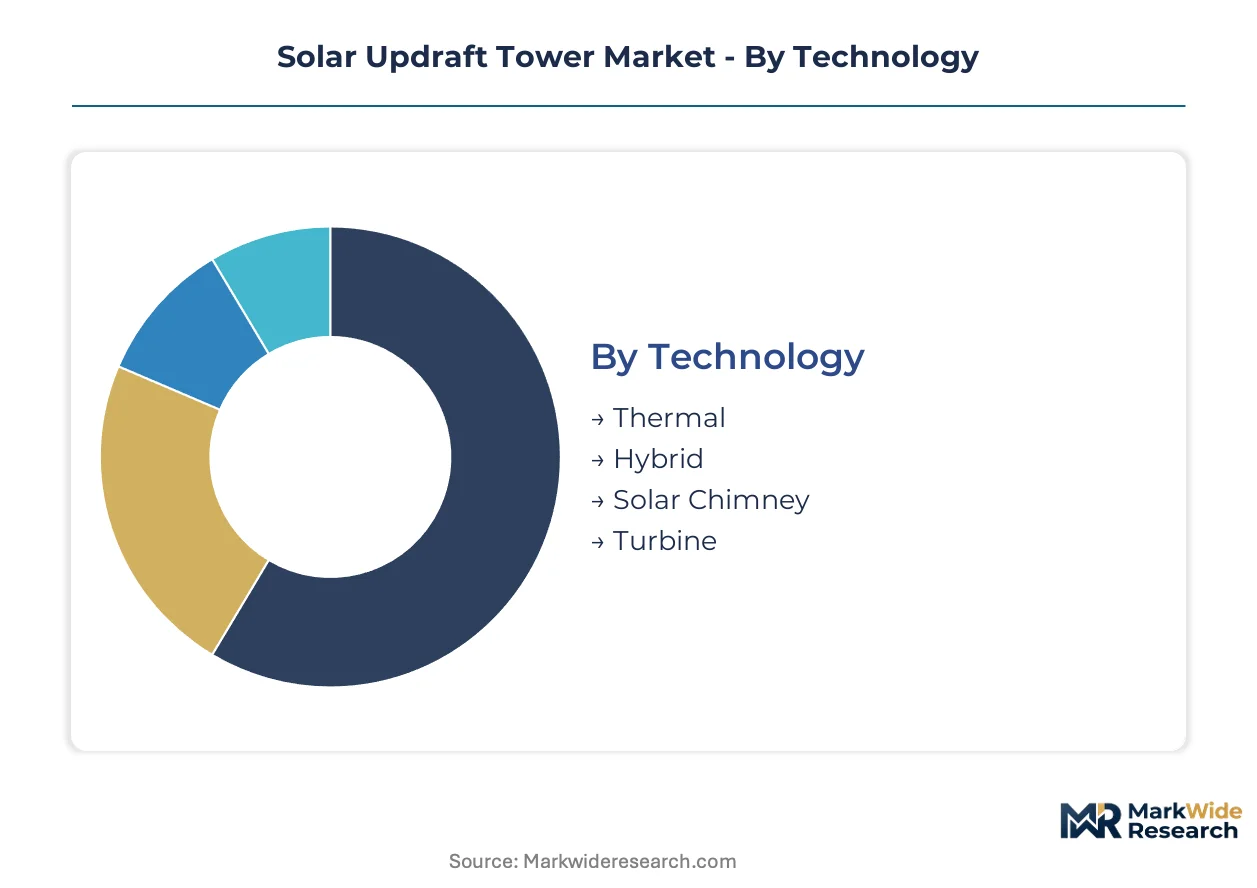
Solar updraft tower deployment economics diverge sharply across technology configurations and site conditions. Segmentation reveals where capital concentrates versus where margins erode, guiding procurement strategy and project bankability assessments.
Technology:
Thermal systems operate as standalone installations with integrated collector-chimney-turbine arrays, while hybrid configurations embed concentrated solar power elements or photovoltaic augmentation into the base infrastructure.
- Thermal:Pure buoyancy-driven systems rely on greenhouse collectors exceeding 100 hectares to heat air masses beneath transparent canopies, driving axial turbines at chimney bases. Spanish developers in Castilla-La Mancha prioritize this configuration for its construction simplicity and proven operational track record in arid interior zones.
- Hybrid:CSP-augmented towers integrate parabolic trough collectors or heliostat fields at the collector perimeter, boosting air temperature differentials and extending generation duration. Australian project pipelines favor this approach for dispatchable capacity contracts requiring evening peak coverage.
- Solar Chimney:Simplified variants omit turbine infrastructure to serve passive ventilation or water pumping applications in remote agricultural settings.
- Turbine:Modular turbine subsystems support retrofit installations at existing industrial chimney structures, reducing greenfield capital requirements.
Thermal configurations lead volumes today; hybrid systems are gaining share fastest on dispatchability premiums.
Application:
Electricity generation commands capital deployment scale, while water desalination and industrial process applications embed towers within larger facility footprints.
- Electricity Generation:Grid-connected baseload supply dominates project economics, with 500-meter-plus chimneys driving continuous turbine operation regardless of direct beam intermittency. EU Green Deal procurement mechanisms in Spain and Italy concentrate tender volumes here.
- Water Desalination:Low-grade thermal output powers multi-effect distillation or membrane thermal processes, pairing favorably with coastal installations in North Africa and the Middle East where freshwater scarcity intersects with solar resource abundance.
- Industrial Heating:Process heat delivery at 80-150°C serves cement curing, mineral processing, and agricultural drying applications with lower chimney height requirements.
- Environmental Cooling:Passive downdraft configurations reverse airflow patterns to provide district cooling in urban peripheries with limited grid interconnection capacity.
Electricity generation leads volumes today; water desalination is climbing the fastest on coastal infrastructure investment cycles.
End User:
Utility offtakers anchor procurement scale through sovereign-backed auctions, while government direct ownership and industrial captive use occupy contrasting risk-return positions.
- Utilities:Grid operators in Spain, Australia, and South Africa issue fifteen-year power purchase agreements with baseload-compatible tariff structures, concentrating developer attention on utility-scale collector field dimensions.
- Government:Direct public ownership models prevail in Gulf Cooperation Council states and Chinese provincial demonstration programs, absorbing technology risk through state balance sheets rather than commercial project finance.
- Industrial Sectors:Mining and mineral processing operators in Chile and Australia pursue captive generation to offset diesel dependence at remote extraction sites.
- Commercial Buildings:District-scale installations serve university campuses and industrial parks with combined heating and cooling loads, though chimney height constraints limit deployment to low-rise peripheries.
Utilities lead volumes today; industrial sectors are expanding most quickly on remote site electrification mandates.
Installation Type:
Rural siting dominates margin pools through lower land acquisition friction and reduced aviation clearance complexity, while urban and offshore variants remain developmental.
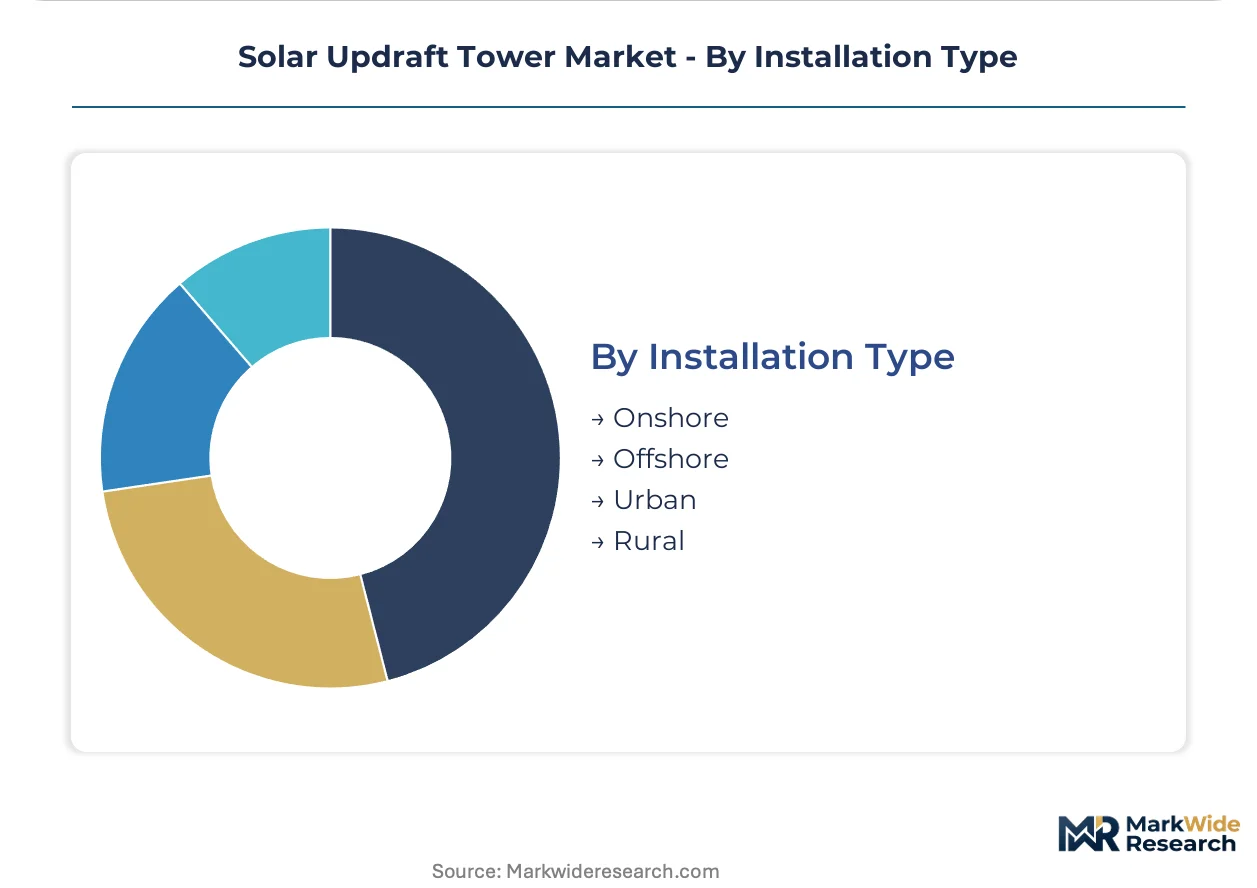
- Rural:Arid interior regions in Spain, Australia, and South Africa offer contiguous land parcels exceeding 500 hectares with minimal elevation change, enabling optimal collector field geometry and streamlined FAA and civil aviation authority approvals.
- Onshore:Coastal and near-urban installations balance grid interconnection proximity against land value premiums, requiring compressed collector footprints or hybrid configurations to maintain project returns.
- Urban:Retrofit applications at existing industrial chimney structures or district cooling installations face severe height restrictions and shadowing constraints from surrounding development.
- Offshore:Floating collector platform concepts remain pre-commercial, with structural engineering challenges around platform stability and salt corrosion resistance unresolved at scale.
Rural installations lead volumes today; onshore configurations are advancing most rapidly on transmission-accessible brownfield sites.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials are redirecting project development capital toward jurisdictions with streamlined permitting and favorable land-use frameworks. Spain's arid interior zones and Australia's remote regions currently absorb the bulk of feasibility investment, while emerging markets compete on aviation clearance efficiency and grid interconnection speed.
Spain
Castilla-La Mancha and Extremadura host the densest concentration of collector field pilots, driven by EU Green Deal renewable procurement mandates and sovereign-backed power auctions. The country's national renewable energy regulator accelerates grid code compliance for dispatchable baseload technologies. Spanish engineering consultancies in Madrid and Barcelona dominate chimney aerodynamic modeling contracts for European project pipelines.
Australia
Remote mining electrification mandates and diesel displacement targets in Western Australia and South Australia propel captive generation interest. The country's Clean Energy Regulator certifies large-scale generation certificates for thermal storage-integrated installations. EnviroMission Limited anchors development activity through extended site control across the nation's interior arid zones.
China
Provincial demonstration programs in Inner Mongolia and Gansu absorb state balance sheet risk for technology validation at scale. MIIT turbine efficiency certifications under GB standards reshape equipment sourcing patterns for grid-connected thermal plants. Domestic EPC contractors in Beijing and Shanghai concentrate chimney construction expertise for export market competition.
United States
Southwest desert states including Arizona and Nevada evaluate collector field deployment against concentrated solar power alternatives. EPA renewable energy siting guidelines extend permitting timelines as state-level implementation varies regionally. BrightSource Energy leverages California-based concentrated solar power engineering heritage for hybrid tower configuration development.
South Africa
Northern Cape solar irradiance and Transnet freight corridor proximity attract utility-scale procurement interest from Eskom and independent power producers. The country's national energy regulator evaluates baseload-compatible renewable tariffs under updated integrated resource plan frameworks. Mining operators in the Bushveld Igneous Complex explore captive generation to offset grid reliability constraints.
Solar Updraft Tower Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue hybrid configuration specialization and thermal storage integration. The vendor base stratifies across three maturity levels: legacy concentrated solar power developers repurposing expertise, pure-play updraft tower specialists securing site control, and diversified renewable EPC contractors bidding on collector field infrastructure. Competitive positioning hardens around chimney construction warranties, thermal storage duration guarantees, and aviation clearance execution speed. Consolidation pressure concentrates among engineering consultancies with tall-structure seismic design capabilities.
Within the pure-play development tier, EnviroMission Limited and BrightSource Energy exemplify contrasting geographic anchoring strategies. EnviroMission Limited occupies a position emphasizing extended site control and thermal storage integration across Australian interior regions. BrightSource Energy represents the legacy concentrated solar power archetype, leveraging CSP engineering heritage for hybrid tower differentiation. Hanwha Q CELLS GmbH sits within the module supply chain tier, competing on collector field deployment scale. SunPower Corporation anchors the photovoltaic-adjacent segment, with project development capabilities informing collector canopy material specifications.
| Leading Market Players |
|---|
| SunCentral |
| SunPower Corporation |
| EnviroMission Limited |
| Pivot Energy Inc. |
| BrightSource Energy |
| Enel Green Power |
| Atlantis Solar |
| Hanwha Q CELLS GmbH |
| Hyperion Solar Energy |
| Others |
Value Network & Pricing Analysis
Sovereign-backed demonstration programs in China and Gulf Cooperation Council states anchor upstream component procurement, compressing margin variability for private developers competing against state-subsidized EPC bids. This ownership pattern tethers pricing discipline to cement and steel input cost cycles while concentrating supply negotiations around GB-standard turbine certifications and REACH-compliant canopy materials.
Pricing Analysis
Direct-to-utility offtake contracts dominate channel economics, with fifteen-year power purchase agreements displacing earlier twenty-five-year tenures as grid operators prioritize dispatchable capacity guarantees. Price differentiation separates thermal storage-integrated installations from pure buoyancy systems, while crystalline silicon substitution pressure intensifies cost compression in collector field deployments. Rural installation buyers exhibit highest price sensitivity due to land acquisition friction differentials, whereas mining sector captive generators absorb premium tariffs for diesel displacement reliability.
Supply Chain Analysis
GB standard turbine efficiency certifications and REACH material compliance gates concentrate equipment sourcing among Chinese and European suppliers with pre-certified manufacturing lines. Reinforced concrete and advanced polymer composite chimney materials draw from Spain, Australia, and China, while transparent canopy polymers rest on German and Japanese optical-grade resin production. Single-source vulnerability runs through tall-structure seismic engineering consultancies concentrated in Madrid and Barcelona. Distribution runs through sovereign-backed auction mechanisms rather than spot procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The solar updraft tower market compounds steadily as baseload-compatible renewable procurement mandates harden across EU and Australian grid codes. Utility offtaker preference shifts toward dispatchable clean capacity anchor predictable demand visibility.
For Market Incumbents: Anticipate photovoltaic substitution threats by deepening thermal storage integration capabilities and securing extended site control in Australia's interior arid zones. Reinforced concrete cost volatility demands fixed-price EPC contract restructuring or captive cement supply arrangements. Chimney construction warranty differentiation remains the critical defensive lever against emerging hybrid configuration specialists. For New Entrants and Emerging Players: Digital-channel engineering procurement platforms offer lower-friction entry for modular turbine subsystem retrofits at existing industrial chimney structures. White-space concentration sits with coastal water desalination applications in North Africa and Middle East markets where freshwater scarcity intersects with solar resource abundance. Target captive generation mandates at remote Chilean and Australian mining extraction sites through diesel displacement reliability guarantees. For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play updraft tower developers with extended site control but unfinanced project pipelines. Long-term viability framing centers on technology maturation through sovereign demonstration programs and subsequent commercial bankability transition. Monitor aviation clearance execution timelines as the critical inflection signal—projects securing FAA and civil aviation authority approvals within standard windows indicate regulatory pathway de-risking.| Strategic Initiative | Industry Significance |
|---|---|
| Thermal Storage Integration | Molten salt systems extend generation duration for Australian evening peak coverage contracts. |
| Hybrid Configuration Development | CSP-augmented towers absorb Spanish and Australian dispatchable capacity premiums. |
| Advanced Polymer Composite Deployment | Spanish pilot programs validate chimney liner durability for reduced maintenance intervals. |
| Extended Site Control Securing | EnviroMission's Australian interior land positions demonstrate margin protection through land scarcity. |
| REACH Material Certification Investment | Pre-certified transparent canopy formulations secure EU collector component market access. |
Research Methodology
Bottom-up electricity generation modeling reconciled against top-down collector field deployment tracking forms the analytical core. Primary interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators combine with secondary validation from EIA data, IEA renewable technology reports, FERC interconnection filings, and EU Green Deal procurement mechanism disclosures. Cross-referencing bottom-up project pipeline assessments against top-down sovereign auction volume announcements ensures triangulation integrity.
Historical trendline analysis of utility-scale renewable procurement volumes and thermal storage integration rates informs projection frameworks across the analysis window. Segmentation dimensions span technology configuration, application type, end-user category, and installation geography, with CAGRs derived from regression-weighted capacity buildout assumptions. Forecast inputs incorporate aviation clearance timeline distributions and grid code compliance duration patterns specific to semi-arid zone deployment economics.
The model assumes a particular technology adoption path favoring hybrid configurations with thermal storage; alternative pathways emphasizing pure thermal simplicity or photovoltaic substitution would alter the outlook. Forecasts reflect assumptions around sovereign-backed demonstration program continuity and EU Green Deal procurement mandate durability. A model refresh is warranted upon material change in national renewable auction designs valuing dispatchable capacity premiums.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
South America Solar Tracker Market
Solar Power Systems
Outdoor Solar LED Market
Solar Power Systems
South America Rooftop Solar Market
Solar Power Systems
North America Concentrated Solar Power (CSP) Market
Solar Power Systems
Iran Solar Energy Market
Solar Power Systems
Kuwait Solar Energy Market
Solar Power Systems
On-Site Photovoltaic Solar Power for Data Centers Market
Solar Power Systems
Bacteria Powered Solar Cell Market
Solar Power Systems
Thin Film Solar PV Market
Solar Power Systems
Solar Pontoon Market
Solar Power Systems
Germany Distributed Solar Power Generation Market
Solar Power Systems
Flat Plate Solar Collector Market
Solar Power Systems
Solar PV Inverter Market
Solar Power Systems
Commercial Solar Panel Market
Solar Power Systems
Home Solar System Market
Solar Power Systems
United Kingdom Solar Power Market