
 Asia Pacific Electric Vehicle VRLA Batteries Market | 2026-2036
Asia Pacific Electric Vehicle VRLA Batteries Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Electric Vehicle VRLA Batteries Market Insights
Lead is expanding its cost advantage over lithium-ion chemistries in price-sensitive commercial EV segments across South and Southeast Asia. GS Yuasa Corporation leverages its Japanese manufacturing base to supply OEM-grade VRLA systems for hybrid electric buses. Amara Raja Energy and Mobility Ltd. anchors the Indian aftermarket through its extensive dealer network serving fleet operators in Chennai and Hyderabad. Leoch International Technology Limited competes on volume production of gel-type batteries for electric two-wheelers exported from its Guangdong facilities.
Asia Pacific electric vehicle VRLA batteries are rechargeable lead-acid cells utilizing immobilized electrolyte in either absorbed glass mat or gel form, typically operating at 12V nominal with 30-100Ah capacity ranges and designed for deep-cycle duty in partial state-of-charge conditions common to urban stop-start driving profiles. Their primary purpose is to provide cost-effective energy storage for low-speed electric vehicles, auxiliary power units, and starter-lighting-ignition functions in hybrid architectures where full electrification remains economically prohibitive. Absorbent glass mat variants dominate unit volumes due to superior vibration resistance demanded by India's autorickshaw electrification programs and Thailand's tuk-tuk conversion schemes. Gel batteries sustain premium positioning in tropical climates where elevated ambient temperatures accelerate conventional flooded cell degradation. The aftermarket provider channel captures disproportionate margin pools as fleet operators prioritize rapid swap-out programs over OEM warranty service in Indonesia and Vietnam.
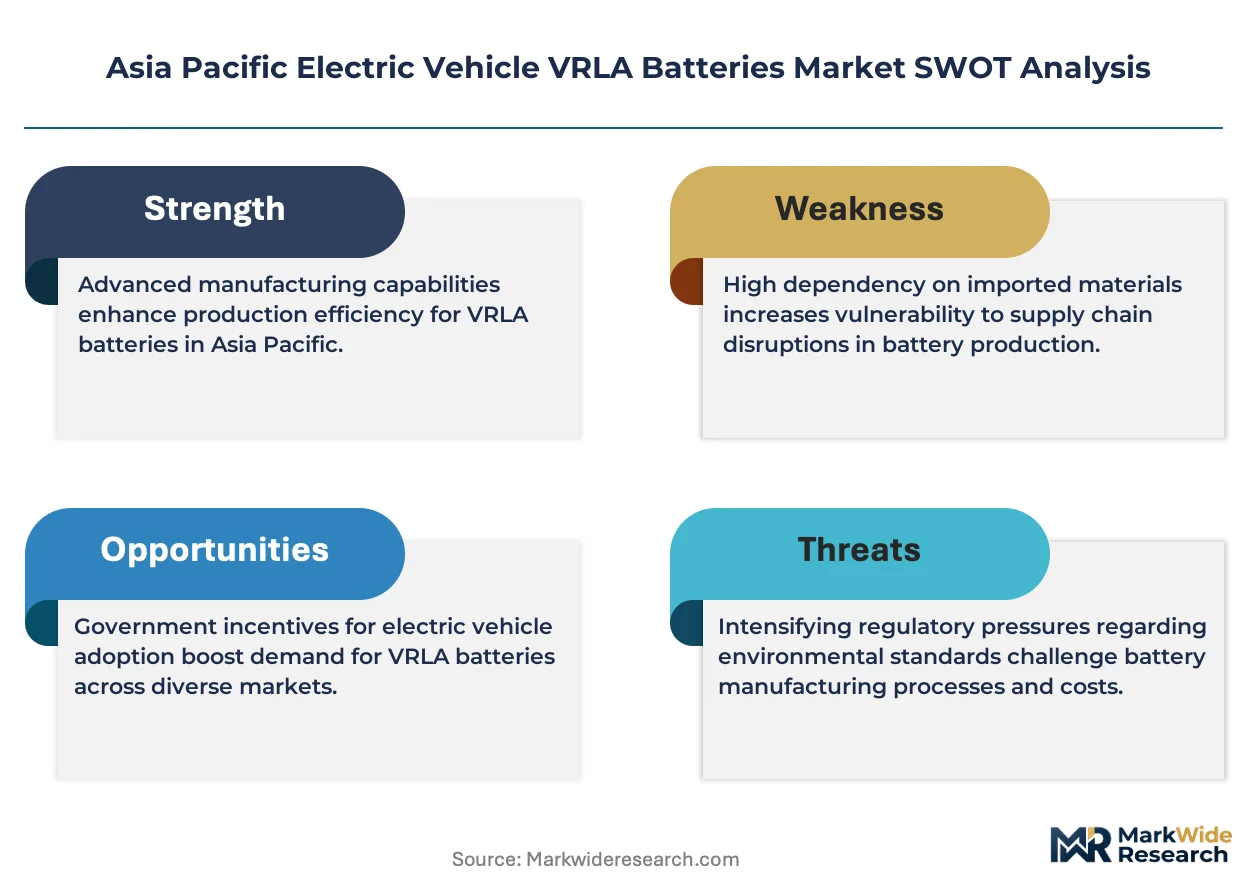
India's BIS certification mandates and China's GB/T standards for lead-acid battery recycling create compliance thresholds that favor established manufacturers with certified closed-loop collection infrastructure. Japan's METI battery safety guidelines and South Korea's MFDS-aligned environmental regulations further constrain market entry for uncertified imports. Thailand's Board of Investment incentives for EV component localization are reshaping supplier geography as Japanese and Korean battery makers establish regional assembly plants. Stakeholders must monitor how Indonesia's downstream nickel processing ambitions and evolving ASEAN harmonized standards for battery traceability will alter raw material sourcing economics and cross-border certification requirements.
Market Dynamics
India's PLI scheme for advanced chemistry cell manufacturing is redirecting capital flows toward domestic battery assembly capacity, compressing import dependency while simultaneously creating stranded asset risk for pure lead-acid producers who fail to diversify chemistry portfolios.
Growth Catalysts
- Indonesia's nickel processing expansion:Downstream smelter investments in Sulawesi and Halmahera are reducing raw material transport costs for regional battery manufacturers serving ASEAN electric two-wheeler assembly plants.
- Thailand's BOI component localization incentives:Tax holidays and import duty exemptions for EV parts are attracting Japanese and Korean battery makers to establish regional assembly facilities in the Eastern Economic Corridor.
- Absorbent glass mat technology maturation:Improved plate pasting and separator formulation are extending cycle life in partial state-of-charge duty, matching the stop-start profiles of urban delivery fleets across Southeast Asia.
Market Restraints
- Lithium-ion cost compression:Falling cell prices from Chinese LFP producers are narrowing the historical cost advantage of lead-acid systems in commercial EV segments where total cost of ownership calculations favor energy density.
- Lead price volatility:Concentrated global smelter capacity in China and Australia transmits commodity shocks directly to battery bill-of-materials, eroding margin predictability for regional assemblers.
- Recycling compliance thresholds:India's BIS certification mandates and China's GB/T standards for closed-loop collection infrastructure favor established manufacturers with certified networks, raising effective barriers for new entrants.
Strategic Opportunities
- Vietnam's emerging fleet electrification:Last-mile delivery operators in Ho Chi Minh City and Hanoi are piloting battery swap networks for electric motorcycles, creating aftermarket service revenue pools beyond unit sales.
- Gel battery premium positioning:Tropical climate degradation of conventional flooded cells in Indonesia and Philippines is sustaining price premiums for temperature-resistant VRLA variants in auxiliary power applications.
- ASEAN harmonized traceability standards:Draft regulations for battery passport requirements are creating first-mover advantages for manufacturers with existing digital chain-of-custody systems.
Industry Challenges
- Electrochemical engineering talent scarcity:Regional universities produce insufficient graduates with specialized expertise in lead-acid paste chemistry and formation process optimization, constraining R&D throughput for domestic manufacturers.
- Dual chemistry certification timelines:Fleet operators demanding lithium-compatible service capabilities require parallel technical training and inventory systems, fragmenting working capital deployment.
- Legacy charging infrastructure incompatibility:Existing lead-acid service equipment in India's autorickshaw garages requires retrofit investment to handle mixed battery chemistries, slowing fleet conversion rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Electric Vehicle VRLA Batteries Market |
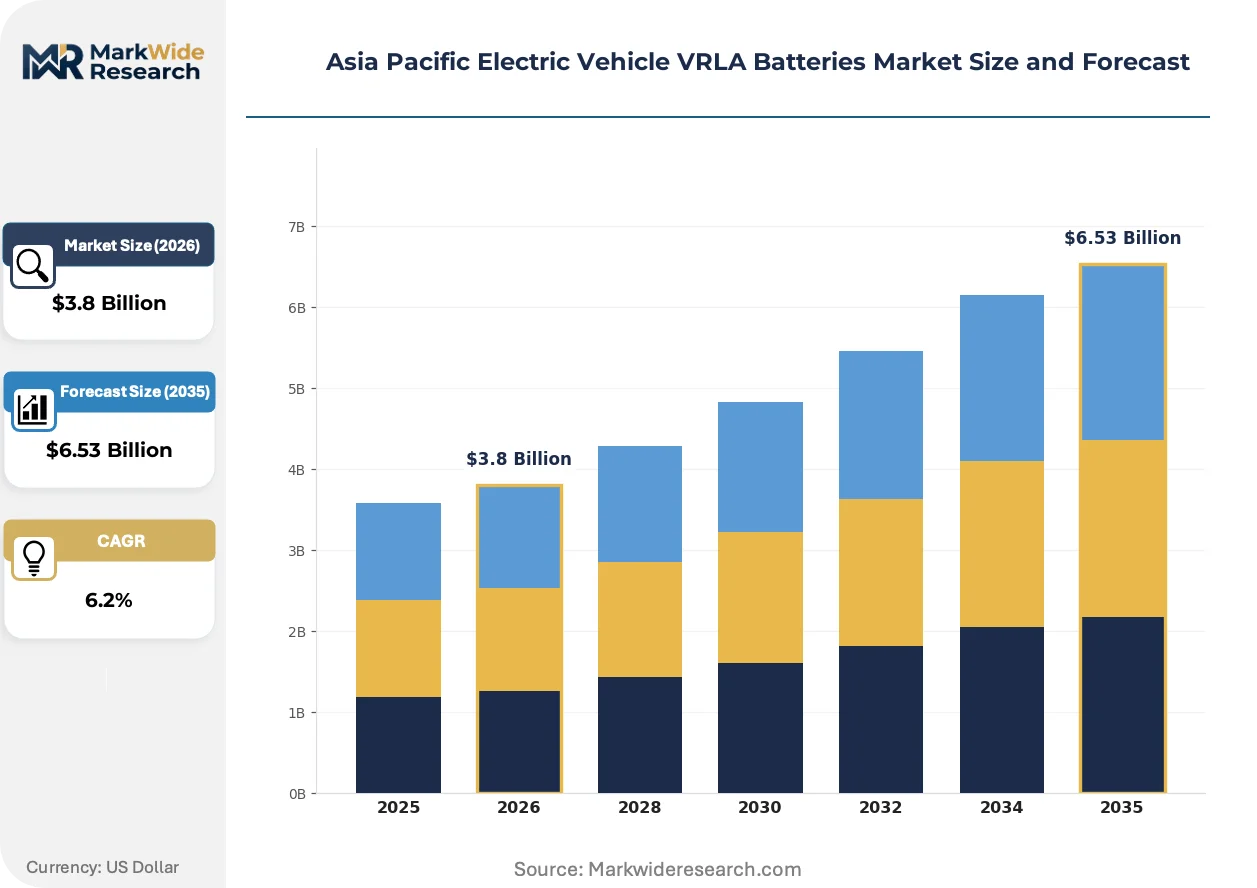
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.53 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Absorbent Glass Mat, Gel, Flooded, Sealed Lead Acid End User: OEMs, Aftermarket Providers, Fleet Operators, Charging Stations Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Public Transport Technology: Lead-Acid, Lithium-Ion, Hybrid, Others |
| Companies Covered | GS Yuasa Corporation, Amara Raja Energy and Mobility Ltd., Leoch International Technology Limited, Exide Technologies, EnerSys, Clarios, East Penn Manufacturing Company, C&D Technologies, Inc., Contemporary Amperex Technology Co. Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Electric Vehicle VRLA Batteries Market Trends and Innovations
Carbon additive formulations and smart battery management integration are redefining performance benchmarks for VRLA systems in hybrid architectures, while regulatory pressure on recycling traceability is forcing supply chain digitization investments.
Silicon-enhanced negative active material is absorbing higher charge acceptance rates in partial state-of-charge cycling, enabling faster regenerative braking energy recovery. Indian electric bus operators in Bengaluru and Delhi are retrofitting AGM systems with carbon-loaded plates to extend daily range without pack replacement. This absorption of advanced carbon structures is compressing the performance gap with entry-level lithium-ion alternatives in price-sensitive municipal procurement.
Japan's METI battery safety guidelines are mandating thermal runaway propagation testing for auxiliary power units in hybrid commercial vehicles, forcing design modifications to cell spacing and venting systems. Korean manufacturers supplying ASEAN markets must align with MFDS-aligned environmental regulations for lead content disclosure, adding documentation overhead. The guidelines most affect gel battery configurations in tropical climate applications where elevated ambient temperatures accelerate degradation mechanisms.
Fleet operators across Indonesia and Vietnam are unbundling after-sales service from OEM warranty programs, prioritizing rapid swap-out capabilities over manufacturer-certified repair networks. Independent battery distributors in Surabaya and Jakarta are capturing margin pools by maintaining regional exchange inventories for commercial van operators. This behavioral shift is most visible in last-mile delivery segments where vehicle downtime costs exceed premium pricing for authorized service channels.
Asia Pacific Electric Vehicle VRLA Batteries Market Segmentation
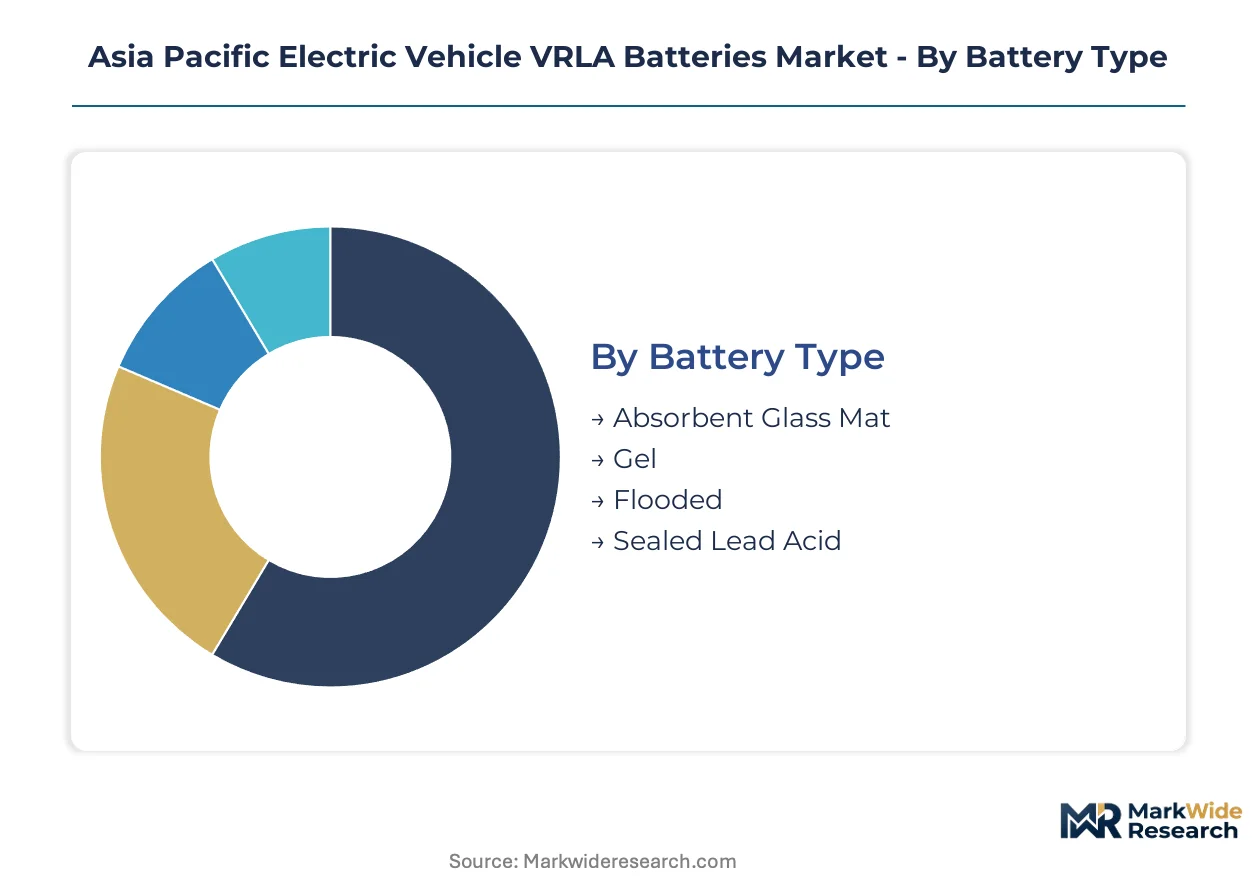
VRLA battery demand fragments across electrochemical architectures, procurement channels, and vehicle duty cycles. Each segmentation axis reveals distinct margin structures and competitive dynamics across the Asia Pacific region.
Battery Type:
Volume concentrates in lower-cost formats serving price-sensitive commercial fleets, while premium positioning attaches to climate-resilient variants.
- Absorbent Glass Mat:Electrolyte immobilized in fiberglass mat separators delivers superior vibration resistance and faster charge acceptance. Demand clusters in India's autorickshaw electrification programs and Thailand's tuk-tuk conversion schemes where rough road conditions dominate. Carbon additive formulations are extending cycle life in partial state-of-charge duty.
- Gel:Silica-thickened electrolyte eliminates stratification and sustains performance across wider temperature ranges. Premium positioning holds in Indonesia and Philippines tropical climates where conventional flooded cells degrade rapidly. Japanese hybrid bus operators specify gel configurations for auxiliary power reliability.
- Flooded:Conventional liquid electrolyte design maintains cost leadership in lowest-price two-wheeler segments.
- Sealed Lead Acid:Maintenance-free construction captures aftermarket swap-out demand from Vietnam's electric motorcycle fleet operators.
Mature deployment sits with Flooded. Newer deployment is concentrated in Absorbent Glass Mat.
End User:
Procurement authority determines warranty terms, technical service requirements, and inventory velocity through distribution channels.
- Fleet Operators:Centralized purchasing of standardized battery packs for delivery van and motorcycle fleets in Ho Chi Minh City, Jakarta, and Surabaya. Unbundled after-sales service prioritizes rapid swap-out capabilities over manufacturer-certified repair networks.
- Aftermarket Providers:Independent distributors capture margin pools by maintaining regional exchange inventories. Dealer networks in Chennai and Hyderabad anchor Indian commercial vehicle service channels.
- OEMs:Original equipment specifications for hybrid bus and low-speed electric vehicle assemblers in China's Guangdong manufacturing zones.
- Charging Stations:Buffer storage applications for grid-stabilized fast-charging infrastructure in metropolitan Thailand.
Aftermarket Providers command the steepest expansion trajectory as fleet operators bypass OEM warranty channels.
Application:
Vehicle duty cycles dictate depth-of-discharge requirements, thermal management needs, and replacement frequency economics.
- Two-Wheelers:Electric motorcycles and scooters dominate unit volumes across ASEAN urban centers. Battery swap pilot programs in Hanoi and Ho Chi Minh City are creating service revenue pools beyond hardware sales.
- Commercial Vehicles:Last-mile delivery vans in Indonesia's emerging manufacturing zones around Jakarta and Batam specify deep-cycle VRLA systems for stop-start urban routing.
- Public Transport:Hybrid electric buses in Bengaluru and Delhi retrofit AGM systems with carbon-loaded plates to extend daily range.
- Passenger Vehicles:Auxiliary power and starter-lighting-ignition functions in hybrid architectures where full electrification remains economically prohibitive.
Two-Wheelers generate highest unit velocity. Commercial Vehicles capture expanding value per pack as electrification scales.
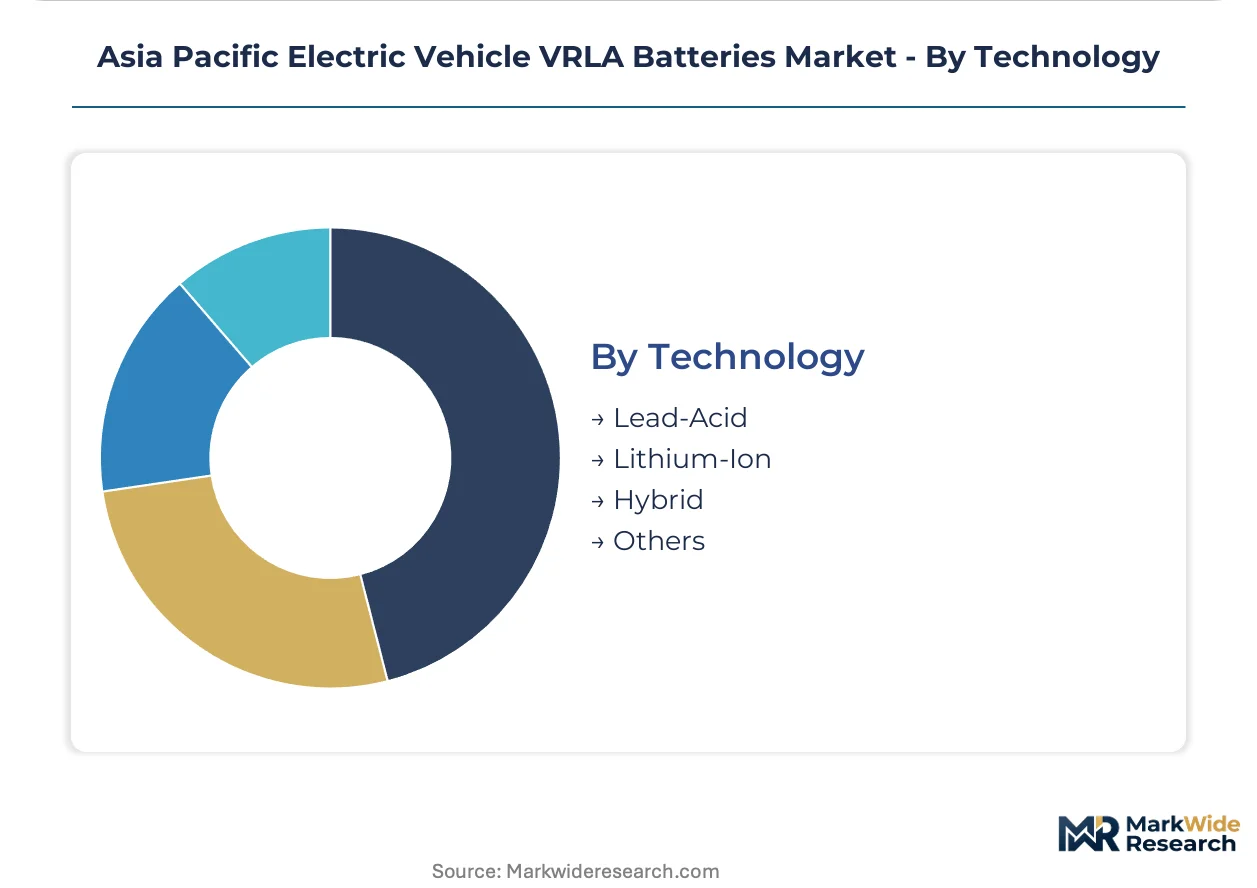
Technology:
Chemistry selection reflects total cost of ownership calculations against energy density requirements and regulatory compliance thresholds.
- Lead-Acid:Established recycling infrastructure and BIS certification compliance anchor cost competitiveness. India's PLI scheme for advanced chemistry cell manufacturing creates stranded asset risk for pure lead-acid producers who fail to diversify.
- Lithium-Ion:Falling LFP cell prices from Chinese producers are narrowing historical cost advantages in commercial EV segments. Dual chemistry certification timelines fragment working capital for service providers.
- Hybrid:Dual-chemistry architectures combining lead-acid starter functions with lithium traction packs in transitional vehicle designs.
- Others:Emerging sodium-ion and solid-state experimental deployments in Japanese R&D programs.
Lead-Acid retains installed base dominance. Lithium-Ion is climbing the fastest in new procurement specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Southeast Asian manufacturing zones and Indian industrial corridors where fleet electrification programs and domestic battery assembly incentives are reshaping procurement geography.
India
Autorickshaw electrification in Chennai and Hyderabad drives absorbent glass mat volumes for rough-road durability. The PLI scheme for advanced chemistry cell manufacturing redirects investment toward domestic battery assembly capacity. Industrial clusters in Tamil Nadu and Telangana anchor aftermarket distribution networks serving commercial fleet operators.
Indonesia
Downstream nickel processing investments in Sulawesi and Halmahera reduce raw material transport costs for regional manufacturers. The country's national industrial regulator mandates environmental compliance thresholds for lead-acid battery recycling infrastructure. Emerging EV manufacturing zones around Jakarta and Batam concentrate demand for deep-cycle VRLA systems in last-mile delivery vans.
Thailand
Tuk-tuk conversion schemes and hybrid bus procurement sustain demand for vibration-resistant battery configurations. Board of Investment incentives for EV component localization attract Japanese and Korean battery makers to the Eastern Economic Corridor. Bangkok metropolitan charging infrastructure creates buffer storage applications for grid-stabilized fast-charging stations.
Vietnam
Last-mile delivery operators in Ho Chi Minh City and Hanoi pilot battery swap networks for electric motorcycles. The country's national standards body aligns with draft ASEAN harmonized traceability regulations for battery passport requirements. Independent distributors in Surabaya and Jakarta capture aftermarket margin pools through rapid swap-out programs.
Japan
Hybrid electric bus operators in Tokyo and Osaka specify gel battery configurations for auxiliary power reliability. METI battery safety guidelines mandate thermal runaway propagation testing for auxiliary power units in hybrid commercial vehicles. Kanto and Kansai manufacturing bases supply OEM-grade VRLA systems for regional export markets.
Asia Pacific Electric Vehicle VRLA Batteries Market Competitive Landscape
Capacity expansion dominates the current landscape as established manufacturers establish regional assembly plants to capture localization incentives. The vendor base separates into three tiers: multinational chemistry specialists with certified closed-loop collection infrastructure, regional volume producers competing on gel-type and AGM formulations, and aftermarket distributors capturing service revenue pools through rapid swap-out networks. Strategic archetypes include Japanese manufacturers leveraging domestic technology bases for OEM supply, Indian firms anchoring aftermarket channels through extensive dealer networks, and Chinese producers competing on scale-driven volume exports. Portfolio diversification and geographic expansion represent the dominant competitive moves as pure lead-acid producers confront stranded asset risk from lithium-ion cost compression.
Within the multinational OEM supply tier, GS Yuasa Corporation represents Japanese manufacturing excellence in hybrid bus auxiliary power systems. Amara Raja Energy and Mobility Ltd. exemplifies the regional aftermarket anchor model through its Indian dealer network concentration. Leoch International Technology Limited occupies the scale-driven export position among Guangdong-based volume producers. These three archetypes illustrate how competitive positioning fragments across technology licensing, distribution depth, and manufacturing scale vectors.
| Leading Market Players |
|---|
| GS Yuasa Corporation |
| Amara Raja Energy and Mobility Ltd. |
| Leoch International Technology Limited |
| Exide Technologies |
| EnerSys |
| Clarios |
| East Penn Manufacturing Company |
| C&D Technologies, Inc. |
| Contemporary Amperex Technology Co. Limited |
| Others |
Pricing and Supply Chain Analysis
Lead-acid battery engineering talent concentration in Tamil Nadu and Guangdong Province feeds labor-cost differentials that widen pricing-tier spreads between premium gel configurations and commodity flooded cells across ASEAN procurement channels.
Pricing Analysis
Volume concentrates in economy-grade AGM systems for India's autorickshaw fleets while margins attach to gel batteries specified for Japanese hybrid bus auxiliary power. Three-tier pricing structure across premium, standard, and economy levels reflects BIS certification grade, carbon additive formulation depth, and after-sales bundling intensity. Cost compression in standard-tier AGM packs is intensifying because Chinese LFP cell prices are narrowing total-cost-of-ownership gaps in commercial van segments. Fleet operators in Jakarta and Surabaya exhibit highest price sensitivity; Japanese OEM procurement teams demonstrate lowest sensitivity due to reliability-weighted total cost calculations.
Supply Chain Analysis
BIS certification and China's GB/T recycling standards gate supplier qualification, favoring established manufacturers with certified closed-loop infrastructure over uncertified imports. Raw lead supply draws from Australian and Chinese smelter concentration, while separator materials and carbon additives rest on Japanese and Korean specialty chemical production. Single-source vulnerability sits with concentrated global lead smelter capacity transmitting commodity shocks directly to regional assemblers. Distribution runs through aftermarket dealer networks in Chennai and Hyderabad anchoring Indian fleet service, alongside independent swap-out distributors capturing margin pools in Indonesian and Vietnamese urban centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified recycling infrastructure scarcity props pricing power for compliant manufacturers as India's PLI scheme for advanced chemistry cells constrains pure lead-acid capacity expansion.
For Market Incumbents: Deepen backward integration into lead smelting and paste chemistry R&D to defend against lithium-ion substitution in commercial EV segments. Secure BIS and GB/T certification renewals ahead of ASEAN harmonized traceability mandates to maintain qualification gating advantages over emerging competitors. For New Entrants and Emerging Players: Aftermarket distributors in Vietnam's battery swap pilot zones represent the most penetrable channel archetype for service-revenue capture beyond hardware margins. Target Ho Chi Minh City and Hanoi electric motorcycle fleet operators through rapid swap-out capability positioning against incumbent OEM warranty channels. For Investors and Strategic Acquirers: The window for entry favors certified closed-loop collection infrastructure owners ahead of ASEAN battery passport requirements. Long-term viability hinges on dual-chemistry service capability buildout; monitor Indonesia's nickel processing expansion timelines as inflection indicator for regional raw material cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Additive Formulation Investment | Extends AGM cycle life in partial state-of-charge duty for Bengaluru electric bus retrofits. |
| ASEAN Certification Pre-Positioning | Captures first-mover advantage in battery passport compliance ahead of harmonized standards. |
| Dual-Chemistry Service Training | Fragments working capital but secures fleet operator loyalty through lithium-compatible capabilities. |
| Regional Assembly Localization | Qualifies for Thailand's BOI tax incentives while reducing logistics exposure to lead price volatility. |
| Aftermarket Swap-Out Network Expansion | Captures margin pools in Indonesian and Vietnamese fleet segments prioritizing uptime over warranty. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with battery plant managers, fleet procurement leads at Indonesian delivery operators, aftermarket distributor principals in Chennai and Surabaya, and R&D directors at Japanese chemistry specialists. Bottom-up triangulation across vehicle registration databases, PLI scheme disbursement records, and nickel smelter investment disclosures reconciled with top-down demand modeling from ASEAN automotive production forecasts.
Data-stream reconciliation across electrochemical architecture splits, procurement channel flows, and vehicle duty cycle applications drove segmentation-specific growth trajectories over the projection horizon. CAGRs derived from installed base turnover rates, replacement frequency economics, and chemistry substitution elasticity parameters. Forecast inputs incorporated India's BIS certification timeline acceleration and Indonesia's downstream nickel processing capacity commissioning schedules.
Caveats apply where lithium-ion cost compression or ASEAN harmonized traceability standard delays could materially shift the outlook. Forecasts reflect assumptions around fleet electrification program continuity and raw material transport cost structures. A model refresh is warranted upon material change in Indonesia's nickel smelter output or India's advanced chemistry cell PLI scheme revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Asia-Pacific Dual Carbon Battery Market
Batteries
Middle East and Africa SLI Battery Market
Batteries
Solid-State Batteries for Electric Vehicles Market
Batteries
Lithium Marine Battery Market
Batteries
Global Primary Cells Market
Batteries
Stationary Lead-Acid Battery Market
Batteries
Rechargeable Coin Cell Market
Batteries
Hybrid Flow Battery Market
Batteries
South Asia Battery Market
Batteries
Nickel Cadmium Battery Market
Batteries
Lithium Pouch Cell Market
Batteries
Forklift Battery Rental Market
Batteries
Lithium Starters Market
Batteries
Tubular GEL Battery Market
Batteries
North America Consumer Battery Market
Batteries
Smart Battery Charger Market