
 Solar Lighting System Market | 2026-2036
Solar Lighting System Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Lighting System Market Intelligence
Chinese photovoltaic module production is broadening cost-competitive supply for integrated solar lighting assemblies. Signify Holding leverages its LED component expertise to control premium commercial fixture lines. Sunna Design anchors autonomous solar street lamp deployments across West African municipalities. Sokoyo Solar Lighting specializes in all-in-one system architectures for emerging-market public pathway budgets.
A solar lighting system converts photovoltaic energy into stored electrical power for illumination through LED arrays, typically incorporating monocrystalline or polycrystalline panels, lithium-based battery banks, and pulse-width modulation charge controllers to regulate discharge cycles. The primary purpose is to deliver grid-independent illumination for outdoor environments where trenching and grid extension prove economically unviable. Solar street lamps occupy the dominant revenue position due to large-scale municipal procurement cycles and longer contract tenors. Solar portable lamps represent the fastest-expanding category, driven by humanitarian relief operations and informal settlement electrification. Solar floodlights concentrate margin pools in commercial perimeter security applications where durability specifications command premium pricing.
FCC equipment authorization governs radio-frequency-enabled motion sensor and remote monitoring modules sold into US installations. The EU Green Deal and associated Ecodesign requirements shape LED efficiency benchmarks and battery recyclability obligations for European system suppliers. India's BIS certification mandates panel efficiency testing and charge controller safety protocols for domestic procurement eligibility. Stakeholders must monitor how diverging national battery chemistry restrictions reshape component sourcing and aftermarket service networks.
Market Dynamics
Lithium iron phosphate battery chemistry is displacing lead-acid storage across new solar lighting deployments, compressing total cost of ownership curves and extending operational lifespans in municipal procurement cycles.
Growth Catalysts
- India's PLI Scheme:Production-linked incentives for solar module manufacturing are expanding domestic assembly capacity for integrated street lighting systems.
- Sub-Saharan Electrification Corridors:Rural electrification programs in Kenya, Nigeria, and Tanzania are channeling development finance into autonomous solar lamp networks.
- LED Efficacy Thresholds:Advances in lumens-per-watt performance are reducing panel and battery sizing requirements for equivalent illumination output.
Market Restraints
- Polysilicon Supply Concentration:Photovoltaic wafer production clusters in Xinjiang create geopolitical exposure for module cost stability.
- Lithium Carbonate Volatility:Battery-grade lithium price swings transmit directly to system bill-of-materials, complicating multi-year municipal contract pricing.
- Technical Degradation in Hot Climates:Lithium-ion cells suffer accelerated capacity fade in ambient temperatures above 45°C, limiting deployment latitude.
Strategic Opportunities
- Humanitarian Relief Channels:Portable solar lamp demand from UNHCR and Red Cross operations represents a high-volume, specification-driven procurement stream.
- EU Battery Passport Mandates:Ecodesign requirements for recyclability documentation are creating first-mover advantage for suppliers with closed-loop material recovery.
- Smart City Convergence:Integration of motion sensors and mesh networking into street luminaires opens data-service revenue layers beyond illumination.
Industry Challenges
- BIS Certification Timelines:India's mandatory panel efficiency testing and charge controller safety protocols extend product qualification cycles by 4-6 months.
- Retrofit Integration Complexity:Legacy sodium-vapor infrastructure in older municipalities requires custom mounting and electrical adaptation for LED-solar upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Lighting System Market |
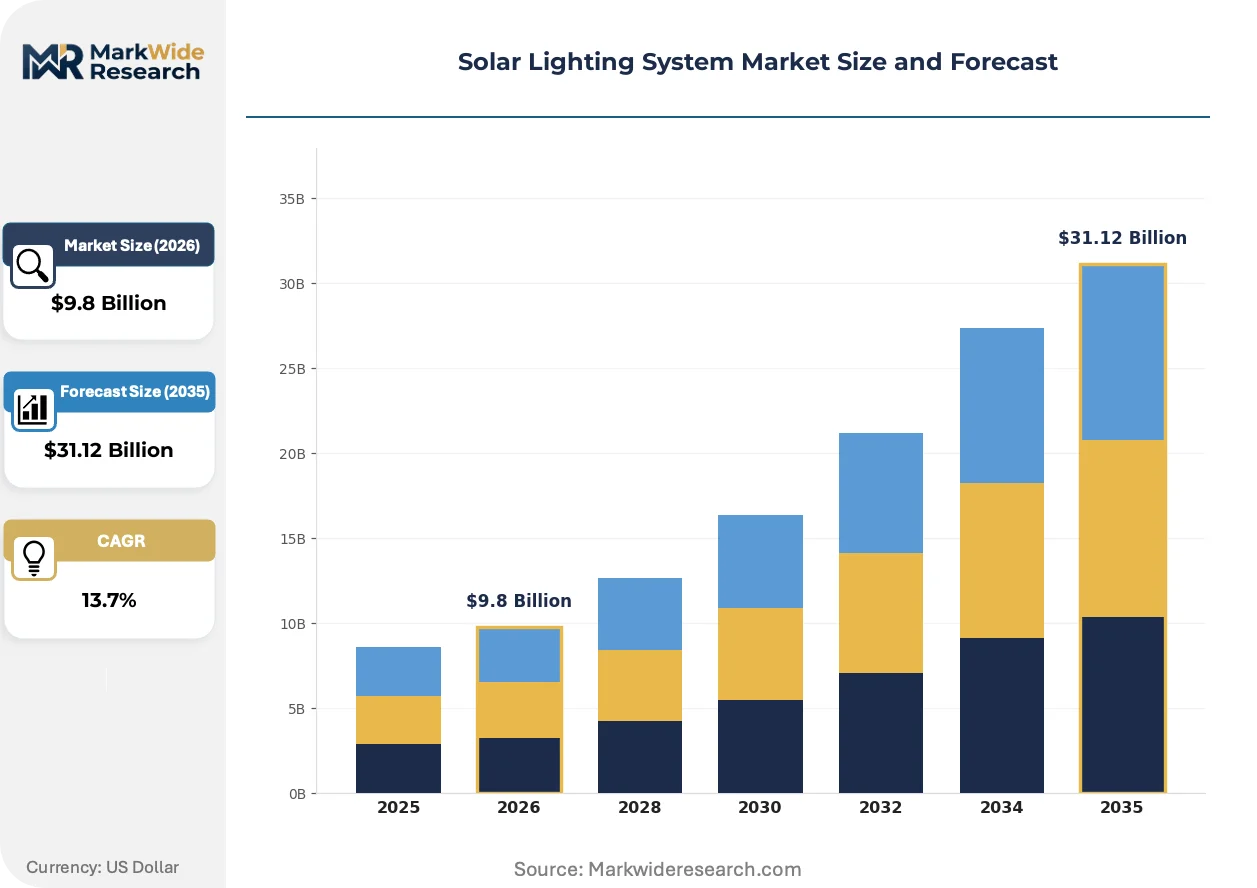
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $31.12 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solar Garden Lights, Solar Street Lamps, Solar Floodlights, Solar Portable Lamps, Solar Wall Lights Technology: Photovoltaic Panels, LED Bulbs, Motion Sensors, Rechargeable Batteries, Charge Controllers Application: Public Pathways, Commercial Premises, Recreational Parks, Agricultural Fields, Urban Plazas End User: Municipal Authorities, Residential Complexes, Hospitality Sector, Educational Institutions, Transportation Facilities |
| Companies Covered | Signify Holding, Sunna Design, Solar Electric Power Company, Greenshine New Energy, Acuity Brands, Eaton Corporation, Sokoyo Solar Lighting, Solektra, Tata Power Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Lighting System Market Strategic Shifts & Innovations
Technology convergence between photovoltaic generation, solid-state storage, and wireless connectivity is redefining what solar lighting systems deliver beyond basic illumination.
Monocrystalline PERC cells are integrating bifacial architectures that harvest reflected ground irradiance, boosting daily energy yield by 8-12% in albedo-rich environments. Municipal buyers in Rajasthan and Arizona are specifying these modules for high-insolation corridors where space constraints limit panel area. The technology is integrating with MPPT charge controllers to maximize harvest during partial shading conditions.
The EU Green Deal's Ecodesign requirements are mandating minimum LED efficacy benchmarks and enforceable battery recyclability obligations for European suppliers. Manufacturers must now document carbon footprints across module assembly and establish take-back programs for end-of-life cells. Commercial perimeter security applications face the steepest compliance costs due to premium durability specifications.
After-sales service unbundling is separating hardware procurement from maintenance contracts in municipal tenders. West African municipalities are piloting performance-based agreements where operators retain ownership and charge per-lumen-hour delivered. This model concentrates in Senegal and Côte d'Ivoire where public sector capex scarcity meets private sector operational capacity.
Solar Lighting System Market Segmentation
Segmentation in solar lighting reveals how capital intensity, technical specifications, and procurement authority reshape competitive positioning across installation types. Understanding these divides exposes where margin pools concentrate and which customer relationships command multi-year contract security.
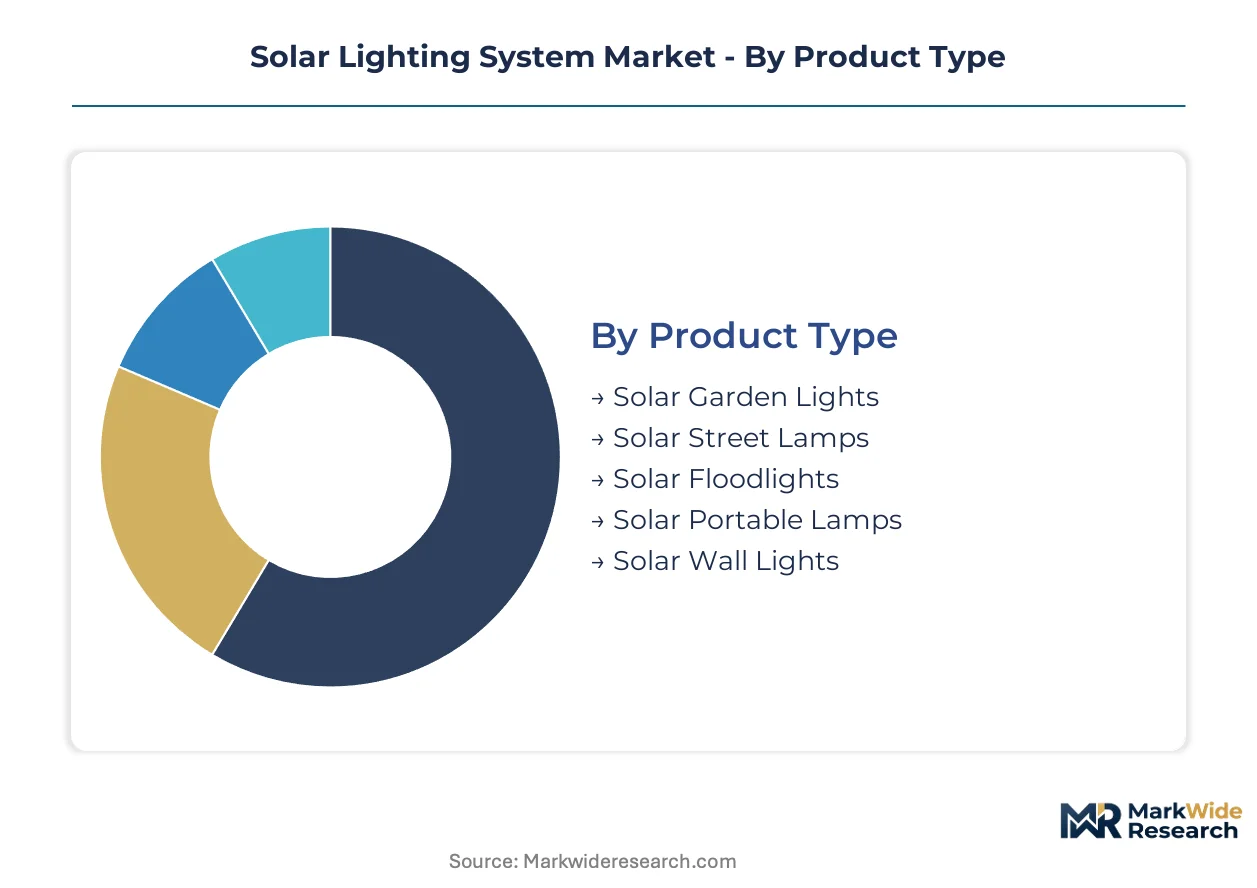
Product Type:
Capital intensity varies sharply across product categories, with municipal-scale infrastructure demanding the heaviest upfront investment in panels, poles, and civil works.
- Solar Street Lamps:Integrated pole-mounted systems incorporate monocrystalline PERC panels, lithium iron phosphate battery banks, and MPPT charge controllers for autonomous operation. Municipal procurement in Rajasthan, Arizona, and Kenyan counties concentrates here due to grid-extension cost avoidance and 10-15 year amortization horizons. Battery degradation in ambient temperatures above 45°C constrains deployment latitude in equatorial zones.
- Solar Portable Lamps:Compact all-in-one units combine small-format panels with lithium-ion cells and USB charging ports for off-grid households. UNHCR and Red Cross operations in sub-Saharan refugee camps and informal settlements drive humanitarian procurement volumes. Durability specifications lag street-grade systems, opening cost-competitive manufacturing in Vietnam and Bangladesh assembly plants.
- Solar Garden Lights:Decorative stake-mounted fixtures with nickel-metal hydride or small lithium cells for residential pathway illumination.
- Solar Floodlights:High-lumen output units for commercial perimeter security with IP65+ ingress protection ratings.
- Solar Wall Lights:Compact facade-mounted units with passive infrared motion sensors for residential entryways and small commercial buildings.
Most installed capacity flows through Solar Street Lamps. Expansion is steepest in Solar Portable Lamps.
Technology:
Component selection determines system reliability curves and aftermarket service requirements across deployment climates.
- Photovoltaic Panels:Monocrystalline PERC cells with bifacial architectures harvest reflected ground irradiance for 8-12% daily yield gains in albedo-rich environments like Rajasthan's desert corridors and Arizona's sunbelt. Polysilicon supply concentration in Xinjiang creates geopolitical exposure for module cost stability. India's PLI scheme is expanding domestic wafer-to-module assembly capacity.
- Rechargeable Batteries:Lithium iron phosphate chemistry is displacing lead-acid storage, compressing total cost of ownership curves and extending operational lifespans. Battery-grade lithium carbonate price volatility transmits directly to system bill-of-materials, complicating multi-year municipal contract pricing in Nigeria and Tanzania.
- LED Bulbs:Solid-state emitters with lumens-per-watt performance advances reducing panel and battery sizing requirements.
- Motion Sensors:Passive infrared and microwave modules enabling demand-responsive illumination and mesh networking integration.
- Charge Controllers:Pulse-width modulation and MPPT architectures regulating discharge cycles and maximizing harvest during partial shading.
Photovoltaic Panels absorb the largest share of bill-of-materials value. Rechargeable Batteries are climbing the fastest as lithium chemistry penetration accelerates.
Application:
Site-specific illumination requirements shape durability specifications and procurement channel access.
- Public Pathways:Linear installations along rural roads and urban walkways requiring uniform spacing and autonomous operation without grid connection. Senegal and Côte d'Ivoire municipalities are piloting performance-based agreements where operators retain ownership and charge per-lumen-hour delivered. Public sector capex scarcity meets private sector operational capacity in these West African deployments.
- Commercial Premises:Perimeter security and parking area illumination where IP ratings and vandal resistance command premium pricing. FCC equipment authorization governs radio-frequency-enabled motion sensor modules sold into US installations. EU Green Deal Ecodesign requirements mandate minimum efficacy benchmarks and battery recyclability obligations.
- Recreational Parks:Aesthetic and safety lighting for pedestrian circulation in green spaces with seasonal usage patterns.
- Agricultural Fields:Remote irrigation access roads and livestock perimeter fencing with minimal maintenance access.
- Urban Plazas:High-visibility civic spaces combining functional illumination with architectural integration requirements.
Public Pathways concentrate the greatest deployment volume. Commercial Premises deliver the steepest margin expansion trajectory.
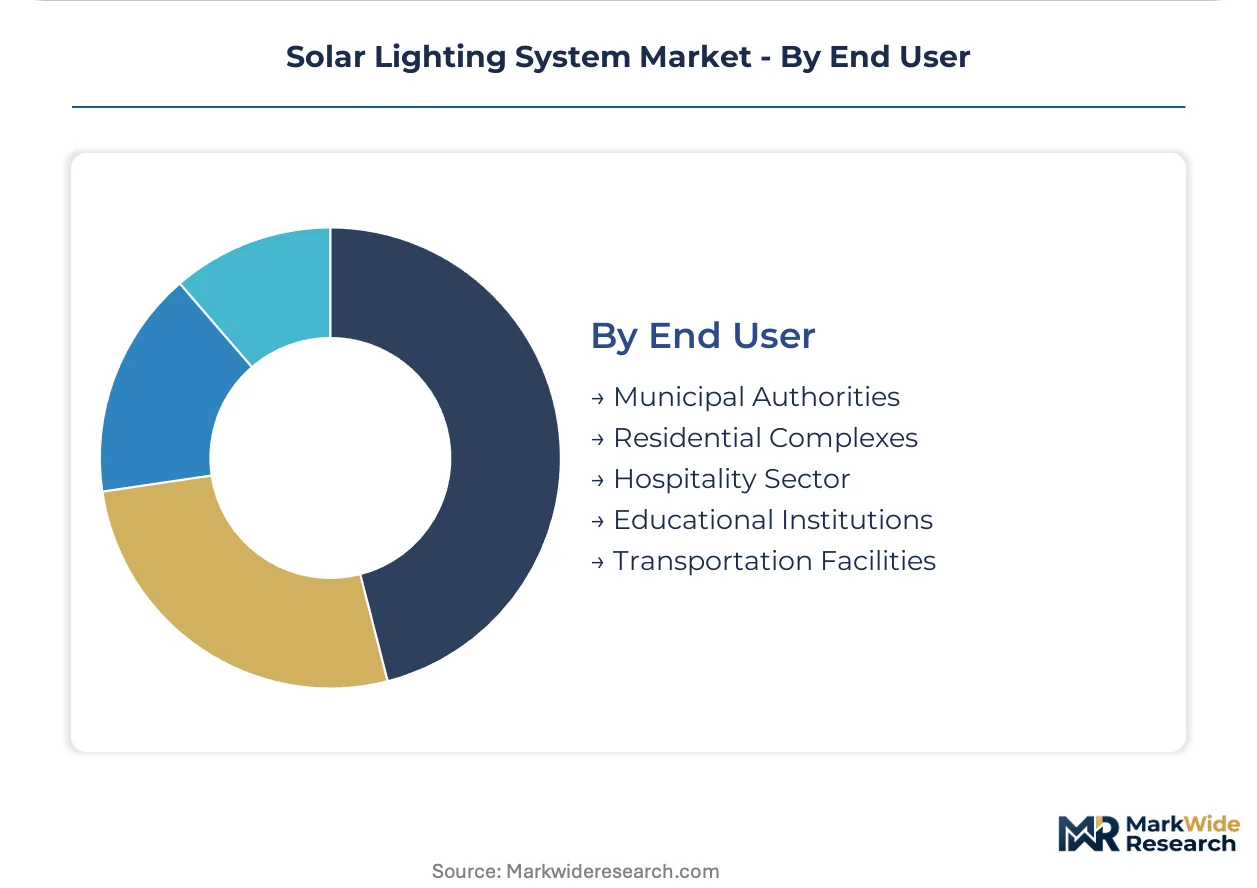
End User:
Procurement authority and budget cycles fragment demand across institutional buyer types with diverging technical sophistication.
- Municipal Authorities:City and county governments with multi-year capital improvement programs and formal tender processes. India's BIS certification mandates panel efficiency testing and charge controller safety protocols, extending product qualification cycles by 4-6 months for domestic procurement eligibility. Legacy sodium-vapor infrastructure in older municipalities requires custom mounting adaptation for LED-solar upgrades.
- Residential Complexes:Gated communities and homeowner associations with distributed decision-making and aesthetic priorities.
- Hospitality Sector:Resorts and hotels seeking off-grid pathway illumination and brand-aligned fixture design.
- Educational Institutions:Schools and universities with sustainability procurement mandates and student safety requirements.
- Transportation Facilities:Airports, ports, and rail terminals with FAA, Coast Guard, or national rail safety compliance obligations.
Municipal Authorities channel the majority of contract value. Educational Institutions are gaining share fastest through sustainability-linked procurement mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping solar lighting production geography. Manufacturers migrate toward jurisdictions where India's PLI scheme and China's wafer-to-module integration compress compliance costs against EU battery passport mandates and US FCC equipment authorization timelines.
India
Rajasthan's desert corridors drive bifacial PERC panel demand for high-albedo installations. The BIS certification mandates panel efficiency testing and charge controller safety protocols, extending qualification cycles by 4-6 months for domestic procurement eligibility. Municipal authorities in Gujarat and Karnataka are expanding off-grid solar street installations under PLI scheme production-linked incentives.
China
Xinjiang's polysilicon production clusters supply cost-competitive photovoltaic wafers for integrated lighting assemblies. The MIIT oversees GB standards compliance for module exports while dual carbon goals accelerate domestic clean energy procurement. Yangtze River Delta manufacturers in Jiangsu and Zhejiang provinces dominate lithium iron phosphate battery integration for export-bound systems.
United States
Arizona's sunbelt municipalities specify high-insolation solar street lamps with 10-15 year amortization horizons. The FCC governs radio-frequency-enabled motion sensor and remote monitoring modules for smart city convergence applications. California and Texas transportation facilities drive commercial perimeter security demand with FAA and state rail safety compliance obligations.
Germany
Industrial machinery corridors in Bavaria and North Rhine-Westphalia anchor LED component expertise for premium commercial fixture lines. The EU Green Deal's Ecodesign requirements mandate minimum LED efficacy benchmarks and enforceable battery recyclability obligations. Berlin-Brandenburg municipalities pilot performance-based agreements separating hardware procurement from maintenance contracts.
Kenya
Rural electrification programs in Nairobi and Mombasa counties channel development finance into autonomous solar lamp networks. The country's national energy regulator oversees off-grid tariff frameworks for public pathway illumination. Kenyan counties concentrate solar portable lamp deployments for refugee camp operations alongside agricultural field perimeter fencing applications.
Solar Lighting System Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue humanitarian relief channels and smart city data-service revenue layers beyond basic illumination. The vendor base stratifies across three tiers: multinational lighting conglomerates with LED component expertise, regional specialists in all-in-one system architectures, and vertically integrated Asian fabricators controlling photovoltaic module supply. Competitive moves concentrate on strategic partnerships for municipal performance-based agreements and technology licensing for mesh networking integration.
Within the multinational tier, Signify Holding and Acuity Brands represent archetypal positions leveraging legacy LED component expertise toward premium commercial fixture lines. Among regional specialists focused on emerging-market deployments, Sunna Design and Sokoyo Solar Lighting exemplify autonomous solar street lamp concentration across West African municipalities. These four entities collectively span the competitive spectrum from high-margin specification-driven procurement to cost-competitive public pathway budgets.
| Leading Market Players |
|---|
| Signify Holding |
| Sunna Design |
| Solar Electric Power Company |
| Greenshine New Energy |
| Acuity Brands |
| Eaton Corporation |
| Sokoyo Solar Lighting |
| Solektra |
| Tata Power Solar |
| Others |
Cost & Logistics Intelligence
Certification-tier divergence between BIS-qualified systems for Indian municipal procurement and uncertified commodity imports for African informal markets manifests in parallel supply chain configurations: domestic assembly plants serving compliance-heavy tenders versus Shenzhen-export hubs feeding cost-driven humanitarian channels.
Pricing Analysis
Distributor margins absorb 18-25% of ex-factory value in African markets where Sokoyo Solar Lighting and Sunna Design compete through regional warehousing networks. Three-tier pricing structure across premium, standard, and economy levels tracks LED efficacy grades and battery chemistry tiers, with lithium iron phosphate systems commanding 40% premiums over lead-acid equivalents. Cost compression in the economy tier intensifies as Vietnamese assemblers enter portable lamp production. Municipal authorities in Kenya and Tanzania exhibit lowest price sensitivity due to development-finance backing; informal settlement households in Nigerian camps show highest sensitivity, driving demand for sub-$15 units.
Supply Chain Analysis
Single-source vulnerability sits with Xinjiang polysilicon purification for photovoltaic wafer feedstock, where four-fifths of global metallurgical-grade silicon originates. Module assembly draws from Jiangsu and Zhejiang provinces in China, with secondary concentration in Gujarat and Karnataka under India's PLI scheme. Lithium carbonate from Chilean salares and Australian spodumene mines feeds Yangtze River Delta cell fabrication. Tariff exposure looms for US-bound systems as domestic content requirements tighten. Distribution runs through Dakar and Lagos regional hubs for West African last-mile deployment, with UNHCR procurement operating through Geneva-based centralized tendering.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards geographic arbitrage between India's BIS-certification infrastructure and China's wafer-cost advantages, with regulatory compliance timelines in Delhi-NCR running 4-6 months against Shenzhen's 3-week export documentation cycles.
For Market Incumbents: Deepen backward integration into lithium iron phosphate cell production to offset carbonate price volatility threatening multi-year municipal contract margins. Fortify certification moats by pre-qualifying systems under Kenya's national energy regulator frameworks before competitors establish local testing partnerships. Channel control through performance-based ownership-retention models in Senegal and Côte d'Ivoire locks out price-driven challengers. For New Entrants and Emerging Players: Humanitarian procurement officers at UNHCR and Red Cross represent the most penetrable channel, with specification-driven volumes and 12-month tender cycles favoring agile responders. Target solar portable lamp deployments in Bangladesh refugee camps where incumbent service networks remain thin. Go-to-market leverage comes through USB-charging feature differentiation for mobile-dependent populations. For Investors and Strategic Acquirers: Consolidation pressure builds where BIS certification timelines and PLI scheme compliance costs strand sub-scale assemblers without Gujarat or Karnataka manufacturing presence. Long-term viability centers on suppliers controlling both module supply and after-sales service networks across sub-Saharan electrification corridors. Watch for lithium carbonate price stabilization as the inflection signal for battery chemistry margin recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into LFP Cell Production | Captive battery supply insulates Signify Holding and Acuity Brands from lithium carbonate volatility. |
| BIS Pre-Certification Investment | Early qualification under India's panel efficiency protocols secures domestic procurement eligibility ahead of PLI scheme maturation. |
| Performance-Based Ownership Model | Per-lumen-hour contracting in West African municipalities transfers degradation risk from public budgets to operator balance sheets. |
| Humanitarian Channel Partnership | UNHCR specification alignment opens high-volume, low-competition procurement streams for portable lamp specialists. |
| Mesh Networking Integration | Smart city data-service layers beyond illumination capture recurring revenue from municipal IoT infrastructure budgets. |
Research Approach
Multiple input streams — municipal procurement database tracking, lithium carbonate futures market monitoring, and photovoltaic module trade flow analysis — were reconciled against primary interviews with India BIS certification officers, Kenya national energy regulator planners, and Senegal municipal public works directors. Secondary validation drew from India's PLI scheme disclosure filings, UNHCR tender documentation, and EU Green Deal Ecodesign regulatory texts. Bottom-up system cost build-ups and top-down electrification program budget allocations were triangulated to anchor volume estimates.
Data-stream reconciliation across product type, battery chemistry tier, and application segment dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from installed base growth curves and replacement cycle assumptions, with segmentation modeling incorporating monocrystalline PERC adoption rates and lithium iron phosphate penetration trajectories. Forecast inputs included Rajasthan and Arizona insolation data, Kenyan county electrification budget allocations, and EU battery passport implementation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to polysilicon supply chain reconfiguration and lithium carbonate price regime shifts. Forecasts reflect documented assumptions about technology cost curves and regulatory enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Africa Solar E-Bike Market
Renewable Energy
Renewable Energy Cable Market
Renewable Energy
South Asia Renewable Energy Market
Renewable Energy
Tidal Energy Generation Systems Market
Renewable Energy
Hydroelectric Cells Market
Renewable Energy
Hybrid Power System Market
Renewable Energy
Switzerland Renewable Energy Market
Renewable Energy
Solar Bicycle Shed Market
Renewable Energy
LAMEA Ocean Power Market
Renewable Energy
China Renewable Energy Market
Renewable Energy
Green Energy Lighting Market
Renewable Energy
Solar Showers Market
Renewable Energy
Europe Power to Gas Market
Renewable Energy
Mexico Renewable Energy Market
Renewable Energy
North Europe Renewable Energy Market
Renewable Energy
Denmark Renewable Energy Market