
 Italy Distributed Solar Power Generation Market | 2026-2036
Italy Distributed Solar Power Generation Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Distributed Solar Power Generation Market Foresight
Commercial rooftop demand is consolidating across Italy's logistics and retail estate sectors. Enel Green Power S.p.A. leverages its utility-scale engineering heritage to dominate utility-adjacent distributed projects. A2A S.p.A. anchors its position through integrated energy retail and behind-the-meter asset ownership. EF Solare Italia S.p.A. specializes in agricultural and commercial ground-mount configurations across the Po Valley.
Distributed solar power generation denotes electricity produced from decentralized photovoltaic or thermal systems typically below 10 MW capacity, sited at or near consumption points and connected through low-to-medium voltage networks. These installations employ monocrystalline or polycrystalline silicon cells with conversion efficiencies ranging from 18% to 22%, feeding power through string or central inverters for on-site use or grid export. Photovoltaic Systems command the dominant technology position due to module cost declines and installer familiarity, while Bifacial Modules represent the fastest-expanding technology category as Italian developers seek yield improvements on reflective surfaces. Agricultural Applications are gaining structural share as farmers deploy agrivoltaic arrays to offset irrigation and processing loads.
Italy's National Integrated Energy and Climate Plan (PNIEC) and the Gestore dei Servizi Energetici (GSE) incentive registry shape project economics through feed-in premium mechanisms and net metering schemes. The EU Green Deal and REPowerEU targets mandate accelerated distributed renewable deployment, tightening grid-code compliance for inverter manufacturers and installation contractors. Stakeholders must monitor the evolution of capacity market rules and local permitting simplifications to capture margin pools in Italy's fragmented municipal authorization landscape.
Market Dynamics
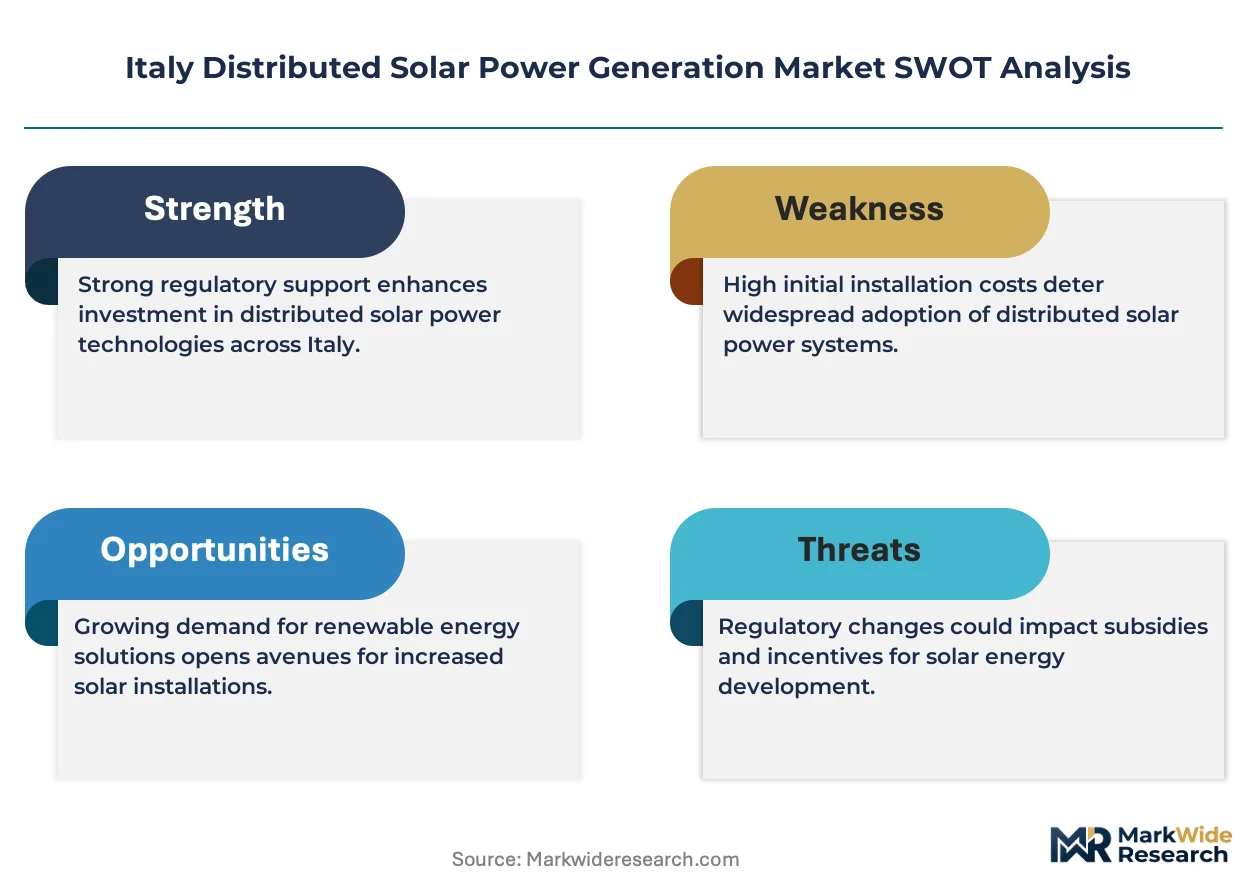
Italy's Superbonus 110% building renovation incentive has compressed payback periods for rooftop photovoltaic systems, triggering a structural demand pull from residential and commercial property owners seeking to maximize tax credits before program phase-out deadlines.
Growth Catalysts
- Superbonus 110% Incentive:The Italian tax credit mechanism covers renovation costs including photovoltaic integration, slashing effective installation expenses for building owners across Lombardy and Veneto.
- Agricultural Load Offset:Farmers in the Po Valley deploy agrivoltaic arrays to power irrigation pumps and cold storage, reducing grid dependency during peak tariff periods.
- EU Green Deal Mandates:REPowerEU targets accelerate distributed renewable deployment, tightening grid-code compliance requirements that favor established Italian installation contractors.
Market Restraints
- Polysilicon Supply Concentration:Module manufacturers face input cost volatility as polysilicon refining concentrates among Chinese producers, exposing Italian developers to freight and tariff pass-throughs.
- Grid Connection Queues:Gestore dei Servizi Energetici processing bottlenecks for net metering authorization extend project commissioning timelines by six to twelve months in saturated northern regions.
- Permitting Fragmentation:Municipal authorization variance across Italy's fragmented landscape forces developers to navigate inconsistent landscape compatibility assessments and heritage overlay restrictions.
Strategic Opportunities
- Southern Region Underpenetration:Puglia and Sicily exhibit lower distributed solar density despite superior irradiance profiles, offering first-mover advantages for ground-mount developers.
- Bifacial Module Convergence:Reflective surface optimization combines with tracking systems to boost yield on agricultural land without displacing cultivation activity.
- Behind-the-Meter Storage Pairing:Battery integration with residential rooftop systems captures time-of-use arbitrage as Italian grid tariffs increasingly penalize peak consumption.
Industry Challenges
- Electrical Engineering Talent Scarcity:Qualified inverter commissioning technicians and medium-voltage connection specialists command premium wages, constraining installer expansion capacity.
- Grid Code Recertification Burden:evolving Terna requirements for fault-ride-through and reactive power capability force inverter fleet upgrades, compressing margins on legacy installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Distributed Solar Power Generation Market |
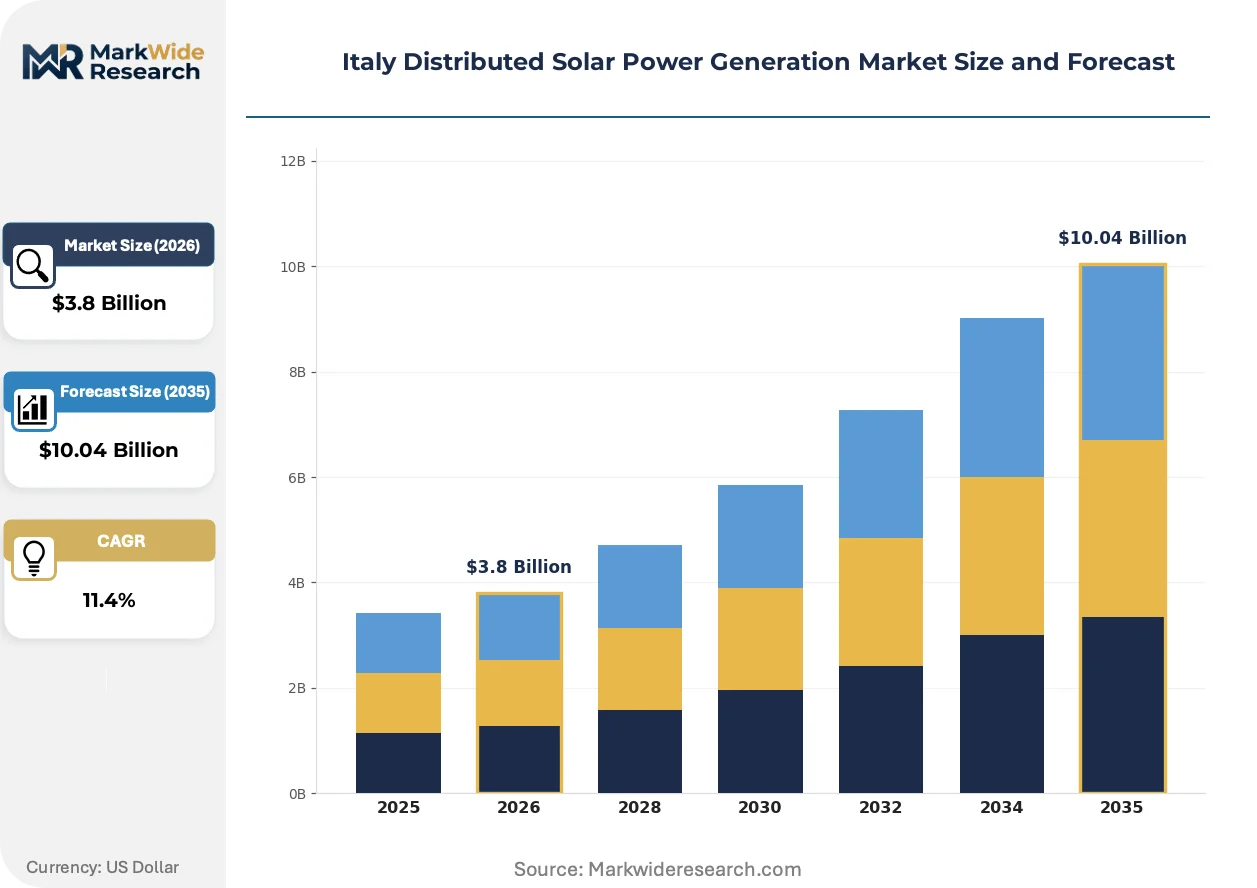
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Photovoltaic Systems, Concentrated Solar Power, Bifacial Modules, Thin-Film Solar Application: Residential, Commercial, Industrial, Agricultural Installation Type: Grid-Connected, Off-Grid, Hybrid Systems, Rooftop Component: Inverters, Mounting Structures, Transformers, Batteries |
| Companies Covered | Sonnedix Power Holdings Ltd, A2A S.p.A., Enel Green Power S.p.A., Capital Dynamics, EDP, EF Solare Italia S.p.A., Renantis S.p.A., Sunscape, Green Utility SpA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Distributed Solar Power Generation Market Shifts & Advancements
Module efficiency improvements and mounting system innovations are compressing levelized costs for distributed photovoltaic deployment, while incentive program evolution and buyer sophistication reshape procurement patterns across Italian regions.
Bifacial photovoltaic modules are overtaking monofacial alternatives in ground-mount applications across the Po Valley. Agricultural developers favor double-sided cell architectures that harvest reflected irradiance from soil and crop surfaces. This technology is overtaking conventional designs in utility-adjacent distributed projects where land-use efficiency determines project viability.
Italy's National Integrated Energy and Climate Plan tightens distributed generation targets while streamlining Gestore dei Servizi Energetici registration protocols. The policy framework compresses authorization timelines for sub-200 kW installations while imposing stricter inverter grid-code compliance. Commercial rooftop segments respond by consolidating procurement around Tier-1 module suppliers with pre-certified European product portfolios.
Aggregated energy service company models disrupt traditional installer-customer relationships in northern industrial zones. Manufacturing facilities and logistics operators contract comprehensive rooftop-as-a-service arrangements replacing capital expenditure ownership. This shift concentrates most visibly across Lombardy's Milan-Bergamo corridor where property portfolio owners prioritize balance-sheet offloading over direct asset control.
Italy Distributed Solar Power Generation Market Segmentation
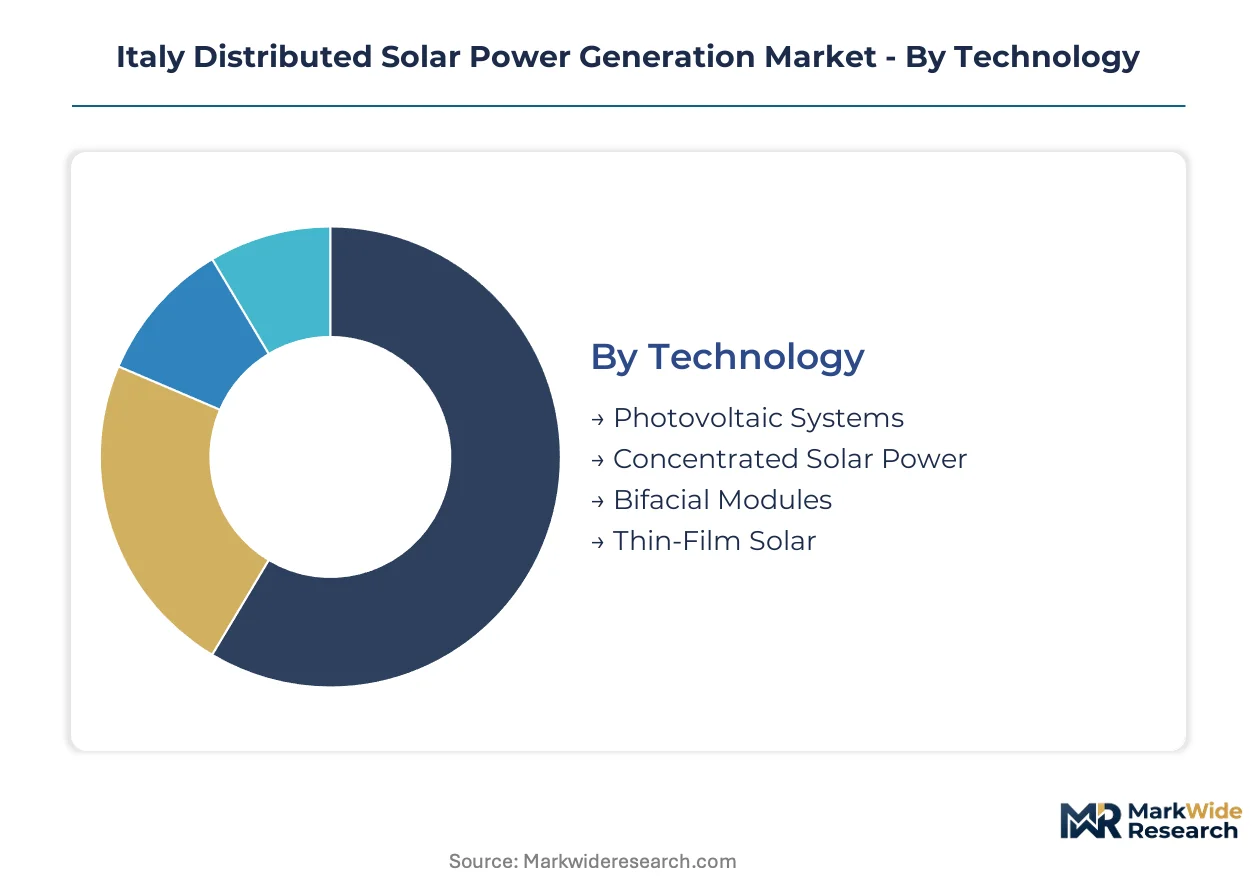
Technology and application boundaries in Italy's distributed solar sector are blurring as retrofit cycles accelerate. Installers now cross-sell across segments, making granular segmentation essential for margin capture and inventory planning.
Technology:
Module replacement cycles in Italy's installed base are compressing as efficiency thresholds rise and incentive windows narrow.
- Photovoltaic Systems:Crystalline silicon arrays dominate Italian rooftops and ground-mounts, with monocrystalline modules achieving 20-22% conversion efficiency. Demand clusters in Lombardy's commercial estate and Veneto's industrial belt as property owners exploit Superbonus depreciation windows.
- Bifacial Modules:Double-sided cell architectures harvest albedo from reflective agricultural surfaces and gravel rooftops. Po Valley farmers favor these for agrivoltaic deployments where land-use efficiency determines project approval.
- Concentrated Solar Power:Parabolic trough and dish-Stirling configurations find limited distributed application due to high capital intensity and maintenance requirements.
- Thin-Film Solar:Cadmium telluride and copper indium gallium selenide modules occupy niche building-integrated roles where weight constraints or aesthetic requirements override efficiency priorities.
Photovoltaic Systems sit at the top of the volume ranking, with Bifacial Modules climbing the fastest.
Application:
Customer archetypes in Italy's distributed solar market stratify sharply by financing sophistication and regulatory access.
- Commercial:Logistics operators and retail chains across Milan-Bergamo corridor deploy rooftop-as-a-service models. Aggregated energy service companies capture long-term power purchase agreements, offloading balance-sheet burden from property owners.
- Agricultural:Po Valley farmers install ground-mount and agrivoltaic arrays to offset irrigation pump loads and cold storage consumption. GSE net metering authorization timelines stretch commissioning by six to twelve months in saturated northern regions.
- Residential:Single-family homeowners leverage Superbonus 110% tax credits for rooftop retrofits. Municipal permitting fragmentation across Italy's fragmented landscape creates postcode-level variance in authorization speed.
- Industrial:Manufacturing facilities in Lombardy and Veneto favor behind-the-meter configurations with battery pairing for time-of-use tariff arbitrage.
Commercial applications command the largest revenue pool, with Agricultural deployments expanding most quickly.
Installation Type:
Grid interconnection topology determines project economics through Terna grid-code compliance burdens and GSE registration protocols.
- Grid-Connected:Low-to-medium voltage network integration dominates Italian distributed solar. Net metering schemes and feed-in premiums from Gestore dei Servizi Energetici shape payback calculations for sub-200 kW installations.
- Rooftop:Building-integrated and building-applied configurations exploit Superbonus incentives across residential and commercial estate. Northern industrial zones exhibit highest penetration density.
- Hybrid Systems:Battery-coupled solar arrays capture peak tariff differentials as Italian grid tariffs increasingly penalize consumption during evening peaks.
- Off-Grid:Standalone configurations serve isolated agricultural operations and mountain refuges where distribution network extension proves uneconomical.
Grid-Connected installations anchor volume, with Hybrid Systems gaining share fastest as storage costs decline.
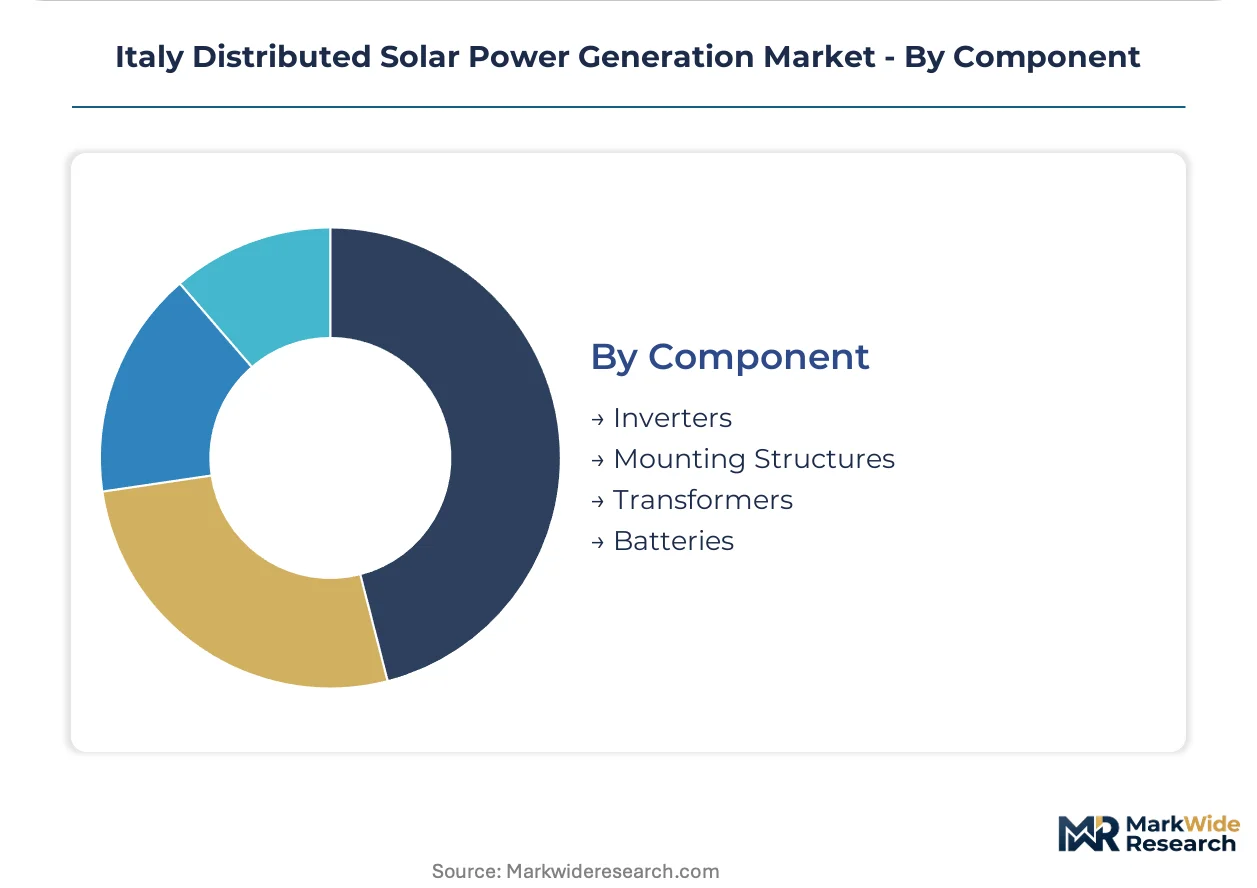
Component:
Supply chain concentration in Asian manufacturing centers exposes Italian developers to freight volatility and tariff pass-throughs.
- Inverters:String and central inverter architectures feed power into low-to-medium voltage networks. Terna's evolving fault-ride-through and reactive power requirements force periodic fleet recertification.
- Batteries:Lithium-ion storage systems pair with residential and commercial rooftop arrays for time-shifting and backup power. Behind-the-meter integration captures time-of-use arbitrage opportunities.
- Mounting Structures:Fixed-tilt and tracking systems secure modules to rooftops or ground-mount foundations. Agricultural developers favor elevated structures permitting continued cultivation beneath arrays.
- Transformers:Medium-voltage step-up equipment connects distributed generation to distribution networks, with capacity sizing critical for GSE authorization eligibility.
Inverters represent the highest-volume component category, with Batteries on the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Milan-Bergamo corridor anchors Italian distributed solar deployment through dense commercial estate and industrial load concentration. Northern industrial zones exploit Superbonus tax incentives while southern regions present untapped irradiance advantages.
Lombardy
Logistics operators and manufacturing facilities across Milan-Bergamo-Brescia drive rooftop-as-a-service procurement. The Superbonus 110% incentive compresses payback periods for commercial property owners. Milan's metropolitan industrial belt exhibits the highest distributed solar penetration density nationwide.
Veneto
Industrial zones around Verona and Padua favor behind-the-meter configurations with battery pairing for time-of-use arbitrage. Gestore dei Servizi Energetici net metering authorization timelines stretch six to twelve months in this saturated region. The Venetian hinterland concentrates agrivoltaic experimentation on reflective agricultural surfaces.
Emilia-Romagna
Food processing and agricultural cold storage facilities deploy ground-mount arrays to offset irrigation and refrigeration loads. The PNIEC distributed generation targets streamline GSE registration protocols for sub-200 kW installations. Bologna's logistics corridor attracts aggregated energy service company models for portfolio-scale rooftop deployment.
Puglia
Superior irradiance profiles and lower distributed solar density attract ground-mount developers seeking first-mover positioning. Municipal permitting fragmentation creates postcode-level variance in authorization speed across Apulian provinces. The Tavoliere delle Puglie plain offers expansive agricultural land for bifacial module deployment.
Sicily
Island grid constraints and high solar resource availability position Sicily for hybrid off-grid and grid-connected experimentation. Terna grid-code compliance requirements for fault-ride-through capability shape inverter selection. Catania's industrial periphery hosts emerging commercial rooftop clusters.
Italy Distributed Solar Power Generation Market Competitive Landscape
Strategic partnerships dominate the current landscape as developers seek to secure land access and streamline GSE authorization. The market structures around three tiers: utility-adjacent engineering specialists, integrated energy retailers with behind-the-meter asset ownership, and agricultural-focused ground-mount developers. Consolidation pressure intensifies as Superbonus incentive windows narrow and installation contractors compete for qualified electrical engineering talent. Portfolio diversification and geographic expansion represent the primary competitive vectors.
Among Italy-based operators, Enel Green Power S.p.A., A2A S.p.A., and EF Solare Italia S.p.A. occupy distinct positioning archetypes. Enel Green Power exemplifies the utility-scale engineering heritage applied to distributed project development. A2A represents integrated energy retail models combining customer acquisition with captive asset ownership. EF Solare Italia sits within the agricultural specialization tier, anchoring ground-mount and agrivoltaic deployment patterns across the Po Valley.
| Leading Market Players |
|---|
| Sonnedix Power Holdings Ltd |
| A2A S.p.A. |
| Enel Green Power S.p.A. |
| Capital Dynamics |
| EDP |
| EF Solare Italia S.p.A. |
| Renantis S.p.A. |
| Sunscape |
| Green Utility SpA |
| Others |
Supply & Pricing Matrix
Polysilicon spot price volatility from Chinese refineries cascades through module assembly tiers into Italian distributed solar pricing bands, compressing margins for developers locked into fixed-price EPC contracts while rewarding agile buyers with volume flexibility.
Pricing Analysis
Input-cost pass-through from Asian polysilicon producers drives module pricing dynamics across Italian procurement tiers. Three-tier pricing structure across premium, standard, and economy levels separates Tier-1 European-certified suppliers from Chinese direct-import alternatives and secondary market inventory. Cost compression in the standard tier is intensifying because freight rate normalization and module oversupply are eroding landed-cost premiums. Agricultural buyers in the Po Valley exhibit highest price sensitivity due to thin operating margins, while Lombardy commercial estate owners prioritize balance-sheet offloading over unit economics.
Supply Chain Analysis
Workforce availability constraints in Chinese ingot-wafer manufacturing centers and Vietnamese module assembly plants are tightening delivery schedules for Italian developers. Module supply concentrates in China, Vietnam, and Malaysia, with inverter sourcing anchored in Germany, China, and Taiwan. Polysilicon ingots, glass substrates, and aluminum frames constitute critical input dependencies. Single-source vulnerability around Chinese polysilicon refining exposes Italian EPCs to tariff and freight pass-through shocks. Distribution runs through Rotterdam and Hamburg port gateways into regional logistics hubs serving Lombardy and Veneto installation corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's distributed solar market compounds steadily as the EU Green Deal mandates tighten renewable penetration targets, embedding structural demand pull regardless of incentive cycle volatility.
For Market Incumbents: Hedge against Superbonus phase-out by accelerating southern region land-banking in Puglia and Sicily before first-mover premiums erode. Deepen backward integration into battery storage assembly to capture time-of-use arbitrage value pools that pure-play solar developers cannot access. Prioritize GSE authorization queue management as the critical operational lever, staffing dedicated regulatory affairs teams to compress net metering timelines.
For New Entrants and Emerging Players: Bifacial module optimization with agrivoltaic mounting systems offers technology-first wedge positioning against established rooftop installers. Southern agricultural ground-mount deployments present the most penetrable white-space, with Tavoliere delle Puglie plain offering contiguous land access unavailable in saturated northern zones. Pursue aggregated energy service company partnerships with food processing cooperatives to bypass direct customer acquisition costs.
For Investors and Strategic Acquirers: Asymmetric upside sits with agricultural-specialist developers holding permitted land positions in underpenetrated southern provinces. Long-term viability hinges on portfolio diversification across regulatory regimes rather than concentrated Superbonus exposure. Watch GSE processing time trends as the inflection signal—compression below six months would validate southern expansion theses and trigger re-rating of regional developer valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Southern Region Land Banking | Puglia and Sicily permits secure first-mover yield premiums before saturation arrives. |
| Behind-the-Meter Storage Integration | Battery pairing captures time-of-use arbitrage as Terna tariffs penalize peak consumption. |
| GSE Authorization Process Automation | Net metering queue compression reduces commissioning delays in saturated northern regions. |
| Agrivoltaic Elevation Structure Development | Continued cultivation compatibility secures agricultural land access against food-security opposition. |
| Tier-1 Module Supplier Consolidation | Pre-certified European portfolios streamline compliance with evolving inverter grid-code requirements. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with EPC contractors, GSE authorization specialists, agricultural cooperative energy managers, and Lombardy commercial property portfolio directors with secondary validation against Gestore dei Servizi Energetici registry data, Terna grid interconnection filings, EU REPowerEU implementation tracking, and Italian customs module import records. Bottom-up project pipeline aggregation and top-down incentive expenditure reconciliation provided cross-check triangulation.
Comparable-period anchoring tied projection assumptions to historical Superbonus uptake curves and net metering authorization velocity patterns across the analysis window. Segmentation modeling spanned technology type, application archetype, installation topology, and regional regulatory cluster dimensions. CAGRs emerged from installed capacity build-up trajectories and unit revenue compression curves, incorporating polysilicon price elasticity coefficients and inverter cost decline slopes as solar-specific forecast inputs.
The model holds under stable EU Green Deal enforcement and continued GSE incentive disbursement; deviation in Superbonus extension decisions or grid-code recertification burdens would shift deployment timing and regional mix. Forecasts embed these assumptions without contingency weighting. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Simulator Market
Solar Power Systems
PERC Solar Cell Market
Solar Power Systems
CPV Solar Sales Market
Solar Power Systems
North America Concentrated Solar Power (CSP) Market
Solar Power Systems
Australia Rooftop Solar Market
Solar Power Systems
Solar Rack Market
Solar Power Systems
Single Axis Solar PV Tracker Market
Solar Power Systems
Solar PV Tracker Market
Solar Power Systems
Thin Film Solar PV Market
Solar Power Systems
New Zealand Solar Energy Market
Solar Power Systems
US Residential Solar PV Market
Solar Power Systems
Philippines Solar Energy Market
Solar Power Systems
Flexible Solar Panel Market
Solar Power Systems
Global Solar PV Balance of System Market
Solar Power Systems
Europe Solar Blanket Market
Solar Power Systems
India Residential Solar Inverter Market