
 AR Photovoltaic Glass Market | 2026-2036
AR Photovoltaic Glass Market Size, Share, and Industry Trends Forecast 2026-2036
AR Photovoltaic Glass Market Insights
IEC 61215 certification for photovoltaic module reliability is rotating supplier eligibility, forcing glass makers to align thermal cycling and humidity freeze test protocols with downstream module integrators. Xinyi Solar Holdings Ltd. leverages captive float-glass capacity to anchor cost structures across tempered AR substrate production. AGC Inc. differentiates through sputtered multi-layer anti-reflection coatings optimized for bifacial module architectures. Saint-Gobain sustains European supply through specialized furnace configurations that reduce iron content below 150 ppm.
AR photovoltaic glass refers to soda-lime silica substrates with nanostructured or thin-film deposited coatings that reduce surface reflectance from approximately 8% to below 2% across the 300-1100 nm solar spectrum, enabling higher photon transmission into crystalline silicon or thin-film absorber layers. The primary industrial purpose is maximizing energy yield per module area in utility and distributed generation systems. Coated glass commands margin concentration due to vacuum deposition equipment intensity and optical uniformity requirements. Crystalline silicon applications dominate volume absorption, while bifacial technology segments expand fastest as rear-side gain sensitivity amplifies coating performance premiums. Building envelope installations occupy a mature niche where aesthetic tinting and structural lamination add value beyond pure optical efficiency.
China's GB standards for photovoltaic glass mechanical strength and the EU's F-Gas Regulation restricting fluorinated greenhouse gases in manufacturing processes shape coating chemistry roadmaps and equipment investment cycles. India's BIS certification mandates and the PLI scheme for solar module manufacturing localize demand for domestically sourced AR glass substrates. Stakeholders must monitor bifacial technology share trajectories and fluoropolymer substitution timelines to align capacity with evolving coating specifications.
Market Dynamics
Bifacial module architectures are forcing AR glass makers to optimize coatings for dual-side photon capture, compressing development cycles and tightening optical uniformity tolerances across the supply base.
Growth Catalysts
- India's PLI scheme for solar module manufacturing:Domestic procurement mandates under this production-linked incentive framework are localizing demand for AR-coated substrates within one of the fastest-expanding utility-scale markets.
- Bifacial technology penetration:Rear-side gain sensitivity in double-glass modules amplifies the performance premium attached to multi-layer anti-reflection coatings optimized for broad-spectrum transmission.
- EU F-Gas Regulation:Fluoropolymer-free coating chemistry roadmaps are accelerating equipment replacement cycles and opening substitution pathways for vacuum deposition processes.
Market Restraints
- High-purity silica sand concentration:Tempered AR substrate production depends on ultra-low-iron sand deposits concentrated in limited geographies, creating input cost volatility and supply security exposure.
- Vacuum deposition equipment intensity:Sputtering and plasma-enhanced chemical vapor deposition systems require substantial capital outlays that constrain new entrant participation and concentrate manufacturing among established players.
- IEC 61215 certification rotation:Evolving thermal cycling and humidity freeze test protocols force continuous reformulation of glass thermal expansion coefficients and edge-sealing compatibility.
Strategic Opportunities
- Building-integrated photovoltaics (BIPV):Aesthetic tinting and structural lamination requirements in commercial envelope applications create value capture beyond pure optical efficiency metrics.
- Fluoropolymer-free sol-gel coatings:Water-based nanostructured surface treatments are converging with roll-to-roll processing equipment to reduce deposition energy intensity and eliminate fluorinated greenhouse gas inputs.
- Utility-scale procurement consolidation:Developer-led module purchasing consortiums in India and the Middle East are creating direct specification channels that bypass traditional distributor intermediaries.
Industry Challenges
- Optical coating technician scarcity:Vacuum deposition process engineering and thin-film metrology expertise pools remain shallow relative to capacity expansion timelines, extending commissioning periods for new production lines.
- Bifacial rear-side performance validation:Absence of standardized outdoor test conditions for rear-irradiance-dependent coating增益 is complicating warranty negotiations and bankability assessments.
- Float glass furnace reconfiguration:Retrofitting existing soda-lime silica capacity for sub-150 ppm iron content requires extended downtime and specialized refractory materials that strain maintenance schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AR Photovoltaic Glass Market |
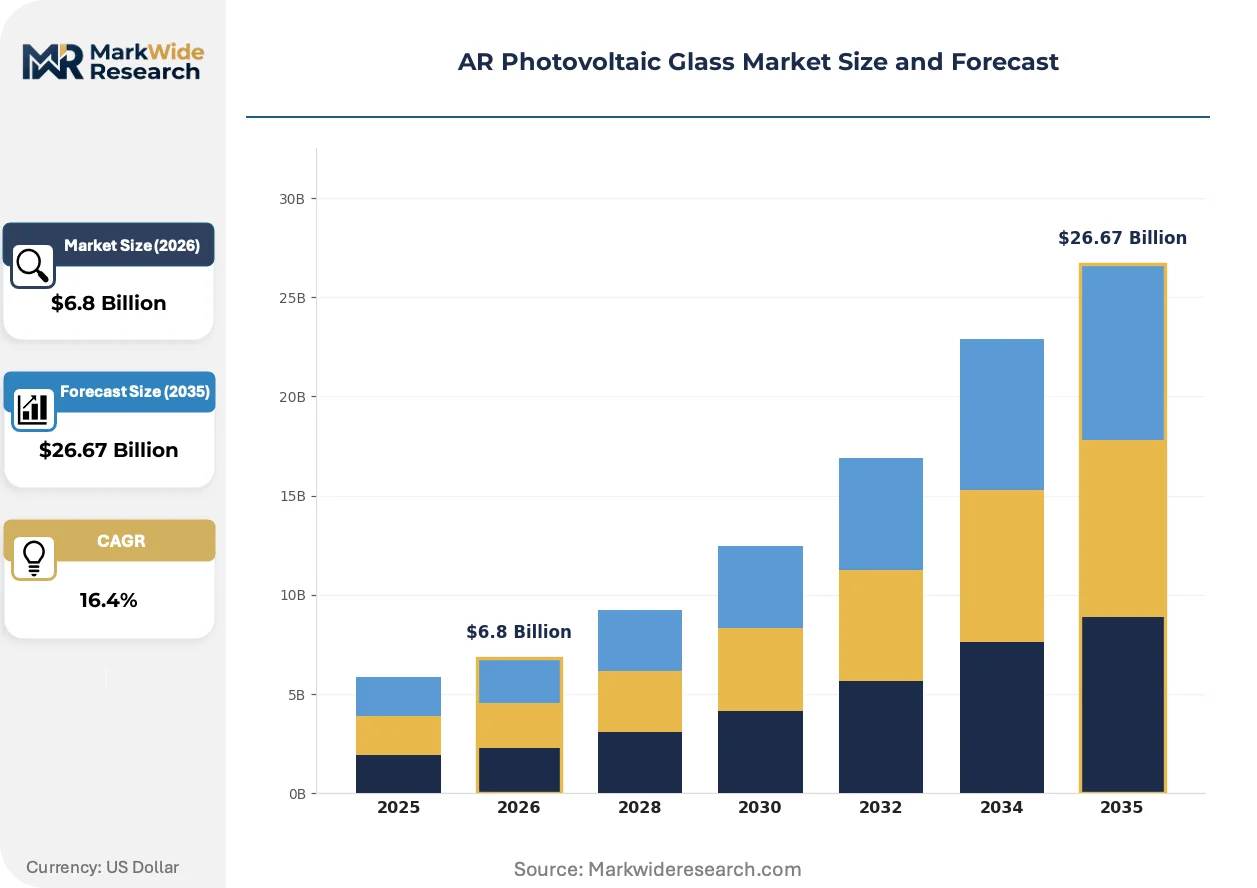
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $26.67 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Glass, Tinted Glass, Laminated Glass, Coated Glass Application: Building Envelopes, Solar Farms, Residential Installations, Automotive Applications Technology: Thin-Film, Crystalline Silicon, Bifacial, Multi-Junction End User: Manufacturers, Contractors, Architects, Homeowners |
| Companies Covered | Xinyi Solar Holdings Ltd., IRICO Group New Energy Co., Ltd., Flat Glass Group Co., Ltd., AGC Inc., Saint-Gobain, NSG Pilkington, CSG Holding Co. Ltd., Dongguan CSG Solar Glass Co., Ltd., Qingdao Jinxin Glass Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AR Photovoltaic Glass Market Trends and Innovations
Coating chemistry and deposition methodology are diverging sharply as environmental regulations and module efficiency targets impose incompatible constraints on legacy process designs.
Sputtered multi-layer anti-reflection coatings are bifurcating the performance tier structure of the AR glass market. These vacuum-deposited thin-film stacks enable sub-2% reflectance across the 300-1100 nm spectrum with superior abrasion resistance compared to sol-gel alternatives. Tier-one module integrators targeting bifacial architectures are specifying sputtered coatings for premium product lines, while cost-sensitive utility procurements retain etched or dip-coated alternatives. This technology is bifurcating margin concentration between high-performance coating houses and commodity substrate suppliers.
Europe's F-Gas Regulation is eliminating fluoropolymer-based plasma etching chemistries from coating manufacturing workflows. Industrial consequence includes accelerated capital redeployment toward water-based sol-gel and physical vapor deposition equipment. Bifacial module producers serving EU utility tenders are most affected, responding by qualifying alternative coating suppliers and extending supply chain due diligence to upstream chemical inputs.
Direct procurement relationships between utility-scale developers and AR glass specialists are displacing traditional module-integrator-mediated purchasing. Large solar farm operators in India and Saudi Arabia are establishing technical specifications and volume commitments independently, compressing distributor margins and forcing coating houses to build direct sales engineering capabilities. This pattern is most visible in markets with concentrated developer ownership and standardized module procurement frameworks.
AR Photovoltaic Glass Market Segmentation
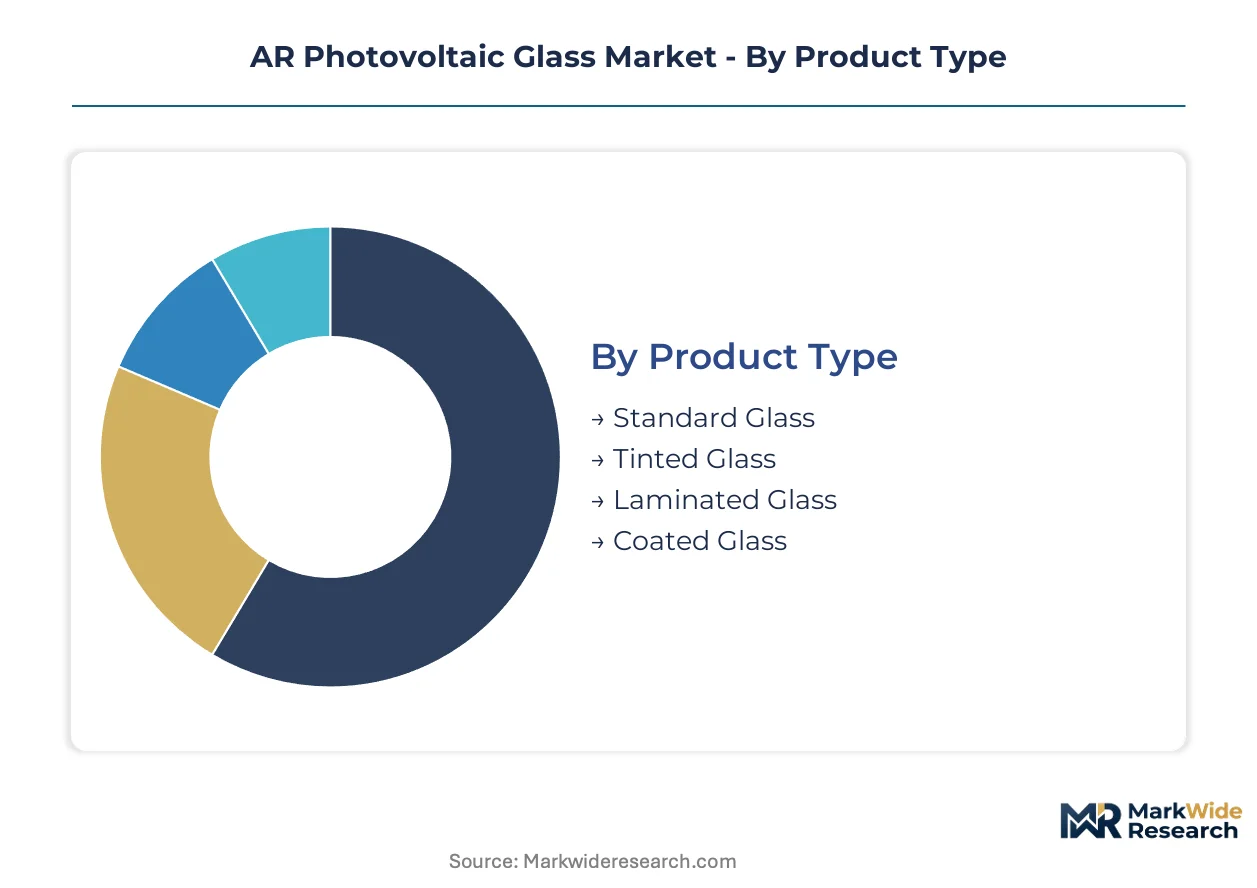
AR photovoltaic glass segments diverge sharply on coating chemistry, mechanical specification, and installation context. Procurement patterns bifurcate between cost-optimized utility-scale volumes and performance-premium distributed generation systems.
Product Type:
Substitution pressure concentrates in commodity substrate tiers where uncoated and single-layer alternatives erode pricing power for basic tempered products.
- Standard Glass:Soda-lime silica substrates without anti-reflective surface treatment serve cost-sensitive installations where module efficiency sacrifices are acceptable. Demand concentrates in legacy residential retrofits across India and Southeast Asia where BIS certification requirements remain less stringent than IEC 61215-aligned markets.
- Coated Glass:Vacuum-deposited multi-layer thin-film stacks reduce surface reflectance below 2% across the 300-1100 nm spectrum. Utility-scale solar farms in Saudi Arabia and the UAE specify these substrates for bifacial module architectures where rear-side gain sensitivity amplifies coating performance premiums.
- Tinted Glass:Iron-doped substrates with controlled spectral absorption address aesthetic requirements in commercial building envelopes. European BIPV installations drive specification.
- Laminated Glass:Polyvinyl butyral interlayers bond multiple glass plies for structural safety in overhead glazing applications. Automotive-integrated photovoltaics and skylight installations represent primary demand nodes.
Coated glass anchors the volume base while laminated glass gains share at the steepest rate as building codes tighten structural safety requirements.
Application:
Margin concentration follows installation scale and performance validation burden, with distributed systems commanding coating premiums per square meter.
- Solar Farms:Utility-scale ground-mounted installations procure AR-coated glass through direct developer relationships, bypassing traditional distributor channels. India's PLI scheme localizes demand for domestically sourced tempered substrates with IEC 61215-aligned thermal cycling protocols.
- Building Envelopes:Curtain wall and skylight integrations require structural lamination and aesthetic tinting beyond pure optical efficiency. EU F-Gas Regulation compliance shapes coating chemistry selection for facade projects in Germany and France.
- Residential Installations:Rooftop distributed generation systems prioritize cost per watt over coating performance. Standard glass retains significant penetration here.
- Automotive Applications:Integrated photovoltaic roof systems for electric vehicles demand lightweight, impact-resistant laminated configurations. Japanese and South Korean automotive OEMs drive specification development.
Solar farms absorb the majority of coated glass shipments while automotive applications expand most quickly as vehicle-integrated photovoltaics mature.
Technology:
Cell architecture determines coating spectral optimization requirements and rear-side performance sensitivity.
- Bifacial:Double-glass module designs capture photon flux from both front and rear surfaces, demanding multi-layer coatings with broad-spectrum transmission stability. Chinese GB standards and IEC 61215 certification protocols increasingly incorporate rear-irradiance test conditions.
- Crystalline Silicon:Monocrystalline and polycrystalline cell technologies dominate installed capacity and absorb the majority of AR glass volume. Standard single-layer sol-gel coatings suffice for monofacial configurations.
- Thin-Film:Cadmium telluride and copper indium gallium selenide absorbers require different spectral transmission profiles than silicon, creating niche coating specification requirements.
- Multi-Junction:III-V compound semiconductor stacks for concentrated photovoltaics demand precision-tuned anti-reflection across narrower wavelength bands. Space and military applications sustain limited demand.
Crystalline silicon maintains volume dominance while bifacial technology climbs the fastest as rear-side gain economics improve.
End User:
Technical specification authority varies sharply across procurement actors, shaping coating house sales engineering requirements.
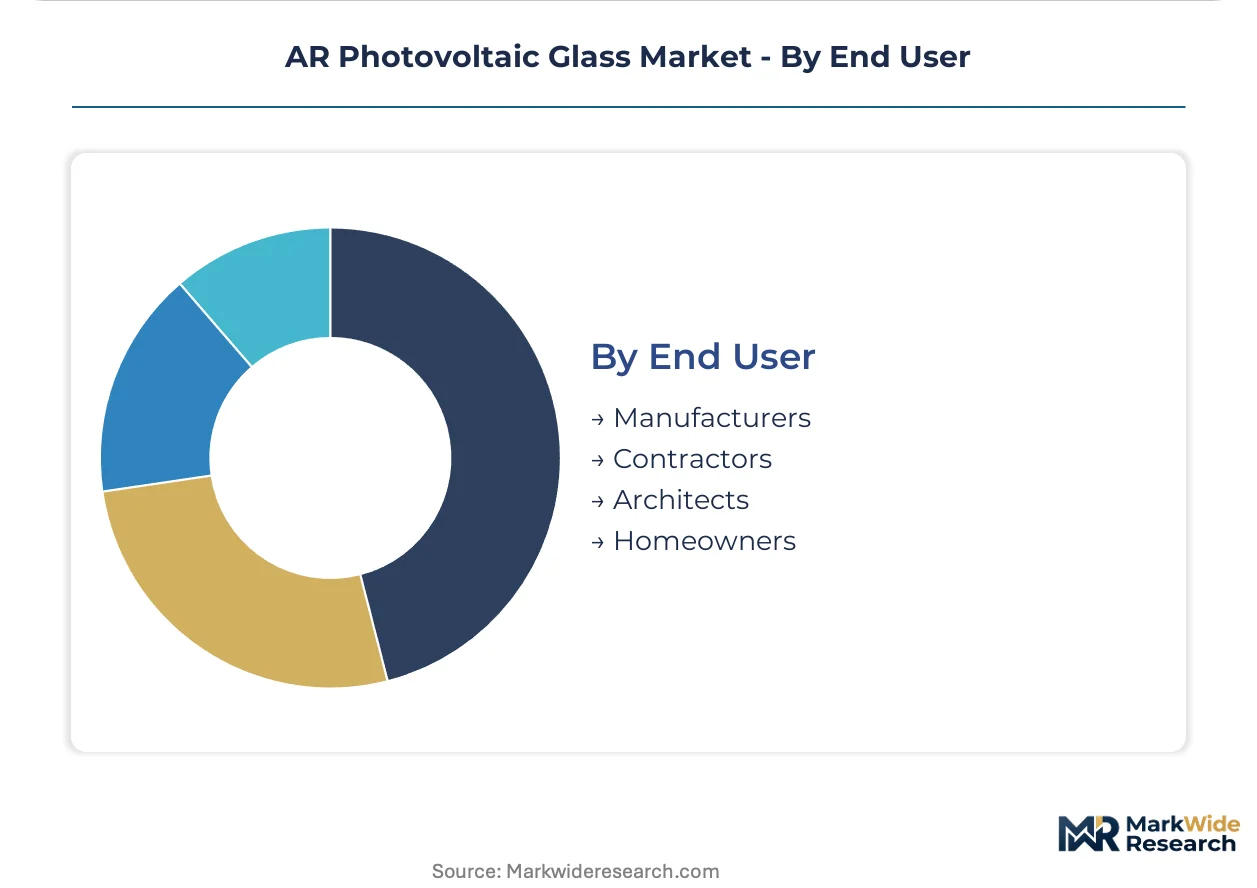
- Manufacturers:Module integrators specify AR glass substrates based on IEC 61215 certification alignment and downstream warranty obligations. Direct procurement relationships with coating specialists are displacing distributor intermediaries in India and the Middle East.
- Contractors:Engineering-procurement-construction firms influence substrate selection through balance-of-system optimization and installation labor considerations. Utility-scale EPCs in Saudi Arabia consolidate specification authority.
- Architects:Commercial envelope designers prioritize aesthetic tinting and structural lamination over pure optical efficiency metrics. EU Green Deal compliance requirements shape project-level coating selection.
- Homeowners:End-consumer price sensitivity limits AR coating penetration in residential retrofit markets. Standard glass retains significant share here.
Manufacturers control the largest procurement volumes while architects drive the steepest specification evolution as BIPV aesthetic requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for solar module manufacturing is redirecting procurement flows toward domestically sourced AR-coated substrates. China's GB standards and captive float-glass capacity anchor supply-side concentration. Europe's F-Gas Regulation accelerates fluoropolymer-free coating chemistry transitions.
China
GB standards for photovoltaic glass mechanical strength and iron content below 150 ppm shape substrate specifications for crystalline silicon module exports. MIIT dual carbon goals compress furnace reconfiguration timelines for low-iron float glass production. The Yangtze River Delta concentrates tempered AR substrate manufacturing with vacuum deposition equipment clusters serving bifacial module integrators.
India
Utility-scale solar farms in Rajasthan and Gujarat expand procurement under MNRE's production-linked incentive scheme with domestic content requirements. BIS certification mandates for tempered glass thermal cycling protocols filter supplier eligibility for module integrators. The Delhi-Mumbai Industrial Corridor anchors glass fabrication clusters scaling to meet PLI-scheme localization targets.
Germany
EU F-Gas Regulation compliance deadlines force coating chemistry roadmaps away from fluoropolymer-based plasma etching toward water-based sol-gel alternatives. The EU Green Deal tightens building envelope efficiency standards for BIPV facade installations. Bavaria's industrial glass corridor sustains specialized furnace configurations producing sub-150 ppm iron content for premium module applications.
United States
IRA production tax credits for domestic solar module manufacturing stimulate downstream demand for IEC 61215-certified AR glass substrates. FERC interconnection queue reforms accelerate utility-scale project commissioning timelines. The Southwest solar belt—Arizona, Nevada, Texas—concentrates developer-led direct procurement relationships bypassing traditional distributor channels.
Saudi Arabia
Vision 2030 renewable energy targets drive gigawatt-scale solar farm development specifying bifacial module architectures with multi-layer anti-reflection coatings. SFDA chemical import regulations shape coating precursor supply chain configurations. The King Abdullah Economic City corridor hosts module integration facilities establishing direct technical specifications with AR glass specialists.
AR Photovoltaic Glass Market Competitive Landscape
Player mix skews toward integrated float-glass producers with captive AR coating capacity. Market structure concentrates around three to five dominant substrate suppliers controlling vacuum deposition equipment and high-purity silica sand access. Strategic archetypes separate into captive glass-coating integrators, independent coating houses, and building envelope specialists. Capacity expansion and fluoropolymer-free chemistry licensing constitute the dominant competitive moves reshaping positioning.
Among China-based fabricators, Xinyi Solar Holdings Ltd., Flat Glass Group Co., Ltd., and CSG Holding Co. Ltd. exemplify the integrated archetype combining captive float-glass production with in-house AR coating deposition. These entities anchor cost structures across tempered substrate supply through backward integration into soda-lime silica melting. AGC Inc. and Saint-Gobain occupy positions within the premium coating tier, representing specialized furnace and sputtered multi-layer expertise aligned with bifacial module efficiency targets. The competitive divide separates scale-driven Chinese substrate volume from European and Japanese precision-coating technology licensors.
| Leading Market Players |
|---|
| Xinyi Solar Holdings Ltd. |
| IRICO Group New Energy Co., Ltd. |
| Flat Glass Group Co., Ltd. |
| AGC Inc. |
| Saint-Gobain |
| NSG Pilkington |
| CSG Holding Co. Ltd. |
| Dongguan CSG Solar Glass Co., Ltd. |
| Qingdao Jinxin Glass Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
IEC 61215 certification protocols gate both supplier qualification and price differentiation simultaneously, bifurcating the market between certified premium substrates and uncertified commodity alternatives while compressing margins for mid-tier producers caught in compliance transition costs.
Pricing Analysis
Long-term offtake contracts with silica sand indexation dominate procurement between Indian utility-scale developers and Chinese substrate suppliers. Three-tier pricing structure across premium, standard, and economy levels separates sputtered multi-layer coatings from sol-gel alternatives and uncoated standard glass. Cost compression in the economy tier intensifies because captive float-glass producers leverage backward integration into soda-lime silica melting. Residential rooftop installers exhibit highest price sensitivity, while bifacial module integrators targeting Saudi and UAE utility tenders absorb premium coating costs without volume negotiation.
Supply Chain Analysis
Strategic stockpiling of high-purity silica sand supersedes just-in-time preferences among tempered AR substrate producers facing deposit concentration in Australia, China, and Vietnam. Vacuum deposition equipment draws from German and Japanese precision manufacturing clusters, while coating precursor chemicals rest on Chinese fluoropolymer-free chemistry roadmaps. Single-source vulnerability concentrates in sub-150 ppm iron float glass furnace capacity controlled by three integrated producers. Distribution runs through direct developer relationships in India and the Middle East, displacing traditional module-integrator intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The AR photovoltaic glass market tracks a cyclical recovery pattern tied to utility-scale solar farm commissioning waves, with procurement cycles amplifying demand volatility as developer consortiums consolidate specification authority.
For Market Incumbents: Fortify captive float-glass capacity positions through furnace reconfiguration for sub-150 ppm iron content, locking in substrate cost structures against emerging Chinese competitors. Accelerate IEC 61215 certification alignment with downstream module integrators to defend premium pricing tiers against sol-gel substitution threats. Prioritize direct sales engineering capabilities in India and Saudi Arabia where developer-led procurement bypasses distributor channels. For New Entrants and Emerging Players: Differentiate on fluoropolymer-free sol-gel coating chemistry optimized for EU F-Gas Regulation compliance, targeting building envelope applications in Germany and France where aesthetic tinting commands value capture beyond pure optical efficiency. Penetrate the automotive-integrated photovoltaics segment through lightweight laminated glass configurations for Japanese and South Korean OEMs. Pursue technology licensing partnerships with established vacuum deposition equipment suppliers to circumvent capital intensity barriers. For Investors and Strategic Acquirers: EU F-Gas Regulation compliance deadlines reshape the acquisition landscape toward coating houses with water-based nanostructured surface treatment capabilities and roll-to-roll processing equipment. Frame long-term viability around 5-10 year technology licensing revenue streams rather than pure manufacturing margin capture. Target acquisition candidates with demonstrated bifacial rear-side performance validation protocols. Monitor PLI scheme localization thresholds in India as inflection indicator for regional supply-demand rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Fluoropolymer-Free Chemistry Licensing | EU F-Gas Regulation compliance opens substitution pathways for water-based sol-gel coating houses. |
| Captive Float-Glass Capacity Expansion | Xinyi Solar and Flat Glass Group anchor cost structures through backward integration into soda-lime silica melting. |
| Bifacial Rear-Side Performance Validation | IEC 61215 certification rotation incorporates rear-irradiance test conditions for bankability assessments. |
| Direct Developer Procurement Channels | Indian and Saudi utility-scale consortiums displace distributor intermediaries with technical specification authority. |
| Building Envelope Aesthetic Specialization | Saint-Gobain and AGC capture BIPV value through controlled iron-doped tinting and structural lamination. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with module integration executives, EPC contractors, and coating process engineers; and secondary validation through customs trade databases, SEC filings of listed glass producers, and IEC certification registries. Bottom-up triangulation across substrate shipment volumes and top-down reconciliation against utility-scale project development databases anchored market sizing. Primary fieldwork concentrated on procurement decision-makers in India, China, Germany, and Saudi Arabia.
Across the projection horizon, the analytical framework modeled coating chemistry type, module architecture application, and regional regulatory cluster as core segmentation dimensions. CAGRs derived from capacity expansion announcements correlated against bifacial technology penetration trajectories and PLI scheme localization targets. Forecast inputs incorporated float-glass furnace reconfiguration timelines and F-Gas Regulation compliance deadlines without specific year anchoring.
Forecasts assume regulatory continuity in EU F-Gas Regulation and India's PLI scheme; material policy shifts would require re-modeling. Revision becomes warranted when bifacial rear-side performance validation protocols achieve standardization or when high-purity silica sand deposit access restrictions cross supply security thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Global Photovoltaic Glass Market
Solar Power Systems
Plastic Solar Cell Market
Solar Power Systems
United Kingdom Distributed Solar Power Generation Market
Solar Power Systems
India Solar Energy Market
Solar Power Systems
Photovoltaic (PV) Materials Market
Solar Power Systems
Solar Appliances Market
Solar Power Systems
Solar PV Backsheet Market
Solar Power Systems
United Kingdom Photovoltaic Mounting System Market
Solar Power Systems
Solar Energy Market
Solar Power Systems
Frameless Solar Panel Market
Solar Power Systems
India Solar Photovoltaic (PV) Market
Solar Power Systems
DSC Solar Technologies Market
Solar Power Systems
Solar PV Inverter Market
Solar Power Systems
Europe Bifacial Solar Market
Solar Power Systems
Solar System in Kuwait Market
Solar Power Systems
Europe Solar Concentrator Market