
 Slovakia Renewable Energy Market | 2026-2036
Slovakia Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Slovakia Renewable Energy Market Analytics
Industrial off-takers is rotating toward long-term power purchase agreements, displacing legacy utility contracting as the dominant procurement mode. Slovenské elektrárne leverages its incumbent hydro fleet to anchor baseload supply for these corporate buyers. GreenWay Infrastructure competes in the transport-electrification segment with charging infrastructure tied to renewable offtake. Enery specializes in distributed solar development, positioning its project pipeline around manufacturing zones in western Slovakia.
Slovakia renewable energy encompasses electricity and thermal output derived from solar irradiance, wind kinetic energy, organic biomass feedstocks, and hydrological flow, typically converted through photovoltaic cells with crystalline silicon efficiencies of 18-22%, horizontal-axis wind turbines with 80-120 meter hub heights, combustion or anaerobic digestion systems for biomass, and Francis or Kaplan turbines for run-of-river hydro. Hydropower occupies the largest installed capacity share given Slovakia's mountainous topography and legacy infrastructure, yet photovoltaic deployment is accelerating fastest as module costs decline and rooftop suitability expands across commercial estates. Bioenergy systems retain structural importance in district heating networks, particularly where agricultural residue supply chains from the Danube lowlands sustain fuel security.
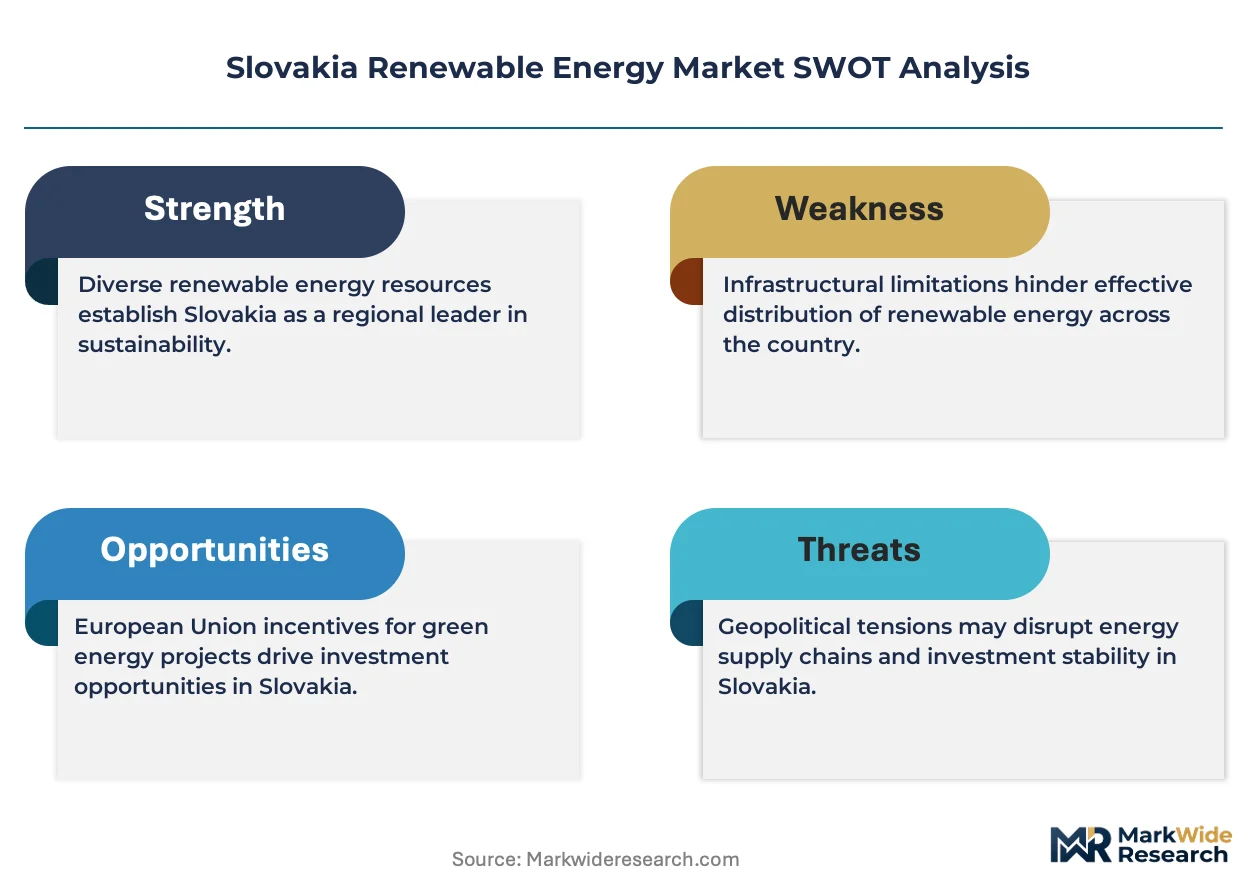
Slovakia's Ministry of Economy implements the National Energy and Climate Plan, while the Regulatory Office for Network Industries governs grid access tariffs and renewable premium mechanisms. The country's central bank and EU cohesion funds shape financing availability for greenfield projects. Stakeholders must monitor auction calendar density and cross-border capacity allocation rules as these instruments determine project bankability faster than technology cost curves alone.
Market Dynamics
Industrial power procurement in Slovakia is pivoting from short-term utility contracts toward long-term power purchase agreements, driven by the National Energy and Climate Plan's tightening emission benchmarks and automotive sector decarbonization mandates.
Growth Catalysts
- Automotive Electrification Mandates:Volkswagen's Bratislava facility and Kia's Žilina plant are binding renewable offtake to EV production targets, creating anchor demand for utility-scale solar and wind projects.
- EU Cohesion Fund Access:Greenfield renewable projects in western Slovakia qualify for blended finance structures that reduce weighted average cost of capital below commercial lending rates.
- Grid Interconnection Upgrades:Slovenská elektrizačná prenosová sústava is expanding substation capacity in Trnava and Nitra regions, unlocking previously constrained project sites.
Market Restraints
- Land Use Competition:Agricultural protection zones in the Danube lowlands block utility-scale solar development on 40% of technically suitable acreage.
- Polysilicon Supply Concentration:Module assembly relies on wafer inputs from three dominant Chinese producers, exposing project timelines to trade policy volatility.
- Legacy District Heating Lock-in:Natural gas cogeneration plants in Bratislava and Košice carry stranded asset risk that slows municipal heat pump adoption.
Strategic Opportunities
- Eastern Slovakia Solar Belt:Košice and Prešov regions offer lower land costs and rising industrial load from electronics manufacturing investment.
- Agrivoltaic Integration:Dual-use installations combining photovoltaic canopies with crop cultivation address land-use constraints while qualifying for agricultural subsidy stacking.
- Cross-Border Capacity Trading:Hungary and Poland interconnection upgrades enable Slovak producers to arbitrage day-ahead price differentials in regional power exchanges.
Industry Challenges
- Grid Connection Queues:Slovenská elektrizačná prenosová sústava processing timelines for distributed generation interconnection now exceed 18 months for projects above 1 MW.
- Specialized EPC Capacity:Crystalline silicon installation expertise concentrates in Bratislava and Trnava, creating labor bottlenecks for eastern region deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Slovakia Renewable Energy Market |
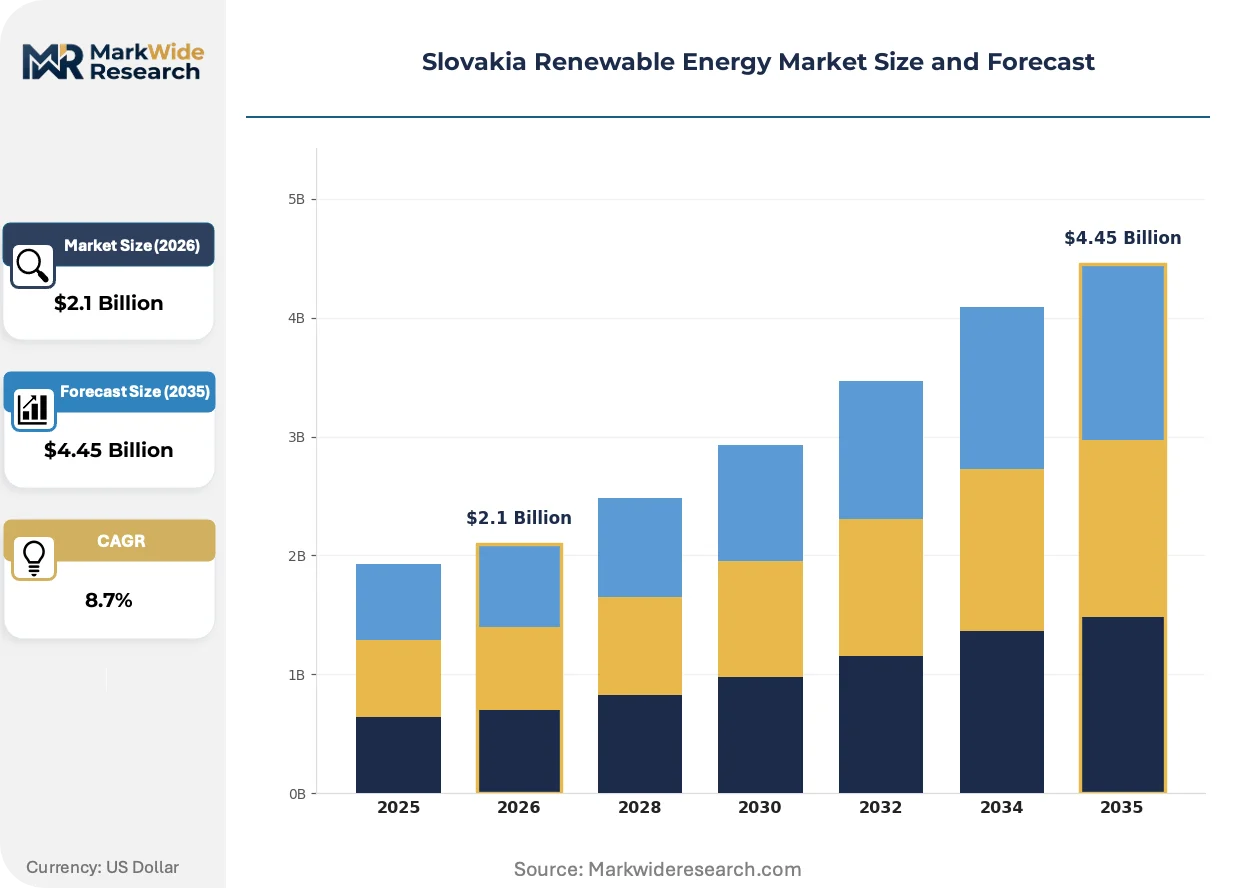
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Energy Source: Solar, Wind, Biomass, Hydropower Application: Electricity Generation, Heating, Cooling, Transportation Technology: Photovoltaic, Wind Turbines, Bioenergy Systems, Hydro Turbines End User: Residential, Commercial, Industrial, Government |
| Companies Covered | Enery, ContourGlobal, Slovenské elektrárne, Stredoslovenská energetika, GreenWay Infrastructure, Axpo Holding AG, Západoslovenská energetika (E.ON), Východoslovenská energetika, ČEZ Slovensko, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Slovakia Renewable Energy Market Evolving Landscape
Module efficiency improvements and mounting system innovations are compressing levelized cost trajectories faster than financing cost reductions alone, reshaping project economics across Slovakia's commercial and industrial segments.
Bifacial photovoltaic modules with dual-glass encapsulation are capturing reflected irradiance from ground surfaces and rooftop membranes, boosting effective capacity factors by 8-12 percentage points in Slovak conditions. Manufacturing facilities in Trnava district are deploying these systems on brownfield industrial roofs where albedo-enhancing coatings amplify rear-side gain. The technology is miniaturizing balance-of-system requirements as higher output per panel reduces combiner box and cabling density.
The EU Green Deal's delegated acts on renewable energy deployment are accelerating permitting streamlining through one-stop-shop administrative procedures. Slovakia's Ministry of Economy has transposed these requirements into national building codes, collapsing environmental impact assessment timelines for sub-10 MW solar projects. Western districts with established industrial zoning are benefiting first, while eastern regions await regional authority capacity building.
Corporate buyers are unbundling energy attribute certificates from physical power delivery, creating synthetic PPA structures that separate price hedging from renewable content claims. Automotive suppliers in the Bratislava-Trnava corridor are leading this shift, purchasing guarantees of origin through specialized trading desks rather than contracting directly with project developers. This behavior is most pronounced among tier-two component manufacturers lacking balance sheet scale for long-term offtake commitments.
Slovakia Renewable Energy Market Segmentation
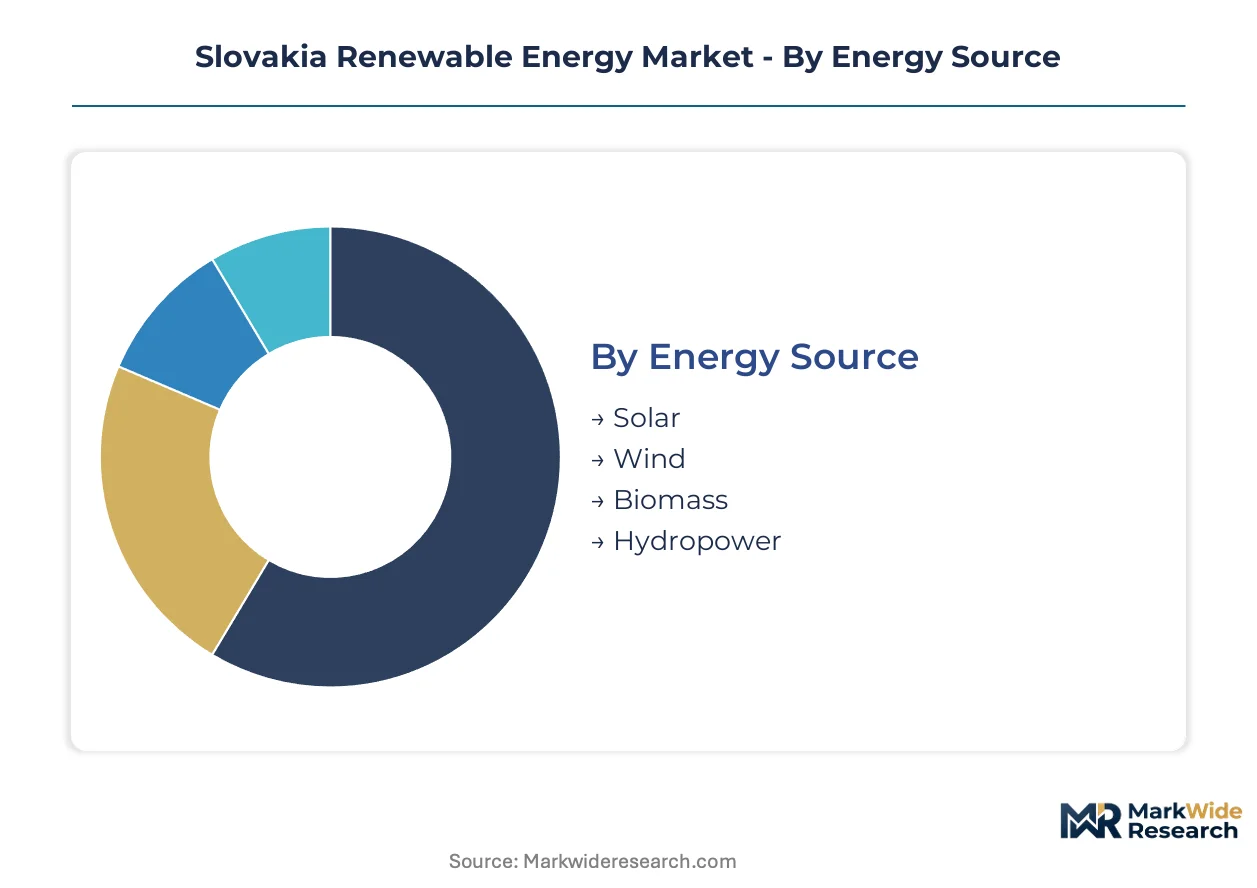
Segmentation reveals how Slovakia's renewable energy market stratifies across distinct technology pathways and customer archetypes. Each dimension exposes different competitive dynamics, from utility-scale procurement patterns to distributed generation economics.
Energy Source:
Domestic demand concentrates in hydropower and solar, with wind and biomass serving more localized or export-linked functions.
- Solar:Crystalline silicon photovoltaic systems dominate new capacity additions. Demand clusters in western districts around Bratislava and Trnava, where industrial rooftops and brownfield commercial sites offer streamlined permitting under EU Green Deal delegated acts.
- Hydropower:Run-of-river and reservoir installations anchor baseload supply through Slovenské elektrárne's incumbent fleet. Slovak mountainous topography sustains this position, though environmental flow requirements constrain greenfield expansion on the Váh and Hron river basins.
- Wind:Horizontal-axis turbines with 80-120 meter hub heights occupy limited suitable sites in the Malé Karpaty foothills. Export orientation to Czech and Austrian markets shapes project economics where interconnection capacity permits.
- Biomass:Agricultural residue combustion and anaerobic digestion systems serve district heating networks in the Danube lowlands. Fuel security depends on straw and woodchip supply chains from Nitra and Trnava agricultural zones.
Hydropower holds the largest share; momentum sits with solar.
Application:
Industrial electrification mandates are redistributing volume across application categories, with automotive sector procurement reshaping traditional utility-dominated patterns.
- Electricity Generation:Utility-scale and distributed photovoltaic arrays feed grid and behind-the-meter consumption. Volkswagen Bratislava and Kia Žilina anchor corporate PPA demand for clean power tied to EV production targets.
- Heating:Bioenergy cogeneration and heat pump systems serve municipal district heating networks. Legacy natural gas infrastructure in Bratislava and Košice creates stranded asset friction for renewable heat adoption.
- Cooling:Absorption chillers powered by biomass or solar thermal systems address industrial process cooling needs. Deployment concentrates in food processing facilities across western Slovakia.
- Transportation:GreenWay Infrastructure's charging networks and electrolytic hydrogen production for heavy freight corridors. Grid interconnection upgrades in Trnava and Nitra regions unlock fleet electrification at scale.
Electricity generation commands current investment; transportation applications are climbing the fastest.
Technology:
Technology selection tracks customer sophistication and project scale, with bifacial modules and smart inverters penetrating commercial segments first.
- Photovoltaic:Monocrystalline silicon modules with PERC or TOPCell architectures, increasingly bifacial with dual-glass encapsulation. Albedo-enhancing roof coatings in Trnava industrial zones amplify rear-side energy capture.
- Wind Turbines:Onshore horizontal-axis designs with variable pitch control and direct-drive generators. Limited deployment given Slovakia's modest wind resource compared to neighboring Austria and Czech Republic.
- Bioenergy Systems:Combustion boilers, anaerobic digesters, and combined heat and power units processing agricultural residues. Enery's project pipeline around manufacturing zones leverages proximity to feedstock supply.
- Hydro Turbines:Francis and Kaplan configurations for run-of-river installations, with pumped storage potential in the Tatra foothills. Slovenská elektrizačná prenosová sústava grid codes govern synchronization and frequency response.
Photovoltaic technology leads deployment velocity; hydro turbines retain the deepest installed base.
End User:
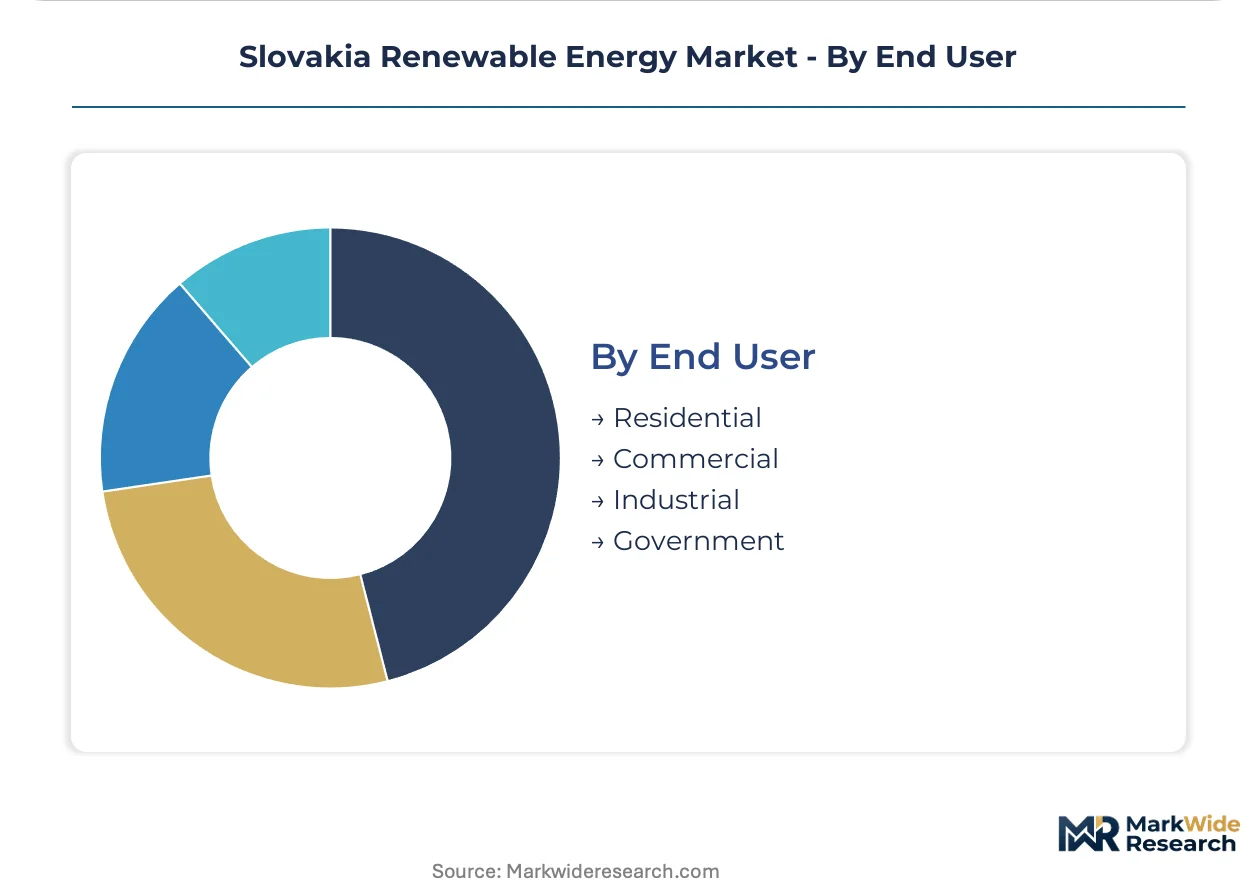
Procurement sophistication varies sharply across user categories, with industrial off-takers driving contract structure innovation while residential adoption lags on financing access.
- Industrial:Automotive and electronics manufacturers procuring through long-term PPAs and synthetic structures unbundling energy attribute certificates. Tier-two suppliers in the Bratislava-Trnava corridor purchase guarantees of origin through specialized trading desks.
- Commercial:Retail, logistics, and service sector entities deploying rooftop solar with battery storage. Grid connection queues exceeding 18 months for projects above 1 MW constrain expansion timelines.
- Residential:Single-family and multi-unit dwellings with net-metered rooftop installations. EU cohesion fund access reduces weighted average cost of capital below commercial lending rates for qualifying households.
- Government:Municipal buildings, military installations, and public infrastructure under National Energy and Climate Plan procurement mandates. Ministry of Economy auction calendars determine project bankability for public sector developers.
Industrial end users dominate contract value; residential adoption shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Slovak renewable energy exports flow primarily toward Czech and Austrian grids through cross-border interconnection capacity, with surplus hydro and solar generation arbitraging day-ahead price differentials in regional power exchanges.
Bratislava Region
Volkswagen's Bratislava facility and tier-one automotive suppliers anchor corporate PPA demand for utility-scale solar projects. The EU Green Deal's delegated acts on permitting streamlining collapse environmental impact assessment timelines for sub-10 MW installations. Trnava district manufacturing zones deploy bifacial photovoltaic modules on brownfield industrial roofs with albedo-enhancing coatings.
Western Slovakia
Grid interconnection upgrades at Slovenská elektrizačná prenosová sústava substations unlock previously constrained project sites in Nitra region. The Ministry of Economy's National Energy and Climate Plan procurement mandates direct public sector renewable deployment toward municipal buildings. Commercial estates concentrate distributed solar development where rooftop suitability expands across logistics and service sector facilities.
Central Slovakia
Run-of-river hydropower on the Váh and Hron river basins sustains baseload supply through Slovenské elektrárne's incumbent fleet. Environmental flow requirements constrain greenfield expansion despite mountainous topography. Žilina's Kia plant binds renewable offtake to EV production targets, creating anchor demand for wind projects in Malé Karpaty foothills.
Eastern Slovakia
Košice and Prešov regions offer lower land costs and rising industrial load from electronics manufacturing investment. Agricultural protection zones in the Danube lowlands block utility-scale solar development, shifting developer attention toward agrivoltaic integration. Specialized EPC capacity for crystalline silicon installation concentrates in Bratislava and Trnava, creating labor bottlenecks for eastern deployment.
Danube Lowlands
Bioenergy cogeneration and anaerobic digestion systems serve district heating networks where straw and woodchip supply chains from Nitra and Trnava agricultural zones sustain fuel security. Legacy natural gas infrastructure in Bratislava and Košice carries stranded asset risk that slows municipal heat pump adoption. Biomass retention in district heating reflects agricultural residue availability rather than technology preference.
Slovakia Renewable Energy Market Competitive Landscape
Player mix skews toward incumbent utilities with legacy hydro assets and specialized distributed generation developers. Market structure concentrates around state-affiliated generators controlling baseload capacity, while solar and transport-electrification segments attract independent developers. Two strategic archetypes dominate: integrated utilities leveraging existing grid relationships, and project-focused independents securing land and permitting rights ahead of auction calendars. Competitive moves center on long-term PPA origination with automotive off-takers and cross-border capacity trading positions.
Within the utility archetype, Slovenské elektrárne represents incumbent hydro-based supply, while Západoslovenská energetika occupies a position within the E.ON group structure. Among independent developers, Enery exemplifies distributed solar specialization, and GreenWay Infrastructure anchors the transport-electrification segment. These named entities illustrate how market positioning separates legacy generation holders from project developers targeting manufacturing zone load centers.
| Leading Market Players |
|---|
| Enery |
| ContourGlobal |
| Slovenské elektrárne |
| Stredoslovenská energetika |
| GreenWay Infrastructure |
| Axpo Holding AG |
| Západoslovenská energetika (E.ON) |
| Východoslovenská energetika |
| ČEZ Slovensko |
| Others |
Value Network & Pricing Analysis
Long-term power purchase agreements lock in both polysilicon supply access and price visibility for Slovak project developers, insulating corporate buyers from module cost volatility while tethering EPC margins to Chinese wafer pricing cycles. This contract-structure pattern concentrates procurement leverage with automotive off-takers in Bratislava and Trnava districts.
Pricing Analysis
Current-generation bifacial photovoltaic modules command premium positioning over prior-generation monofacial PERC systems, while next-generation TOPCon architectures are displacing both in utility-scale tenders. Three-tier pricing structure across premium, standard, and economy levels tracks module efficiency grades and certification tiers. Cost compression in standard-tier crystalline silicon is intensifying because Chinese polysilicon capacity expansion outpaces European demand growth. Tier-two automotive suppliers exhibit highest price sensitivity, lacking balance sheet scale for long-term offtake commitments.
Supply Chain Analysis
Inbound logistics costs from Shanghai to Hamburg container terminals expose Slovak developers to Red Sea routing disruptions and Baltic port congestion, compressing project commissioning windows. Module assembly draws from polysilicon ingots sourced from China, Malaysia, and Vietnam, with wafer slicing concentrated in Chinese provinces. Single-source vulnerability in metallurgical-grade silicon feedstock threatens timeline certainty for western Slovakia manufacturing zone deployments. Distribution runs through Bratislava-based EPC contractors with crystalline silicon installation expertise, creating labor bottlenecks for eastern region projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized EPC capacity for bifacial module installation represents the binding constraint, with project timelines extending beyond auction validity periods where skilled labor pools exhaust.
For Market Incumbents: Consolidate grid interconnection queue positions through strategic acquisitions of permitted but unbuilt projects in Trnava and Nitra regions. Slovenské elektrárne should deepen backward integration into energy storage systems to defend baseload positioning against solar-plus-storage entrants. Channel control over district heating networks in Bratislava and Košice remains defensible against heat pump substitution. For New Entrants and Emerging Players: Lead with agrivoltaic development in eastern Slovakia's Košice and Prešov regions, where agricultural protection zones block conventional utility-scale solar. Dual-use installations combining photovoltaic canopies with crop cultivation penetrate the white-space between farming subsidies and renewable energy premiums. Go-to-market execution should target electronics manufacturing facilities seeking synthetic PPA structures unbundled from physical delivery. For Investors and Strategic Acquirers: Capital is best deployed toward distributed solar developers with secured land positions in western Slovakia manufacturing zones, where industrial load density supports behind-the-meter economics. Long-term viability hinges on EU cohesion fund access sustaining weighted average cost of capital advantages over commercial lending. The signal to watch is Ministry of Economy auction calendar density, which determines project bankability faster than technology cost curves alone.| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement | Volkswagen Bratislava and Kia Žilina anchor corporate renewable offtake tied to EV production mandates. |
| Capacity Buildout | Slovenská elektrizačná prenosová sústava substation upgrades unlock previously constrained project sites in Nitra region. |
| Backward Integration | Enery's project pipeline around manufacturing zones secures proximity to agricultural residue supply chains. |
| Green Certification Program | EU Green Deal delegated acts collapse environmental impact assessment timelines for sub-10 MW solar installations. |
| Technology Licensing | Bifacial module deployment with albedo-enhancing roof coatings amplifies rear-side energy capture in Trnava industrial zones. |
Research Methodology
A spread of perspectives from IPP project developers, EPC contractors, utility planning officers, and grid operators converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against EIA data, IEA reports, FERC filings, and project development databases. Bottom-up capacity addition modeling triangulated against top-down National Energy and Climate Plan target trajectories.
Segmentation dimensions modeled span fuel source, generation capacity tier, project scale, regulatory framework, and regional grid type across the projection horizon. CAGRs were derived from technology cost curve trajectories, auction calendar density, and cross-border capacity allocation rule changes. Forecast inputs incorporated polysilicon supply concentration risk and EU cohesion fund disbursement timelines.
Underlying assumptions cover module cost decline continuity, grid interconnection upgrade schedules, and automotive sector electrification mandates, with deviation risk concentrated in trade policy volatility affecting Chinese wafer inputs. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
India Solar Energy Market
Solar Power Systems
Solar Power Market
Solar Power Systems
Germany Distributed Solar Power Generation Market
Solar Power Systems
Mexico Solar Energy Market
Solar Power Systems
Solar-Powered EV Charging Stations Market
Solar Power Systems
Solar Updraft Tower Market
Solar Power Systems
Solar Panel Cleaning System Market
Solar Power Systems
Solar PV Junction Box Market
Solar Power Systems
Solar Panels for Home Market
Solar Power Systems
US Solar Power Meters Market
Solar Power Systems
Solar PV Tracker Market
Solar Power Systems
Boat Solar Panel Market
Solar Power Systems
Solar Freezer Market
Solar Power Systems
Solar Rack Market
Solar Power Systems
Commercial Solar Panel Market
Solar Power Systems
Solar Grid-Tied Systems Market