
 Thin Film Photovoltaic Modules Market | 2026-2036
Thin Film Photovoltaic Modules Market Size, Share, and Industry Trends Forecast 2026-2036
Thin Film Photovoltaic Modules Market Outlook
The performance gap between premium cadmium telluride modules and commodity amorphous silicon products is realigning procurement strategies across utility portfolios. First Solar leverages its vertically integrated Ohio manufacturing footprint to anchor long-term supply contracts with domestic developers. Kaneka Corporation specializes in high-efficiency amorphous silicon architectures for constrained rooftop geometries in Japanese urban corridors. Ascent Solar Technologies competes through flexible CIGS form factors that occupy niche aerospace and portable power segments where rigid glass-glass modules fail.
Thin Film Photovoltaic Modules are semiconductor-based energy conversion devices manufactured through vapor deposition of light-absorbing layers onto glass, metal, or polymer substrates, typically achieving active layer thicknesses below ten micrometers. Cadmium telluride dominates utility-scale deployment through its favorable temperature coefficient and streamlined manufacturing, while CIGS segments capture premium building-integrated applications where aesthetic flexibility and partial shading tolerance command margin premiums. Organic photovoltaics remain experimental in commercial volumes but attract R&D intensity from materials chemistry groups targeting indoor and disposable electronics power harvesting.
The U.S. Federal Energy Regulatory Commission and the Department of Energy shape grid interconnection timelines and loan guarantee access for utility-scale thin-film installations, while India's Central Electricity Authority mandates domestic content requirements that filter module eligibility for national solar park auctions. The EU Green Deal and F-Gas Regulation impose embodied carbon disclosure and fluorinated gas phase-down obligations that disadvantage certain thin-film chemistries in European public tenders. Stakeholders must weigh technology-specific regulatory exposure against regional manufacturing incentive durability when committing to multi-gigawatt expansion plans.
Market Dynamics
The U.S. Inflation Reduction Act's domestic content bonus credits are forcing a geographic reconfiguration of thin-film manufacturing capacity, pulling investment away from Southeast Asian supply chains toward American production facilities. This regulatory gravity is compressing procurement timelines for utility-scale developers while elevating capital requirements for market entry.
Growth Catalysts
- India's PLI scheme:The country's production-linked incentive program for solar manufacturing is attracting thin-film module assembly investments to serve Rajasthan and Gujarat solar parks. Domestic content mandates from the Central Electricity Authority lock in procurement pipelines for qualified suppliers.
- Cadmium telluride temperature performance:The material's favorable coefficient in desert climates reduces thermal derating losses, making it the default choice for utility-scale installations in high-irradiance zones.
- Green hydrogen mandates:National hydrogen strategies requiring gigawatt-scale electrolyzer power are creating dedicated offtake agreements for thin-film modules with predictable supply curves.
Market Restraints
- Tellurium supply concentration:The element's extraction ties to copper refining create geographic concentration risk, with primary refining capacity concentrated in limited jurisdictions.
- F-Gas Regulation phase-down:The EU's fluorinated gas restrictions disadvantage certain thin-film chemistries in European public tenders by imposing embodied carbon disclosure obligations.
- Crystalline silicon cost compression:Perovskite-silicon tandem development threatens to absorb thin-film's temperature coefficient advantage while undercutting its cost position in utility procurement.
Strategic Opportunities
- Building-integrated photovoltaics:CIGS aesthetic flexibility and partial shading tolerance command margin premiums in European commercial facade applications where crystalline silicon fails.
- Aerospace power systems:Flexible polymer-substrate CIGS modules are penetrating satellite and unmanned aerial vehicle markets where weight constraints dominate design choices.
- Domestic content bonus credits:The IRA's manufacturing incentives create a decade-long tariff shelter for U.S.-produced cadmium telluride modules, locking in price premiums against imported competition.
Industry Challenges
- Vapor deposition technician scarcity:The specialized semiconductor manufacturing skills required for thin-film production are concentrated in legacy electronics regions, constraining facility ramp rates.
- Interconnection queue delays:Federal Energy Regulatory Commission timelines for utility-scale project approval are extending developer capital lockup periods, compressing module supplier payment terms.
- Certification fragmentation:Divergent IEC and national testing protocols across target markets multiply qualification costs for multi-gigawatt expansion programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thin Film Photovoltaic Modules Market |
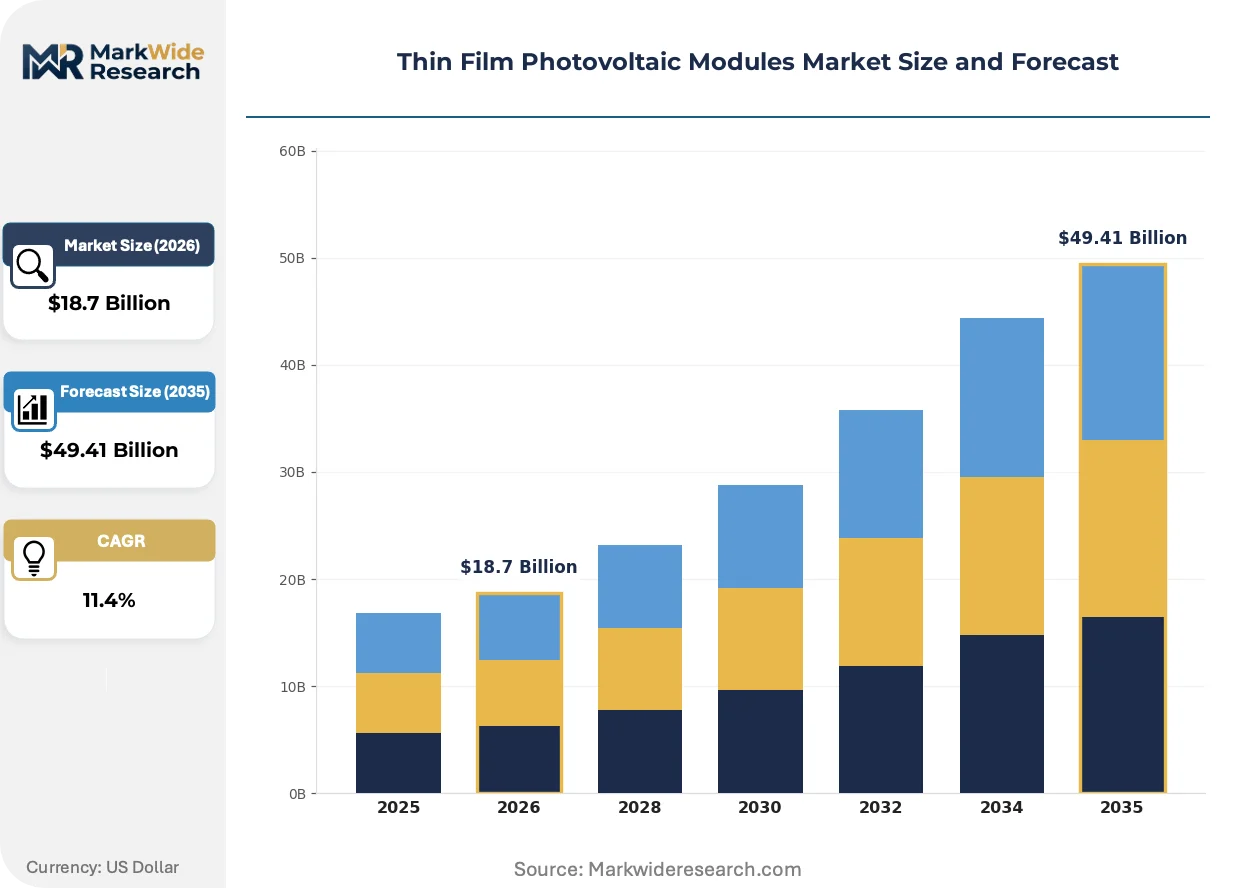
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CIGS, CdTe, Amorphous Silicon, Organic Photovoltaics Technology: Thin-Film, Emerging Technologies, BIPV, Flexible Modules End User: Residential, Commercial, Industrial, Utility Scale Application: Solar Farms, Rooftop Installations, Building Integrated Photovoltaics, Off-Grid Solutions |
| Companies Covered | First Solar, Ascent Solar Technologies, Kaneka Corporation, MiaSolé Hi-Tech Corp., Oxford Photovoltaics, Solar Frontier K.K., Hanergy Thin Film Power Group, Solibro GmbH, Avancis GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thin Film Photovoltaic Modules Market Strategic Shifts
Perovskite tandem architectures are disrupting the historical efficiency ceiling for thin-film technologies, pulling R&D investment away from incremental cadmium telluride improvements toward next-generation stack designs. This materials transition is compressing product development cycles while elevating capital intensity.
Tandem perovskite-silicon cells are integrating into pilot production lines at established thin-film manufacturers, with vapor deposition equipment retrofitted for dual-junction processing. Utility developers in high-irradiance zones are piloting these modules for 2028-2030 delivery slots. The technology is integrating efficiency gains that threaten to collapse the performance gap with premium crystalline silicon while retaining thin-film's manufacturing cost structure.
The EU F-Gas Regulation is tightening disclosure requirements for fluorinated compounds used in certain thin-film manufacturing processes, forcing process chemistry revisions at European production facilities. Module suppliers are reformulating etching and cleaning chemistries to maintain eligibility for Green Deal-aligned public tenders. CIGS manufacturers with European assembly capacity face the steepest compliance cost escalations.
Long-term power purchase agreements are displacing merchant exposure as the dominant procurement model for utility-scale thin-film deployment. Developers are locking in 20-25 year offtake contracts with investment-grade counterparties to secure project finance, compressing supplier selection criteria toward bankability metrics over unit cost. This pattern is most visible in U.S. Southwest utility portfolios where IRA incentives amplify contract value.
Thin Film Photovoltaic Modules Market Segmentation
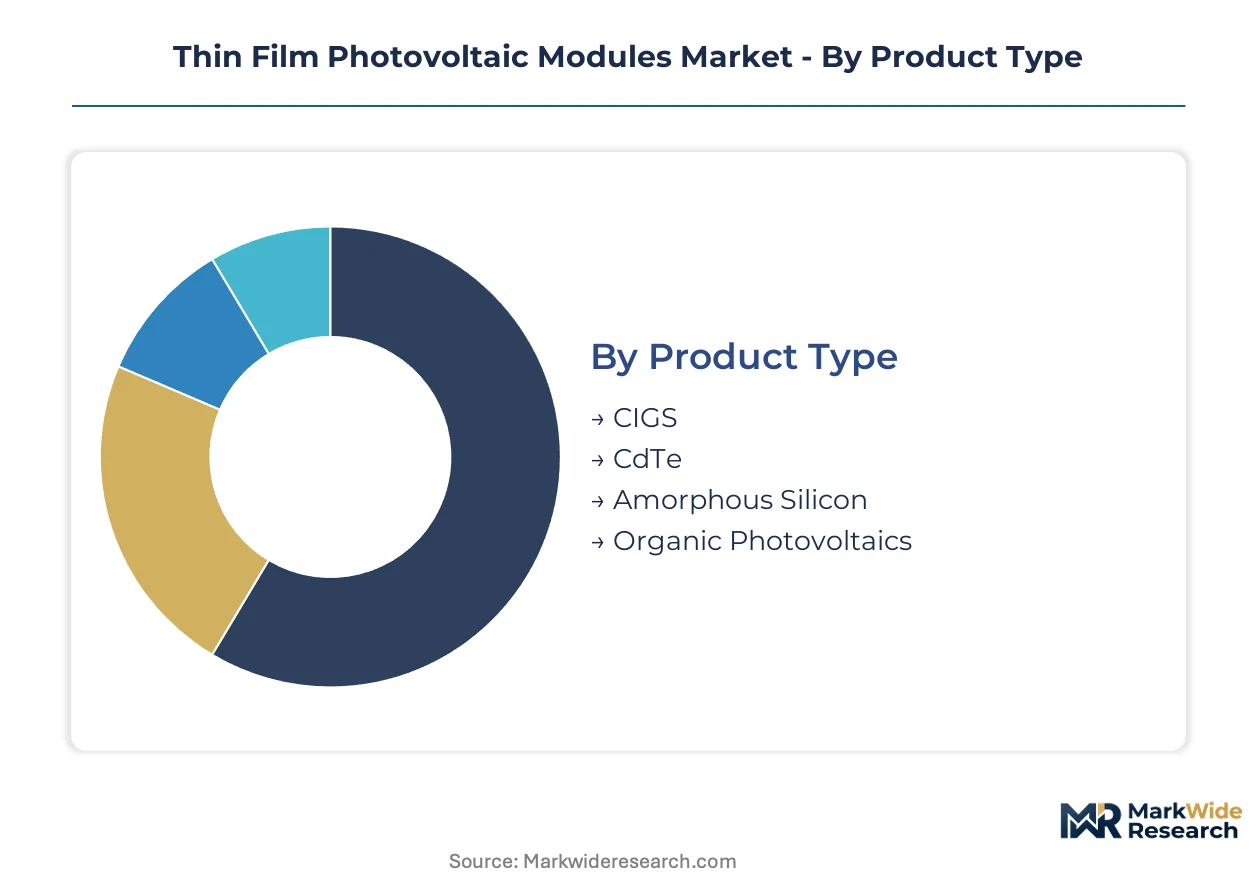
Thin-film procurement decisions pivot on temperature coefficients, form factor constraints, and domestic content eligibility. Buyers weigh CdTe's desert performance against CIGS's architectural flexibility, while emerging chemistries reshape long-term technology roadmaps.
Product Type:
Material chemistry determines thermal behavior, supply chain risk exposure, and regulatory compliance burden across procurement portfolios.
- CdTe:Cadmium telluride deposition onto glass substrates achieves favorable temperature coefficients that minimize thermal derating in high-irradiance desert installations. Utility-scale developers in Rajasthan and Gujarat favor CdTe for gigawatt-scale solar parks where heat-induced performance degradation would erode project returns.
- CIGS:Copper indium gallium selenide enables flexible substrate architectures and partial shading tolerance that command margin premiums in building-integrated applications. European commercial facade projects specify CIGS where aesthetic integration and irregular surface coverage requirements exclude rigid glass-glass alternatives.
- Amorphous Silicon:Hydrogenated silicon thin-film targets constrained rooftop geometries in dense urban corridors where weight and installation complexity limit crystalline silicon deployment.
- Organic Photovoltaics:Polymer-based absorber layers remain experimental at commercial volumes, attracting R&D intensity from materials chemistry groups targeting indoor and disposable electronics power harvesting.
CdTe leads on scale; Organic Photovoltaics leads on momentum.
Technology:
Manufacturing process maturity and substrate flexibility separate bankable production lines from pilot-scale demonstrations.
- Thin-Film:Established vapor deposition processes using CdTe and CIGS chemistries anchor utility-scale supply contracts with predictable yield curves and IEC certification pathways.
- Emerging Technologies:Perovskite tandem architectures integrate into pilot production lines at established manufacturers, with vapor deposition equipment retrofitted for dual-junction processing that threatens to collapse the performance gap with premium crystalline silicon.
- BIPV:Building-integrated photovoltaic systems embed active layers into facade and roofing materials, requiring aesthetic flexibility and structural load-bearing characteristics that CIGS form factors satisfy.
- Flexible Modules:Polymer-substrate CIGS architectures penetrate satellite and unmanned aerial vehicle markets where weight constraints dominate design choices and rigid modules fail.
Thin-Film leads on scale; Emerging Technologies leads on momentum.
End User:
Capital intensity and offtake contract duration filter supplier selection criteria across customer categories.
- Utility Scale:Gigawatt-scale developers lock in 20-25 year power purchase agreements with investment-grade counterparties, compressing module selection toward bankability metrics and domestic content eligibility over unit cost alone.
- Industrial:Manufacturing facilities and data centers pursue behind-the-meter installations to hedge volatile grid tariffs, favoring thin-film modules with predictable degradation curves for long-term energy cost forecasting.
- Commercial:Office and retail property owners prioritize building-integrated aesthetics and partial shading tolerance in urban environments where rooftop geometry constraints limit crystalline silicon deployment.
- Residential:Distributed rooftop installations concentrate in markets with favorable net metering policies, though thin-film penetration lags crystalline silicon on unit cost metrics.
Utility Scale leads on scale; Industrial leads on momentum.
Application:
Installation environment and grid connectivity requirements determine module form factor and certification needs.
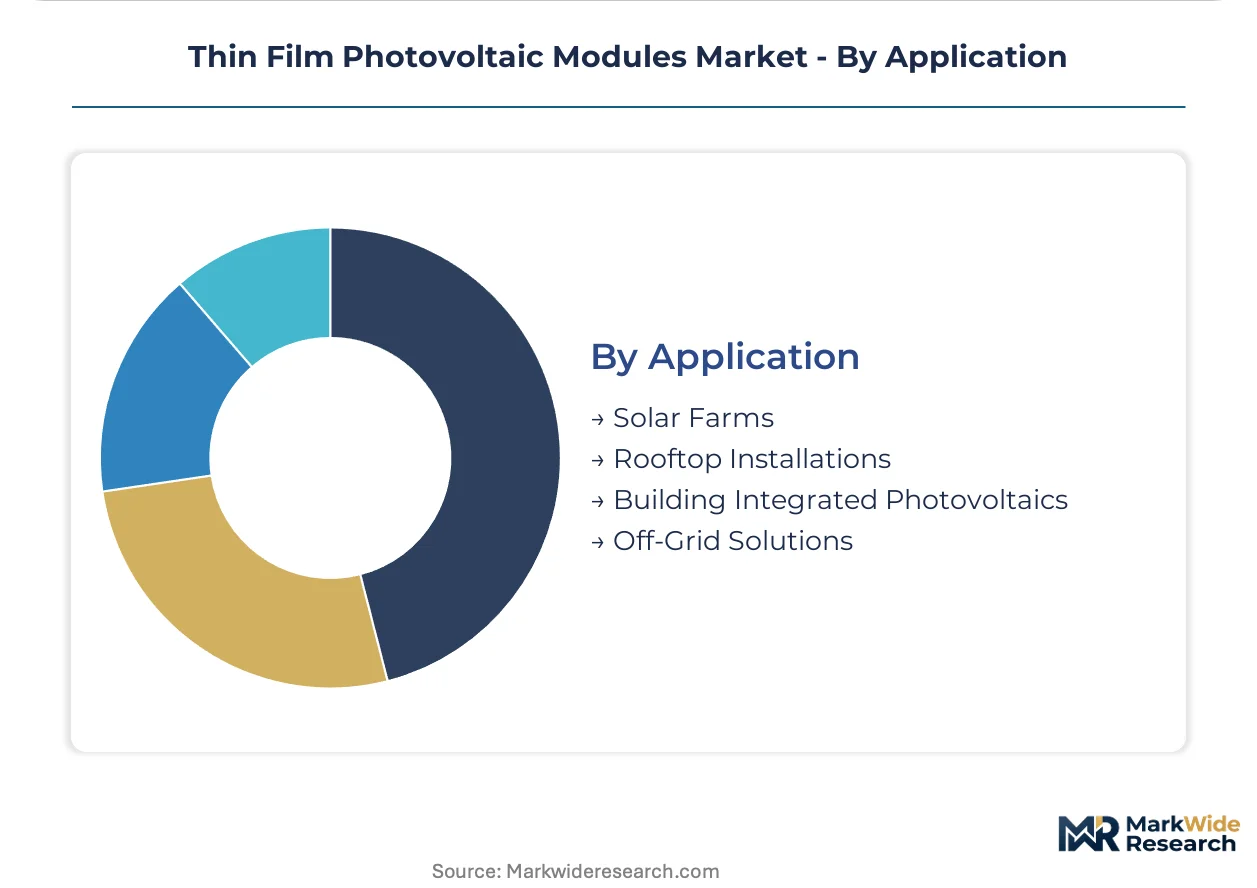
- Solar Farms:Ground-mounted desert installations in Rajasthan and Gujarat specify CdTe modules for temperature coefficient advantages that reduce thermal derating losses in high-irradiance zones.
- Building Integrated Photovoltaics:European commercial facade applications demand CIGS aesthetic flexibility and partial shading tolerance where crystalline silicon fails to meet architectural integration requirements.
- Rooftop Installations:Constrained urban geometries in Japanese metropolitan corridors favor amorphous silicon architectures for weight-sensitive residential and commercial retrofits.
- Off-Grid Solutions:Remote telecommunications and rural electrification projects specify flexible CIGS modules for portable deployment scenarios where grid interconnection is unavailable.
Solar Farms leads on scale; Building Integrated Photovoltaics leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized semiconductor manufacturing skills concentrate in legacy electronics regions, constraining facility ramp rates while pulling investment toward jurisdictions with established vapor deposition expertise and policy certainty.
United States
The Inflation Reduction Act's domestic content bonus credits redirect manufacturing investment toward American thin-film production facilities. FERC interconnection timelines and DOE loan guarantee access shape grid deployment schedules for utility-scale installations. Ohio anchors cadmium telluride manufacturing with vertically integrated production serving domestic developers.
India
State solar parks in Rajasthan and Gujarat drive gigawatt-scale module deployment under national green hydrogen mandates. The Central Electricity Authority's domestic content requirements filter module eligibility for national auctions. The western states concentrate procurement pipelines for qualified suppliers under the PLI scheme.
Germany
The EU F-Gas Regulation imposes fluorinated gas phase-down obligations that disadvantage certain thin-film chemistries in public tenders. Embodied carbon disclosure requirements under the EU Green Deal reshape process chemistry at European production facilities. Bavaria hosts CIGS assembly capacity facing steep compliance cost escalations.
Japan
Constrained rooftop geometries in dense urban corridors sustain demand for high-efficiency amorphous silicon architectures. METI industrial policy supports domestic manufacturing retention for strategic energy security. The Kanto region around Tokyo concentrates installation activity for weight-sensitive residential retrofits.
China
Dual carbon goals and MIIT industrial planning accelerate domestic thin-film capacity expansion for export markets. GB standards and SAMR certification protocols create parallel qualification pathways distinct from IEC frameworks. The Yangtze River Delta clusters equipment manufacturing and materials refining for supply chain control.
Thin Film Photovoltaic Modules Market Competitive Environment
Top-tier vendors anchor utility-scale procurement with bankable production lines, while mid-tier specialists occupy building-integrated and flexible substrate niches. The competitive structure stratifies across three archetypes: vertically integrated cadmium telluride producers, CIGS flexibility specialists, and amorphous silicon efficiency optimizers. Capacity expansion and strategic partnerships dominate competitive moves as firms secure domestic content eligibility under divergent national incentive regimes.
Among North American producers, First Solar anchors the vertically integrated archetype with Ohio-based manufacturing serving domestic utility procurement. Within the CIGS specialization tier, Ascent Solar Technologies and Kaneka Corporation occupy distinct positions—Ascent targeting flexible form factors for aerospace applications, Kaneka concentrating high-efficiency architectures for constrained Japanese rooftops. These three firms exemplify how geographic policy incentives and substrate technology choices segment competitive positioning across the thin-film landscape.
| Leading Market Players |
|---|
| First Solar |
| Ascent Solar Technologies |
| Kaneka Corporation |
| MiaSolé Hi-Tech Corp. |
| Oxford Photovoltaics |
| Solar Frontier K.K. |
| Hanergy Thin Film Power Group |
| Solibro GmbH |
| Avancis GmbH |
| Others |
Value Chain & Pricing Dynamics
Tellurium spot price volatility cascades through cadmium telluride module manufacturing into three distinct procurement tiers, compressing margins for unhedged buyers while rewarding long-term offtake contractors with supply certainty.
Pricing Analysis
Module procurement splits between bundled EPC contracts and unbundled component sales, with utility-scale developers favoring the former to transfer construction risk. Three-tier pricing structure across premium, standard, and economy levels tracks efficiency binning and domestic content certification, with IRA-compliant U.S. manufacturing commanding sustained premiums. Pricing pressure stems from crystalline silicon tandem cell development eroding thin-film's historical cost advantage. Industrial behind-the-meter buyers exhibit highest price sensitivity due to thin capital allocation for energy projects, while utility-scale developers prioritize bankability over unit cost.
Supply Chain Analysis
Regional distribution centers in Ohio, Gujarat, and Bavaria anchor hub-and-spoke fulfillment patterns for module deployment. Manufacturing concentration spans the United States, India, and China, with tellurium refining tethered to copper smelting in Canada, Japan, and Russia. Vapor deposition equipment, high-purity selenium, and specialized glass substrates constitute critical input dependencies. Single-source vulnerability in tellurium supply creates exposure to base metal market cycles. Distribution runs through EPC contractor networks and direct utility procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The thin film photovoltaic modules market functions as a stable compounder, with national renewable portfolio standards and green hydrogen mandates providing durable demand visibility across multi-decade deployment horizons.
For Market Incumbents: Anchor domestic content eligibility through captive U.S. manufacturing expansion under IRA incentive windows, securing long-term supply contracts with investment-grade utility offtakers. Deepen backward integration into tellurium recovery and refining to mitigate raw material concentration risk from copper smelter dependency. Perovskite-silicon tandem development threatens to absorb temperature coefficient advantages; accelerate R&D partnerships to maintain technology differentiation. For New Entrants and Emerging Players: Perovskite tandem architectures offer a technology-first wedge for specialized manufacturers lacking legacy CdTe scale. Building-integrated photovoltaics in European commercial facade applications present the most penetrable white space, with CIGS form factors commanding margin premiums where crystalline silicon fails aesthetically. Pursue certification partnerships with established European assembly facilities to bypass F-Gas Regulation compliance cost barriers. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated CdTe producers holding U.S. manufacturing footprints and locked utility offtake pipelines. Five-to-ten-year viability hinges on sustained IRA incentive durability and successful perovskite tandem commercialization timelines. Monitor FERC interconnection queue clearance rates as the critical signal for utility-scale deployment velocity and module supplier payment term compression.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Manufacturing Buildout | IRA bonus credits create decade-long tariff shelter for Ohio-based CdTe production serving U.S. utility procurement. |
| Perovskite Tandem Licensing | Technology transfer agreements with European research institutes accelerate dual-junction pilot line deployment. |
| Long-term Power Purchase Agreements | Twenty-year offtake contracts with investment-grade counterparties secure project finance for Rajasthan solar parks. |
| Tellurium Supply Integration | Captive refining partnerships with Canadian copper smelters reduce geographic concentration risk in critical raw materials. |
| Building-integrated Certification | CE marking and aesthetic performance validation unlock European commercial facade procurement premiums for CIGS modules. |
Study Parameters
Multiple input streams — primary interviews with utility procurement officers, EPC contractors, and vapor deposition equipment specialists, alongside secondary validation through FERC interconnection filings, IEA renewable deployment databases, and SEC manufacturing capex disclosures — were reconciled through bottom-up and top-down triangulation to construct market estimates.
Historical capacity expansion patterns were cross-referenced against panel input from technology roadmapping sessions to anchor projections across the analysis window. Segmentation modeling incorporated material chemistry, manufacturing process maturity, end-use capital intensity, and regional regulatory framework dimensions. CAGRs were derived from fitted growth curves calibrated to disclosed module shipment volumes and announced production capacity additions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to perovskite tandem commercialization timelines, IRA incentive renewal politics, and tellurium supply disruption events. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Building-Integrated Photovoltaic (BIPV) Roofing Market
Solar Power Systems
Solar Panel Cleaning Equipment Market
Solar Power Systems
Denmark Solar Energy Market
Solar Power Systems
Residential Solar Shading System Market
Solar Power Systems
Outdoor Solar LED Market
Solar Power Systems
Distributed Solar Energy Market
Solar Power Systems
Rooftop Solar Panels Market
Solar Power Systems
France Solar Energy Market
Solar Power Systems
United Arab Emirates Solar Photovoltaic (PV) Market
Solar Power Systems
India Solar Photovoltaic (PV) Market
Solar Power Systems
Australia Solar Market
Solar Power Systems
Spray-On Solar Cells Market
Solar Power Systems
GCC Solar Photovoltaic (PV) Market
Solar Power Systems
Global Rooftop Solar Photovoltaic Market
Solar Power Systems
On-Grid Solar Inverter Market
Solar Power Systems
Third Generation Solar Cell Sales Market