
 Orthopedic Soft Tissue Repair Market | 2026-2036
Orthopedic Soft Tissue Repair Market Size, Share, and Industry Trends Forecast 2026-2036
Orthopedic Soft Tissue Repair Market Intelligence
Bioresorbable scaffold technology is rewriting how orthopedic surgeons approach rotator cuff and ligament reconstruction, shifting fixation strategies from permanent metal anchors toward polymer-based solutions that integrate with native tissue remodeling. Arthrex leverages its vertically integrated R&D pipeline to dominate sports medicine anchor innovation. Stryker sustains manufacturing scale across suture and graft portfolios. Smith & Nephew navigates European and Asian regulatory pathways for biologic mesh products.
Orthopedic soft tissue repair encompasses surgical restoration of tendons, ligaments, cartilage, and muscle through mechanical fixation, biological augmentation, or synthetic reinforcement, typically employing absorbable polymers, allograft matrices, or braided polyester sutures rated for tensile loads exceeding 50 Newtons to restore biomechanical function after acute trauma or degenerative failure. Sutures and anchors anchor the majority of revenue given their universal application across knee and shoulder procedures, while grafts capture premium margins due to processing complexity and biologic sourcing constraints. Arthroscopic surgery delivery mode is displacing open approaches in ambulatory settings, though hybrid techniques persist for multi-ligament knee reconstructions requiring combined visualization and direct access.
FDA 510(k) clearance pathways and EU MDR conformity assessments shape product development timelines and clinical evidence requirements for soft tissue fixation devices, with biologic grafts facing heightened scrutiny under EMA and FDA donor-safety standards. ISO 13485 quality management and ASTM F1635 bioresorption testing protocols further constrain formulation choices and supplier qualification. Stakeholders must monitor how CMS reimbursement adjustments for outpatient musculoskeletal procedures reshape site-of-care economics and device procurement priorities.
Market Dynamics
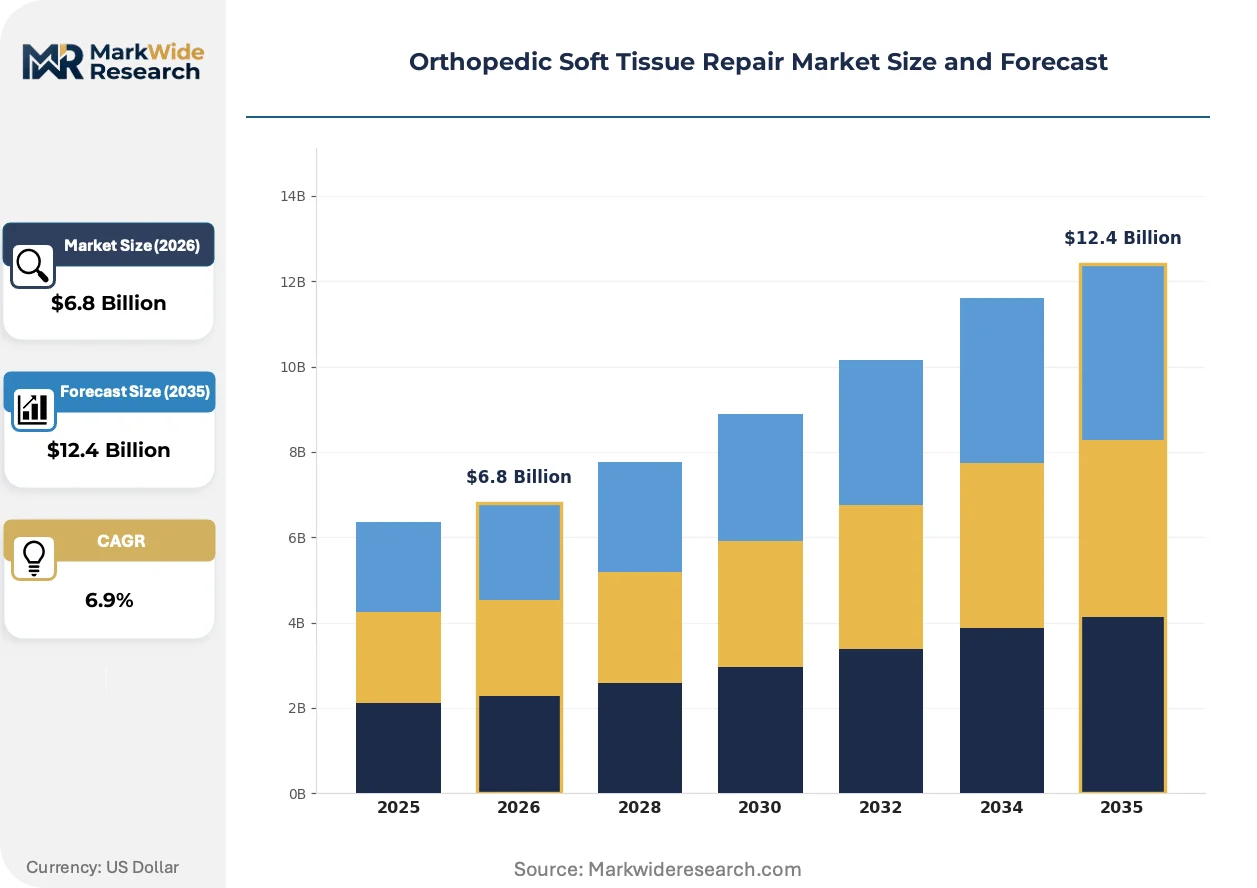
The orthopedic soft tissue repair market pivots on bioresorbable polymer innovation, which is systematically displacing permanent metal fixation across rotator cuff and ligament procedures. Manufacturers face compressed development cycles as surgeons demand implants that match native tissue remodeling timelines rather than outlasting them.
Growth Catalysts
- Sports medicine clinic expansion:Ambulatory surgical centers in the United States are scaling same-day arthroscopic procedures, creating pull-through demand for suture anchors and allograft matrices optimized for rapid deployment.
- FDA biologic guidance evolution:Tighter quality benchmarks for biologic-based implants are filtering out marginal suppliers and concentrating procurement among qualified manufacturers with validated donor-safety protocols.
- Arthroscopic technique maturation:Visualization technology advances enable complex multi-ligament knee reconstructions through minimally invasive approaches previously requiring open surgery.
Market Restraints
- Allograft sourcing constraints:Limited donor tissue availability and extended processing timelines for demineralized bone matrices constrain graft portfolio expansion regardless of demand signals.
- EU MDR conformity costs:Heightened clinical evidence requirements for soft tissue fixation devices extend time-to-market by 18-36 months and favor well-capitalized incumbents over emerging competitors.
- Metal anchor residual value:Established surgeons with decades of titanium anchor experience exhibit switching friction despite polymer performance parity in biomechanical testing.
Strategic Opportunities
- Point-of-care biologic processing:Autologous cell concentration systems at ambulatory sites enable patient-specific graft augmentation without centralized tissue bank dependency.
- Pediatric sports medicine:Growing youth athletic participation in Germany and Australia creates demand for growth-plate-sparing fixation techniques absent from adult-focused portfolios.
- ISO 13485 certification arbitrage:Contract manufacturers in Ireland and Switzerland with established quality management systems offer accelerated market access for device startups lacking in-house regulatory infrastructure.
Industry Challenges
- Surgeon training bandwidth:Arthroscopic knot-tying proficiency and graft tensioning technique require proctored case volumes that conflict with compressed fellowship schedules.
- Bioresorption rate standardization:ASTM F1635 testing protocol variability across laboratories produces inconsistent degradation data that complicates regulatory submissions and clinical messaging.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Orthopedic Soft Tissue Repair Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.4 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sutures, Anchors, Grafts, Staples Application: Knee Surgery, Shoulder Surgery, Hip Repair, Sports Medicine Delivery Mode: Open Surgery, Arthroscopic Surgery, Minimally Invasive, Hybrid End User: Hospitals, Ambulatory Surgical Centers, Orthopedic Clinics, Rehabilitation Centers |
| Companies Covered | DePuy Synthes Inc., CONMED Corporation, Arthrex Inc., LifeNet Health, Integra LifeSciences Holding Corporation, Stryker Corporation, Smith & Nephew plc, Medtronic plc, Zimmer Biomet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orthopedic Soft Tissue Repair Market Strategic Shifts & Innovations
Fixation strategies are converging on tissue-matched resorption timelines, with mechanical performance no longer the sole purchase criterion. Surgeons now evaluate how implants interact with remodeling biology over multi-year horizons.
Knotless suture anchor designs are migrating from passive interference fixation toward active tensioning mechanisms that maintain graft-to-bone contact through early healing phases. High-volume shoulder specialists in academic medical centers are adopting these systems for revision rotator cuff repairs where tissue quality compromises traditional repair integrity. The shift compresses revenue per procedure while expanding addressable case complexity.
EU MDR Article 10 clinical evaluation requirements are forcing manufacturers to generate prospective registry data for Class III soft tissue devices previously cleared on predicate equivalence. Small and mid-size firms without legacy implant portfolios face existential documentation burdens. German notified bodies report 14-month average review queues for biologic mesh submissions.
Hospital purchasing committees are consolidating vendor relationships around full-procedure kits rather than à la carte anchor and suture procurement. Integrated delivery networks in Texas and Florida negotiate multi-year supply agreements that bundle fixation devices with arthroscopy capital equipment. This concentration pressures independent distributors and rewards manufacturers with comprehensive sports medicine portfolios.
Orthopedic Soft Tissue Repair Market Segmentation
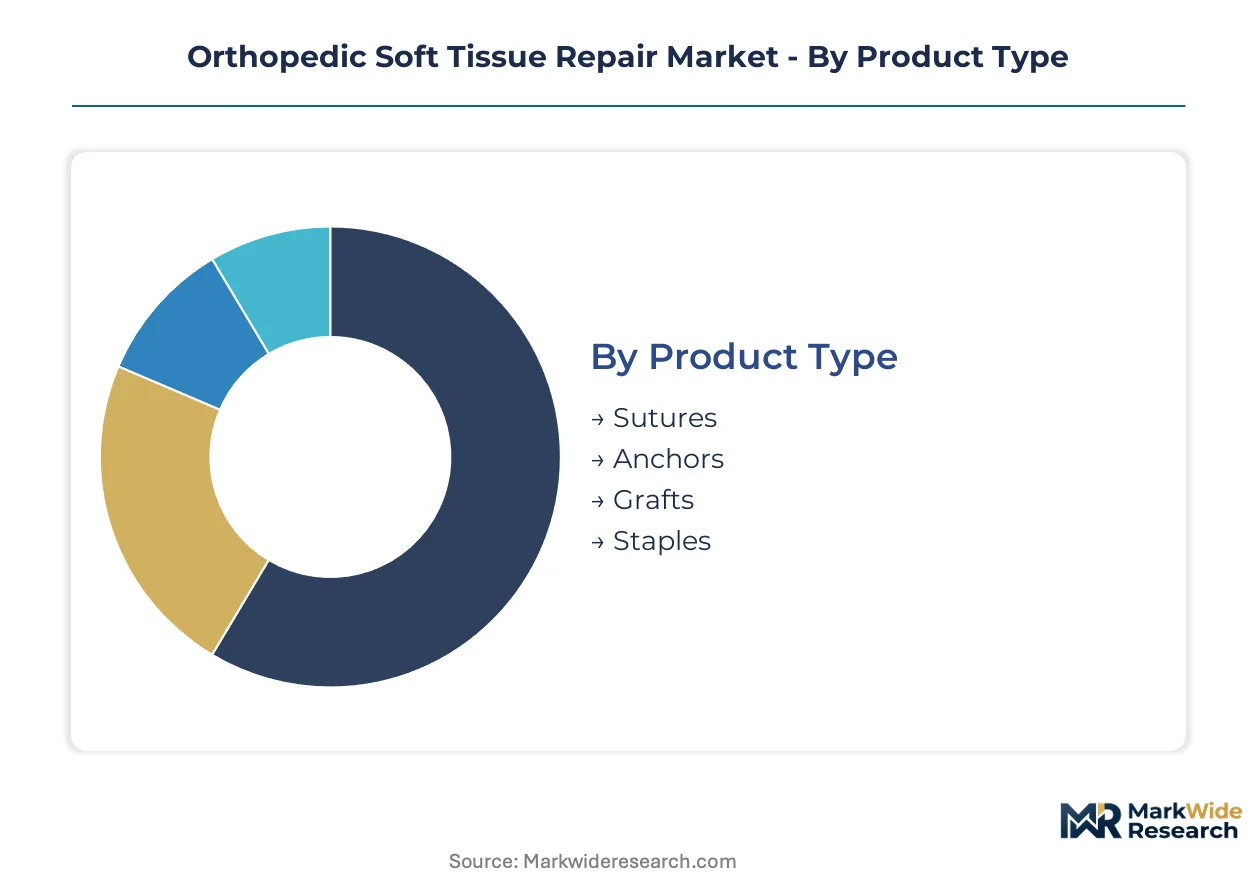
Segmentation in orthopedic soft tissue repair reveals divergent procurement rhythms across product categories. Suture and anchor inventories turn every 90 days in high-volume ambulatory settings, while graft portfolios require 18-month planning cycles tied to tissue bank processing timelines.
Product Type:
Cycle times vary dramatically within this category, with braided polyester sutures turning monthly at busy sports medicine clinics versus allograft grafts requiring extended donor screening and processing windows.
- Sutures:Braided polyester and ultra-high molecular weight polyethylene constructions rated for tensile loads exceeding 50 Newtons dominate rotator cuff and ligament repairs. Demand concentrates in United States ambulatory surgical centers where same-day shoulder procedures drive monthly inventory replenishment cycles.
- Anchors:Bioresorbable polymer and titanium interference devices secure tendon-to-bone fixation across arthroscopic platforms. Sports medicine specialists in Germany and Australia are switching from permanent metal toward polymer-based solutions that integrate with native tissue remodeling timelines.
- Grafts:Demineralized bone matrices and allograft tendons face donor-sourcing constraints regardless of demand signals.
- Staples:Metallic and absorbable configurations serve niche applications in tendon reattachment and capsular closure procedures.
Sutures and anchors anchor the volume base while grafts gain share at the steepest rate despite processing bottlenecks.
Application:
Procedure economics stratify sharply across anatomical targets, with knee reconstruction commanding bundled payment premiums and shoulder repair driving anchor consumption intensity.
- Knee Surgery:Anterior cruciate ligament reconstruction and multi-ligament repair procedures consume allograft tendons and interference screws in high volumes. Academic medical centers in Texas and Florida are scaling same-day arthroscopic anterior cruciate ligament protocols that compress length-of-stay metrics.
- Shoulder Surgery:Rotator cuff repair and labral fixation represent the highest anchor-per-procedure consumption in orthopedic surgery. High-volume shoulder specialists demand knotless tensioning systems for revision cases where tissue quality compromises traditional repair integrity.
- Hip Repair:Labral reconstruction and capsular closure procedures employ specialized curved anchors and suture passing devices.
- Sports Medicine:Youth athletic participation growth in Germany and Australia creates demand for growth-plate-sparing fixation techniques absent from adult-focused portfolios.
Knee procedures generate the highest absolute procedure counts while shoulder applications drive per-case device revenue intensity.
Delivery Mode:
Capital equipment requirements and surgeon training investments create distinct competitive moats between open and arthroscopic platforms.
- Open Surgery:Direct visualization approaches persist for multi-ligament knee reconstructions requiring combined access and graft tensioning. Hybrid technique demand concentrates in trauma centers managing complex athletic injuries.
- Arthroscopic Surgery:Visualization technology advances enable complex procedures through minimally invasive portals previously requiring open access. United States ambulatory surgical centers are displacing hospital-based volume for isolated ligament repairs.
- Minimally Invasive:Percutaneous fixation techniques reduce soft tissue dissection for select tendon reattachment procedures.
- Hybrid:Combined arthroscopic visualization with mini-open graft harvesting addresses complex revision scenarios.
Arthroscopic platforms capture the majority of new procedure growth while hybrid approaches defend share in complex reconstruction segments.
End User:
Purchasing authority and procurement sophistication diverge materially between integrated delivery networks and independent specialty clinics.
- Hospitals:Orthopedic departments within integrated delivery networks negotiate multi-year supply agreements bundling fixation devices with arthroscopy capital equipment. Texas and Florida hospital systems are consolidating vendor relationships around full-procedure kits rather than à la carte procurement.
- Ambulatory Surgical Centers:Same-day procedure economics favor rapid-deployment suture anchors and pre-packaged graft kits. United States site-of-care migration toward outpatient settings is reshaping device procurement priorities.
- Orthopedic Clinics:Sports medicine specialists require inventory flexibility for urgent athletic injury management.
- Rehabilitation Centers:Post-operative bracing and early mobilization protocols create adjacency demand for fixation monitoring.
Hospitals retain negotiating leverage through volume aggregation while ambulatory surgical centers are expanding their share of soft tissue procedure volume fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export bioresorbable polymer anchors to United States ambulatory surgical centers, while Swiss tissue processors supply allograft matrices across European hospital networks. Trade corridors concentrate high-value soft tissue fixation devices between established orthopedic clusters.
United States
Texas and Florida hospital systems drive procurement of full-procedure kits bundling fixation devices with arthroscopy equipment. FDA 510(k) clearance pathways shape product development timelines for biologic-based implants. Greater Boston anchors academic medical center demand for revision rotator cuff repair systems.
Germany
Sports medicine clinics in Bavaria and North Rhine-Westphalia scale same-day arthroscopic procedures for youth athletic injuries. EU MDR Article 10 clinical evaluation requirements extend review queues for biologic mesh submissions to 14 months. The Eindhoven-to-Düsseldorf corridor concentrates knotless anchor manufacturing for European distribution.
Switzerland
Contract manufacturers with ISO 13485 certification offer accelerated market access for device startups lacking in-house regulatory infrastructure. Swissmedic oversight maintains stringent donor-safety protocols for allograft processing. Zurich and Basel anchor bioresorbable scaffold R&D partnerships with German notified bodies.
Australia
Growing youth athletic participation in New South Wales and Victoria creates demand for growth-plate-sparing fixation techniques. TGA conformity assessments align with ASTM F1635 bioresorption testing protocols for polymer-based solutions. Sydney sports medicine specialists adopt arthroscopic repair solutions from United States suppliers.
Japan
PMDA regulatory frameworks govern soft tissue fixation device approvals with emphasis on long-term bioresorption data. Tokyo and Osaka academic centers pioneer hybrid techniques for multi-ligament knee reconstructions. METI industrial policy supports domestic manufacturing of braided polyester sutures rated for high tensile loads.
Orthopedic Soft Tissue Repair Market Key Industry Players
Channel-controlling players compete with product-specialist players across procurement tiers. The vendor base concentrates around manufacturers with validated donor-safety protocols and established quality management systems. Three archetypes dominate: vertically integrated sports medicine portfolios, specialized biologic graft processors, and contract manufacturers with regulatory infrastructure. M&A activity targets tissue bank capabilities, while strategic partnerships secure EU MDR conformity assessment capacity.
Among United States-based incumbents, DePuy Synthes Inc., Stryker Corporation, and Smith & Nephew plc exemplify the channel-controlling archetype through comprehensive fixation portfolios. Arthrex Inc. occupies a specialist position in anchor innovation. CONMED Corporation and Integra LifeSciences Holding Corporation represent mid-tier diversification strategies. LifeNet Health anchors the biologic sourcing tier. Medtronic plc and Zimmer Biomet sit within diversified orthopedic conglomerates with cross-segment procurement leverage.
| Leading Market Players |
|---|
| DePuy Synthes Inc. |
| CONMED Corporation |
| Arthrex Inc. |
| LifeNet Health |
| Integra LifeSciences Holding Corporation |
| Stryker Corporation |
| Smith & Nephew plc |
| Medtronic plc |
| Zimmer Biomet |
| Others |
Cost & Logistics Intelligence
Polymer resin concentration in Germany and Switzerland feeds directly into margin capture by anchor manufacturers with captive compounding facilities, while independent device assemblers face 15-20 point gross margin compression against integrated competitors.
Pricing Analysis
Current-generation bioresorbable anchors command 40-60% premiums over prior-generation titanium equivalents, while next-generation knotless tensioning systems with active compression mechanisms stratify above both tiers. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance tier, ISO 13485 certification status, and after-sales surgeon training bundling. Pricing pressure stems from hospital purchasing committee consolidation around full-procedure kits in Texas and Florida integrated delivery networks. Ambulatory surgical centers exhibit highest price sensitivity due to same-day procedure economics, while academic medical centers prioritize performance metrics over unit cost.
Supply Chain Analysis
Extended payment terms from 60 to 120 days among United States hospital systems have forced contract manufacturers in Ireland and Switzerland to deploy supply-chain finance facilities backed by medical device receivables. Raw material sourcing concentrates on medical-grade polylactic acid from Germany, ultra-high molecular weight polyethylene fiber from the Netherlands, and allograft tissue from United States and Swiss tissue banks. Single-source vulnerability pervades demineralized bone matrix processing due to limited AATB-accredited tissue bank capacity. Distribution runs through orthopedic distributor networks with consignment inventory at high-volume sports medicine clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against non-operative biologic injection therapies that promise rotator cuff healing without mechanical fixation, threatening anchor volume in degenerative indications.
For Market Incumbents: Entrench position through backward integration into polymer compounding and allograft tissue banking to secure input cost control against bioresorbable resin price volatility. Prioritize EU MDR notified body pre-submission pathways to compress 14-month review queues for Class III biologic mesh devices. Defend against biologic injection substitutes by embedding anchors within comprehensive sports medicine portfolios that bundle fixation with rehabilitation protocols. For New Entrants and Emerging Players: Australian pediatric sports medicine represents the most penetrable white-space segment, with growth-plate-sparing fixation demand outpacing domestic supply from adult-focused incumbents. Target point-of-care autologous cell concentration systems for ambulatory surgical centers seeking to reduce tissue bank dependency. Pursue ISO 13485 certification arbitrage through Swiss and Irish contract manufacturers to bypass 18-36 month EU MDR conformity cost barriers that constrain well-capitalized competitors. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated sports medicine specialists with validated donor-safety protocols and established quality management systems rather than pure-play anchor innovators lacking graft portfolios. Long-term viability hinges on bioresorption rate standardization capabilities that resolve ASTM F1635 testing protocol variability. Monitor FDA biologic guidance evolution for tightening quality benchmarks that filter marginal suppliers and concentrate procurement among qualified manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates market entry for bioresorbable polymer anchors against metal predicate devices. |
| EU MDR Notified Body Partnership | Secures 14-month review queue capacity for Class III biologic mesh submissions. |
| Hospital System Supply Agreement | Locks multi-year procurement of full-procedure kits with arthroscopy capital equipment bundling. |
| Allograft Tissue Bank Acquisition | Eliminates donor-sourcing constraints that constrain graft portfolio expansion regardless of demand. |
| Surgeon Training Program Expansion | Builds arthroscopic knot-tying proficiency that conflicts with compressed fellowship schedules. |
Research Approach
The analysis maps suture anchor innovation, allograft graft processing, and bioresorbable scaffold development, each validated through orthopedic surgeons, hospital purchasing committees, biomedical engineers, and GPO contracts managers. Primary interviews combined with secondary validation from FDA 510(k) filings, EU MDR submission databases, hospital procurement contracts, and CMS reimbursement data. Bottom-up procedure volume modeling triangulated against top-down manufacturer revenue segmentation.
Assumption sets held regulatory pathway timelines and site-of-care migration rates fixed while varying sports medicine clinic expansion pace and biologic injection therapy substitution rates across the analysis window. Segmentation dimensions modeled include product type, application anatomy, delivery mode, and end-user procurement sophistication. CAGRs derived from procedure volume elasticity to ambulatory surgical center capacity expansion and anchor-per-procedure consumption intensity in revision rotator cuff repairs. Forecast inputs incorporated EU MDR review queue durations and AATB-accredited tissue bank processing capacity constraints.
Practitioners should monitor FDA biologic guidance tightening, EU MDR notified body capacity constraints, and biologic injection therapy clinical trial readouts for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedics
Anti-Osteoporosis Therapy and Fracture Healing Market
Orthopedics
Global Foot Drop Treatment Market
Orthopedics
Elbow Stiffness Market
Orthopedics
Swollen Knee Treatment Market
Orthopedics
Skeletal Deformation Correction Market
Orthopedics
Canine Orthopedics Market
Orthopedics
Genu Recurvatum Market
Orthopedics
ACL Reconstruction Market
Orthopedics
Hallux Rigidus Market
Orthopedics
US Arthritis Market
Orthopedics
Plantar Fasciitis Market
Orthopedics
Orthopedic Pillow Market
Orthopedics
Europe Bone Metastasis Market
Orthopedics
Podiatry Services Market
Orthopedics
United States Orthopedic Braces and Support Market
Orthopedics
Orthopedics Market