
 United States Orthopedic Braces and Support Market | 2026-2036
United States Orthopedic Braces and Support Market Size, Share, and Industry Trends Forecast 2026-2036
United States Orthopedic Braces and Support Market Intelligence
Market Context
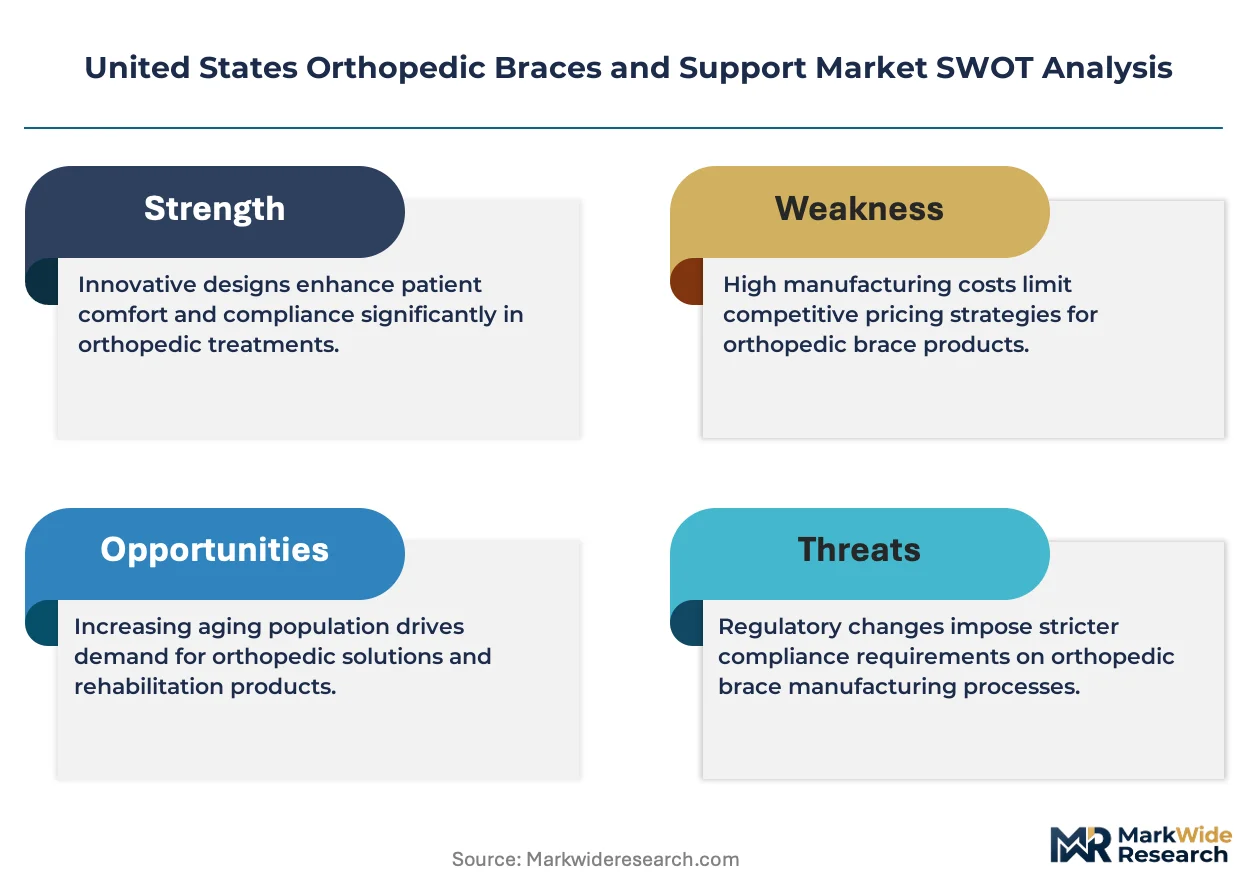
Buyer concentration among large hospital networks and orthopedic surgery centers is realigning procurement leverage toward group purchasing organizations. DJO, LLC (Enovis) leverages its rehabilitation technology portfolio to sustain contracts with major health systems across the Southeast. Breg, Inc. anchors its position through specialized sports medicine distribution, while Össur competes on advanced prosthetic and bracing integration.
Technical Definition and Segment Structure
Orthopedic braces and support devices are mechanical apparatuses constructed from neoprene, thermoplastic, or composite materials that restrict, guide, or assist musculoskeletal movement through calibrated compression and joint stabilization. These devices serve primary commercial purposes in post-injury immobilization, chronic condition management, and surgical rehabilitation across clinical and consumer channels. Knee braces and ankle supports occupy the largest revenue pools due to high incidence rates in sports injuries and osteoarthritis, while back supports gain traction among occupational therapists addressing workplace musculoskeletal disorders. Preventive care applications represent the fastest-expanding demand segment as employers and athletic programs prioritize injury avoidance over reactive treatment.
Regulatory Framework and Outlook
FDA 510(k) premarket notification requirements govern Class II brace classifications, with quality system regulation enforcement shaping manufacturing compliance costs for domestic producers. NHTSA and OSHA guidelines intersect with occupational brace standards, particularly for workplace back support mandates in logistics and construction sectors. Stakeholders must monitor evolving CMS reimbursement codes for durable medical equipment, as coverage determinations directly influence patient out-of-pocket decisions and channel economics.
Market Dynamics
Hospital outpatient departments are consolidating brace procurement under group purchasing organizations, compressing margins for mid-tier manufacturers while rewarding suppliers with comprehensive rehabilitation portfolios. This buyer concentration is forcing product differentiation around clinical outcomes data rather than price alone.
Growth Catalysts
- CMS Reimbursement Expansion:Durable medical equipment coverage determinations for post-surgical knee and ankle braces are widening patient access across Medicare Advantage plans in Texas and Florida.
- Neoprene-Composite Hybrid Materials:Advanced thermoplastic blends with moisture-wicking properties are extending wear-time compliance in occupational therapy applications.
- Sports Medicine Infrastructure:Collegiate athletic programs in the Southeast are mandating preventive bracing protocols, creating institutional demand independent of injury incidence.
Market Restraints
- Petroleum-Derived Input Volatility:Neoprene and thermoplastic resin costs fluctuate with crude oil markets, squeezing gross margins for domestic molders without long-term supply contracts.
- FDA 510(k) Timeline Friction:Premarket notification requirements for Class II brace modifications average 90-150 days, delaying feature iterations behind European CE-marked competitors.
- Generic Rigid Splint Substitution:Low-cost aluminum and polyethylene alternatives from offshore manufacturers capture price-sensitive segments in cash-pay retail channels.
Strategic Opportunities
- OSHA Workplace Mandate Tailwinds:Updated ergonomic standards for logistics and construction sectors are creating compliance-driven demand for lumbar support systems with documented load-reduction certification.
- Remote Patient Monitoring Integration:Sensor-embedded braces transmitting adherence data to orthopedic surgeons are opening reimbursement pathways through telehealth parity laws.
- Direct-to-Employer Contracting:Self-insured corporations in manufacturing-heavy Midwestern states are procuring preventive bracing programs as workers' compensation cost containment measures.
Industry Challenges
- Biomechanical Engineering Talent Scarcity:The specialized skill set combining orthopedics and wearable sensor design commands premium compensation, constraining R&D expansion for mid-market firms.
- Legacy ERP Integration Complexity:Hospital procurement systems require EDI compliance and UDI serialization that smaller brace manufacturers lack capital to implement without third-party logistics partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Orthopedic Braces and Support Market |
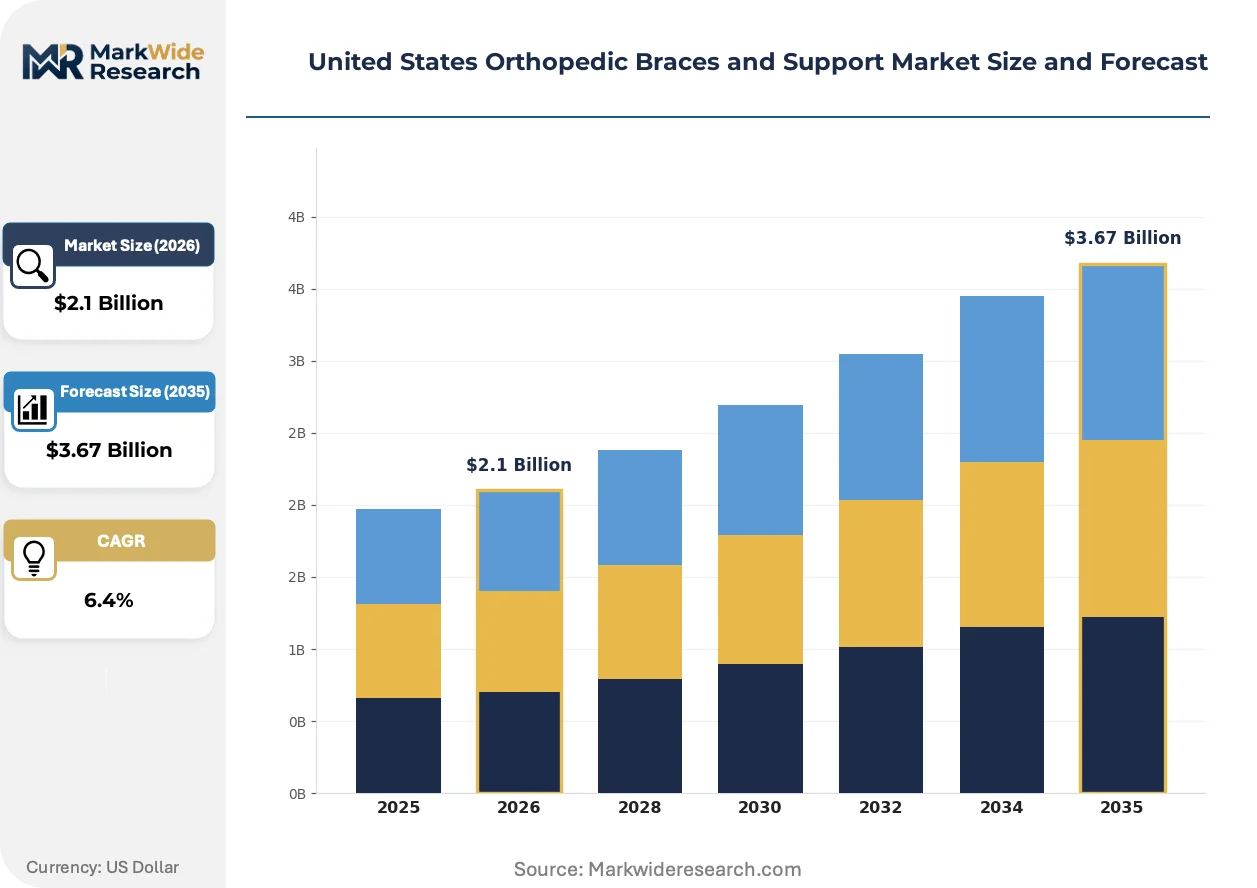
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Knee Braces, Ankle Supports, Back Supports, Arm Slings Application: Sports Injuries, Arthritis, Post-Surgery Recovery, Preventive Care Material: Neoprene, Thermoplastic, Fabric, Composites End User: Athletes, Elderly, Occupational Therapists, Rehabilitation Centers |
| Companies Covered | Breg, Inc., Össur, DJO, LLC (Enovis), DeRoyal Industries, Inc., Bauerfeind, Ottobock, 3M Company, Zimmer Biomet, Frank Stubbs Company Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Orthopedic Braces and Support Market Strategic Shifts & Innovations
Additive manufacturing of patient-specific brace components is collapsing production lead times from weeks to days. This shift is compressing the traditional mold-and-inventory model while enabling anatomical customization previously reserved for prosthetic applications.
3D-printed lattice structures from medical-grade nylon powders are decentralizing production geography. Regional fabrication hubs near major orthopedic centers in Denver and Phoenix are eliminating cross-country shipping for custom-molded ankle-foot orthoses. Hospital systems with in-house print capabilities are bypassing traditional distributor markups entirely.
FDA's evolving software-as-a-medical-device guidance is capturing sensor-enabled braces under premarket submission requirements. Manufacturers incorporating step-counting or gait-analysis algorithms must now validate clinical accuracy through predicate comparisons. Knee brace segments with integrated activity tracking face the steepest compliance burden as CMS weighs coverage for data-generating devices.
Employer-sponsored onsite clinics are displacing traditional durable medical equipment suppliers for workplace injury bracing. Manufacturing facilities in Ohio and Michigan are contracting directly with orthopedic product vendors for just-in-time inventory at plant health centers. This channel bypass eliminates retail pharmacy and home medical equipment intermediary margins while accelerating return-to-work protocols.
United States Orthopedic Braces and Support Market Segmentation
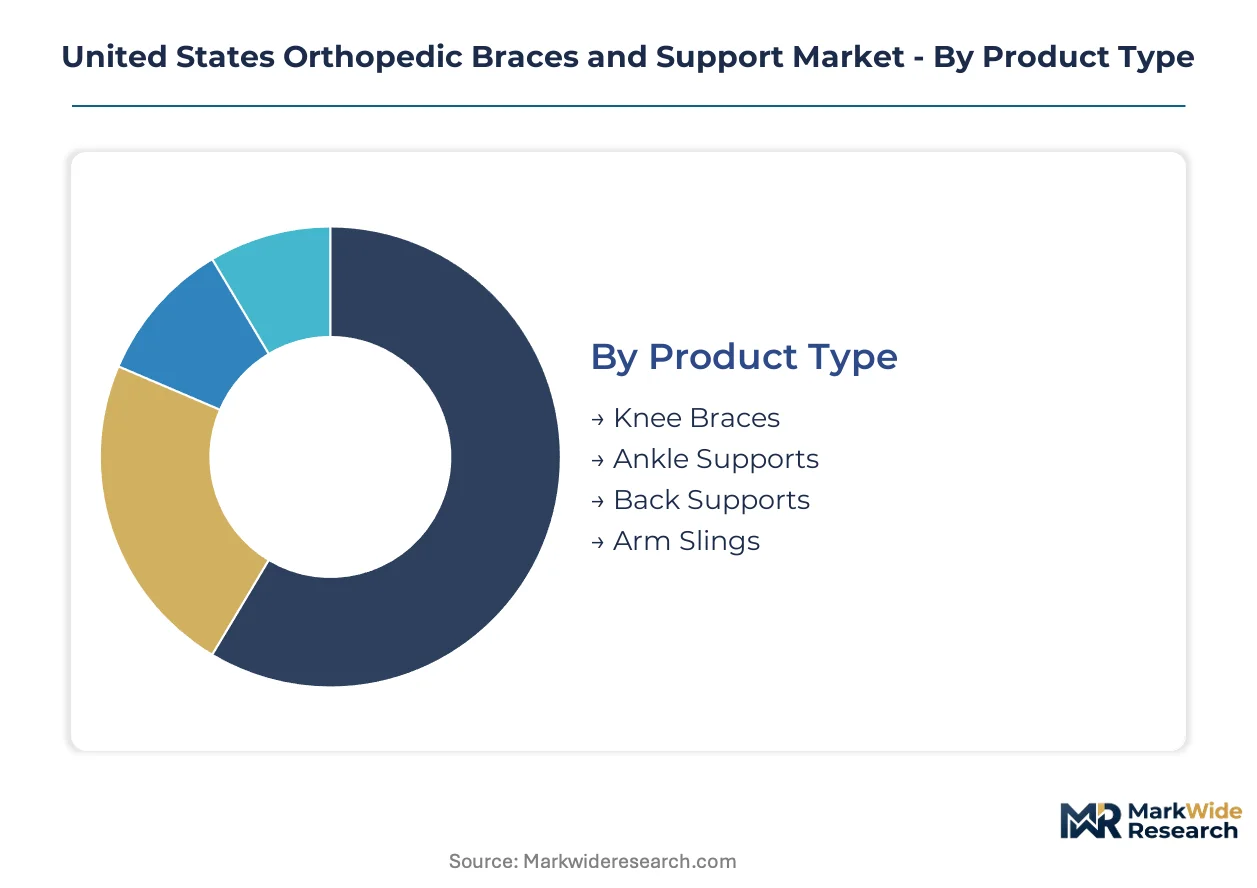
Orthopedic brace manufacturers align production capacity against distinct demand profiles. Product specifications, clinical use cases, material science, and end-user workflows each create separate procurement channels with unique margin structures and compliance requirements.
Product Type:
Supply concentration clusters around high-volume joint stabilization devices where Texas and Florida hospital networks drive contract consolidation.
- Knee Braces:Hinged and compression designs constructed from aluminum alloy frames with neoprene sleeves. Demand concentrates in post-surgical recovery protocols across Florida Medicare Advantage networks, where CMS reimbursement determinations directly influence patient access decisions.
- Ankle Supports:Lace-up and stirrup configurations using thermoplastic shells with adjustable strapping systems. Texas sports medicine infrastructure and collegiate athletic programs in the Southeast generate institutional procurement volumes independent of acute injury incidence.
- Back Supports:Rigid and semi-rigid lumbar belts with pulley-adjusted compression mechanisms. OSHA workplace mandates in logistics sectors drive compliance-based purchasing.
- Arm Slings:Envelope and shoulder immobilization designs using breathable mesh fabrics with adjustable neck straps. Emergency department and urgent care channels dominate volume.
Today's leader: Knee Braces. Tomorrow's challenger: Back Supports.
Application:
Cost tier differentiation separates premium clinical-grade devices from economy retail alternatives, with reimbursement eligibility determining channel placement.
- Sports Injuries:Acute ligament and tendon trauma requiring immediate stabilization and graduated rehabilitation protocols. Collegiate athletic programs in the Southeast mandate preventive bracing, creating institutional demand streams.
- Arthritis:Chronic osteoarthritis and rheumatoid conditions requiring daily wear compliance through moisture-wicking material innovations. Florida's aging demographics sustain consistent utilization patterns.
- Post-Surgery Recovery:ACL reconstruction, rotator cuff repair, and spinal fusion protocols requiring physician-prescribed immobilization. Hospital outpatient departments in Texas consolidate procurement under group purchasing organization contracts.
- Preventive Care:Prophylactic joint stabilization for high-risk occupational and athletic populations. Self-insured Midwestern manufacturers deploy direct-to-employer contracting for workers' compensation cost containment.
Post-Surgery Recovery commands current procurement volumes. Preventive Care shows the steepest expansion trajectory as employers prioritize injury avoidance.
Material:
Volume concentration favors petroleum-derived inputs where long-term supply contracts protect domestic molders from crude oil price volatility.
- Neoprene:Synthetic rubber polymer providing thermal retention and compression with moisture-wicking liner compatibility. Texas and Florida humid climates drive demand for extended wear-time comfort in occupational therapy applications.
- Thermoplastic:Heat-moldable copolymer materials enabling patient-specific fit adjustment at point-of-care. FDA 510(k) clearance pathways for Class II device modifications average 90-150 days, delaying feature iterations.
- Fabric:Elastic and woven textile blends offering breathability for low-intensity stabilization needs. Retail pharmacy channels favor these lower-cost alternatives.
- Composites:Carbon fiber and fiberglass hybrid structures delivering strength-to-weight ratios for high-performance athletic and clinical applications. Additive manufacturing of lattice structures is collapsing production lead times from weeks to days.
Neoprene retains manufacturing scale advantages. Composites are gaining share fastest through 3D-printed customization capabilities.
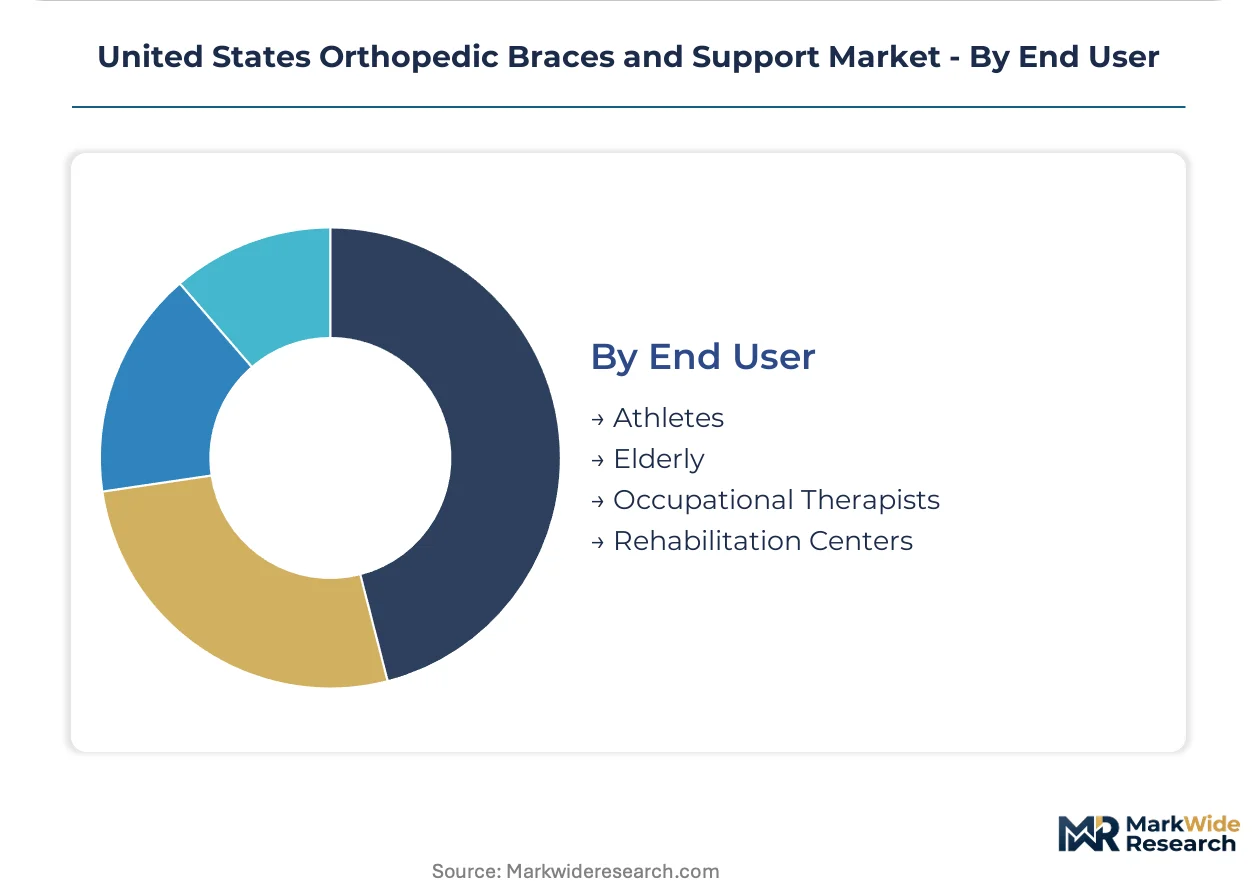
End User:
Customer type fragmentation separates institutional procurement systems from direct-to-consumer channels, with EDI compliance and UDI serialization requirements filtering supplier participation.
- Athletes:Amateur through professional competitors requiring injury prevention and performance protection protocols. Southeastern collegiate programs mandate preventive bracing independent of injury history.
- Elderly:Medicare-eligible populations with osteoarthritis and post-surgical rehabilitation needs. CMS coverage determinations for durable medical equipment directly influence out-of-pocket decisions.
- Occupational Therapists:Licensed clinicians prescribing workplace and home-based musculoskeletal interventions. OSHA ergonomic standards create compliance-driven demand for documented load-reduction certification.
- Rehabilitation Centers:Post-acute facilities managing coordinated recovery protocols across orthopedic surgery networks. Group purchasing organization consolidation compresses margins for mid-tier manufacturers.
Rehabilitation Centers anchor institutional procurement volume. Occupational Therapists represent the fastest-expanding prescription channel through workplace mandate expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Orthopedic brace procurement concentrates in states with dense orthopedic surgeon networks and aging Medicare populations. Hospital system consolidation and sports medicine infrastructure create distinct demand clusters across the Southeast, Southwest, and Midwest.
Texas
Texas Medical Center in Houston anchors one of the nation's largest orthopedic surgery volumes, driving institutional procurement through group purchasing organization contracts. FDA 510(k) clearance pathways for Class II devices shape product development timelines for suppliers serving Dallas-Fort Worth hospital networks. Austin and San Antonio sports medicine clinics expand preventive bracing protocols for collegiate and high school athletic programs.
Florida
Medicare Advantage enrollment expansion in Miami-Dade and Broward counties sustains durable medical equipment demand for post-surgical knee and ankle braces. CMS reimbursement determinations directly influence patient access decisions across the state's retirement corridor. Tampa and Orlando orthopedic surgery centers consolidate brace procurement under health system contracts, compressing margins for mid-tier manufacturers.
California
Silicon Valley sensor-embedded brace developers face FDA software-as-a-medical-device guidance compliance burdens for gait-analysis algorithms. Los Angeles and San Diego sports medicine infrastructure serves professional and collegiate athletic programs with preventive bracing mandates. Northern California hospital networks pioneer remote patient monitoring integration for post-surgical rehabilitation protocols.
Ohio
Self-insured manufacturing corporations in Cleveland and Cincinnati deploy direct-to-employer contracting for workplace injury bracing as workers' compensation cost containment. OSHA ergonomic standards drive compliance-based purchasing for lumbar support systems in logistics and automotive assembly facilities. Columbus orthopedic surgery centers consolidate procurement under statewide health system contracts.
Michigan
Detroit-area automotive manufacturers sponsor onsite clinics with just-in-time bracing inventory at plant health centers, bypassing traditional distributor channels. Grand Rapids and Ann Arbor rehabilitation centers coordinate post-acute recovery protocols across orthopedic surgery networks. Michigan Medicine's procurement leverage shapes supplier contract terms for knee and ankle stabilization devices.
United States Orthopedic Braces and Support Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the orthopedic brace market. Hospital network consolidation favors suppliers with comprehensive rehabilitation portfolios and EDI-compliant procurement systems. Three archetypes dominate: diversified medical device conglomerates with orthopedic divisions, focused bracing specialists with sports medicine distribution, and prosthetic-orthotic integrators with advanced materials capabilities. M&A activity concentrates rehabilitation technology portfolios, while geographic expansion targets direct-to-employer contracting channels in manufacturing-heavy states.
Among diversified medical device conglomerates, 3M Company and Zimmer Biomet occupy positions spanning multiple orthopedic product categories. DJO, LLC (Enovis) exemplifies the rehabilitation technology specialist archetype with health system contract concentration. Breg, Inc. and Össur represent focused bracing and prosthetic-orthotic integration specialists competing on sports medicine distribution and advanced materials respectively. DeRoyal Industries, Inc. anchors the mid-tier manufacturer segment serving regional hospital networks.
| Leading Market Players |
|---|
| Breg, Inc. |
| Össur |
| DJO, LLC (Enovis) |
| DeRoyal Industries, Inc. |
| Bauerfeind |
| Ottobock |
| 3M Company |
| Zimmer Biomet |
| Frank Stubbs Company Inc. |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up rehabilitation specialists dominate supply consolidation, compressing procurement leverage for mid-tier molders while anchoring pricing discipline through long-term GPO contracts with Texas and Florida hospital networks.
Pricing Analysis
Bundled service contracts with rehabilitation centers command premium positioning, while unbraced cash-pay retail channels compete on unit economics. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared Class II devices with clinical outcomes data from generic aluminum splints and offshore thermoplastic alternatives. Pricing pressure stems from petroleum-derived neoprene cost volatility and buyer consolidation under group purchasing organizations. Self-insured employers in manufacturing-heavy Midwestern states exhibit lowest price sensitivity due to workers' compensation cost containment priorities, while retail pharmacy channels face acute margin compression from generic substitution.
Supply Chain Analysis
Reverse-logistics flows for custom-molded ankle-foot orthoses remain underdeveloped, with most 3D-printed lattice structures scrapped rather than remanufactured due to patient-specific anatomical constraints. Manufacturing concentrates in China for neoprene raw material, Mexico for thermoplastic molding operations, and domestic regional hubs in Denver and Phoenix for point-of-care additive production. Supply chains draw from petroleum-derived resin feedstocks, medical-grade nylon powders, and aluminum alloy stock. Single-source vulnerability runs through offshore neoprene suppliers exposed to crude oil price swings. Distribution runs through group purchasing organization contracts with health systems, bypassing traditional durable medical equipment intermediaries in direct-to-employer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as post-surgical recovery protocols shift toward sensor-embedded braces with remote patient monitoring integration, favoring suppliers with FDA software-as-a-medical-device validation capabilities.
For Market Incumbents: Lock in GPO contract renewals with Texas and Florida hospital networks before CMS reimbursement determinations widen coverage for data-generating devices. Deepen backward integration into medical-grade nylon powder supply for additive manufacturing hubs, defending against 3D-printing specialists capturing custom-molded orthoses volume. Prioritize EDI compliance and UDI serialization investments to filter mid-tier competitors from institutional procurement channels. For New Entrants and Emerging Players: OSHA ergonomic standards in Ohio and Michigan open a window for lumbar support systems with documented load-reduction certification, bypassing entrenched hospital supply relationships through direct-to-employer contracting. Target self-insured manufacturing corporations with preventive bracing programs as the most penetrable white-space segment. Pursue telehealth parity law reimbursement pathways for sensor-embedded knee braces as the primary go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier manufacturers lacking EDI-compliant procurement systems but holding FDA 510(k) cleared portfolios. Long-term viability hinges on rehabilitation technology consolidation and software-enabled device differentiation over commodity molding capacity. Monitor CMS coverage determinations for durable medical equipment with data-generating capabilities as the critical inflection signal for premium-multiple expansion.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-a-Medical-Device Submission | Validates clinical accuracy of gait-analysis algorithms in sensor-embedded knee braces for CMS coverage eligibility. |
| Hospital System Partnership | Secures group purchasing organization contracts with Texas Medical Center and Florida retirement corridor networks. |
| Reimbursement Strategy | Aligns durable medical equipment coding with Medicare Advantage expansion in post-surgical recovery protocols. |
| Backward Integration into Nylon Powder Supply | Captures captive supply of medical-grade additive manufacturing feedstock for regional 3D-printing hubs. |
| Direct-to-Employer Contracting | Bypasses distributor markups through workplace injury bracing programs at Ohio and Michigan manufacturing facilities. |
Research Approach
Bottom-up orthopedic surgery volume modeling reconciled against top-down neoprene and thermoplastic resin consumption tracking forms the analytical core. Primary interviews with orthopedic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers combined with secondary validation against FDA 510(k) filings, CMS Medicare data, hospital procurement databases, and OSHA workplace safety records. Triangulation across demand-side utilization patterns and supply-side material flows ensures statistical integrity.
Input-output matrices map patient procedure volumes through brace utilization rates, material intensity per device, and channel margin structures across the projection horizon. Segmentation dimensions include product type, application, material composition, and end-user workflow. CAGRs derive from procedure growth trajectories, reimbursement expansion patterns, and material cost pass-through assumptions. Forecast inputs incorporate collegiate athletic program preventive bracing mandates and additive manufacturing adoption curves in regional orthopedic centers.
Revisions become necessary when FDA software-as-a-medical-device guidance tightens premarket requirements for sensor-enabled braces, or when petroleum price volatility exceeds historical bands. Practitioners should monitor CMS coverage determinations for data-generating devices and OSHA ergonomic standard enforcement actions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedics
Bilateral Osteoarthritis Treatment Market
Orthopedics
Osteoporosis Treatment Market
Orthopedics
Genu Recurvatum Market
Orthopedics
Cruciate Ligament Repair Procedures Market
Orthopedics
Osteonecrosis Treatment Market
Orthopedics
Swollen Knee Treatment Market
Orthopedics
Global Foot Drop Treatment Market
Orthopedics
ACL Reconstruction Market
Orthopedics
Kyphosis Market
Orthopedics
Knee Hyaluronic Acid Injections Market
Orthopedics
Orthopedic Repair Market
Orthopedics
Osteopenia Treatment Market
Orthopedics
Elbow Stiffness Market
Orthopedics
Skeletal Deformation Correction Market
Orthopedics
Orthopedics Market
Orthopedics
Orthopedic Pillow Market