
 Germany Minimally Invasive Surgery Devices Market | 2026-2036
Germany Minimally Invasive Surgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Minimally Invasive Surgery Devices Market Foresight
German precision instrument manufacturers is recalibrating production capacity toward robotic surgical platforms and advanced visualization systems. Siemens Healthineers leverages its domestic engineering base to dominate imaging-integrated surgical workflows. Medtronic anchors its European minimally invasive portfolio through specialized catheter and energy device operations from regional facilities. Intuitive Surgical competes by sustaining technical leadership in robotic-assisted procedure adoption across German teaching hospitals.
Minimally invasive surgery devices encompass instruments, visualization systems, electrosurgical tools, and robotic platforms engineered for tissue manipulation through incisions under 15 millimeters, utilizing advanced imaging and computer-assisted control to reduce patient trauma and recovery time. Robotic surgical systems command premium positioning due to capital intensity and proprietary ecosystem lock-in, while laparoscopic instruments represent the mature volume base with established reimbursement pathways. Electrosurgical units and surgical staplers capture concentrated margin pools where disposable consumables generate recurring revenue streams, and 3D visualization technology is gaining structural share as hospitals prioritize depth perception in complex procedures.
MDR conformity assessment through notified bodies and BfArM post-market surveillance shape device approval timelines and clinical evidence requirements for manufacturers seeking German market access. ISO 13485 quality management standards and DIN EN technical specifications further define manufacturing protocols that differentiate compliant suppliers from restricted entrants. Stakeholders must monitor how evolving MDR implementation timelines and health technology assessment rulings by the G-BA reshape procurement criteria and hospital capital allocation priorities.
Market Dynamics
The German minimally invasive surgery devices market is being fundamentally restructured by MDR implementation timelines, which are compressing product certification cycles and forcing manufacturers to accelerate clinical evidence generation for legacy device portfolios.
Growth Catalysts
- MDR transition deadlines:BfArM vigilance requirements and notified body capacity constraints are accelerating consolidation among compliant manufacturers, privileging established players with robust quality management systems.
- University hospital clusters:Bavaria and Baden-Württemberg teaching hospitals are driving procurement volume for robotic platforms and advanced visualization systems through consolidated tender processes.
- 3D visualization technology:Depth perception capabilities in complex laparoscopic procedures are expanding surgeon adoption curves and displacing conventional 2D systems in high-acuity settings.
Market Restraints
- Notified body bottleneck:MDR conformity assessment capacity constraints in Germany are extending device approval timelines by 12-18 months for mid-tier manufacturers lacking prior CE mark transition experience.
- Capital intensity concentration:Robotic surgical platforms require 2-3 million euro installations, restricting penetration to university hospitals and large municipal centers while excluding regional clinics.
- Disposable cost inflation:Electrosurgical consumables and single-use stapler cartridges are experiencing input cost pressure from specialized polymer supply chains concentrated in Central European chemical manufacturing zones.
Strategic Opportunities
- Ambulatory surgical center expansion:Outpatient procedure volume in North Rhine-Westphalia and Lower Saxony is creating demand for compact laparoscopic towers and mobile visualization systems.
- AI-integrated imaging convergence:Real-time tissue recognition algorithms combined with 4K fluorescence imaging are enabling new revenue streams in oncologic resection guidance.
- G-BA innovation funding:Federal Joint Committee health technology assessment pathways for novel surgical methods are creating reimbursement tailwinds for evidence-generating device trials.
Industry Challenges
- Robotic surgery training pipelines:Certified proctor availability and simulator access are constraining surgeon credentialing velocity for da Vinci and competing platforms.
- Legacy instrument interoperability:Hospital information system integration with proprietary robotic ecosystems is generating IT infrastructure reconfiguration costs and workflow friction.
- Post-market surveillance compliance:BfArM adverse event reporting and periodic safety update report requirements are absorbing regulatory affairs bandwidth at smaller device manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Minimally Invasive Surgery Devices Market |
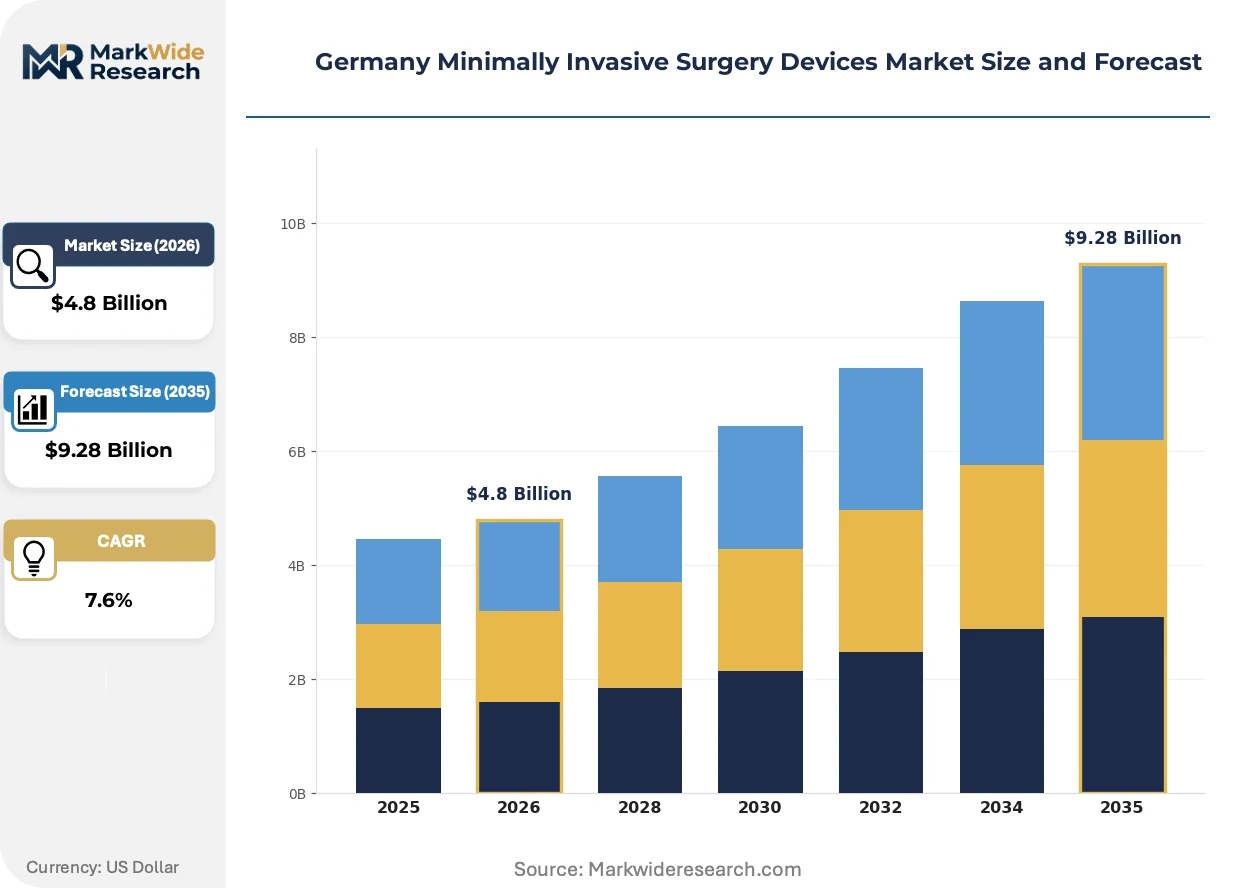
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laparoscopic Instruments, Endoscopic Devices, Robotic Surgical Systems, Surgical Cameras, Electrosurgical Units, Surgical Staplers Technology: 3D Visualization, Image-Guided Surgery, Wireless Connectivity, Artificial Intelligence, Sensor Integration, Augmented Reality Application: Gynecological Procedures, Urological Procedures, Orthopedic Interventions, Thoracic Surgery, Neurosurgical Operations, Colorectal Surgery End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions, Academic Medical Centers, Outpatient Facilities |
| Companies Covered | Siemens Healthineers, Intuitive Surgical, Medtronic, Stryker Corporation, Koninklijke Philips, GE Healthcare, Smith & Nephew, Abbott Laboratories, Olympus Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Minimally Invasive Surgery Devices Market Shifts & Advancements
Digital surgical workflows are displacing conventional operating room configurations across German hospital networks, with three interconnected developments reshaping capital allocation and technology adoption patterns.
Single-port robotic platforms are expanding into general surgery and gynecology departments previously dependent on multi-port laparoscopy. Municipal hospitals in Hesse and Rhineland-Palatinate are piloting these systems for cholecystectomy and hysterectomy procedures to differentiate outpatient service lines. The technology is expanding into mid-tier acute care settings by reducing facility space requirements and enabling same-day discharge protocols.
MDR Article 117 and harmonized standard updates are mandating enhanced clinical evaluation reports for legacy laparoscopic instruments. German notified bodies are applying stricter scrutiny to equivalence claims, forcing manufacturers to generate new PMCF study data. Class IIa reusable instruments face the steepest compliance burden, with several product lines exiting the market rather than absorbing retrospective clinical trial costs.
Hospital purchasing consortia in Berlin-Brandenburg and Hamburg are consolidating tender processes for electrosurgical generators and energy devices. Single-source agreements with 3-5 year consumable lock-in terms are displacing fragmented multi-vendor procurement. This concentration is most visible among municipal hospital associations seeking volume discounts against tightening DRG reimbursement margins.
Germany Minimally Invasive Surgery Devices Market Segmentation
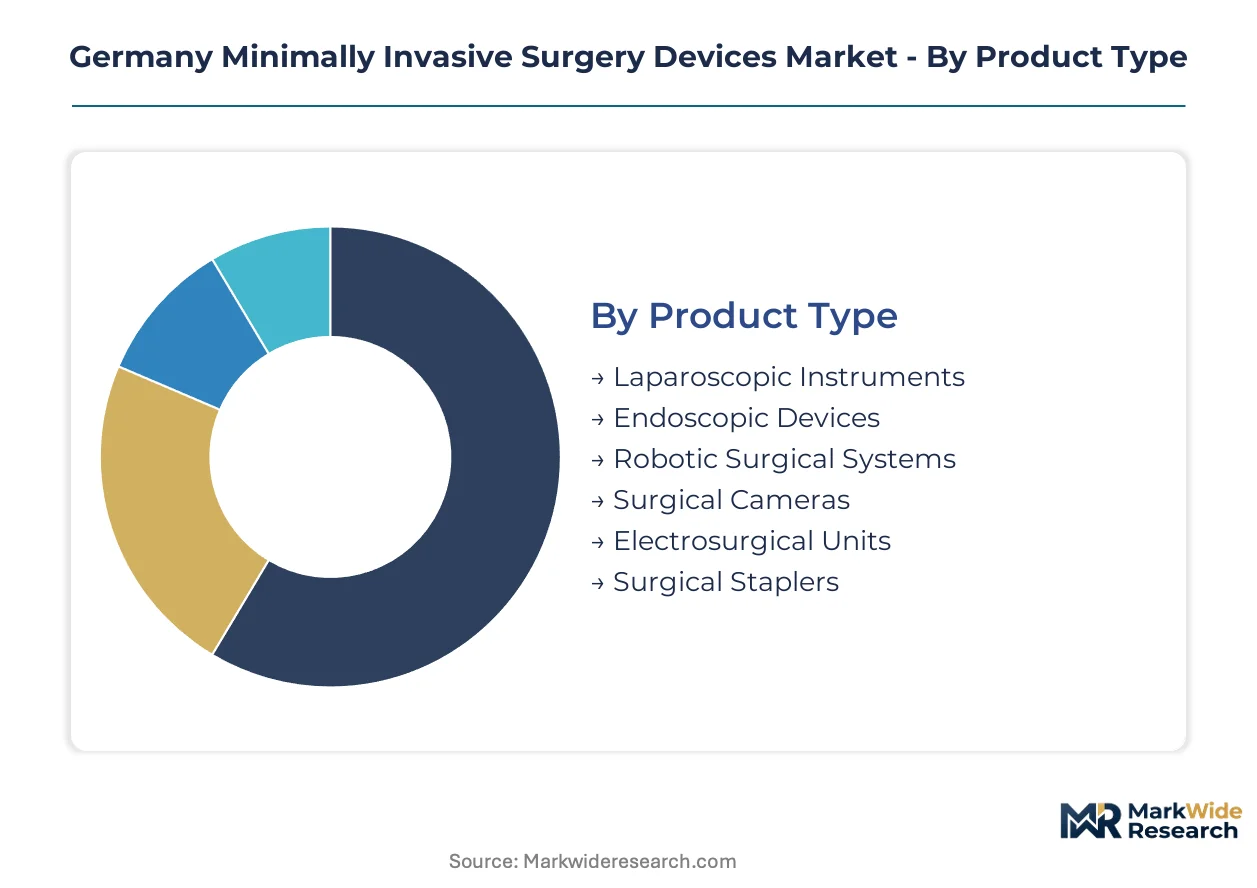
Device segmentation in Germany reflects divergent capital allocation strategies across hospital tiers, with university medical centers prioritizing robotic platforms while municipal hospitals optimize laparoscopic throughput. Procurement patterns concentrate in Bavaria and Baden-Württemberg, where teaching hospital clusters drive premium technology adoption.
Product Type:
Customization intensity spans from commoditized reusable instruments to proprietary robotic ecosystems that lock hospitals into single-vendor consumable streams.
- Robotic Surgical Systems:Multi-arm platforms with haptic feedback and tremor filtration enable precision suturing in confined anatomical spaces. Bavarian university hospitals anchor procurement volume through consolidated tenders for da Vinci and competing systems, constrained by 2-3 million euro capital thresholds and proctor availability bottlenecks.
- Laparoscopic Instruments:Reusable graspers, scissors, and dissectors with modular shaft lengths constitute the procedural volume foundation across German general surgery departments. Municipal hospitals in North Rhine-Westphalia prioritize instrument durability and sterilization cycle tolerance over feature expansion.
- Endoscopic Devices:Flexible scopes with narrow-band imaging for gastrointestinal and respiratory diagnostics.
- Surgical Cameras:4K and fluorescence-capable imaging heads integrated with tower systems.
- Electrosurgical Units:Radiofrequency generators with vessel sealing algorithms for hemostasis.
- Surgical Staplers:Disposable cartridge systems for anastomosis in colorectal and thoracic procedures.
Leading the category by volume: Laparoscopic Instruments. Growing fastest: Robotic Surgical Systems.
Technology:
Adoption velocity correlates with reimbursement complexity, where proven modalities penetrate faster than experimental interfaces requiring G-BA assessment.
- 3D Visualization:Stereoscopic laparoscopes with depth perception restoration reduce operative time in complex resections. Baden-Württemberg teaching hospitals displace 2D systems in high-acuity settings, driven by surgeon demand for spatial precision in oncologic procedures.
- Artificial Intelligence:Real-time tissue classification algorithms overlay malignancy probability maps during resection. Berlin-Brandenburg consortia pilot AI-integrated platforms through innovation funding pathways, contingent on prospective clinical evidence generation.
- Image-Guided Surgery:Preoperative CT/MRI fusion with intraoperative navigation.
- Wireless Connectivity:Bluetooth-enabled instrument tracking and OR data transmission.
- Sensor Integration:Force-sensing graspers with haptic feedback modulation.
- Augmented Reality:Heads-up displays projecting anatomical overlays.
Volume concentration rests with 3D Visualization. Steepest expansion trajectory belongs to Artificial Intelligence.
Application:
Procedure complexity dictates device specification, with multi-quadrant abdominal operations requiring broader instrument portfolios than single-cavity interventions.
- Gynecological Procedures:Hysterectomy and myomectomy drive demand for uterine manipulators and morcellation containment systems. Hesse municipal hospitals adopt single-port robotic platforms for same-day discharge protocols in benign gynecology.
- Colorectal Surgery:Low anterior resection and total mesorectal excision require advanced stapling and fluorescence perfusion assessment. Rhineland-Palatinate centers prioritize anastomotic leak reduction through indocyanine green imaging integration.
- Urological Procedures:Prostatectomy and partial nephrectomy with nerve-sparing dissection.
- Orthopedic Interventions:Arthroscopic joint repair and spinal decompression.
- Thoracic Surgery:VATS lobectomy and mediastinal mass resection.
- Neurosurgical Operations:Endoscopic skull base and ventricular approaches.
Gynecological Procedures generate highest installed base utilization. Colorectal Surgery exhibits the fastest technology refresh cycles.
End User:
Capital intensity separates institutional tiers, with reimbursement margins determining whether facilities absorb robotic depreciation or concentrate on laparoscopic efficiency.
- Hospitals:Maximum care institutions with 24/7 emergency surgical capacity anchor device procurement through DRG-funded capital budgets. University hospitals in Hamburg and Berlin-Brandenburg dominate robotic platform density.
- Ambulatory Surgical Centers:Outpatient-focused facilities in Lower Saxony expand laparoscopic cholecystectomy and hernia repair volume through streamlined preoperative pathways.
- Specialty Clinics:Focused orthopedic or ophthalmic surgical centers.
- Research Institutions:Preclinical and translational surgery laboratories.
- Academic Medical Centers:Hybrid clinical-research operations with training mandates.
- Outpatient Facilities:Office-based endoscopy and minor procedure suites.
Hospitals command the largest capital deployment. Ambulatory Surgical Centers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision polymer feedstock from the Ruhr industrial corridor anchors surgical instrument manufacturing across German sub-regions, with specialized chemical intermediates flowing into device production clusters.
Bavaria
University hospital procurement consortia in Munich and Erlangen drive robotic platform adoption through consolidated tenders. BfArM post-market surveillance requirements compress certification timelines for manufacturers supplying these institutions. The Munich-Erlangen medical technology corridor concentrates imaging-integrated surgical workflow development.
Baden-Württemberg
Teaching hospitals in Stuttgart and Heidelberg prioritize 3D visualization systems for complex oncologic resections. MDR Article 117 harmonized standards mandate enhanced clinical evaluation reports for legacy instruments sold into this cluster. The Stuttgart-Tübingen surgical innovation zone anchors fluorescence imaging platform pilots.
North Rhine-Westphalia
Ambulatory surgical centers in Cologne and Düsseldorf expand laparoscopic cholecystectomy volume through streamlined preoperative pathways. DIN EN technical specifications govern sterilization cycle tolerance for reusable instruments deployed across these outpatient networks. The Cologne-Düsseldorf corridor concentrates compact laparoscopic tower demand.
Berlin-Brandenburg
Hospital purchasing consortia consolidate tender processes for electrosurgical generators across municipal associations. G-BA health technology assessment pathways shape reimbursement criteria for novel surgical methods trialed in this region. The Berlin metropolitan area anchors AI-integrated imaging convergence pilots through innovation funding.
Lower Saxony
Outpatient facilities in Hanover and Brunswick deploy mobile visualization systems for hernia repair expansion. ISO 13485 quality management standards differentiate compliant suppliers serving these ambulatory networks. The Hanover-Brunswick corridor concentrates demand for cost-optimized laparoscopic instrument portfolios.
Germany Minimally Invasive Surgery Devices Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue AI-augmented imaging and single-port robotic platforms. The vendor base concentrates around three strategic archetypes: diversified medical technology conglomerates with imaging integration capabilities, pure-play robotic surgical specialists with proprietary ecosystem lock-in, and mid-tier instrument manufacturers competing on sterilization durability and MDR compliance velocity. Consolidation pressures favor players with captive notified body relationships and retrospective clinical trial funding capacity. Competitive moves center on strategic partnerships for AI algorithm licensing and backward integration into specialized polymer consumable production.
Among diversified medical technology conglomerates, Siemens Healthineers and GE Healthcare exemplify the imaging-integrated surgical workflow archetype, anchoring capital equipment procurement through domestic engineering bases. Medtronic occupies a position within the catheter and energy device specialization tier, while Intuitive Surgical represents the pure-play robotic platform archetype competing on technical leadership in surgeon credentialing pipelines. These three anchors demonstrate how competitive positioning stratifies across capital intensity tiers and regulatory compliance bandwidth.
| Leading Market Players |
|---|
| Siemens Healthineers |
| Intuitive Surgical |
| Medtronic |
| Stryker Corporation |
| Koninklijke Philips |
| GE Healthcare |
| Smith & Nephew |
| Abbott Laboratories |
| Olympus Corporation |
| Others |
Supply & Pricing Matrix
Robotic platform standardization is compressing service contract economics while concentrating procurement leverage among Bavarian university hospital consortia. This dual shift simultaneously elevates total cost of ownership transparency and tightens margin capture for manufacturers lacking captive maintenance networks.
Pricing Analysis
Extended warranty bundling with consumable replenishment programs separates premium robotic vendors from unbundled laparoscopic instrument suppliers. Three-tier pricing structure across premium, standard, and economy levels reflects MDR certification velocity and ISO 13485 quality tier differentiation. Cost compression in reusable instrument lines is intensifying because sterilization cycle tolerance specifications are tightening under DIN EN harmonized standards. Municipal hospital associations in North Rhine-Westphalia exhibit highest price sensitivity due to DRG reimbursement compression, while university medical centers prioritize outcome-linked service agreements over unit economics.
Supply Chain Analysis
Domestic-content thresholds under Germany's Medical Devices Regulation implementation are redirecting polymer feedstock sourcing toward Ruhr corridor chemical manufacturers. Precision instrument production draws from German engineering clusters, Swiss precision component specialists, and Italian polymer processing facilities. Single-source vulnerability concentrates in specialized optical sensor arrays tethered to Baden-Württemberg imaging technology suppliers. Distribution runs through hospital purchasing consortia and specialized medical device distributors serving ambulatory surgical center networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Notified body capacity constraints are creating a supply-constrained certification pipeline that props pricing power for MDR-compliant manufacturers with established BfArM relationships.
For Market Incumbents: Anticipate consolidation pressure from mid-tier manufacturers exiting Class IIa reusable instrument markets rather than absorbing retrospective PMCF study costs. Deepen backward integration into specialized polymer consumable production to capture margin pools threatened by Central European chemical input inflation. Prioritize captive notified body relationship maintenance as competitive moat against accelerated certification timelines. For New Entrants and Emerging Players: Enter via ambulatory surgical center expansion corridors in Lower Saxony and North Rhine-Westphalia where compact laparoscopic tower demand outpaces established vendor coverage. Target same-day discharge protocol enablement as differentiated value proposition for municipal hospital procurement committees. Deploy direct clinical specialist engagement model bypassing traditional distributor markups in fragmented outpatient networks. For Investors and Strategic Acquirers: Exit pathways concentrate in AI-augmented imaging convergence plays with demonstrated G-BA innovation funding traction. Long-term viability hinges on regulatory compliance bandwidth rather than pure technology differentiation, favoring targets with established MDR transition experience over pre-revenue platform developers. Monitor BfArM adverse event reporting velocity as inflection indicator for post-market surveillance cost absorption capacity.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Certification Fast-Track | Accelerated notified body engagement compresses time-to-revenue for legacy device portfolios. |
| AI-Integrated Imaging Partnership | Real-time tissue recognition algorithms unlock G-BA reimbursement pathways for oncologic resection guidance. |
| Ambulatory Surgical Center Distribution | Direct channel control in Lower Saxony outpatient networks bypasses hospital purchasing consortium concentration. |
| Single-Port Robotic Platform Launch | Municipal hospital same-day discharge protocols in Hesse create differentiated procedural volume capture. |
| Fluorescence Imaging Reimbursement Strategy | Indocyanine green perfusion assessment integration secures DRG coding recognition for anastomotic leak reduction. |
Research Methodology
Hospital procurement databases, BfArM vigilance registries, and G-BA health technology assessment rulings formed the secondary backbone for market sizing and regulatory trajectory mapping. Primary interviews with hospital purchasing committee chairs, biomedical engineering directors, GPO contracts managers, and robotic surgery program coordinators validated demand assumptions and procurement timeline intelligence. Bottom-up and top-down triangulation reconciled device shipment data against DRG-funded capital budget disclosures.
Bottom-up modeling anchored volume projections to hospital bed capacity, surgical procedure mix, and robotic platform installation density across German federal states. Top-down validation cross-referenced medical device trade flow data and notified body certification throughput. Segmentation dimensions spanned product type, technology tier, application specialty, and end-user facility class. CAGRs derived from procedure volume elasticity to reimbursement rate adjustments and capital equipment replacement cycles.
Forecast precision tightens around the base case; tail outcomes carry wider variance under MDR implementation timeline extensions or G-BA reimbursement exclusion rulings. Analytical boundaries exclude experimental surgical methods lacking CE marking and preclinical-stage device platforms. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Recanalization System Market
Medical Devices
Global Radial Artery Compression Devices Market
Medical Devices
Transabdominal Retrieval Kits Market
Medical Devices
Dynamic Spinal Tethering Systems Market
Medical Devices
Japan Medical Device Regulatory Affairs Market
Medical Devices
Tumour Ablation Devices Market
Medical Devices
Brachytherapy Afterloaders Market
Medical Devices
Software As a Medical Device Market
Medical Devices
Bioactive Fillings Market
Medical Devices
Orbital Tissue Expander Market
Medical Devices
Veterinary Ventilators Market
Medical Devices
Intravenous Stopcock Market
Medical Devices
Global Vein Illuminator Market
Medical Devices
Inversion Table Market
Medical Devices
Interventional Spine Devices Market
Medical Devices
Stethoscope Hygiene Devices Market