
 Orthopedic Braces and Supports Market | 2026-2036
Orthopedic Braces and Supports Market Size, Share, and Industry Trends Forecast 2026-2036
Orthopedic Braces and Supports Market Intelligence
The substitution of traditional metal alloys with lightweight carbon fiber composites is expanding design possibilities for high-performance braces. This material shift allows for products that offer superior strength-to-weight ratios, improving patient compliance and mobility. Össur specializes in innovative solutions incorporating these advanced materials for prosthetic and bracing applications. DJO LLC leverages its vast distribution network to supply a wide range of devices to orthopedic clinics globally. Bauerfeind differentiates its product line through a focus on medical-grade compression technology and precise anatomical fit.
Orthopedic braces and supports are medical devices designed to align, stabilize, correct, or protect joints and body parts affected by injury, disease, or post-surgical conditions. These devices often feature specific material compositions, such as neoprene for compression or metal alloys for rigid support, to achieve a desired therapeutic outcome. Their primary purpose is to manage pain, prevent further injury, and assist in rehabilitation. Knee braces represent the largest product segment, driven by the high prevalence of sports-related ligament tears and osteoarthritis. Within applications, demand for post-surgical protection devices is steady, while chronic pain management is a rapidly expanding area.
Market access is governed by stringent medical device regulations. In the United States, the FDA classifies these products and mandates specific premarket notifications or approvals. In Europe, braces must comply with the Medical Device Regulation (MDR) to receive CE marking, ensuring safety and performance standards. Japan's PMDA has its own distinct approval process for medical devices. Navigating these varied regional reimbursement frameworks and regulatory pathways remains the central challenge for manufacturers seeking to scale their operations.
Market Dynamics
The primary market tension is between strict medical device regulations and a growing consumer demand for accessible, high-performance supports for lifestyle and sports applications.
Growth Catalysts
- Aging Demographics:The rising prevalence of osteoarthritis in aging populations, especially in Japan and Germany, sustains demand for supportive devices.
- Sports Medicine Growth:Increased sports participation drives a rise in ligament injuries, requiring braces for recovery and prevention.
- Reimbursement Policies:Favorable codes for non-surgical interventions in systems like US Medicare encourage brace use as a first-line treatment.
Market Restraints
- Reimbursement Complexity:Inconsistent reimbursement policies, particularly in the US market, limit patient access and create revenue uncertainty for manufacturers.
- Regulatory Hurdles:The EU's Medical Device Regulation (MDR) imposes high compliance costs and extends market entry timelines, creating barriers for innovators.
- Alternative Therapies:Minimally invasive surgery and regenerative medicine offer alternatives that can reduce the need for long-term bracing post-injury.
Strategic Opportunities
- Emerging Market Expansion:Demand in Brazil and India is growing due to rising incomes and improving healthcare access, creating new patient populations.
- Smart Device Integration:Incorporating IoT sensors into braces enables remote patient monitoring, providing valuable clinical data to improve therapeutic outcomes.
- Occupational Health Niche:Preventative braces for workers in logistics and construction address an unmet need for workplace injury prevention.
Industry Challenges
- Regulatory Navigation:Aligning product development with the distinct requirements of the FDA, PMDA, and EU MDR creates a significant operational burden.
- Material Supply Chains:Securing stable supplies of specialized materials like carbon fiber is challenged by price volatility and logistical disruptions.
- Mass Customization:Balancing demand for personalized 3D-printed devices with the economics of mass production is a key operational hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Orthopedic Braces and Supports Market |
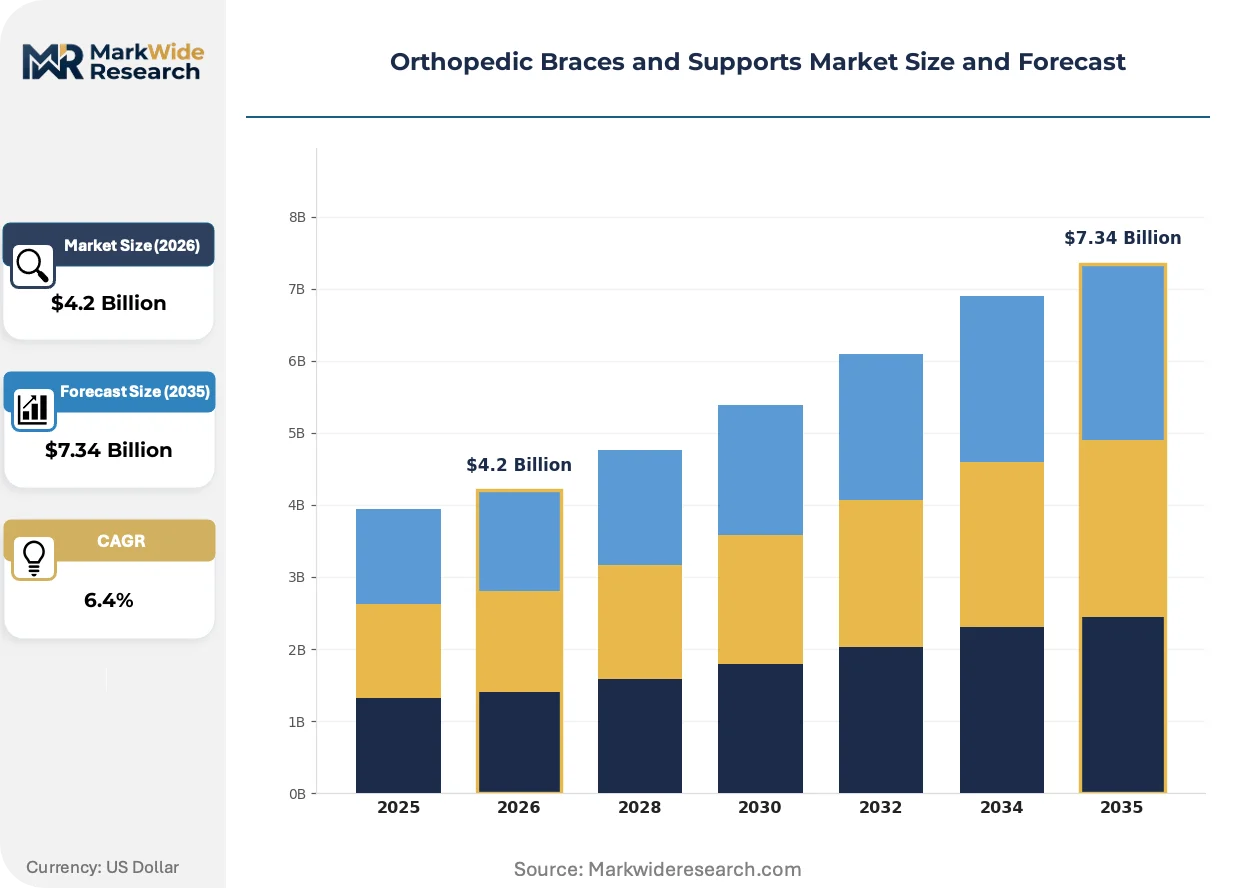
| Market Size in 2026 | $4.2 Billion |
| Market Size in 2035 | $7.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Knee Braces, Wrist Supports, Ankle Wraps, Back Braces, Elbow Supports Material: Neoprene, Elastic Fabric, Metal Alloy, Plastic Composite, Carbon Fiber Application: Sports Injury Recovery, Post-Surgical Protection, Chronic Pain Management, Joint Stabilization, Mobility Assistance End User: Orthopedic Clinics, Rehabilitation Centers, Physical Therapy Facilities, Home Care Patients |
| Companies Covered | Össur, Breg, Inc., DJO LLC, Bauerfeind, 3M, Ottobock, Zimmer Biomet, DeRoyal Industries, Inc., Essity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orthopedic Braces and Supports Market Strategic Shifts & Innovations
The convergence of material science and digital health is redefining the capabilities of orthopedic supports. This evolution shifts patient expectations from passive stabilization toward active, data-informed rehabilitation tools, compelling design innovation.
Smart textiles integrate micro-sensors to monitor joint angles and muscle exertion. Rehabilitation clinics and sports medicine programs are adopting this technology for objective progress tracking. The infusion of this active feedback capability is electrifying the passive support category, turning braces into interactive therapeutic instruments.
The European Union's Medical Device Regulation (MDR) requires manufacturers to provide more robust clinical evidence and post-market surveillance. This forces a portfolio review to ensure CE marking compliance, adding documentation and testing costs. The soft goods segment faces pressure to generate new data to substantiate therapeutic claims.
A behavioral shift sees consumers purchasing supports directly via e-commerce, bypassing traditional medical equipment suppliers. This channel disintermediation disrupts distribution models centered on orthotists and clinics. This direct-to-consumer movement is most advanced in the US for over-the-counter braces for non-acute conditions.
Orthopedic Braces and Supports Market Segmentation
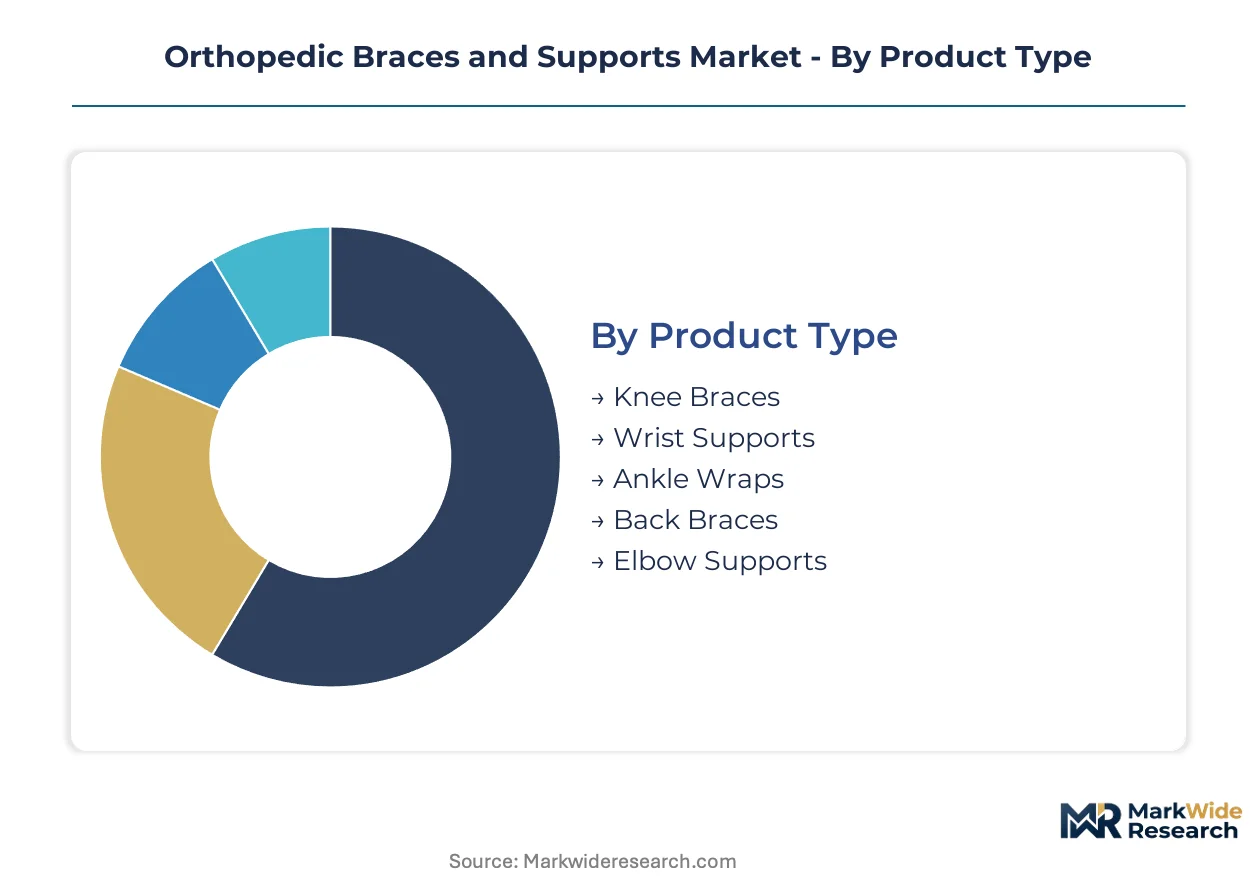
Understanding the distinct segments within the orthopedic braces and supports market reveals where product innovation and patient needs intersect. Each category highlights specific design considerations, material science advancements, or end-user requirements. This granular view assists manufacturers in tailoring solutions for optimized therapeutic outcomes across diverse patient populations.
Product Type:
The product type segmentation reflects the anatomical areas demanding support, often driven by the need for device upgrades or replacements following injury progression or wear and tear. Devices are specialized to address the unique biomechanics of each joint, influencing material selection and design complexity.
- Knee Braces:These devices stabilize the knee joint, often incorporating hinges and straps to manage ligamentous injuries or osteoarthritis. Demand concentrates in developed healthcare markets like Germany, driven by an aging population and high sports participation rates requiring robust recovery solutions.
- Back Braces:Designed to support the spinal column, these braces alleviate pain from conditions like disc herniation or provide post-surgical stabilization. Their market expansion is particularly visible in countries with increasing rates of occupational back injuries and chronic pain management needs.
- Wrist Supports:These devices immobilize or compress the wrist, commonly used for carpal tunnel syndrome, sprains, or post-fracture recovery.
- Ankle Wraps:Ankle wraps offer compression and stabilization for sprains, strains, or chronic instability, particularly prevalent in athletic populations.
- Elbow Supports:These braces target conditions like tennis elbow or golfer's elbow, providing compression and reducing stress on tendons during activity.
Volume placements concentrate in Knee Braces; the faster expansion belongs to Back Braces.
Material:
The choice of material directly influences a brace's cost tier, performance characteristics, and patient comfort, impacting both initial procurement and long-term compliance. Manufacturers balance durability, weight, and flexibility to meet varied clinical requirements and pricing strategies.
- Carbon Fiber:This advanced composite offers exceptional strength-to-weight ratios, enabling lightweight yet rigid braces ideal for high-performance applications and patient mobility. Demand for carbon fiber components is rising in specialized prosthetic and bracing solutions in regions like the United States.
- Metal Alloy:Traditional metal alloys, such as aluminum or titanium, provide robust structural support and durability for complex orthopedic devices requiring significant load-bearing capacity. These materials maintain steady demand in heavy-duty stabilization and post-surgical applications globally.
- Neoprene:A synthetic rubber, neoprene provides compression, warmth, and flexibility, commonly used in soft tissue support and mild joint stabilization.
- Elastic Fabric:Woven elastic textiles offer breathable compression and light support, suitable for mild sprains, strains, and general joint awareness.
- Plastic Composite:These versatile materials, often thermoplastics, allow for custom molding and lightweight rigid support in various brace designs, balancing cost and function.
The segment for Carbon Fiber commands a premium, while Plastic Composite drives volume penetration.
Application:
Segmentation by application highlights the distinct patient types and clinical scenarios where orthopedic braces provide therapeutic value, influencing product design and distribution channels. Each application addresses specific biomechanical needs, from acute injury to long-term chronic conditions.
- Sports Injury Recovery:Braces in this category facilitate healing and protect injured ligaments or joints during the rehabilitation phase for athletes. Adoption is high in countries with strong sports medicine infrastructure, such as the United States, due to increased sports participation.
- Chronic Pain Management:These devices reduce discomfort and provide ongoing support for conditions like osteoarthritis or persistent back pain, improving quality of life. This application is expanding rapidly among aging populations, particularly in Japan, seeking non-pharmacological pain relief.
- Post-Surgical Protection:These braces immobilize or limit movement after surgery, safeguarding healing tissues and preventing re-injury during recovery.
- Joint Stabilization:Braces for joint stabilization prevent unwanted motion, often used for hypermobility or to provide proprioceptive feedback during daily activities.
- Mobility Assistance:This segment includes devices that aid walking or movement for individuals with neurological conditions or severe weakness, enhancing functional independence.
The largest patient cohort is served by Sports Injury Recovery, with Chronic Pain Management addressing a specialized need.
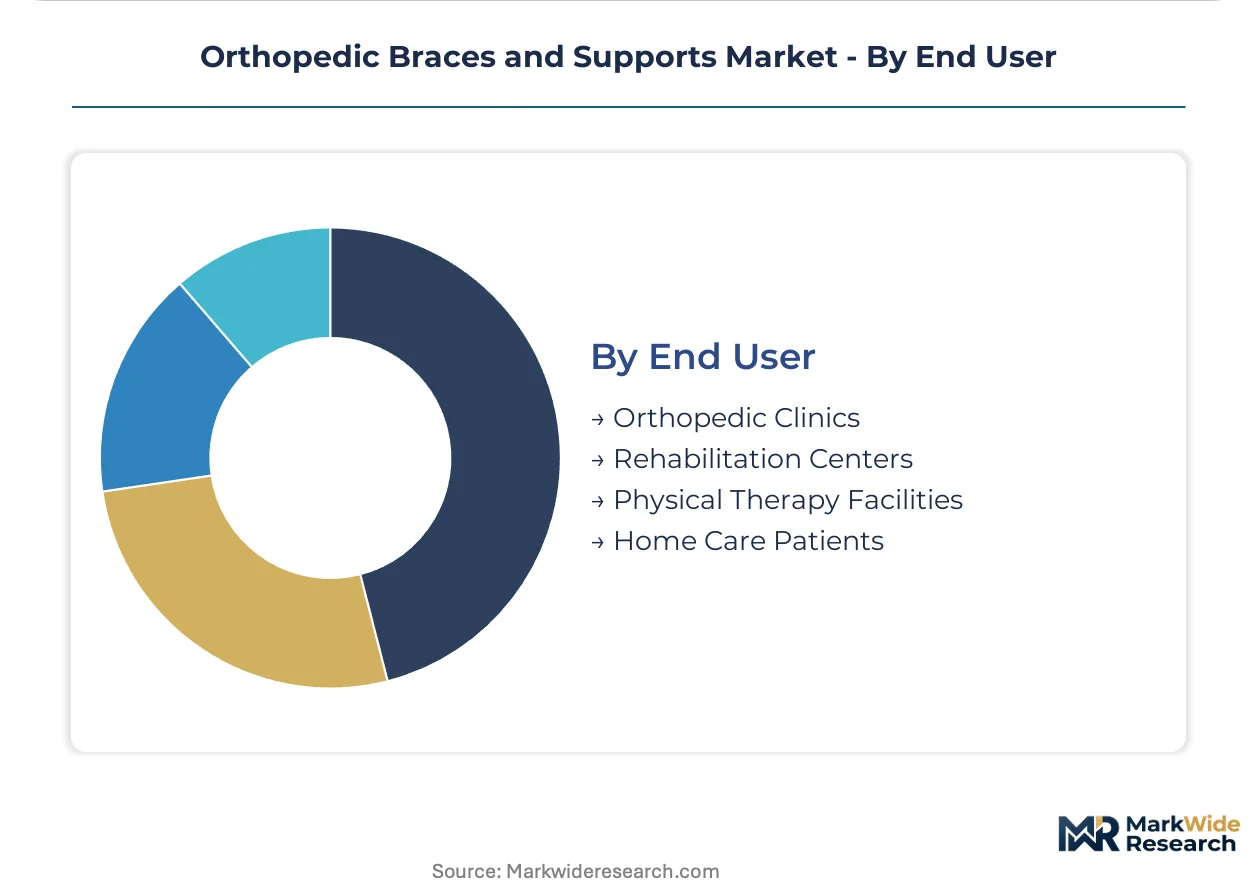
End User:
The end-user segmentation delineates the primary healthcare settings and patient environments where orthopedic braces are prescribed, dispensed, and utilized, shaping distribution strategies. Each end-user type has specific procurement processes and patient care models that influence product demand.
- Orthopedic Clinics:These specialized medical facilities represent a traditional distribution channel, where orthopedic surgeons and specialists prescribe and fit braces. Clinics in developed markets like Germany emphasize high-quality, customized solutions for complex patient cases.
- Home Care Patients:This segment encompasses individuals using braces in their home environment, often for long-term chronic conditions or post-acute recovery. Demand is growing in regions with robust home healthcare networks, like some parts of Europe, driven by convenience and cost-effectiveness.
- Rehabilitation Centers:These facilities focus on restoring function after injury or surgery, utilizing braces as part of a comprehensive physical therapy program.
- Physical Therapy Facilities:Physical therapists often recommend and fit braces for injury prevention, rehabilitation, and performance enhancement in their clinics.
While Orthopedic Clinics generate substantial revenue, Home Care Patients demonstrate significant growth potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Concentrations of advanced healthcare infrastructure, particularly in developed markets, drive significant demand for orthopedic braces. These regions foster innovation and rapid adoption of high-performance supportive devices. The market benefits from specialized medical technology hubs.
Germany
Demand for knee braces is strong due to an aging population and robust sports participation. Braces must comply with the Medical Device Regulation (MDR) for CE marking before market entry. Munich's medical technology cluster drives innovation in high-quality orthopedic solutions. German healthcare policies prioritize rehabilitation services.
United States
Sports injury recovery applications fuel substantial demand for orthopedic supports. The FDA classifies medical devices and mandates specific premarket notifications or approvals. Boston's biotech corridor fosters advanced material development for high-performance braces. Favorable reimbursement codes encourage brace use as a first-line treatment.
Japan
An aging demographic significantly contributes to demand for chronic pain management devices. Japan's PMDA has a distinct approval process for medical devices. The Kansai region's medical device manufacturers focus on precision-engineered solutions. Government health initiatives support non-pharmacological pain relief options.
Brazil
Growing patient populations due to rising incomes and improving healthcare access are expanding the market for orthopedic devices. ANVISA regulates medical devices, ensuring product safety and efficacy. São Paulo's medical equipment industry addresses the country's increasing rehabilitation needs. Demand for post-surgical protection is increasing.
United Kingdom
High sports participation rates drive demand for injury prevention and recovery braces. The UK's Medicines and Healthcare products Regulatory Agency (MHRA) oversees medical device approvals. London's health tech ecosystem supports the integration of smart device technologies. The National Health Service (NHS) influences procurement decisions.
Orthopedic Braces and Supports Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the orthopedic braces market. The landscape features established medical device giants alongside agile innovation-focused firms. Archetypes include material science pioneers developing cutting-edge composites, broad-portfolio providers catering to diverse patient needs, and specialized compression technology developers. Geographic expansion into high-growth emerging markets and strategic partnerships for digital health integration remain dominant competitive moves.
Within the material science pioneer tier, Össur exemplifies advanced composite integration for high-performance prosthetic and bracing applications. DJO LLC, a broad-portfolio provider, occupies a position leveraging extensive distribution networks to supply a wide range of orthopedic devices to clinics globally. Bauerfeind, a German-based firm, sits within the specialized compression technology developer archetype, focusing on medical-grade compression and precise anatomical fit. These firms collectively demonstrate the market's emphasis on both material innovation and comprehensive patient solutions across various therapeutic areas.
| Leading Market Players |
|---|
| Össur |
| Breg, Inc. |
| DJO LLC |
| Bauerfeind |
| 3M |
| Ottobock |
| Zimmer Biomet |
| DeRoyal Industries, Inc. |
| Essity |
| Others |
Cost & Logistics Intelligence
Stringent medical device regulations, especially the EU's MDR, mandate extensive testing and documentation for orthopedic braces. This regulatory demand increases compliance costs for manufacturers, directly influencing their pricing strategies across global markets.
Pricing Analysis
Premium pricing often applies to orthopedic braces with short lead times or specialized custom features. The market primarily utilizes a tiered pricing structure, differentiating between medical-grade, certified devices and over-the-counter supports. Price differentiation stems from material innovation, such as carbon fiber composites, and regulatory approvals like CE marking or FDA clearance. Reimbursement complexity, particularly in the US market, creates pricing softness, making Home Care Patients highly price-sensitive.
Supply Chain Analysis
Dual-sourcing requirements for critical components enhance supply chain resilience for orthopedic brace manufacturers. The supply chain draws heavily from specialized material producers globally, particularly for carbon fiber composites, medical-grade textiles, and integrated IoT sensors. Price volatility in specialized materials presents a structural risk. Distribution runs through established Orthopedic Clinics and increasingly via direct-to-consumer e-commerce channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The orthopedic braces market is evolving into a vertical-integration race, with manufacturers increasingly pursuing advanced material development to control product innovation. This upstream control ensures differentiation and performance in a competitive landscape.
For Market Incumbents: To counter the increasing regulatory hurdles from the EU MDR and FDA, incumbents must streamline their compliance processes. Investment in R&D for advanced materials, like carbon fiber, secures a performance advantage. Strategic partnerships for smart device integration enhance product capabilities and offer remote monitoring solutions. Expanding product portfolios with data-driven rehabilitation tools reinforces market leadership.
For New Entrants and Emerging Players: Capture unmet demand within the occupational health niche by developing preventative braces for logistics and construction workers. Focus on emerging markets like Brazil and India, leveraging improving healthcare access and rising incomes. A specialized product focus, combined with agile e-commerce distribution models, can bypass traditional channels. Offer personalized 3D-printed devices to address specific patient needs.
For Investors and Strategic Acquirers: The window for entry favors mid-cap specialists with strong intellectual property in advanced materials or digital health integration. The market exhibits long-term viability, driven by aging populations and sports medicine growth. Target firms specializing in smart textiles or those with robust distribution networks in high-growth emerging markets. Increased adoption of smart devices in rehabilitation clinics signals a key inflection point.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Device Integration | Incorporating IoT sensors into braces provides valuable clinical data for improved patient outcomes. |
| Advanced Material R&D | Developing next-generation carbon fiber composites enhances product performance and patient comfort. |
| Emerging Market Entry | Expanding distribution into Brazil and India addresses new patient populations with rising incomes. |
| Regulatory Compliance Streamlining | Efficiently navigating EU MDR and FDA approval processes reduces time-to-market for new devices. |
| Direct-to-Consumer Channel Development | Establishing e-commerce platforms bypasses traditional distributors, reaching a broader consumer base. |
Research Approach
FDA filings, EU MDR guidelines, and PMDA reports formed the secondary backbone for this analysis. Researchers conducted primary interviews with orthopedic surgeons, physical therapists, and material science engineers to gather granular insights. This approach combined qualitative expert perspectives with quantitative data from industry associations and company reports. Bottom-up and top-down triangulation validated market size and growth projections.
A robust analytical framework, integrating both bottom-up and top-down approaches, underpinned market projections across the analysis window. Segmentation dimensions modeled included product type, material, application, end-user, and regional regulatory cluster. Compound Annual Growth Rates were derived from historical trends and anticipated future drivers. Key forecast inputs included global sports participation rates and aging population demographics.
The model holds under current regulatory frameworks and material supply chain stability; deviation in these triggers would shift the outlook. Forecasts reflect documented assumptions regarding technological advancements and healthcare policy. Deviation in regulatory stringency or material availability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Middle East and Africa Knee Cartilage Repair Market
Orthopedic Devices
Orthopedic Devices Market
Orthopedic Devices
Orthopedic Joint Reconstruction Market
Orthopedic Devices
Prosthetics and Orthotics Market
Orthopedic Devices
Global Orthopedic Navigation Systems Market
Orthopedic Devices
Humeral Implant Market
Orthopedic Devices
Orthotic Devices Orthotic Splints and Orthopedic Braces and Support Market
Orthopedic Devices
Asia-Pacific Kyphoplasty Market
Orthopedic Devices
Orthopedic Artificial Bone Defect Repair Materials Market
Orthopedic Devices
Spinal Implants and Devices Market
Orthopedic Devices
Computer-Assisted Orthopedic Surgery Market
Orthopedic Devices
Orthopedic Trauma Devices Market
Orthopedic Devices
Orthopedic Trauma Fixation Devices Market
Orthopedic Devices
Spine Devices Market
Orthopedic Devices
India Orthopedic Braces and Supports Market
Orthopedic Devices
Orthopedic Pedicle Screw Market