
 Netherlands Aesthetic Devices Market | 2026-2036
Netherlands Aesthetic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Netherlands Aesthetic Devices Market Foresight
Clinic procurement channels in the Netherlands is tilting toward direct manufacturer partnerships over traditional medical distributors. AbbVie (Allergan Inc.) leverages its injectable portfolio to sustain long-term contracts with Dutch dermatology chains. Alma Lasers competes through localized service networks that reduce equipment downtime for Rotterdam and Amsterdam clinics. Cynosure anchors its position with training academies that lock in practitioner loyalty across the country's aesthetic medicine community.
Aesthetic devices comprise electromechanical and energy-based systems engineered to deliver controlled thermal, optical, or mechanical energy to cutaneous and subcutaneous tissue, typically operating at wavelengths between 400 nm and 10,600 nm with pulse durations calibrated to target specific chromophores or tissue structures. These systems serve commercial purposes in non-invasive and minimally invasive cosmetic procedures, enabling practitioners to modify skin appearance, reduce adipose tissue, or alter hair growth patterns without surgical intervention. Injectable fillers command the deepest margin pools within product type categories, while laser devices occupy the broadest installed base across Dutch clinics. Radiofrequency technology leads technology adoption for skin tightening applications, though ultrasound platforms are gaining traction in fat reduction protocols among Amsterdam's premium dermatology centers.
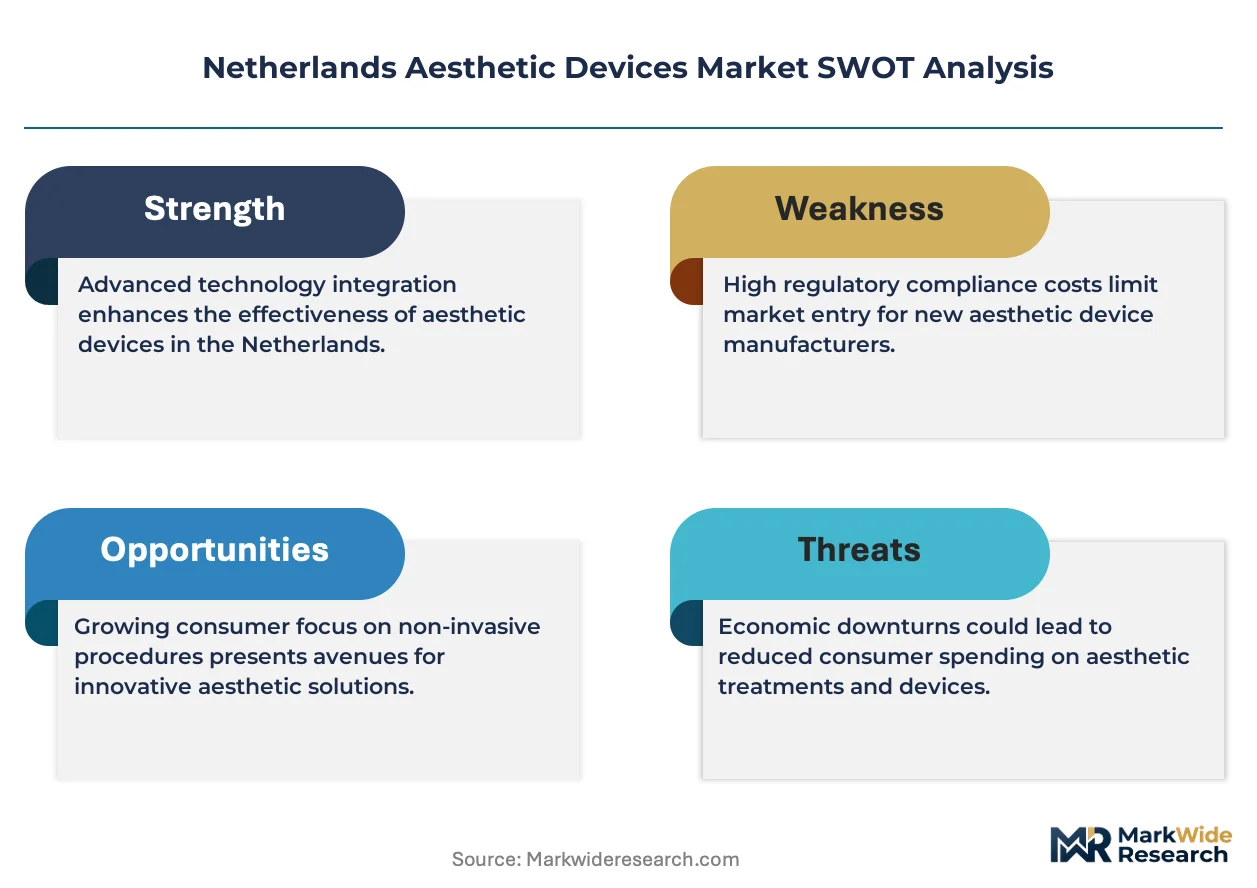
The Medical Devices Regulation and CE marking framework govern market access for aesthetic devices in the Netherlands, with the Dutch Health and Youth Care Inspectorate enforcing post-market surveillance obligations that compel manufacturers to maintain vigilant adverse event reporting systems. The EU AI Act introduces emerging compliance layers for software-enabled devices with automated treatment planning functions, creating new documentation burdens for Dutch importers. Stakeholders must monitor how the Netherlands' implementation of the CSRD affects sustainability disclosure requirements across their European supply chains.
Market Dynamics
The Dutch aesthetic devices market is experiencing structural compression from the MDR's elevated clinical evidence requirements, which force manufacturers to redirect R&D budgets toward regulatory compliance rather than feature innovation. This regulatory tightening coincides with clinic consolidation in Randstad corridors, creating procurement leverage that reshapes vendor pricing power.
Growth Catalysts
- MDR Harmonization:The Medical Devices Regulation's unified CE marking pathway reduces fragmentation for Dutch importers, streamlining market access across EU member states and lowering duplicate certification costs for Rotterdam-based distributors.
- Radiofrequency Platforms:Energy-based skin tightening systems are capturing procedure volume previously served by surgical lifts, with Amsterdam dermatology chains expanding device floorspace for non-invasive protocols.
- Randstad Disposable Income Concentration:Metropolitan household income premiums in Amsterdam and Rotterdam sustain pricing tolerance for premium aesthetic treatments that subsidize equipment amortization.
Market Restraints
- Optical Component Supply Concentration:Laser resonator crystals and fiber couplers concentrate among German and Swiss precision optics suppliers, exposing Dutch device assemblers to input bottlenecks.
- MDR Clinical Evidence Burden:The Medical Devices Regulation's expanded PMCF requirements extend time-to-revenue for novel wavelengths, compressing ROI windows before technology obsolescence.
- Injectable Substitute Threat:Hyaluronic acid fillers and botulinum toxins compete for facial rejuvenation budgets, diverting capital that might otherwise fund energy-based device acquisition.
Strategic Opportunities
- CSRD-Driven Sustainability Disclosure:The Corporate Sustainability Reporting Directive creates service revenue for Dutch distributors offering lifecycle documentation and carbon footprint auditing to manufacturer clients.
- AI Act Software Classification:Automated treatment planning modules fall under the EU AI Act's high-risk category, opening compliance consulting opportunities for Rotterdam-based technical file specialists.
- Secondary City Clinic Expansion:Eindhoven and Utrecht demonstrate underpenetrated device density relative to disposable income benchmarks, offering first-mover positioning before saturation.
Industry Challenges
- Photonics Technician Scarcity:Laser calibration and fiber alignment require specialized optical engineering skills that Dutch vocational pipelines underproduce, extending service response times.
- Legacy System Integration:Established clinics operate mixed-device fleets with proprietary software protocols, complicating unified patient record systems and cross-platform treatment sequencing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherlands Aesthetic Devices Market |
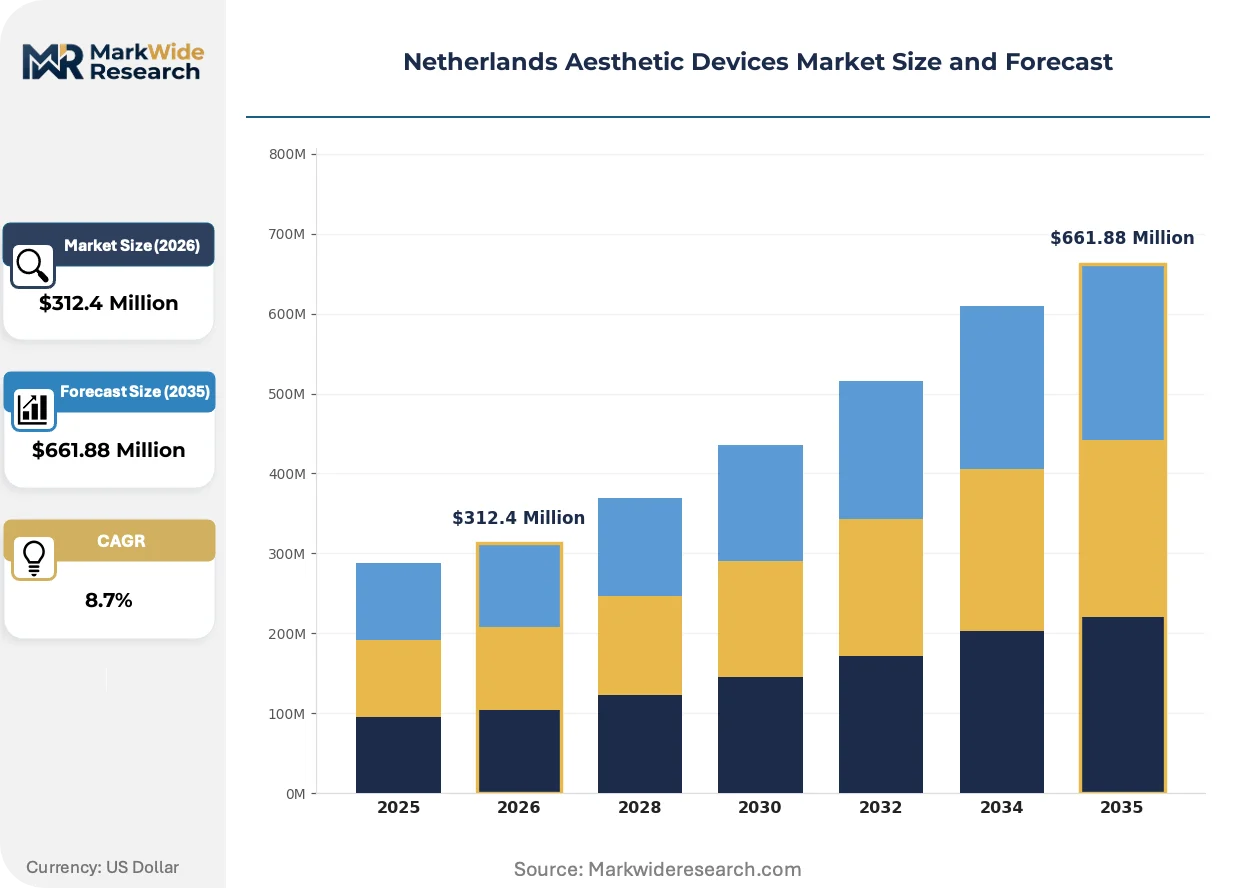
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Devices, Injectable Fillers, Liposuction Equipment, Body Contouring Devices End User: Clinics, Hospitals, Beauty Salons, Dermatology Centers Technology: Radiofrequency, Ultrasound, LED, Intense Pulsed Light Application: Skin Rejuvenation, Hair Removal, Fat Reduction, Anti-Aging Treatments |
| Companies Covered | AbbVie (Allergan Inc.), Cynosure, Alma Lasers, Galderma SA (Nestlé Skin Health), Sciton Inc., Lumenis Inc., Entercare, Merz Pharmaceuticals, Johnson & Johnson, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherlands Aesthetic Devices Market Shifts & Advancements
Energy delivery modalities and software-enabled treatment planning are converging to redefine procedural economics in Dutch aesthetic medicine. Three developments are compressing competitive differentiation timelines and reshaping buyer-vendor relationships.
Picosecond laser platforms operate at pulse durations below skin thermal relaxation time, enabling pigment and tattoo clearance with reduced collateral tissue heating. Premium dermatology centers in Amsterdam are replacing nanosecond Q-switched systems at replacement cycles compressed to 36 months. This acceleration is rendering obsolete the five-year depreciation schedules that previously structured clinic capital planning.
The EU AI Act imposes conformity assessment obligations on software with autonomous treatment parameter selection, creating documentation burdens for devices with embedded dose algorithms. Dutch importers must now maintain technical files spanning both MDR and AI Act requirements, with Rotterdam customs authorities screening for dual compliance at entry. Energy-based device categories with integrated skin analysis cameras face the steepest adaptation costs.
Direct manufacturer partnerships are displacing traditional medical distributor relationships among Dutch clinic chains seeking volume pricing and priority service access. AbbVie's injectable portfolio anchors long-term supply agreements that bundle device procurement, compressing independent distributor margins. This channel restructuring concentrates procurement authority within Rotterdam and Amsterdam headquarters functions, marginalizing regional sales representation.
Netherlands Aesthetic Devices Market Segmentation
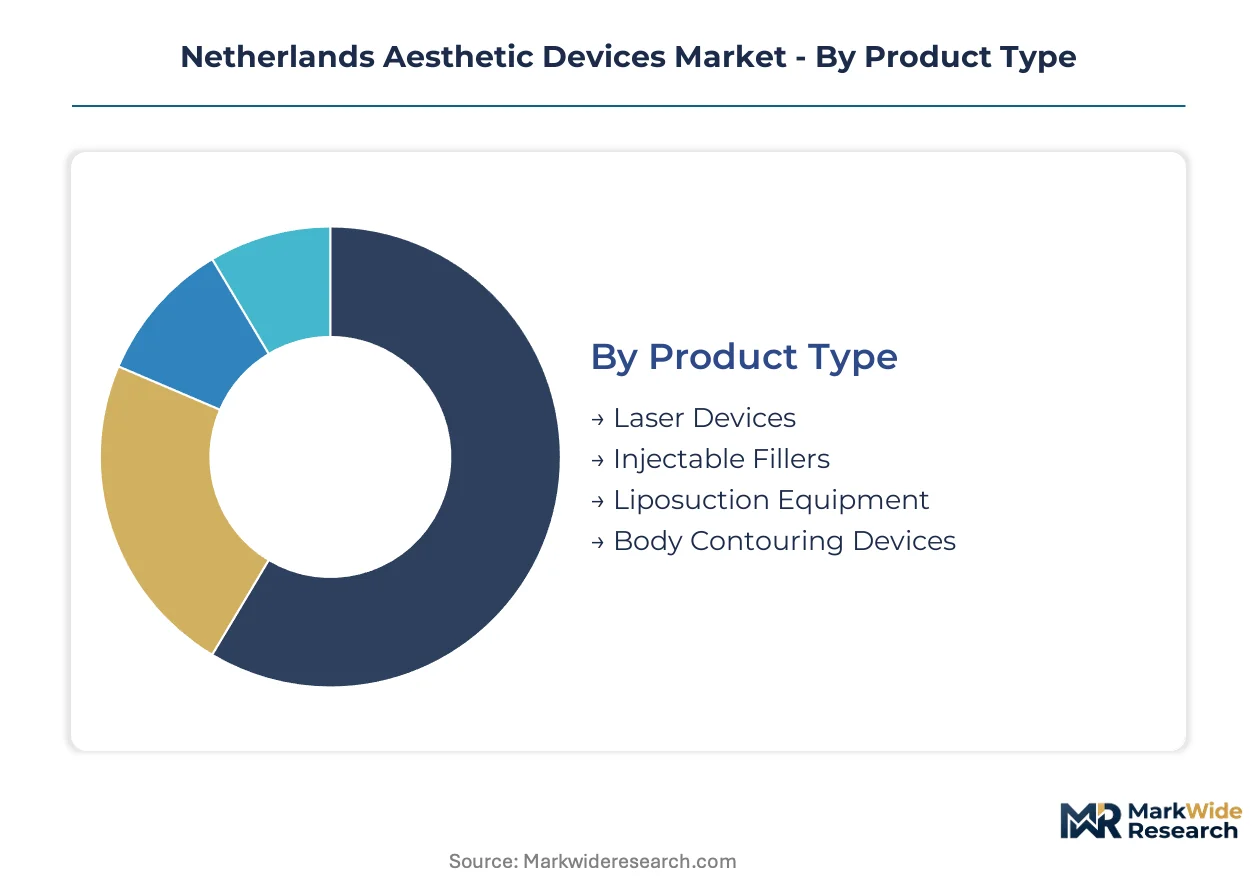
Equipment lifecycle economics and service dependency vary sharply across aesthetic device categories in the Netherlands. Procurement committees weigh capital intensity against consumable revenue streams when structuring vendor relationships.
Product Type:
After-sales service intensity distinguishes capital equipment from consumable-driven categories, with laser platforms demanding specialized photonics technicians and injectable portfolios requiring cold-chain logistics rather than field engineering.
- Injectable Fillers:Hyaluronic acid and botulinum toxin formulations command premium pricing through recurring purchase cycles rather than depreciation schedules. Dutch dermatology chains in Amsterdam and Rotterdam structure multi-year supply agreements that bundle volume discounts with practitioner training credits.
- Laser Devices:Solid-state and diode laser systems operate across 400-10,600 nm wavelengths with resonator crystals requiring factory-level recalibration. Service response times in the Randstad corridor depend on localized technician density, with Alma Lasers and Cynosure maintaining dedicated Dutch field teams.
- Body Contouring Devices:Cryolipolysis and electromagnetic muscle stimulation platforms target non-invasive fat reduction with lower consumable attachment than injectables.
- Liposuction Equipment:Power-assisted and laser-assisted aspiration systems serve surgical suites with higher capital barriers and longer replacement cycles.
Injectable fillers hold the largest share; momentum sits with laser devices as picosecond platforms displace nanosecond systems.
End User:
Procurement authority concentrates differently across facility types, with chain-affiliated clinics centralizing purchasing decisions while independent dermatology centers retain local vendor selection.
- Dermatology Centers:Physician-led facilities in Amsterdam and Rotterdam command premium device specifications and prioritize clinical evidence portfolios. MDR compliance documentation and PMCF study commitments factor heavily into vendor selection.
- Clinics:Medical spa chains achieve procurement leverage through fleet standardization, negotiating priority service tiers and extended warranties.
- Hospitals:Academic medical centers in Utrecht and Leiden emphasize research collaboration opportunities and training academy access.
- Beauty Salons:Non-medical aesthetic venues face stricter scope-of-practice limitations under Dutch healthcare regulations, constraining device categories to superficial applications.
Dermatology centers anchor premium segment revenue; clinics are expanding most quickly as consolidation creates procurement scale.
Technology:
Energy delivery modalities compete for procedural volume based on tissue interaction specificity, with thermal relaxation time and chromophore targeting determining clinical indications.
- Radiofrequency:Monopolar and multipolar systems generate dermal heating through tissue impedance, with Amsterdam chains expanding device floorspace for skin tightening protocols. Non-ablative delivery enables minimal downtime positioning against surgical alternatives.
- Ultrasound:High-intensity focused acoustic energy penetrates to adipose tissue depths for non-invasive fat reduction. Premium Rotterdam dermatology centers are adopting micro-focused platforms for facial lifting applications previously served by injectables.
- Intense Pulsed Light:Broadband flashlamp systems address pigmentation and vascular lesions with lower capital barriers than single-wavelength lasers.
- LED:Photobiomodulation panels target inflammatory skin conditions with minimal regulatory classification burden.
Radiofrequency holds the largest installed base; ultrasound gains share fastest as fat reduction protocols displace surgical liposuction demand.
Application:
Procedure economics and reimbursement positioning shape equipment allocation across treatment categories, with facial applications commanding higher per-session pricing than body contouring.
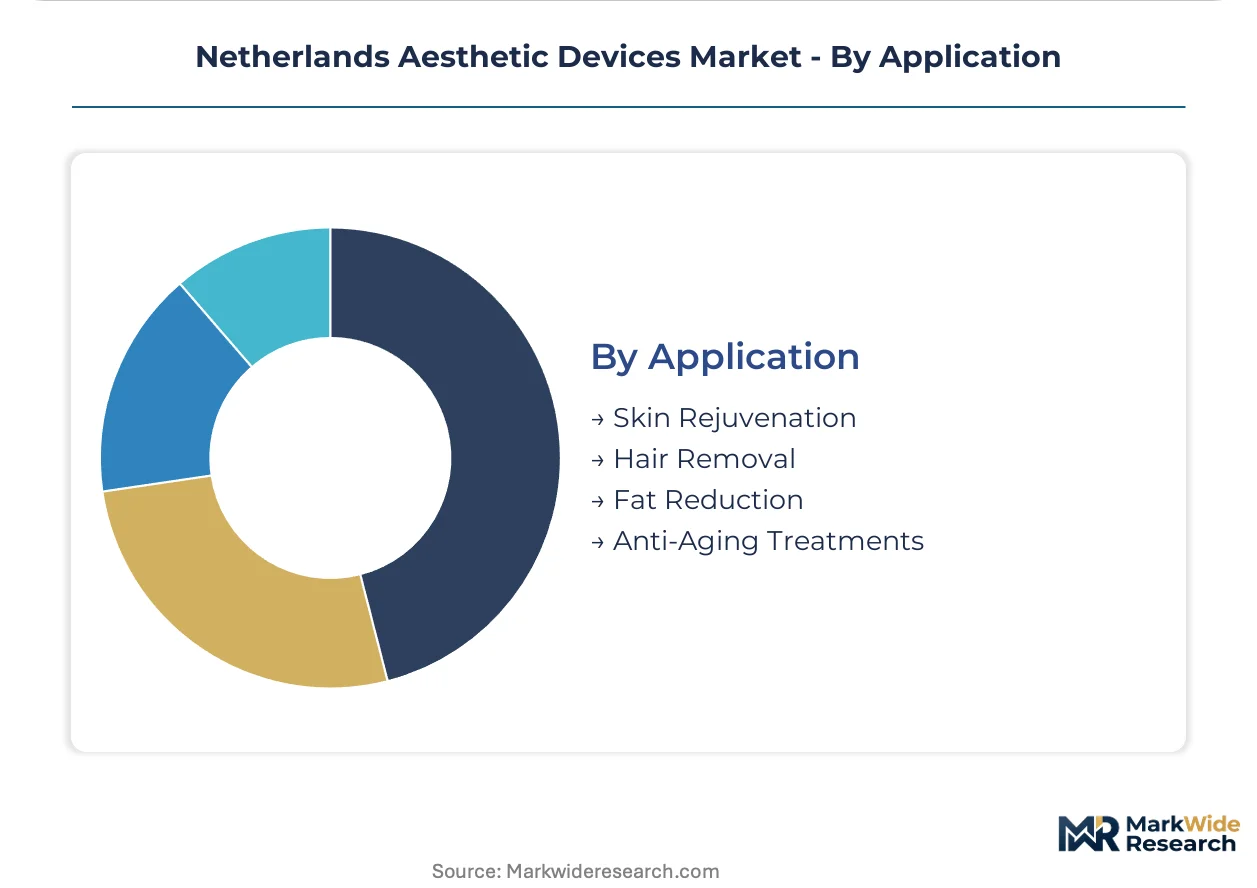
- Skin Rejuvenation:Resurfacing, pigment correction, and texture improvement procedures utilize fractional lasers and IPL platforms. Dutch clinics prioritize devices with minimal erythema duration to maximize daily patient throughput.
- Anti-Aging Treatments:Combination protocols integrating radiofrequency, ultrasound, and injectables target facial laxity and volume loss. Amsterdam premium centers bundle multi-modality packages at price points subsidizing equipment amortization.
- Hair Removal:Alexandrite and diode laser systems serve high-volume, repeat-visit patient cohorts with predictable maintenance revenue.
- Fat Reduction:Cryolipolysis and HIFU applications compete with surgical alternatives on downtime positioning rather than single-session efficacy.
Skin rejuvenation holds the largest share; anti-aging treatments show the steepest expansion trajectory as combination protocols displace standalone procedures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Randstad metropolitan corridors command pricing premiums 25-35% above peripheral Dutch provinces, while Eindhoven and Brabant manufacturing clusters exert procurement leverage through concentrated device demand.
Randstad
Amsterdam and Rotterdam dermatology chains drive premium device specifications through consolidated purchasing power. The Dutch Health and Youth Care Inspectorate enforces MDR compliance documentation with particular rigor in these dense clinical corridors. Medical spa expansion along the Amsterdam-Rotterdam-Utrecht axis absorbs picosecond laser platforms at replacement cycles compressed to 36 months.
Brabant
Eindhoven's technical university corridor supplies photonics engineering talent to device service networks. CSRD sustainability disclosure requirements affect supply chain documentation for distributors headquartered in this southern province. Tilburg and Breda clinic clusters demonstrate rising ultrasound platform adoption for fat reduction protocols.
Utrecht Province
Academic medical centers in Utrecht emphasize research collaboration opportunities and training academy access in procurement decisions. The EU AI Act's high-risk classification for automated treatment planning creates compliance consulting demand among importers based here. Device density remains underpenetrated relative to disposable income benchmarks, offering expansion runway.
Northern Netherlands
Groningen and Leeuwarden aesthetic clinics operate with thinner manufacturer service coverage, extending equipment downtime risks. Dutch healthcare regulations constrain non-medical beauty salon device categories more stringently than in southern provinces. Secondary city procurement committees prioritize extended warranty terms over cutting-edge specifications.
Netherlands Aesthetic Devices Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying resonator crystals and fiber couplers to Dutch assemblers. The Netherlands aesthetic devices market structures around three archetypes: multinational injectable portfolios anchoring long-term supply agreements, laser platform vendors with localized Dutch service networks, and regional distributors pivoting toward compliance consulting under MDR and AI Act pressures. Competitive moves concentrate on direct manufacturer partnerships displacing traditional distributor channels, and sustainability documentation services capturing CSRD-driven revenue.
Among the named players, AbbVie (Allergan Inc.) occupies a position exemplifying the injectable-led portfolio archetype, while Cynosure and Alma Lasers represent laser platform vendors with established Dutch field presence. These three entities anchor distinct competitive vectors within the market's procurement ecosystem.
| Leading Market Players |
|---|
| AbbVie (Allergan Inc.) |
| Cynosure |
| Alma Lasers |
| Galderma SA (Nestlé Skin Health) |
| Sciton Inc. |
| Lumenis Inc. |
| Entercare |
| Merz Pharmaceuticals |
| Johnson & Johnson |
| Others |
Supply & Pricing Matrix
Overcapacity in German precision optics foundries is compressing component pricing for Dutch laser device assemblers while simultaneously extending supplier payment terms, creating working capital advantages that Rotterdam-based distributors exploit to offer competitive equipment financing.
Pricing Analysis
The customization-premium spread between configured-to-order picosecond laser systems and standard diode platforms spans approximately 40-60 percent in Dutch clinic procurement. Pricing stratifies across premium, standard, and economy tiers with CE-MDR certification grade and field service response guarantees as primary differentiation drivers. Cost compression in the standard equipment tier is intensifying because Amsterdam dermatology chains are consolidating purchasing volume and demanding extended warranty bundling. Independent clinics in peripheral provinces exhibit the highest price sensitivity, while Randstad medical spa chains prioritize uptime guarantees over capital expenditure minimization.
Supply Chain Analysis
Export-control restrictions on high-power laser diodes and precision optical coatings limit flows from certain jurisdictions into Dutch assembly operations. Component sourcing draws from Germany, Switzerland, and the United States for resonator crystals, fiber couplers, and beam delivery systems. Single-source vulnerability concentrates in ytterbium-doped fiber suppliers, where qualified alternative vendors require 18-month MDR technical file requalification. Distribution runs through Rotterdam port customs for EU-wide fulfillment, with specialized photonics logistics providers handling vibration-sensitive optical subassemblies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as MDR compliance burdens and AI Act documentation requirements splinter procurement authority across Dutch clinic chains, creating service niches for specialized technical file consultants and sustainability auditors.
For Market Incumbents: Build regulatory compliance moats through captive PMCF study infrastructure that locks Dutch dermatology chains into long-term data partnerships. Deepen backward integration into resonator crystal supply through exclusive offtake agreements with German photonics foundries. Defend against injectable substitute threats by bundling energy-based device procurement with practitioner training academy credits that raise switching costs.
For New Entrants and Emerging Players: Pursue secondary city clinic expansion in Eindhoven and Utrecht where device density lags disposable income benchmarks by 30-40 percent. Target ultrasound platform adoption for fat reduction protocols where premium Rotterdam centers are displacing surgical liposuction demand. Enter through compliance-as-a-service offerings that address CSRD sustainability documentation burdens for Dutch importers lacking in-house carbon auditing capabilities.
For Investors and Strategic Acquirers: Capital is best deployed toward regional distributors with established Rotterdam customs relationships and technical file specialization spanning both MDR and AI Act requirements. The five-to-ten year viability window favors platform integrators over component specialists as clinic consolidation concentrates procurement authority. Watch for inflection signals in picosecond laser replacement cycle compression below 30 months, which would indicate accelerated obsolescence risk in installed base portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| CE-MDR Technical File Expansion | Dual compliance with EU AI Act requirements opens service revenue streams for Rotterdam-based specialists. |
| Photonics Technician Training Academy | Alma Lasers and Cynosure lock practitioner loyalty through certified calibration programs in Amsterdam. |
| Direct Manufacturer Partnership | AbbVie's injectable portfolio anchors long-term supply agreements that compress independent distributor margins. |
| CSRD Sustainability Documentation Service | Lifecycle carbon auditing captures compliance-driven revenue from Dutch importers facing disclosure mandates. |
| Secondary City Clinic Fleet Standardization | Eindhoven and Utrecht expansion offers first-mover positioning before device density saturation. |
Research Methodology
Initial hypotheses were tested against primary input from dermatology clinic procurement directors, biomedical equipment engineers, GPO contracts managers, and Dutch Health and Youth Care Inspectorate officials, then refined through secondary validation against CE marking databases, MDR technical file registries, hospital procurement records, and customs import documentation for laser device components. Bottom-up clinic fleet inventory analysis triangulated with top-down manufacturer shipment data.
Demand-supply balance across the analysis window was modeled through procedure volume projections, equipment replacement cycle dynamics, and import capacity constraints at Rotterdam customs. Segmentation dimensions included product type, end-user facility category, energy delivery technology, and regional disposable income clustering. CAGRs were derived from installed base growth rates and per-clinic device penetration benchmarks. Forecast inputs incorporated MDR compliance timeline delays and AI Act software classification rulings.
Macroeconomic conditions sit as an overlay; deviation in Randstad household income growth or euro-zone precision optics trade flows would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory implementation timelines and clinic consolidation velocity. Material shifts in MDR notified body capacity or EU AI Act enforcement interpretation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Japan Minimally Invasive Surgery Devices Market
Medical Devices
Global Artificial Tendons and Ligaments Market
Medical Devices
Australia Respiratory Devices Market
Medical Devices
Smart Syringe Market
Medical Devices
Pharma Robots Market
Medical Devices
North America Vagus Nerve Stimulation Market
Medical Devices
Bare Metal Stents Market
Medical Devices
Tattoo Removal Lasers Market
Medical Devices
Mexico Ultrasound Devices Market
Medical Devices
Radiotherapy Devices Market
Medical Devices
Foot and Ankle Devices Market
Medical Devices
Heart Failure POC and LOC Devices Market
Medical Devices
Memory Implants Market
Medical Devices
Penile Implants Market
Medical Devices
Capsule Endoscope and Workstations Market
Medical Devices
Saudi Arabia Ophthalmic Devices Market