
 ACL Reconstruction Market | 2026-2036
ACL Reconstruction Market Size, Share, and Industry Trends Forecast 2026-2036
ACL Reconstruction Market Analysis
Multi-source procurement of biologic graft materials is rebalancing toward vertically integrated suppliers with captive tissue processing capabilities. Arthrex leverages in-house allograft processing to control supply consistency across its sports medicine portfolio. Smith+Nephew anchors its position through synthetic ligament R&D programs in European manufacturing hubs. Stryker competes by extending its arthroscopic instrument lines into integrated procedure kits for ambulatory surgery centers.
Anterior cruciate ligament reconstruction encompasses surgical restoration of knee joint stability through tendon graft fixation using interference screws, suture anchors, or cortical suspension devices, typically performed arthroscopically with fiberoptic visualization systems. The procedure restores rotational stability and anterior tibial translation resistance for patients with complete ACL rupture. Autograft procedures utilizing patellar tendon or hamstring harvest dominate volume in hospital settings due to established reimbursement pathways and superior graft incorporation rates. Robotic-assisted surgery represents the fastest-growing technology segment, though arthroscopic platforms still capture the majority of margin pools through disposable instrument recurring revenue. Sports medicine facilities now drive demand for minimally invasive techniques that reduce perioperative morbidity and accelerate rehabilitation protocols.
FDA 510(k) premarket notification requirements govern fixation device commercialization in the United States, while the EU Medical Device Regulation mandates clinical evidence thresholds for ACL implant class III certification. Japan's PMDA enforces stringent biocompatibility testing protocols for synthetic ligament materials entering its reimbursed procedure catalog. Stakeholders must monitor evolving health technology assessment criteria in Germany and France, where graft selection decisions increasingly hinge on comparative effectiveness data rather than surgeon preference alone.
Market Dynamics
Robotic-assisted ACL reconstruction platforms are compressing procedure times and standardizing tunnel placement precision, forcing arthroscopic instrument manufacturers to defend recurring revenue streams against capital-intensive automation systems that promise reproducible outcomes.
Growth Catalysts
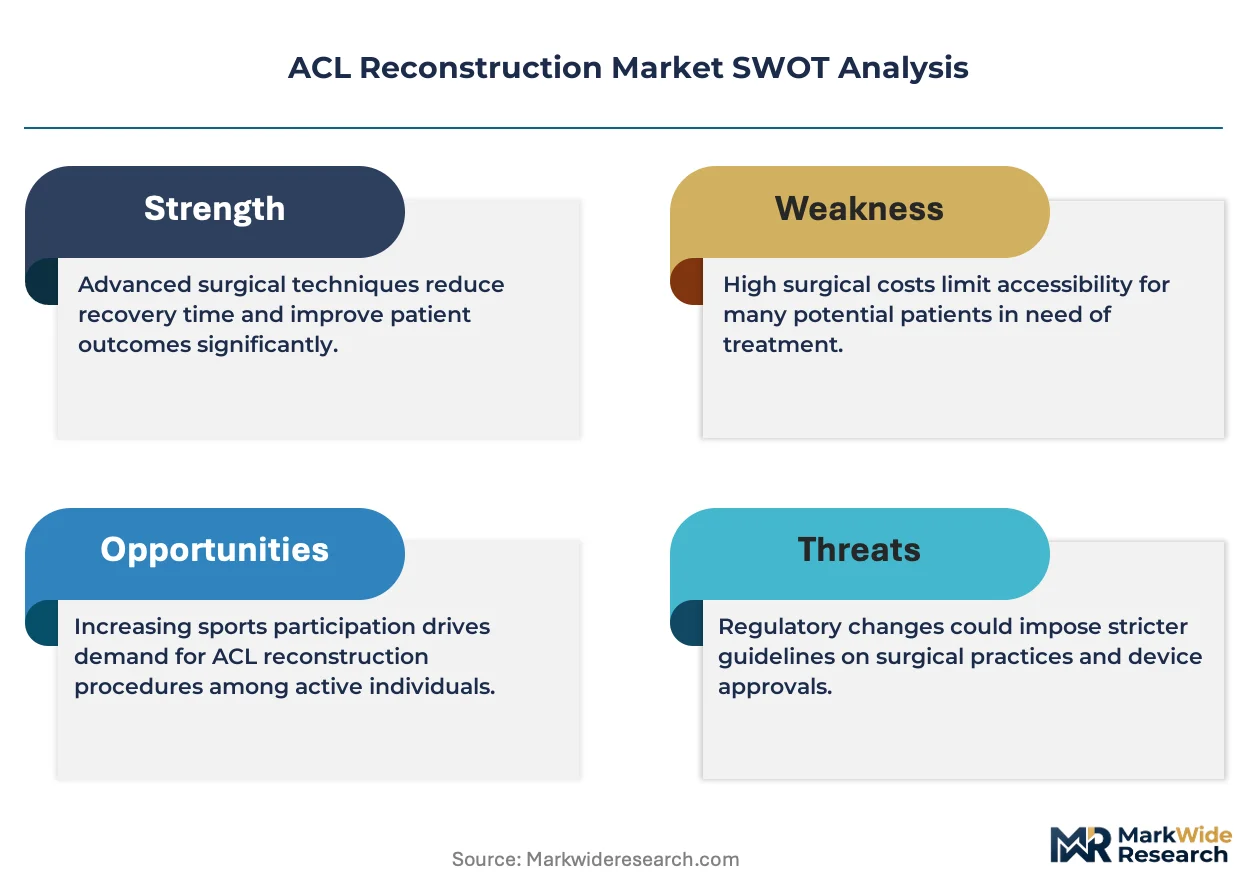
- EU MDR Class III Certification Pathways:Elevated clinical evidence requirements for fixation devices are filtering marginal competitors and consolidating procurement decisions around established manufacturers with robust quality management systems.
- Sports Medicine Facility Expansion:Dedicated arthroscopy centers in Germany, the United States, and Japan are driving volume concentration and protocol standardization for autograft-dominant procedures.
- Biologic Graft Processing:Captive tissue processing capabilities are securing supply consistency for allograft-dependent product portfolios amid volatile donor tissue availability.
Market Restraints
- Allograft Supply Volatility:Donor tissue procurement depends on regional tissue bank networks with uneven geographic coverage, creating batch-to-batch inconsistency in graft mechanical properties.
- Reimbursement Compression:Hospital outpatient prospective payment systems in the United States are narrowing margins on hardware-intensive procedures relative to physician fee schedules.
- Synthetic Ligament Biocompatibility Hurdles:PMDA-mandated long-term implantation studies delay Japanese market entry for polyester-based ligament substitutes by 24-36 months versus FDA 510(k) timelines.
Strategic Opportunities
- Ambulatory Surgery Center Channel Development:Freestanding ASCs in the United States are capturing migrating case volume from hospital outpatient departments, creating demand for compact, disposable-heavy procedure kits.
- Hamstring Autograft Harvest Optimization:Converging advances in ultrasound-guided tendon identification and minimally invasive harvest techniques are reducing donor-site morbidity and expanding patient candidacy.
- German Arthroscopy Center Clustering:Munich and Berlin specialist hubs are generating referral network effects that concentrate high-complexity revision reconstruction demand.
Industry Challenges
- Robotic Platform Integration Complexity:Capital equipment purchases require retraining surgical staff and reconfiguring OR workflows, extending implementation timelines beyond typical capital budget cycles.
- Graft Selection Standardization Delays:Absence of consensus guidelines comparing patellar tendon, hamstring, and quadriceps tendon autograft outcomes perpetuates surgeon-specific variability in technique adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ACL Reconstruction Market |
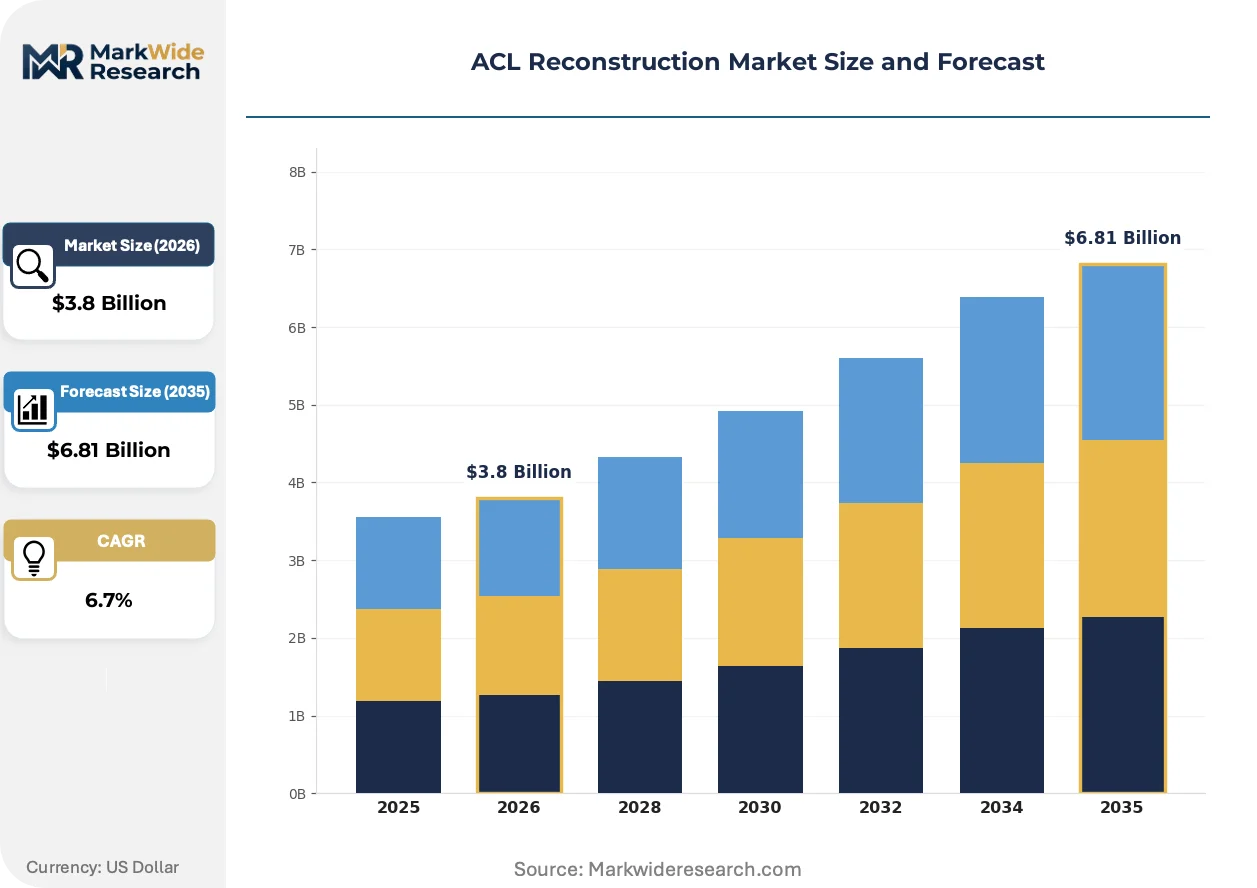
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autograft, Allograft, Synthetic, Others End User: Hospitals, Orthopedic Clinics, Rehabilitation Centers, Sports Medicine Facilities Technology: Arthroscopic Surgery, Open Surgery, Robotic-Assisted Surgery, Minimally Invasive Techniques Application: Athletic Injuries, General Trauma, Chronic Injuries, Revision Surgeries |
| Companies Covered | Johnson & Johnson (DePuy Synthes), CONMED Corporation, Arthrex, Inc., Olympus Corporation, B. Braun Melsungen AG, Stryker Corporation, Zimmer Biomet Holdings, Inc., Karl Storz SE & Co. KG, Smith+Nephew plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ACL Reconstruction Market Emerging Trajectories
Three interconnected developments are restructuring how ACL reconstruction procedures are performed, reimbursed, and supplied: capital equipment automation, evidence-based regulatory gatekeeping, and site-of-care migration toward lower-acuity settings.
Quadriceps tendon autograft harvest is overtaking hamstring tendon as the preferred graft source for revision reconstructions and high-demand athletes. Sports medicine surgeons in tertiary referral centers are adopting the technique for its favorable donor-site morbidity profile and larger graft diameter potential. This shift is compressing demand for traditional hamstring harvest instrumentation while expanding the addressable market for quadriceps-specific harvest guides and fixation systems.
Japan's PMDA has tightened biocompatibility testing protocols for permanent implantable devices, requiring extended cytotoxicity and sensitization studies for synthetic ligament materials. Manufacturers seeking inclusion in Japan's reimbursed procedure catalog must now submit 24-month implantation data from large-animal models. Synthetic ligament developers are responding by prioritizing biodegradable scaffold architectures over permanent polymer implants to circumvent the most burdensome testing requirements.
Athletic trainers and physical therapy groups are demanding bundled rehabilitation protocols that tie surgical fixation selection to postoperative functional milestones. Hospital systems in the United States are responding by contracting with sports medicine practices that demonstrate standardized return-to-play timelines. This behavioral shift is most visible in NCAA Division I athletic programs, where team physicians face institutional pressure to minimize season-ending recovery periods through graft selection and fixation method optimization.
ACL Reconstruction Market Segmentation
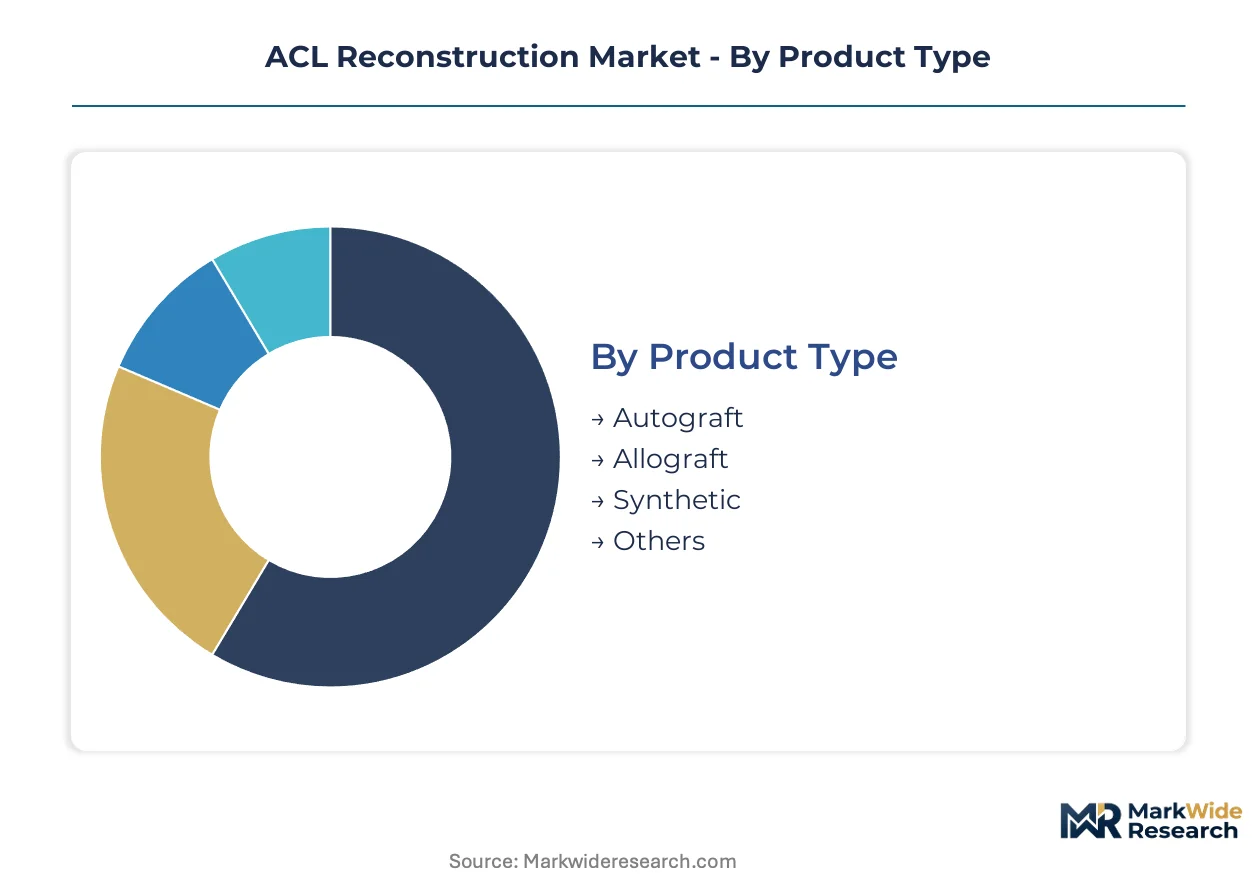
Segmentation in the ACL reconstruction market reveals how graft selection, surgical venue, and technology sophistication stratify procurement decisions. Manufacturers configure product portfolios differently for high-volume hospital systems versus specialized sports medicine centers. Understanding these divisions exposes where margin pools concentrate and which segments drive instrumentation innovation cycles.
Product Type:
Autograft and allograft materials anchor standalone procedure economics, while synthetic alternatives embed into broader ligament reconstruction platforms requiring longer validation timelines.
- Autograft:Patellar tendon and hamstring tendon harvests dominate hospital volume due to established reimbursement codes and superior biological incorporation rates. Demand concentrates in Germany and the United States, where sports medicine facilities prioritize graft-tendon mechanical matching for athlete return-to-play protocols.
- Allograft:Cadaveric tendon tissue eliminates donor-site morbidity and appeals to revision reconstruction candidates with compromised harvest sites. Procurement depends on regional tissue bank networks, with supply volatility creating batch-to-batch mechanical property inconsistency that constrains adoption in high-performance athletic populations.
- Synthetic:Polyester-based ligament substitutes face extended PMDA biocompatibility testing timelines in Japan. Developers are pivoting toward biodegradable scaffold architectures to circumvent permanent implant regulatory burdens.
- Others:Xenograft materials and tissue-engineered constructs remain experimental, with clinical evidence insufficient for routine commercial deployment.
Volume placements concentrate in autograft; the faster expansion belongs to synthetic as regulatory pathways for biodegradable scaffolds mature.
End User:
Site-of-care economics separate capital-intensive hospital systems from disposable-heavy ambulatory venues, reshaping how manufacturers configure instrument and fixation kit offerings.
- Hospitals:Academic medical centers and community hospitals capture complex revision reconstructions and polytrauma cases requiring overnight observation. Reimbursement compression under outpatient prospective payment systems is narrowing hardware margins relative to physician fee schedules.
- Orthopedic Clinics:Physician-owned specialty practices concentrate primary ACL reconstructions with streamlined preoperative workup protocols. These venues favor compact arthroscopic towers and single-use instrument kits that minimize sterilization overhead.
- Rehabilitation Centers:Postoperative physical therapy groups are demanding bundled care contracts that tie surgical fixation selection to functional milestone achievement. This behavioral shift pressures surgeons to standardize graft and fixation choices around demonstrated recovery timelines.
- Sports Medicine Facilities:Dedicated arthroscopy centers in Munich and Berlin generate referral network effects for high-complexity cases. NCAA Division I programs in the United States drive demand for minimally invasive techniques that compress season-ending recovery periods.
Case volume is migrating fastest toward orthopedic clinics; sports medicine facilities command the highest per-procedure fixation spend.
Technology:
Capital equipment intensity varies dramatically across platforms, with robotic systems requiring multi-year implementation timelines versus disposable-heavy arthroscopic workflows.
- Arthroscopic Surgery:Fiberoptic visualization with specialized instrument portals remains the dominant technical approach, capturing recurring revenue through single-use shavers, burrs, and fixation devices. Stryker and Arthrex defend position through integrated procedure kits for ambulatory surgery centers.
- Open Surgery:Extensor mechanism exposure for complex revision reconstructions with compromised tunnels persists in tertiary referral settings. Volume is contracting as arthroscopic techniques advance.
- Robotic-Assisted Surgery:Tunnel placement automation is compressing procedure times and standardizing anatomic graft positioning. Capital equipment purchases force retraining surgical staff and reconfiguring OR workflows, extending implementation beyond typical budget cycles.
- Minimally Invasive Techniques:Quadriceps tendon harvest through limited incisions is overtaking hamstring approaches for favorable donor-site morbidity profiles. Ultrasound-guided tendon identification is expanding patient candidacy.
Arthroscopic platforms still capture the majority of margin pools; robotic-assisted systems are climbing the fastest as precision demands intensify.
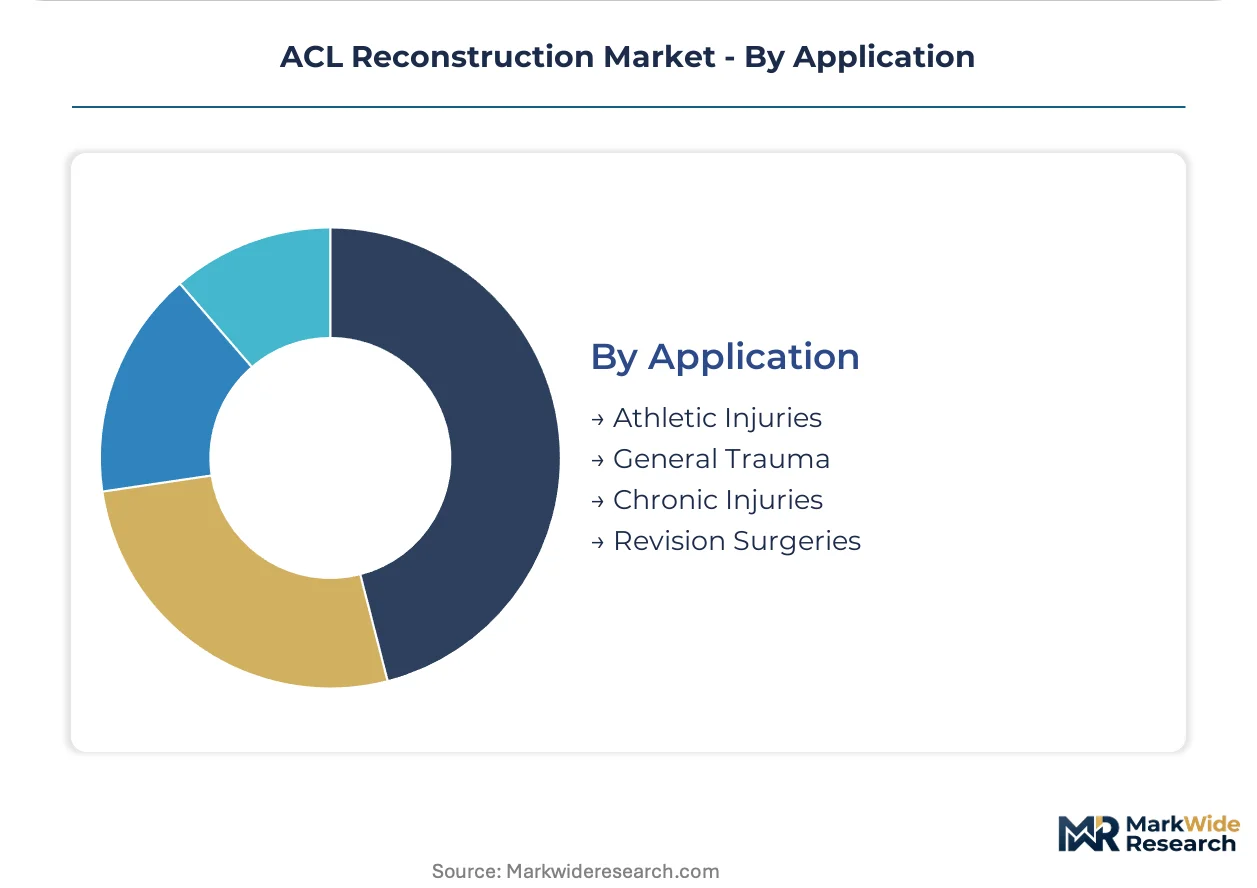
Application:
Acuity and patient profile separate high-volume primary reconstructions from complex revision work that demands specialized instrumentation and graft strategies.
- Athletic Injuries:Complete ACL rupture in competitive athletes drives demand for autograft-dominant protocols with aggressive rehabilitation timelines. Graft selection decisions increasingly hinge on comparative effectiveness data rather than surgeon preference alone.
- General Trauma:Polytrauma patients with multi-ligament knee injuries require staged reconstruction approaches. These cases concentrate in level I trauma centers with 24-hour orthopedic coverage.
- Chronic Injuries:Delayed presentation with meniscal deficiency and articular cartilage damage complicates graft selection and fixation strategy. Patient-reported outcome measures now influence preoperative counseling.
- Revision Surgeries:Graft failure with tunnel osteolysis demands allograft or quadriceps tendon autograft alternatives and specialized fixation hardware. German arthroscopy centers in Munich and Berlin cluster high-complexity revision demand.
Primary athletic injuries generate the highest procedure volume; revision surgeries are expanding most quickly as earlier reconstruction cohorts age.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Human donor tissue availability in the United States anchors the geographic distribution of allograft supply networks, while specialized arthroscopy equipment manufacturing clusters in Germany and Japan concentrate R&D investment for fixation device innovation.
United States
FDA 510(k) clearance pathways for interference screws and cortical suspension devices compress product development timelines for domestic manufacturers. Ambulatory surgery centers in Florida and Texas are capturing migrating case volume from hospital outpatient departments, creating demand for compact, disposable-heavy procedure kits. NCAA Division I athletic programs in the Southeast drive demand for minimally invasive techniques that compress season-ending recovery periods.
Germany
EU MDR Class III certification requirements for fixation devices filter marginal competitors and consolidate procurement decisions around established manufacturers with robust quality management systems. Munich and Berlin host specialized arthroscopy centers that generate referral network effects for high-complexity revision reconstruction demand. The country's statutory health insurance system increasingly ties graft selection decisions to comparative effectiveness data rather than surgeon preference alone.
Japan
PMDA-mandated biocompatibility testing protocols for synthetic ligament materials require 24-month implantation data from large-animal models, delaying market entry versus FDA timelines. METI funding programs support domestic development of biodegradable scaffold architectures to circumvent permanent implant regulatory burdens. Osaka-based medical device manufacturers concentrate production of arthroscopic visualization systems for export to Asian markets.
United Kingdom
NICE health technology assessment criteria increasingly influence graft selection protocols in NHS trusts, shifting procurement toward evidence-backed autograft-dominant procedures. London teaching hospitals anchor clinical trial networks for novel fixation devices seeking CE marking under EU MDR transitional arrangements. The Midlands region concentrates distribution logistics for allograft tissue imported from United States tissue banks.
Switzerland
Swissmedic certification requirements for class III implants maintain stringent quality benchmarks that domestic manufacturers leverage as competitive differentiation in export markets. The Lake Geneva region hosts orthopedic research institutes collaborating with sports medicine facilities on return-to-play protocol standardization. Zurich-based medical technology companies supply arthroscopic instrument lines to German and Austrian hospital systems.
ACL Reconstruction Market Vendor Landscape
Portfolio diversification dominates the current landscape as manufacturers extend arthroscopic instrument lines into integrated procedure kits and captive tissue processing capabilities. The vendor base stratifies across three tiers: diversified orthopedic conglomerates with full sports medicine portfolios, mid-cap arthroscopy specialists with concentrated fixation device offerings, and emerging synthetic ligament developers navigating extended regulatory timelines. Competitive intensity concentrates on securing ambulatory surgery center contracts, controlling allograft supply consistency, and accelerating robotic-assisted platform adoption.
Among diversified orthopedic conglomerates, Johnson & Johnson (DePuy Synthes), Stryker Corporation, and Zimmer Biomet Holdings, Inc. occupy positions defined by scale-driven procurement advantages and integrated distribution networks. These companies exemplify the tier characterized by comprehensive sports medicine portfolios spanning fixation hardware, arthroscopic instruments, and biologic graft materials. Their market presence anchors competitive dynamics in hospital and ambulatory surgery center channels where bundled contracting preferences favor suppliers with breadth across procedure kits.
| Leading Market Players |
|---|
| Johnson & Johnson (DePuy Synthes) |
| CONMED Corporation |
| Arthrex, Inc. |
| Olympus Corporation |
| B. Braun Melsungen AG |
| Stryker Corporation |
| Zimmer Biomet Holdings, Inc. |
| Karl Storz SE & Co. KG |
| Smith+Nephew plc |
| Others |
Supply Flow & Price Mechanics
Specialized arthroscopy instrument technicians in southern Germany command wage premiums that compress hardware margins for manufacturers serving mid-tier European hospital systems. Labor-cost differentials between Bavarian manufacturing clusters and outsourced assembly operations in Eastern Europe drive three-tier pricing spreads across premium arthroscopic towers, standard fixation kits, and economy-grade disposable instruments.
Pricing Analysis
Service-bundling arrangements separate premium-tier manufacturers offering multi-year maintenance contracts and surgeon training programs from unbundled competitors selling hardware-only configurations. Pricing stratifies across premium, standard, and economy tiers based on CE marking tier and after-sales service depth. Pricing pressure stems from ASC procurement committees demanding disposable-heavy kits that minimize sterilization overhead. Hospital outpatient departments exhibit highest price sensitivity; specialized sports medicine facilities in Munich and Berlin show lowest sensitivity given per-procedure fixation budgets.
Supply Chain Analysis
Freight costs for temperature-controlled allograft tissue shipments from United States tissue banks to European processing centers add 15-20% to landed graft material costs. Supply concentrates in the United States for donor tissue, Germany for arthroscopy instrument manufacturing, and Switzerland for precision fixation components. Raw material dependencies include medical-grade titanium alloys, high-molecular-weight polyethylene suture materials, and cryopreserved tendon matrices. Single-source vulnerability characterizes regional tissue bank networks with uneven geographic coverage. Distribution runs through orthopedic distributor networks serving hospital systems and direct-to-facility contracts with ambulatory surgery centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where captive tissue processing capabilities and in-house graft material production determine margin sustainability. Players are pursuing backward integration into biologic material supply to secure consistency amid donor tissue volatility.
For Market Incumbents: Cement market position by acquiring regional tissue bank networks to secure allograft supply consistency against batch-to-batch mechanical property variation. Expand arthroscopic instrument lines into integrated procedure kits for ambulatory surgery centers capturing migrating case volume. Prioritize CE marking investment under EU MDR Class III pathways to filter marginal competitors from procurement decisions.
For New Entrants and Emerging Players: FDA 510(k) clearance pathways in the United States open a window for novel fixation device developers seeking compressed product development timelines versus EU MDR routes. Target ambulatory surgery center channels in Florida and Texas with compact, disposable-heavy procedure kits. Pursue white-space in quadriceps tendon harvest optimization through ultrasound-guided instrumentation.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap arthroscopy specialists given robotic-assisted platform adoption curves and ASC channel expansion. Long-term viability over the next decade hinges on securing bundled rehabilitation protocol contracts that tie surgical fixation to functional milestone achievement. Watch for inflection signals in German statutory health insurance graft selection criteria shifting toward comparative effectiveness data.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Tissue Processing Acquisition | Arthrex-style backward integration secures supply consistency against donor tissue volatility. |
| Robotic-Assisted Platform Development | Capital equipment automation compresses procedure times and standardizes tunnel placement precision. |
| ASC Channel Direct Contracting | Freestanding surgery centers in Texas and Florida demand disposable-heavy kit configurations. |
| EU MDR Class III Certification Investment | Robust quality management systems filter marginal competitors from German procurement decisions. |
| Quadriceps Tendon Harvest Instrumentation | Ultrasound-guided systems expand patient candidacy and reduce donor-site morbidity profiles. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this ACL reconstruction market assessment. Primary interviews with orthopedic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers combined with FDA 510(k) databases, EU MDR submission records, and hospital procurement databases. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue disclosures.
Data-stream reconciliation across product type, end user, technology platform, and application segments shaped the analytical framework. Modeled dimensions included graft material category, surgical venue tier, capital equipment intensity, and patient acuity profile. CAGRs derived from procedure volume trajectories and per-procedure fixation spend evolution across the projection horizon. Industry-specific inputs incorporated NCAA athletic program injury incidence patterns and German statutory health insurance reimbursement schedule adjustments.
The model assumes a particular technology adoption path; alternative pathways for robotic-assisted surgery would alter the outlook if capital equipment purchase cycles extend beyond typical hospital budget timelines. Forecasts reflect assumptions regarding EU MDR implementation pace, allograft donor tissue availability, and ASC case migration velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedics
Tendon Repair Market
Orthopedics
Costochondritis Market
Orthopedics
Europe Extremity Reconstruction Market
Orthopedics
US Arthritis Market
Orthopedics
Podiatry Services Market
Orthopedics
Genu Recurvatum Market
Orthopedics
Elbow Stiffness Market
Orthopedics
Anti-Osteoporosis Therapy and Fracture Healing Market
Orthopedics
Orthopedic Repair Market
Orthopedics
Kyphosis Market
Orthopedics
Global Osteoarthritis Therapeutics Market
Orthopedics
Rickets Market
Orthopedics
Osteoporosis Treatment Market
Orthopedics
Bilateral Osteoarthritis Treatment Market
Orthopedics
Swollen Knee Treatment Market
Orthopedics
Canine Orthopedics Market