
 Europe Bone Metastasis Market | 2026-2036
Europe Bone Metastasis Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Bone Metastasis Market Foresight
The divergence between premium biologic therapies and commodity bisphosphonate generics is hardening across European reimbursement landscapes. Amgen leverages its RANK ligand inhibitor portfolio to sustain premium positioning in oncology clinics. Fresenius Kabi anchors its presence through generic injectable supply chains that compete aggressively on price in hospital tenders.
Bone metastasis encompasses the pathological colonization of bone by malignant cells originating from primary tumors, typically involving osteolytic or osteoblastic disruption of normal bone remodeling through RANK-RANKL signaling and cytokine-mediated osteoclast activation. The condition demands therapeutic intervention to prevent skeletal-related events including fracture, spinal cord compression, and hypercalcemia. RANK ligand inhibitors command the strongest margin pools among product types due to their biologic complexity and patent-protected status, while radiopharmaceuticals represent the fastest-expanding segment driven by alpha-emitter clinical advances. Intravenous administration dominates hospital workflows, though subcutaneous delivery gains traction in outpatient settings seeking reduced infusion chair time.
EMA centralized marketing authorization requirements shape product entry timelines for bone-targeting agents across EU member states, while national health technology assessment bodies including NICE in the United Kingdom and IQWiG in Germany determine reimbursement thresholds that directly constrain pricing flexibility. The EU Clinical Trials Regulation harmonizes investigator-initiated study protocols for novel radiopharmaceutical combinations. Stakeholders must monitor HTA convergence discussions between France's HAS and Germany's G-BA, as aligned evidentiary standards would reshape competitive dynamics for pipeline entrants.
Market Dynamics
The European bone metastasis market is being reshaped by EMA's accelerated assessment pathway for radiopharmaceuticals, which compresses approval timelines and pulls alpha-emitter therapies into earlier lines of treatment across oncology networks.
Growth Catalysts
- Radiopharmaceutical pipeline expansion:Alpha-emitters like radium-223 and emerging actinium-based compounds are advancing through EMA centralized procedures, creating new therapeutic categories for castration-resistant prostate cancer with bone metastases.
- France's HAS early access schemes:Temporary authorization for use pathways enable reimbursement for bone-targeting radiopharmaceuticals before full marketing authorization, accelerating patient access in university hospital networks.
- Multidisciplinary tumor boards:German university hospitals are institutionalizing bone metastasis as a distinct disease management vertical, driving protocol standardization and volume concentration in specialized centers.
Market Restraints
- Isotope supply fragility:Reactor-produced radium-223 and actinium-225 depend on aging European research reactors in Belgium and the Netherlands, creating geographic concentration risk for radiopharmaceutical manufacturers.
- Biologic manufacturing complexity:RANK ligand inhibitors require mammalian cell culture facilities with multi-year capacity lead times, constraining supply elasticity against demand surges.
- IQWiG benefit assessment thresholds:Germany's health technology assessment body applies stringent incremental cost-effectiveness ratios that frequently downgrade bone-targeting agents to non-reimbursable status.
Strategic Opportunities
- Central and Eastern European expansion:Poland, Czech Republic, and Hungary show underpenetrated radiopharmaceutical infrastructure relative to Western Europe, offering first-mover advantages for therapy access programs.
- Subcutaneous administration formats:Outpatient oncology clinics in Spain and Italy are adopting subcutaneous bisphosphonate and RANK ligand inhibitor delivery to reduce infusion chair utilization and hospital pharmacy costs.
- EU Green Deal pharmaceutical manufacturing incentives:Sustainable production certifications for biologic manufacturing facilities unlock preferential tender positioning in Nordic procurement frameworks.
Industry Challenges
- Radiopharmaceutical logistics coordination:Short half-lives of therapeutic isotopes require synchronized production, customs clearance, and patient scheduling across national borders, straining cold chain and nuclear pharmacy capabilities.
- Cross-border reimbursement fragmentation:Divergent national health technology assessment methodologies between France's HAS, Germany's G-BA, and England's NICE create parallel evidentiary requirements that prolong market access timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Bone Metastasis Market |
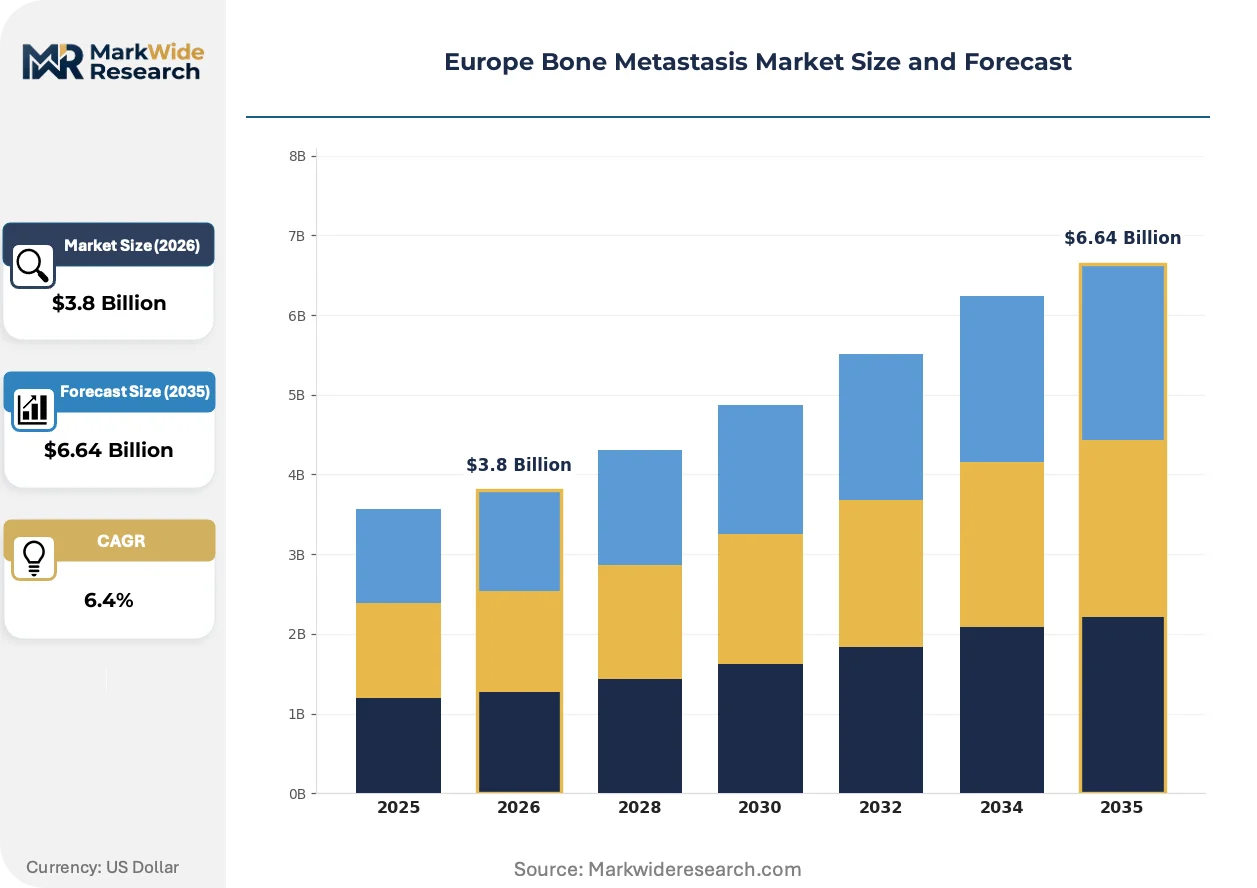
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bone-Targeting Agents, Bisphosphonates, RANK Ligand Inhibitors, Radiopharmaceuticals End User: Oncology Clinics, Research Institutions, Hospitals, Specialty Pharmacies Treatment Approach: Chemotherapy, Immunotherapy, Targeted Therapy, Palliative Care Administration Route: Intravenous, Subcutaneous, Oral, Local Injection |
| Companies Covered | Pfizer, Amgen, F. Hoffmann-La Roche, Medtronic, Fresenius Kabi, Bayer, Novartis, Boston Scientific, Merck, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Bone Metastasis Market Shifts & Advancements
Alpha-emitter radiopharmaceuticals are compressing treatment paradigms in bone metastasis care, unifying diagnostic and therapeutic functions while pulling manufacturing investment toward specialized isotope production infrastructure.
Theranostic platforms combining gallium-68 PET imaging with lutetium-177 or actinium-225 therapy is unifying patient selection and treatment monitoring workflows. Major oncology centers in Germany and France are consolidating these capabilities into dedicated nuclear medicine theranostic units. This convergence is compressing the traditional separation between diagnostic radiology and therapeutic oncology, creating integrated revenue pools that favor academic medical centers with cyclotron access.
EMA's 2023 revision to the radiopharmaceuticals guideline introduced streamlined quality and non-clinical requirements for well-established radionuclides. This regulatory recalibration reduces development costs for bone-seeking agents using calcium mimetics or phosphonate carriers. Smaller biotechnology developers in Switzerland and the Netherlands are responding by advancing novel alpha-emitter constructs through the centralized procedure rather than national pathways.
Hospital procurement consortia in Italy and Spain are consolidating radiopharmaceutical purchasing through centralized tenders that bundle isotope supply with administration services. These aggregated contracts displace traditional distributor relationships and shift margin capture toward logistics-integrated suppliers with direct cyclotron or generator access. The model is most visible in Lombardy and Catalonia, where regional health authorities have consolidated nuclear medicine procurement across multiple hospital networks.
Europe Bone Metastasis Market Segmentation
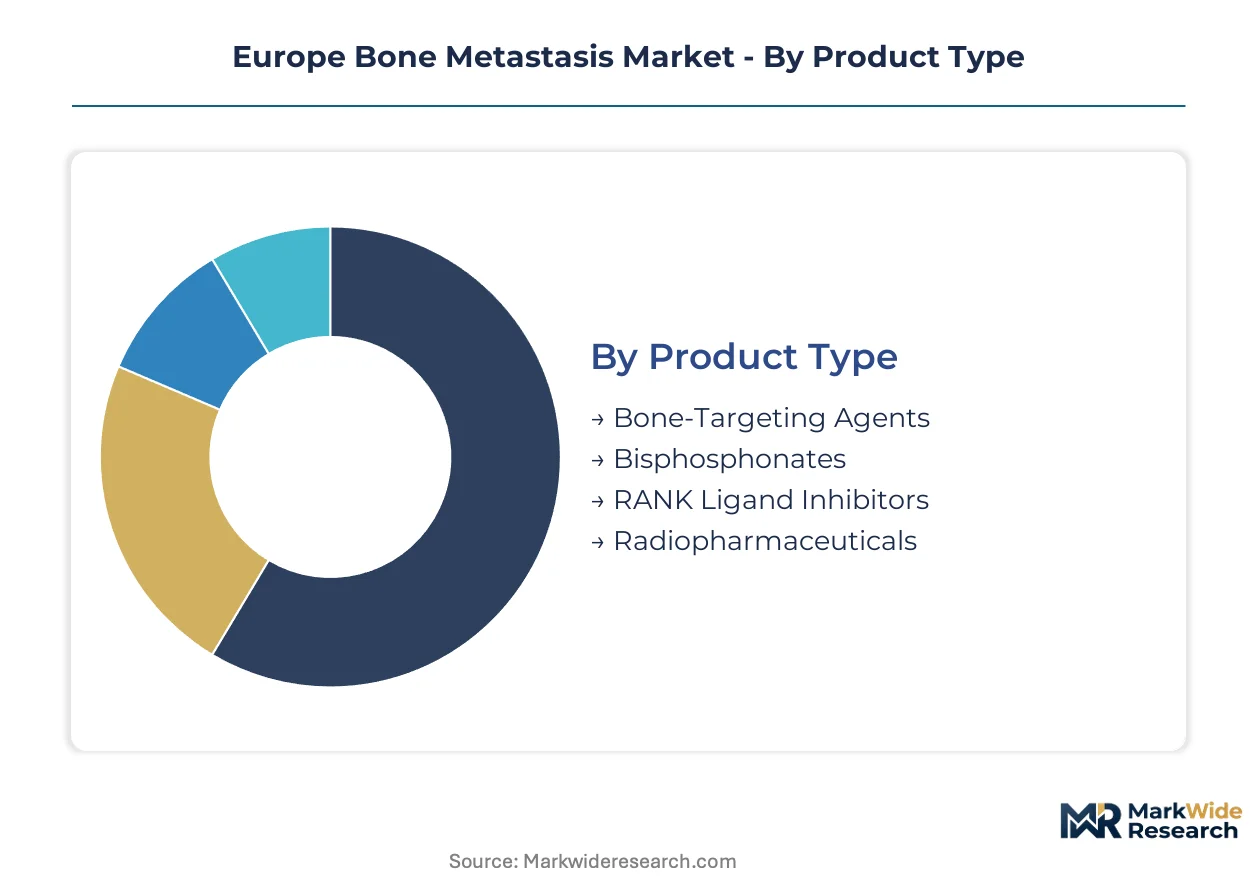
Segmentation in the Europe bone metastasis market reveals how supply chain configurations, reimbursement pathways, and clinical workflows fragment demand across distinct product and service categories. Understanding these divisions exposes where margin pools concentrate and where access barriers persist.
Product Type:
Supply concentration varies sharply across product categories, with biologic manufacturing capacity constraining availability of high-margin therapies while generic production floods commoditized segments.
- RANK Ligand Inhibitors:These monoclonal antibodies block the RANK-RANKL signaling pathway to suppress osteoclast-mediated bone destruction. Manufacturing requires mammalian cell culture facilities with multi-year capacity lead times. Demand concentrates in German university hospitals where G-BA reimbursement decisions determine formulary placement, and supply elasticity remains chronically tight against oncology clinic demand surges.
- Radiopharmaceuticals:Alpha-emitters like radium-223 and emerging actinium-based compounds deliver targeted cytotoxic radiation to bone metastases. Production depends on aging research reactors in Belgium and the Netherlands, creating geographic chokepoints. French HAS early access schemes accelerate patient availability before full EMA authorization, pulling these therapies into earlier treatment lines.
- Bisphosphonates:Generic injectable and oral formulations inhibit osteoclast activity through mineral binding. Fresenius Kabi and other injectable suppliers compete aggressively on price in hospital tenders across Spain and Italy.
- Bone-Targeting Agents:Small molecule calcium mimetics and phosphonate carriers localize to bone remodeling sites. EMA's 2023 radiopharmaceutical guideline revision streamlines development for well-established radionuclide conjugates.
Today's leader: RANK Ligand Inhibitors. Tomorrow's challenger: Radiopharmaceuticals.
End User:
Cost tier differentiation separates high-complexity academic centers from community oncology practices, with reimbursement mechanisms determining where novel therapies launch first.
- Hospitals:Academic medical centers in Germany and France anchor multidisciplinary bone metastasis networks with integrated nuclear medicine and radiation oncology capabilities. These institutions capture radiopharmaceutical revenue pools through theranostic service lines combining gallium-68 PET imaging with lutetium-177 or actinium-225 therapy.
- Oncology Clinics:Outpatient settings in Spain and Italy adopt subcutaneous administration formats to reduce infusion chair utilization and hospital pharmacy costs. These clinics face tighter margin pressure under regional procurement consolidation.
- Specialty Pharmacies:Nuclear pharmacy operations with direct cyclotron or generator access displace traditional distributor relationships in Lombardy and Catalonia through bundled isotope supply and administration service contracts.
- Research Institutions:Investigator-initiated studies under EU Clinical Trials Regulation harmonization advance novel radiopharmaceutical combinations through centralized protocols.
Premium positioning belongs to Hospitals. Volume expansion favors Oncology Clinics.
Treatment Approach:
Application urgency separates curative-intent systemic therapy from symptom-focused interventions, with regulatory pathways and clinical evidence standards diverging accordingly.
- Targeted Therapy:Precision agents directed at molecular drivers in bone metastatic disease require companion diagnostic infrastructure and biomarker testing networks concentrated in Western European academic centers.
- Immunotherapy:Checkpoint inhibitors and cellular therapies demonstrate emerging efficacy in select bone metastasis histologies, though bone microenvironment immunosuppression complicates response assessment.
- Chemotherapy:Cytotoxic regimens retain role in hormone-refractory prostate and breast cancer bone metastases, with administration protocols standardized through German tumor board networks.
- Palliative Care:Pain management and skeletal-related event prevention dominate late-line treatment, with radiopharmaceuticals displacing external beam radiation in oligometastatic bone disease.
Clinical investment flows to Targeted Therapy. Patient volume concentrates in Palliative Care.
Administration Route:
Customer workflow preferences drive format innovation, with outpatient economics favoring reduced chair time and hospital pharmacy cost structures.
- Intravenous:Dominates hospital workflows for bisphosphonates and RANK ligand inhibitors, requiring infusion center capacity and nursing supervision that constrains patient throughput.
- Subcutaneous:Gaining traction in Spanish and Italian outpatient clinics seeking to decompress infusion chair utilization and reduce pharmacy preparation complexity.
- Oral:Limited to selected bisphosphonate formulations with bioavailability challenges and gastrointestinal tolerability concerns affecting adherence.
- Local Injection:Reserved for radiopharmaceutical administration requiring nuclear medicine specialist handling and specialized waste management protocols.
Workflow efficiency favors Intravenous. Format innovation targets Subcutaneous.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany captures the largest share of bone metastasis treatment volume across Europe, while France accelerates patient access through early reimbursement schemes that outpace neighboring markets.
Germany
University hospitals in Berlin, Munich, and Heidelberg anchor multidisciplinary bone metastasis networks with integrated nuclear medicine capabilities. IQWiG benefit assessments constrain pricing flexibility for novel agents, forcing manufacturers to demonstrate incremental clinical value against established bisphosphonate protocols. The G-BA's stringent cost-effectiveness thresholds concentrate premium therapy adoption in academic centers with research funding offsets.
France
HAS temporary authorization for use pathways pull alpha-emitter radiopharmaceuticals into earlier treatment lines before full EMA marketing authorization. Paris and Lyon university hospital networks capture theranostic revenue pools through consolidated gallium-68 PET imaging and lutetium-177 therapy services. National reimbursement pre-approval reduces access delays that plague German and UK markets.
United Kingdom
NICE technology appraisals create extended evidentiary review periods that delay formulary placement for bone-targeting agents. London's Royal Marsden and Manchester's Christie Hospital concentrate radiopharmaceutical expertise amid patchy regional availability. Devolved health administration in Scotland and Wales produces divergent access timelines within the same regulatory jurisdiction.
Italy
Lombardy and Catalonia-style procurement consolidation has not yet reached Italian nuclear medicine services, preserving traditional distributor relationships. Milan's Istituto Nazionale dei Tumori and Rome's Policlinico Gemelli anchor subcutaneous administration adoption in outpatient oncology clinics seeking reduced infusion chair utilization. Regional health authority fragmentation sustains pricing variability across northern and southern treatment centers.
Spain
Andalusian and Catalan regional health authorities pioneer bundled radiopharmaceutical tenders that combine isotope supply with administration logistics. Barcelona's Hospital Clínic and Madrid's Hospital 12 de Octubre institutionalize theranostic workflows for prostate cancer bone metastases. Subcutaneous bisphosphonate delivery gains traction in community oncology settings seeking pharmacy cost reduction.
Europe Bone Metastasis Market Competitive Landscape
Top-tier vendors anchor biologic therapy segments through patent-protected RANK ligand inhibitors, while generic injectable suppliers compete aggressively on price in hospital tenders. Mid-scale radiopharmaceutical developers concentrate around alpha-emitter manufacturing partnerships with European reactor facilities. Strategic archetypes include mammalian cell culture biologic manufacturers, reactor-dependent isotope suppliers, and hospital-integrated nuclear pharmacy operators. Dominant competitive moves center on EMA centralized marketing authorization pursuit and subcutaneous formulation development for outpatient clinic penetration.
Within the biologic therapy tier, Amgen and Novartis occupy positions representing RANK ligand inhibitor archetypes with multi-year manufacturing capacity lead times. Among radiopharmaceutical developers, Bayer exemplifies the reactor-access-dependent model for alpha-emitter supply chain control. Fresenius Kabi anchors the generic injectable supplier archetype competing through hospital tender aggregation across Southern European markets.
| Leading Market Players |
|---|
| Pfizer |
| Amgen |
| F. Hoffmann-La Roche |
| Medtronic |
| Fresenius Kabi |
| Bayer |
| Novartis |
| Boston Scientific |
| Merck |
| Others |
Supply & Pricing Matrix
German university hospital procurement consortia anchor pricing power for bone-targeting agents, compressing margins through aggregated tender volumes while France's HAS early access schemes preserve premium positioning for radiopharmaceutical innovators.
Pricing Analysis
Bundled theranostic service contracts in France and unbundled isotope-only supply in Germany create divergent pricing models across European markets. Three-tier pricing structure across premium biologics, mid-tier radiopharmaceuticals, and economy bisphosphonate generics reflects manufacturing complexity and patent status. Pricing pressure stems from IQWiG cost-effectiveness thresholds that downgrade novel agents to non-reimbursable status in Germany. Oncology clinics in Southern Europe exhibit highest price sensitivity due to regional procurement fragmentation, while academic medical centers in France and Germany show lowest sensitivity where research funding offsets acquisition costs.
Supply Chain Analysis
Specialized nuclear pharmacy workforce scarcity in Belgium and the Netherlands constrains alpha-emitter production capacity expansion despite reactor availability. Manufacturing concentrates in Belgium's BR2 reactor facility, the Netherlands' Petten research reactor, and German mammalian cell culture sites for biologic production. Raw material dependencies include radium-223 chloride, actinium-225 nitrate, and CHO cell culture media. Single-source vulnerability around aging European research reactors creates geographic concentration risk for radiopharmaceutical manufacturers. Distribution runs through hospital-integrated nuclear pharmacy operations with direct cyclotron access, displacing traditional wholesale channels in consolidated procurement regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in subcutaneous formulation shifts that reduce hospital pharmacy handling costs, and in theranostic service bundling that captures diagnostic-to-treatment revenue streams.
For Market Incumbents: Lock in radiopharmaceutical supply agreements with Belgium's BR2 and Netherlands' Petten reactor operators before capacity constraints tighten. Secure G-BA orphan drug designation pathways in Germany to bypass standard IQWiG cost-effectiveness thresholds for novel alpha-emitter therapies. Threats include emerging actinium-225 producers in Poland and Czech Republic that could erode Western European supply dominance. For New Entrants and Emerging Players: EMA's 2023 radiopharmaceutical guideline revision opens a window for streamlined centralized marketing authorization of bone-seeking agents using well-established radionuclides. Target Poland, Czech Republic, and Hungary where radiopharmaceutical infrastructure remains underpenetrated relative to Western European adoption rates. Pursue subcutaneous bisphosphonate formulations for Italian and Spanish outpatient clinics seeking reduced infusion chair utilization. For Investors and Strategic Acquirers: Large-cap biopharmaceutical manufacturers with existing oncology portfolios are the most active acquirer in this space, seeking radiopharmaceutical assets to complement immuno-oncology pipelines. Long-term viability hinges on theranostic platform integration capabilities spanning gallium-68 imaging and lutetium-177 or actinium-225 therapy. Monitor EMA centralized procedure approval timelines for novel alpha-emitter constructs as inflection indicators for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | Spanish and Italian outpatient clinics adopt reduced-infusion formats to decompress chair utilization. |
| Reactor Supply Agreement | Belgium's BR2 and Netherlands' Petten facilities anchor alpha-emitter production capacity for European markets. |
| Theranostic Service Integration | Paris and Lyon university hospitals consolidate gallium-68 PET imaging with lutetium-177 therapy revenue streams. |
| EMA Centralized Procedure Pursuit | Swiss and Dutch biotechnology developers leverage streamlined quality requirements for bone-seeking agents. |
| Central and Eastern European Expansion | Poland, Czech Republic, and Hungary offer first-mover advantages for therapy access program establishment. |
Research Methodology
Direct dialogue with nuclear medicine specialists, hospital pharmacy directors, EMA regulatory affairs leads, and health technology assessment officers combined with secondary validation from EMA centralized procedure filings, ClinicalTrials.gov investigator-initiated study records, and national reimbursement database extracts. Bottom-up patient volume modeling across German, French, UK, Italian, and Spanish treatment centers triangulated with top-down pharmaceutical sales audit data.
Segmentation outputs reflect treatment approach, product type, administration route, and end-user facility tier across the projection horizon. CAGRs derive from patient incidence projections, therapy line penetration assumptions, and pricing trajectory modeling under varying reimbursement scenarios. Forecast inputs incorporate EMA approval timeline distributions, reactor production capacity constraints, and HTA body evidentiary requirement evolution.
Forecast precision tightens around the base case; tail outcomes carry wider variance under radiopharmaceutical reactor shutdown scenarios or G-BA reimbursement downgrades. Practitioners should monitor EMA radiopharmaceutical guideline revisions, Belgian and Dutch reactor maintenance schedules, and HAS-G-BA HTA convergence discussions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedics
Hallux Rigidus Market
Orthopedics
Osteoporosis Treatment Market
Orthopedics
Orthopedic Pillow Market
Orthopedics
Hips and Knees Reconstructive Market
Orthopedics
Orthopedic Repair Market
Orthopedics
Athletic Knee Treatment Market
Orthopedics
Plantar Fasciitis Market
Orthopedics
Osteonecrosis Treatment Market
Orthopedics
Bilateral Osteoarthritis Treatment Market
Orthopedics
Swollen Knee Treatment Market
Orthopedics
Orthopedic Soft Tissue Repair Market
Orthopedics
Canine Orthopedics Market
Orthopedics
Rickets Market
Orthopedics
United States Orthopedic Braces and Support Market
Orthopedics
Costochondritis Market
Orthopedics
Tendon Repair Market