
 Bioresorbable Coronary Scaffolds Market | 2026-2036
Bioresorbable Coronary Scaffolds Market Size, Share, and Industry Trends Forecast 2026-2036
Bioresorbable Coronary Scaffolds Market Outlook
Academic medical centers and specialized cardiology clinics is reorganizing procurement priorities around bioresorbable platforms, shifting volume away from general hospitals that historically dominated stent purchasing. Abbott Laboratories leverages polymer science expertise to sustain leadership in scaffold thickness reduction. Biotronik SE & Co. KG anchors its competitive position through integrated catheter-scaffold delivery systems. Meril Life Sciences Pvt. Ltd. differentiates via cost-optimized manufacturing that competes aggressively in price-sensitive Asian markets.
Bioresorbable coronary scaffolds are temporary implantable devices fabricated from polymers such as poly-L-lactic acid or magnesium alloys, engineered to provide radial support during vessel healing before complete metabolic absorption within 24-36 months. Their primary purpose is restoring coronary lumen patency without leaving permanent foreign material that provokes late adverse events. Polymer-based scaffolds occupy the dominant revenue position due to extensive clinical validation and established supply chains, while metallic scaffolds—particularly magnesium platforms—represent the fastest-growing category as manufacturers resolve early-generation corrosion control limitations. The balloon catheter delivery mode captures the largest procedure volume, though drug-coated delivery systems concentrate margin pools through premium pricing tied to antiproliferative agent integration.
The FDA maintains stringent premarket approval requirements for bioresorbable scaffolds, mandating extended follow-up data that shapes trial design and commercialization timelines for all manufacturers seeking US market access. Europe's MDR framework and EMA oversight impose additional clinical evidence burdens that filter out undercapitalized competitors. China's NMPA has accelerated review pathways for innovative cardiovascular devices, creating alternative regulatory momentum. Stakeholders must monitor how real-world evidence requirements evolve across these jurisdictions to determine optimal sequencing of regulatory submissions and commercial investments.
Market Dynamics
Cardiology clinics are reorganizing procurement priorities around bioresorbable platforms, shifting volume away from general hospitals that historically dominated stent purchasing and creating new competitive entry points for specialized manufacturers.
Growth Catalysts
- Europe's MDR framework:The updated medical device regulation accelerates clinical trial investments by mandating enhanced clinical evidence standards, filtering out undercapitalized competitors and strengthening positions for established scaffold developers.
- Polymer science advancement:Continuous refinement of poly-L-lactic acid formulations improves radial strength and absorption predictability, addressing early-generation performance limitations that constrained physician confidence.
- German reimbursement pathways:Mature interventional cardiology procedure codes enable predictable hospital budgeting for bioresorbable scaffold adoption, concentrating initial European demand in this market.
Market Restraints
- Extended FDA premarket timelines:The agency's stringent approval requirements mandate follow-up data collection that stretches commercialization timelines and consumes disproportionate capital relative to metallic stent pathways.
- Magnesium alloy corrosion control:Metallic scaffold platforms face persistent technical limitations in managing degradation rates, constraining their addressable patient populations despite faster resorption profiles.
- Polymer raw material concentration:Specialized bioresorbable polymer supply chains concentrate among limited chemical manufacturers, creating input cost volatility and qualification bottlenecks for scaffold producers.
Strategic Opportunities
- China's NMPA accelerated review:The national medical products administration has established priority pathways for innovative cardiovascular devices, creating regulatory momentum distinct from Western approval timelines.
- Drug-coated delivery convergence:Integration of antiproliferative agents with bioresorbable platforms opens premium pricing tiers currently captured by drug-eluting metallic stents.
- Specialized catheter-scaffold systems:Integrated delivery device development creates differentiation beyond the scaffold itself, capturing margin pools in the interventional cardiology workflow.
Industry Challenges
- Interventional cardiologist training gaps:Deployment techniques for bioresorbable scaffolds differ meaningfully from metallic stent procedures, requiring dedicated proctoring programs that strain commercial team bandwidth.
- Real-world evidence generation:Post-market surveillance requirements across FDA, EMA, and NMPA jurisdictions demand coordinated registry investments that fragment quality assurance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bioresorbable Coronary Scaffolds Market |
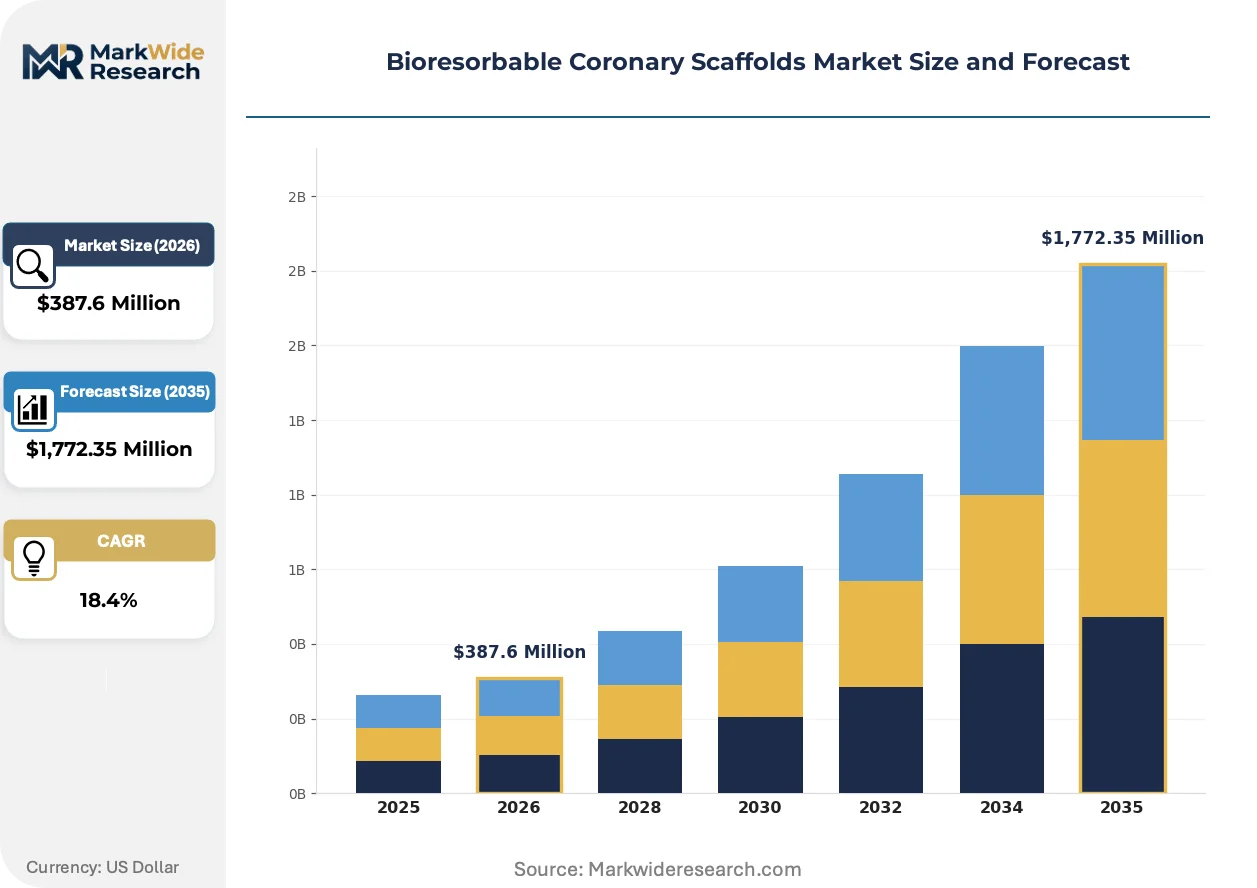
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,772.35 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer-based Scaffolds, Metallic Scaffolds, Composite Scaffolds, Bioactive Scaffolds Delivery Mode: Balloon Catheter, Drug-coated Delivery, Self-expanding Systems, Manual Delivery End User: Cardiology Clinics, Hospitals, Research Institutes, Surgical Centers Application: Coronary Artery Disease, Angioplasty, Vascular Grafting, Drug Delivery |
| Companies Covered | Abbott Laboratories, Boston Scientific Corporation, Biotronik SE & Co. KG, Terumo Corporation, Elixir Medical Corporation, REVA Medical, MicroPort Scientific Corporation, Meril Life Sciences Pvt. Ltd., Amaranth Medical Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bioresorbable Coronary Scaffolds Market Strategic Shifts
Scaffold thickness reduction is compressing the performance gap with metallic alternatives while regulatory frameworks evolve to accommodate accelerated evidence generation. These forces are reshaping competitive positioning across material science and clinical trial design.
Polymer-based scaffold technology is miniaturizing strut dimensions below 100 micrometers while maintaining radial strength sufficient for coronary lesion support. Academic medical centers in Germany and the United States are piloting these ultra-thin platforms in complex bifurcation cases previously reserved for metallic alternatives. This miniaturization is enabling expansion into patient anatomies previously excluded from bioresorbable candidacy, broadening addressable procedure volumes.
Europe's MDR clinical evidence requirements are extending follow-up obligations for bioresorbable devices beyond metallic stent comparators, forcing manufacturers to redesign trial architectures around five-year outcome tracking. The regulatory burden falls most heavily on polymer-based platforms with longer absorption timelines, prompting strategic portfolio rebalancing toward faster-resorbing magnesium alternatives. German notified bodies are interpreting these requirements most stringently, creating divergence in CE marking timelines across European jurisdictions.
Hospital purchasing committees are consolidating stent procurement authority from individual cardiologists to centralized value analysis teams, compressing vendor negotiation cycles and demanding outcome guarantees. General hospitals with mixed interventional volumes are ceding bioresorbable decisions to specialized cardiology clinics with concentrated procedure expertise. This concentration is most visible in United States metropolitan markets where academic medical center networks control referral patterns and device formulary access.
Bioresorbable Coronary Scaffolds Market Segmentation
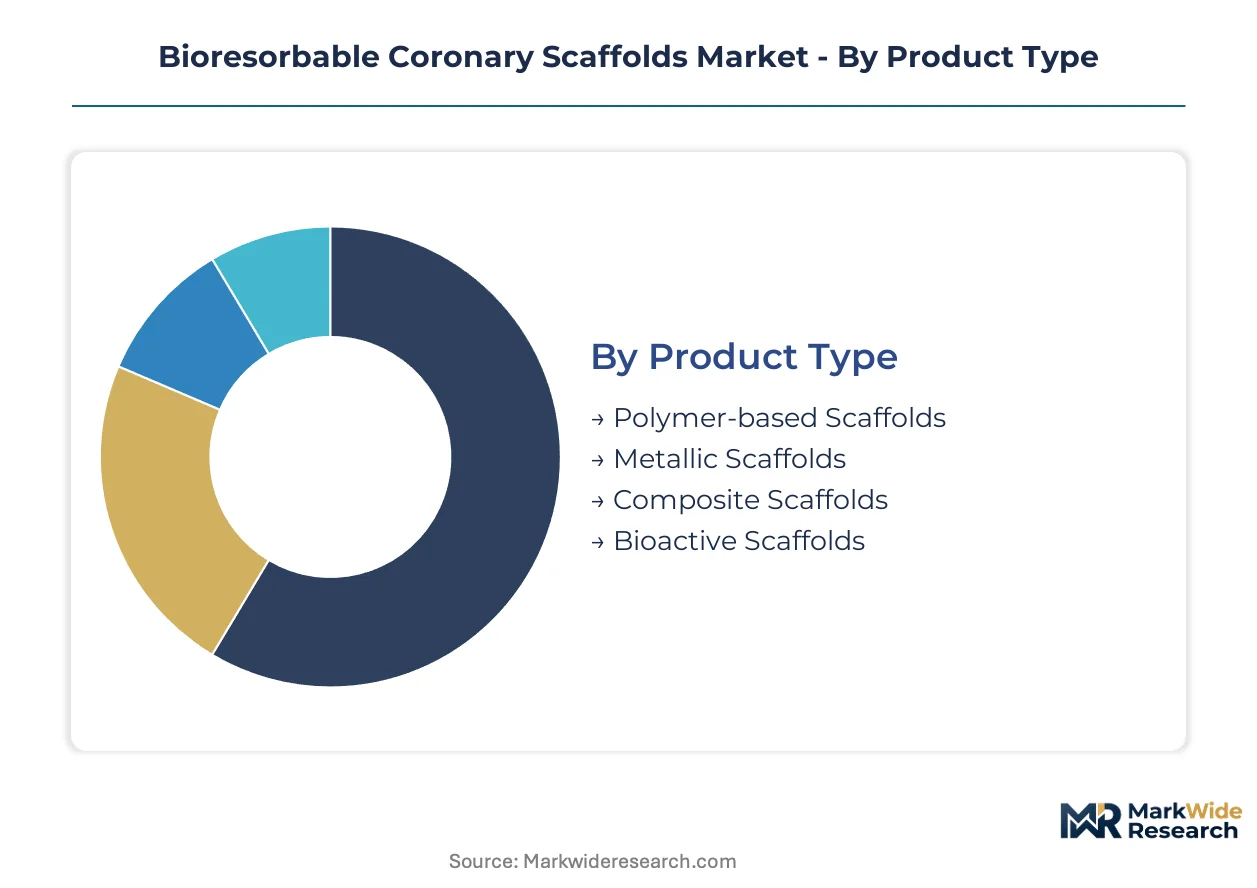
Segmentation in bioresorbable coronary scaffolds reveals how material science, delivery technology, and care setting economics intersect to determine commercial viability. Each dimension carries distinct regulatory pathways and reimbursement implications that reshape competitive priorities across manufacturers.
Product Type:
FDA premarket approval timelines vary substantially by material class, with polymer platforms facing extended follow-up obligations that metallic alternatives are beginning to circumvent through accelerated degradation profiles.
- Polymer-based Scaffolds:Fabricated primarily from poly-L-lactic acid or polyglycolic acid, these devices dominate current procedure volumes through established radial strength profiles and predictable 24-36 month absorption kinetics. German cardiology clinics concentrate procurement of these platforms where mature reimbursement codes enable predictable budgeting for interventional procedures.
- Metallic Scaffolds:Magnesium alloy constructions achieve complete resorption within 12-18 months, addressing physician preference for faster foreign material clearance. China's NMPA has prioritized review pathways for these devices, creating regulatory momentum distinct from Western polymer-centric frameworks.
- Composite Scaffolds:Hybrid polymer-metallic architectures attempt to balance radial strength with controlled degradation.
- Bioactive Scaffolds:Surface-modified platforms incorporate endothelialization promoters or antiproliferative coatings.
Established volume favors polymer-based scaffolds; emerging adoption favors metallic scaffolds.
Delivery Mode:
Cost tier differentiation separates premium-integrated systems from commodity balloon platforms, with margin concentration tracking antiproliferative agent sophistication rather than mechanical delivery alone.
- Balloon Catheter:The standard deployment mechanism captures baseline procedure economics across all geographies. United States hospital purchasing committees negotiate these devices through centralized value analysis teams that demand outcome guarantees.
- Drug-coated Delivery:Integration of sirolimus or everolimus with bioresorbable matrices commands premium pricing tiers previously captured by drug-eluting metallic stents. Cardiology clinics in Western Europe drive concentrated demand for these systems where procedure reimbursement accommodates device cost differentials.
- Self-expanding Systems:Nitinol-assisted deployment mechanisms address tortuous anatomy cases.
- Manual Delivery:Bare scaffold platforms without integrated delivery systems serve cost-sensitive markets.
Procedure volume concentrates in balloon catheter platforms; margin expansion clusters in drug-coated delivery systems.
End User:
Customer type reconfiguration is shifting procurement authority from general hospitals toward specialized intervention centers with concentrated expertise and dedicated proctoring capabilities.
- Cardiology Clinics:Specialized intervention centers with high procedural volumes are capturing disproportionate bioresorbable adoption as deployment technique complexity exceeds generalist capability. German metropolitan markets exhibit this concentration most visibly, where academic medical center networks control referral patterns.
- Hospitals:General acute care facilities with mixed interventional volumes retain metallic stent preference due to lower training overhead and established supply chain relationships.
- Research Institutes:Academic medical centers in the United States and Germany drive clinical trial enrollment and first-in-human evaluations of next-generation platforms.
- Surgical Centers:Ambulatory settings with limited cardiac catheterization capabilities represent minimal current uptake.
Volume leadership is consolidating in cardiology clinics; research institutes anchor pipeline access.
Application:
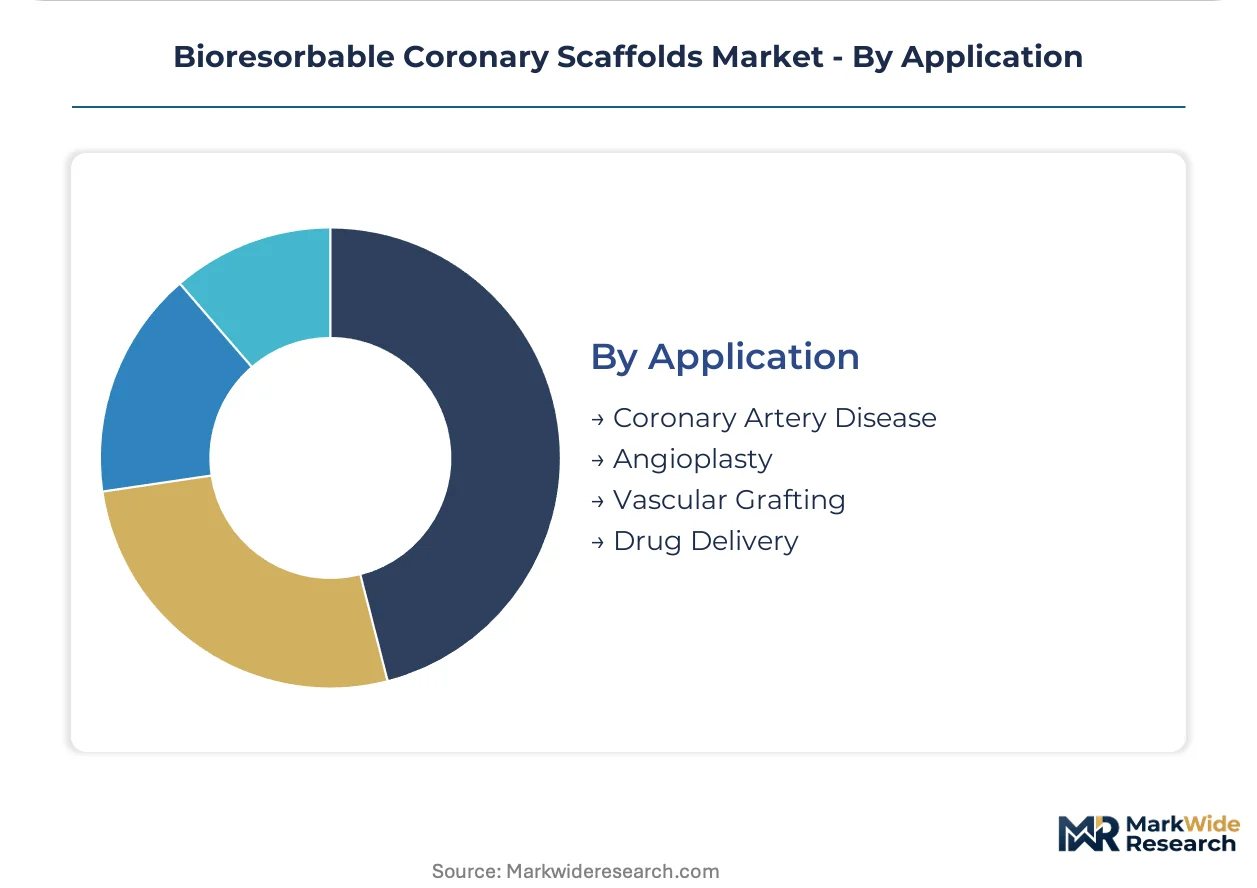
Clinical indication maturity determines reimbursement codification, with coronary interventions enjoying established pathways that vascular grafting and localized drug delivery have yet to secure.
- Coronary Artery Disease:De novo lesion treatment in native vessels represents the validated indication with complete regulatory dossiers across FDA, EMA, and NMPA jurisdictions. United States cardiology clinics drive procedural volume where commercial payers have established coverage determinations.
- Angioplasty:Scaffold-assisted balloon angioplasty procedures are expanding into complex bifurcation lesions previously reserved for metallic alternatives, enabled by strut thickness reduction below 100 micrometers.
- Vascular Grafting:Peripheral and coronary bypass applications remain investigational with limited clinical evidence bases.
- Drug Delivery:Scaffold-as-platform approaches for localized pharmaceutical administration are early-stage development programs.
Revenue concentration rests with coronary artery disease; steepest expansion trajectory appears in angioplasty complexity escalation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Academic medical centers and specialized cardiology clinics concentrate procurement authority in Germany, the United States, China, Japan, and Switzerland. These countries anchor clinical trial enrollment, regulatory precedent, and manufacturing expertise for bioresorbable scaffold platforms.
United States
Cardiology clinics in metropolitan markets drive procedural volume as hospital purchasing committees consolidate authority. The FDA mandates extended premarket approval timelines with five-year follow-up data. Boston and Cleveland anchor clinical trial networks evaluating next-generation magnesium platforms.
Germany
Specialized intervention centers capture disproportionate adoption through mature reimbursement codes for interventional cardiology. The MDR framework imposes stringent clinical evidence requirements through German notified bodies. Munich and Heidelberg concentrate proctoring programs for ultra-thin polymer deployments.
China
Domestic manufacturers compete aggressively on cost-optimized production for price-sensitive patient populations. The NMPA has established accelerated review pathways for innovative cardiovascular devices. Shanghai and Beijing anchor priority regulatory submissions for magnesium alloy platforms.
Japan
Academic medical centers prioritize scaffold thickness reduction in complex bifurcation cases. The PMDA maintains rigorous post-market surveillance requirements for bioresorbable devices. Tokyo and Osaka concentrate first-in-human evaluations of composite scaffold architectures.
Switzerland
Research institutes drive polymer science advancement for controlled degradation kinetics. Swissmedic coordinates with EMA on clinical evidence standards for resorbable implants. Basel and Zurich anchor supply chain relationships for specialized bioresorbable polymer feedstocks.
Bioresorbable Coronary Scaffolds Market Competitive Environment
Player mix skews toward diversified medical technology conglomerates with polymer science or interventional cardiology heritage. Market structure concentrates around three to five established developers with completed regulatory dossiers, while mid-cap specialists pursue niche indications or regional price positioning. Strategic archetypes include integrated catheter-scaffold system builders, pure-play scaffold innovators, and diversified cardiovascular device houses. Dominant competitive moves center on portfolio diversification into drug-coated delivery convergence and geographic expansion through prioritized NMPA submissions.
Among diversified technology conglomerates, Abbott Laboratories and Boston Scientific Corporation exemplify scale-driven archetypes with cardiovascular device breadth, while Biotronik SE & Co. KG occupies a specialized position within integrated catheter-scaffold system development. Meril Life Sciences Pvt. Ltd. represents cost-optimized manufacturing archetypes competing in price-sensitive Asian markets. These three companies anchor distinct competitive vectors without overlapping strategic positioning.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Boston Scientific Corporation |
| Biotronik SE & Co. KG |
| Terumo Corporation |
| Elixir Medical Corporation |
| REVA Medical |
| MicroPort Scientific Corporation |
| Meril Life Sciences Pvt. Ltd. |
| Amaranth Medical Inc. |
| Others |
Value Chain & Pricing Dynamics
Polymer batch-scale economics at specialized chemical manufacturers in Germany and Switzerland create steep minimum efficient scale thresholds that filter out smaller scaffold producers while anchoring price floors for qualified suppliers serving FDA and EMA submission pathways. This concentration simultaneously limits downstream pricing leverage for device manufacturers and protects incumbent feedstock suppliers from commodity-style margin erosion.
Pricing Analysis
Cost-plus contracts with poly-L-lactic acid suppliers typically index to petrochemical feedstock benchmarks, creating predictable but inflexible input cost structures for scaffold manufacturers. Pricing stratifies across drug-coated delivery premiums, standard balloon catheter platforms, and manual delivery economy tiers, with differentiation resting on antiproliferative agent integration and catheter-scaffold system bundling. Cost compression in the manual delivery tier is intensifying as Chinese domestic manufacturers expand magnesium alloy production for NMPA priority review pathways. Cardiology clinics in Western Europe exhibit the lowest price sensitivity due to mature reimbursement codes, while general hospitals in price-sensitive Asian markets drive aggressive vendor negotiation.
Supply Chain Analysis
Inbound logistics costs for specialized bioresorbable polymers have escalated on Rotterdam-Singapore trade lane congestion and container availability constraints at Swiss chemical export hubs. Manufacturing concentration centers on Germany, Switzerland, and China, with polymer synthesis expertise anchored in Basel and Zurich while magnesium alloy processing scales through Shanghai and Beijing. Raw material dependencies include high-purity lactic acid monomers, magnesium ingots with controlled corrosion profiles, and specialized extrusion equipment. Single-source vulnerability persists for medical-grade polymer qualification batches required for FDA premarket approval submissions. Distribution runs through hospital purchasing committee consolidation in the United States and specialized cardiology clinic networks in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Proctoring program expansion and registry maintenance contracts represent faster-expanding recurring revenue layers than scaffold hardware sales alone, transforming device manufacturers into service-anchored platform vendors with stickier hospital relationships.
For Market Incumbents: Compound defensive positioning through backward integration into polymer synthesis capabilities and captive supply of magnesium alloy feedstocks to offset raw material concentration risks. Prioritize CE marking pathway investments under German notified body interpretation of MDR clinical evidence requirements to maintain European market access against emerging metallic scaffold competitors. Channel control through integrated catheter-scaffold system development remains the priority lever for margin defense. For New Entrants and Emerging Players: Anchor in China's NMPA accelerated review pathways for magnesium alloy platforms, the most penetrable regulatory entry point distinct from polymer-centric FDA and EMA frameworks. Target cardiology clinic procurement consolidation in United States metropolitan markets where academic medical center network control creates formulary access chokepoints. Pursue white-space positioning in drug-coated delivery convergence as established metallic stent manufacturers hesitate on bioresorbable antiproliferative integration. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors diversified cardiovascular device houses with polymer science heritage and completed regulatory dossiers across multiple jurisdictions. Long-term viability rests on five-to-ten year real-world evidence generation capabilities and registry infrastructure ownership rather than single-product scaffold approvals. Acquisition target archetype: integrated catheter-scaffold system developers with established German reimbursement relationships. Watch FDA premarket approval timeline compression for magnesium platforms as the inflection signal for metallic scaffold category acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Clinical Evidence Investment | Five-year follow-up data generation satisfies German notified body requirements for CE marking retention. |
| NMPA Priority Review Submission | Accelerated pathways for magnesium alloy platforms bypass Western polymer-centric regulatory timelines. |
| Integrated Catheter-Scaffold Development | Delivery system bundling captures margin pools in interventional cardiology workflow consolidation. |
| Proctoring Program Scale-Up | Deployment technique training addresses interventional cardiologist capability gaps in complex lesion cases. |
| Drug-Coated Delivery Convergence | Antiproliferative agent integration opens premium pricing tiers previously reserved for metallic stents. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with interventional cardiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers; and secondary validation against FDA premarket approval filings, EMA submissions, ClinicalTrials.gov registries, and hospital procurement databases. Bottom-up scaffold shipment estimates by material class and delivery mode were triangulated against top-down interventional cardiology procedure volume projections.
Across the analysis window, the forecasting framework modeled segmentation dimensions including material class degradation kinetics, delivery mode antiproliferative sophistication, end-user procurement authority concentration, and application-specific reimbursement codification maturity. CAGRs were derived from procedure volume elasticity to regulatory approval timelines and pricing tier migration patterns. Forecast inputs incorporated NMPA review pathway velocity differentials and MDR clinical evidence burden evolution.
Underlying assumptions cover stable FDA premarket approval stringency, sustained German reimbursement code maturity, and NMPA priority pathway continuity, with deviation risk concentrated in magnesium alloy corrosion control breakthroughs or polymer raw material supply disruptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global External Fixators Market
Medical Devices
Refurbished Medical Devices Market
Medical Devices
Repositioning and Offloading Devices Market
Medical Devices
France Contraceptive Devices Market
Medical Devices
Medical Device Technologies Market
Medical Devices
Orthokeratology Lens Market
Medical Devices
Ultrasound Probe Market
Medical Devices
Global Breast Surgery Retractors Market
Medical Devices
Laser Therapy Devices Market
Medical Devices
South Korea Minimally Invasive Surgery Devices Market
Medical Devices
Foot Massage Machine Market
Medical Devices
Global Trauma Fixation Devices Market
Medical Devices
Military Wearable Medical Device Market
Medical Devices
Global Insulin Pumps Market
Medical Devices
Bone Conduction Hearing Devices Market
Medical Devices
Home Dialysis Systems Market