
 Anti-Osteoporosis Therapy and Fracture Healing Market | 2026-2036
Anti-Osteoporosis Therapy and Fracture Healing Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Osteoporosis Therapy and Fracture Healing Market Analysis
Denosumab-based biologics are hardening as the preferred alternative to oral bisphosphonates in high-risk fracture populations due to superior adherence profiles and reduced gastrointestinal burden. Eli Lilly and Company leverages its established endocrinology infrastructure to sustain dominance in the anabolic therapy segment. Amgen Inc. anchors the monoclonal antibody category with deep manufacturing scale for rank ligand inhibitors. Pfizer Inc. competes through broad portfolio breadth spanning both hormonal and injectable modalities.
Anti-osteoporosis therapy and fracture healing encompasses pharmacological interventions and biological agents designed to inhibit bone resorption, stimulate osteoblast activity, or accelerate callus formation, typically administered via subcutaneous injection at doses calibrated by bone mineral density T-scores and fracture risk algorithms. The primary commercial purpose centers on reducing hip and vertebral fracture incidence in postmenopausal women and elderly males while shortening union time for traumatic and stress fractures. Bisphosphonates retain the largest volume share but face margin compression as generic oral formulations saturate reimbursement tiers. Monoclonal antibodies command premium positioning where injectable delivery modes penetrate hospital and rehabilitation center formularies. Hormonal therapies occupy a narrowing niche as selective estrogen receptor modulators confront safety labeling constraints.
FDA oversees New Drug Application pathways for novel anabolic agents while EMA's Committee for Medicinal Products for Human Use evaluates centralized marketing authorizations across EU member states, with both agencies tightening cardiovascular safety requirements for long-term osteoporosis regimens. The EU Medical Device Regulation and ISO 13485 standards govern bone graft substitutes and fracture fixation biologics, creating differentiated compliance burdens between pharmaceutical and device pathways. Stakeholders must monitor evolving pharmacovigilance mandates for extended bisphosphonate holidays and emerging real-world evidence requirements for biologic switching protocols.
Market Dynamics
The transition from oral bisphosphonates to injectable biologics is compressing reimbursement hierarchies and forcing formulary managers to recalibrate risk-stratification protocols across hospital systems.
Growth Catalysts
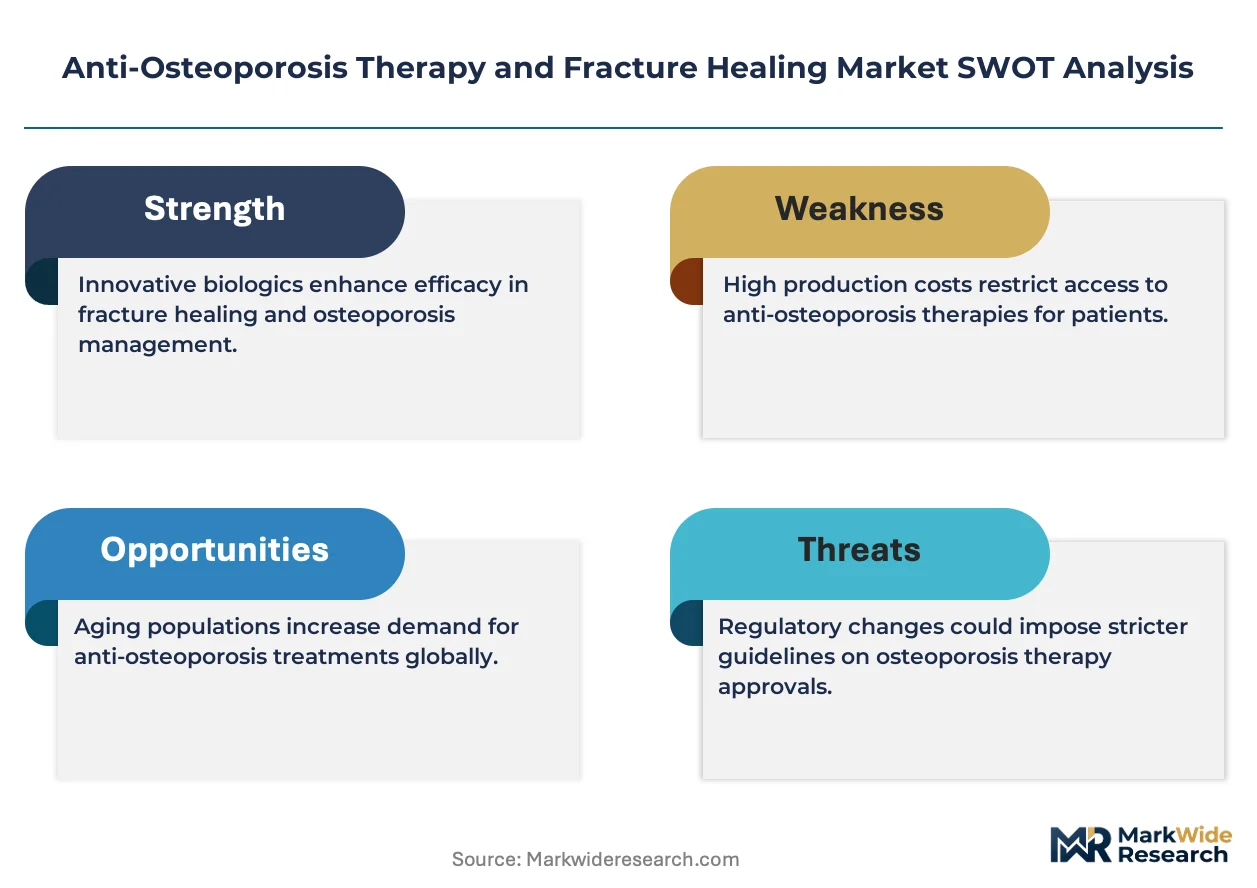
- Aging Demographics in Japan:The world's oldest population drives sustained public reimbursement for bone-density screening and anabolic therapy protocols in tertiary care centers.
- FDA Biosimilar Pathways:Streamlined abbreviated approval routes for rank ligand inhibitors are accelerating competitive entry and expanding patient access to injectable alternatives.
- Biomarker-Guided Dosing:Real-time bone turnover marker integration into fracture risk algorithms enables precision titration of anabolic agents in post-surgical recovery.
Market Restraints
- Extended Bisphosphonate Holidays:FDA-mandated atypical fracture warnings have institutionalized treatment interruptions that erode therapy persistence and commercial continuity.
- Reimbursement Tier Compression:Generic oral alendronate saturation in Medicare Part D formularies caps premium pricing power for novel injectable entrants.
- Cold Chain Infrastructure Gaps:Subcutaneous biologics require uninterrupted temperature control that rural health systems in the United States struggle to maintain.
Strategic Opportunities
- Underpenetrated Male Osteoporosis:Diagnostic protocols in Germany increasingly screen elderly men for vertebral fractures, opening a historically neglected prescription segment.
- EU Medical Device Regulation Convergence:MDR harmonization for bone graft substitutes creates single-market access for synthetic scaffold manufacturers.
- Digital Adherence Monitoring:Bluetooth-enabled injection devices paired with pharmacy benefit managers enable outcome-linked reimbursement contracts.
Industry Challenges
- Specialized Endocrinology Workforce Scarcity:The United States faces insufficient fellowship-trained metabolic bone specialists to manage complex anabolic switching protocols.
- Pharmacovigilance Reporting Burden:EMA's extended follow-up requirements for monoclonal antibodies demand costly post-market surveillance infrastructure that mid-tier manufacturers struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Osteoporosis Therapy and Fracture Healing Market |
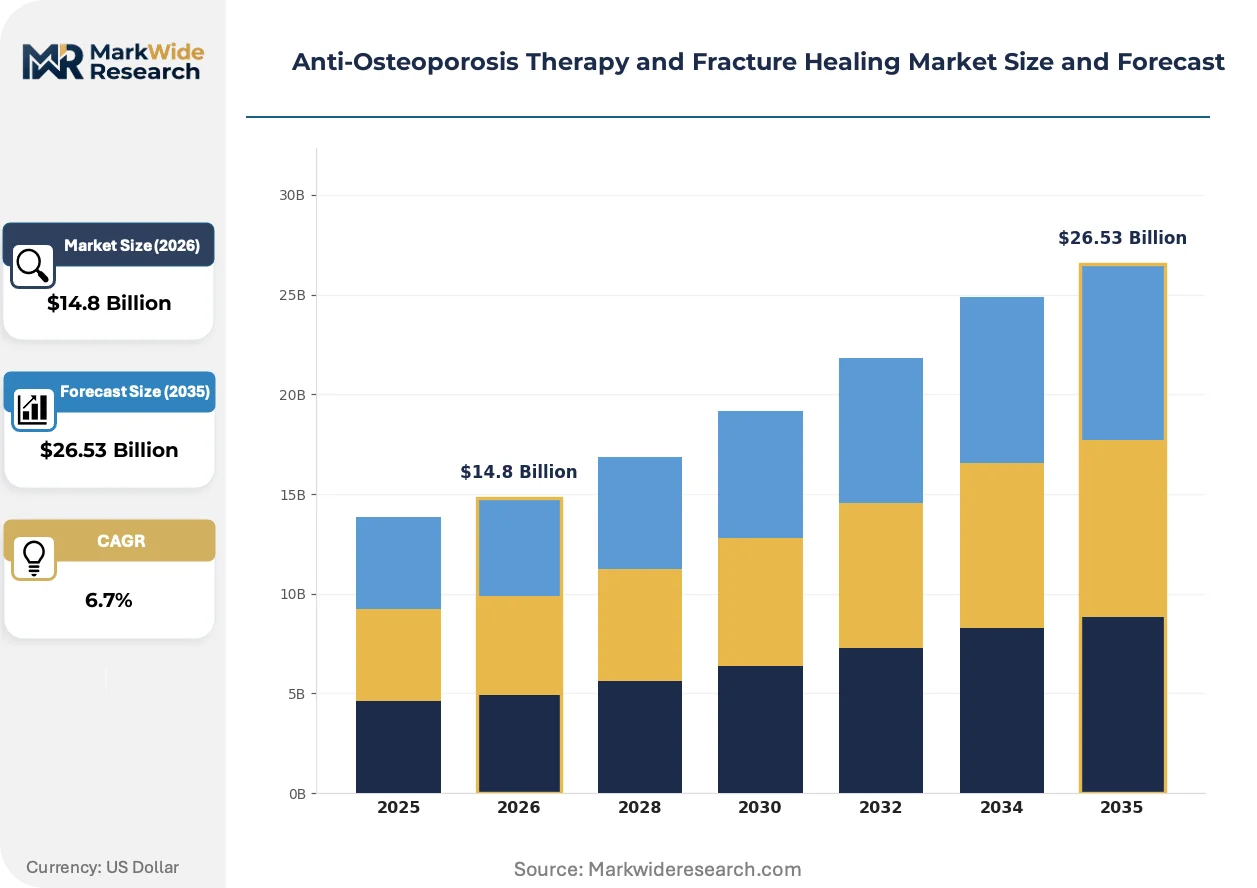
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bisphosphonates, Hormonal Therapies, Monoclonal Antibodies, Calcium Supplements Delivery Mode: Oral, Injectable, Transdermal, Combination Therapy End User: Clinics, Hospitals, Home Care, Rehabilitation Centers Therapy Area: Osteoporosis, Fracture Repair, Bone Density Improvement, Pain Management |
| Companies Covered | Amgen Inc., Eli Lilly and Company, Novartis AG, Pfizer Inc., Merck & Co., Inc., F. Hoffmann-La Roche Ltd., GlaxoSmithKline plc, Sanofi S.A., Teva Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Osteoporosis Therapy and Fracture Healing Market Emerging Trajectories
Injectable delivery platforms and biomarker integration are displacing static dosing paradigms, while regulatory convergence between pharmaceutical and device pathways compresses development timelines.
Romosozumab's dual-action mechanism—simultaneously inhibiting sclerostin and stimulating bone formation—is converging with automated injection devices in United States hospital outpatient departments. Orthopedic surgeons in high-volume trauma centers adopt these combination therapies for complex non-union cases. The convergence is compressing traditional distinctions between metabolic bone disease management and acute fracture repair.
EMA's tightened cardiovascular safety requirements for long-term osteoporosis regimens now mandate extended electrocardiographic monitoring in Phase III trials. This regulatory elevation has delayed approval timelines for novel anabolic candidates by 12-18 months. European sponsors are responding by embedding cardiology endpoints earlier in development to preempt regulatory queries.
Japanese hospital procurement committees increasingly bundle bone-density testing with fracture liaison services, unbundling traditional pharmaceutical-only contracts. This service-integration model displaces standalone drug purchasing in metropolitan Tokyo and Osaka health systems. The shift rewards manufacturers with comprehensive patient-support infrastructure over pure molecule suppliers.
Anti-Osteoporosis Therapy and Fracture Healing Market Segmentation
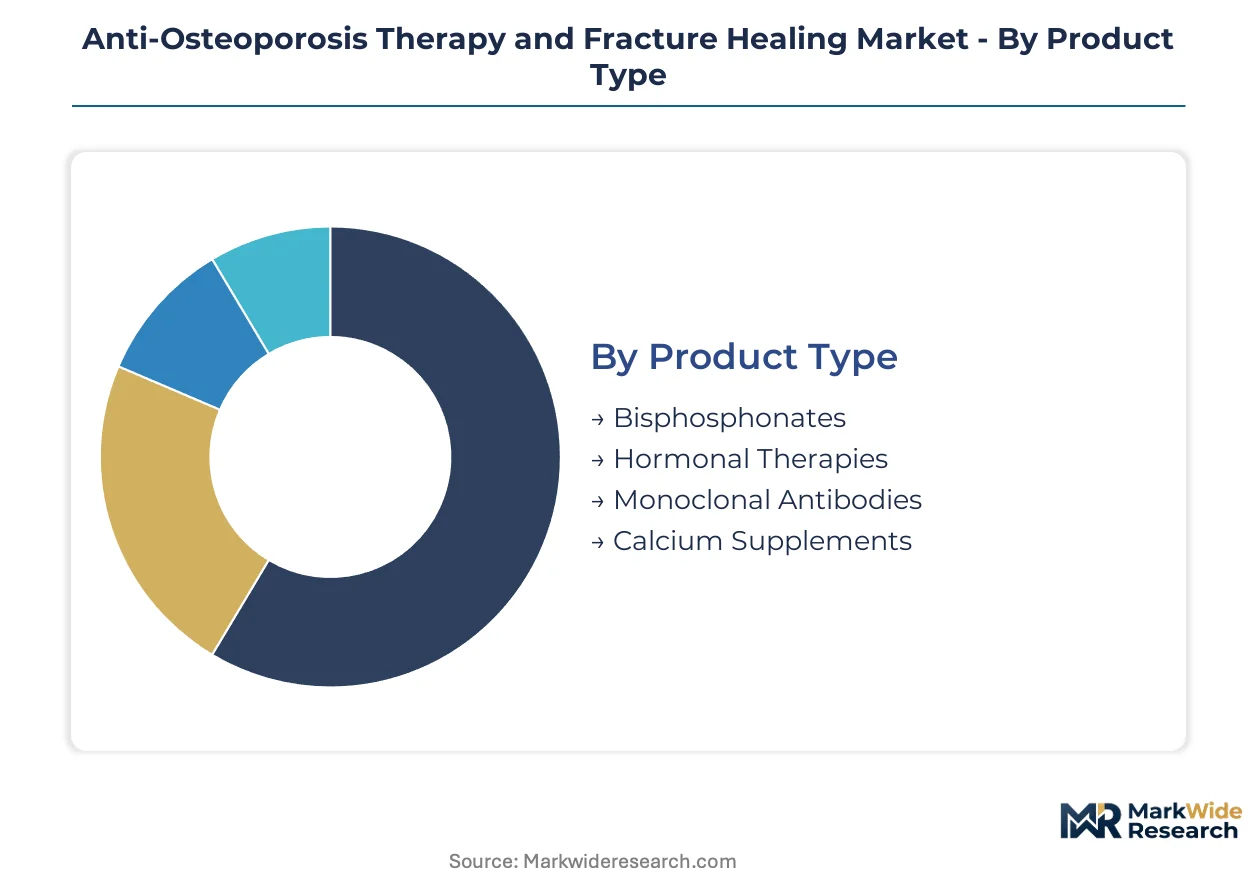
Segmentation in anti-osteoporosis therapy reveals how treatment protocols fragment across delivery technologies, care settings, and therapeutic objectives. Each dimension carries distinct reimbursement logic, infrastructure requirements, and patient adherence profiles that determine commercial viability.
Product Type:
Upgrade cycles from oral generics to biologic alternatives are compressing traditional category boundaries as hospital formularies recalibrate risk-stratification protocols.
- Bisphosphonates:Alendronate and zoledronic acid formulations remain the volume foundation, though generic saturation in Medicare Part D formularies caps pricing power. Demand concentrates in United States retail pharmacy channels where cost-tier pressure from pharmacy benefit managers favors oral compliance programs over clinical efficacy differentiation.
- Monoclonal Antibodies:Denosumab and romosozumab rank-ligand inhibitors command premium positioning through subcutaneous delivery modes that reduce gastrointestinal burden. German hospital outpatient departments lead adoption, driven by fracture liaison service protocols that bundle biologic administration with bone-density monitoring.
- Hormonal Therapies:Selective estrogen receptor modulators occupy narrowing niches as FDA cardiovascular safety labeling constrains long-term prescribing.
- Calcium Supplements:Over-the-counter formulations face margin compression from private-label substitution in United States retail chains.
Volume sits with bisphosphonates; growth tilts toward monoclonal antibodies.
Delivery Mode:
Cost-tier stratification separates hospital-administered injectables from retail-dispensed oral therapies, with cold-chain infrastructure determining geographic penetration ceilings.
- Injectable:Prefilled syringe and autoinjector platforms for denosumab and teriparatide require uninterrupted temperature control that favors metropolitan health systems. Japanese tertiary care centers in Tokyo and Osaka deploy automated injection devices integrated with electronic health record systems to track adherence.
- Oral:Weekly alendronate and monthly ibandronate tablets dominate prescription volume through Medicare Part D preferred drug lists, though gastrointestinal side effects drive discontinuation rates.
- Transdermal:Estrogen patches for postmenopausal bone preservation confront reimbursement tier compression as FDA narrows approved indications.
- Combination Therapy:Sequential anabolic-antiresorptive protocols for severe osteoporosis patients require endocrinology specialist coordination that limits penetration to academic medical centers.
Injectable delivery claims the steepest expansion trajectory as hospital systems consolidate biologic procurement.
End User:
Patient acuity and reimbursement complexity concentrate high-value biologic administration in institutional settings while stable chronic management shifts toward ambulatory alternatives.
- Hospitals:Inpatient fracture liaison services in United States academic medical centers coordinate biologic initiation with orthopedic surgery discharge planning, capturing anabolic therapy episodes under bundled payment models.
- Clinics:Endocrinology and rheumatology practices in Germany manage long-term bisphosphonate holidays and switching protocols through bone turnover marker monitoring.
- Rehabilitation Centers:Post-acute facilities in Japan integrate bone-density testing with fall prevention programs for hip fracture recovery patients.
- Home Care:Self-administered subcutaneous injections expand through specialty pharmacy distribution networks that manage cold-chain logistics for rural United States patients.
Hospital systems capture biologic volume; home care channels are gaining share fastest for established therapies.
Therapy Area:
Application focus determines regulatory pathway complexity, with fracture repair biologics facing device-pharmaceutical convergence requirements that extend development timelines.
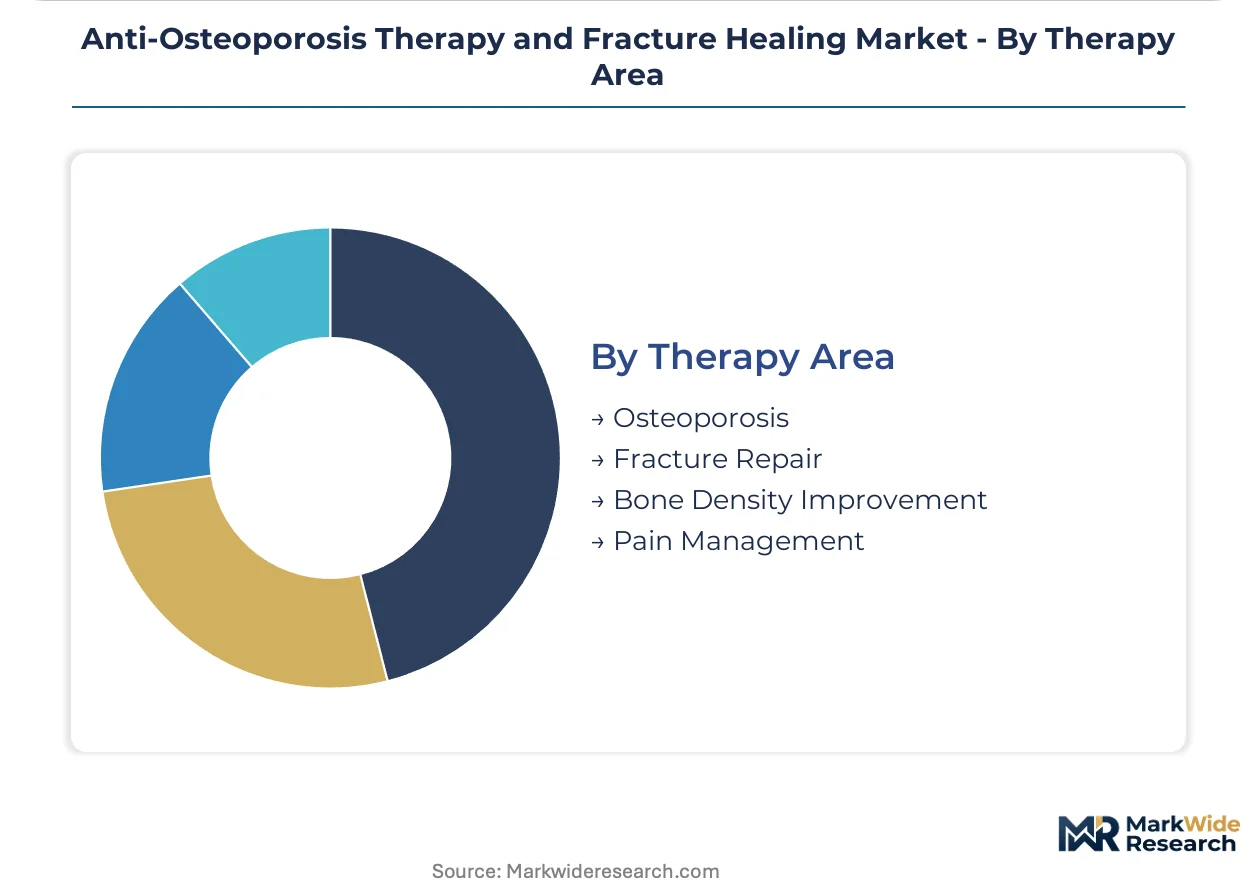
- Osteoporosis:Chronic bone-density management protocols in postmenopausal women drive prescription volume through United States Medicare risk adjustment programs that reward fracture prevention metrics.
- Fracture Repair:Orthobiologics for non-union and delayed union cases, including bone morphogenetic protein formulations, command premium pricing in high-volume United States trauma centers where surgical volume correlates with biologic adoption.
- Bone Density Improvement:Anabolic therapy for glucocorticoid-induced osteoporosis occupies a narrowing indication segment as FDA tightens cardiovascular safety requirements.
- Pain Management:Adjunctive therapy for vertebral compression fractures overlaps with interventional radiology procedures in German hospital outpatient departments.
Osteoporosis management holds volume concentration; fracture repair applications are climbing the fastest as orthopedic surgeons adopt biologic-enhanced fixation protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States, Germany, and Japan concentrate the majority of reimbursed prescription volume for bone-density therapies, with hospital procurement patterns and public reimbursement frameworks determining competitive access in each market.
United States
Medicare Part D risk adjustment programs reward fracture prevention metrics, driving hospital outpatient departments to bundle biologic administration with orthopedic discharge planning. FDA maintains tightened cardiovascular safety requirements for long-term osteoporosis regimens. Academic medical centers in Boston and New York Metro coordinate anabolic therapy initiation through fracture liaison services.
Germany
Fracture liaison service protocols in tertiary care centers bundle biologic administration with bone-density monitoring, expanding screening to historically underpenetrated elderly male populations. EMA's Committee for Medicinal Products for Human Use evaluates centralized marketing authorizations with extended pharmacovigilance mandates. Hospital outpatient departments in Bavaria and North Rhine-Westphalia lead adoption of rank-ligand inhibitors.
Japan
The world's oldest population sustains public reimbursement for bone-density screening and anabolic therapy protocols in metropolitan Tokyo and Osaka health systems. PMDA oversees marketing authorization pathways for novel anabolic agents with streamlined review for geriatric indications. Procurement committees increasingly bundle pharmaceutical contracts with comprehensive patient-support infrastructure.
United Kingdom
NICE technology appraisals determine formulary access for injectable biologics within NHS England, with cost-effectiveness thresholds favoring sequential therapy protocols. MHRA post-Brexit regulatory autonomy maintains alignment with EMA pharmacovigilance standards. Specialist metabolic bone centers in London and the Midlands manage complex switching protocols for severe osteoporosis patients.
Switzerland
Swissmedic marketing authorizations for biologic therapies require demonstration of superiority over oral bisphosphonates in adherence outcomes. Mandatory health insurance reimbursement tiers differentiate premium injectable positioning from generic oral alternatives. Hospital networks in Zurich and Geneva concentrate prescription volume for dual-action anabolic agents in post-surgical recovery.
Anti-Osteoporosis Therapy and Fracture Healing Market Vendor Landscape
Portfolio diversification dominates the current landscape as established pharmaceutical manufacturers extend endocrinology franchises into biologic alternatives. The market structure consolidates around large-cap developers with existing manufacturing scale for monoclonal antibodies and anabolic peptides. Three archetypes define competitive positioning: integrated biologics manufacturers with rank-ligand inhibitor expertise, diversified pharmaceutical conglomerates spanning hormonal and injectable modalities, and specialty peptide developers focused on bone formation stimulation. Geographic expansion into Japanese and German hospital procurement channels and technology licensing for automated injection platforms constitute the dominant competitive moves.
Within the integrated biologics tier, Amgen Inc. and Eli Lilly and Company exemplify scale-driven positioning. Amgen anchors monoclonal antibody manufacturing infrastructure for subcutaneous delivery systems. Eli Lilly leverages established endocrinology distribution networks to sustain anabolic therapy segment presence. Pfizer Inc. occupies a diversified portfolio position spanning both hormonal and injectable modalities. Novartis AG and Merck & Co., Inc. represent European and US-based pharmaceutical conglomerates with broad osteoporosis therapy franchises. F. Hoffmann-La Roche Ltd. and GlaxoSmithKline plc exemplify Swiss and UK-based manufacturers with biologics development capabilities. Sanofi S.A. and Teva Pharmaceutical Industries Ltd. represent French and Israeli-based competitors with generic and specialty pharmaceutical exposure to the category.
| Leading Market Players |
|---|
| Amgen Inc. |
| Eli Lilly and Company |
| Novartis AG |
| Pfizer Inc. |
| Merck & Co., Inc. |
| F. Hoffmann-La Roche Ltd. |
| GlaxoSmithKline plc |
| Sanofi S.A. |
| Teva Pharmaceutical Industries Ltd. |
| Others |
Supply Flow & Price Mechanics
Bifurcation between premium biologic injectables and commoditized oral generics manifests in divergent margin structures and supply chain configurations across United States, German, and Japanese procurement channels. Injectable rank-ligand inhibitors command cold-chain distribution networks that concentrate manufacturing in Swiss and Irish contract development organizations, while oral alendronate saturates retail pharmacy tiers through Indian and Chinese active pharmaceutical ingredient feedstocks.
Pricing Analysis
Volume-margin compression splits the market into high-unit oral generics and low-volume premium biologics. Generic alendronate pricing stratifies across Medicare Part D tiers based on pharmacy benefit manager formulary placement and 90-day adherence program enrollment. Cost compression in the oral segment intensifies as Indian API manufacturers expand capacity, while hospital outpatient departments absorb biologic premium markups through bundled fracture liaison service contracts. Pharmacy benefit managers exhibit highest price sensitivity for chronic oral therapies; orthopedic surgery departments show lowest sensitivity for acute post-fracture biologic protocols.
Supply Chain Analysis
Monoclonal antibody production rests on mammalian cell culture capacity concentrated in Ireland, Switzerland, and Singapore contract manufacturing organizations. Denosumab and romosozumab active substances draw from Chinese hamster ovary cell lines and single-use bioreactor platforms. Single-source vulnerability concentrates in fill-finish capacity for prefilled syringe presentation. Distribution runs through specialty pharmacy networks with validated cold-chain logistics for subcutaneous autoinjector delivery to United States home care settings and Japanese tertiary care centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market consolidation accelerates as FDA biosimilar pathway streamlining erodes originator pricing power and forces mid-tier manufacturers toward exit or acquisition. Generic oral saturation and biologic cold-chain infrastructure requirements create barriers that favor scaled incumbents.
For Market Incumbents: Lock in fracture liaison service partnerships with United States academic medical centers and German hospital outpatient departments to secure anabolic therapy initiation volume. Backward integration into automated injection device manufacturing reduces dependency on third-party platform suppliers. Defend against biosimilar entrants by embedding real-world evidence generation into post-market surveillance infrastructure for cardiovascular safety differentiation. For New Entrants and Emerging Players: Begin with elderly male osteoporosis screening protocols in Germany, where diagnostic penetration lags female populations by 40 percentage points. Target Japanese rehabilitation center channels for post-acute bone-density testing and fall prevention program integration. Pursue licensing agreements with established rank-ligand inhibitor developers to access validated manufacturing infrastructure rather than greenfield biologics capacity. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap peptide developers possessing Phase III anabolic assets and existing endocrinology sales infrastructure given EMA cardiovascular safety requirement elevation. Long-term viability favors manufacturers with demonstrated hospital formulary access and bundled service contracting capabilities. Watch FDA advisory committee outcomes for novel dual-action mechanisms as inflection indicators for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Fracture Liaison Service Partnership | Hospital system integration secures anabolic therapy initiation under bundled payment models in United States academic centers. |
| Biosimilar Manufacturing Scale-Up | FDA abbreviated approval pathways for rank-ligand inhibitors expand patient access and compress originator pricing power. |
| Automated Injection Device Development | Bluetooth-enabled adherence tracking enables outcome-linked reimbursement contracts with pharmacy benefit managers. |
| Real-World Evidence Infrastructure | Extended cardiovascular safety monitoring satisfies EMA pharmacovigilance mandates and differentiates novel anabolic candidates. |
| Elderly Male Diagnostic Expansion | German screening protocol adoption opens historically underpenetrated prescription segment for vertebral fracture detection. |
Methodological Framework
Document review covered FDA New Drug Application filings, EMA centralized marketing authorization assessments, ClinicalTrials.gov protocol registrations, and Medicare Part D formulary databases, complemented by interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation drew from SEC 10-K pharmaceutical disclosures, Japanese PMDA review reports, and German hospital procurement committee minutes. Bottom-up prescription volume modeling and top-down market sizing triangulated segment-level estimates.
Historical prescription trends were cross-referenced against panel input from formulary directors and fracture liaison service coordinators to anchor growth assumptions across the analysis window. Segmentation modeling incorporated treatment line, delivery mode, care setting, patient population risk stratum, and regional regulatory cluster dimensions. CAGRs were derived from epidemiological fracture incidence projections, reimbursement tier evolution, and biologic switching protocol adoption curves. Forecast inputs included bone turnover marker integration rates and cold-chain infrastructure expansion timelines.
Underlying measurement precision varies by segment; hospital-administered biologics carry tighter precision than over-the-counter calcium supplement estimates due to procurement database granularity. Forecasts reflect documented assumptions regarding FDA cardiovascular safety labeling evolution and EMA pharmacovigilance requirement tightening. Biosimilar entry timing, extended bisphosphonate holiday institutionalization, and rural cold-chain infrastructure gaps warrant ongoing watch as revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedics
Bone Spur Market
Orthopedics
Hallux Rigidus Market
Orthopedics
Orthopedic Pillow Market
Orthopedics
Europe Extremity Reconstruction Market
Orthopedics
Rickets Market
Orthopedics
Cruciate Ligament Repair Procedures Market
Orthopedics
Elbow Stiffness Market
Orthopedics
Osgood-Schlatter Market
Orthopedics
Athletic Knee Treatment Market
Orthopedics
Osteoarthritis Treatment Market
Orthopedics
Osteonecrosis Treatment Market
Orthopedics
Orthopedics Market
Orthopedics
Orthopedic Repair Market
Orthopedics
Genu Recurvatum Market
Orthopedics
Knee Hyaluronic Acid Injections Market
Orthopedics
Orthopedic Soft Tissue Repair Market