
 Hallux Rigidus Market | 2026-2036
Hallux Rigidus Market Size, Share, and Industry Trends Forecast 2026-2036
Hallux Rigidus Market Outlook
Hospital procurement of hallux rigidus implants is narrowing as ambulatory surgery centers gain purchasing power across North America and Western Europe. Zimmer Biomet leverages its extremities portfolio to sustain direct-to-facility contracts that bypass traditional distributor markups. Stryker competes through integrated power tool and implant bundles that anchor its position in high-volume orthopedic networks.
Hallux rigidus denotes degenerative osteoarthritis of the first metatarsophalangeal joint, characterized by dorsal osteophyte formation, joint space narrowing, and progressive loss of dorsiflexion that impairs gait mechanics. The condition affects approximately one in forty adults over fifty, with surgical intervention reserved for cases failing conservative management involving orthotic modification and intra-articular corticosteroid injection. Surgical implants dominate value capture due to premium pricing of titanium and cobalt-chrome metatarsal head resurfacing components, while orthotic devices represent the highest-volume segment sustained by recurring replacement cycles and direct-to-consumer availability. Non-surgical treatment categories face margin compression from generic oral analgesic saturation and limited reimbursement for hyaluronic acid viscosupplementation.
FDA 510(k) premarket notification requirements govern synthetic cartilage and hemiarthroplasty systems, while the EU Medical Device Regulation mandates clinical evidence thresholds that delay CE marking for novel implant surfaces. ISO 14155 standards for orthopedic clinical investigations shape trial design for companies seeking regulatory approval across multiple jurisdictions. Stakeholders must monitor reimbursement policy divergence between Medicare Advantage plans and commercial payers regarding outpatient joint replacement site-of-service differentials.
Market Dynamics
Minimally invasive cheilectomy procedures are displacing open arthrodesis as the default surgical intervention, compressing hospital length-of-stay metrics and redirecting implant demand toward ambulatory surgery centers. This procedural shift reconfigures purchasing authority and forces manufacturers to recalibrate sales force deployment toward outpatient facility networks.
Growth Catalysts
- FDA 510(k) Clearance Pathway:Streamlined premarket notification for synthetic cartilage implants accelerates product development timelines and reduces regulatory capital requirements for orthopedic device manufacturers seeking US market entry.
- Germany's Statutory Health Insurance:Reimbursement coverage for first metatarsophalangeal joint arthrodesis procedures sustains surgical volumes and creates predictable demand for titanium resurfacing components.
- Outpatient Migration:Patient preference for same-day discharge drives adoption of cheilectomy techniques that preserve joint motion and reduce postoperative recovery periods.
Market Restraints
- Titanium and Cobalt-Chrome Input Costs:Premium-grade orthopedic alloys face price volatility from concentrated mining operations in southern Africa, compressing margins on metatarsal head resurfacing implants.
- EU MDR Clinical Evidence Thresholds:The Medical Device Regulation mandates expanded clinical investigation requirements that delay CE marking timelines for novel implant surfaces and hemiarthroplasty systems.
- Generic Oral Analgesic Saturation:Non-surgical treatment categories confront margin erosion from commoditized NSAID formulations that limit pricing power for conservative management protocols.
Strategic Opportunities
- Direct-to-Consumer Orthotics:E-commerce channels bypass traditional podiatry clinic distribution, capturing recurring replacement cycles for hallux rigidus bracing and footwear modifications.
- Hyaluronic Acid Viscosupplementation:Emerging clinical protocols for intra-articular injection create demand for formulations targeting first metatarsophalangeal joint osteoarthritis.
- ISO 14155 Harmonization:Standardized orthopedic clinical investigation frameworks enable single-trial designs that satisfy multiple regulatory jurisdictions simultaneously.
Industry Challenges
- Site-of-Service Reimbursement Divergence:Medicare Advantage plans and commercial payers apply inconsistent outpatient joint replacement differentials, complicating pricing strategy and contract negotiation.
- Surgeon Training Pipeline:Minimally invasive cheilectomy techniques require specialized arthroscopic skills that reside in limited fellowship programs, constraining procedural expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hallux Rigidus Market |
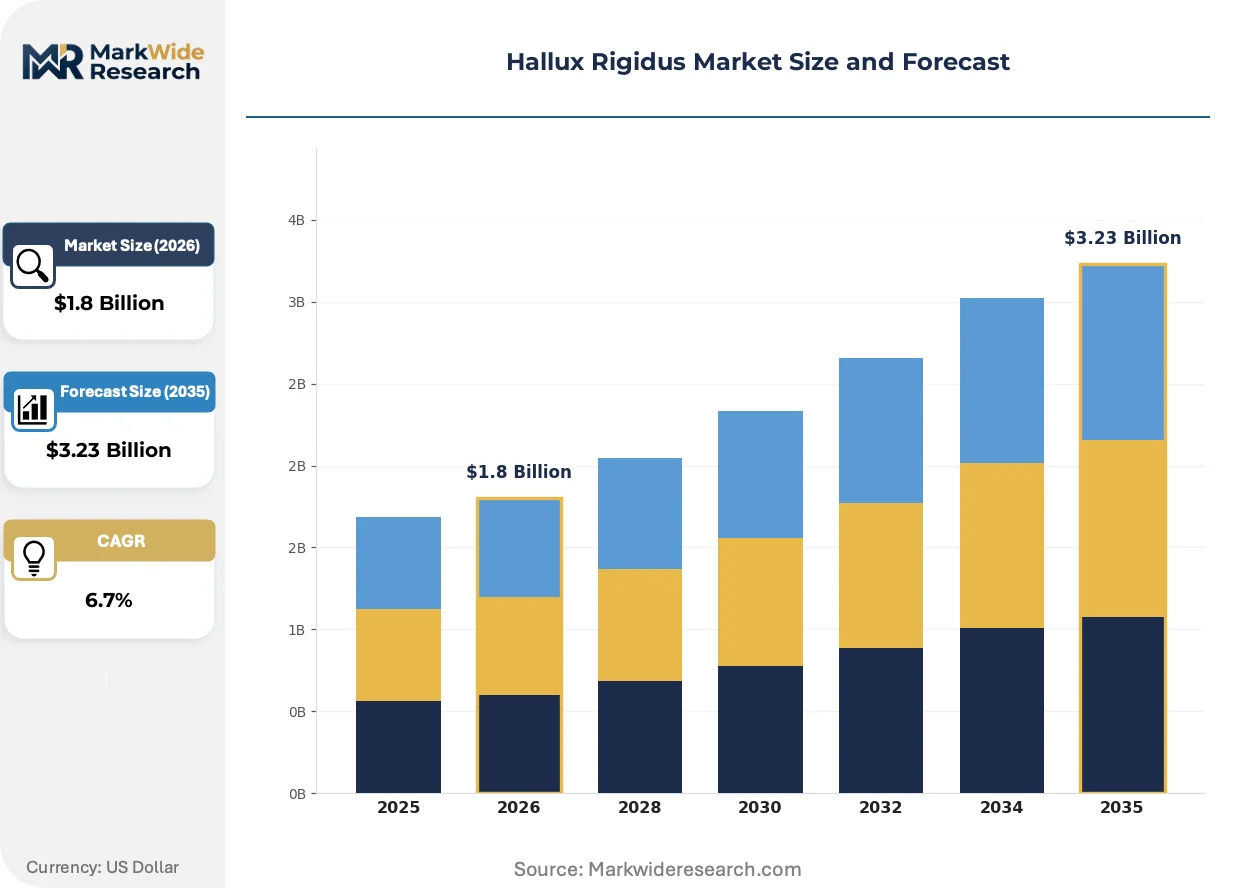
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Orthotic Devices, Surgical Implants, Injections, Medication End User: Clinics, Hospitals, Rehabilitation Centers, Home Care Treatment Type: Non-Surgical, Surgical, Physiotherapy, Pharmaceuticals Severity Level: Mild, Moderate, Severe, Advanced |
| Companies Covered | Zimmer Biomet, Smith & Nephew, Stryker, DePuy Synthes, Wright Medical Group, Integra LifeSciences, Arthrex, Acumed, Advanced Orthopaedic Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hallux Rigidus Market Strategic Shifts
Product development trajectories in hallux rigidus intervention are converging on motion-preserving alternatives to arthrodesis, with synthetic resurfacing systems and hemiarthroplasty designs commanding disproportionate R&D investment. Regulatory strategy and procurement model evolution are simultaneously reshaping competitive positioning.
Polyethylene and ceramic composite bearing surfaces are hybridizing with titanium metatarsal head components to reduce osteolysis risk and extend implant longevity. Ambulatory surgery centers in the United States and Germany are adopting these hybrid constructs at accelerating pace, displacing traditional metal-on-metal configurations that dominated arthroplasty portfolios through 2020. This material convergence is compressing the addressable market for revision procedures while elevating upfront device costs.
The EU Medical Device Regulation's clinical evidence requirements are forcing manufacturers to sponsor prospective registry studies that track synthetic cartilage outcomes across five-year follow-up periods. Orthopedic networks in France and the Netherlands are delaying procurement decisions until CE-marked products demonstrate superiority data against arthrodesis controls. High-volume hospital systems are consolidating supplier relationships around vendors with established MDR technical documentation.
Buyer concentration among integrated orthopedic networks is displacing independent surgeon preference as the primary purchasing determinant. Hospital procurement departments in the United States are bundling cheilectomy implants with power tool service contracts, extracting volume discounts that erode traditional distributor margins. This consolidation is most visible in Medicare Advantage–dominated markets where site-of-service differentials incentivize outpatient facility investment.
Hallux Rigidus Market Segmentation
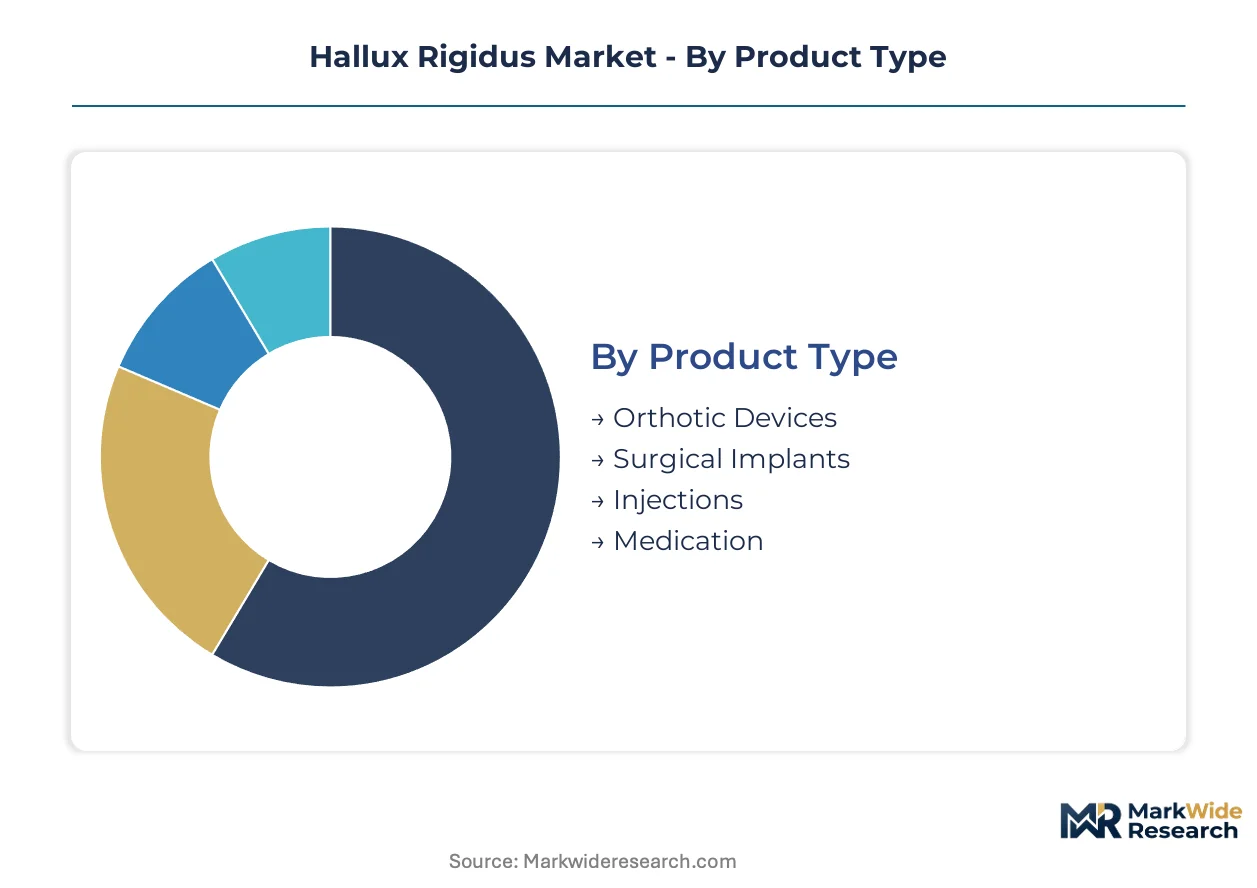
Segmentation in hallux rigidus intervention reveals divergent margin profiles across conservative and surgical pathways. Procurement patterns differ sharply between institutional buyers managing implant inventories and direct-to-consumer channels for orthotic replacement cycles.
Product Type:
Mature hardware categories coexist with emerging biologic alternatives, each commanding distinct pricing architectures and replacement cadences.
- Surgical Implants:Titanium and cobalt-chrome metatarsal head resurfacing components anchor value capture through premium alloy specifications and arthrodesis fixation systems. Demand concentrates in ambulatory surgery centers across Germany and the United States, where statutory reimbursement and Medicare site-of-service differentials sustain procedural volumes.
- Orthotic Devices:Custom-molded foot orthoses and rigid-soled footwear modifications deliver recurring revenue through replacement cycles every 18-24 months. Direct-to-consumer e-commerce channels in North America bypass traditional podiatry distribution, capturing margin that previously flowed through clinical intermediaries.
- Injections:Intra-articular corticosteroid and hyaluronic acid formulations target symptomatic flare management.
- Medication:Oral NSAIDs and analgesics face generic saturation compressing branded pricing power.
Surgical implants handle the majority of throughput; orthotic devices are gaining share fastest through channel disintermediation.
End User:
Facility type determines purchasing authority, with site-of-service economics reshaping where intervention decisions originate.
- Clinics:Podiatry and orthopedic clinics serve as gatekeepers for conservative management and surgical referral, controlling initial diagnosis and orthotic prescription. Patient volume concentrates in Medicare Advantage–dominated US markets and Germany's statutory insurance networks, where outpatient preference redirects surgical cases to ambulatory settings.
- Hospitals:Inpatient orthopedic departments retain complex revision arthrodesis and salvage procedures requiring extended monitoring. Procurement authority is narrowing as integrated delivery networks consolidate supplier contracts around bundled implant and power tool arrangements.
- Rehabilitation Centers:Postoperative physiotherapy and gait retraining extend the care continuum.
- Home Care:Self-administered orthotic use and telehealth monitoring expand the addressable base.
Clinics process the highest patient volume; home care is climbing the fastest on share as remote monitoring technologies mature.
Treatment Type:
Intervention intensity maps to disease progression, with early-stage categories exhibiting higher volume but lower per-case yield.
- Non-Surgical:Orthotic modification, activity limitation, and injection protocols constitute first-line management for mild-to-moderate presentations. Demand concentrates in primary care and podiatry clinics across Western Europe, where conservative step-up protocols delay surgical referral under cost-containment guidelines.
- Surgical:Cheilectomy, arthrodesis, and hemiarthroplasty procedures generate disproportionate revenue through implant utilization. Ambulatory surgery centers in the United States and Germany are expanding capacity to capture site-of-service reimbursement differentials.
- Physiotherapy:Manual therapy and joint mobilization support functional preservation.
- Pharmaceuticals:Systemic analgesia addresses symptomatic management without structural intervention.
Non-surgical approaches dominate episode initiation; surgical intervention delivers the steepest expansion trajectory as minimally invasive techniques broaden candidacy.
Severity Level:
Disease staging drives intervention selection, with later categories requiring more resource-intensive management.
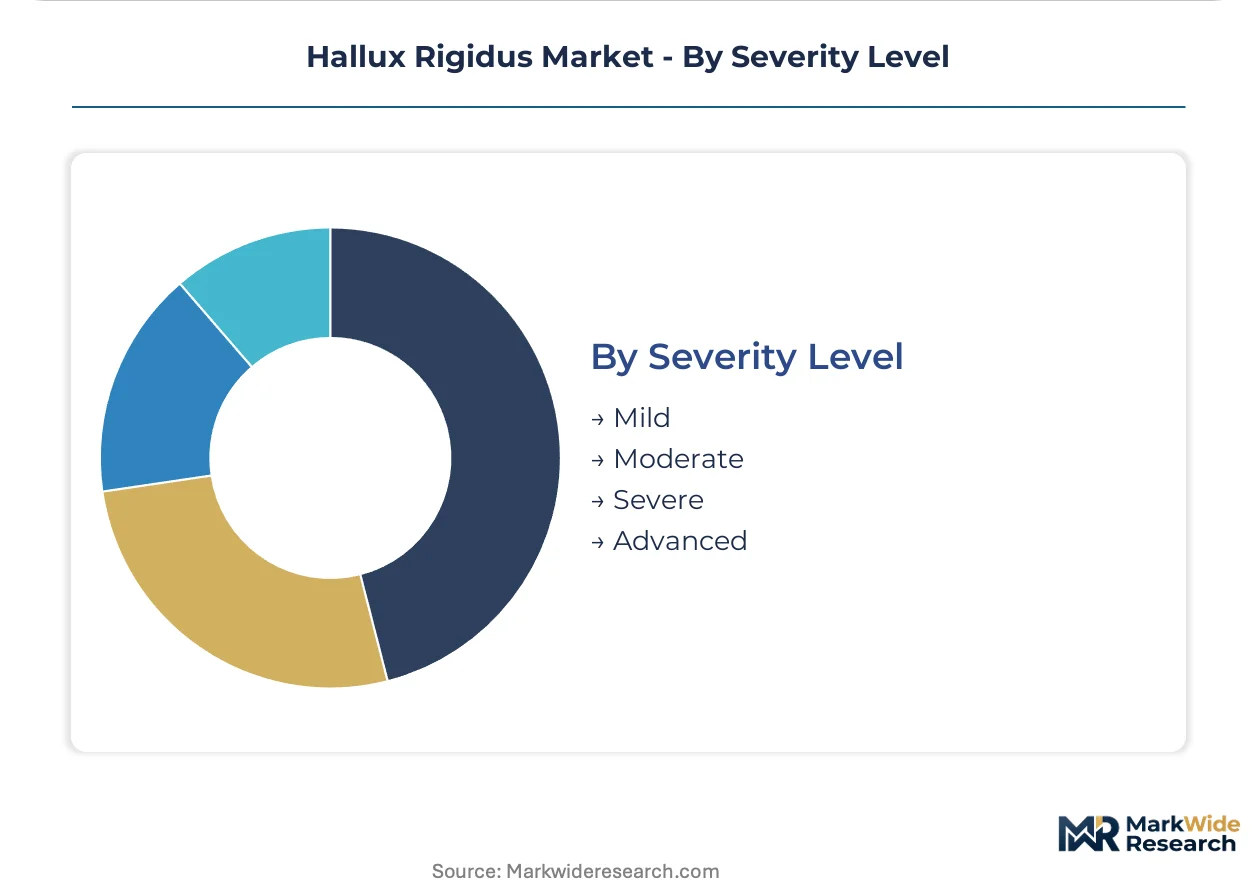
- Moderate:Dorsal osteophyte formation with preserved but painful range of motion represents the decision point between conservative escalation and surgical consultation. Patient concentration is highest in adults aged 55-70 across the United States and Germany, where activity demands and insurance coverage align to support intervention.
- Severe:Advanced joint space narrowing and fixed deformity typically mandate arthrodesis or resurfacing arthroplasty. Surgical volumes concentrate in high-volume orthopedic networks with established implant supplier relationships and fellowship-trained foot and ankle specialists.
- Mild:Early degenerative changes respond to activity modification.
- Advanced:End-stage arthritis with significant deformity may require salvage procedures.
Moderate severity generates the highest clinical encounter volume; severe presentations show the fastest procedural growth as motion-preserving alternatives to arthrodesis mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's statutory reimbursement environment while the United States extracts discounts through Medicare Advantage site-of-service differentials, creating a transatlantic asymmetry in implant margin capture.
United States
Medicare Advantage penetration drives ambulatory surgery center construction in Florida and Texas, redirecting arthrodesis volumes from inpatient settings. FDA 510(k) clearance timelines compress product development cycles for synthetic cartilage developers. The Greater Phoenix orthopedic corridor anchors high-volume foot and ankle specialist networks that consolidate purchasing around bundled implant and power tool contracts.
Germany
Statutory health insurance reimbursement for first metatarsophalangeal joint arthrodesis sustains predictable surgical demand across Baden-Württemberg and Bavaria. The EU Medical Device Regulation mandates clinical evidence thresholds that delay CE marking for novel implant surfaces. The Stuttgart-Tübingen medical technology cluster concentrates hemiarthroplasty R&D and manufacturing operations for European distribution.
United Kingdom
NHS England cost-containment protocols prioritize conservative management step-up before surgical referral, compressing implant utilization rates versus continental Europe. The Medicines and Healthcare products Regulatory Agency enforces post-market surveillance requirements for orthopedic devices. The Oxford-Cambridge arc hosts academic medical centers that generate clinical evidence for synthetic cartilage registry studies.
France
Haute Autorité de Santé health technology assessments delay reimbursement decisions for motion-preserving alternatives to arthrodesis, constraining premium implant uptake. The EU MDR technical documentation requirements favor established manufacturers with legacy clinical data portfolios. The Lyon-Grenoble corridor concentrates orthopedic device distribution infrastructure serving southern European markets.
Japan
PMDA consultation procedures extend premarket approval timelines for foreign-manufactured hemiarthroplasty systems, protecting domestic device makers. The aging population demographic expands the addressable base for hallux rigidus intervention beyond Western market saturation levels. The Kansai region's medical device manufacturing base supplies titanium resurfacing components across Asia-Pacific markets.
Hallux Rigidus Market Competitive Environment
Extremities-focused conglomerates and specialized foot-and-ankle developers split the market along portfolio breadth versus clinical depth lines. Consolidation pressure concentrates procurement authority within integrated delivery networks that extract volume discounts from implant suppliers. Three archetypes dominate: diversified orthopedic majors with extremities divisions, pure-play foot-and-ankle specialists, and emerging synthetic cartilage developers. Competitive moves center on direct-to-facility contracting that bypasses distributor markups, and M&A activity targeting complementary motion-preserving technologies.
Among diversified orthopedic majors, Zimmer Biomet, Stryker, and Smith & Nephew occupy positions that span the full intervention spectrum from conservative management to arthrodesis and arthroplasty. These companies exemplify the scale-driven archetype that leverages integrated power tool and implant bundles to anchor relationships with high-volume orthopedic networks. Their geographic footprints and established regulatory dossiers create defensive moats against emerging competitors seeking to commercialize novel bearing surfaces or synthetic cartilage alternatives.
| Leading Market Players |
|---|
| Zimmer Biomet |
| Smith & Nephew |
| Stryker |
| DePuy Synthes |
| Wright Medical Group |
| Integra LifeSciences |
| Arthrex |
| Acumed |
| Advanced Orthopaedic Solutions |
| Others |
Value Chain & Pricing Dynamics
Stuttgart-Tübingen's medical technology cluster anchors European titanium resurfacing component supply, with capacity utilization rates directly transmitting to downstream implant pricing power across German ambulatory surgery centers and US Medicare Advantage networks. This geographic concentration creates asymmetric margin capture between alloy specification tiers and standard-grade alternatives.
Pricing Analysis
The customization-premium spread separates patient-specific titanium metatarsal head components from standard arthrodesis fixation systems by three-to-five-fold. Pricing stratifies across premium, standard, and economy tiers based on alloy grade certification and surgical volume commitments. Cost compression in standard-grade categories is intensifying because generic oral analgesic saturation limits conservative management pricing power. Ambulatory surgery centers exhibit highest price sensitivity due to site-of-service reimbursement differentials, while integrated orthopedic networks extract volume discounts through bundled power tool arrangements.
Supply Chain Analysis
Upstream feedstock for premium-grade orthopedic alloys draws from concentrated mining operations in South Africa and Zimbabwe, with secondary refining capacity in Germany and the United States. Titanium sponge and cobalt-chrome master alloys constitute critical input dependencies alongside polyethylene bearing surfaces. Single-source vulnerability in southern African ore supply creates exposure to export restriction risk. Distribution runs through direct-to-facility contracts that bypass traditional distributor markups, consolidating procurement authority within high-volume orthopedic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward ambulatory surgery centers as Medicare Advantage site-of-service differentials consolidate purchasing authority within integrated delivery networks, fragmenting independent surgeon preference as the primary pricing determinant.
For Market Incumbents: Build regulatory dossier moats through expanded EU MDR technical documentation and FDA 510(k) predicate device libraries that delay emerging synthetic cartilage competitors. Anchor relationships with high-volume orthopedic networks via bundled implant and power tool service contracts. Invest backward integration into titanium alloy specification control to defend margin position against South African feedstock volatility. For New Entrants and Emerging Players: France's delayed Haute Autorité de Santé reimbursement decisions for motion-preserving alternatives create underpenetration white space for hemiarthroplasty systems with established CE marking. Target direct-to-consumer orthotic channels in North America where e-commerce bypasses podiatry clinic distribution intermediaries. Pursue ISO 14155 harmonization to enable single-trial designs satisfying multiple regulatory jurisdictions simultaneously. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors synthetic cartilage developers with five-year prospective registry data approaching MDR compliance maturity. Long-term viability hinges on demonstrating superiority against arthrodesis controls in orthopedic network procurement decisions. Watch for CE marking acceleration signals as established manufacturers clear MDR technical documentation backlogs.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Streamlined premarket notification accelerates synthetic cartilage product development timelines for US market entry. |
| EU MDR Technical Documentation | Expanded clinical evidence requirements delay CE marking but create defensive moats for established manufacturers. |
| Direct-to-Facility Contracting | Bypassing distributor markups captures margin compression pressure within ambulatory surgery center networks. |
| ISO 14155 Harmonization | Standardized orthopedic clinical investigation frameworks reduce trial redundancy across regulatory jurisdictions. |
| Hyaluronic Acid Viscosupplementation | Intra-articular injection protocols create demand expansion for first metatarsophalangeal joint osteoarthritis formulations. |
Study Parameters
The analysis maps surgical implants, orthotic devices, injection formulations, and pharmaceutical categories, each validated through orthopedic surgeons, ambulatory surgery center administrators, hospital purchasing committee members, and GPO contracts managers. Primary interview data triangulates against FDA 510(k) filings, EU MDR technical documentation databases, CMS Medicare reimbursement schedules, and hospital procurement contract records. Bottom-up demand modeling and top-down market sizing converge across product type, end user facility, treatment intensity, and disease severity dimensions.
Assumption sets held reimbursement policy divergence and alloy feedstock pricing volatility fixed across the projection horizon while varying procedural migration rates toward outpatient settings. Segmentation dimensions include hardware category, facility type, intervention intensity, and geographic regulatory cluster. CAGRs derive from installed base expansion and replacement cycle analysis. Forecast inputs incorporate ambulatory surgery center construction permits and fellowship program graduation rates.
Macroeconomic conditions sit as an overlay; deviation in statutory health insurance reimbursement rates or South African mining export policies would shift the trajectory. Cross-checking against orthopedic network implant utilization benchmarks and GPO contract award databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedics
Orthopedic Repair Market
Orthopedics
US Arthritis Market
Orthopedics
Rotator Cuff Arthropathy Repair Market
Orthopedics
Kyphosis Market
Orthopedics
Osteonecrosis Treatment Market
Orthopedics
Europe Extremity Reconstruction Market
Orthopedics
Europe Bone Metastasis Market
Orthopedics
Swollen Knee Treatment Market
Orthopedics
Canine Orthopedics Market
Orthopedics
Cruciate Ligament Repair Procedures Market
Orthopedics
Bilateral Osteoarthritis Treatment Market
Orthopedics
Spinal Stenosis Market
Orthopedics
Genu Recurvatum Market
Orthopedics
Orthopedics Market
Orthopedics
United States Orthopedic Braces and Support Market
Orthopedics
Septic Arthritis Market