
 Swollen Knee Treatment Market | 2026-2036
Swollen Knee Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Swollen Knee Treatment Market Analysis
Outpatient clinics is unwinding the historical hospital-centric model for swollen knee interventions, pulling procedure volumes into lower-acuity settings where convenience and cost efficiency align. Stryker Corporation leverages its arthroscopy and implant portfolio to anchor position across the surgical segment of knee effusion management. Zimmer Biomet competes through robotics-assisted platforms that extend precision into osteoarthritis debridement and synovectomy workflows.
Swollen knee treatment encompasses pharmacologic and interventional modalities targeting joint effusion, bursitis, and synovial inflammation, with hyaluronic acid formulations requiring molecular weights between 500 and 6,000 kDa to achieve viscosupplementation efficacy and corticosteroid suspensions formulated for intra-articular depot release. The therapy area dimension shows osteoarthritis commanding the largest patient pool while biological agents represent the fastest-expanding product type as platelet-rich plasma and cell-derived therapies capture premium positioning. Delivery mode preferences are fragmenting, with injection routes dominating clinical practice but oral NSAIDs sustaining volume in primary care and home care transitions.
The FDA regulates intra-articular devices and biologic combinations under distinct premarket pathways, while CMS reimbursement determinations directly shape site-of-care economics for hyaluronic acid and corticosteroid administration. ISO 13485 quality management requirements govern manufacturing consistency for implantable knee drainage and lavage systems across international supply chains. Stakeholders must monitor convergence between regenerative medicine regulatory frameworks and real-world evidence requirements as biological agents challenge conventional small-molecule dominance.
Market Dynamics
Outpatient migration is compressing the swollen knee treatment value chain, pulling procedures from hospital ORs into ambulatory surgery centers and physician offices where CMS reimbursement differentials favor same-day interventions.
Growth Catalysts
- CMS site-of-care payment differentials:Medicare's higher reimbursement rates for ASC-based viscosupplementation and arthrocentesis accelerate facility investment in injection suites.
- Hyaluronic acid molecular engineering:Cross-linked formulations extending joint residence time from days to weeks reduce injection frequency burdens for osteoarthritis patients.
- Sports medicine clinic expansion:Athlete-focused outpatient networks in Texas, Florida, and California deploy ultrasound-guided injection protocols that improve needle placement accuracy.
Market Restraints
- Biologic raw material volatility:Platelet-rich plasma preparation requires FDA-registered 510(k) centrifuge systems with single-use consumable costs that fluctuate with medical-grade plastic resin pricing.
- Hyaluronic acid supply concentration:Fermentation-derived sodium hyaluronate API production clusters in Shandong Province, China, exposing formulators to export license delays.
- Corticosteroid intra-articular safety limits:FDA-mandated black box warnings on repeated triamcinolone injections cap treatment frequency at 3-4 per joint annually.
Strategic Opportunities
- Home care injection training protocols:Self-administered subcutaneous biologic alternatives to intra-articular delivery bypass facility dependency entirely.
- EMA Advanced Therapy Medicinal Products pathway:Cell-derived allogeneic therapies for refractory synovitis access centralized EU marketing authorization with orphan drug incentives.
- Telehealth-integrated pain monitoring:Remote patient-reported outcome capture via smartphone apps extends prescriber reach into rural counties lacking rheumatology coverage.
Industry Challenges
- Point-of-care ultrasound certification bottlenecks:Sports medicine physicians require ARDMS RPVI credentials or equivalent training hours to bill for guided injection procedures.
- Cold chain integrity for autologous therapies:PRP and stromal vascular fraction preparations demand 2-8°C transport logistics that ASCs lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Swollen Knee Treatment Market |
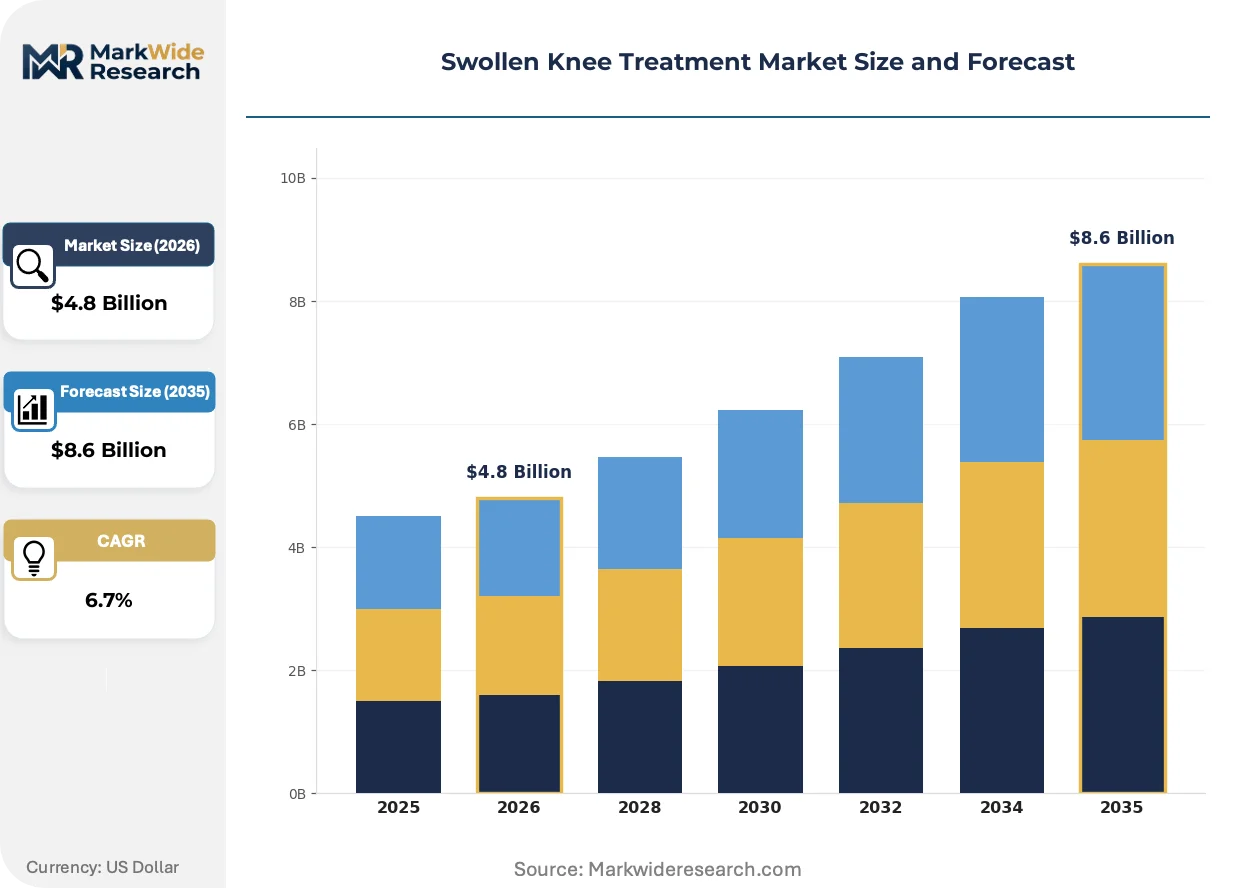
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: NSAIDs, Corticosteroids, Hyaluronic Acid, Biological Agents Delivery Mode: Oral, Injection, Topical, Infusion End User: Hospitals, Outpatient Clinics, Rehabilitation Centers, Home Care Therapy Area: Osteoarthritis, Rheumatoid Arthritis, Post-Traumatic Injuries, Gout |
| Companies Covered | Stryker Corporation, Zimmer Biomet, Smith & Nephew, Johnson & Johnson (DePuy Synthes), Pfizer, Arthrex, Medtronic, B. Braun Melsungen AG, Exactech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Swollen Knee Treatment Market Emerging Trajectories
Biologic processing workflows and regulatory data requirements are forcing parallel investments in manufacturing quality systems and real-world evidence infrastructure.
Platelet-rich plasma preparation is fragmenting across multiple centrifugation protocols, with leukocyte-poor systems gaining adoption in orthopedic practices seeking to minimize post-injection flare reactions. Academic medical centers in Boston and Philadelphia publish head-to-head efficacy studies that drive formulary divergence. This technology is fragmenting the historical corticosteroid-first algorithm into indication-specific decision trees.
FDA's 2023 draft guidance on human cells, tissues, and cellular and tissue-based products reclassifies certain adipose-derived stromal vascular fraction preparations as drugs rather than minimally manipulated tissue. Manufacturers must now submit IND applications and conduct Phase I/II trials for knee osteoarthritis indications. Small biologic processors in California and Texas face facility upgrades to meet cGMP standards or exit the market.
Patients increasingly demand single-visit bundled pricing that combines imaging, injection, and follow-up assessment. ASCs in Arizona and Nevada respond with all-inclusive episode rates that undercut hospital outpatient department fees by 30-40 percent. Employer-sponsored health plans in self-insured manufacturing sectors actively steer members toward these transparent pricing models.
Swollen Knee Treatment Market Segmentation
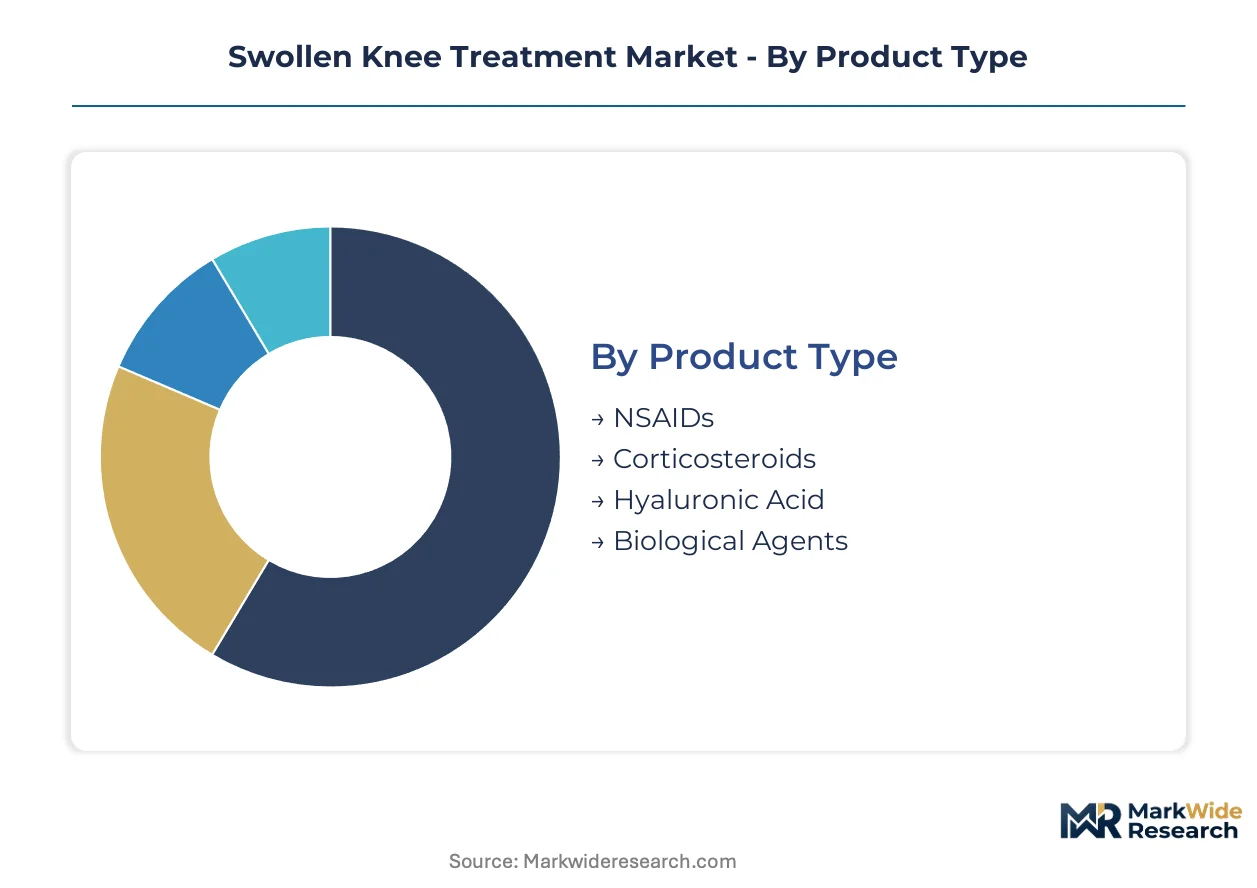
Swollen knee treatment segmentation reveals divergent margin structures across pharmacologic and interventional modalities. Product type and delivery mode categories concentrate value capture differently, with biological agents commanding premium positioning while oral NSAIDs sustain volume throughput in primary care channels.
Product Type:
Margin pools concentrate in biological agents and cross-linked hyaluronic acid formulations, where manufacturing complexity and regulatory barriers protect pricing power.
- NSAIDs:Oral formulations including ibuprofen and naproxen sodium dominate prescription volume in primary care settings. Demand concentrates in United States Medicare Part D plans where prior authorization requirements for branded alternatives sustain generic substitution rates.
- Corticosteroids:Intra-articular depot suspensions of triamcinolone and methylprednisolone deliver immediate anti-inflammatory efficacy through crystalline particle formulations. Rheumatology practices in Florida and Texas deploy ultrasound-guided injection protocols that improve accuracy and reduce procedure time.
- Hyaluronic Acid:Viscosupplementation requires molecular weights between 500 and 6,000 kDa to achieve joint residence time extension.
- Biological Agents:Platelet-rich plasma and cell-derived therapies represent the steepest expansion trajectory in premium outpatient segments.
Hyaluronic acid holds installed capacity. Biological agents are rotating up the share rankings.
Delivery Mode:
Volume distribution favors injection routes in orthopedic and sports medicine settings, while oral administration sustains reach into rural and home-based care environments.
- Oral:Tablets and capsules of NSAIDs and colchicine formulations enable patient-managed therapy initiation without facility dependency. Primary care networks in underserved counties rely on oral pathways where specialist injection access is limited.
- Injection:Intra-articular and periarticular needle placement delivers corticosteroids, hyaluronic acid, and biologics directly to synovial compartments. Ambulatory surgery centers in Arizona and Nevada bundle imaging, injection, and follow-up into single-visit episode pricing.
- Topical:Diclofenac gels and capsaicin patches provide localized delivery with minimal systemic absorption for patients with contraindications to oral NSAIDs.
- Infusion:Intravenous biologic delivery for refractory inflammatory arthritis requires infusion center infrastructure and monitoring protocols.
Injection routes command procedure-based reimbursement. Oral pathways are expanding fastest into telehealth-integrated prescription models.
End User:
Site-of-care economics drive patient migration toward lower-acuity settings where CMS reimbursement differentials favor same-day interventions.
- Hospitals:Academic medical centers manage complex multi-joint presentations and coordinate surgical intervention for failed conservative therapy. Boston and Philadelphia institutions publish comparative effectiveness research that influences regional formulary decisions.
- Outpatient Clinics:Sports medicine and rheumatology practices deploy ultrasound-guided injection suites with immediate availability. Texas and California clinic networks capture patient volume through athlete-focused service lines and transparent bundled pricing.
- Rehabilitation Centers:Post-injection physical therapy protocols optimize functional outcomes following viscosupplementation.
- Home Care:Self-administered oral NSAID and topical therapy transitions extend treatment continuity beyond facility encounters.
Outpatient clinics hold procedure volume leadership. Home care is climbing the fastest as remote monitoring technology matures.
Therapy Area:
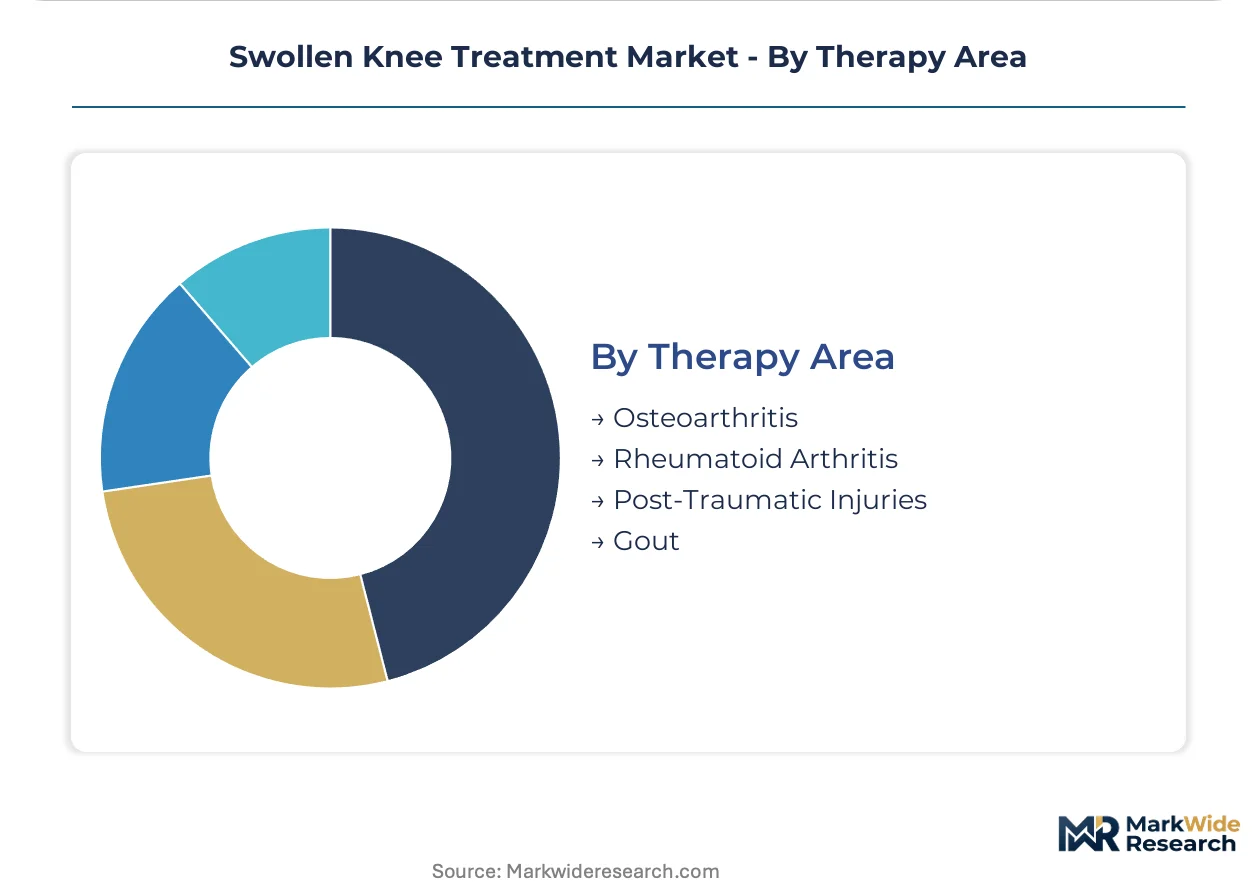
Patient pool size and treatment intensity vary significantly across underlying etiologies, with osteoarthritis presenting the largest addressable population.
- Osteoarthritis:Degenerative cartilage loss drives chronic synovial inflammation and effusion requiring repeated intervention cycles. Aging demographics in United States sunbelt states sustain procedure volume concentration.
- Rheumatoid Arthritis:Systemic autoimmune pathology demands disease-modifying therapy alongside symptomatic knee management. Academic rheumatology divisions coordinate biologic sequencing to preserve joint structure.
- Post-Traumatic Injuries:Acute hemarthrosis and reactive synovitis following sports or occupational trauma require urgent aspiration and corticosteroid injection.
- Gout:Crystal-induced inflammatory flares respond to colchicine and intra-articular corticosteroid with rapid resolution.
Osteoarthritis holds installed patient base. Post-traumatic indications are rotating up the share rankings through sports medicine network expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold chain infrastructure underwrites European distribution of temperature-sensitive biologics, while the Shenzhen-Guangzhou pharmaceutical corridor anchors Asia-Pacific manufacturing scale for hyaluronic acid API.
United States
Medicare Part D enrollment growth and ASC reimbursement differentials drive procedure volume concentration. FDA's 2023 HCT/P draft guidance reclassifies certain adipose-derived therapies as drugs requiring IND submissions. Boston and Philadelphia academic medical centers publish comparative effectiveness research influencing regional formulary adoption.
Germany
Aging demographics and statutory health insurance coverage for viscosupplementation sustain outpatient clinic expansion. EMA's Advanced Therapy Medicinal Products pathway enables centralized EU marketing authorization for cell-derived therapies. Bavaria's medical device cluster around Munich anchors robotics-assisted surgical platform development.
China
Fermentation-derived sodium hyaluronate API production concentrates in Shandong Province, supplying global formulators. NMPA's evolving biologic registration requirements align with ICH guidelines for multinational trial acceptance. Yangtze River Delta medical centers in Shanghai deploy ultrasound-guided injection protocols at scale.
Japan
Super-aging society demographics and long-term care insurance reimbursement sustain chronic osteoarthritis management demand. PMDA's Sakigake designation system accelerates regenerative medicine product reviews. Kansai region Osaka-based orthopedic networks specialize in hyaluronic acid repeat-injection protocols.
United Kingdom
NHS England's RightCare program steers appropriate knee pain referrals toward community-based musculoskeletal services. MHRA's post-Brexit regulatory autonomy enables accelerated approval pathways for novel biologics. London's Harley Street private clinic cluster captures premium self-pay viscosupplementation volume.
Swollen Knee Treatment Market Vendor Landscape
Concentration sits with diversified orthopedic conglomerates that leverage arthroscopy portfolios to anchor position across surgical and interventional segments. The vendor base stratifies into three tiers: integrated device-pharma hybrids controlling hospital procurement channels, mid-cap sports medicine specialists capturing outpatient clinic share, and regional hyaluronic acid formulators competing on price. Dominant competitive moves include M&A to acquire ultrasound-guided injection technology and vertical integration into biologic processing workflows.
Within the integrated orthopedic tier, Stryker Corporation and Zimmer Biomet represent archetypal positioning through device-synergy strategies that bundle arthroscopy systems with implant portfolios. Smith & Nephew occupies a position exemplifying sports medicine-focused specialization, while Johnson & Johnson's DePuy Synthes sits within the diversified healthcare conglomerate archetype leveraging pharmaceutical distribution reach.
| Leading Market Players |
|---|
| Stryker Corporation |
| Zimmer Biomet |
| Smith & Nephew |
| Johnson & Johnson (DePuy Synthes) |
| Pfizer |
| Arthrex |
| Medtronic |
| B. Braun Melsungen AG |
| Exactech |
| Others |
Supply Flow & Price Mechanics
Cross-linked hyaluronic acid formulations displacing conventional linear polymers are redrawing manufacturing geography toward Shandong Province fermentation clusters while compressing per-injection reimbursement ceilings across United States Medicare channels.
Pricing Analysis
Volume-discount tiering structures separate premium biologic therapies from standard viscosupplementation and economy oral NSAID categories. Price differentiation rests on molecular weight certification tiers and ultrasound-guided delivery bundling rather than raw material costs alone. Pricing pressure intensifies in the standard tier as ASC bundled episodes undercut hospital outpatient department fees. Primary care networks exhibit highest price sensitivity, while sports medicine clinics absorb premium positioning for athlete-focused service lines.
Supply Chain Analysis
Just-in-time inventory strategies dominate hyaluronic acid API procurement, though strategic stockpiling of medical-grade plastic resins buffers platelet-rich plasma centrifuge consumable volatility. Fermentation-derived sodium hyaluronate concentrates in China, with secondary API finishing in Germany and Japan. Raw material dependencies include glucose feedstock, single-use bioreactor liners, and FDA-registered 510(k) centrifuge systems. Single-source vulnerability in Shandong Province export licensing exposes formulators to regulatory delay risk. Distribution runs through cold-chain logistics networks serving ambulatory surgery centers and physician injection suites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The swollen knee treatment market functions as a defensive-moat story anchored in FDA regulatory entrenchment, where biologic reclassification barriers and cGMP facility requirements protect incumbent positioning against commodity substitution.
For Market Incumbents: Compound defensive positioning through backward integration into biologic processing workflows and captive supply of cross-linked hyaluronic acid API. Stryker Corporation and Zimmer Biomet should extend robotics-assisted platform ecosystems into outpatient injection protocols before mid-cap sports medicine specialists capture ultrasound-guided market share. Prioritize cGMP facility upgrades to meet FDA's 2023 HCT/P draft guidance standards. For New Entrants and Emerging Players: Differentiate on telehealth-integrated remote monitoring capabilities that bypass established ASC channel control. White-space targets include rural counties lacking rheumatology coverage and employer-sponsored self-insured plans seeking transparent bundled pricing. The most penetrable segment is home care injection training protocols for subcutaneous biologic alternatives. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors diversified orthopedic conglomerates with device-pharma hybrid capabilities. Long-term viability over the next decade hinges on regulatory data infrastructure and real-world evidence capture systems. Acquisition target archetypes include ultrasound-guided injection technology specialists and point-of-care biologic processing workflow innovators. Watch FDA enforcement patterns on adipose-derived stromal vascular fraction preparations as the primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Biologic Processing Workflow Integration | Captive PRP and cell-derived therapy manufacturing secures margin pools against raw material volatility. |
| Ultrasound-Guided Injection Certification | ARDMS RPVI credentialing requirements create specialist bottlenecks that protect premium service pricing. |
| Telehealth-Integrated Pain Monitoring | Smartphone-based patient-reported outcome capture extends prescriber reach into underserved rural geographies. |
| ASC Bundled Episode Pricing | All-inclusive same-visit rates undercut hospital outpatient department fees by 30-40 percent in competitive markets. |
| FDA HCT/P Regulatory Compliance | cGMP facility investments defend market access against 2023 draft guidance reclassification enforcement. |
Methodological Framework
The analysis maps pharmacologic modalities, interventional delivery systems, and biologic processing workflows, each validated through rheumatology practice administrators, ASC operations directors, and orthopedic device procurement managers. Primary fieldwork combined structured interviews with hospital purchasing committees and GPO contracts managers against secondary validation through FDA 510(k) filings, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up volume triangulation across product type and delivery mode segments converged with top-down value estimates anchored in manufacturer revenue disclosures.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled therapy area, end-user site-of-care, and molecular weight tier segmentation throughout the forecast period. CAGRs derived from procedure volume trajectories and per-intervention reimbursement trends incorporated hyaluronic acid injection frequency patterns and biologic therapy adoption curves as industry-specific inputs.
Material uncertainties — FDA enforcement intensity on adipose-derived therapies, CMS site-of-care payment recalibration, and Shandong Province export license continuity — sit outside the modeled envelope. Forecasts reflect assumptions on regulatory pathway stability and reimbursement differential persistence. Revision becomes warranted when biologic reclassification enforcement crosses thresholds that trigger widespread cGMP facility exit.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedics
Orthopedic Pillow Market
Orthopedics
Skeletal Deformation Correction Market
Orthopedics
Kyphosis Market
Orthopedics
Bone Spur Market
Orthopedics
Orthopedic Soft Tissue Repair Market
Orthopedics
Orthopedics Market
Orthopedics
Osgood-Schlatter Market
Orthopedics
Anti-Osteoporosis Therapy and Fracture Healing Market
Orthopedics
Athletic Knee Treatment Market
Orthopedics
Rotator Cuff Arthropathy Repair Market
Orthopedics
Osteoarthritis Treatment Market
Orthopedics
US Arthritis Market
Orthopedics
Osteoporosis Treatment Market
Orthopedics
Europe Bone Metastasis Market
Orthopedics
Canine Orthopedics Market
Orthopedics
Osteonecrosis Treatment Market