
 Elbow Stiffness Market | 2026-2036
Elbow Stiffness Market Size, Share, and Industry Trends Forecast 2026-2036
Elbow Stiffness Market Analysis
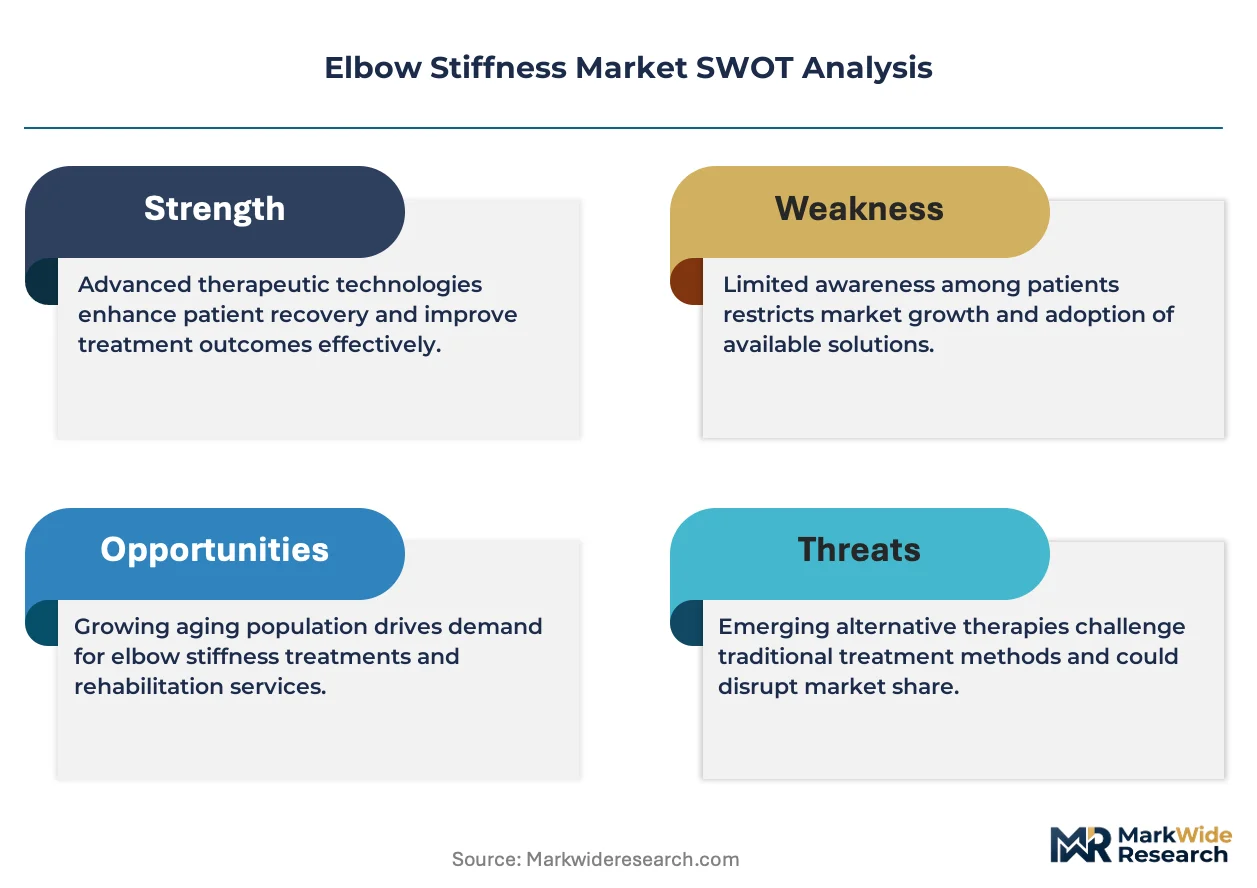
Single-source reliance on captive biologics manufacturing is decoupling from the broader procurement strategies of large orthopedic pharmaceutical suppliers. AbbVie sustains its position through concentrated R&D investment in inflammatory pathway modulation for joint mobility restoration. Johnson & Johnson Services, Inc. anchors its elbow stiffness portfolio through backward integration into biomaterial substrate production. Boehringer Ingelheim GmbH differentiates via specialized formulation expertise in sustained-release intra-articular therapies.
Elbow stiffness denotes the pathological reduction in range of motion at the ulnohumeral articulation, typically quantified by flexion-extension arc measurements below 100 degrees and often accompanied by heterotopic ossification or capsular contracture. The condition arises from trauma, prolonged immobilization, or degenerative processes, with treatment protocols targeting restoration of functional arcs exceeding 30-130 degrees for daily activities. Orthotic devices and braces occupy mature margin pools where reimbursement coding stability supports predictable cash flows, while robotic assistance technologies represent the fastest-expanding segment as hospitals justify capital expenditure through reduced revision rates and shortened rehabilitation cycles. Surgical implants concentrate value capture in tertiary referral centers performing complex release arthroplasties.
FDA 510(k) clearance requirements and ISO 13485 quality management standards govern device commercialization, with the former mandating substantial equivalence demonstrations for implantable elbow hardware and the latter enforcing risk-based process controls across manufacturing sites. The EU Medical Device Regulation imposes enhanced clinical evidence thresholds for class III joint restoration devices, extending certification timelines for manufacturers seeking CE marking. Stakeholders must monitor evolving health technology assessment methodologies at Germany's Institute for Quality and Efficiency in Health Care as these criteria increasingly determine market access for premium-priced robotic and modular intervention platforms.
Market Dynamics
Post-traumatic rehabilitation protocols in sports medicine are compressing device procurement cycles, forcing orthopedic suppliers to align implant releases with accelerated physical therapy timelines rather than traditional surgical scheduling.
Growth Catalysts
- FDA 510(k) pathway acceleration:Streamlined substantial equivalence demonstrations for implantable elbow hardware are shortening commercialization timelines for novel surface technologies.
- Sports medicine clinic expansion:Post-traumatic rehabilitation programs are standardizing continuous passive motion device protocols across Germany, the United Kingdom, and France.
- Biomaterial substrate innovation:Captive manufacturing of inflammatory pathway modulation compounds is decoupling large orthopedic suppliers from external biologics sourcing constraints.
Market Restraints
- EU MDR clinical evidence thresholds:Enhanced documentation requirements for class III joint restoration devices are extending CE marking timelines by 18-24 months for modular implant platforms.
- Silicone and polymer feedstock volatility:Orthotic brace manufacturers face margin compression from petrochemical price swings affecting elastomer component costs.
- Tertiary center concentration:Complex release arthroplasty volume clusters in university hospital networks, limiting addressable market for mid-tier surgical implant suppliers.
Strategic Opportunities
- Robotic assistance platform penetration:Hospitals in Spain and Italy are justifying capital expenditure through reduced revision rate data from German reference centers.
- Sustained-release intra-articular formulation gaps:Specialized depot injection expertise creates white space for localized anti-inflammatory delivery systems.
- Health technology assessment alignment:IQWiG methodology evolution in Germany is opening premium pricing corridors for outcome-validated modular intervention platforms.
Industry Challenges
- ISO 13485 audit density:Risk-based process control documentation requirements are straining quality management staffing at mid-scale manufacturing sites.
- Legacy CPM device integration:Continuous passive motion hardware lacks standardized data interoperability with emerging electronic health record systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Elbow Stiffness Market |
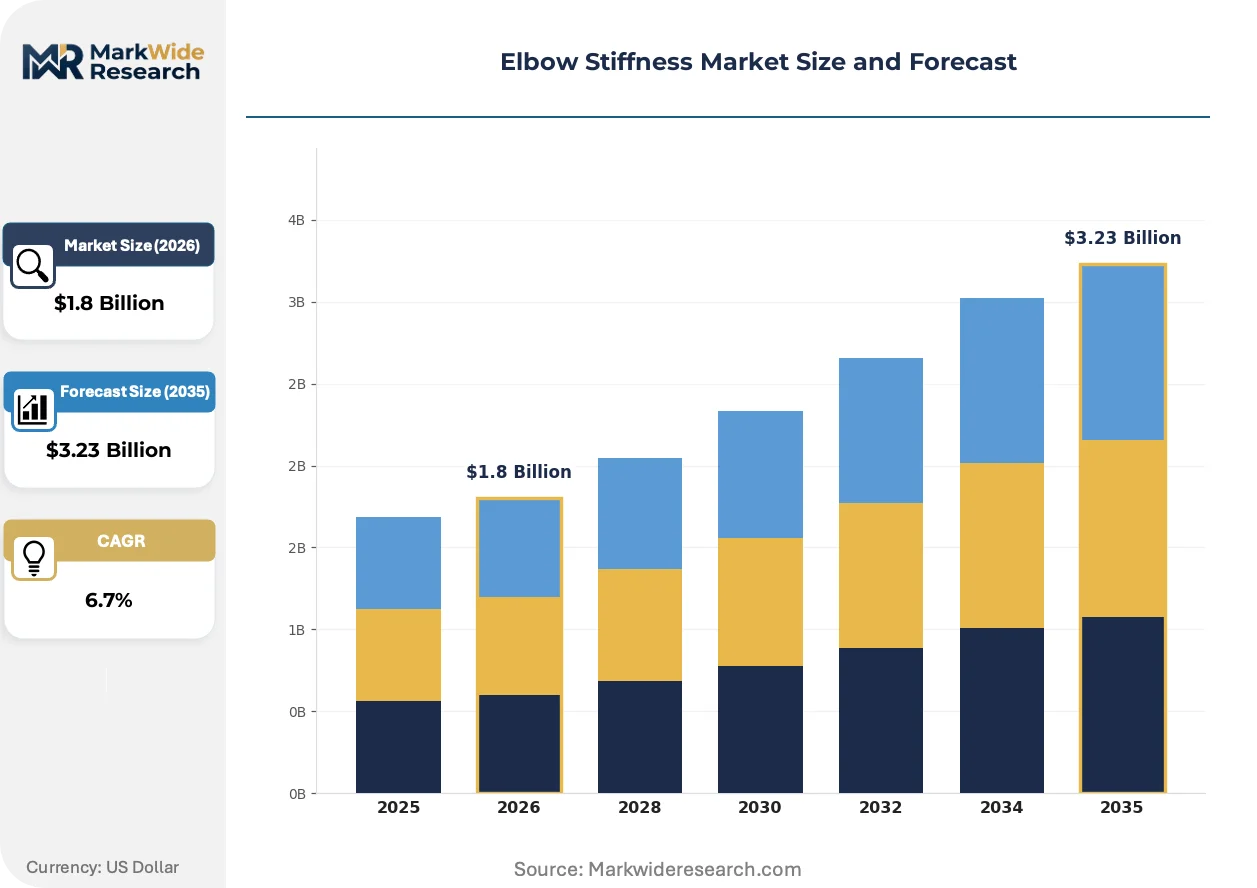
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Orthotic Devices, Physiotherapy Equipment, Surgical Implants, Braces Application: Rehabilitation, Pain Management, Surgery, Occupational Therapy End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Technology: Non-invasive, Surgical Procedures, Robotic Assistance, Modular Systems |
| Companies Covered | Regeneron Pharmaceuticals, Inc., Bristol-Myers Squibb Company, AbbVie, Johnson & Johnson Services, Inc., Hoffmann-La Roche Ltd., Boehringer Ingelheim GmbH, Pfizer, Inc., Amgen, Inc., Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Elbow Stiffness Market Emerging Trajectories
Orthopedic device development is pivoting from hardware-centric releases toward integrated rehabilitation ecosystems that bundle surgical implants with post-operative monitoring protocols.
Patient-specific 3D-printed titanium lattice implants are rewriting treatment protocols for complex heterotopic ossification cases. Tertiary referral centers in Germany and the Netherlands are adopting these platforms within 12-month procurement cycles. The technology is compressing revision surgery incidence by enabling anatomically precise capsular release geometries.
EU Medical Device Regulation Article 61 clinical evaluation requirements are forcing manufacturers to generate post-market surveillance data for existing elbow arthroplasty portfolios. This regulatory pressure is favoring incumbent suppliers with established clinical study infrastructure over emerging competitors. Class III joint restoration device segments are responding by consolidating certification resources through notified body partnerships.
Hospital procurement committees are unbundling after-sales service contracts from capital equipment purchases. Buyers in France and Belgium now negotiate robotic assistance platform maintenance separately from initial hardware acquisition. This behavioral shift is most visible in university hospital systems where orthopedic departments operate with independent capital allocation authority.
Elbow Stiffness Market Segmentation
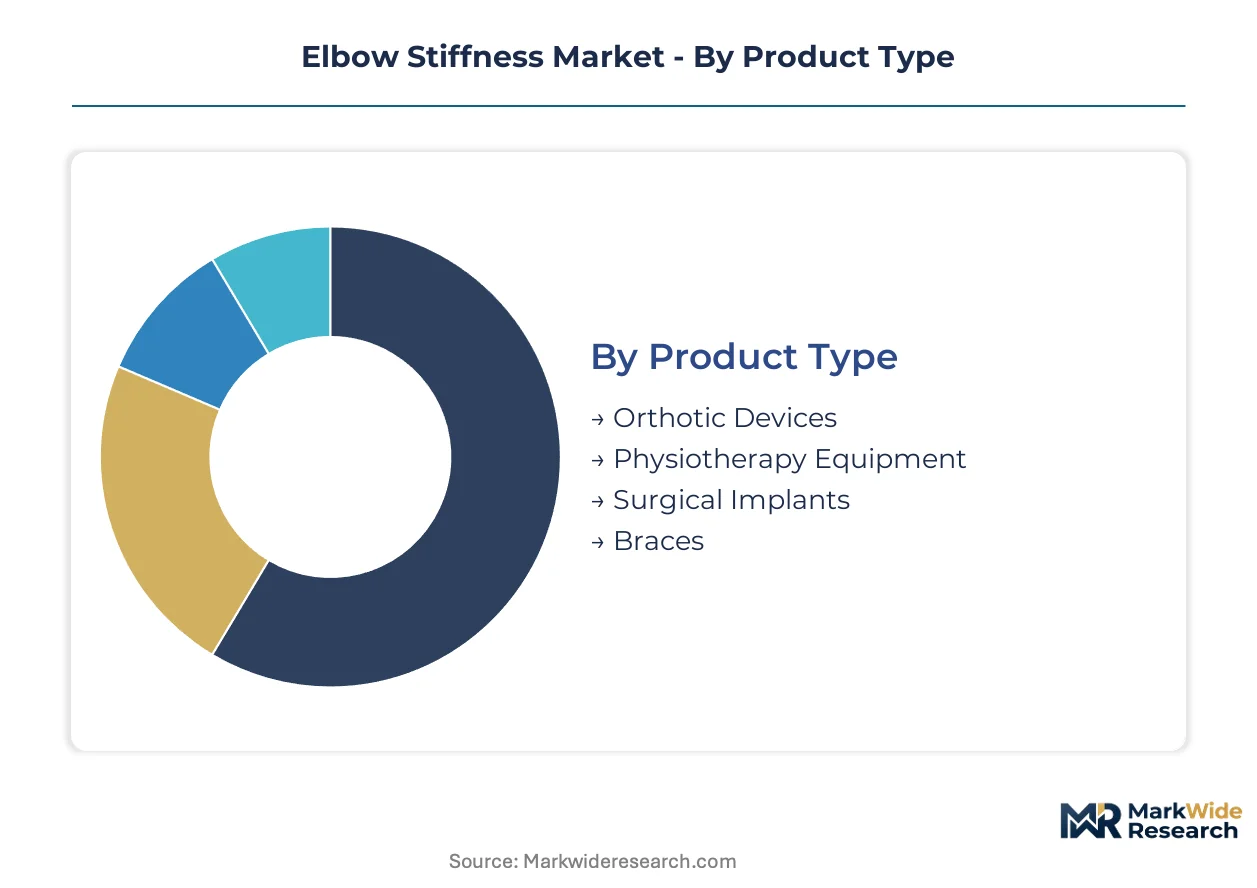
Elbow stiffness treatment protocols fragment across hardware, biologics, and service delivery models, with each segment carrying distinct regulatory burdens and margin profiles. Procurement committees in German university hospitals weight technology categories differently based on reimbursement coding stability and capital depreciation schedules.
Product Type:
FDA 510(k) clearance governs surgical implants and certain powered orthotic devices, while physiotherapy equipment falls under general wellness exemptions in the United States; the EU MDR captures all four segments under class IIA to III designations depending on invasiveness.
- Surgical Implants:Titanium and cobalt-chrome alloy constructs with porous surface treatments for osseointegration. Demand concentrates in Berlin, Hamburg, and Munich university hospital networks where complex release arthroplasty volume justifies specialized instrument tray investments.
- Orthotic Devices:Custom-molded thermoplastic and carbon-fiber composite braces with adjustable hinge mechanisms. German sports medicine clinics standardize procurement around DIN-certified suppliers, compressing replacement cycles to 18-24 months for high-utilization athletes.
- Physiotherapy Equipment:Continuous passive motion devices with programmable flexion-extension arcs.
- Braces:Off-the-shelf neoprene and elastic compression supports for post-immobilization maintenance.
Leading the category by volume: Braces. Growing fastest: Surgical Implants.
Application:
Cost tier stratification separates capital-intensive surgical intervention from recurring-revenue rehabilitation and pain management protocols, with occupational therapy occupying a mid-tier reimbursement position in German statutory health insurance frameworks.
- Rehabilitation:Structured protocols combining manual therapy, CPM device utilization, and progressive resistance training to restore 30-130 degree functional arcs. German rehabilitation centers in Baden-Württemberg and Bavaria cluster near orthopedic surgery hubs, enabling seamless post-operative handoffs.
- Surgery:Open and arthroscopic release procedures, heterotopic ossification excision, and total elbow arthroplasty for end-stage degeneration. Tertiary referral concentration in the Netherlands and Belgium limits addressable market for mid-tier implant suppliers without academic center contracts.
- Pain Management:Ultrasound-guided corticosteroid and hyaluronic acid injections with fluoroscopic verification.
- Occupational Therapy:Activity-based interventions targeting activities of daily living restoration.
Highest reimbursement per episode: Surgery. Expanding most quickly: Rehabilitation.
End User:
Customer type fragmentation creates divergent procurement behaviors, with hospitals bundling implant and robotic platform purchases while home care channels prioritize lightweight, patient-operable devices.
- Hospitals:Comprehensive service lines spanning emergency trauma stabilization through elective arthroplasty, with capital equipment committees in France and Belgium unbundling maintenance contracts from initial robotic platform acquisition. IQWiG assessment alignment determines premium pricing acceptance for modular intervention systems.
- Rehabilitation Centers:Dedicated post-acute facilities with standardized CPM protocols and physical therapist specialization in elbow mobilization techniques. Spanish and Italian centers reference German outcome data to justify capital expenditure on robotic assistance platforms.
- Clinics:Outpatient sports medicine and orthopedic practices with limited procedure room capacity.
- Home Care:Patient-directed brace wear and prescribed exercise program compliance.
Dominant procurement volume: Hospitals. Gaining share fastest: Rehabilitation Centers.
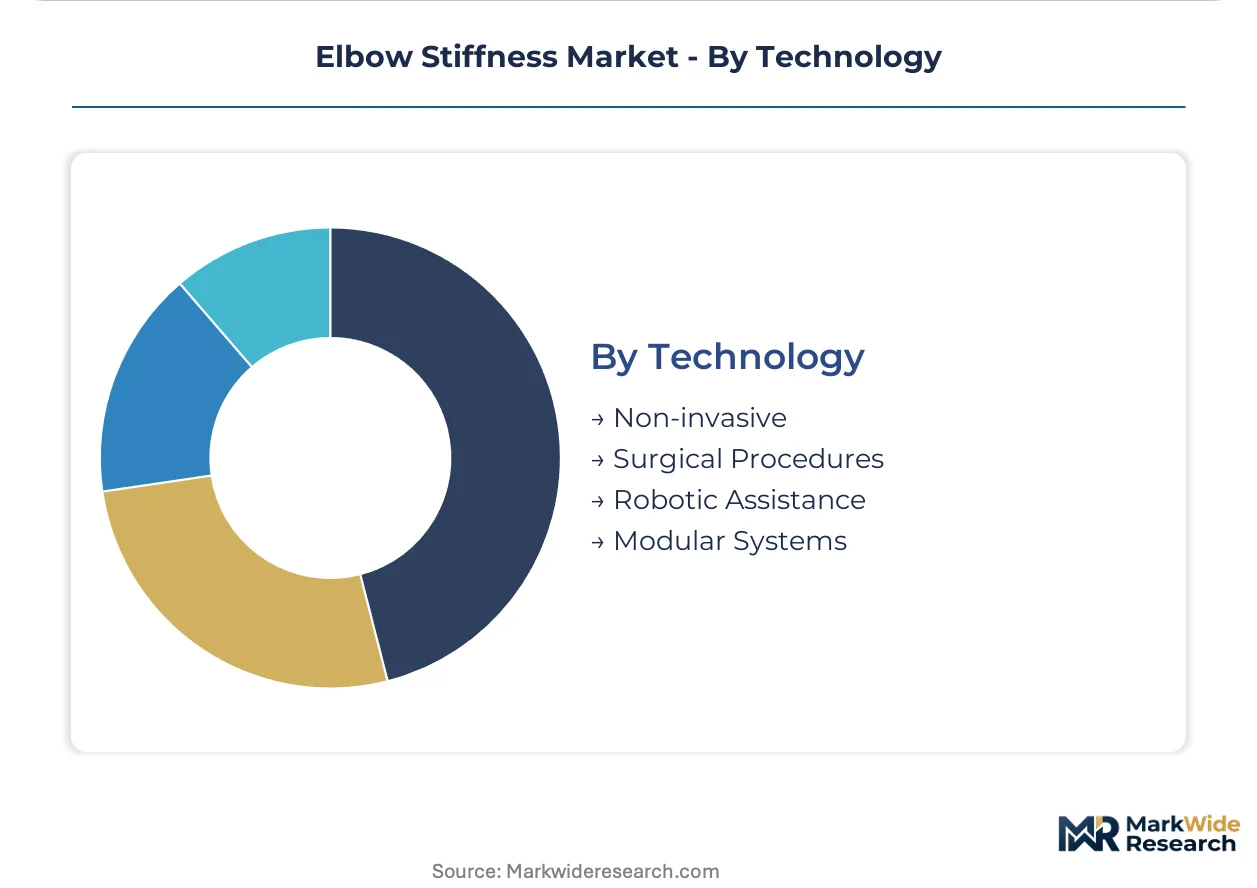
Technology:
Maturity gradient separates established non-invasive modalities from emerging robotic and modular platforms, with the latter requiring substantial equivalence demonstrations or novel device investigations depending on predicate availability.
- Robotic Assistance:Haptic-guided surgical platforms with preoperative planning software and intraoperative navigation for precise capsular release and implant positioning. German reference centers in Berlin and Munich generate revision rate data that Spanish and Italian hospitals cite in capital allocation justifications.
- Surgical Procedures:Open arthrolysis, arthroscopic debridement, and implant-based reconstruction with established CPT and DRG reimbursement codes. ISO 13485 quality management documentation density strains mid-scale manufacturing sites supplying this segment.
- Non-invasive:Manual therapy, splinting, and therapeutic ultrasound without device implantation.
- Modular Systems:Interchangeable implant components enabling intraoperative customization of constraint levels.
Widest installed base: Surgical Procedures. Steepest expansion trajectory: Robotic Assistance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German university hospitals in Berlin, Hamburg, and Munich anchor European demand for complex elbow arthroplasty hardware. Titanium feedstock supply from the Ruhr industrial basin supports regional implant manufacturing clusters.
Germany
IQWiG health technology assessments determine reimbursement corridors for robotic assistance platforms across Berlin, Hamburg, and Munich university hospital networks. The EU MDR Article 61 clinical evaluation requirements extend CE marking timelines for class III joint restoration devices. Specialized elbow arthroplasty centers cluster around Charité Berlin and Ludwig-Maximilians-Universität München, compressing procurement cycles for patient-specific 3D-printed titanium lattice implants.
United States
FDA 510(k) pathway acceleration shortens commercialization timelines for novel implant surface technologies targeting post-traumatic rehabilitation protocols. ISO 13485 quality management standards enforce risk-based process controls across manufacturing sites supplying orthopedic device OEMs. Tertiary referral centers in Boston and Philadelphia concentrate complex release arthroplasty volume, limiting addressable market for mid-tier surgical implant suppliers without academic contracts.
France
ANSM regulatory oversight governs class III device commercialization alongside EU MDR harmonized standards for joint restoration platforms. Hospital procurement committees in Paris and Lyon unbundle after-sales service contracts from robotic assistance platform capital purchases. University hospital systems with independent orthopedic department budgets negotiate maintenance agreements separately from initial hardware acquisition.
United Kingdom
NICE technology appraisals shape access decisions for premium-priced modular intervention systems within NHS England procurement frameworks. Post-market surveillance requirements under EU MDR transition protocols favor incumbent suppliers with established clinical study infrastructure. Tertiary centers in London and Manchester reference German outcome data to justify capital expenditure on haptic-guided surgical platforms.
Spain
Hospital procurement committees in Madrid and Barcelona cite German reference center revision rate data to justify robotic assistance platform capital allocation. Sports medicine clinic expansion across Catalonia and Andalusia standardizes continuous passive motion device protocols. Rehabilitation centers reference IQWiG-aligned outcome metrics when negotiating equipment procurement budgets.
Elbow Stiffness Market Vendor Landscape
Global majors compete with regional champions across regulatory certification capabilities and clinical evidence generation infrastructure. The vendor base stratifies between consolidated pharmaceutical-biologic conglomerates with captive manufacturing assets and specialized orthopedic device suppliers dependent on external substrate sourcing. Three archetypes dominate: inflammatory pathway modulation specialists, biomaterial substrate integrators, and sustained-release formulation experts. Competitive dynamics center on M&A activity targeting clinical study infrastructure and strategic partnerships with German university hospital reference centers.
Among biologic-centric developers, Regeneron Pharmaceuticals, Inc. and Bristol-Myers Squibb Company exemplify the inflammatory pathway modulation archetype, occupying positions anchored by concentrated R&D investment in joint mobility restoration. AbbVie and Johnson & Johnson Services, Inc. represent the backward integration archetype, with the latter controlling captive biomaterial substrate production. Boehringer Ingelheim GmbH anchors the specialized formulation tier through depot injection expertise in sustained-release intra-articular therapies.
| Leading Market Players |
|---|
| Regeneron Pharmaceuticals, Inc. |
| Bristol-Myers Squibb Company |
| AbbVie |
| Johnson & Johnson Services, Inc. |
| Hoffmann-La Roche Ltd. |
| Boehringer Ingelheim GmbH |
| Pfizer, Inc. |
| Amgen, Inc. |
| Novartis AG |
| Others |
Supply Flow & Price Mechanics
Captive biomaterial substrate production by Johnson & Johnson Services, Inc. and AbbVie anchors both supply security and premium pricing power for inflammatory pathway modulation compounds. This backward integration insulates large orthopedic suppliers from external biologics sourcing constraints while supporting sustained-release intra-articular therapy premiums.
Pricing Analysis
Warranty and after-sales service unbundling from capital equipment purchases dominates hospital procurement negotiations in France and Belgium. Pricing stratifies across premium robotic assistance platforms, standard surgical implant tiers, and economy orthotic brace levels, with DIN-certified suppliers in Germany commanding 15-20% brand premiums over uncertified alternatives. Cost compression in silicone and polymer feedstock components is intensifying because petrochemical price volatility directly impacts elastomer brace margins. Rehabilitation centers exhibit highest price sensitivity due to standardized CPM device protocols, while tertiary referral centers absorb premium implant pricing through DRG reimbursement stability.
Supply Chain Analysis
Regional distribution centers in the Ruhr industrial basin feed German university hospital networks with titanium feedstock for patient-specific 3D-printed lattice implants. Manufacturing draws from cobalt-chrome alloy suppliers in Germany, thermoplastic processors in the Netherlands, and sustained-release formulation specialists in Switzerland. Single-source vulnerability concentrates in captive biologics manufacturing where inflammatory pathway modulation compounds hinge on concentrated R&D infrastructure. Distribution runs through orthopedic device OEMs with ISO 13485-certified quality management systems serving hospital capital equipment committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints in EU MDR-certified manufacturing capacity prop pricing power for incumbent orthopedic device suppliers. Class III joint restoration device certification timelines extending 18-24 months limit rapid capacity expansion.
For Market Incumbents: Acquire clinical study infrastructure to defend against emerging competitors lacking post-market surveillance capabilities. Consolidate notified body partnerships to streamline CE marking timelines for modular implant platforms. Expand captive biomaterial substrate production in Germany to reduce dependency on external inflammatory compound sourcing. For New Entrants and Emerging Players: Begin with sustained-release intra-articular formulation gaps in Spanish and Italian rehabilitation centers referencing German outcome data. Target white space in depot injection expertise for localized anti-inflammatory delivery systems. Pursue hospital procurement committee engagement through unbundled maintenance contract offerings that separate capital expenditure from service agreements. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by large orthopedic pharmaceutical suppliers seeking clinical evidence generation infrastructure. Five-to-ten year viability favors backward-integrated biomaterial substrate producers over pure-play formulation specialists. Monitor IQWiG health technology assessment methodology evolution as the inflection signal determining premium pricing corridor access for robotic assistance platforms.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Investment | Notified body partnerships compress CE marking timelines for class III joint restoration devices by 12-18 months. |
| Hospital System Partnership | Charité Berlin and Ludwig-Maximilians-Universität München reference center contracts validate robotic platform efficacy data. |
| Backward Integration into Biomaterials | Captive inflammatory pathway modulation compound production decouples suppliers from external biologics constraints. |
| Software Companion Development | Preoperative planning platforms for haptic-guided surgical systems reduce revision rates in tertiary centers. |
| Reimbursement Strategy Alignment | IQWiG outcome validation opens premium pricing corridors for modular intervention platforms in German statutory insurance. |
Methodological Framework
Multi-period observation of FDA 510(k) clearance timelines, EU MDR certification completion rates, and hospital capital equipment procurement cycles anchored the trend analysis, supplemented by interviews with orthopedic surgeons, hospital purchasing committee members, biomedical engineers, GPO contracts managers, and regulatory affairs leads at device manufacturers. Secondary validation drew from FDA 510(k) database filings, EMA submissions, IQWiG health technology assessment publications, and hospital procurement databases. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the orthopedic device sector.
Segment-weighting across product type, application, end user, and technology dimensions calibrated volume and value outputs throughout the forecast period. Surgical implant, orthotic device, physiotherapy equipment, and brace categories each carried distinct regulatory burden coefficients. CAGRs derived from procedure volume growth trajectories in German university hospital networks and rehabilitation center expansion patterns in Spain and Italy. Forecast inputs incorporated continuous passive motion device protocol standardization rates and robotic assistance platform capital expenditure justification timelines.
Underlying measurement precision varies by segment; surgical implants and robotic assistance platforms carry tighter precision than orthotic braces due to concentrated tertiary center reporting. Forecasts reflect documented assumptions regarding EU MDR transition completion, IQWiG methodology stability, and silicone feedstock price normalization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedics
Athletic Knee Treatment Market
Orthopedics
Hips and Knees Reconstructive Market
Orthopedics
Genu Recurvatum Market
Orthopedics
Rotator Cuff Arthropathy Repair Market
Orthopedics
Swollen Knee Treatment Market
Orthopedics
Osteoporosis Treatment Market
Orthopedics
Canine Orthopedics Market
Orthopedics
Tendon Repair Market
Orthopedics
Anti-Osteoporosis Therapy and Fracture Healing Market
Orthopedics
Osteoarthritis Treatment Market
Orthopedics
ACL Reconstruction Market
Orthopedics
Hallux Rigidus Market
Orthopedics
Rickets Market
Orthopedics
Global Osteoarthritis Therapeutics Market
Orthopedics
Orthopedic Repair Market
Orthopedics
Orthopedic Pillow Market