
 Canine Orthopedics Market | 2026-2036
Canine Orthopedics Market Size, Share, and Industry Trends Forecast 2026-2036
Canine Orthopedics Market Intelligence
Modular surgical implant kits is rebalancing how veterinary purchasing departments evaluate capital outlay against per-procedure flexibility. DePuy Synthes anchors its position through backward integration into precision-machined titanium components. Movora competes with a focused portfolio of cruciate repair systems designed exclusively for companion animals. KYON AG differentiates through proprietary locking-plate technology developed for canine-specific anatomical geometries.
Canine orthopedics encompasses the surgical and non-surgical correction of musculoskeletal disorders in dogs, employing titanium alloy implants, polyethylene bearing surfaces, and carbon-fiber composite braces manufactured to sub-millimeter tolerances for load-bearing recovery. The field serves primarily to restore mobility in working, sporting, and companion animals while reducing chronic pain and euthanasia rates. Surgical implants command the dominant share of product-type revenue due to irreversible joint degradation in large-breed dogs, while rehabilitation equipment represents the fastest-expanding category as post-operative physical therapy protocols gain protocol adoption. Ligament injuries, particularly cranial cruciate rupture, generate the highest procedure volume among application segments and sustain recurring instrument and implant consumption.
The FDA Center for Veterinary Medicine mandates pre-market notification for implantable orthopedic devices, while ISO 10993 biocompatibility testing governs material safety acceptance across North American and European distribution channels. The EU Veterinary Medicines Regulation and MDR framework impose additional conformity requirements on devices sold through European veterinary distributors. Stakeholders must monitor evolving reimbursement pathways through pet insurance carriers and specialty credentialing standards set by the American College of Veterinary Surgeons.
Market Dynamics
Modular surgical implant kits are compressing capital expenditure timelines for specialty veterinary clinics while fragmenting purchasing authority away from centralized hospital procurement departments toward individual surgeons.
Growth Catalysts
- FDA Center for Veterinary Medicine pre-market notification pathway:Streamlined 510(k) clearance for titanium alloy implants accelerates product launch cycles for domestic manufacturers targeting cranial cruciate repair procedures.
- Pet insurance reimbursement expansion:Specialty carriers now cover 70-90% of orthopedic surgery costs in the United States, removing price barriers for large-breed dog owners facing ligament failure.
- ISO 10993 biocompatibility harmonization:Unified material safety testing protocols reduce redundant certification costs across North American and European distribution channels.
Market Restraints
- Titanium sponge supply concentration:Russian and Chinese smelters control 60% of aerospace-grade titanium feedstock, exposing implant manufacturers to raw material price volatility and export restriction risk.
- American College of Veterinary Surgeons credentialing scarcity:Board-certified orthopedic specialists number fewer than 400 across the United States, creating procedural bottleneck capacity constraints.
- Polyethylene bearing surface oxidation:Gamma sterilization-induced degradation limits shelf life and complicates inventory management for distributors serving low-volume practices.
Strategic Opportunities
- Brazilian specialty clinic underpenetration:São Paulo and Rio de Janeiro metro areas host fewer than 15 dedicated orthopedic referral centers for a population exceeding 30 million companion animals.
- 3D-printed patient-specific implant convergence:Additive manufacturing of cobalt-chrome cutting guides paired with titanium porous scaffolds enables anatomically matched procedures previously impossible with standard inventory.
- Direct-to-clinic digital distribution platforms:Veterinary purchasing cooperatives are consolidating procurement volume through cloud-based implant ordering systems that bypass traditional distributor markups.
Industry Challenges
- Orthopedic surgery residency pipeline gaps:American College of Veterinary Surgeons-approved training programs graduate insufficient residents to replace retiring specialists, extending recruitment timelines for expanding practices.
- Implant-bone interface validation complexity:Osseointegration studies for novel surface coatings require 24-month longitudinal follow-up, delaying regulatory submissions and commercialization timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canine Orthopedics Market |
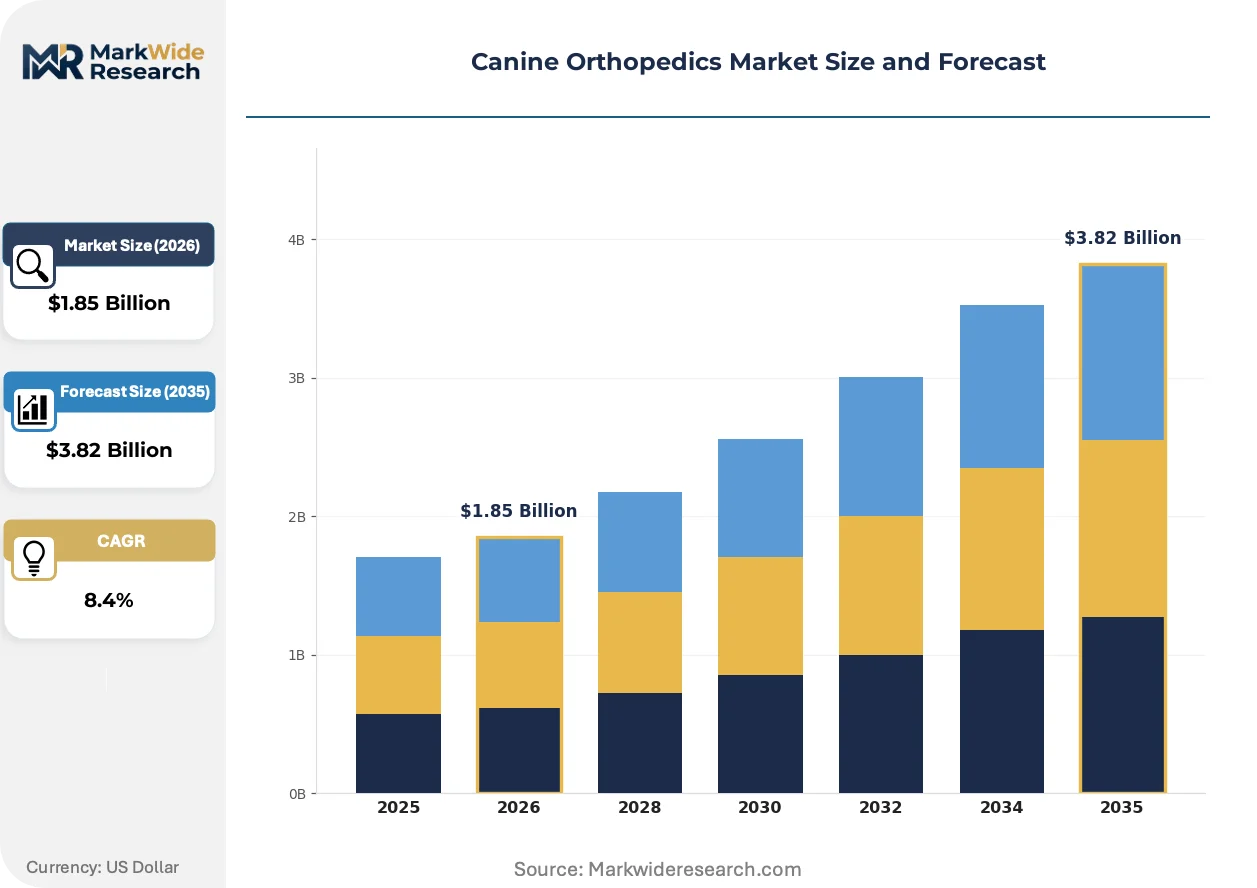
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Orthotic Braces, Surgical Implants, Rehabilitation Equipment, Pain Management Devices Application: Fractures, Ligament Injuries, Arthritis, Joint Replacement End User: Veterinary Clinics, Animal Hospitals, Research Institutions, Pet Owners Delivery Mode: Online Sales, Direct Sales, Distributors, Veterinary Suppliers |
| Companies Covered | B. Braun Melsungen AG, Movora, DePuy Synthes (Johnson & Johnson), Arthrex, Inc., Orthomed (UK) Ltd, Veterinary Instrumentation, BioMedtrix, LLC, KYON AG, Integra LifeSciences Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canine Orthopedics Market Strategic Shifts & Innovations
Digital surgical planning tools and biomaterial surface engineering are compressing the gap between human and veterinary orthopedic standards while redistributing value capture toward software-enabled implant systems.
Patient-specific 3D-printed titanium cutting guides are modularizing pre-operative workflow in high-volume cruciate repair centers. Specialty practices with annual procedure counts exceeding 200 cases have adopted CT-to-implant planning software at accelerating rates. This technology is modularizing the traditional surgeon-manufacturer relationship by enabling direct digital file transfer that bypasses conventional instrument tray logistics.
EU Medical Device Regulation (MDR) reclassification of active implantable orthopedic devices imposes notified body involvement previously exempt under the veterinary medical device directive. Manufacturers must now maintain quality management system certification through designated European organizations regardless of human-device equivalence claims. Smaller implant suppliers serving exclusively veterinary markets face disproportionate compliance cost burdens relative to diversified human health device portfolios.
After-sales technical support unbundling is separating implant purchase from intraoperative assistance in mature United States markets. Large specialty groups now negotiate direct surgeon training contracts independent of implant procurement agreements, reversing the historical bundled model. This pattern concentrates most visibly in California and Texas metropolitan corridors where corporate practice ownership aggregates purchasing leverage across multiple facilities.
Canine Orthopedics Market Segmentation
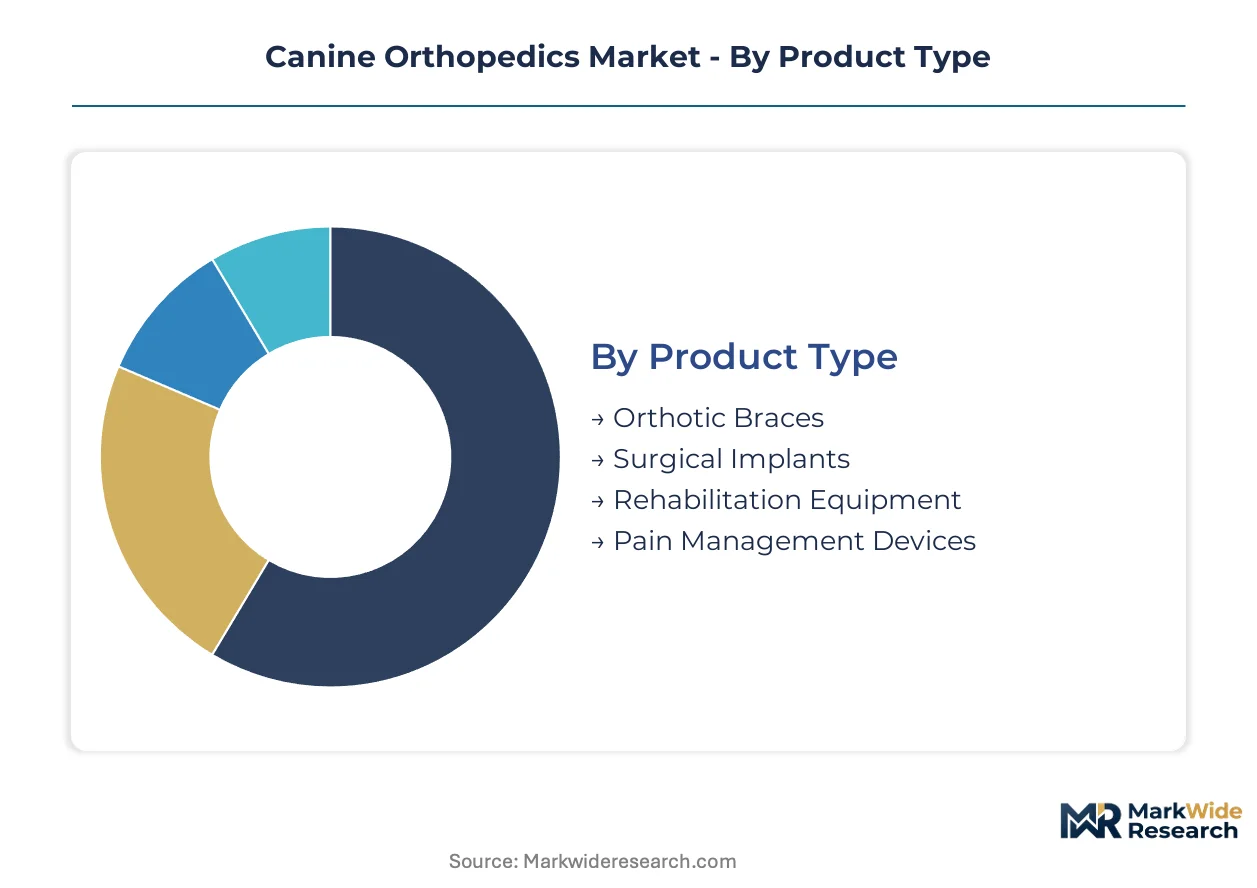
Canine orthopedic purchasing splits along procedure complexity and care setting economics. Product customization ranges from off-the-shelf rehabilitation aids to patient-matched surgical implants requiring CT-based preoperative planning.
Product Type:
Standardization dominates consumable categories while customization concentrates in permanent implants where anatomical fit determines outcomes.
- Surgical Implants:Titanium alloy plates, screws, and interlocking nails manufactured to sub-millimeter tolerances for load-bearing applications. Demand concentrates in United States specialty practices performing cranial cruciate ligament repairs on large-breed dogs, driven by pet insurance reimbursement expansion removing cost barriers for owners.
- Rehabilitation Equipment:Underwater treadmills, therapeutic laser systems, and passive range-of-motion devices supporting postoperative recovery protocols. Adoption accelerates in California and Texas metropolitan corridors where corporate practice groups aggregate physical therapy service lines across multiple facilities.
- Orthotic Braces:Carbon-fiber composite and thermoplastic support devices for non-surgical management of joint instability.
- Pain Management Devices:Implantable drug delivery pumps and transcutaneous electrical nerve stimulation units for chronic osteoarthritis.
Leading the category by volume: Surgical Implants. Growing fastest: Rehabilitation Equipment.
Application:
Procedure frequency inversely correlates with intervention invasiveness across this category.
- Ligament Injuries:Cranial cruciate rupture generates the highest annual procedure volume in companion animal orthopedics, sustaining recurring consumption of suture materials, bone anchors, and specialized instrument sets. United States referral practices report this indication consumes over half of implant inventory budgets.
- Fractures:Traumatic long-bone and pelvic injuries requiring internal fixation with locking plate systems or external skeletal fixation. Military and police working dog programs in Germany and the Netherlands drive specification standards for implant durability under extreme mechanical loading.
- Arthritis:Degenerative joint disease managed through pharmaceutical intervention, intra-articular injections, and salvage procedures.
- Joint Replacement:Total hip and elbow arthroplasty using cemented and cementless prosthetic systems.
Most procedures annually: Ligament Injuries. Steepest expansion trajectory: Joint Replacement.
End User:
Capital intensity and credentialing requirements stratify purchasing authority across this category.
- Veterinary Clinics:Primary care and limited specialty practices performing soft-tissue procedures and fracture management with portable radiography and basic orthopedic instrument sets. These facilities concentrate implant purchasing through veterinary distributors serving low-volume accounts with consignment inventory models.
- Animal Hospitals:Multi-specialty referral institutions with dedicated orthopedic surgery suites, CT imaging capability, and residency training programs. The American College of Veterinary Surgeons credentialing scarcity concentrates purchasing leverage among fewer than 400 board-certified specialists across United States academic and private referral centers.
- Research Institutions:Veterinary schools and contract research organizations conducting implant biocompatibility studies and surgical technique validation.
- Pet Owners:Direct consumers of over-the-counter orthotic braces, joint supplements, and home rehabilitation aids.
Category leader by revenue: Animal Hospitals. Gaining share fastest: Veterinary Clinics adding orthopedic service lines.
Delivery Mode:
Channel selection tracks order frequency, technical support requirements, and geographic proximity to implant manufacturing.
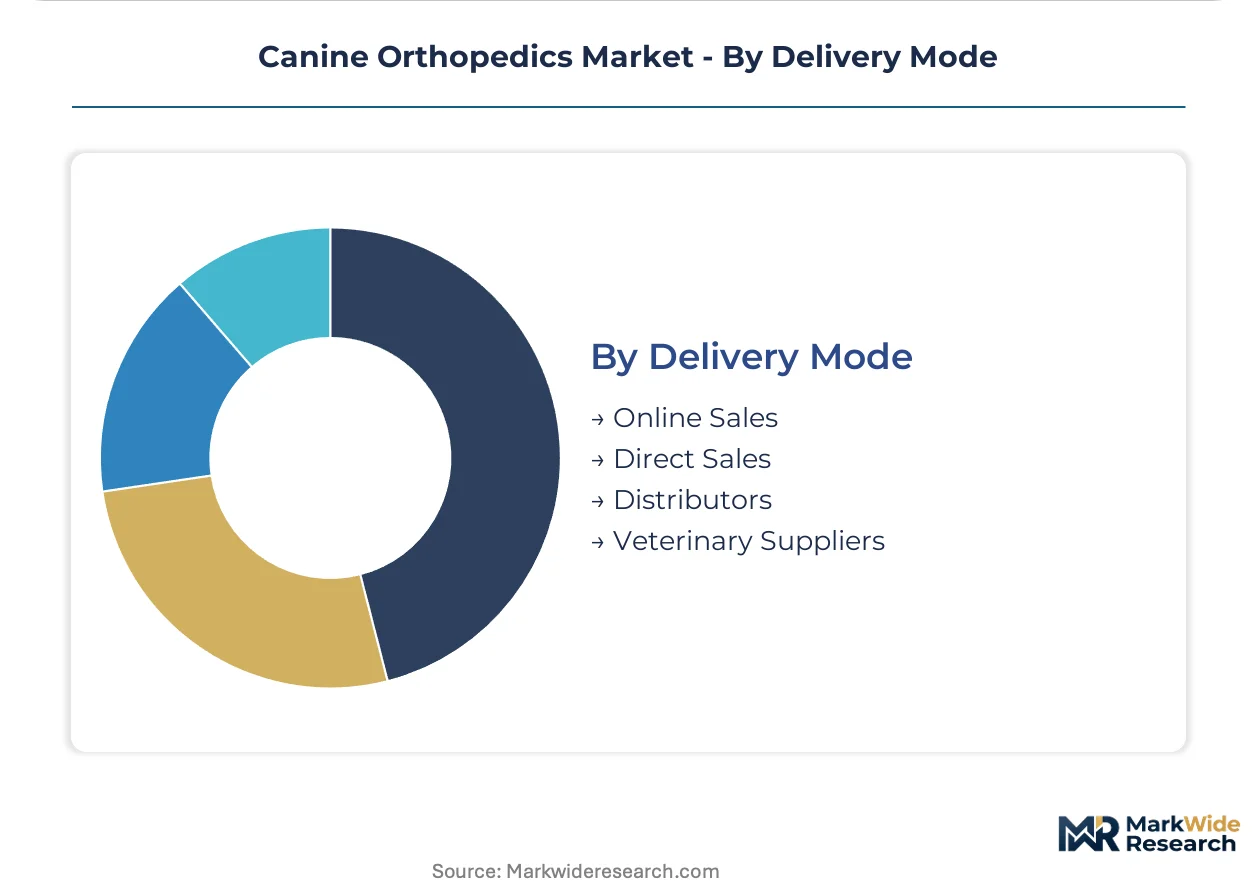
- Distributors:Regional veterinary supply houses maintaining local inventory of standard plates, screws, and suture materials with same-day delivery to metropolitan practices. These intermediaries face margin compression as manufacturer direct-sales initiatives bypass traditional markups.
- Direct Sales:Manufacturer representatives serving high-volume specialty accounts with surgeon training, intraoperative technical support, and custom implant procurement. DePuy Synthes and Movora deploy dedicated field teams for United States academic veterinary medical centers.
- Online Sales:E-commerce platforms for consumable fixation components and rehabilitation supplies.
- Veterinary Suppliers:Cooperative purchasing organizations consolidating procurement volume across independent practice networks.
Dominant channel by transaction volume: Distributors. Expanding most quickly: Direct Sales with unbundled technical support contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Implant manufacturing concentrates in precision-machining clusters across Germany, Switzerland, and the United States, while procedure volume and pet insurance reimbursement drive consumption in North American and Western European veterinary markets.
United States
Specialty referral practices in California and Texas metropolitan corridors perform the highest annual procedure volumes for cranial cruciate ligament repair. The FDA Center for Veterinary Medicine maintains pre-market notification requirements for titanium alloy implants under streamlined 510(k) pathways. Greater Boston hosts contract research organizations conducting longitudinal osseointegration studies for novel surface coatings.
Germany
Military and police working dog programs in Bavaria and North Rhine-Westphalia establish durability specifications for locking plate systems under extreme mechanical loading. The EU Medical Device Regulation reclassification imposes notified body involvement for active implantable orthopedic devices regardless of human-device equivalence. Stuttgart precision-machining suppliers provide aerospace-grade titanium feedstock to veterinary implant manufacturers.
Switzerland
Swissmedic maintains quality management system certification requirements for manufacturers distributing through European veterinary channels. Zurich and Basel host engineering firms developing proprietary locking-plate technology calibrated for canine-specific anatomical geometries. The country's medical device heritage supports sub-millimeter tolerance manufacturing for load-bearing applications.
United Kingdom
Veterinary distributor networks in London and the Southeast maintain consignment inventory models for standard fixation components serving low-volume primary care practices. The Veterinary Medicines Directorate aligns with EU MDR frameworks for cross-border device conformity. Scotland's agricultural colleges contribute to surgical technique validation research for working dog populations.
Brazil
São Paulo and Rio de Janeiro metro areas host fewer than fifteen dedicated orthopedic referral centers serving a companion animal population exceeding thirty million. ANVISA regulates imported implantable devices through registration pathways that delay product launch timelines relative to North American markets. Specialty clinic underpenetration creates expansion opportunities for direct-to-clinic distribution platforms bypassing traditional veterinary supply intermediaries.
Canine Orthopedics Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across three discernible tiers. Human health device manufacturers leverage backward integration into precision-machined titanium components to serve adjacent veterinary markets. Dedicated animal health companies compete through canine-exclusive product portfolios and surgeon training relationships. The competitive terrain rewards scale-driven manufacturing efficiency, regulatory pathway expertise, and unbundled technical support contracts negotiated independently of implant procurement.
Within the diversified conglomerate tier, DePuy Synthes anchors a position through captive supply of aerospace-grade components, while B. Braun Melsungen AG occupies a comparable manufacturing scale. Movora exemplifies the pure-play specialist archetype with focused cruciate repair systems. KYON AG represents the engineering-intensive segment through proprietary locking-plate development. Arthrex, Inc. sits within the human-veterinary crossover category, leveraging surgical technique platforms across species boundaries.
| Leading Market Players |
|---|
| B. Braun Melsungen AG |
| Movora |
| DePuy Synthes (Johnson & Johnson) |
| Arthrex, Inc. |
| Orthomed (UK) Ltd |
| Veterinary Instrumentation |
| BioMedtrix, LLC |
| KYON AG |
| Integra LifeSciences Corporation |
| Others |
Cost & Logistics Intelligence
3D-printed patient-specific implant convergence simultaneously compresses per-unit manufacturing economics and concentrates titanium feedstock purchasing power among additive-capable producers. This dual shift rewards backward-integrated manufacturers with captive aerospace-grade titanium sponge access while fragmenting pricing authority across unbundled technical support contracts.
Pricing Analysis
Margin tightening in standard implant tiers reflects distributor disintermediation as direct-to-clinic digital platforms bypass traditional markups. Pricing stratifies across premium patient-matched implants, standard modular kits, and economy consumables, with differentiation anchored in ISO 10993 certification tier and surgeon training bundling. Cost-down pressure on economy fixation components accelerates because Brazilian and Southeast Asian clinics prioritize capital efficiency over brand premium. Corporate specialty groups in California and Texas corridors exhibit lowest price sensitivity due to pet insurance reimbursement density, while independent primary care practices face acute budget constraints.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Zurich, and Boston coordinate hub-and-spoke fulfillment patterns for precision-machined titanium components. Manufacturing gravity centers on Germany, Switzerland, and the United States, with aerospace-grade titanium sponge drawing from Russian and Chinese smelter concentration. Raw material dependencies span titanium alloy billet, polyethylene bearing stock, and cobalt-chrome cutting guide substrates. Single-source vulnerability in titanium sponge supply exposes implant manufacturers to export restriction risk. Distribution runs through veterinary purchasing cooperatives consolidating procurement volume across independent practice networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Medical Device Regulation reclassification imposes notified body certification costs that erect compliance moats around quality management system investments, disadvantaging smaller veterinary-exclusive suppliers relative to diversified human health device portfolios.
For Market Incumbents: Deepen backward integration into precision-machined titanium components to defend margin position against raw material volatility from Russian and Chinese smelter concentration. Expand captive supply agreements for aerospace-grade feedstock while investing in ISO 10993 biocompatibility testing infrastructure to accelerate regulatory submissions. Lock in surgeon training relationships through unbundled technical support contracts independent of implant procurement.
For New Entrants and Emerging Players: Launch via direct-to-clinic digital distribution platforms targeting Brazilian specialty clinic underpenetration in São Paulo and Rio de Janeiro metro corridors. Focus initial product portfolios on rehabilitation equipment where regulatory barriers remain lowest and corporate practice physical therapy service line expansion drives demand. Prioritize cloud-based implant ordering systems that bypass traditional distributor markups.
For Investors and Strategic Acquirers: Re-rating potential sits with engineering-intensive pure-play specialists given proprietary locking-plate technology differentiation and canine-exclusive portfolio focus. Long-term viability hinges on additive manufacturing capability convergence and direct digital file transfer workflows. Watch for American College of Veterinary Surgeons residency pipeline gaps resolving as inflection indicator for procedural capacity expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Titanium Feedstock | Captive supply of aerospace-grade sponge insulates margin from Russian and Chinese export volatility. |
| ISO 10993 Biocompatibility Certification Investment | Accelerated regulatory submissions compress commercialization timelines for novel surface coatings. |
| Direct-to-Clinic Digital Platform Launch | Bypasses traditional veterinary distributor markups in Brazilian and Southeast Asian expansion markets. |
| Surgeon Training Contract Unbundling | Separates technical support from implant procurement in California and Texas corporate practice corridors. |
| 3D-Printed Patient-Specific Implant Development | Enables anatomically matched procedures previously impossible with standard inventory kits. |
Research Approach
Independent corroboration across veterinary orthopedic surgeons, implant manufacturing executives, and pet insurance reimbursement specialists underwrites the qualitative findings. Primary interviews with board-certified specialists, biomedical engineers at precision-machining suppliers, and procurement managers at corporate specialty practice groups combined with secondary validation from FDA 510(k) filings, ISO 10993 test reports, and American College of Veterinary Surgeons residency program data. Bottom-up procedure volume estimates and top-down implant consumption patterns were triangulated to anchor market sizing.
Comparable-period anchoring tied projection horizons to historical cranial cruciate repair procedure growth and pet insurance penetration trajectories. The analytical framework modeled segmentation across surgical implants, rehabilitation equipment, orthotic braces, and pain management devices, with further disaggregation by ligament injury, fracture, arthritis, and joint replacement applications. CAGRs were derived from procedure volume elasticity to insured pet population growth and specialty clinic expansion rates. Forecast inputs incorporated titanium sponge price volatility indices and American College of Veterinary Surgeons credentialing pipeline data.
Titanium export restrictions, polyethylene bearing surface oxidation shelf-life limitations, and orthopedic surgery residency graduation shortfalls are the dominant revision risks. Forecasts reflect documented assumptions regarding pet insurance reimbursement expansion and EU MDR compliance cost trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedics
Osteonecrosis Treatment Market
Orthopedics
Orthopedic Pillow Market
Orthopedics
Rotator Cuff Arthropathy Repair Market
Orthopedics
Swollen Knee Treatment Market
Orthopedics
Global Foot Drop Treatment Market
Orthopedics
Osteopenia Treatment Market
Orthopedics
Podiatry Services Market
Orthopedics
Athletic Knee Treatment Market
Orthopedics
Osgood-Schlatter Market
Orthopedics
Osteoarthritis Treatment Market
Orthopedics
ACL Reconstruction Market
Orthopedics
Orthopedic Soft Tissue Repair Market
Orthopedics
Plantar Fasciitis Market
Orthopedics
Bilateral Osteoarthritis Treatment Market
Orthopedics
Bone Spur Market
Orthopedics
Spinal Stenosis Market