
 Orthopedics Market | 2026-2036
Orthopedics Market Size, Share, and Industry Trends Forecast 2026-2036
Orthopedics Market Outlook
Multi-source procurement for implant-grade titanium and polyethylene is decoupling from traditional single-source contracts across the orthopedics supply base. Stryker Corporation leverages captive manufacturing networks to secure alloy supply chains for its trauma portfolio. Zimmer Biomet Holdings anchors its joint reconstruction franchise through R&D intensity in patient-matched instrumentation. Johnson & Johnson MedTech differentiates via robotics-integrated surgical platforms that tighten its grip on high-complexity spine procedures.
Orthopedics encompasses the surgical discipline and device ecosystem dedicated to restoring musculoskeletal function through implantable hardware, biologics, and instrumented intervention, typically involving cobalt-chrome alloys, ultra-high molecular weight polyethylene bearings, and recombinant protein matrices engineered for osteoinduction. Joint Replacement commands the largest revenue pool within Product Type as procedure volumes for knee and hip arthroplasty sustain hospital purchasing commitments, while Robotics within Technology is capturing disproportionate capital expenditure as ASCs compete on precision positioning and reduced length-of-stay metrics. Sports Medicine within Application remains structurally fragmented, with margin accretion flowing to allograft and biologic adjuncts rather than commodity anchors.
The FDA's 510(k) clearance pathway and the EU MDR's enhanced clinical evidence requirements for Class III implantables are elevating barriers to market entry and extending validation timelines for novel device submissions. ISO 5832 standards for metallic implant materials shape alloy selection and biocompatibility testing protocols that manufacturers must satisfy before commercial distribution. Stakeholders must monitor how FDA digital health pre-certification and EU MDR notified body capacity constraints will reshape competitive timelines for next-generation robotic and patient-specific implant platforms.
Market Dynamics
The orthopedics market is experiencing a fundamental restructuring as ambulatory surgery centers displace inpatient hospital volumes for joint replacement procedures, compressing traditional purchasing hierarchies and forcing manufacturers to reconfigure distribution networks around same-day discharge protocols.
Growth Catalysts
- Aging Demographics:The United States sustains procedure volumes through Medicare-eligible population expansion and commercial payer reimbursement dynamics that incentivize outpatient migration.
- EU Medical Device Regulation:MDR's enhanced clinical evidence requirements for Class III implantables are elevating barriers that favor established manufacturers with robust quality management systems.
- Patient-Matched Instrumentation:Preoperative planning software and additive manufacturing convergence enables personalized cutting guides that reduce operative time and implant malposition rates.
Market Restraints
- Alloy Supply Concentration:Implant-grade titanium procurement depends on a limited supplier base concentrated in specific mining and processing geographies, exposing trauma portfolios to input volatility.
- Notified Body Capacity:EU MDR implementation has created bottlenecks at designated conformity assessment organizations, extending validation timelines for novel device submissions by 12-24 months.
- Polyethylene Bearing Wear:Cross-linked ultra-high molecular weight polyethylene exhibits oxidative degradation in vivo, limiting long-term survivorship data for younger, active patient cohorts.
Strategic Opportunities
- Robotics-Integrated Platforms:Capital expenditure competition among ASCs for precision positioning systems creates white space for vendors bundling hardware with disposable instrument revenue streams.
- Biologic Adjuncts:Allograft and recombinant protein matrices command margin accretion in sports medicine applications where commodity anchors face pricing compression.
- Digital Health Pre-Certification:FDA's pilot program for software-as-a-medical-device offers accelerated pathways for AI-enabled surgical planning tools that complement implantable hardware.
Industry Challenges
- Surgeon Training Bandwidth:Robotic system adoption requires proctored case volumes that strain orthopedic residency programs and community hospital credentialing committees.
- Legacy System Integration:Electronic health record interoperability gaps complicate preoperative planning data flows between imaging systems, surgical navigation platforms, and implant registries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Orthopedics Market |
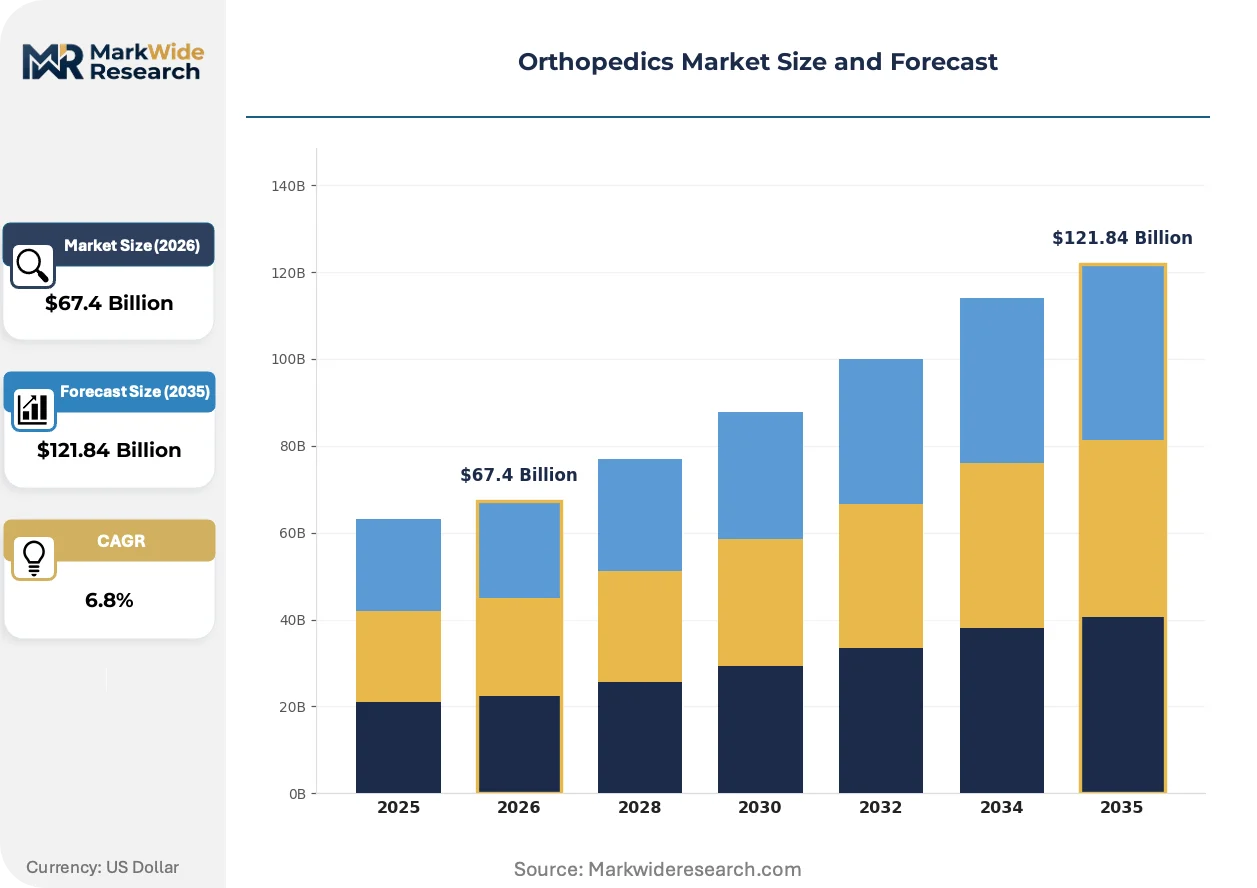
| Market Size in 2026 | $67.4 Billion |
| Market Size in 2035 | $121.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Joint Implants, Bone Plates, Screws, Orthobiologics End User: Hospitals, Ambulatory Surgery Centers, Orthopedic Clinics, Rehabilitation Centers Application: Fracture Treatment, Joint Replacement, Spine Surgery, Sports Medicine Technology: 3D Printing, Robotics, Biomaterials, Imaging Techniques |
| Companies Covered | Stryker Corporation, Zimmer Biomet Holdings, Johnson & Johnson MedTech, Smith+Nephew, Medtronic, Arthrex, Globus Medical, Enovis, B. Braun, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orthopedics Market Strategic Shifts
Orthopedic device development is pivoting from standalone implant engineering toward integrated surgical ecosystems that capture value across the episode of care. This shift demands new competencies in software, sensors, and data analytics.
Smart implant technology is modularizing the traditional hip and knee replacement construct by embedding sensors for postoperative load monitoring and wear detection. ASCs with bundled payment contracts are piloting these devices to reduce revision surgery rates and capture shared savings. The structural consequence is a compression of the aftermarket service model, with manufacturers retaining connectivity revenue streams throughout the implant lifecycle.
The EU MDR's post-market surveillance requirements are mandating systematic implant registry participation and periodic safety update reports for Class III devices. Manufacturers must now maintain clinical evidence generation infrastructure that extends far beyond premarket approval. Joint reconstruction portfolios face the steepest compliance burden, with notified body audits scrutinizing biological evaluation reports and risk management files.
Hospital purchasing consortia are consolidating orthopedic procurement decisions through single-source agreements that bundle implants with instrumentation and logistics services. Independent ASCs respond through group purchasing organizations that aggregate volume across multi-state networks. The geographic concentration of this behavior is most visible in the southeastern United States, where private equity-backed ASC chains are capturing market share from nonprofit health systems.
Orthopedics Market Segmentation
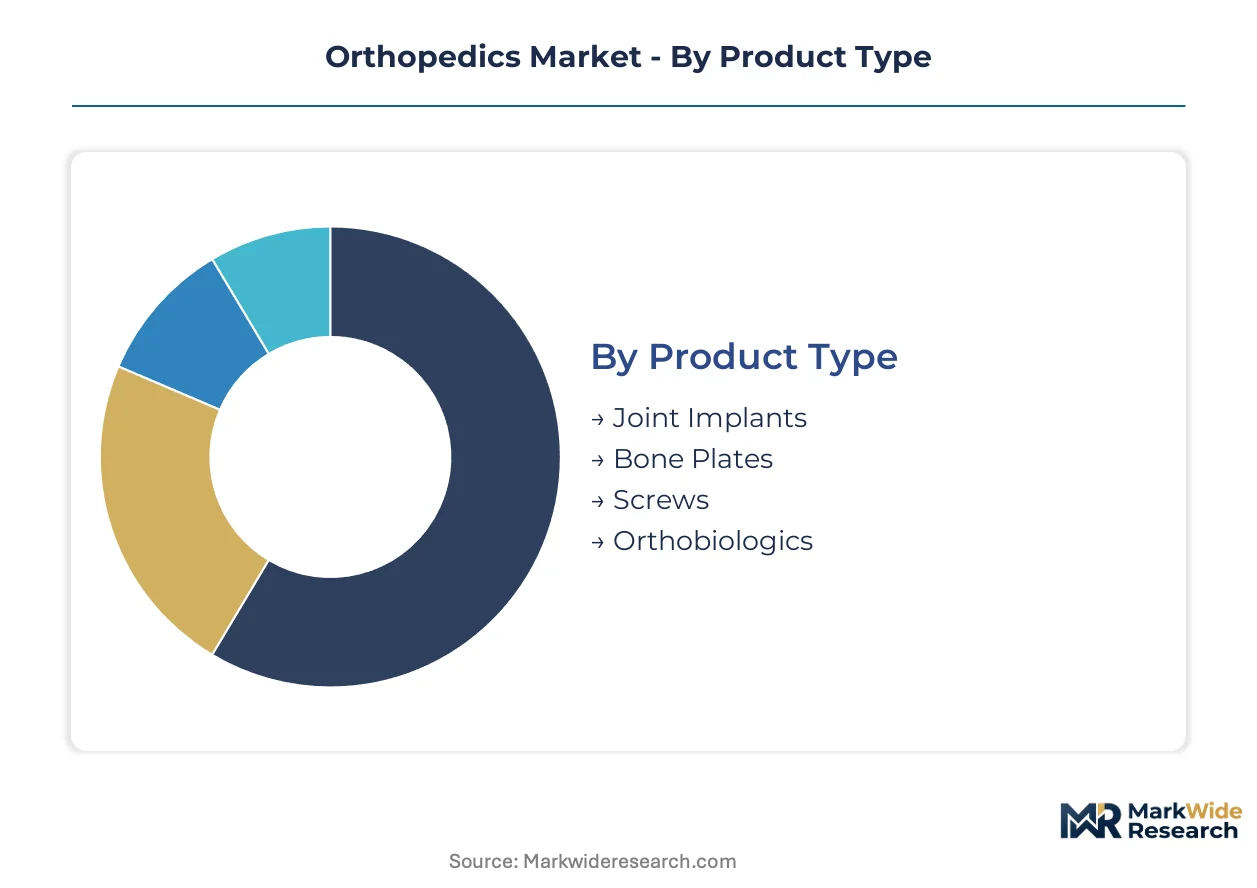
Orthopedic device procurement follows distinct upgrade cycles across hardware, biologics, and enabling technologies. Understanding these replacement rhythms reveals where purchasing committees allocate capital versus operating budgets.
Product Type:
Replacement cycles vary dramatically between permanent implants and consumable biologics, reshaping how manufacturers structure service contracts and inventory commitments.
- Joint Implants:Cobalt-chrome and titanium alloy constructs with ultra-high molecular weight polyethylene bearings dominate hospital purchasing committees in the United States. Medicare reimbursement dynamics for knee and hip arthroplasty sustain high-volume placements, though younger patient cohorts are driving demand for longer-wear bearing surfaces.
- Orthobiologics:Recombinant protein matrices and allograft scaffolds engineered for osteoinduction command premium pricing in sports medicine applications. Demand concentrates in ambulatory settings where surgeons seek to differentiate on healing acceleration rather than hardware alone.
- Bone Plates:Locked plating systems for trauma fixation follow emergency department admission patterns.
- Screws:Cannulated and cortical screw varieties anchor fragment stabilization across trauma and sports procedures.
Volume placements concentrate in Joint Implants; the faster expansion belongs to Orthobiologics.
End User:
Capital expenditure thresholds and reimbursement models create sharp divides between institutional settings.
- Hospitals:Academic medical centers and community hospitals maintain the deepest implant inventories and robotics infrastructure. Bundled payment contracts with commercial payers in the United States are compressing length-of-stay metrics and forcing same-day discharge protocols.
- Ambulatory Surgery Centers:Physician-owned facilities are capturing joint replacement volumes previously reserved for inpatient settings. Group purchasing organizations aggregate procurement power across multi-state networks, particularly in the southeastern United States.
- Orthopedic Clinics:Office-based practices handle preoperative planning and postoperative surveillance.
- Rehabilitation Centers:Post-acute facilities manage recovery protocols and functional outcome measurement.
Procedure volumes remain anchored in Hospitals; ASCs are gaining share fastest.
Application:
Clinical indication shapes everything from regulatory pathway to pricing architecture and surgeon training requirements.
- Joint Replacement:Knee and hip arthroplasty generate the largest revenue pool within orthopedics. Preoperative planning software and patient-matched instrumentation are reducing operative time and implant malposition rates in high-volume United States markets.
- Sports Medicine:Arthroscopic repair and biologic augmentation address younger, active patient populations. Margin accretion flows to allograft and recombinant protein matrices rather than commodity anchors facing pricing compression.
- Fracture Treatment:Trauma fixation responds to emergency department admission volumes and injury severity patterns.
- Spine Surgery:Deformity correction and fusion procedures demand the most complex instrumentation and navigation support.
Revenue concentration sits with Joint Replacement; Sports Medicine shows the steepest expansion trajectory.
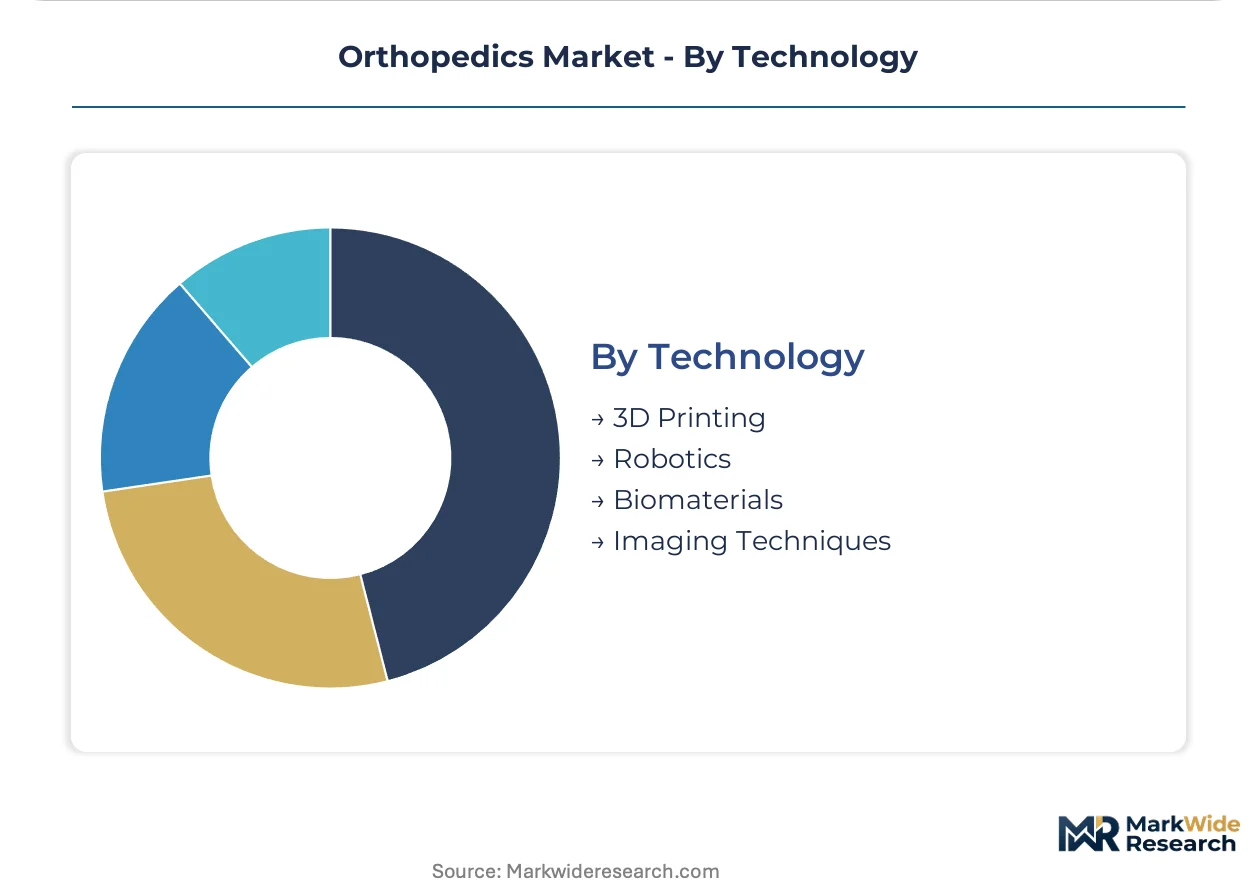
Technology:
Enabling technologies are capturing disproportionate capital expenditure as facilities compete on precision and efficiency metrics.
- Robotics:Precision positioning systems for joint replacement and spine procedures command seven-figure capital commitments. ASCs are prioritizing these platforms to reduce length-of-stay and capture shared savings under bundled payment models.
- 3D Printing:Additive manufacturing enables patient-specific implants and surgical guides from preoperative imaging data. FDA clearance pathways for these devices are extending as software validation requirements tighten.
- Biomaterials:Advanced alloys and cross-linked polyethylene formulations address wear and biocompatibility challenges.
- Imaging Techniques:Intraoperative navigation and augmented reality visualization support complex reconstructive procedures.
Capital allocation prioritizes Robotics; 3D Printing is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Implant-grade titanium sponge production concentrates in Japan and Kazakhstan, anchoring raw material flows that feed precision-forging operations in Germany, Switzerland, and the United States. This geographic pattern shapes finished device manufacturing and regulatory compliance investments across major demand centers.
United States
Medicare-eligible population expansion sustains knee and hip arthroplasty volumes, while commercial payers accelerate outpatient migration to ASCs. FDA 510(k) clearance pathways dominate regulatory strategy for Class II devices, though PMA requirements tighten for novel bearing surfaces. Warsaw, Indiana hosts the densest cluster of joint reconstruction manufacturers, with supply chains radiating to regional distribution hubs.
Germany
Precision machining heritage supports high-value trauma and spine instrumentation demand across academic medical centers. EU MDR notified body audits scrutinize biological evaluation reports, extending validation timelines for implantable portfolios. The Baden-Württemberg corridor around Tuttlingen concentrates surgical instrument manufacturing, with family-owned Mittelstand firms supplying global OEMs.
Japan
Aging demographics exceed US intensity, with super-aged prefectures driving revision surgery demand for failed primary arthroplasties. PMDA consultations require local clinical data for novel materials, favoring incremental innovation over disruptive platform shifts. The Kobe-Osaka industrial zone anchors domestic implant manufacturing, with titanium sponge from domestic smelters feeding captive forging operations.
Switzerland
Private healthcare financing sustains premium pricing for patient-matched instrumentation and ceramic bearing systems. Swissmedic maintains alignment with EU MDR through bilateral agreements, though sovereign certification requirements persist for high-risk devices. The Jura Arc watchmaking belt has pivoted toward orthopedic precision engineering, with micro-machining expertise transferring to surgical guide manufacturing.
China
Volume expansion in tier-two cities drives demand for domestic-manufactured joint implants priced below imported alternatives. NMPA innovation pathway approvals accelerate for devices with substantial overseas clinical history, though local trial requirements persist for novel materials. The Suzhou-Wuxi corridor in Jiangsu Province concentrates foreign-invested manufacturing, with domestic champions scaling production in Tianjin and Beijing.
Orthopedics Market Competitive Environment
Global majors compete with regional champions across technology integration intensity, with consolidated leadership in robotics and fragmented specialization in biologics and trauma hardware. Three archetypes dominate: diversified conglomerates with captive R&D infrastructure, mid-cap specialists with deep vertical integration into materials processing, and emerging platform vendors bundling software with disposable revenue streams. Competitive moves center on strategic partnerships for ASC distribution access and portfolio diversification into adjacent wound care or neuromodulation segments.
Among diversified US-based conglomerates, Stryker Corporation and Zimmer Biomet Holdings exemplify scale-driven archetypes with integrated manufacturing footprints spanning implant forging to surgical navigation. Johnson & Johnson MedTech occupies a distinct position through robotics-integrated platform investments that tighten procedural control in high-complexity spine segments. These three entities represent contrasting strategic postures: materials-forward vertical integration, patient-matched instrumentation specialization, and software-hardware convergence for episode-of-care capture.
| Leading Market Players |
|---|
| Stryker Corporation |
| Zimmer Biomet Holdings |
| Johnson & Johnson MedTech |
| Smith+Nephew |
| Medtronic |
| Arthrex |
| Globus Medical |
| Enovis |
| B. Braun |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up ASC chains in the southeastern United States are consolidating procurement leverage and compressing implant pricing through multi-year volume commitments, while simultaneously demanding guaranteed supply security and instrumentation refresh cycles from vendor partners.
Pricing Analysis
Warranty and service bundling separates premium joint reconstruction vendors from commodity trauma suppliers, with robotics-integrated platforms commanding comprehensive maintenance contracts and disposable instrument revenue streams. Three-tier pricing structure across premium ceramic-bearing systems, standard cobalt-chrome constructs, and economy titanium nails reflects certification intensity and surgeon training investment. Cost compression in standard-bearing segments is intensifying because hospital purchasing consortia are consolidating orthopedic procurement through single-source agreements. ASC group purchasing organizations exhibit the highest price sensitivity, while academic medical centers prioritize clinical outcomes over unit economics.
Supply Chain Analysis
Direct-to-hospital channels handle high-volume joint replacement demand, while distributor-mediated routes serve fragmented trauma and sports medicine practices. Implant-grade titanium sponge production concentrates in Japan and Kazakhstan, with precision forging operations anchored in Germany, Switzerland, and the United States. Finished device manufacturing draws from cobalt-chrome alloy feedstock, ultra-high molecular weight polyethylene resin, and recombinant protein matrices. Single-source vulnerability in titanium sponge processing exposes trauma portfolios to input disruption. Distribution runs through regional logistics hubs serving hospital networks and ASC chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR compliance costs and extended validation timelines are forcing weaker notified body-dependent manufacturers toward exit or acquisition, consolidating competitive position around established quality management systems.
For Market Incumbents: Acquire robotics software assets to tighten procedural control and capture episode-of-care revenue streams. Secure captive titanium forging capacity in Japan or Kazakhstan to insulate trauma portfolios from alloy supply volatility. Defend against emerging platform vendors by embedding AI-enabled surgical planning tools within existing instrumentation franchises.
For New Entrants and Emerging Players: Capture white space in ASC-targeted disposable instrument bundles that complement capital-light robotic platforms. Target southeastern United States group purchasing organization networks where private-equity-backed chains seek vendor flexibility. Pursue FDA digital health pre-certification pathways for AI-enabled preoperative planning software.
For Investors and Strategic Acquirers: Distressed-cycle entries favor EU MDR-compliant mid-cap specialists with notified body relationships in Germany and Switzerland. Long-term viability hinges on clinical evidence generation infrastructure extending beyond premarket approval. Watch notified body audit queue lengths as an inflection indicator for valuation compression among backlog-constrained targets.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Investment | Notified body relationships in Germany and Switzerland accelerate Class III implantable market access. |
| Robotics Platform Integration | Precision positioning systems capture ASC capital expenditure and disposable instrument revenue streams. |
| Patient-Matched Instrumentation Development | Additive manufacturing convergence reduces operative time and implant malposition rates in knee arthroplasty. |
| Biologic Adjunct Portfolio Expansion | Allograft and recombinant protein matrices command margin accretion in sports medicine applications. |
| ASC Distribution Partnership | Group purchasing organization access in the southeastern United States displaces traditional hospital procurement hierarchies. |
Study Parameters
FDA 510(k) clearance databases, EU MDR notified body audit records, and hospital procurement contract filings formed the secondary backbone, supplemented by primary interviews with orthopedic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Bottom-up and top-down triangulation validated segmentation outputs across product type, end user, application, and technology dimensions.
Bottom-up modeling anchored volume projections to Medicare procedure data and commercial payer claims patterns, while top-down cross-checks referenced macroeconomic healthcare expenditure trends across the analysis window. Segmentation dimensions included implant material grade, surgical setting reimbursement model, clinical indication complexity, and enabling technology integration level. CAGRs were derived from procedure volume elasticity to demographic shifts and capital expenditure cycles for robotics infrastructure.
The model holds under stable EU MDR notified body capacity and continued Medicare outpatient migration; deviation in regulatory enforcement intensity or reimbursement rate compression would shift competitive timelines. Forecasts reflect assumptions about surgeon training bandwidth and ASC capital access. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedics
United States Orthopedic Braces and Support Market
Orthopedics
Hips and Knees Reconstructive Market
Orthopedics
Elbow Stiffness Market
Orthopedics
Hallux Rigidus Market
Orthopedics
Osteonecrosis Treatment Market
Orthopedics
Athletic Knee Treatment Market
Orthopedics
Canine Orthopedics Market
Orthopedics
Rotator Cuff Arthropathy Repair Market
Orthopedics
Kyphosis Market
Orthopedics
Tendon Repair Market
Orthopedics
Genu Recurvatum Market
Orthopedics
Osteopenia Treatment Market
Orthopedics
Europe Extremity Reconstruction Market
Orthopedics
Osteoarthritis Treatment Market
Orthopedics
Europe Bone Metastasis Market
Orthopedics
Global Foot Drop Treatment Market