
 Skeletal Deformation Correction Market | 2026-2036
Skeletal Deformation Correction Market Size, Share, and Industry Trends Forecast 2026-2036
Skeletal Deformation Correction Market Analysis
Hospital procurement consortiums is reshaping how orthopedic implant manufacturers secure long-term supply contracts across integrated delivery networks. Zimmer Biomet leverages direct-to-hospital logistics platforms to sustain high-volume plate and screw placements in tier-one trauma centers. Stryker anchors its position through robotics-assisted deformity correction systems that command premium positioning in academic hospitals. Medtronic competes via spine-orthopedic crossover portfolios that extend its reach into complex malalignment procedures.
Skeletal deformation correction encompasses the surgical and non-surgical realignment of bone structures using metallic implants, external fixation frames, and computer-navigated instrumentation to restore anatomical geometry and load-bearing function. Titanium alloy compositions with porosity gradients between 300 and 600 micrometers promote osseointegration while maintaining fatigue resistance under cyclic loading. Plates and screws constitute the mature revenue base, whereas 3D-printed patient-specific implants capture the fastest-growing margin pool due to reduced revision rates. Robotics-assisted orthopedic surgery now sits at the technology frontier, with navigation platforms commanding per-procedure fees that reshape hospital capital allocation.
FDA premarket notification pathways and ISO 13485 quality management standards govern implant biocompatibility and traceability across U.S. distribution channels. The EU Medical Device Regulation imposes stricter clinical evidence requirements for custom-made deformity correction devices entering European markets. Stakeholders must monitor how FDA breakthrough device designations for AI-surgical planning tools alter competitive entry barriers and reimbursement negotiations.
Market Dynamics
Robotics-assisted orthopedic surgery is compressing revision rates while elevating capital expenditure requirements across academic medical centers, fundamentally restructuring how hospitals allocate procurement budgets between navigation platforms and conventional implant inventories.
Growth Catalysts
- FDA Breakthrough Device Designations:Accelerated review pathways for AI-surgical planning tools compress clinical validation timelines from years to months, enabling faster commercialization of patient-specific correction systems.
- Pediatric Orthopedic Clinic Expansion:Specialized pediatric facilities in the United States are driving adoption volumes for deformity correction devices tailored to skeletally immature patients.
- 3D-Printed Titanium Lattice Structures:Porosity gradients between 300 and 600 micrometers promote osseointegration while maintaining fatigue resistance under cyclic loading, improving implant longevity.
Market Restraints
- Raw Material Concentration:Titanium sponge supply concentrates in a limited number of smelting facilities, exposing manufacturers to input cost volatility and supply disruption risks.
- EU MDR Clinical Evidence Burden:The European Medical Device Regulation imposes stricter documentation requirements for custom-made deformity correction devices, extending market entry timelines.
- Non-Surgical Substitutes:Advanced bracing systems and growth modulation techniques for adolescent deformities reduce surgical intervention rates in specific patient cohorts.
Strategic Opportunities
- India Orthopedic Infrastructure Buildout:Government hospital modernization programs and medical tourism initiatives create demand for mid-tier deformity correction implants.
- AI-Surgical Planning Convergence:Integration of machine learning algorithms with preoperative imaging enables predictive modeling of bone remodeling, differentiating premium service offerings.
- Direct-to-Hospital Logistics Platforms:Bypassing traditional distributor networks reduces implant markup layers and captures margin for manufacturers with established supply chain infrastructure.
Industry Challenges
- Robotics Technician Shortage:Academic medical centers face recruitment gaps for specialized surgical navigation engineers, limiting utilization rates of installed capital equipment.
- ISO 13485 Certification Complexity:Quality management system audits for additive manufacturing processes require extended validation protocols for 3D-printed patient-specific implants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Skeletal Deformation Correction Market |
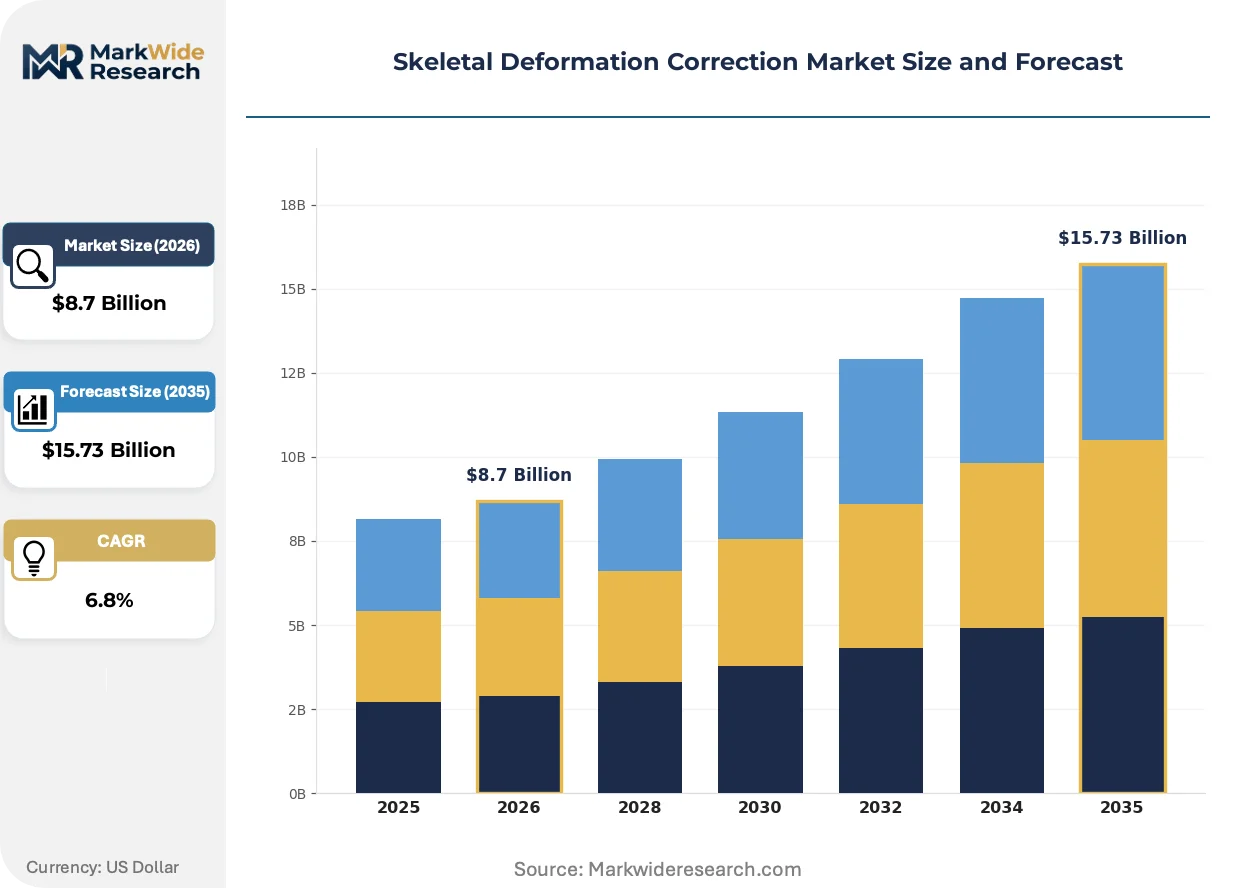
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Braces, Plates, Screws, Rods Technology: Orthopedic Surgery, Robotics, 3D Printing, CAD End User: Orthopedic Clinics, Hospitals, Rehabilitation Centers, Home Care Application: Post-Traumatic Correction, Congenital Deformities, Malalignment Treatment, Others |
| Companies Covered | Zimmer Biomet, Johnson & Johnson, Stryker, Smith & Nephew, Orthofix Medical, Arthrex, Wright Medical Group, Sonoma Orthopedic Products, Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Skeletal Deformation Correction Market Emerging Trajectories
Patient-specific implant fabrication is migrating from prototyping labs to production floors, compressing lead times while forcing recalibration of inventory management models across orthopedic supply chains.
3D-printed titanium lattice implants with architected porosity are rendering obsolete solid monolithic plates for complex deformity reconstructions. Academic medical centers in the United States are adopting these structures at accelerating pace for revision surgeries. The technology is rendering obsolete conventional machining workflows while compressing revision rates through improved osseointegration.
The EU Medical Device Regulation imposes post-market surveillance obligations that extend liability timelines for custom-made deformity correction devices. Manufacturers must maintain clinical follow-up databases spanning implant lifecycles. High-complexity academic hospitals in Germany and France are responding by consolidating procurement with vendors possessing established MDR technical documentation capabilities.
Hospital procurement consortiums are consolidating orthopedic implant purchasing across integrated delivery networks, displacing individual hospital negotiations. Tier-one trauma centers are aggregating volume commitments to extract pricing concessions and dedicated inventory guarantees. This concentration is most visible in the United States, where academic medical center systems command preferential access to robotics-assisted surgery platforms.
Skeletal Deformation Correction Market Segmentation
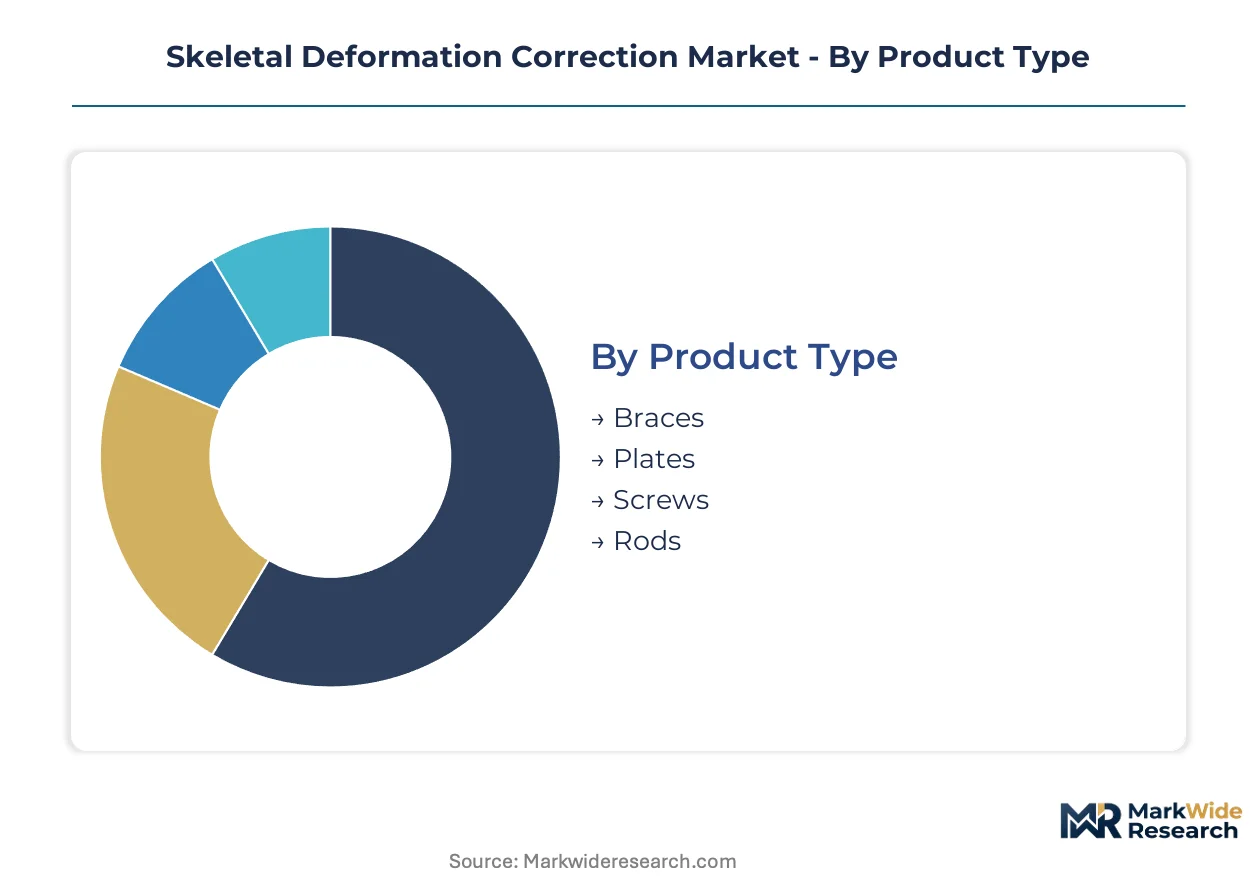
Segmentation in skeletal deformation correction reveals how procurement priorities diverge across clinical settings. Product durability requirements, navigation precision demands, and reimbursement pathways reshape competitive positioning within each category.
Product Type:
After-sales service intensity varies sharply across implant categories, with revision-prone segments demanding dedicated surgical support teams and inventory consignment models.
- Plates:Titanium alloy compositions with anodized surfaces dominate trauma reconstruction. Academic medical centers in the United States concentrate procurement for complex deformity cases requiring anatomical contouring capabilities.
- Screws:Self-tapping cortical and cancellous thread designs anchor fixation constructs. Demand clusters in tier-one trauma centers where high-volume plating procedures drive consumable replenishment cycles.
- Rods:Intramedullary and external fixation configurations address long-bone deformities.
- Braces:External orthotic systems serve non-surgical and post-operative stabilization protocols.
By volume, screws lead due to universal plating procedure requirements. By growth pace, patient-specific plate configurations are expanding most quickly.
Technology:
Capital intensity and per-procedure economics stratify technology adoption, with navigation platforms commanding premium positioning against conventional instrumentation.
- Robotics:Navigation platforms with haptic feedback and real-time bone tracking compress revision rates. Academic medical centers in the United States prioritize these systems for complex multi-planar deformity corrections despite elevated capital expenditure requirements.
- 3D Printing:Additive manufacturing of titanium lattice implants with architected porosity enables patient-specific geometries. German and French academic hospitals drive adoption for revision surgeries where osseointegration performance differentiates outcomes.
- Orthopedic Surgery:Conventional mechanical instrumentation retains volume dominance across mid-tier facilities.
- CAD:Preoperative planning software integrates with imaging workflows for surgical simulation.
By installed base, conventional orthopedic surgery tools dominate. By margin expansion, robotics-assisted platforms command the steepest trajectory.
End User:
Procurement authority and reimbursement sophistication fragment demand across facility types, with integrated delivery networks consolidating purchasing leverage.
- Hospitals:Academic medical centers and tier-one trauma centers concentrate complex deformity reconstruction volumes. United States hospital systems leverage robotics-assisted surgery platforms to differentiate service lines and command premium reimbursement.
- Orthopedic Clinics:Specialized pediatric and adult deformity practices drive adoption of patient-specific implants. These facilities prioritize direct manufacturer relationships to compress lead times for custom devices.
- Rehabilitation Centers:Post-operative monitoring and bracing protocols extend care continuity.
- Home Care:Remote patient monitoring and orthotic adjustment services expand access.
By procedure volume, hospitals anchor demand. By growth velocity, specialized orthopedic clinics are gaining share fastest through targeted deformity expertise.
Application:
Clinical complexity and reimbursement adequacy stratify application segments, with congenital cases demanding specialized pediatric orthopedic infrastructure.
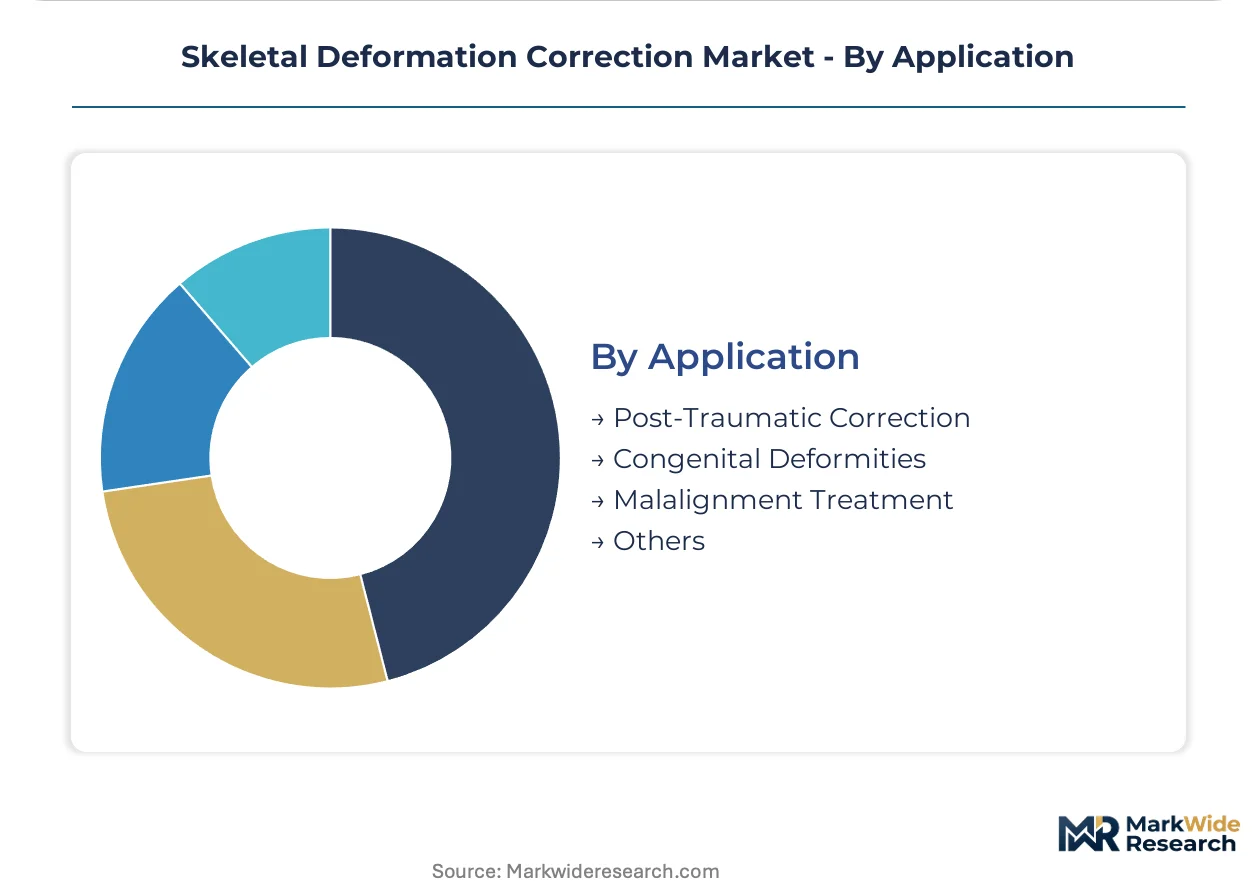
- Post-Traumatic Correction:Fracture malunion and nonunion reconstructions require revision-grade implant systems. United States trauma centers concentrate these procedures, driving demand for 3D-printed patient-specific plates that address bone defects.
- Congenital Deformities:Skeletally immature patients require growth-preserving correction strategies. Pediatric orthopedic clinics in the United States expand specialized capacity, propelling adoption of adjustable implant systems and growth modulation techniques.
- Malalignment Treatment:Degenerative and developmental axis deviations drive osteotomy procedures.
- Others:Tumor reconstruction and infection-related deformities represent niche indications.
By caseload, post-traumatic correction leads. By unmet need intensity, congenital deformities command the most specialized resource allocation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold chain logistics infrastructure underwrites Europe's distribution capacity for temperature-sensitive orthopedic implants. United States hospital systems leverage the Port of Long Beach automated container terminal for Pacific Rim titanium alloy shipments. The Qingdao-Jinan high-speed rail corridor connects Shandong Peninsula titanium sponge refineries to coastal export terminals.
United States
Academic medical centers in Boston and Baltimore drive complex deformity reconstruction volumes. FDA breakthrough device designations compress clinical validation timelines for AI-surgical planning tools. The Texas Medical Center in Houston anchors pediatric orthopedic capacity expansion for congenital deformity cases.
Germany
EU MDR technical documentation requirements favor established manufacturers with clinical follow-up databases. The Medical Valley cluster around Erlangen-Nuremberg concentrates navigation platform engineering talent. Charité Berlin and Heidelberg University Hospital consolidate procurement with MDR-compliant vendors for revision surgeries.
China
NMPA innovation channel approvals accelerate market entry for domestic 3D-printed implant manufacturers. The Yangtze River Delta medical device manufacturing belt around Shanghai hosts titanium lattice fabrication facilities. Beijing Tiantan Hospital and West China Hospital in Chengdu drive adoption of robotics-assisted deformity correction platforms.
Japan
PMDA sakigake designation pathways prioritize regenerative medicine and patient-specific implants for accelerated review. The Kobe biomedical innovation cluster concentrates orthopedic robotics development. Keio University Hospital and Osaka University Hospital lead clinical validation of navigation platforms for multi-planar deformity corrections.
India
CDSCO medical device rules harmonization with IMDRF standards streamlines import licensing for deformity correction implants. Government hospital modernization under Ayushman Bharat creates demand for mid-tier plating systems. The Maharashtra medical device manufacturing zone around Pune attracts contract manufacturers for European orthopedic OEMs.
Skeletal Deformation Correction Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in the supply chain. The market exhibits tiered concentration with multinational conglomerates dominating high-complexity academic hospital contracts while regional fabricators serve mid-tier trauma centers. Three strategic archetypes define competitive positioning: navigation platform vendors capturing premium per-procedure fees, patient-specific implant specialists leveraging additive manufacturing differentiation, and broad-line trauma implant suppliers defending volume share. Dominant competitive moves include direct-to-hospital logistics bypassing distributor markups and robotics-assisted surgery platform installations locking in long-term implant purchasing commitments.
Among diversified orthopedic conglomerates, Zimmer Biomet, Stryker, and Medtronic occupy positions spanning conventional trauma implants through robotics-assisted navigation systems. Zimmer Biomet represents the direct-to-hospital logistics archetype with established supply chain infrastructure. Stryker exemplifies the robotics platform strategy commanding premium positioning in academic medical centers. Medtronic anchors the spine-orthopedic crossover portfolio archetype extending reach into complex malalignment procedures. These three entities collectively illustrate how scale-driven manufacturers balance mature plating-screw revenue bases against capital-intensive navigation platform investments.
| Leading Market Players |
|---|
| Zimmer Biomet |
| Johnson & Johnson |
| Stryker |
| Smith & Nephew |
| Orthofix Medical |
| Arthrex |
| Wright Medical Group |
| Sonoma Orthopedic Products |
| Medtronic |
| Others |
Supply Flow & Price Mechanics
Titanium sponge smelting capacity clusters in China, Russia, and Japan, concentrating input cost leverage among a handful of upstream suppliers and compressing margin pools for downstream implant fabricators dependent on aerospace-grade alloy specifications. Hospital procurement consortiums exploit this concentration by demanding volume-based pricing concessions that redistribute margin toward integrated delivery networks.
Pricing Analysis
Volume-discount tiering structures dominate orthopedic implant contracting, with academic medical centers extracting 15-25% markups below standard distributor rates through multi-year volume commitments. Price differentiation hinges on FDA breakthrough device designation status and ISO 13485 certification grade, with MDR-compliant vendors commanding premiums in European markets. Cost compression in standard plating systems is intensifying because mid-tier manufacturers are replicating titanium alloy compositions without navigation platform bundling. Pediatric orthopedic clinics exhibit highest price sensitivity due to constrained reimbursement pathways, while tier-one trauma centers prioritize outcome guarantees over unit economics.
Supply Chain Analysis
Contract-manufacturing concentration rests with specialized titanium lattice fabricators in Germany's Medical Valley cluster and Shandong Peninsula refineries near Qingdao. Raw material flows draw from Russian VSMPO-AVISMA sponge output, Chinese ilmenite processing, and Japanese Kobe Steel premium billet production. Single-source vulnerability concentrates in aerospace-qualified titanium alloy certification, where dual-qualified smelters number fewer than twelve globally. Distribution runs through hospital procurement consortiums and direct-to-hospital logistics platforms that displace traditional orthopedic distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized surgical navigation engineers and additive manufacturing validation specialists represent the scarcest capabilities in this market, with academic medical centers competing against aerospace and automotive sectors for identical metallurgical talent pools. Firms that secure captive access to these skill sets will dictate next-generation platform development timelines.
For Market Incumbents: Harden defensive positions by acquiring ISO 13485-certified additive manufacturing facilities in Germany or the United States to secure MDR technical documentation capabilities before EU compliance deadlines tighten. Deepen backward integration into titanium sponge offtake agreements with Russian or Japanese smelters to insulate against raw material volatility. Robotics-assisted surgery platform installations should lock in exclusive implant purchasing commitments through embedded navigation software that complicates competitor switching.
For New Entrants and Emerging Players: Mid-tier trauma centers in India's Maharashtra medical device manufacturing zone represent the most penetrable entry point, where government hospital modernization under Ayushman Bharat creates demand for domestically fabricated plating systems lacking premium navigation bundling. Pediatric orthopedic clinics in the United States present secondary white-space opportunity through direct manufacturer relationships that compress lead times for patient-specific implants. A software companion strategy targeting AI-surgical planning tools offers the lowest capital barrier to hospital system partnerships.
For Investors and Strategic Acquirers: Capital is best deployed toward patient-specific implant specialists possessing established FDA breakthrough device designations and validated titanium lattice fabrication workflows. Long-term viability over the next decade hinges on regulatory data infrastructure rather than manufacturing scale alone. The signal to watch is consolidation velocity among hospital procurement consortiums, as accelerated integrated delivery network formation will collapse viable customer counts for standalone implant suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerated review compresses clinical validation timelines for AI-surgical planning tools. |
| CE Marking Pathway under EU MDR | Post-market surveillance obligations extend liability timelines for custom-made devices. |
| Hospital System Partnership | Direct-to-hospital logistics platforms capture margin by bypassing distributor markups. |
| Software Companion Development | Machine learning integration with preoperative imaging differentiates premium service offerings. |
| Reimbursement Strategy | Pediatric orthopedic clinic expansion requires specialized coding for congenital deformity procedures. |
Methodological Framework
A spread of perspectives from orthopedic surgeons, hospital purchasing committee chairs, biomedical engineers specializing in additive manufacturing, and GPO contracts managers converged on the working assumptions driving implant demand forecasts. Secondary validation drew from FDA 510(k) premarket notification filings, EU MDR technical documentation databases, hospital procurement consortium contract disclosures, and CMS Medicare reimbursement schedules. Bottom-up procedure volume estimates triangulated against top-down titanium alloy consumption data from customs records.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation modeled across product type, technology platform, end-user facility tier, and application complexity. CAGRs were derived from procedure volume growth rates applied to average selling price trajectories, incorporating robotics platform adoption curves and 3D-printed implant penetration assumptions. Industry-specific inputs included FDA breakthrough device designation velocity and EU MDR compliance cost burdens for custom-made device manufacturers.
Practitioners should monitor raw material cost volatility in titanium sponge markets and recruitment gaps for surgical navigation engineers for early signals of forecast deviation. Quarterly review of hospital procurement consortium formation rates and MDR technical documentation submission volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedics
Osteoarthritis Treatment Market
Orthopedics
Orthopedic Soft Tissue Repair Market
Orthopedics
Orthopedic Repair Market
Orthopedics
Orthopedics Market
Orthopedics
Kyphosis Market
Orthopedics
United States Orthopedic Braces and Support Market
Orthopedics
Tendon Repair Market
Orthopedics
Athletic Knee Treatment Market
Orthopedics
Osteoporosis Treatment Market
Orthopedics
Genu Recurvatum Market
Orthopedics
ACL Reconstruction Market
Orthopedics
Swollen Knee Treatment Market
Orthopedics
Spinal Stenosis Market
Orthopedics
Bilateral Osteoarthritis Treatment Market
Orthopedics
Knee Hyaluronic Acid Injections Market
Orthopedics
Canine Orthopedics Market