
 Podiatry Services Market | 2026-2036
Podiatry Services Market Size, Share, and Industry Trends Forecast 2026-2036
Podiatry Services Market Intelligence
Buyer concentration among integrated health systems is hardening as hospital networks consolidate outpatient podiatry under single vendor contracts. HCA Healthcare leverages its scale across freestanding surgical centers to capture high-margin bunionectomy and hammertoe procedures. Kaiser Permanente anchors its market position through capitated contracts that embed podiatry within diabetes care pathways. Apollo Hospitals competes on medical tourism flows, drawing Middle Eastern and Southeast Asian patients to its specialized foot surgery units in Chennai and Hyderabad.
Podiatry services encompass the diagnosis, treatment, and prevention of disorders affecting the foot, ankle, and lower extremity, employing biomechanical assessment tools such as pressure-mapping platforms and gait-analysis systems to guide orthotic fabrication and surgical planning. The field serves industrial, athletic, and geriatric populations where mobility impairment carries cascading comorbidity costs. Surgical Treatments within the Service Type dimension command premium reimbursement tiers, while Diagnostic Services expand fastest as point-of-care ultrasound and Doppler systems decentralize vascular assessment from radiology departments. The Geriatrics patient segment occupies the deepest volume pool, though Athletes represents the highest per-episode spend category driven by return-to-play urgency and cash-pay orthotic channels.
Medicare's Therapeutic Shoes for Persons with Diabetes benefit shapes US demand through strict documentation requirements enforced by CMS contractors, while the FDA regulates custom orthotic devices as Class I medical equipment with 510(k) exemptions for prefabricated equivalents. Germany's statutory health insurance system, governed by the Federal Joint Committee (G-BA), mandates podiatric coverage within diabetes disease-management programs. Stakeholders must monitor how CMS value-based payment models and EU Medical Device Regulation reclassification of active orthotic components reshape capital deployment toward in-house fabrication versus outsourced laboratory partnerships.
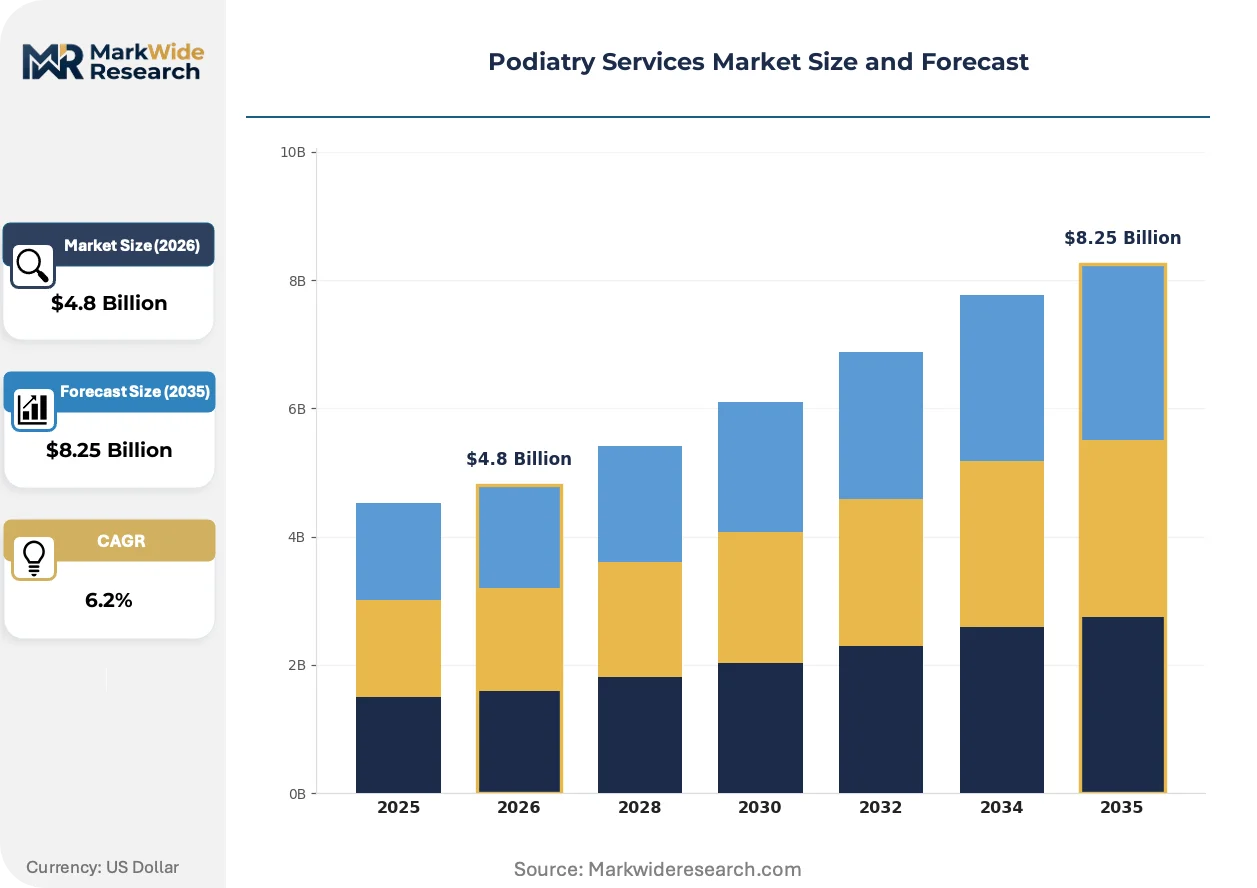
Market Dynamics
Medicare's Therapeutic Shoes benefit documentation mandates and the EU Medical Device Regulation reclassification of active orthotic components are compressing margins while forcing capital redeployment toward in-house fabrication capabilities.
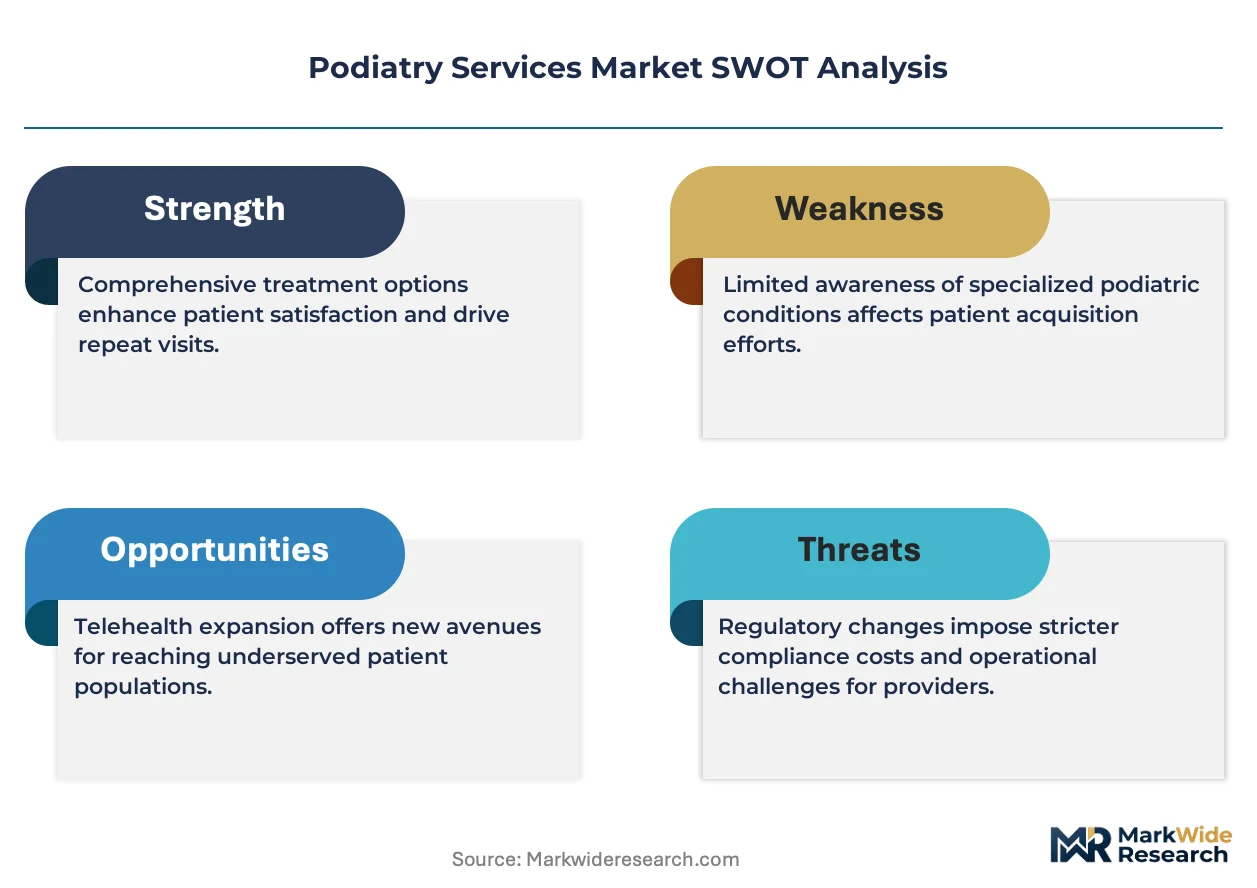
Growth Catalysts
- CMS Diabetic Foot Screening Mandates:Medicare contractors enforce strict documentation requirements that expand preventive podiatry visits across US health systems.
- Germany's G-BA Disease-Management Programs:Statutory health insurance mandates podiatric coverage within diabetes care pathways, building dedicated foot and ankle centers.
- Pressure-Mapping Platform Adoption:Biomechanical assessment tools guide orthotic fabrication and surgical planning in athletic and geriatric populations.
Market Restraints
- Custom Orthotic Input Cost Volatility:Carbon fiber composite and medical-grade silicone prices fluctuate with aerospace and electronics sector demand cycles.
- Radiology Department Supply Concentration:Vascular assessment decentralization depends on point-of-care ultrasound manufacturers concentrated in Massachusetts and Bavaria.
- FDA 510(k) Pathway Friction:Prefabricated orthotic exemptions create reimbursement gaps that disadvantage custom fabrication laboratories.
Strategic Opportunities
- India Medical Tourism Flows:Apollo Hospitals draws Middle Eastern and Southeast Asian patients to specialized foot surgery units in Chennai and Hyderabad.
- Capitated Contract Embedding:Kaiser Permanente embeds podiatry within diabetes care pathways, creating template contracts for integrated health systems.
- Gait-Analysis and 3D-Printing Convergence:Digital orthotic fabrication compresses laboratory turnaround from weeks to days.
Industry Challenges
- Podiatric Surgeon Training Pipeline Gaps:Fellowship positions in foot and ankle surgery fail to match demand from consolidating hospital networks.
- EU MDR Active Component Reclassification:Motorized orthotic devices face elevated clinical evidence requirements that delay market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Podiatry Services Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Orthotic Services, Surgical Treatments, Diagnostic Services, Rehabilitation Patient Type: Pediatrics, Adults, Geriatrics, Athletes Care Setting: Hospitals, Clinics, Home Care, Rehabilitation Centers Treatment Method: Conservative Care, Surgical Intervention, Physical Therapy, Education |
| Companies Covered | The London Podiatry Center, HCA Healthcare, Massachusetts General Hospital, Apollo Hospitals, Ascension Health Alliance, Kaiser Permanente, The Royal Free Hospital, Schoen Clinic, Fortis Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Podiatry Services Market Strategic Shifts & Innovations
Digital fabrication methods and decentralized diagnostic capabilities are compressing traditional laboratory and radiology workflows while opening direct-to-patient channels previously controlled by hospital systems.
Three-dimensional printing of custom orthotic shells is electrifying the fabrication landscape. Podiatry clinics and hospital-based services are adopting in-house production systems to bypass commercial laboratory partnerships. This technology is electrifying margin capture for high-volume bunionectomy and hammertoe practices while shortening patient turnaround from casting to fitting.
The EU Medical Device Regulation reclassification of active orthotic components imposes clinical evidence requirements previously reserved for Class II devices. German and French manufacturers face extended notified body review timelines for motorized ankle-foot orthoses. Prefabricated device suppliers exploit this friction by expanding 510(k)-exempt product lines into European markets.
Cash-pay orthotic channels are fragmenting traditional reimbursement-dependent distribution. Athletes and industrial workers purchase directly from biomechanical assessment platforms that bypass physician referral requirements. This pattern concentrates in Germany's statutory insurance gaps and the United States' high-deductible health plan populations.
Podiatry Services Market Segmentation
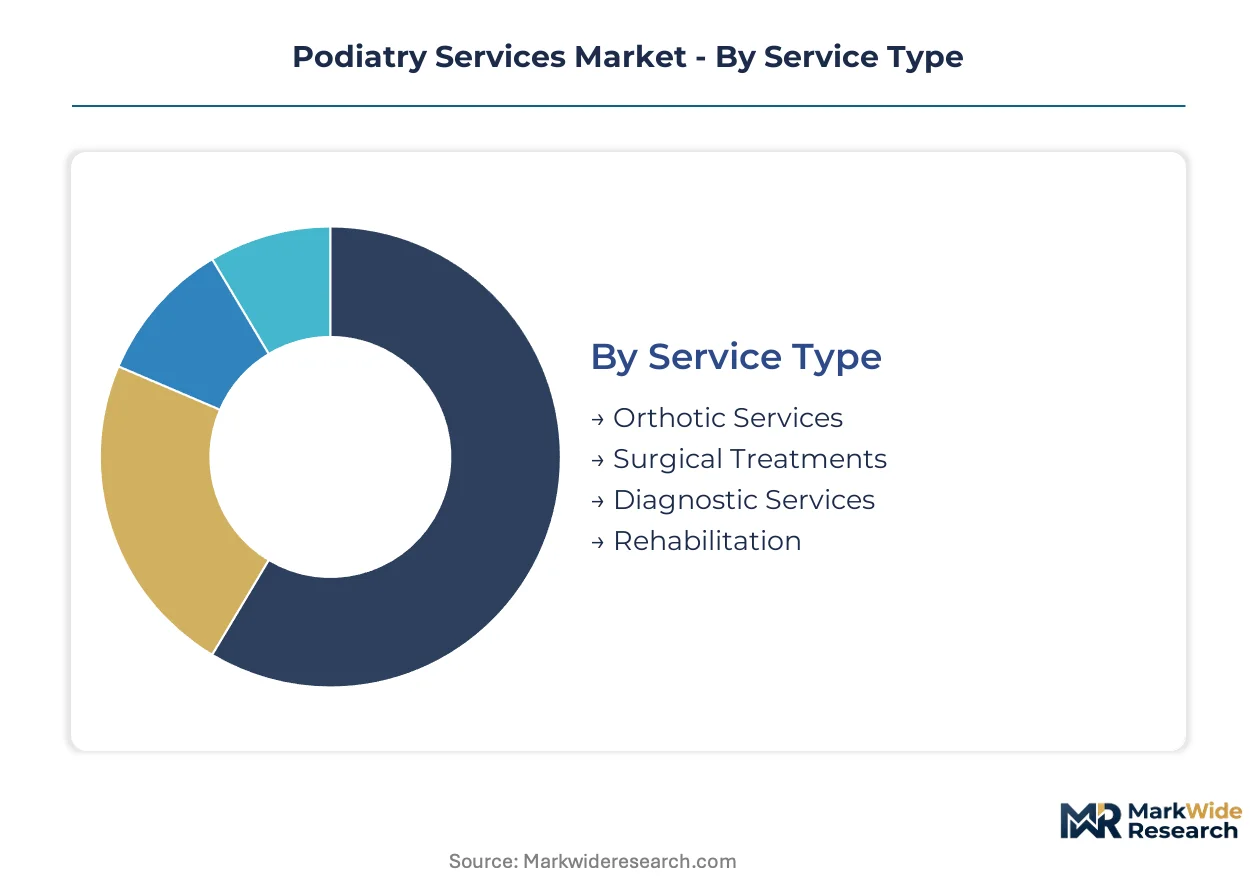
Service configuration in podiatry hinges on reimbursement pathways and regulatory classification, with each segment carrying distinct documentation burdens and capital requirements that shape provider economics.
Service Type:
FDA 510(k) exemptions govern prefabricated orthotics as Class I devices, while surgical treatments fall under facility fee structures and EU MDR scrutiny for motorized components.
- Surgical Treatments:Bunionectomy, hammertoe correction, and ankle arthroscopy command premium reimbursement tiers through ASC facility fees. Demand concentrates in HCA Healthcare's freestanding surgical centers across Florida and Texas, driven by Medicare's site-neutral payment differentials.
- Diagnostic Services:Point-of-care ultrasound and Doppler systems decentralize vascular assessment from radiology departments. Germany's Schoen Clinic networks deploy pressure-mapping platforms to capture diabetic foot screening volumes mandated by G-BA disease-management programs.
- Orthotic Services:Custom fabrication laboratories face input cost volatility from carbon fiber composite pricing tied to aerospace demand cycles.
- Rehabilitation:Post-surgical protocols and gait retraining programs align with bundled payment models in integrated health systems.
Surgical Treatments sits at the top of the volume ranking, with Diagnostic Services climbing the fastest.
Patient Type:
Cost tiers stratify sharply across age and activity profiles, from capitated diabetes pathways to cash-pay athletic channels.
- Geriatrics:Medicare's Therapeutic Shoes for Persons with Diabetes benefit creates strict documentation requirements enforced by CMS contractors. This segment anchors volume through chronic disease management and mobility preservation.
- Athletes:Return-to-play urgency drives the highest per-episode spend through direct-to-patient biomechanical assessment platforms. Germany's statutory insurance gaps and US high-deductible plan populations fuel cash-pay orthotic channels.
- Adults:Occupational injuries and progressive deformities generate steady referral flows from employer health programs.
- Pediatrics:Congenital conditions and gait abnormalities require specialized fellowship-trained providers concentrated in university hospital networks.
Geriatrics captures the deepest volume pool, with Athletes expanding most quickly through bypassed reimbursement structures.
Care Setting:
Margin profiles diverge based on capital intensity and payer mix concentration, from hospital outpatient departments to decentralized home modalities.
- Hospitals:Academic medical centers anchor complex rearfoot reconstruction and limb salvage programs. Kaiser Permanente embeds podiatry within diabetes care pathways through capitated contracts that cross-subsidize facility infrastructure.
- Clinics:Private podiatry practices and hospital-affiliated outpatient units capture high-margin procedural volumes. Apollo Hospitals draws Middle Eastern and Southeast Asian patients to specialized foot surgery units in Chennai and Hyderabad.
- Rehabilitation Centers:Post-acute facilities manage wound care and offloading protocols under bundled episode payments.
- Home Care:Mobile diagnostic services and telehealth consultations extend reach into rural geographies with provider shortages.
Hospitals retain the dominant share, with Clinics gaining ground fastest through medical tourism and direct contracting.
Treatment Method:
Maturity curves separate established conservative protocols from technology-enabled surgical and educational interventions.
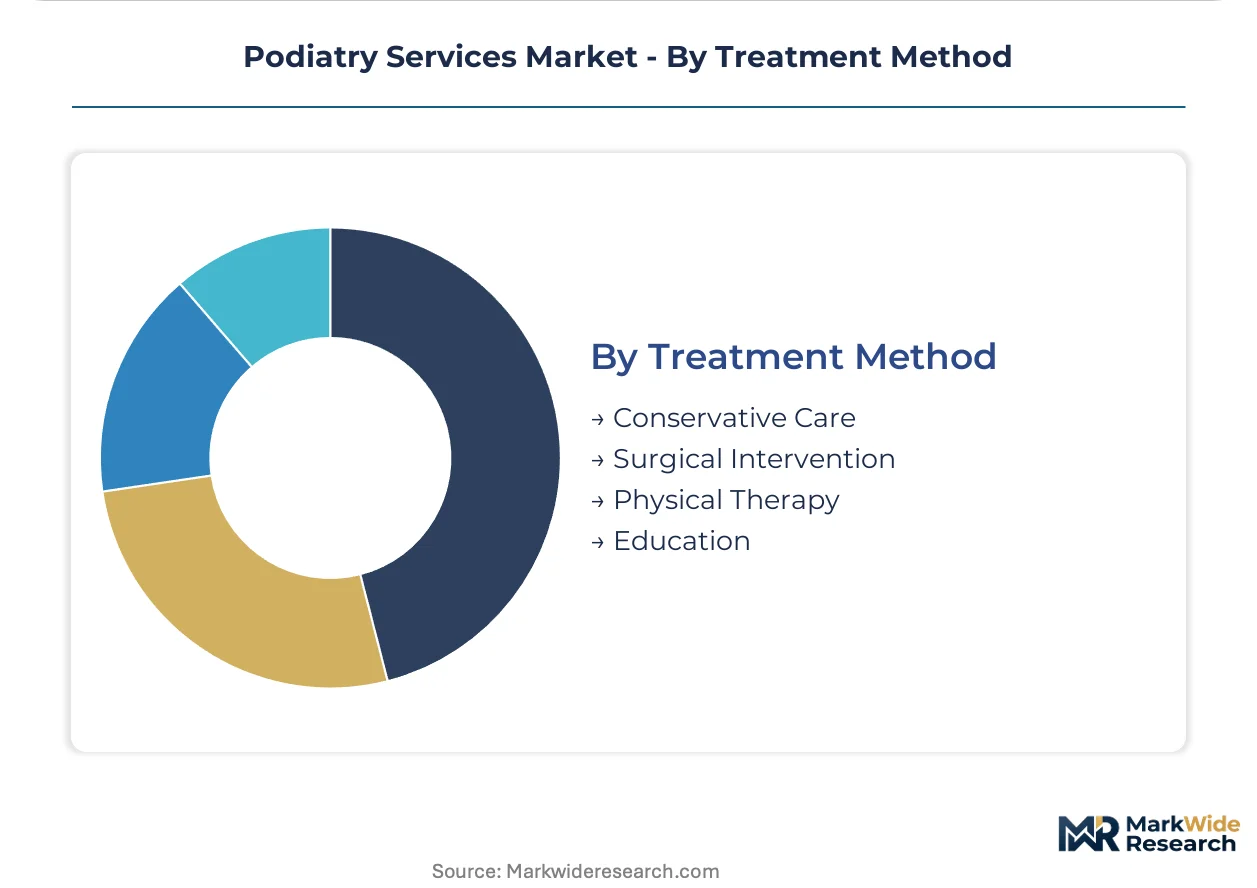
- Conservative Care:Orthotic prescription, footwear modification, and activity modification remain first-line protocols. Gait-analysis and 3D-printing convergence compresses laboratory turnaround from weeks to days in high-volume practices.
- Surgical Intervention:Minimally invasive techniques and percutaneous fixation reduce recovery timelines. Fellowship-trained foot and ankle surgeons concentrate in consolidating hospital networks facing pipeline gaps.
- Physical Therapy:Biomechanical retraining and proprioceptive exercise programs integrate with orthopedic surgery bundles.
- Education:Diabetic foot self-examination training and ulcer prevention protocols satisfy Medicare documentation requirements for therapeutic shoe benefits.
Conservative Care holds the volume lead, with Surgical Intervention showing the steepest expansion trajectory amid training shortages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Podiatric surgeon training programs concentrate in university hospital networks across Germany, the United States, and India, anchoring specialized foot and ankle service delivery in these geographies.
United States
Medicare's Therapeutic Shoes for Persons with Diabetes benefit drives preventive podiatry volumes through strict CMS documentation requirements. HCA Healthcare operates freestanding surgical centers across Florida and Texas that capture site-neutral payment differentials for bunionectomy procedures. Kaiser Permanente embeds podiatry within diabetes care pathways through capitated contracts that cross-subsidize facility infrastructure across California and the Pacific Northwest.
Germany
The Federal Joint Committee mandates podiatric coverage within statutory health insurance disease-management programs. G-BA regulations enforce diabetic foot screening protocols that expand dedicated foot and ankle center construction. Schoen Clinic networks in Bavaria and North Rhine-Westphalia deploy pressure-mapping platforms to capture mandated screening volumes.
India
Medical tourism flows from the Middle East and Southeast Asia concentrate demand for specialized foot surgery units. Apollo Hospitals in Chennai and Hyderabad draw international patients through direct contracting relationships with Gulf state health ministries. The country's national pharmaceutical regulator oversees orthotic device quality standards for export markets.
United Kingdom
NHS England's diabetes transformation program embeds podiatry within integrated care systems. The Royal Free Hospital in London anchors complex rearfoot reconstruction referrals from across Greater London and the Southeast. Cash-pay orthotic channels fragment in high-deductible private insurance gaps.
United Arab Emirates
MOHAP licensing requirements for podiatric specialists concentrate expatriate clinical talent in Dubai and Abu Dhabi. Medical city developments in Dubai Healthcare City attract Indian and European-trained foot surgeons. The regulator's health facility licensing framework shapes capital deployment toward ambulatory surgical centers.
Podiatry Services Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the podiatry services landscape. Hospital networks consolidate outpatient podiatry under single vendor contracts while independent practices retain niche biomechanical assessment capabilities. Three archetypes dominate: integrated health systems with capitated contracts, freestanding surgical center operators, and medical tourism destination hospitals. Competitive moves center on geographic expansion through acquisition and in-house fabrication technology deployment.
Among integrated health system operators, Kaiser Permanente and HCA Healthcare exemplify divergent scale strategies. Apollo Hospitals occupies a position within the medical tourism archetype, drawing international patient flows to specialized units. Schoen Clinic represents the European dedicated-center model, building foot and ankle service lines within statutory insurance frameworks.
| Leading Market Players |
|---|
| The London Podiatry Center |
| HCA Healthcare |
| Massachusetts General Hospital |
| Apollo Hospitals |
| Ascension Health Alliance |
| Kaiser Permanente |
| The Royal Free Hospital |
| Schoen Clinic |
| Fortis Healthcare |
| Others |
Cost & Logistics Intelligence
Three-dimensional printing adoption in podiatric orthotic fabrication simultaneously collapses laboratory turnaround timelines and redistributes margin capture toward high-volume clinical practices equipped with in-house production systems. This technology shift compresses cost structures for custom shell production while eroding the pricing power of centralized commercial laboratories that previously controlled fabrication workflows.
Pricing Analysis
Bundled episode payments for surgical procedures coexist with unbundled fee-for-service billing for diagnostic and orthotic services across US and German markets. Three-tier pricing structure across premium, standard, and economy levels separates cash-pay athletic channels from capitated diabetes pathways and government-mandated screening programs. Cost compression in custom fabrication is intensifying because carbon fiber composite input costs fluctuate with aerospace sector demand cycles. Employer health programs demonstrate highest price sensitivity, while return-to-play athletes accept premium pricing for expedited biomechanical assessment and direct-to-patient orthotic delivery.
Supply Chain Analysis
Direct-to-clinic distribution of pressure-mapping platforms and point-of-care ultrasound systems bypasses traditional radiology equipment procurement channels. Manufacturing concentration for carbon fiber composite materials centers on Germany, Japan, and the United States, while medical-grade silicone production draws from specialized chemical processors in Bavaria and Massachusetts. Single-source vulnerability characterizes the point-of-care Doppler device segment, with manufacturers concentrated in specific regional clusters. Distribution runs through hospital system GPO contracts for capital equipment and direct manufacturer relationships for consumable orthotic components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where Medicare's Therapeutic Shoes benefit documentation mandates and Germany's G-BA disease-management program requirements continuously expand addressable service volumes through compliance-driven demand generation.
For Market Incumbents: Cement market position by deploying in-house 3D-printing fabrication capabilities to capture margin otherwise lost to commercial laboratory partnerships. Pursue backward integration into carbon fiber composite sourcing to buffer input cost volatility from aerospace demand cycles. Kaiser Permanente's capitated contract template offers a replicable model for embedding podiatry within diabetes care pathways across integrated health systems. For New Entrants and Emerging Players: The gap between premium cash-pay athletic channels and economy-tier Medicare screening programs creates white-space opportunity for mid-market positioning. Target India's medical tourism corridor through direct contracting with Gulf state health ministries, replicating Apollo Hospitals' Chennai and Hyderabad model. Emphasize digital biomechanical assessment platforms that bypass traditional physician referral requirements to accelerate patient acquisition. For Investors and Strategic Acquirers: Valuations sit cheapest among independent podiatry practices lacking in-house fabrication technology or hospital system affiliation. Acquisition focus should center on high-volume bunionectomy and hammertoe practices in Florida and Texas where HCA Healthcare has demonstrated ASC facility fee capture. Monitor FDA 510(k) pathway modifications for prefabricated orthotic devices as an inflection indicator for custom laboratory viability.| Strategic Initiative | Industry Significance |
|---|---|
| In-House 3D-Printing Deployment | Captures laboratory margin and compresses patient turnaround from casting to fitting. |
| Capitated Contract Embedding | Replicates Kaiser Permanente's diabetes care pathway integration across health systems. |
| Medical Tourism Destination Development | Apollo Hospitals' Chennai model draws Middle Eastern patients through health ministry contracts. |
| Pressure-Mapping Platform Adoption | Schoen Clinic networks capture G-BA mandated diabetic foot screening volumes in Germany. |
| Fellowship Pipeline Investment | Addresses foot and ankle surgeon shortages constraining hospital network expansion. |
Research Approach
Direct dialogue with podiatric surgeons, hospital purchasing committee members, biomedical equipment specialists, and GPO contract managers grounded the qualitative foundation of this analysis. Secondary validation drew from CMS Medicare reimbursement databases, FDA 510(k) device filings, German Federal Joint Committee (G-BA) regulatory documents, and hospital procurement records. Bottom-up service volume estimates triangulated against top-down health system expenditure data to ensure consistency across geographic markets.
Segmented outputs across service type, patient category, care setting, and treatment method dimensions informed the analytical framework applied throughout the projection horizon. CAGRs were derived from regression analysis against diabetic population growth trajectories, Medicare policy implementation timelines, and technology adoption curves for point-of-care diagnostic systems. EU Medical Device Regulation reclassification timelines and carbon fiber composite pricing volatility indices served as industry-specific forecast inputs.
The model assumes a particular technology adoption path for digital orthotic fabrication; alternative pathways for decentralized 3D-printing deployment would alter the outlook for commercial laboratory market share. Forecasts reflect documented assumptions regarding CMS value-based payment model penetration and G-BA screening mandate enforcement intensity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedics
Europe Extremity Reconstruction Market
Orthopedics
Cruciate Ligament Repair Procedures Market
Orthopedics
Septic Arthritis Market
Orthopedics
ACL Reconstruction Market
Orthopedics
Kyphosis Market
Orthopedics
Hips and Knees Reconstructive Market
Orthopedics
Elbow Stiffness Market
Orthopedics
US Arthritis Market
Orthopedics
Knee Hyaluronic Acid Injections Market
Orthopedics
Rickets Market
Orthopedics
Spinal Stenosis Market
Orthopedics
Rotator Cuff Arthropathy Repair Market
Orthopedics
Skeletal Deformation Correction Market
Orthopedics
Osteonecrosis Treatment Market
Orthopedics
Orthopedics Market
Orthopedics
Athletic Knee Treatment Market