
 Genu Recurvatum Market | 2026-2036
Genu Recurvatum Market Size, Share, and Industry Trends Forecast 2026-2036
Genu Recurvatum Market Analytics
A capital-intensity divergence between implant manufacturers and bracing specialists is reorganizing competitive tiers in the Genu Recurvatum Market. Zimmer Biomet Holdings, Inc. leverages its orthopedic implant foundry network to control surgical device margins across multiple continents. Össur hf anchors its position through carbon-fiber composite expertise in custom knee orthosis fabrication. Smith & Nephew plc competes via distributed rehabilitation partnerships that extend reach into outpatient physiotherapy channels.
Genu recurvatum denotes pathological knee hyperextension exceeding five degrees beyond neutral anatomical alignment, typically quantified via radiographic tibiofemoral angle measurement or dynamic gait analysis. Braces dominate current volume as first-line conservative intervention, while surgical devices command premium pricing for complex multi-ligament reconstruction cases. The pediatrics segment shows fastest uptake due to early screening protocols in school sports programs, whereas seniors represent the mature rehabilitation cohort with recurring home-care dependency.
FDA 510(k) pathways govern orthotic device clearance in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for surgical implants entering European markets. ISO 13485 quality management standards shape supplier qualification across manufacturing tiers. Stakeholders must monitor reimbursement coding shifts for preventive versus corrective bracing as payors recalibrate coverage thresholds.
Market Dynamics
The Genu Recurvatum Market pivots on 3D-printed orthotics compressing traditional manufacturing cycles, with FDA clearance pathways reducing device-to-market intervals from years to months. This technological inflection is redistributing competitive advantage toward digital fabrication specialists and away from conventional brace foundries.
Growth Catalysts
- Pediatric Screening Mandates:School sports programs in the United States and Canada now require pre-participatory knee alignment assessments, expanding addressable volume for preventive bracing among adolescent athletes.
- EU Medical Device Regulation (MDR):Stricter clinical evidence requirements for surgical implants are diverting R&D investment toward conservative orthotic solutions, accelerating brace innovation cycles.
- Carbon-Fiber Composite Maturation:Advanced layup techniques originally developed for aerospace applications are migrating into custom knee orthosis fabrication, improving strength-to-weight ratios for competitive skiing populations.
Market Restraints
- Titanium Alloy Price Volatility:Surgical implant manufacturers face margin compression from spot-market fluctuations in aerospace-grade titanium feedstock sourced primarily from Russian and Chinese smelters.
- ISO 13485 Certification Bottlenecks:Quality management system audits for new entrants stretch 18-24 months, freezing smaller fabricators out of hospital procurement networks.
- Activity-Tracking Wearables:Consumer-grade knee motion sensors from Apple and Garmin are capturing patient attention for self-monitoring, threatening professional-grade gait analysis service revenue.
Strategic Opportunities
- German Statutory Coverage Expansion:Preventive bracing for adolescent competitive skiers now qualifies for full reimbursement under Gesetzliche Krankenversicherung, creating a template for adjacent European markets.
- Telehealth-Integrated Fitting:Remote 3D scanning protocols combined with cloud-based biomechanical modeling are opening rural and exurban patient cohorts previously unreachable through orthotist office networks.
- Bioresorbable Scaffold Convergence:Intersection of orthopedic bracing with tissue engineering is enabling temporary hyperextension correction devices that dissolve post-ligament maturation in pediatric patients.
Industry Challenges
- Digital Orthotist Training Deficits:Clinical workforce lacks proficiency in CAD-based brace design and 3D printing workflow management, slowing technology adoption despite hardware availability.
- Multi-Ligament Reconstruction Integration Complexity:Surgical device portfolios must interface with proprietary fixation systems from competing implant manufacturers, complicating product development roadmaps.
- Post-Market Surveillance Data Gaps:Long-term biomechanical outcomes for 3D-printed custom orthotics remain underdocumented, exposing manufacturers to retrospective liability exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Genu Recurvatum Market |
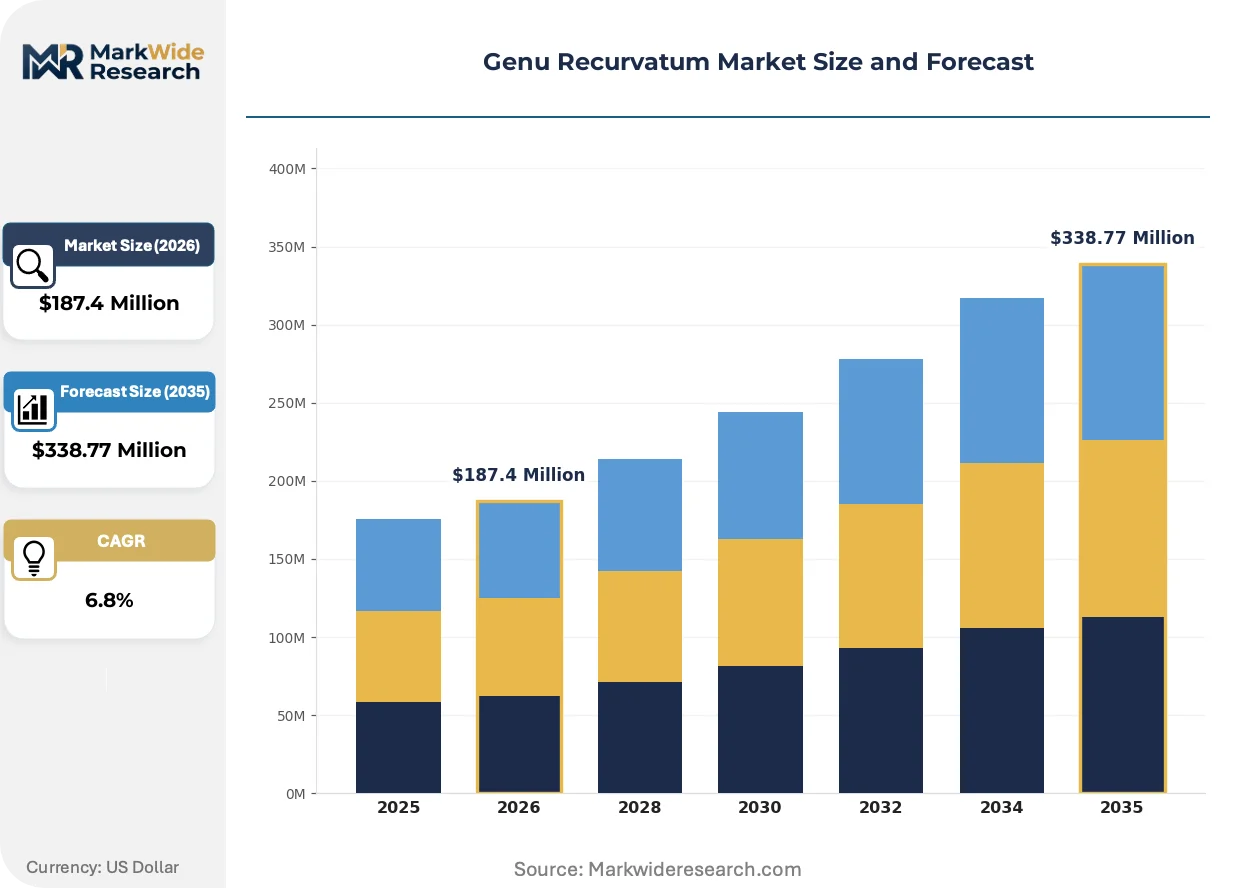
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Braces, Surgical Devices, Physical Therapy Equipment, Assessments Treatment Method: Orthopedic Surgery, Physiotherapy, Medication, Rehabilitation Age Group: Pediatrics, Adolescents, Adults, Seniors End User: Hospitals, Clinics, Rehabilitation Centers, Home Care |
| Companies Covered | Zimmer Biomet Holdings, Inc., Medtronic plc, Johnson & Johnson MedTech, Globus Medical Inc., Össur hf, Stryker Corporation, Smith & Nephew plc, Arthrex Inc., DePuy Synthes Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Genu Recurvatum Market Evolving Landscape
Digital fabrication and biomaterial advances are collapsing traditional boundaries between conservative and surgical intervention pathways. These shifts are compressing product lifecycles while elevating patient-specific customization from premium niche to standard expectation.
Topology-optimized lattice structures generated through generative design algorithms are fragmenting conventional brace architecture. Adolescent competitive skiers and post-surgical rehabilitation patients in Germany and Austria are adopting these ultralight configurations within single seasons. The technology is fragmenting manufacturing economics by eliminating mold costs and enabling batch-size-one production at mass-market price points.
The EU Medical Device Regulation's clinical evidence requirements for Class III surgical implants are redirecting investment flows toward conservative device categories. Manufacturers now prioritize brace portfolios that qualify under simpler conformity assessment procedures. Knee orthosis specialists with established MDR technical documentation are capturing shelf space from implant-focused competitors struggling with extended approval timelines.
Parents of pediatric athletes are increasingly demanding preventive bracing consultations before symptom onset, compressing traditional reactive care models. Orthopedic practices in North American suburban markets are unbundling screening services from device sales, creating subscription-based monitoring programs. This behavioral shift is most pronounced in Colorado and Utah, where ski racing culture normalizes proactive joint protection.
Genu Recurvatum Market Segmentation
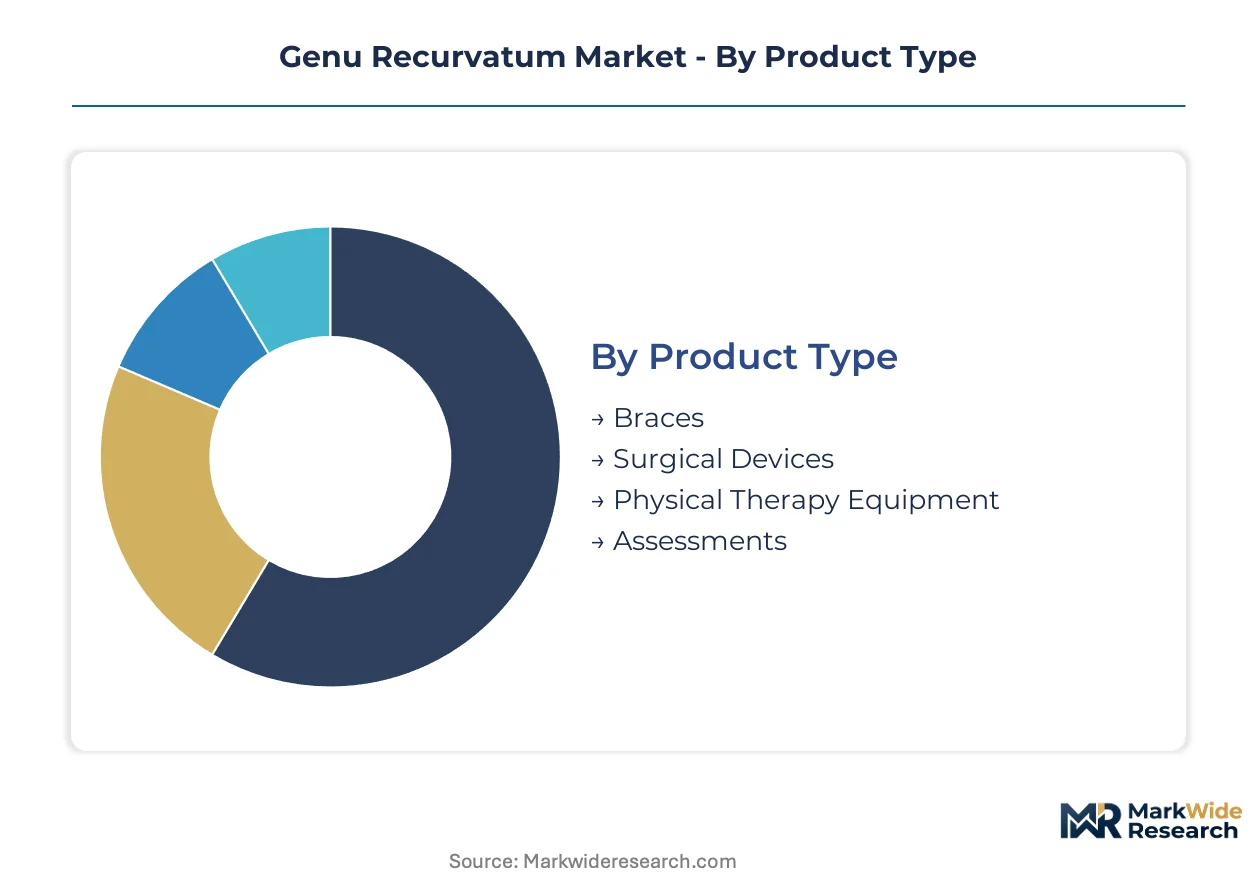
Segmentation in the Genu Recurvatum Market reveals divergent procurement patterns across conservative versus surgical intervention pathways. Product type and age group classifications expose where reimbursement codes concentrate volume, while end-user distribution tracks the shift from institutional toward home-based care models.
Product Type:
Brace fabrication clusters in domestic manufacturing zones serving regional orthotist networks, while surgical device supply chains span multiple continents through implant foundry partnerships.
- Braces:Carbon-fiber composite and 3D-printed polymer configurations dominate preventive applications. German statutory coverage for adolescent skiers anchors European demand, while North American school sports screening programs drive pediatric volume through custom fabrication channels.
- Surgical Devices:Multi-ligament reconstruction systems and osteotomy fixation hardware command premium pricing in complex deformity cases. FDA 510(k) clearance pathways govern US market entry, with EU MDR clinical evidence requirements extending European approval timelines.
- Physical Therapy Equipment:Gait analysis platforms and resistance training systems support post-brace rehabilitation protocols.
- Assessments:Radiographic measurement tools and dynamic motion capture services quantify tibiofemoral angle deviation for treatment planning.
Braces command the established base. The steepest expansion runs through surgical devices as complex multi-ligament reconstruction case volumes climb.
Treatment Method:
Cost tier differentiation separates high-acuity surgical interventions from recurring outpatient physiotherapy sessions, with medication playing an ancillary role in pain management protocols.
- Orthopedic Surgery:Tibial tubercle osteotomy and posterior cruciate ligament reconstruction address severe hyperextension deformities. German and Austrian ski medicine centers concentrate specialized surgical volume for competitive athlete populations.
- Physiotherapy:Quadriceps strengthening and proprioceptive training form the conservative backbone. North American suburban practices in Colorado and Utah unbundle screening from device sales through subscription monitoring programs.
- Medication:Non-steroidal anti-inflammatory drugs and topical analgesics manage symptomatic discomfort during bracing periods.
- Rehabilitation:Structured post-surgical protocols integrate brace weaning with progressive load-bearing progression.
Physiotherapy captures the highest patient touchpoint frequency. Orthopedic surgery delivers the steepest revenue per procedure.
Age Group:
Volume concentration tilts toward pediatric and adolescent cohorts where early screening enables preventive intervention, while seniors represent recurring maintenance demand.
- Pediatrics:Pre-pubertal patients with flexible hyperextension respond to guided growth modulation and nighttime bracing. US and Canadian school sports mandates expand addressable screening pools.
- Adolescents:Competitive skiers and soccer players drive custom carbon-fiber brace adoption. German Gesetzliche Krankenversicherung reimbursement normalizes preventive fitting before symptom onset.
- Adults:Post-traumatic hyperextension from workplace or recreational injury sustains mid-market brace demand.
- Seniors:Degenerative joint changes complicate conservative management, pushing toward surgical consultation or long-term home bracing dependency.
Adolescents command the established base. Pediatrics shows the steepest expansion trajectory as early screening protocols proliferate.
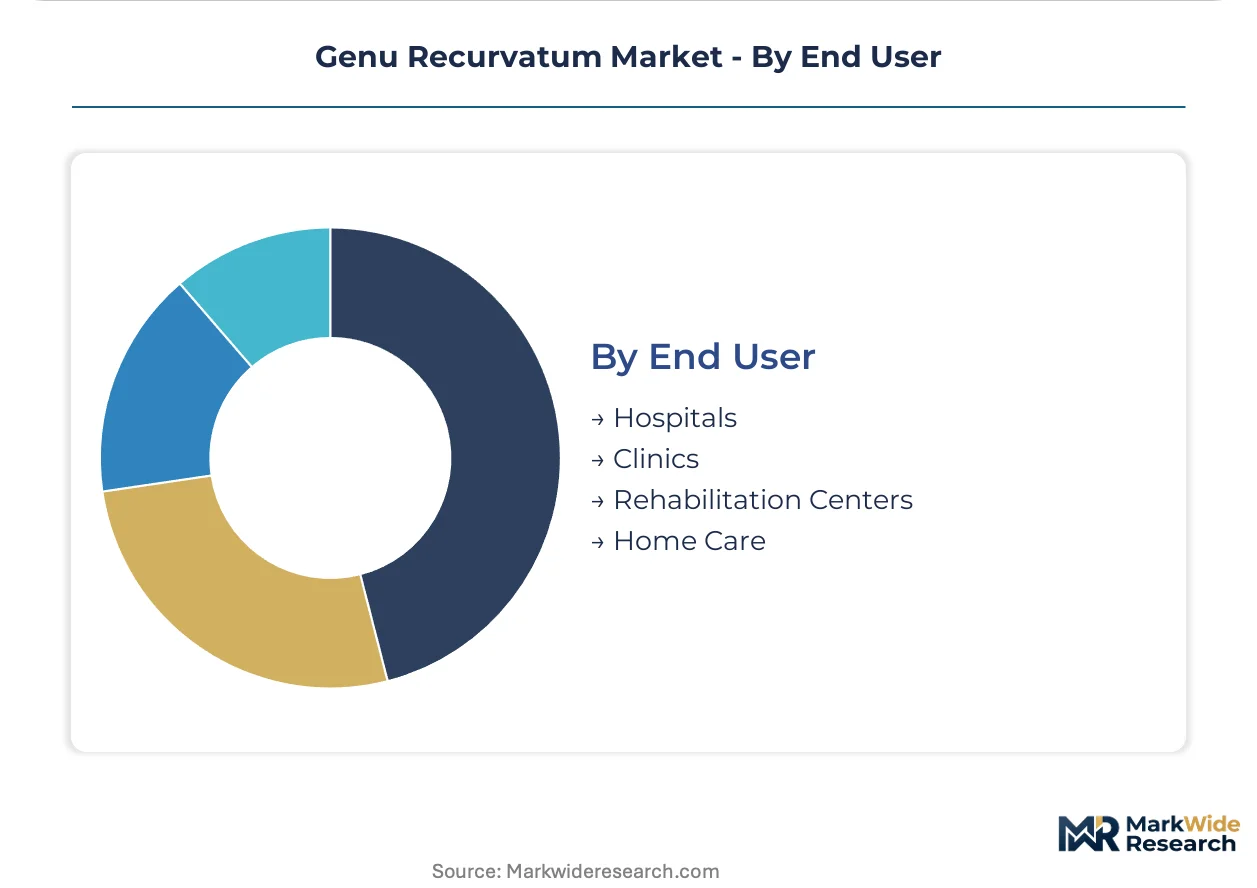
End User:
Customer type stratification tracks the migration from acute hospital episodes toward distributed outpatient and home-based care delivery models.
- Hospitals:Academic medical centers handle complex multi-ligament reconstruction and revision surgeries. ISO 13485 certification requirements filter supplier access to procurement networks.
- Clinics:Orthopedic and sports medicine practices unbundle assessment from device dispensing. Telehealth-integrated 3D scanning extends rural reach beyond traditional orthotist office footprints.
- Rehabilitation Centers:Outpatient physiotherapy facilities manage post-surgical progression and brace weaning protocols.
- Home Care:Direct-to-patient delivery of prefabricated and custom-fitted braces accelerates as remote fitting technology matures.
Hospitals command the established base. Home care channels show the steepest expansion as remote biomechanical modeling collapses geographic barriers to custom fitting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import flows of carbon-fiber composite materials and 3D-printed polymer feedstocks concentrate in Germany and the United States, while export-oriented brace fabrication clusters in Austria and Switzerland serve alpine skiing populations. Trade imbalances in aerospace-grade titanium shape surgical device cost structures across manufacturing hubs.
United States
Pediatric screening mandates in Colorado and Utah school districts drive preventive bracing consultations among competitive skiers and soccer players. FDA 510(k) clearance pathways compress orthotic device approval timelines from years to months. The Denver-Boulder corridor anchors custom fabrication networks serving Rocky Mountain sports medicine centers.
Germany
Gesetzliche Krankenversicherung reimbursement for adolescent preventive bracing normalizes early intervention before symptom onset. EU Medical Device Regulation clinical evidence requirements for Class III surgical implants redirect investment toward conservative orthotic portfolios. Bavarian ski medicine centers in Garmisch-Partenkirchen concentrate specialized surgical volume for competitive athlete populations.
Austria
Carbon-fiber composite expertise from aerospace suppliers migrates into custom knee orthosis fabrication for World Cup skiing circuits. National healthcare coverage for competitive youth athletes eliminates cost barriers to preventive fitting. Innsbruck's Tyrolean medical technology cluster integrates alpine sports science with orthopedic device development.
Switzerland
Swissmedic quality standards shape supplier qualification for precision brace components entering European hospital procurement networks. Private health insurance models incentivize proactive joint protection among amateur and professional skiers. Zurich and Basel host orthopedic research consortia bridging conservative and surgical intervention pathways.
Canada
Provincial healthcare variations create patchwork coverage for pediatric preventive bracing across British Columbia and Alberta ski regions. Health Canada regulatory alignment with FDA pathways accelerates cross-border product launches for 3D-printed custom orthotics. Calgary and Vancouver anchor distribution networks serving mountain resort medical clinics.
Genu Recurvatum Market Competitive Landscape
Concentration sits with diversified orthopedic implant manufacturers controlling surgical device margins through foundry networks and specialized bracing fabricators leveraging carbon-fiber composite expertise. The market structure splits between capital-intensive implant portfolios requiring extended regulatory timelines and nimble digital fabrication specialists compressing product development cycles. Strategic archetypes include multi-continental implant conglomerates, regional custom orthosis specialists, and emerging 3D-printing technology integrators. Dominant competitive moves encompass M&A activity targeting digital fabrication capabilities and strategic partnerships with sports medicine clinic networks.
Within the diversified implant manufacturer tier, Zimmer Biomet Holdings, Inc. and Stryker Corporation represent archetypes leveraging orthopedic foundry infrastructure across multiple continents. Össur hf exemplifies the specialized bracing fabricator model, anchoring position through composite materials expertise. These three entities occupy distinct competitive vectors—implant scale, surgical breadth, and conservative customization—without direct portfolio overlap in hyperextension-specific device categories.
| Leading Market Players |
|---|
| Zimmer Biomet Holdings, Inc. |
| Medtronic plc |
| Johnson & Johnson MedTech |
| Globus Medical Inc. |
| Össur hf |
| Stryker Corporation |
| Smith & Nephew plc |
| Arthrex Inc. |
| DePuy Synthes Inc. |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts for aerospace-grade titanium feedstock lock in surgical implant manufacturers' margin visibility while exposing brace fabricators to spot-market volatility in carbon-fiber composite precursors. German statutory reimbursement codes stabilize demand forecasting for adolescent preventive bracing, compressing price uncertainty for custom orthosis specialists serving Gesetzliche Krankenversicherung-covered populations.
Pricing Analysis
Hospital procurement committees anchor brace pricing through volume-tiered contracting frameworks that stratify across premium carbon-fiber custom configurations, standard 3D-printed polymer models, and economy prefabricated alternatives. FDA 510(k) clearance tier and ISO 13485 certification grade drive price differentiation, with MDR-compliant surgical devices commanding substantial premiums over conservative orthotics. Cost compression in titanium alloy feedstock is intensifying because Russian and Chinese smelter supply disruptions, though pediatric screening program expansion in North American school districts shows lowest price sensitivity due to parental out-of-pocket tolerance for preventive fitting.
Supply Chain Analysis
Port congestion on transpacific trade lanes elevates inbound logistics costs for 3D-printed polymer resin shipments sourced from East Asian chemical manufacturers. Brace fabrication concentrates in Germany, Austria, and the United States, drawing carbon-fiber composite from aerospace suppliers in Japan and the United States while surgical implant foundries rest on titanium feedstock from Russian and Chinese smelters. Single-source vulnerability in aerospace-grade titanium creates structural risk for multi-ligament reconstruction device manufacturers. Distribution runs through hospital procurement networks, orthotist office channels, and emerging direct-to-patient telehealth-integrated fitting platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Remote biomechanical monitoring subscriptions and cloud-based gait analysis platforms are expanding faster than hardware sales, converting transactional brace purchases into recurring revenue relationships. This service-attach dynamic rewards stakeholders who integrate software companion development with physical device portfolios.
For Market Incumbents: Fortify carbon-fiber composite supply relationships through backward integration into aerospace material partnerships, insulating against feedstock volatility that threatens margin stability. Accelerate MDR technical documentation investment to capture shelf space from implant-focused competitors struggling with extended EU approval timelines. Prioritize digital orthotist training program deployment to address CAD proficiency gaps slowing 3D-printing adoption despite hardware availability.
For New Entrants and Emerging Players: Telehealth-integrated remote fitting services represent a service-layer gap where established fabricators under-serve rural and exurban patient cohorts. Target North American mountain resort medical clinics in Colorado and Utah through subscription-based screening programs unbundled from device sales. Pursue strategic partnerships with school sports medicine programs to embed preventive bracing consultations before symptom onset.
For Investors and Strategic Acquirers: Capital is best deployed toward digital fabrication specialists with established FDA 510(k) clearance pathways and MDR technical documentation, positioned to compress product development cycles relative to conventional brace foundries. Long-term viability across the projection horizon hinges on software-hardware integration capabilities and reimbursement strategy sophistication. Watch German statutory coverage expansion into adjacent European markets as the inflection indicator for conservative orthotic demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Software Companion Development | Remote gait analysis platforms from Stryker enable subscription-based patient monitoring beyond device sale. |
| MDR Technical Documentation Investment | Comprehensive EU clinical evidence packages from Össur accelerate brace portfolio market access relative to surgical implants. |
| Hospital System Partnership | Academic medical center alliances with Zimmer Biomet anchor complex multi-ligament reconstruction case volume. |
| Reimbursement Strategy | German GKV preventive bracing coverage expansion creates template for statutory insurance adoption across alpine European markets. |
| CE Marking Pathway | Streamlined conformity assessment for Class I orthotic devices from Smith & Nephew redirects R&D from Class III surgical timelines. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with orthopedic surgeons, certified prosthetist-orthotists, hospital GPO contracts managers, and sports medicine clinic directors. Secondary validation drew from FDA 510(k) clearance databases, EU MDR technical documentation filings, German Gesetzliche Krankenversicherung reimbursement code updates, and alpine skiing federation medical guidelines. Bottom-up patient volume modeling and top-down manufacturer revenue triangulation anchored market size estimation.
Across the analysis window, the quantitative framework modeled segmentation dimensions spanning product type, age group, treatment method, and end-user channel with regional regulatory cluster overlays. CAGRs were derived through logarithmic trend fitting applied to procedure volume and device pricing trajectories. Forecast inputs incorporated pediatric screening mandate adoption curves, carbon-fiber composite cost forecasting, and telehealth-integrated fitting penetration assumptions.
Underlying assumptions cover stable FDA 510(k) pathway efficiency and continued German statutory reimbursement generosity, with deviation risk concentrated in titanium alloy supply disruptions and EU MDR implementation timeline extensions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedics
Spinal Stenosis Market
Orthopedics
Costochondritis Market
Orthopedics
Hips and Knees Reconstructive Market
Orthopedics
Europe Extremity Reconstruction Market
Orthopedics
Bilateral Osteoarthritis Treatment Market
Orthopedics
Rickets Market
Orthopedics
Rotator Cuff Arthropathy Repair Market
Orthopedics
Tendon Repair Market
Orthopedics
Canine Orthopedics Market
Orthopedics
US Arthritis Market
Orthopedics
Global Osteoarthritis Therapeutics Market
Orthopedics
Hallux Rigidus Market
Orthopedics
Orthopedic Pillow Market
Orthopedics
Cruciate Ligament Repair Procedures Market
Orthopedics
Septic Arthritis Market
Orthopedics
Podiatry Services Market