
 Global Foot Drop Treatment Market | 2026-2036
Global Foot Drop Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Foot Drop Treatment Market Foresight
Rehabilitation centers is consolidating their purchasing power around functional electrical stimulation systems as post-stroke patient referrals expand across integrated care networks. Ottobock leverages its European manufacturing footprint to sustain orthotic supply contracts with major hospital chains. Bioness Inc. specializes in implantable neurostimulation platforms that anchor its position in the high-acuity segment. Stryker Corporation competes through its surgical and neurotechnology portfolio, extending reach into peripheral nerve repair procedures that precede orthotic intervention.
Foot drop treatment encompasses mechanical bracing, electrical neuromuscular activation, and surgical intervention to restore dorsiflexion and improve gait kinematics in patients with upper motor neuron lesions or peripheral nerve injury. Ankle foot orthosis devices remain the dominant product category due to their non-invasive profile and broad clinical eligibility, though functional electrical stimulation is displacing passive bracing in ambulatory stroke rehabilitation programs where active muscle retraining is prioritized. Within therapy areas, stroke rehabilitation generates the deepest volume pools while multiple sclerosis presents the most complex reimbursement navigation due to progressive disease monitoring requirements. Margin concentration sits with neuroprosthetics and custom-fabricated orthotic systems where clinical fitting expertise creates service-based pricing power.
FDA 510(k) premarket notification requirements govern electrical stimulation devices in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence standards for neuroprosthetic classifications across European markets. Japan's PMDA reviews functional electrical stimulation systems under specific controlled medical device categories, creating staggered approval timelines that shape manufacturer launch sequencing. Stakeholders must monitor evolving reimbursement codes for home-based FES therapy as payers reassess coverage boundaries between clinic-administered and patient-operated devices.
Market Dynamics
Functional electrical stimulation systems are compressing the traditional mechanical orthotics value chain as rehabilitation centers consolidate procurement around active neuromuscular retraining platforms. Stroke rehabilitation protocols now prioritize dorsiflexion restoration through programmable electrical pulse delivery over passive ankle-foot orthosis bracing.
Growth Catalysts
- Stroke rehabilitation protocols:Integrated care networks in Germany, Japan, and the United States are standardizing functional electrical stimulation as first-line ambulatory therapy for hemiplegic gait disorders.
- FDA 510(k) pathway streamlining:The United States regulator's abbreviated premarket notification process for neuroprosthetic devices accelerates commercial entry for electrical stimulation manufacturers targeting home-based therapy segments.
- EU Medical Device Regulation harmonization:Stricter clinical evidence standards under MDR are consolidating manufacturer compliance capabilities and filtering marginal orthotic producers from European distribution channels.
Market Restraints
- Custom fabrication cost structures:Carbon fiber and thermoplastic ankle-foot orthosis manufacturing requires specialized orthotist labor that scales poorly across decentralized patient populations.
- PMDA staggered review timelines:Japan's pharmaceutical and medical device agency classifies functional electrical stimulation systems as controlled devices, creating six-to-eighteen month approval gaps versus FDA clearance windows.
- Passive bracing substitution ceiling:Mechanical orthotics retain dominance in pediatric cerebral palsy and peripheral nerve trauma segments where electrical stimulation contraindications persist.
Strategic Opportunities
- Home-based FES therapy reimbursement:United States payers are reassessing Current Procedural Terminology codes to distinguish clinic-administered from patient-operated electrical stimulation, potentially unlocking direct-to-consumer channels.
- Multiple sclerosis progressive monitoring:Wearable sensor integration with functional electrical stimulation platforms addresses disease trajectory documentation requirements that currently block reimbursement in European markets.
- Telehealth-orthotic fitting convergence:Remote gait analysis algorithms combined with 3D-printed custom bracing enable distributed care models in rural Australia and Canadian provinces.
Industry Challenges
- Orthotist workforce scarcity:Clinical fitting expertise for custom-fabricated neuroprosthetic systems concentrates in metropolitan hospital clusters, constraining service-based pricing power in secondary markets.
- Cross-border MDR technical documentation:European authorized representative requirements and notified body capacity bottlenecks delay neurostimulation device launches by twelve to twenty-four months.
- Legacy electronic health record integration:Functional electrical stimulation prescription workflows require API connectivity with Epic and Cerner systems that rehabilitation centers have deferred upgrading.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Foot Drop Treatment Market |
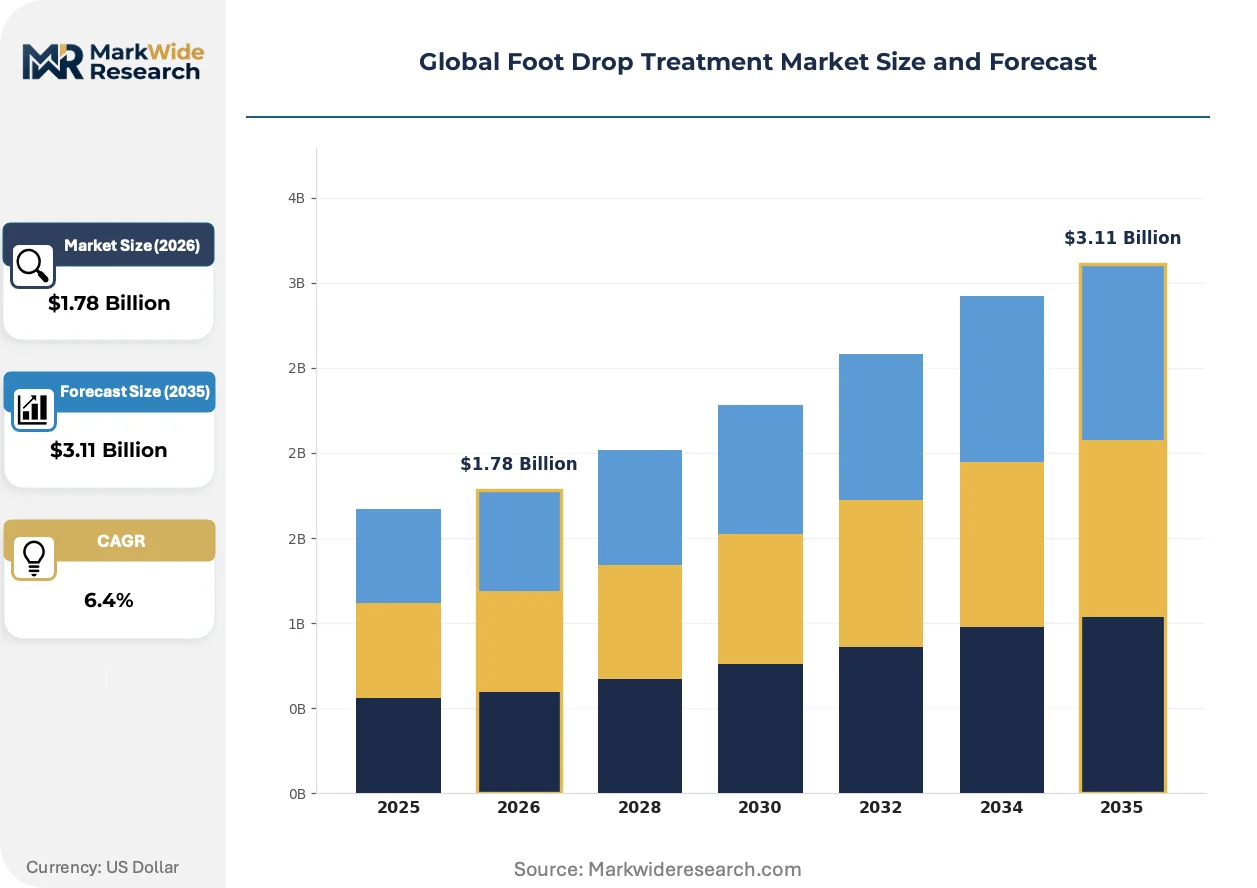
| Market Size in 2026 | $1.78 Billion |
| Market Size in 2035 | $3.11 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ankle Foot Orthosis, Functional Electrical Stimulation, Neuroprosthetics, Assistive Footwear Therapy Area: Stroke Rehabilitation, Multiple Sclerosis, Cerebral Palsy, Peripheral Neuropathy End User: Physiotherapy Clinics, Rehabilitation Centers, Home Care, Specialized Hospitals Distribution Channel: Hospitals, Orthotic Clinics, Online Stores, Medical Device Distributors |
| Companies Covered | Ossur, Axio Bionics, Ottobock, Hanger Inc., Smith & Nephew, Bioness Inc., Stryker Corporation, DJO Global Inc., Saebo Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Foot Drop Treatment Market Shifts & Advancements
Programmable neuromuscular electrical stimulation is compressing the boundary between passive bracing and active rehabilitation, forcing orthotic manufacturers to embed sensor feedback and adaptive pulse algorithms into traditional mechanical platforms.
Implantable peroneal nerve stimulators with wireless charging coils are rewriting the competitive map between external wearable and surgically implanted foot drop solutions. Academic medical centers in the United States and Germany are piloting these systems for chronic stroke patients who have plateaued with surface electrode functional electrical stimulation. The technology is compressing the addressable market for high-end custom ankle-foot orthosis fabrication among ambulatory adults with permanent upper motor neuron lesions.
Japan's PMDA has tightened electrical medical device electromagnetic compatibility standards under revised ministerial ordinances, requiring manufacturers to submit expanded shielding validation for functional electrical stimulation systems. The regulation is forcing European and North American exporters to redesign power management circuits and resubmit technical files, delaying product launches by nine to fourteen months. Home-use neurostimulation categories face the steepest compliance burden as PMDA applies hospital-grade safety margins to patient-operated devices.
Rehabilitation center purchasing departments are unbundling orthotic device procurement from clinical fitting services, creating separate vendor relationships for carbon fiber ankle-foot orthosis shells and certified orthotist labor. Hospital chains in the United States and Germany are negotiating multi-year device supply contracts with Ottobock and smaller regional fabricators while contracting orthotist services through staffing agencies. The split procurement model is most advanced in Medicare Advantage networks where device and professional service reimbursement rates diverge sharply.
Global Foot Drop Treatment Market Segmentation
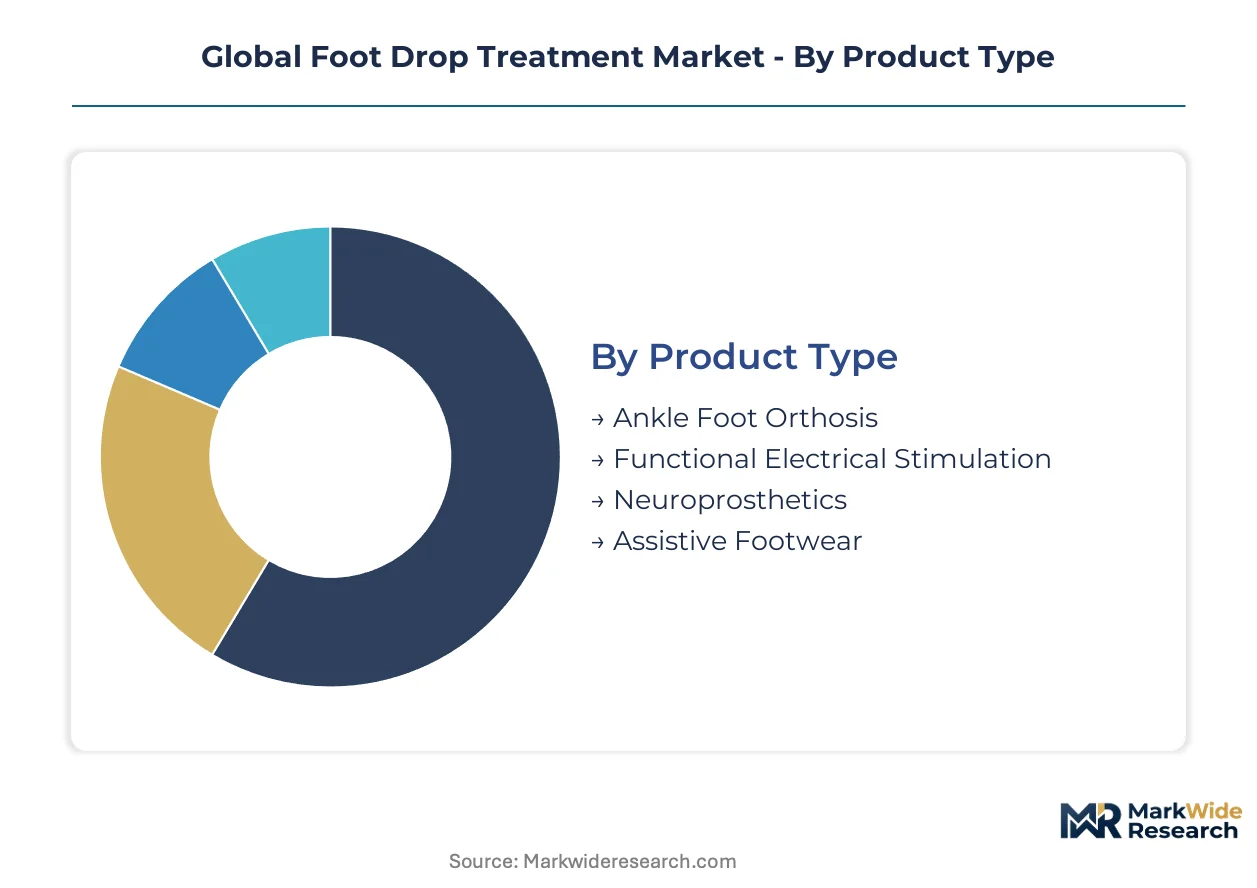
Foot drop treatment markets fragment across device physics, clinical indication, care setting, and procurement pathway. Each segmentation dimension carries distinct regulatory overlays and margin structures that shape manufacturer commercial strategy.
Product Type:
FDA 510(k) clearance governs functional electrical stimulation and neuroprosthetic systems, while ankle foot orthosis devices face lighter FDA Class I registration or self-certification under EU MDR general safety requirements.
- Ankle Foot Orthosis:Carbon fiber and thermoplastic shells provide passive dorsiflexion support through mechanical leverage. Demand concentrates in Medicare Advantage networks across Florida, Texas, and California where custom fabrication reimbursement remains stable.
- Functional Electrical Stimulation:Surface electrode systems deliver programmable pulse trains to peroneal nerve pathways. German rehabilitation centers in Bavaria and North Rhine-Westphalia are consolidating procurement around active neuromuscular platforms for hemiplegic gait disorders.
- Neuroprosthetics:Implantable peroneal nerve stimulators with wireless charging architectures.
- Assistive Footwear:Rocker-bottom and reinforced upper designs for mild dorsiflexion weakness.
Ankle foot orthosis sits at the top of the volume ranking, with functional electrical stimulation climbing the fastest.
Therapy Area:
Stroke rehabilitation generates the deepest patient pools across all geographies, while multiple sclerosis presents the most complex documentation burden for European reimbursement.
- Stroke Rehabilitation:Hemiplegic gait disorders drive the largest addressable population. Integrated care networks in Japan's Kanto and Kansai regions are standardizing functional electrical stimulation protocols for subacute stroke patients.
- Multiple Sclerosis:Progressive disease monitoring requirements create reimbursement friction. Wearable sensor integration is expanding fastest in United Kingdom NHS trusts and Dutch academic medical centers to satisfy payer documentation demands.
- Cerebral Palsy:Pediatric mechanical bracing dominates where electrical stimulation contraindications persist.
- Peripheral Neuropathy:Diabetic and compressive etiologies with variable prognosis.
Stroke rehabilitation commands the largest absolute volume, though multiple sclerosis is gaining share fastest through sensor-augmented therapy platforms.
End User:
Rehabilitation centers wield consolidated purchasing power in Germany and the United States, while home care channels depend on evolving CPT code distinctions for patient-operated devices.
- Rehabilitation Centers:Institutional procurement of functional electrical stimulation systems for ambulatory stroke programs. Major chains in Germany's Rhineland and United States Sun Belt are negotiating multi-year supply contracts.
- Physiotherapy Clinics:Outpatient settings with device rental and per-session billing models.
- Home Care:Patient-operated neurostimulation with reimbursement uncertainty.
- Specialized Hospitals:Academic medical centers piloting implantable peroneal nerve systems.
Rehabilitation centers anchor procurement volume, with home care expanding most quickly pending CPT code clarification.
Distribution Channel:
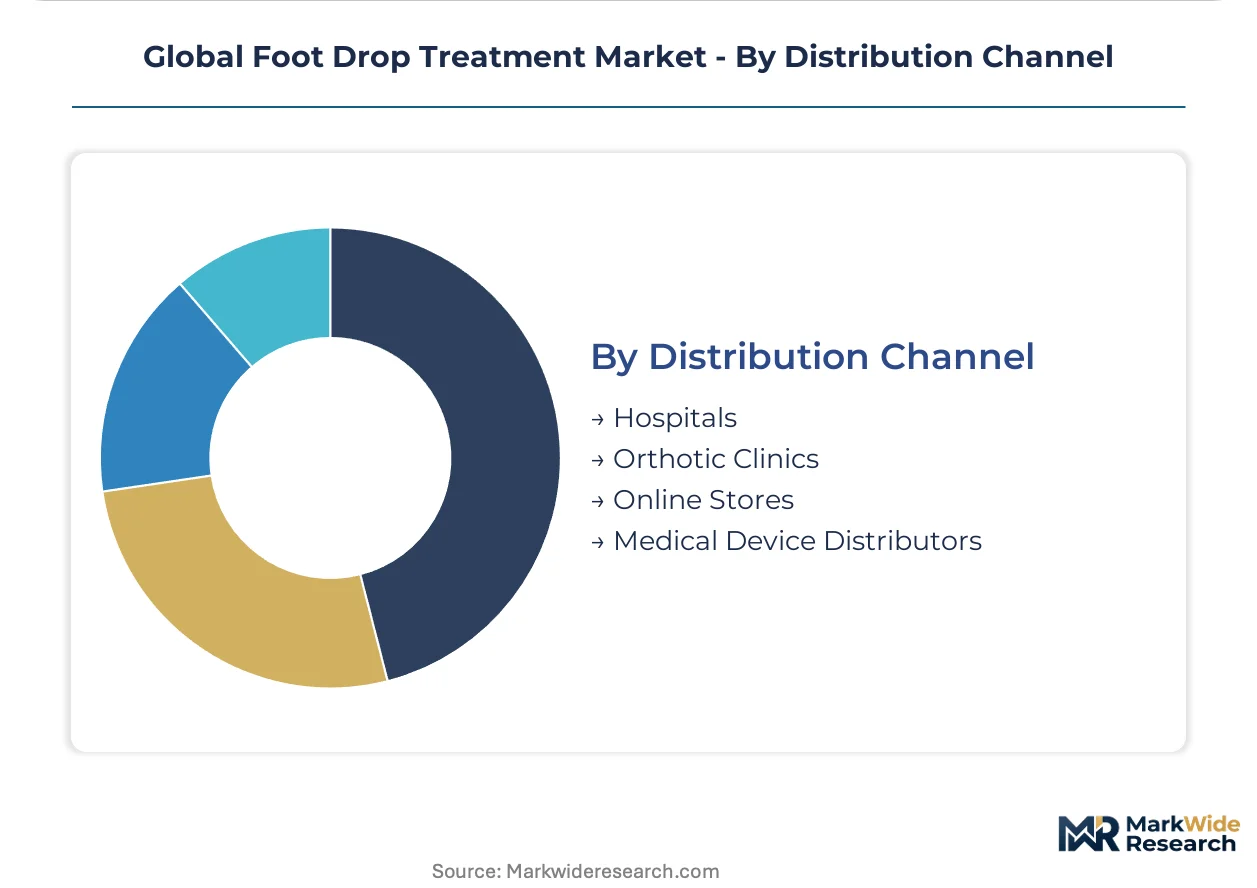
Orthotic clinics retain fitting service premiums, while online stores and medical device distributors compete on carbon fiber shell logistics.
- Orthotic Clinics:Certified orthotist labor bundled with custom fabrication. Metropolitan clusters in Chicago, Munich, and Tokyo concentrate clinical expertise and service-based pricing power.
- Hospitals:Direct procurement for inpatient and acute rehabilitation settings.
- Medical Device Distributors:Regional logistics for prefabricated ankle foot orthosis components.
- Online Stores:Direct-to-consumer prefabricated bracing with remote fitting guidance.
Orthotic clinics dominate value capture, with online stores climbing fastest among younger patient cohorts seeking prefabricated alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Rhineland industrial corridor anchors European procurement consolidation for functional electrical stimulation systems, with rehabilitation centers in Düsseldorf and Cologne negotiating multi-year supply contracts. Japan's Kanto region generates comparable device volumes through standardized stroke rehabilitation protocols. The United States Sun Belt and Australia's eastern seaboard complete the geographic concentration pattern.
United States
Medicare Advantage networks in Florida, Texas, and California drive carbon fiber ankle-foot orthosis demand through stable custom fabrication reimbursement. FDA 510(k) premarket notification pathways accelerate neuroprosthetic commercial entry for home-based therapy segments. Rehabilitation center chains across the Sun Belt are unbundling device procurement from orthotist labor contracts.
Germany
Bavaria and North Rhine-Westphalia rehabilitation centers consolidate procurement around active neuromuscular platforms for hemiplegic gait disorders. EU Medical Device Regulation harmonization filters marginal orthotic producers from European distribution channels. The Rhineland cluster concentrates clinical fitting expertise and service-based pricing power for custom-fabricated systems.
Japan
Kanto and Kansai integrated care networks standardize functional electrical stimulation protocols for subacute stroke patients. PMDA classifies electrical stimulation systems as controlled devices, creating six-to-eighteen month approval gaps versus FDA clearance windows. Tokyo metropolitan rehabilitation centers anchor institutional procurement volume for implantable peroneal nerve pilot programs.
Australia
New South Wales and Victoria physiotherapy clinics adopt remote gait analysis algorithms combined with 3D-printed custom bracing. The Therapeutic Goods Administration reviews functional electrical stimulation systems under active medical device classifications. Sydney and Melbourne metropolitan clusters concentrate telehealth-orthotic fitting convergence capabilities for rural patient distribution.
Global Foot Drop Treatment Market Competitive Landscape
Portfolio diversification dominates the current landscape as orthotic manufacturers embed sensor feedback into traditional mechanical platforms and neurostimulation specialists expand into implantable architectures. The market structure concentrates around three tiers: diversified medical technology conglomerates with surgical and neurotechnology portfolios, European orthotic fabricators with manufacturing scale advantages, and specialized neurostimulation developers focused on electrical pulse delivery systems. Strategic archetypes include integrated rehabilitation solution providers, component-focused contract manufacturers, and high-acuity implantable device developers. M&A activity and technology licensing agreements represent the dominant competitive moves as firms bridge gaps between passive bracing and active neuromuscular activation.
Among diversified medical technology conglomerates, Stryker Corporation and Smith & Nephew occupy positions spanning surgical intervention and neurotechnology portfolios. Ottobock exemplifies the European manufacturing-scale archetype with supply contract relationships across major hospital chains. Bioness Inc. anchors the specialized neurostimulation tier with implantable platform development. These three company types represent the structural segmentation: conglomerates extending into peripheral nerve repair, fabricators sustaining orthotic supply relationships, and specialists concentrating on electrical pulse delivery architectures.
| Leading Market Players |
|---|
| Ossur |
| Axio Bionics |
| Ottobock |
| Hanger Inc. |
| Smith & Nephew |
| Bioness Inc. |
| Stryker Corporation |
| DJO Global Inc. |
| Saebo Inc. |
| Others |
Supply & Pricing Matrix
Captive in-house production of carbon fiber shells and surface electrode assemblies anchors pricing power for integrated manufacturers serving German rehabilitation networks. Ottobock's Rhineland manufacturing footprint sustains margin capture through direct control over thermoplastic molding and orthotist training pipelines, while outsourced component sourcing in Asian electronics hubs exposes smaller FES developers to currency and tariff volatility.
Pricing Analysis
Carbon fiber and lithium-ion battery cost pass-through dominates pricing structures for ankle-foot orthosis and functional electrical stimulation systems respectively. Three-tier pricing structure across premium custom-fabricated, standard prefabricated, and economy off-the-shelf levels reflects certification grade differentiation under FDA 510(k) and EU MDR pathways. Pricing pressure stems from Medicare Advantage reimbursement compression in Florida and Texas markets where custom fabrication rates face annual adjustment. Hospital procurement committees exhibit highest price sensitivity for passive bracing, while academic medical centers absorb premium neuroprosthetic pricing for implantable pilot programs.
Supply Chain Analysis
Direct-to-hospital contracts handle institutional rehabilitation center demand in Germany, Japan, and the United States, bypassing traditional distributor markups for high-volume functional electrical stimulation procurement. Component sourcing concentrates on South Korean lithium-ion cells, Chinese printed circuit board assemblies, and German precision polymers for carbon fiber layup. Raw material dependencies include medical-grade silicone for surface electrodes, rare earth magnets for wireless charging coils, and aerospace-certified epoxy resins. Single-source vulnerability in PMDA-compliant electromagnetic shielding components creates nine-to-fourteen month launch delays for exporters entering Japanese markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where stroke rehabilitation protocols in Bavaria and North Rhine-Westphalia shift procurement toward sensor-integrated functional electrical stimulation platforms commanding service-based premiums.
For Market Incumbents: Cement orthotist workforce control through captive training academies in Düsseldorf and Cologne metropolitan clusters, insulating service-based pricing from staffing agency competition. Lock multi-year carbon fiber supply contracts before aerospace demand recovery tightens precursor availability. FDA 510(k) clearance velocity serves as the priority defensive lever against emerging neurostimulation specialists targeting home-based therapy segments. For New Entrants and Emerging Players: FDA 510(k) pathway streamlining in the United States opens a window for surface electrode functional electrical stimulation systems targeting direct-to-consumer channels pending CPT code clarification. White-space concentrates in Australian rural telehealth-orthotic fitting convergence and United Kingdom NHS trust sensor-augmented multiple sclerosis monitoring platforms. Go-to-market acceleration through 3D-printed custom bracing partnerships with New South Wales physiotherapy networks bypasses orthotist scarcity constraints. For Investors and Strategic Acquirers: Consolidation pressure builds where EU MDR technical documentation requirements exceed marginal orthotic producer compliance capabilities, filtering subscale competitors from German distribution channels. Long-term viability favors implantable neurostimulation platforms with wireless charging architectures addressing chronic stroke patient plateau populations. Acquisition target archetype: specialized FES developers with PMDA pre-submission files and United States rehabilitation center pilot data. Signal to watch: CMS National Coverage Determination for home-based patient-operated electrical stimulation.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Multi-year supply contracts with German Rhineland rehabilitation chains lock recurring revenue streams. |
| CE Marking Pathway | MDR clinical evidence investment filters marginal competitors from European neuroprosthetic distribution. |
| Software Companion Development | Wearable sensor integration satisfies United Kingdom NHS progressive disease monitoring requirements. |
| Reimbursement Strategy | CPT code distinction advocacy unlocks United States home-based FES therapy direct-to-consumer channels. |
| FDA Submission | Premarket notification clearance accelerates commercial entry for surface electrode neurostimulation platforms. |
Research Methodology
Coverage spans Germany, Japan, the United States, and Australia, with primary inputs from each market's rehabilitation center procurement directors, orthotist clinical specialists, biomedical engineers, and GPO contracts managers. Secondary validation draws from FDA 510(k) premarket notification databases, PMDA controlled device approval records, EU MDR notified body technical file disclosures, and hospital procurement contract registries. Bottom-up patient volume modeling triangulates against top-down manufacturer revenue estimates across the analysis window.
Rate-of-change decomposition separates volume drivers from pricing dynamics across product type, therapy area, end user, and distribution channel segmentation. CAGRs derive from patient referral trend analysis in integrated stroke care networks, reimbursement code evolution tracking, and neuroprosthetic device replacement cycle assumptions. Industry-specific forecast inputs include PMDA staggered review timeline probabilities and Medicare Advantage custom fabrication rate stability indices.
Revisions become necessary when PMDA electromagnetic compatibility standards tighten, EU notified body capacity bottlenecks extend, or United States CPT code bundling decisions reshape home-based therapy economics. Forecasts reflect documented assumptions regarding stroke patient volume trajectories and carbon fiber precursor supply elasticity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedics
ACL Reconstruction Market
Orthopedics
Elbow Stiffness Market
Orthopedics
Orthopedic Pillow Market
Orthopedics
Bilateral Osteoarthritis Treatment Market
Orthopedics
Athletic Knee Treatment Market
Orthopedics
US Arthritis Market
Orthopedics
Knee Hyaluronic Acid Injections Market
Orthopedics
Osteopenia Treatment Market
Orthopedics
Osgood-Schlatter Market
Orthopedics
Costochondritis Market
Orthopedics
Swollen Knee Treatment Market
Orthopedics
Kyphosis Market
Orthopedics
Orthopedics Market
Orthopedics
Osteoarthritis Treatment Market
Orthopedics
Canine Orthopedics Market
Orthopedics
Cruciate Ligament Repair Procedures Market