
 US Arthritis Market | 2026-2036
US Arthritis Market Size, Share, and Industry Trends Forecast 2026-2036
US Arthritis Market Analytics
Buyer concentration among hospital purchasing consortia is hardening as integrated delivery networks consolidate formulary decisions across multistate systems. AbbVie Inc. leverages its immunology portfolio depth to sustain high physician loyalty in academic medical centers. Johnson & Johnson Services, Inc. anchors its position through autoimmune franchise breadth spanning multiple therapy areas. Bristol-Myers Squibb Company differentiates via oncology-immunology crossover expertise that competes for specialist prescribing attention.
Arthritis encompasses inflammatory and degenerative joint disorders characterized by synovial membrane inflammation, cartilage erosion, and progressive functional impairment requiring pharmacologic intervention and surgical management. The condition demands therapies targeting cytokine pathways, prostaglandin synthesis, and immune modulation to preserve mobility and reduce systemic complications. Biologics command premium positioning among product types as targeted monoclonal antibodies displace conventional DMARDs in moderate-to-severe rheumatoid arthritis. Injectable delivery modes capture growing share as self-administration devices improve adherence, while oral NSAIDs remain entrenched in osteoarthritis maintenance protocols. Rheumatoid arthritis leads therapy area revenue due to chronic treatment duration, though psoriatic arthritis segments expand with dermatology-rheumatology convergence.
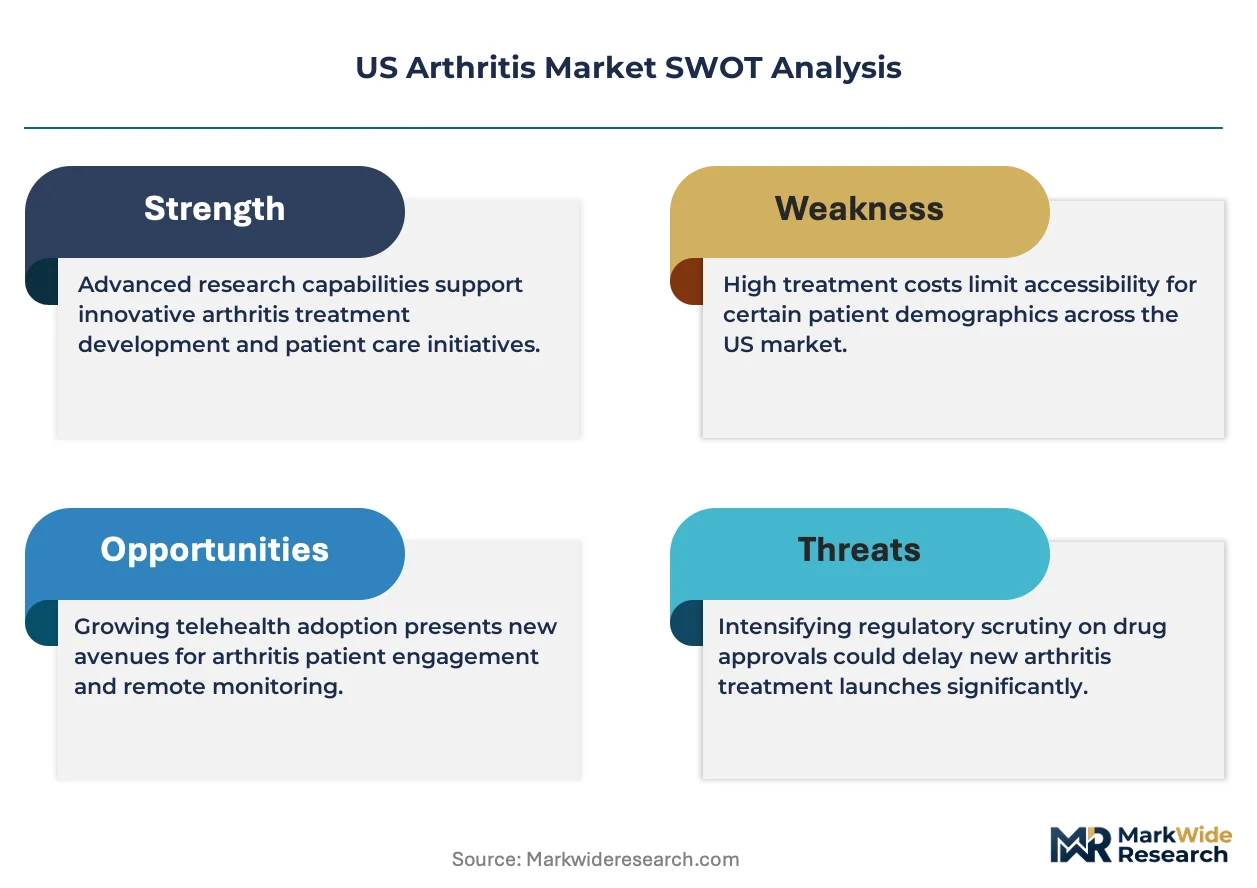
FDA approval pathways for biosimilars and CMS reimbursement determinations directly shape product commercialization timelines and physician adoption thresholds in the US market. The IRA Medicare price negotiation provisions and FDA accelerated approval standards together reshape investment calculus for novel mechanism assets. Stakeholders must monitor how state Medicaid prior authorization variations and FDA labeling expansions interact to determine accessible patient populations for next-generation therapies.
Market Dynamics
Medicare reimbursement policies under the IRA are accelerating formulary consolidation across hospital purchasing consortia, compressing commercial timelines for novel biologic assets and reshaping prescriber access hierarchies.
Growth Catalysts
- IRA Medicare Price Negotiation:The Inflation Reduction Act's drug pricing provisions create predictable revenue floors that stabilize investment in next-generation immunology assets.
- Self-Administration Devices:Prefilled syringes and auto-injectors for biologics reduce infusion center dependency and expand addressable patient populations in rural corridors.
- Texas-Florida-California Corridors:Aging demographic concentration and rheumatology specialist density in these states generate disproportionate prescription volume for advanced therapies.
Market Restraints
- Biosimilar Erosion:FDA-approved adalimumab biosimilars are compressing originator pricing power and narrowing commercial margin structures for reference products.
- Infusion Center Capacity:Biologic administration requires specialized nursing infrastructure that concentrates in urban academic medical centers, limiting rural access.
- Prior Authorization Friction:State Medicaid programs impose variable step-therapy requirements that delay biologic initiation and extend conventional DMARD exposure.
Strategic Opportunities
- Oral JAK Inhibitor Expansion:Small-molecule alternatives to injectable biologics capture patients with needle aversion and those seeking pharmacy-channel dispensing convenience.
- Dermatology-Rheumatology Convergence:Psoriatic arthritis diagnosis at dermatology entry points expands the treatable population before joint damage progression.
- Value-Based Contracting:CMS ACO REACH and Medicare Advantage risk arrangements enable outcomes-based reimbursement for sustained disease remission.
Industry Challenges
- Rheumatology Workforce Scarcity:Fellowship program output fails to match patient population growth, extending wait times for specialist evaluation.
- Biosimilar Switching Complexity:Nocebo effects and immunogenicity concerns complicate non-medical substitution protocols across integrated delivery networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Arthritis Market |
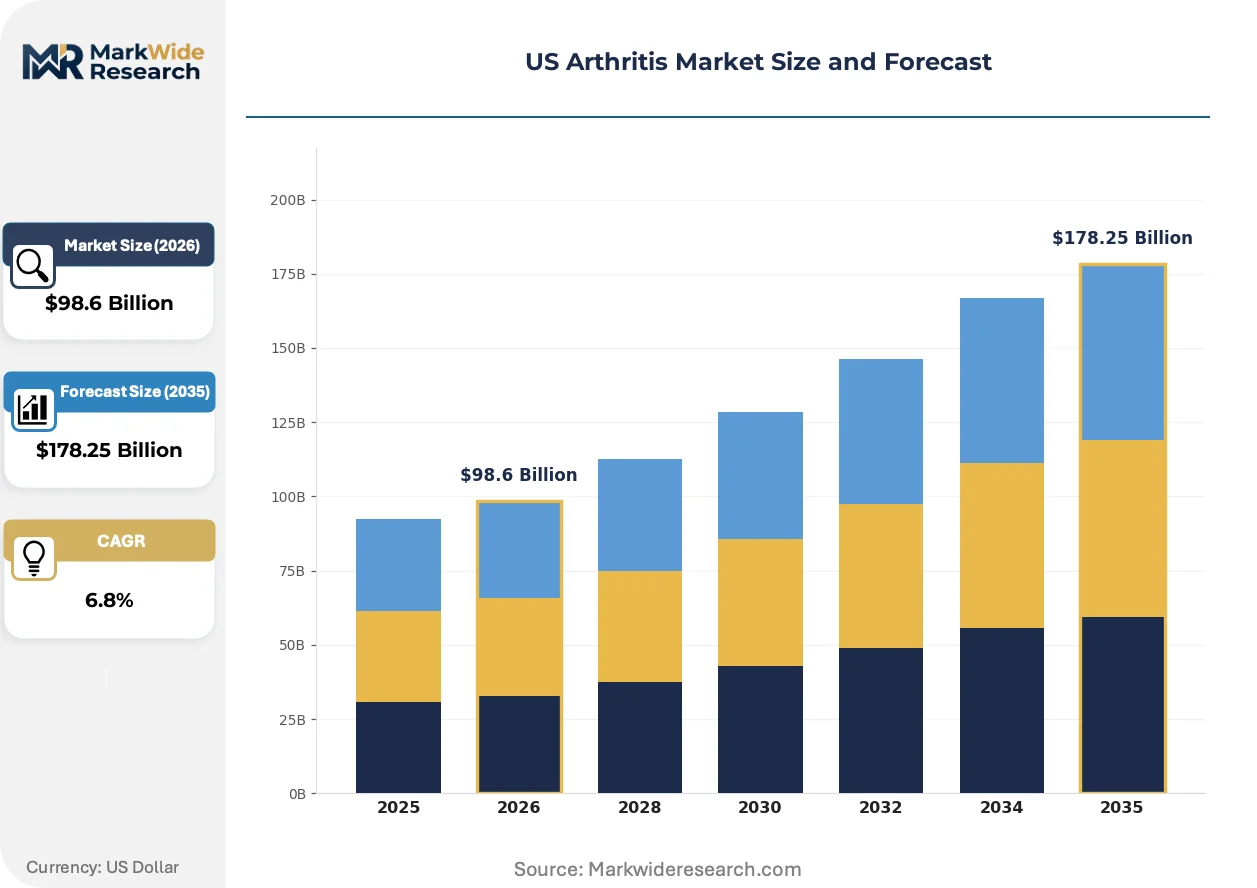
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $178.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: NSAIDs, DMARDs, Biologics, Corticosteroids End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Therapy Area: Rheumatoid Arthritis, Osteoarthritis, Psoriatic Arthritis, Gout Delivery Mode: Oral, Injectable, Topical, Infusion |
| Companies Covered | AbbVie Inc., Johnson & Johnson Services, Inc., Bristol-Myers Squibb Company, Amgen Inc., Pfizer Inc., Novartis AG, Sanofi, F. Hoffmann-La Roche Ltd, Anika Therapeutics, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Arthritis Market Evolving Landscape
Biologic delivery modalities and reimbursement architectures are undergoing parallel transformation, with self-administration technologies and outcomes-based payment models converging to redefine patient access pathways and prescriber workflow economics.
Subcutaneous biologic formulations are expanding into rheumatology practice settings previously reserved for infusion center administration. Community-based rheumatology clinics in the Midwest and Southeast are adopting these devices to retain patients who would otherwise migrate to hospital outpatient departments. This geographic decentralization is compressing site-of-care revenue capture for academic medical centers while expanding manufacturer addressable markets.
FDA accelerated approval standards for inflammatory disease therapies are tightening evidentiary requirements for surrogate endpoints. The agency now demands larger safety databases and longer observation periods before full approval conversion, extending commercialization timelines for novel mechanism assets. Sponsors are responding with adaptive trial designs that embed confirmatory efficacy studies within initial registration programs.
Hospital purchasing consortia are consolidating formulary decisions across multistate integrated delivery networks, reducing the number of distinct contracting negotiations required for national product access. This buyer concentration compresses price differentiation opportunities and elevates the importance of real-world evidence packages in competitive positioning. The phenomenon is most visible in the Northeast and Mid-Atlantic regions where IDN merger activity has accelerated since 2022.
US Arthritis Market Segmentation
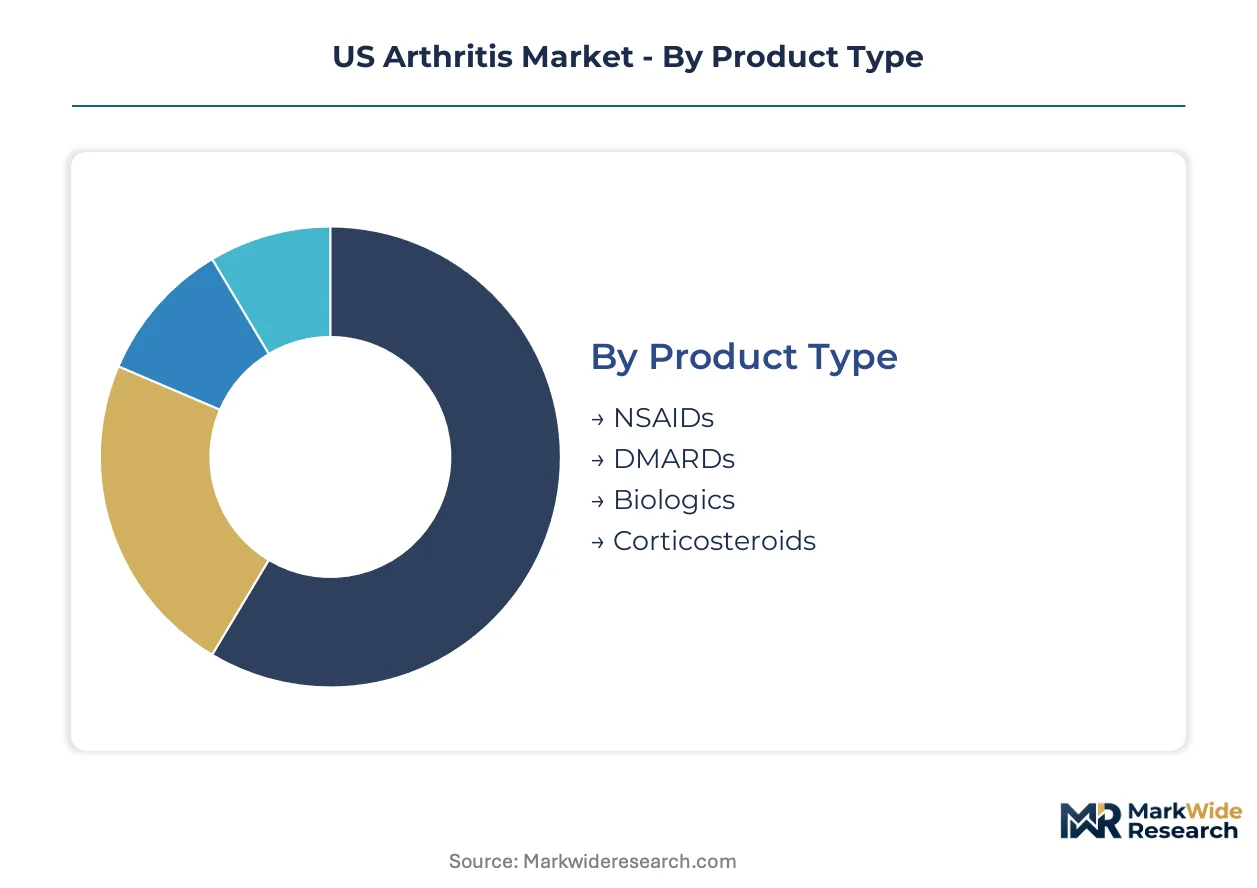
Arthritis market segmentation reveals how FDA approval pathways, CMS reimbursement tiers, and site-of-care economics partition commercial opportunity across distinct product and delivery categories. Each segment carries specific regulatory certification burdens that determine manufacturer investment thresholds and prescriber access hierarchies.
Product Type:
FDA BLA versus NDA pathways impose divergent clinical trial requirements and post-market surveillance obligations across product categories, with biologics facing the most stringent immunogenicity monitoring mandates.
- NSAIDs:Oral small-molecule formulations targeting cyclooxygenase enzymes for osteoarthritis pain management. Demand concentrates in retail pharmacy channels across Florida and California where Medicare Part D formularies favor low-cost maintenance therapy.
- DMARDs:Conventional synthetic agents like methotrexate and hydroxychloroquine that modulate immune cell proliferation. Texas Medicaid programs drive volume through mandatory step-therapy protocols that require DMARD failure before biologic authorization.
- Biologics:Engineered proteins requiring cold-chain distribution and REMS compliance for TNF-alpha and IL-6 pathway inhibition.
- Corticosteroids:Glucocorticoid formulations for acute flare management with intra-articular and systemic delivery options.
NSAIDs sit at the top of the volume ranking, with biologics climbing the fastest as FDA biosimilar approvals expand prescriber comfort with originator alternatives.
End User:
Site-of-care economics and nursing infrastructure availability segment prescriber behavior, with infusion center capacity constraints pushing biologic administration toward lower-acuity settings.
- Hospitals:Academic medical centers and community hospitals with 340B pricing eligibility and specialist rheumatology departments. Urban corridors in Houston, Miami, and Los Angeles anchor biologic infusion volume due to rheumatologist density and Medicare Advantage penetration.
- Clinics:Community-based rheumatology practices adopting subcutaneous self-administration protocols. The Southeast and Midwest show steepest expansion as independent practices invest in cold storage and REMS certification to retain patients.
- Home Care:Home health nursing services for patient-administered injectables with telemedicine oversight.
- Rehabilitation Centers:Post-surgical and physical therapy facilities managing osteoarthritis recovery protocols.
Hospitals capture the largest revenue share per patient episode, though clinics are gaining share fastest as self-administration devices reduce site-of-care dependency.
Therapy Area:
Disease duration, joint damage reversibility, and comorbidity profiles determine treatment intensity and lifetime value calculations across rheumatologic indications.
- Rheumatoid Arthritis:Chronic autoimmune synovitis requiring continuous immune modulation to prevent irreversible joint destruction. Northeast and Mid-Atlantic IDN consolidation has compressed formulary access to three preferred TNF inhibitors per system.
- Osteoarthritis:Degenerative cartilage erosion managed primarily through analgesia and surgical intervention. California's aging demographic concentration and high knee replacement rates generate disproportionate NSAID and intra-articular corticosteroid demand.
- Psoriatic Arthritis:Dermatology-rheumatology crossover indication with skin manifestation precedents.
- Gout:Urate crystal deposition disorder with acute flare and chronic prophylaxis segments.
Rheumatoid arthritis leads absolute prescription volume, with psoriatic arthritis expanding most quickly as IL-17 and IL-23 inhibitors capture dermatology referral pathways.
Delivery Mode:
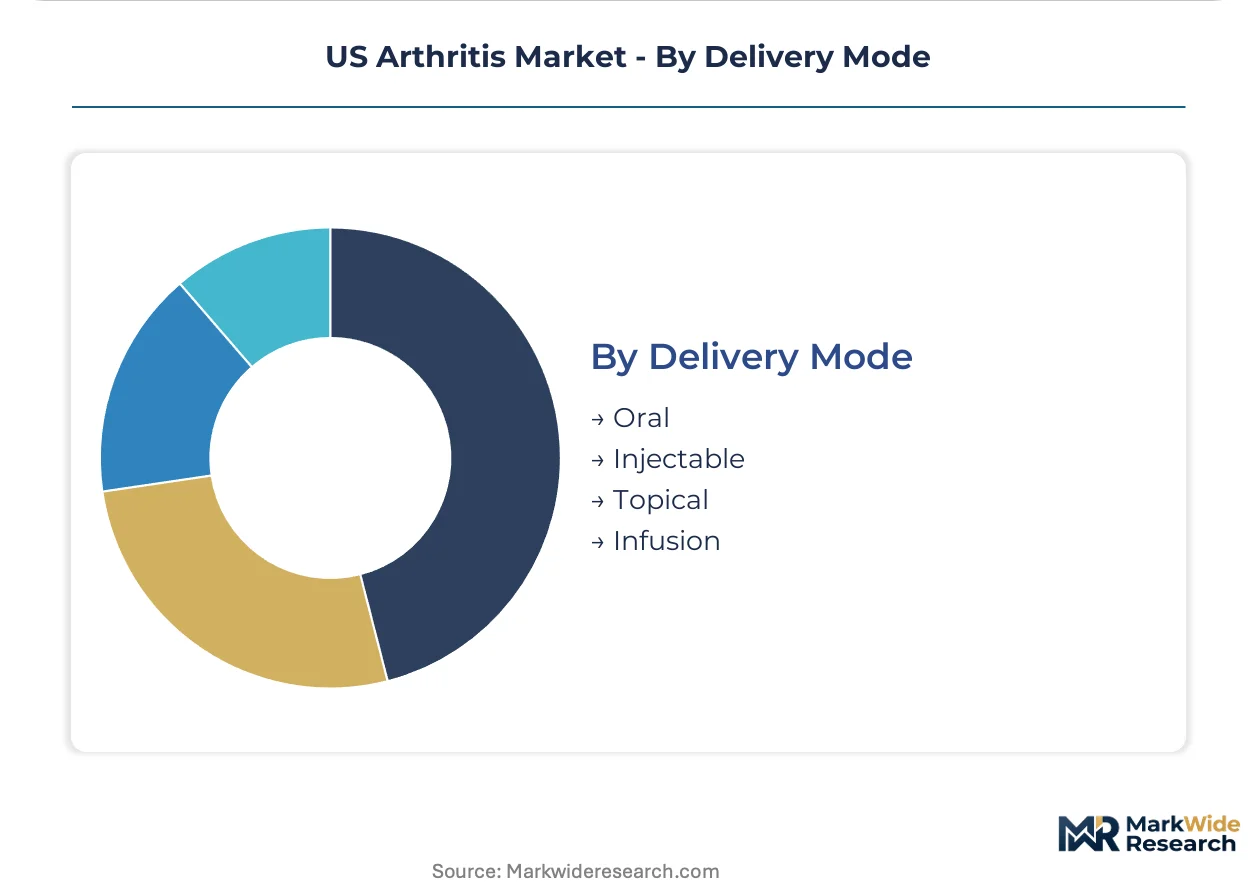
Administration complexity, patient self-efficacy requirements, and pharmacy versus medical benefit classification partition reimbursement economics across delivery modalities.
- Oral:Small-molecule formulations with pharmacy benefit administration and patient-controlled dosing schedules. Medicare Part D coverage gaps in Texas and Florida create seasonal adherence patterns around catastrophic coverage thresholds.
- Injectable:Prefilled syringes and auto-injectors for subcutaneous biologic administration. Rural access expansion in Mountain West states depends on mail-order pharmacy cold-chain reliability and patient training program availability.
- Topical:Localized NSAID and capsaicin formulations for osteoarthritis symptom management.
- Infusion:Intravenous biologic administration requiring specialized nursing supervision and adverse event monitoring.
Oral formulations dominate total prescription counts, with injectables posting the steepest volume trajectory as subcutaneous biologics displace infusion center visits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas and Florida outperform California in biologic prescription density per rheumatologist, while the Northeast corridor leads in integrated delivery network consolidation and formulary standardization.
Texas
Texas Medicaid mandates step-therapy protocols that delay biologic authorization until conventional DMARD failure, creating extended treatment windows for methotrexate and hydroxychloroquine. The state's 340B pricing eligibility concentrates hospital purchasing power in Houston and Dallas medical centers. San Antonio's rheumatology specialist shortage extends wait times beyond 90 days, pushing stable patients toward telemedicine oversight.
Florida
Florida's Medicare Part D catastrophic coverage thresholds generate seasonal adherence patterns for oral NSAIDs among osteoarthritis patients in retirement communities. The state's prior authorization friction varies by county, with Broward and Miami-Dade imposing stricter biologic documentation requirements than northern counties. Tampa's infusion center capacity constraints accelerate subcutaneous device adoption among community rheumatology practices.
California
California's aging demographic concentration drives disproportionate demand for knee replacement recovery protocols and intra-articular corticosteroid administration. The state's Medicaid managed care expansion integrates dermatology-rheumatology referral pathways for psoriatic arthritis diagnosis. Los Angeles academic medical centers anchor biologic infusion volume through Medicare Advantage risk arrangements and specialist density.
Northeast Corridor
Integrated delivery network merger activity since 2022 has compressed formulary access to three preferred TNF inhibitors per system across New York, Massachusetts, and Pennsylvania. The IRA Medicare price negotiation provisions reshape investment calculus for novel mechanism assets in Boston's biotech cluster. Philadelphia's hospital purchasing consortia consolidate multistate contracting negotiations, reducing price differentiation opportunities for manufacturers.
Southeast
The Southeast exhibits the steepest expansion of community-based rheumatology clinics adopting subcutaneous self-administration protocols to retain patients. Georgia and North Carolina Medicaid programs impose variable step-therapy requirements that extend conventional DMARD exposure. Atlanta's independent practices invest in cold storage and REMS certification to compete with hospital outpatient departments for biologic prescribing volume.
US Arthritis Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the US arthritis market, creating a tiered structure where portfolio breadth and immunology depth determine formulary positioning. Large pharmaceutical conglomerates leverage autoimmune franchise cross-selling to secure hospital system contracts, while biotechnology specialists concentrate on monoclonal antibody innovation. Three archetypes dominate: diversified immunology portfolio holders, targeted biologic developers, and biosimilar manufacturers. M&A activity concentrates autoimmune assets under integrated platforms, while strategic partnerships between device manufacturers and drug sponsors expand self-administration reach.
Within the diversified portfolio tier, AbbVie Inc. and Johnson & Johnson Services, Inc. occupy positions shaped by immunology franchise breadth and hospital system loyalty. Bristol-Myers Squibb Company exemplifies the oncology-immunology crossover archetype, competing for specialist prescribing attention through mechanism differentiation. These three companies represent the competitive anchors around which formulary consolidation and value-based contracting architectures organize.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Johnson & Johnson Services, Inc. |
| Bristol-Myers Squibb Company |
| Amgen Inc. |
| Pfizer Inc. |
| Novartis AG |
| Sanofi |
| F. Hoffmann-La Roche Ltd |
| Anika Therapeutics, Inc. |
| Others |
Value Network & Pricing Analysis
Captive distribution through hospital purchasing consortia anchors both supply positioning and pricing power for biologic manufacturers serving the US arthritis market. These integrated delivery networks consolidate formulary decisions across multistate systems, compressing price differentiation opportunities while elevating real-world evidence requirements for competitive positioning.
Pricing Analysis
Capacity additions in biosimilar manufacturing are reshaping price floors for reference biologics as FDA-approved adalimumab alternatives compress originator margin structures. Value-based contracting models dominate reimbursement architectures, with outcomes-based arrangements tethered to sustained disease remission metrics. Cost compression in the TNF-inhibitor tier is intensifying because Medicare Advantage risk arrangements demand demonstration of superior cost-effectiveness. Hospital systems exhibit highest price sensitivity due to 340B pricing eligibility, while academic medical centers retain lowest sensitivity through specialist loyalty and formulary control.
Supply Chain Analysis
Cold-chain logistics costs for biologics concentrate distribution investment in proximity to rheumatology specialist density corridors. Manufacturing capacity clusters in the United States, Ireland, and Puerto Rico for fill-finish operations serving the domestic market. Active pharmaceutical ingredient production rests on mammalian cell culture capacity and single-use bioreactor availability. Single-source vulnerability persists for specialized auto-injector device components. Distribution runs through specialty pharmacy channels with REMS-certified cold storage infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US arthritis market functions as a stable compounder anchored by the IRA's predictable revenue floors for immunology assets, which stabilize investment in next-generation therapies despite biosimilar headwinds.
For Market Incumbents: Deploy real-world evidence generation as the primary defensive lever against biosimilar substitution protocols across integrated delivery networks. Invest in subcutaneous formulation development to capture patients migrating from infusion centers to community rheumatology practices. Strengthen REMS certification programs to maintain hospital system formulary preference against emerging biologic developers.
For New Entrants and Emerging Players: The premium-to-economy pricing gap in oral JAK inhibitors offers white-space entry for small-molecule specialists seeking pharmacy-channel dispensing convenience. Target the Southeast and Midwest community clinic segments where independent practices seek cold storage partnerships to retain biologic prescribing volume. Pursue dermatology-rheumatology convergence pathways for psoriatic arthritis diagnosis before joint damage progression.
For Investors and Strategic Acquirers: Roll-up economics work for mid-cap biologic developers because formulary consolidation across multistate IDNs rewards scaled immunology portfolios with preferred contracting status. Five-to-ten year viability hinges on pipeline depth beyond TNF-alpha mechanisms. Monitor FDA accelerated approval conversion rates as the inflection indicator for novel mechanism asset valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | Reduces infusion center dependency and expands rural patient access corridors. |
| Real-World Evidence Generation | Strengthens formulary positioning against biosimilar substitution in IDN negotiations. |
| Dermatology Partnership Expansion | Captures psoriatic arthritis patients before rheumatology referral pathways. |
| Value-Based Contracting Infrastructure | Enables CMS ACO REACH participation for outcomes-based reimbursement. |
| REMS Certification Investment | Qualifies community clinics for biologic dispensing outside hospital systems. |
Research Methodology
Multiple input streams — rheumatology practice administrators, hospital formulary directors, payer access specialists, and biologic supply chain managers — were reconciled with secondary validation from FDA BLA filings, CMS reimbursement determinations, and integrated delivery network procurement databases. Bottom-up prescription volume modeling and top-down market sizing triangulation anchored value estimates across the analysis window.
Historical prescription trends were cross-referenced against expert panel assessments to derive growth trajectories across product type, delivery mode, therapy area, and end-user segments. CAGRs were calibrated using patient population projections, rheumatology workforce expansion rates, and biosimilar penetration assumptions. Forecast inputs incorporated IRA Medicare price negotiation provisions and state Medicaid prior authorization variation patterns.
Caveats apply where FDA labeling expansions or state Medicaid step-therapy modifications could materially shift the outlook for novel mechanism assets. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedics
Bone Spur Market
Orthopedics
Orthopedic Soft Tissue Repair Market
Orthopedics
Kyphosis Market
Orthopedics
Elbow Stiffness Market
Orthopedics
Anti-Osteoporosis Therapy and Fracture Healing Market
Orthopedics
Costochondritis Market
Orthopedics
Skeletal Deformation Correction Market
Orthopedics
Swollen Knee Treatment Market
Orthopedics
Rickets Market
Orthopedics
Tendon Repair Market
Orthopedics
Athletic Knee Treatment Market
Orthopedics
United States Orthopedic Braces and Support Market
Orthopedics
Europe Extremity Reconstruction Market
Orthopedics
Hallux Rigidus Market
Orthopedics
Osteoporosis Treatment Market
Orthopedics
Europe Bone Metastasis Market