
 Orthopedic Pillow Market | 2026-2036
Orthopedic Pillow Market Size, Share, and Industry Trends Forecast 2026-2036
Orthopedic Pillow Market Insights
Memory foam formulations derived from petroleum-based polyols are decoupling from conventional supply chains as plant-based alternatives gain scale. Tempur-Pedic International leverages proprietary viscoelastic chemistry to sustain premium positioning across North American retail channels. Sleep Number Corporation anchors its orthopedic pillow line within an integrated sleep ecosystem, competing on adjustable firmness technology rather than material alone. Coop Home Goods differentiates through shredded memory foam designs that allow user-customizable loft, occupying the mid-market segment with strong Amazon channel control.
An orthopedic pillow is a ergonomically contoured support device engineered to maintain cervical spine alignment during sleep or rest, typically fabricated from viscoelastic polyurethane foam, natural latex, or gel-infused composites with densities ranging from 40 to 100 kg/m³. Its primary commercial purpose is to alleviate neck pain, reduce pressure points, and support postural correction for consumers with musculoskeletal conditions or recovery needs. Memory foam products lead the product type landscape due to established consumer familiarity and manufacturing scale, while gel-infused variants represent the fastest-growing sub-category as thermal regulation becomes a decisive purchase factor. The home care end user segment commands the largest volume share, though physiotherapy clinics concentrate margin pools through practitioner-endorsed premium positioning and repeat institutional procurement.
The U.S. FDA's Class I medical device framework governs labeling claims for pain relief and therapeutic efficacy, while the EPA's CertiPUR-US voluntary certification program shapes consumer trust around foam emissions and content safety. The EU's REACH regulation restricts certain chemical additives in polyurethane production, forcing reformulation investments for European market access. Stakeholders must monitor evolving state-level flammability standards in California and New York alongside emerging ESG disclosure requirements that will increasingly bind foam suppliers to verified supply chain transparency.
Market Dynamics
The orthopedic pillow market faces structural pressure from the U.S. FDA's Class I medical device classification, which compresses labeling freedom for therapeutic claims while simultaneously creating certification moats that filter marginal competitors from premium positioning.
Growth Catalysts
- REACH chemical restrictions:The EU's additive bans force polyurethane reformulation, accelerating plant-based polyol substitution and creating first-mover advantages for certified European suppliers.
- Aging home care populations:Non-invasive cervical support demand concentrates among consumers over 65 seeking alternatives to pharmaceutical pain management.
- Thermal regulation technology:Gel-infused foam composites address sleep temperature complaints, capturing dissatisfied memory foam users through measurable cooling performance.
Market Restraints
- Petroleum polyol volatility:Crude oil price swings transmit directly to viscoelastic foam input costs, compressing margin predictability for mid-tier manufacturers without captive chemical supply.
- Chinese foam concentration:Bulk polyurethane production clusters in Shandong and Zhejiang provinces, exposing buyers to single-geography supply disruption risk and freight cost spikes.
- CertiPUR-US compliance friction:The EPA-aligned voluntary certification demands third-party emissions testing that extends new product timelines by 4-6 months for non-integrated brands.
Strategic Opportunities
- Direct-to-consumer channel expansion:Sleep wellness clinics and telehealth platforms create practitioner-endorsed distribution bypassing traditional retail margin stacking.
- Adjustable loft customization:Shredded foam architectures enable user-modified cervical support, addressing anatomical diversity that one-piece contours fail to capture.
- California flammability standard alignment:TB 117-2013 compliance investments unlock the largest U.S. state market while satisfying emerging ESG disclosure requirements for supply chain transparency.
Industry Challenges
- Biomechanical engineering talent scarcity:Ergonomic design expertise sits concentrated within medical device firms, forcing pillow manufacturers to compete for specialized human factors specialists.
- Multi-certification coordination:Simultaneous FDA device registration, CertiPUR-US foam validation, and state-level fire safety approvals create parallel compliance workflows that strain smaller R&D teams.
- Legacy retail inventory reconciliation:Big-box return policies and seasonal demand forecasting mismatches generate working capital intensity for brands dependent on brick-and-mortar shelf presence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Orthopedic Pillow Market |
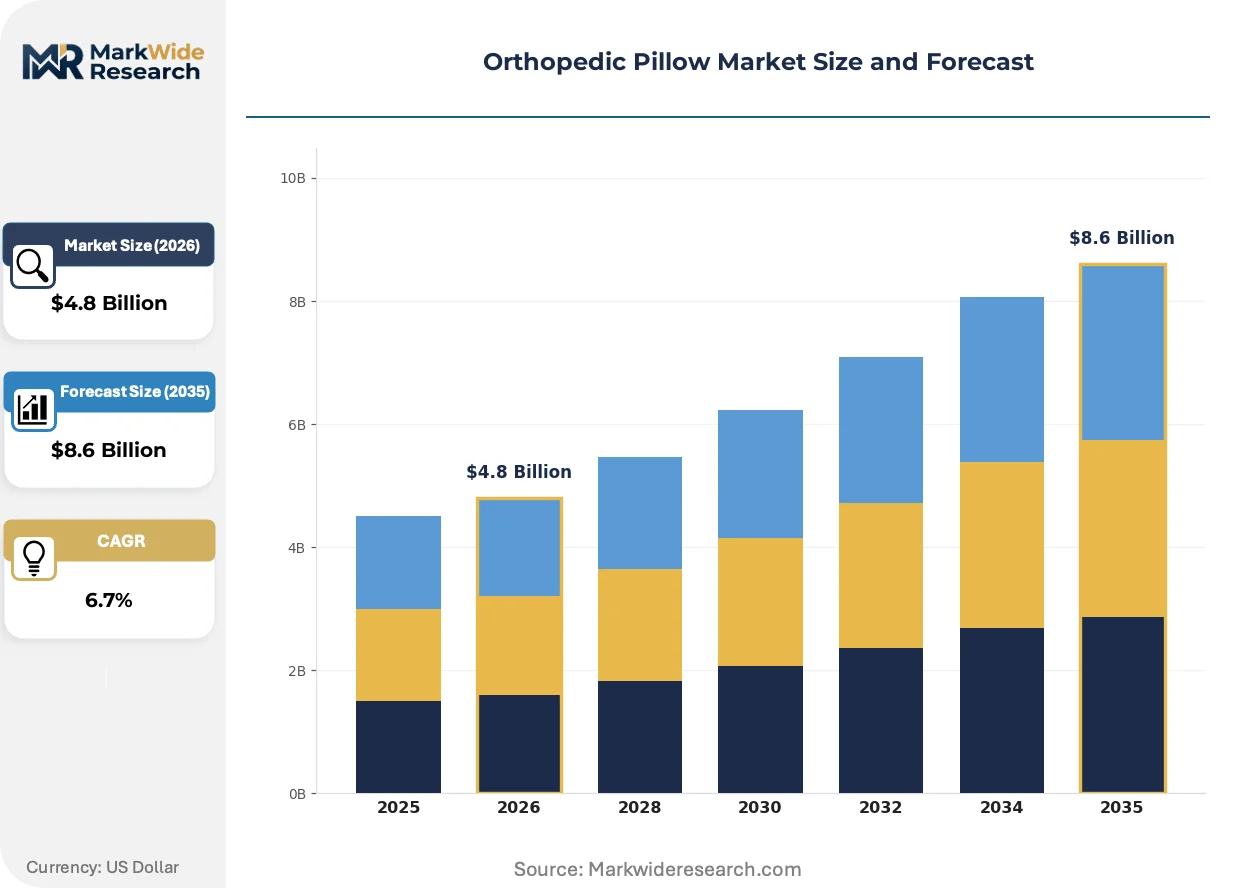
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Memory Foam, Latex, Microbead, Gel End User: Hospitals, Chiropractors, Physiotherapy Clinics, Home Care Size: Standard, Large, Travel, Custom Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Supermarkets |
| Companies Covered | Tempur-Pedic International, Inc., Sleep Number Corporation, Mediflow Inc., PharMeDoc, Coop Home Goods, Malouf, Core Products International, Inc., Contour Products, Inc., Relax The Back, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orthopedic Pillow Market Trends and Innovations
Material science convergence with sleep medicine protocols is restructuring how cervical support products demonstrate efficacy, shifting competitive advantage from marketing claims toward measurable biomechanical outcomes.
Phase-change material integration is electrifying thermal comfort engineering in orthopedic sleep products. Microencapsulated paraffin waxes absorb and release body heat through solid-liquid transitions, maintaining surface temperatures within the 28-32°C range preferred by thermoregulatory research. Sleep clinics and physiotherapy practices are specifying these formulations for patients with night sweats or menopausal temperature dysregulation. This temperature precision is compressing commodity foam margins by establishing performance-based procurement criteria that generic viscoelastic cannot satisfy.
California's TB 117-2013 smolder-resistant standard is propagating beyond state borders as de facto national compliance. The regulation eliminates open-flame testing in favor of cigarette ignition resistance, forcing foam suppliers to reformulate with phosphorus-based or intumescent additives rather than legacy brominated retardants. Manufacturers targeting the U.S. market are consolidating production lines to this single standard, accepting margin compression to avoid dual-SKU complexity. The transition most affects budget-tier imports previously optimized for export-only flame retardant packages.
Practitioner prescription channels are capturing volume previously routed through retail. Chiropractors and physical therapists now retail private-label orthopedic pillows directly to patients, embedding product recommendations within treatment protocols. This clinical channel displaces Amazon and big-box discovery for consumers with diagnosed cervical conditions. The shift is most visible in United States metropolitan markets where integrated sleep medicine practices have consolidated diagnostic and retail functions under single ownership.
Orthopedic Pillow Market Segmentation
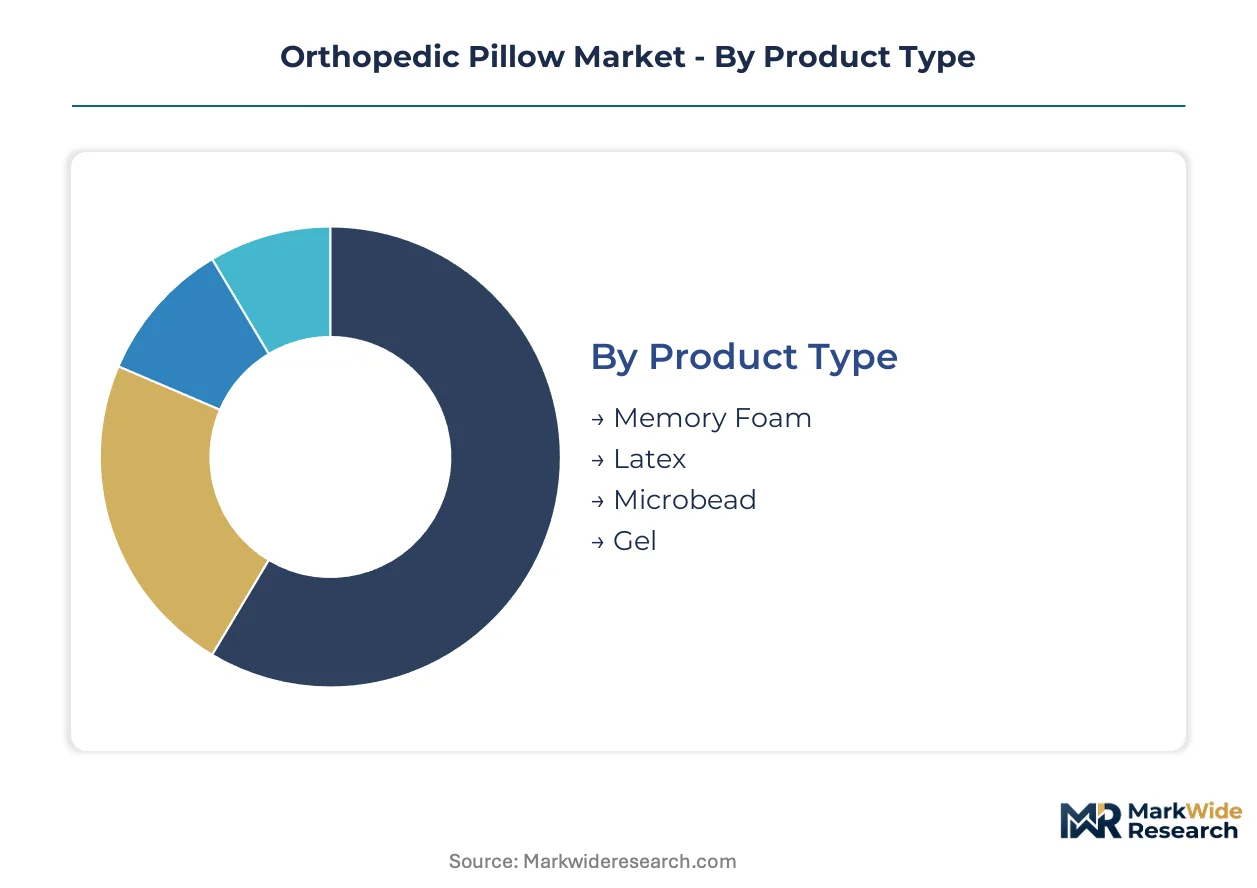
Orthopedic pillow segmentation reveals how material chemistry, clinical endorsement, and channel access partition margin pools. Manufacturers align R&D investments and certification strategies to the specific performance thresholds each segment demands.
Product Type:
Supply concentration in viscoelastic chemistry creates divergent margin profiles across formulation technologies.
- Memory Foam:Viscoelastic polyurethane formulations dominate manufacturing scale due to established molding infrastructure and consumer familiarity with contouring response. Demand concentrates in United States home care channels where CertiPUR-US certification filters non-compliant imports and sustains premium positioning for validated domestic suppliers.
- Gel:Phase-change and gel-infused composites address thermal regulation complaints that plague traditional viscoelastic, capturing dissatisfied users through measurable cooling performance. Physiotherapy clinics in Germany and Japan specify these formulations for patients with night sweats or temperature dysregulation, embedding procurement within treatment protocols.
- Latex:Natural rubber derivatives appeal to chemical-averse consumers seeking biodegradable alternatives to petroleum-based polyols.
- Microbead:Polystyrene bead fillings occupy travel and temporary-use applications where compressibility outweighs durability requirements.
Today's leader: Memory Foam. Tomorrow's challenger: Gel.
End User:
Volume distribution inverts when measured against margin concentration, with institutional channels capturing disproportionate value per unit.
- Home Care:Aging populations in the United States and Japan drive non-invasive cervical support adoption as pharmaceutical alternatives face reimbursement pressure. Direct-to-consumer channels and sleep wellness clinics embed product recommendations within broader wellness protocols, bypassing traditional retail margin stacking.
- Physiotherapy Clinics:Practitioner-endorsed positioning commands premium pricing through diagnostic integration and repeat institutional procurement. Chiropractors in United States metropolitan markets retail private-label products directly, displacing Amazon discovery for diagnosed cervical conditions.
- Hospitals:Post-surgical and inpatient recovery applications demand flame-retardant certifications and disposable covers for infection control.
- Chiropractors:Spinal manipulation practices specify anatomical contours aligned with adjustment protocols, creating stickier patient relationships than retail transactions.
Home Care captures volume leadership. Physiotherapy Clinics concentrate margin pools fastest.
Size:
SKU proliferation in dimensional variants strains inventory management while enabling price discrimination across use cases.
- Standard:Conventional dimensions align with North American bedding specifications and mass-market retail shelf standards. United States big-box chains drive procurement consolidation, forcing suppliers to absorb working capital intensity from seasonal demand forecasting mismatches.
- Travel:Compressible and inflatable architectures address portability requirements for business travelers and clinical house calls. Japanese railway operators and airline amenity programs specify compact cervical support for premium cabin service, creating institutional volume anchors.
- Large:Expanded dimensions accommodate broader shoulder frames and side-sleeping positions prevalent among athletic and bariatric populations.
- Custom:3D scanning and CNC contouring enable patient-specific cervical mapping for post-surgical recovery and congenital deformities.
Standard sizing commands shelf presence. Travel formats are expanding most quickly through transportation partnerships.
Distribution Channel:
Channel fragmentation reflects divergent consumer journeys between diagnosed conditions and wellness-oriented discovery.
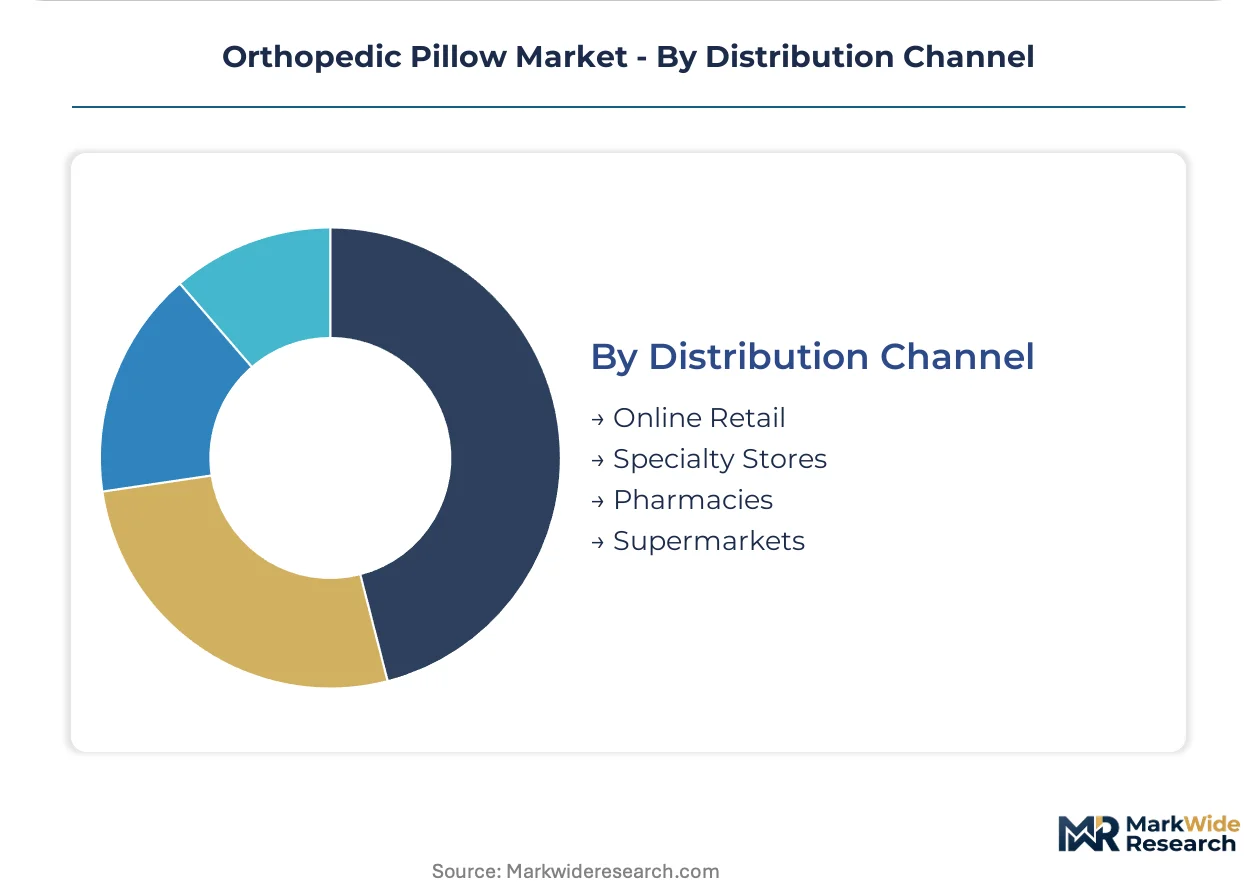
- Online Retail:Amazon and direct-to-consumer platforms enable specification comparison and review aggregation that commodity foam cannot satisfy. Coop Home Goods and similar mid-market operators exercise channel control through shredded foam architectures with user-customizable loft.
- Specialty Stores:Sleep Number Corporation and integrated mattress retailers anchor orthopedic pillow lines within ecosystem plays, competing on adjustable technology rather than material alone. United States mall-based sleep shops provide tactile evaluation that pure e-commerce lacks.
- Pharmacies:CVS and Walgreens stock entry-level contours for impulse purchase alongside pain management categories, accepting lower margins for traffic generation.
- Supermarkets:Mass merchandisers like Walmart and Target allocate shelf space to private-label alternatives, compressing brand premium through volume procurement.
Online Retail leads transaction volume. Specialty Stores defend margin through ecosystem lock-in.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong province anchors polyurethane foam supply for orthopedic pillow manufacturing, with Zhejiang and Guangdong provinces supporting downstream fabrication and export logistics. Demand concentrates in aging economies seeking non-invasive cervical support alternatives to pharmaceutical pain management.
United States
FDA Class I medical device classification shapes labeling claims and premium positioning for therapeutic efficacy. The EPA's CertiPUR-US voluntary certification filters non-compliant imports from domestic retail channels. Sleep wellness clinics in California and New York metropolitan areas embed product recommendations within integrated diagnostic and retail operations.
Germany
ECHA REACH chemical restrictions force polyurethane reformulation investments for European market access. Physiotherapy clinics in Bavaria and North Rhine-Westphalia specify gel-infused composites for patients with temperature dysregulation conditions. Stuttgart-based foam suppliers accelerate plant-based polyol substitution to capture first-mover certification advantages.
Japan
METI standards govern product safety claims for cervical support devices distributed through medical and retail channels. Railway operators and airline amenity programs in Tokyo and Osaka metropolitan areas drive institutional procurement of compact travel-format orthopedic pillows. Kansai region manufacturers specialize in latex alternatives to petroleum-based foam formulations.
China
MIIT industrial standards coordinate quality benchmarks for polyurethane foam production across domestic and export markets. Shandong province chemical clusters supply viscoelastic raw materials to pillow fabricators in Zhejiang and Guangdong export processing zones. Shenzhen and Guangzhou logistics hubs consolidate containerized shipments for North American and European distribution.
United Kingdom
UKCA marking requirements replace CE conformity assessment for orthopedic products entering Great Britain post-Brexit. London and Southeast England sleep medicine practices retail private-label cervical support products directly to diagnosed patients. Midlands manufacturing centers reformulate foam additives to satisfy simultaneous EU REACH and domestic flammability compliance.
Orthopedic Pillow Market Competitive Landscape
Global majors compete with regional champions across material chemistry and channel access dimensions. The vendor base separates into integrated sleep ecosystem operators, specialized ergonomic fabricators, and private-label contract manufacturers serving clinical procurement channels. Three archetypes dominate: proprietary viscoelastic formulators, adjustable-technology platform builders, and shredded-foam customization specialists. Consolidation pressure operates through M&A targeting CertiPUR-US certified foam suppliers and strategic partnerships between pillow brands and telehealth platforms.
Within the proprietary chemistry tier, Tempur-Pedic International anchors premium positioning through viscoelastic material science differentiation. Sleep Number Corporation exemplifies ecosystem-integrated competition, embedding orthopedic pillows within adjustable sleep technology platforms. Coop Home Goods occupies the user-customization vector, representing shredded-foam architectures that enable consumer-modified cervical support configurations.
| Leading Market Players |
|---|
| Tempur-Pedic International, Inc. |
| Sleep Number Corporation |
| Mediflow Inc. |
| PharMeDoc |
| Coop Home Goods |
| Malouf |
| Core Products International, Inc. |
| Contour Products, Inc. |
| Relax The Back |
| Others |
Pricing and Supply Chain Analysis
Physiotherapy clinic procurement concentrates margin pools through practitioner-endorsed positioning, embedding orthopedic pillows within treatment protocols that command premium pricing over retail channels. This clinical buyer concentration sustains value-based pricing for certified formulations while compressing commodity foam margins in direct-to-consumer tiers.
Pricing Analysis
Petroleum polyol cost pass-through dominates viscoelastic foam pricing, transmitting crude oil volatility directly to manufacturer input structures. Three-tier pricing structure across premium, standard, and economy levels separates CertiPUR-US certified domestic suppliers from uncertified imports and private-label alternatives. Cost compression in the mid-market tier is intensifying because Shandong chemical clusters face simultaneous REACH reformulation and TB 117-2013 compliance investments. Home care consumers exhibit highest price sensitivity, while physiotherapy clinics demonstrate inelastic demand for diagnostic-integrated products.
Supply Chain Analysis
Regional distribution centers in Shenzhen and Guangzhou consolidate containerized shipments for North American and European markets, creating hub-and-spoke patterns that buffer against single-geography disruption. Viscoelastic polyurethane production draws from Shandong province chemical clusters, with Zhejiang and Guangdong fabricators handling downstream pillow assembly. Supply chain risk centers on Chinese foam concentration exposing buyers to freight cost spikes and regulatory restriction cascades. Distribution runs through integrated sleep ecosystem operators and Amazon-controlled direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The orthopedic pillow market reads as a late-cycle quality story where aging populations shift demand toward premium specifications with measurable biomechanical outcomes. This specification upgrade favors certified suppliers with clinical channel access over commodity foam competitors.
For Market Incumbents: Anticipate plant-based polyol substitution acceleration by securing captive supply agreements with European REACH-compliant chemical suppliers. Defensive consolidation should target CertiPUR-US certified foam fabricators to filter emerging competitors from premium positioning. Channel control investments in sleep wellness clinic partnerships create certification moats that marginal entrants cannot replicate. For New Entrants and Emerging Players: Begin with shredded foam customization architectures that address anatomical diversity gaps in one-piece contour designs. The most penetrable white space sits in travel-format orthopedic pillows for Japanese railway and airline amenity programs, where institutional procurement lacks established supplier relationships. A practitioner-endorsed go-to-market angle through chiropractic private-label partnerships bypasses Amazon margin compression. For Investors and Strategic Acquirers: Sleep technology ecosystem operators are the most active acquirer in this space, seeking pillow brands that anchor adjustable firmness platforms. Long-term viability favors suppliers with simultaneous FDA device registration and state-level fire safety approvals that strain smaller R&D teams. The signal to watch is telehealth platform partnerships that embed product recommendations within remote diagnostic protocols.| Strategic Initiative | Industry Significance |
|---|---|
| CertiPUR-US Certification Investment | EPA-aligned emissions validation filters non-compliant imports from domestic retail channels. |
| Plant-Based Polyol Transition | REACH chemical restrictions in Europe force reformulation investments for market access. |
| Direct-to-Consumer Channel Expansion | Sleep wellness clinics and telehealth platforms bypass traditional retail margin stacking. |
| Adjustable Loft Customization | Shredded foam architectures address anatomical diversity that fixed contours fail to capture. |
| Clinical Channel Partnership | Chiropractor and physiotherapist retail displaces Amazon discovery for diagnosed conditions. |
Research Methodology
Coverage spans the United States, Germany, Japan, China, and the United Kingdom, with primary inputs from each market's stakeholder ecosystem. The analysis combines structured interviews with foam chemists, orthopedic device procurement managers, sleep clinic operators, and CertiPUR-US certification auditors with secondary validation from FDA 510(k) filings, ECHA REACH substance databases, MIIT industrial standards, and EPA emissions disclosure records. Bottom-up demand modeling triangulates against top-down chemical production capacity assessments.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. The analytical framework models segmentation dimensions including material chemistry tier, end-user channel, distribution format, and regional regulatory cluster. CAGRs derive from fitted trend analysis applied to historical shipment data and forward-looking procurement survey responses. Industry-specific forecast inputs incorporate petroleum polyol price trajectory assumptions and aging demographic penetration curves.
Several conditions sit outside the modeled scope, including sudden tariff regime shifts on Chinese foam imports, breakthrough biomaterial substitutions, and pandemic-scale supply chain disruptions. Forecasts reflect documented assumptions around regulatory stability and crude oil price bands. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedics
Knee Hyaluronic Acid Injections Market
Orthopedics
Costochondritis Market
Orthopedics
Kyphosis Market
Orthopedics
United States Orthopedic Braces and Support Market
Orthopedics
Europe Extremity Reconstruction Market
Orthopedics
Global Osteoarthritis Therapeutics Market
Orthopedics
Septic Arthritis Market
Orthopedics
Elbow Stiffness Market
Orthopedics
Osteopenia Treatment Market
Orthopedics
Cruciate Ligament Repair Procedures Market
Orthopedics
Skeletal Deformation Correction Market
Orthopedics
Podiatry Services Market
Orthopedics
Athletic Knee Treatment Market
Orthopedics
Spinal Stenosis Market
Orthopedics
Hips and Knees Reconstructive Market
Orthopedics
ACL Reconstruction Market