
 Global Orthopedic Bone Cement Market | 2026-2036
Global Orthopedic Bone Cement Market Size, Share, and Industry Trends Forecast 2026-2036
Global Orthopedic Bone Cement Market Foresight
Pre-mixed antibiotic bone cement kits is hardening as the default procurement format, bundling PMMA powder, liquid monomer, and gentamicin into single sterile packages. Stryker leverages its trauma and extremities portfolio to control hospital formulary access across North American accounts. Zimmer Biomet anchors its position through proprietary mixing systems that lock clinicians into recurring cement cartridge purchases. Heraeus Medical GmbH specializes in high-viscosity cements for hip arthroplasty, competing on European surgeon training density.
Orthopedic bone cement comprises polymethyl methacrylate-based formulations, typically combining liquid methyl methacrylate monomer with powdered PMMA copolymer and radiopaque additives like barium sulfate or zirconium dioxide, cured via exothermic free-radical polymerization to achieve interdigitation with cancellous bone. The material functions primarily as a grout for prosthetic fixation and localized antibiotic delivery in total joint arthroplasty. PMMA formulations occupy the dominant volume position due to decades of clinical validation and established reimbursement codes, while calcium phosphate cements capture faster growth in spinal fusion applications where resorbability reduces revision burden. Joint replacement applications concentrate the largest revenue pool, though trauma repair segments show expanding use in geriatric fracture management where polymetric fixation demands biocompatible void fillers.
FDA 510(k) clearance pathways and EU MDR conformity assessments shape product development cycles, with both regulators demanding enhanced biocompatibility documentation and post-market surveillance for permanent implant materials. ISO 5833 standards for acrylic resin cements establish baseline mechanical performance thresholds that manufacturers must meet for market access across multiple jurisdictions. Stakeholders should monitor evolving FDA guidance on antibiotic-loaded cement classifications, as reclassification could shift regulatory burden and timeline assumptions for new entrants.
Market Dynamics
Antibiotic-loaded PMMA formulations are displacing plain cement in joint replacement protocols, as hospital infection control committees mandate prophylactic gentamicin delivery in revision arthroplasty cases. This shift compresses margins for commodity cement suppliers while rewarding integrated kit providers.
Growth Catalysts
- EU MDR compliance deadlines:European orthopedic centers are accelerating cement procurement to lock in approved suppliers before 2027 renewal cycles tighten biocompatibility documentation requirements.
- Geriatric fracture volume:Trauma applications for polymetric fixation in hip and distal radius fractures are expanding as aging populations in Germany, Japan, and Italy drive operative intervention rates.
- Ambulatory surgical center expansion:United States outpatient joint replacement programs are standardizing pre-mixed antibiotic cement kits to reduce pharmacy compounding errors and operative turnaround times.
Market Restraints
- Methyl methacrylate monomer price volatility:Petrochemical feedstock fluctuations directly compress formulation margins, particularly for European manufacturers exposed to naphtha cracking economics.
- High-viscosity cement supply concentration:German and Swiss specialty chemical producers control critical PMMA copolymer grades, creating single-source risk for hip arthroplasty formulations.
- Calcium phosphate substitution in spinal fusion:Resorbable cements are capturing lumbar interbody fusion cases where PMMA's permanent presence complicates revision surgery.
Strategic Opportunities
- China's tier-2 city hospital expansion:Provincial medical centers in Chengdu, Wuhan, and Xi'an are building joint replacement capacity faster than domestic cement supply can match.
- FDA antibiotic-loaded cement guidance evolution:Potential reclassification of high-dose gentamicin formulations as combination products could create first-mover advantages for sponsors with pre-submission meetings.
- Robot-assisted arthroplasty integration:Cement application systems that interface with surgical navigation platforms are converging with orthopedic robotics workflows in United States academic medical centers.
Industry Challenges
- Polymerization kinetics expertise scarcity:Formulation chemists capable of tuning working time and doughing time for specific surgical climates command premium compensation in tight labor markets.
- ISO 5833 mechanical testing backlog:Certification delays at notified bodies extend product launch timelines by 8-14 months for novel radiopaque additive formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Orthopedic Bone Cement Market |
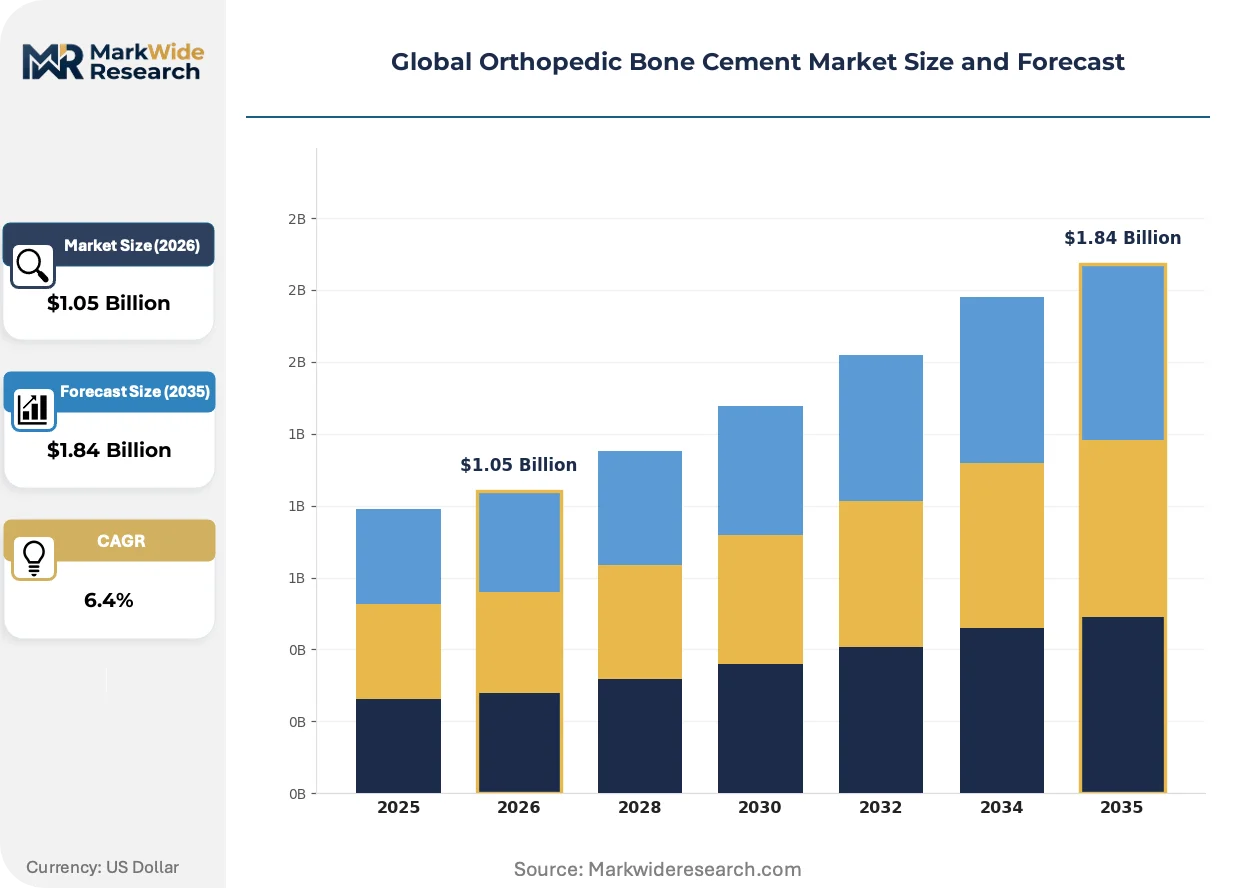
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.84 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PMMA, Calcium Phosphate, Biodegradable, Synthetic Application: Joint Replacement, Trauma Repair, Spinal Surgery, Bone Resurfacing End User: Hospitals, Orthopedic Clinics, Rehabilitation Centers, Academic Institutions Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | Stryker, Zimmer Biomet, DePuy Synthes, Smith & Nephew, Heraeus Medical GmbH, DJO Global Inc. (Enovis), Cardinal Health, Arthrex Inc., Tecres S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Orthopedic Bone Cement Market Shifts & Advancements
Digital surgical planning and patient-specific instrumentation are reshaping how bone cement is selected, mixed, and delivered in the operating theater. Three interconnected developments are compressing traditional procurement and application workflows.
Smart mixing systems with integrated barcode verification and wireless inventory tracking are converging with hospital enterprise resource planning platforms. Orthopedic service lines in United States health systems are deploying these connected devices to eliminate lot number transcription errors and automate consignment replenishment. The resulting data exhaust enables predictive consumption modeling that compresses distributor safety stock requirements.
EU MDR Article 10 post-market surveillance obligations are forcing manufacturers to rebuild clinical follow-up infrastructure for legacy cement formulations. German and French notified bodies are rejecting technical documentation that lacks systematic retrieval data on implant-cement constructs. Small and mid-sized suppliers are responding by outsourcing vigilance reporting to specialized contract research organizations rather than building in-house pharmacovigilance teams.
Surgeon preference for single-use, pre-sterilized cement delivery systems is displacing reusable mixing bowls and vacuum pumps in ambulatory settings. United States multi-specialty surgery centers are negotiating all-inclusive per-case pricing that bundles cement, antibiotics, and application hardware. This consumption pattern is most visible in Florida and Texas markets where certificate-of-need restrictions have accelerated outpatient joint replacement migration from hospital campuses.
Global Orthopedic Bone Cement Market Segmentation
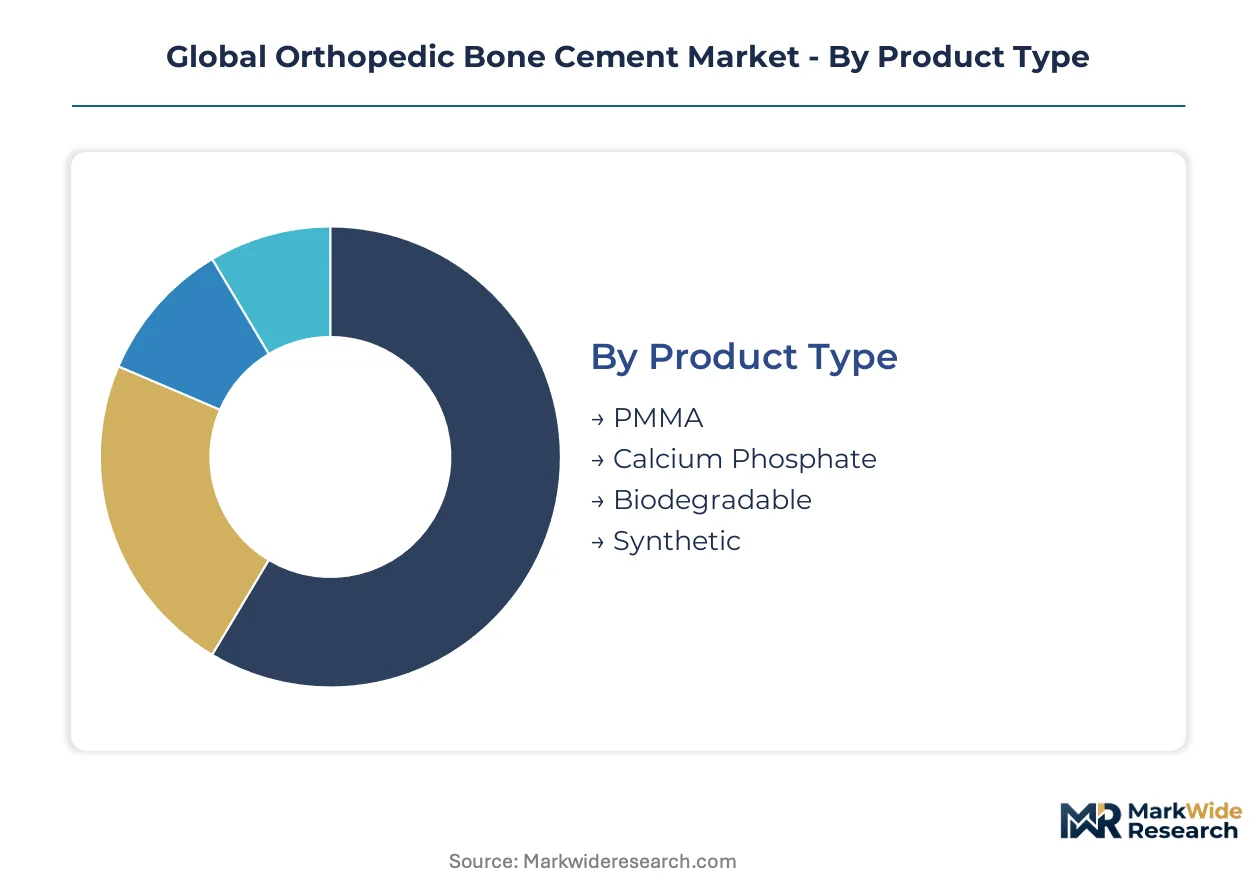
Orthopedic bone cement segmentation reveals how formulation chemistry, surgical application, and procurement channel each create distinct margin structures and competitive dynamics. Understanding these axes clarifies where integrated suppliers command premium positioning versus where commodity competition prevails.
Product Type:
PMMA formulations dominate through mechanical reliability and regulatory familiarity, while alternative chemistries exploit specific clinical limitations of acrylic cements.
- PMMA:Polymethyl methacrylate combines liquid methyl methacrylate monomer with powdered copolymer and barium sulfate radiopacifiers, curing via exothermic polymerization. Demand concentrates in United States hospital joint replacement programs where FDA 510(k) clearance pathways and established CPT reimbursement codes sustain procurement continuity. German hip arthroplasty centers favor high-viscosity PMMA grades for press-fit femoral component fixation.
- Calcium Phosphate:Resorbable hydroxyapatite and tricalcium phosphate formulations eliminate permanent foreign body burden in spinal fusion applications. Surgeon preference is accelerating in Japan and South Korea where lumbar interbody fusion volumes exceed revision-tolerant PMMA indications. Osteoconductive properties support faster bony integration compared to acrylic alternatives.
- Biodegradable:Poly(lactic-co-glycolic acid) and polycaprolactone matrices target pediatric deformity correction and temporary fixation where skeletal growth demands material resorption.
- Synthetic:Engineered bioactive glasses and calcium sulfate preparations serve trauma void-filling applications requiring rapid resorption kinetics and minimal inflammatory response.
Mature deployment sits with PMMA. Newer deployment is concentrated in Calcium Phosphate.
Application:
Surgical indication determines cement specification requirements, with load-bearing applications demanding compressive strength thresholds that resorbable formulations cannot satisfy.
- Joint Replacement:Total hip and knee arthroplasty consumes antibiotic-loaded PMMA for prosthetic fixation and infection prophylaxis. United States ambulatory surgical centers are standardizing pre-mixed gentamicin kits to reduce operative pharmacy errors. German university hospitals specify high-viscosity formulations for cemented femoral stem pressurization.
- Spinal Surgery:Vertebroplasty, kyphoplasty, and interbody fusion applications favor injectable cements with controlled viscosity profiles. Calcium phosphate cements are gaining lumbar fusion share in China where revision surgery access constraints make permanent PMMA presence clinically problematic.
- Trauma Repair:Geriatric hip fracture fixation employs cement augmentation for screw purchase in osteoporotic bone, particularly in Italy and Japan where aging demographics expand operative intervention rates.
- Bone Resurfacing:Focal cartilage defects and subchondral bone restoration utilize specialized cements with tunable setting times for arthroscopic delivery.
Volume concentration remains in Joint Replacement. Steepest expansion trajectory appears in Spinal Surgery.
End User:
Procurement sophistication varies sharply across care settings, with integrated delivery networks extracting price concessions unavailable to independent practices.
- Hospitals:Academic medical centers and community hospitals command formulary control through GPO contracts and vendor consolidation. United States health systems leverage Stryker and Zimmer Biomet portfolio breadth for enterprise-wide pricing agreements.
- Orthopedic Clinics:Specialized ambulatory surgery centers negotiate all-inclusive per-case cement bundles covering material, antibiotics, and delivery hardware. Texas and Florida multi-specialty centers pioneered this procurement model.
- Rehabilitation Centers:Post-acute settings utilize cement primarily for fracture brace customization and orthotic fabrication rather than surgical applications.
- Academic Institutions:Research hospitals drive adoption of experimental formulations through investigator-initiated studies and compassionate use protocols.
Contract leverage concentrates with Hospitals. Procurement innovation originates in Orthopedic Clinics.
Distribution Channel:
Channel selection reflects cement shelf-life constraints and sterile handling requirements that complicate inventory positioning.
- Direct Sales:Manufacturers deploy field representatives for high-volume hospital accounts requiring consignment inventory and operating room technical support. Stryker and Heraeus Medical GmbH maintain direct presence in German and United States metropolitan surgical clusters.
- Distributors:Regional medical-surgical distributors serve mid-tier hospitals and orthopedic clinics with aggregated product portfolios and local logistics capabilities.
- Online Retail:E-procurement platforms facilitate standard cement kit ordering for small practices and international buyers outside major distributor territories.
- Wholesalers:Pharmaceutical and device wholesalers handle bulk cement procurement for government tenders and centralized purchasing organizations in China and India.
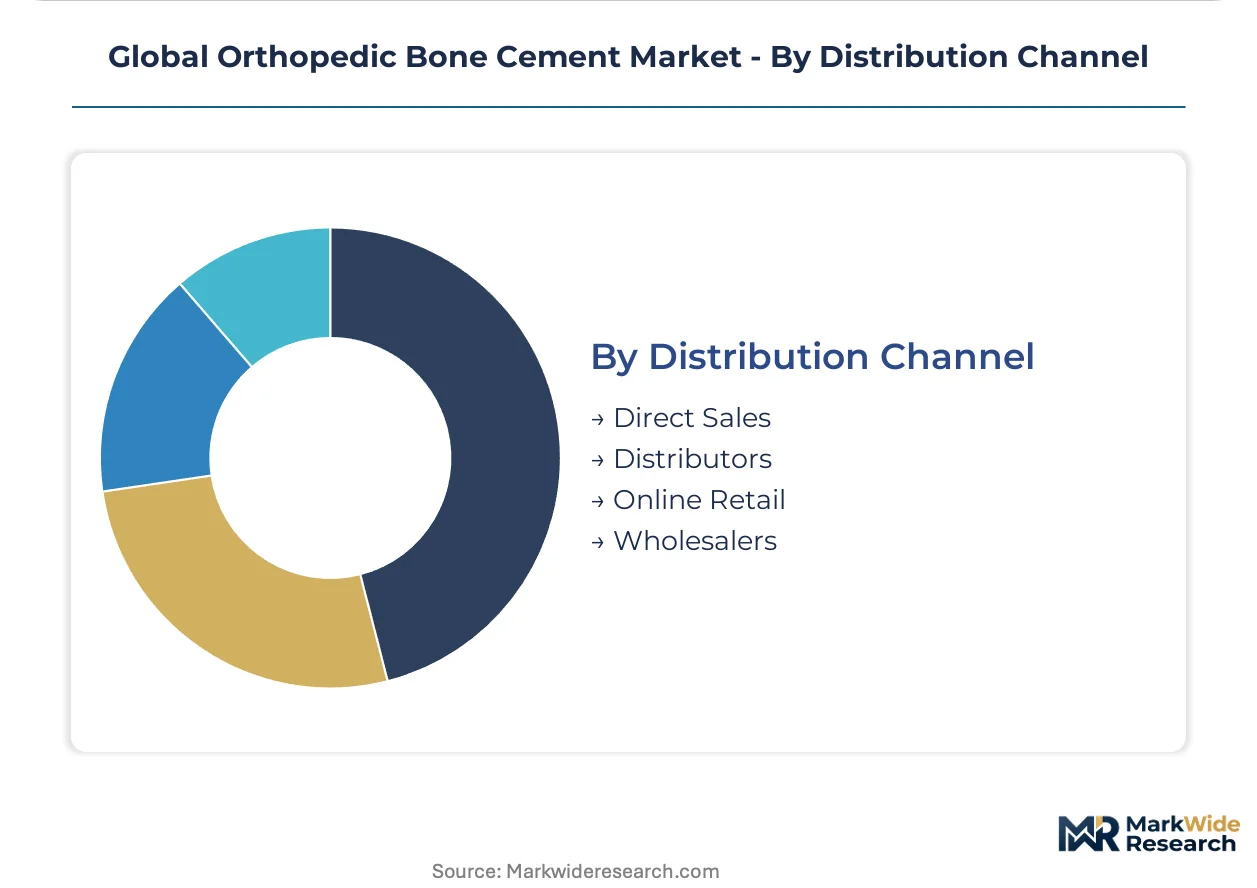
Relationship intensity peaks with Direct Sales. Geographic reach extends through Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany manufactures high-viscosity PMMA formulations for export while the United States and China absorb the majority of global consumption through expanding joint replacement volumes. Production clusters concentrate in German chemical corridors and Swiss specialty polymer facilities. Demand fragmentation across regulatory jurisdictions creates divergent procurement specifications.
United States
Ambulatory surgical centers in Florida and Texas are standardizing pre-mixed antibiotic cement kits to streamline outpatient joint replacement workflows. FDA 510(k) clearance pathways and established CPT reimbursement codes sustain procurement continuity for PMMA formulations. Academic medical centers in Boston and New York Metro negotiate enterprise-wide pricing through GPO contracts with integrated device suppliers.
Germany
University hospitals in Bavaria and North Rhine-Westphalia specify high-viscosity PMMA grades for cemented femoral stem pressurization in hip arthroplasty. EU MDR Article 10 post-market surveillance obligations are forcing manufacturers to rebuild clinical follow-up infrastructure for legacy cement formulations. The Rhine-Main chemical corridor hosts specialty PMMA copolymer production that feeds European hip arthroplasty supply chains.
China
Provincial medical centers in Chengdu, Wuhan, and Xi'an are building joint replacement capacity faster than domestic cement supply can match. NMPA regulatory pathways for imported orthopedic materials create documentation bottlenecks for foreign manufacturers. Government hospital procurement tenders in tier-2 cities favor bundled cement-antibiotic kits to reduce pharmacy compounding errors.
Japan
Surgeon preference for resorbable calcium phosphate cements is accelerating in lumbar interbody fusion applications where permanent PMMA presence complicates revision surgery. PMDA marketing authorization requirements for combination products extend review timelines for antibiotic-loaded formulations. Tokyo and Osaka academic hospitals drive adoption of experimental formulations through investigator-initiated studies.
Italy
Geriatric hip fracture fixation employs cement augmentation for screw purchase in osteoporotic bone as aging demographics expand operative intervention rates. Regional health authorities in Lombardy and Emilia-Romagna negotiate centralized purchasing agreements for trauma cement supplies. The country's national pharmaceutical regulator enforces biocompatibility documentation standards aligned with EU MDR conformity assessments.
Global Orthopedic Bone Cement Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation chemistry and delivery system integration. The vendor base stratifies into three tiers: multinational orthopedic device conglomerates with portfolio breadth, regional chemical specialists with polymerization expertise, and emerging kit assemblers targeting price-sensitive procurement channels. Consolidation pressure intensifies as hospital systems demand single-source accountability for implant-cement constructs. Dominant competitive moves include backward integration into PMMA copolymer production and strategic partnerships with surgical navigation platform developers.
Among diversified orthopedic conglomerates, Stryker and Zimmer Biomet anchor the premium tier through integrated trauma and joint replacement portfolios that control hospital formulary access. Heraeus Medical GmbH represents the European specialist archetype, occupying a position defined by high-viscosity formulation expertise and surgeon training density in German-speaking markets. These three entities exemplify how competitive positioning depends on either portfolio breadth or technical specialization in polymerization kinetics.
| Leading Market Players |
|---|
| Stryker |
| Zimmer Biomet |
| DePuy Synthes |
| Smith & Nephew |
| Heraeus Medical GmbH |
| DJO Global Inc. (Enovis) |
| Cardinal Health |
| Arthrex Inc. |
| Tecres S.p.A. |
| Others |
Supply & Pricing Matrix
High-viscosity PMMA certification tiers bifurcate procurement economics, with ISO 5833-validated formulations commanding premium positioning through German chemical corridor supply security while commodity antibiotic-loaded kits compete on consignment pricing in United States ambulatory surgical centers. This tier divergence concentrates margin capture among integrated device conglomerates that control captive copolymer supply, whereas independent kit assemblers absorb methyl methacrylate monomer volatility through spot market exposure.
Pricing Analysis
Margin tightening in standard-grade antibiotic cement reflects petrochemical feedstock volatility and GPO contract compression across United States hospital systems. Three-tier pricing structure across premium, standard, and economy levels differentiates by viscosity grade and radiopacifier specification, with high-viscosity hip arthroplasty formulations least sensitive to price pressure and trauma void-fillers most exposed to commoditization.
Supply Chain Analysis
Expired cement kit returns and vacuum pump refurbishment flows create reverse-logistics complexity for consignment inventory programs in German and United States metropolitan surgical clusters. Manufacturing concentrates in Germany, Switzerland, and the United States, drawing from naphtha-derived methyl methacrylate monomer, barium sulfate radiopacifiers, and gentamicin sulfate antibiotic APIs. Single-source vulnerability in high-viscosity PMMA copolymer grades amplifies disruption risk. Distribution runs through manufacturer field representatives for high-volume accounts and regional medical-surgical distributors for mid-tier hospitals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in orthopedic bone cement increasingly depends on backward integration into PMMA copolymer production and captive control over high-viscosity formulation chemistry. Players that secure Rhine-Main corridor supply relationships or in-house polymerization capabilities gain structural advantage in margin defense.
For Market Incumbents: Extend formulary lock-in through proprietary mixing system ecosystems that cement recurring cartridge purchase obligations, while accelerating EU MDR technical documentation renewal to preempt 2027 supplier consolidation windows. Calcium phosphate substitution in spinal fusion and gentamicin reclassification risk demand defensive patent portfolio investment in resorbable cement adjacencies. For New Entrants and Emerging Players: Launch via online retail and provincial distributor partnerships into China's tier-2 city hospital expansion, where NMPA documentation bottlenecks for foreign incumbents create temporary procurement gaps. Robot-assisted arthroplasty integration and pre-mixed antibiotic kit assembly for ambulatory surgical centers represent the most penetrable white-space, with lowest competitive density in Texas and Florida multi-specialty centers. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap European formulation specialists given EU MDR compliance-driven supplier consolidation and scarcity value in polymerization kinetics expertise. Five-to-ten year viability favors targets with established notified body relationships and systematic retrieval data infrastructure for post-market surveillance obligations. Watch FDA guidance evolution on high-dose gentamicin combination product classification as the critical inflection signal for regulatory burden reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PMMA Copolymer Production | Captive supply of high-viscosity grades insulates German manufacturers from naphtha cracking volatility. |
| EU MDR Technical Documentation Renewal | Systematic retrieval data infrastructure preserves market access against notified body rejection risk. |
| Robot-Assisted Arthroplasty System Partnership | Cement delivery hardware integration with surgical navigation platforms locks United States academic medical center procurement. |
| Pre-Mixed Antibiotic Kit Assembly Scale-Up | Standardized gentamicin bundling reduces pharmacy compounding errors for ambulatory surgical center expansion. |
| China Tier-2 City Distributor Network Buildout | Provincial medical center procurement tenders in Chengdu and Wuhan outpace domestic cement supply growth. |
Research Methodology
Independent corroboration across hospital purchasing committee interviews, biomedical engineer consultations, and GPO contracts manager discussions underwrites the qualitative findings, validated against FDA 510(k) clearance databases, EU MDR notified body technical documentation, and hospital procurement expenditure records. Bottom-up cement consumption modeling triangulates with top-down joint replacement procedure volume estimates.
Comparable-period anchoring to historical joint replacement migration patterns from inpatient to ambulatory settings structured the forecast window across the analysis window. Segmentation dimensions modeled include formulation chemistry, surgical application, end-user procurement sophistication, and regional regulatory cluster. CAGRs derive from procedure volume elasticity and kit penetration assumptions, with methyl methacrylate monomer price indices and EU MDR compliance timelines as orthopedic-specific forecast inputs.
Regulatory reclassification, petrochemical feedstock disruption, and ambulatory surgical center reimbursement policy shifts are the dominant revision risks to consumption assumptions. Forecasts embed documented assumptions on antibiotic-loaded cement classification stability and polymerization kinetics labor market tightness. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Wrist Replacement Orthopedic Devices Market
Orthopedic Devices
US Orthopedic Implants Market
Orthopedic Devices
Femoral Head Prostheses Market
Orthopedic Devices
Europe Kyphoplasty Market
Orthopedic Devices
Patient Lifts Market
Orthopedic Devices
Orthopedic Pedicle Screw Market
Orthopedic Devices
Cementless Total Knee Arthroplasty (TKA) Market
Orthopedic Devices
Saudi Arabia Spinal Surgery Devices Market
Orthopedic Devices
Chondroplasty Market
Orthopedic Devices
Orthobiologics Market
Orthopedic Devices
Europe Orthopedic Braces and Support Market
Orthopedic Devices
Orthopedic Bone Cement and Casting Materials Market
Orthopedic Devices
China Spinal Surgery Devices Market
Orthopedic Devices
USA Spinal Surgery Devices Market
Orthopedic Devices
Global Shoulder Replacement Market
Orthopedic Devices
Orthopedic Joint Reconstruction Market