
 Limb Salvage Systems Market | 2026-2036
Limb Salvage Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Limb Salvage Systems Market Outlook
Germany is narrowing its orthopedic manufacturing capacity gap through targeted investments in precision implant fabrication. Stryker Corporation leverages its integrated surgical technologies portfolio to dominate navigation-assisted limb reconstruction procedures. Zimmer Biomet Holdings, Inc. anchors its European position through specialized oncologic prosthesis development. Onkos Surgical, Inc. differentiates via patient-specific instrumentation for musculoskeletal tumor surgery.
Limb salvage systems encompass implantable and external devices designed to preserve functional extremities following trauma, oncologic resection, or infectious destruction, typically incorporating cobalt-chrome alloys, titanium porous structures, or antibiotic-loaded cement spacers with load-bearing thresholds exceeding 300 MPa. These systems serve primarily to avoid amputation while restoring biomechanical integrity and ambulatory capacity in compromised limbs. Implants command the largest revenue share within product categories due to recurring revision cycles and premium pricing for modular tumor endoprostheses. 3D printing represents the fastest-expanding technology segment as additive manufacturing enables anatomically matched porous scaffolds that osseointegrate more predictably than conventional forged components. Cancer treatment applications generate substantial procedure volumes in tertiary referral centers, though diabetic ulcers are gaining share as limb preservation protocols expand to vascular surgery departments.
The FDA enforces rigorous premarket approval pathways for permanent implantable limb salvage devices through its Center for Devices and Radiological Health, while the EU Medical Device Regulation mandates notified body conformity assessments and post-market clinical follow-up for Class III implantables. ISO 5832 standards govern metallic material biocompatibility and mechanical fatigue resistance, directly influencing supplier qualification and procurement specifications. Stakeholders must monitor evolving reimbursement thresholds for complex limb reconstruction across Medicare, commercial payers, and European DRG systems to align portfolio investments with viable care delivery economics.
Market Dynamics
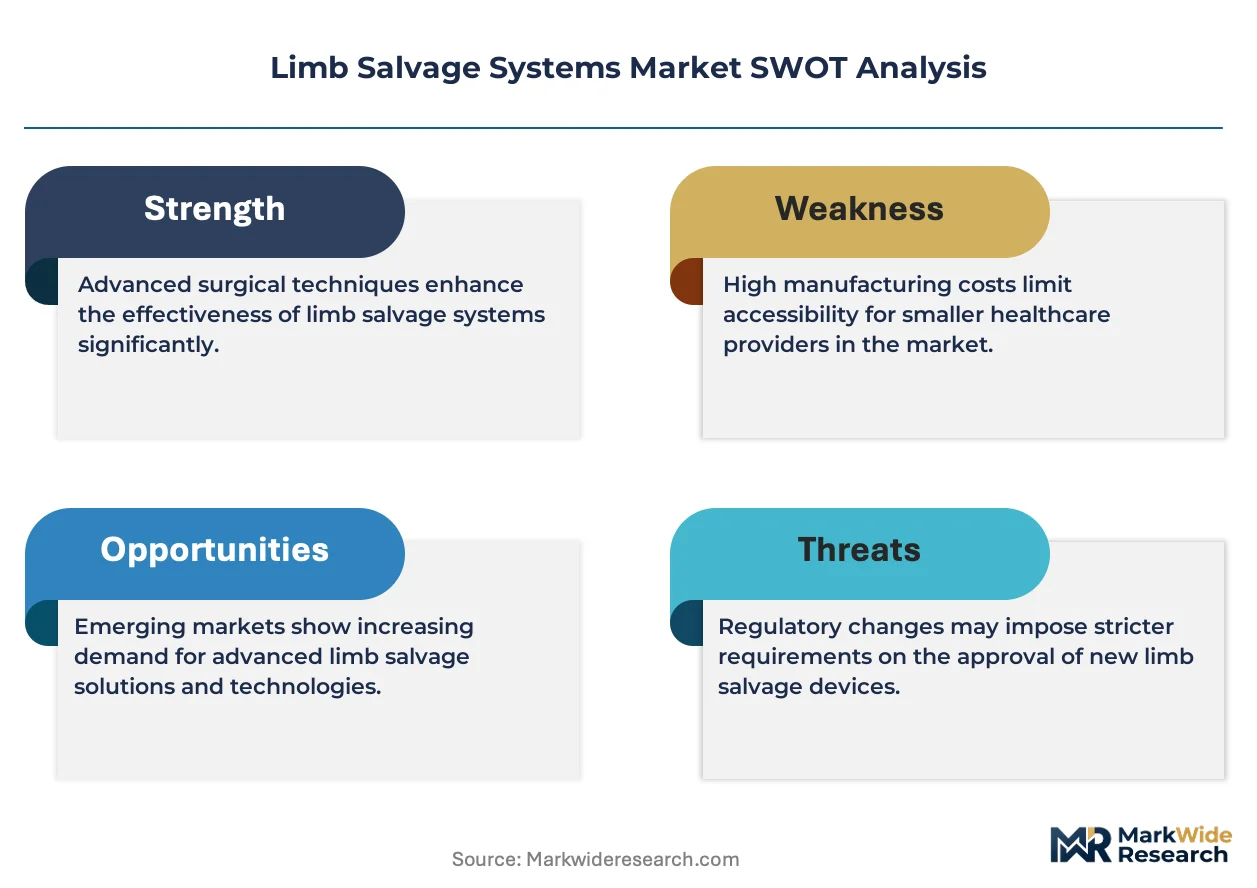
The EU Medical Device Regulation is compressing commercialization timelines for implantable limb salvage devices while simultaneously elevating clinical evidence requirements, forcing manufacturers to restructure regulatory affairs teams and front-load development costs.
Growth Catalysts
- 3D-printed porous titanium scaffolds:Additive manufacturing enables anatomically matched implants with superior osseointegration properties. Tertiary referral centers in the United States are rapidly adopting these patient-specific constructs for complex tumor resections.
- Integrated limb preservation centers:Consolidated referral networks across American healthcare systems are centralizing complex reconstructive procedures. These centers generate predictable case volumes that justify capital investment in navigation-assisted surgical suites.
- EU MDR post-market clinical follow-up mandates:Stricter surveillance requirements are paradoxically strengthening incumbent positions by raising barriers for new entrants lacking longitudinal data portfolios.
Market Restraints
- Cobalt-chrome alloy supply concentration:Primary smelting capacity for medical-grade alloys concentrates in a limited number of European and East Asian suppliers. Price volatility in cobalt feedstock directly impacts implant manufacturing economics.
- FDA premarket approval pathway duration:Permanent implantable devices face extended review cycles at the Center for Devices and Radiological Health. Small manufacturers lack capital reserves to sustain operations during multi-year approval processes.
- Antibiotic-loaded cement spacer substitution:Temporary spacer systems compete with definitive implants in infectious destruction cases. These lower-cost alternatives capture cases where patient comorbidities preclude immediate reconstruction.
Strategic Opportunities
- Diabetic limb preservation protocols:Vascular surgery departments in Germany are expanding reconstructive capabilities for diabetic foot complications. This application vertical currently penetrates only a fraction of eligible case volumes.
- Navigation-assisted surgical technology convergence:Integration of intraoperative imaging with robotic positioning systems creates premium procedure tiers. Academic medical centers in the United States are standardizing these workflows for pelvic and shoulder reconstructions.
- Indian orthopedic hospital expansion:Private hospital chains in Mumbai and Delhi are building dedicated musculoskeletal oncology units. Regulatory pathways through CDSCO offer faster market access than FDA or EMA routes for qualified manufacturers.
Industry Challenges
- Biomechanical engineer talent scarcity:Specialized expertise in orthopedic implant design and finite element analysis concentrates at a handful of academic programs. Manufacturers compete aggressively for graduates with computational modeling capabilities.
- ISO 5832 fatigue testing certification timelines:Validating metallic material compliance for novel alloys requires extended cyclical loading studies. Third-party testing laboratory capacity constraints extend development schedules unpredictably.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Limb Salvage Systems Market |
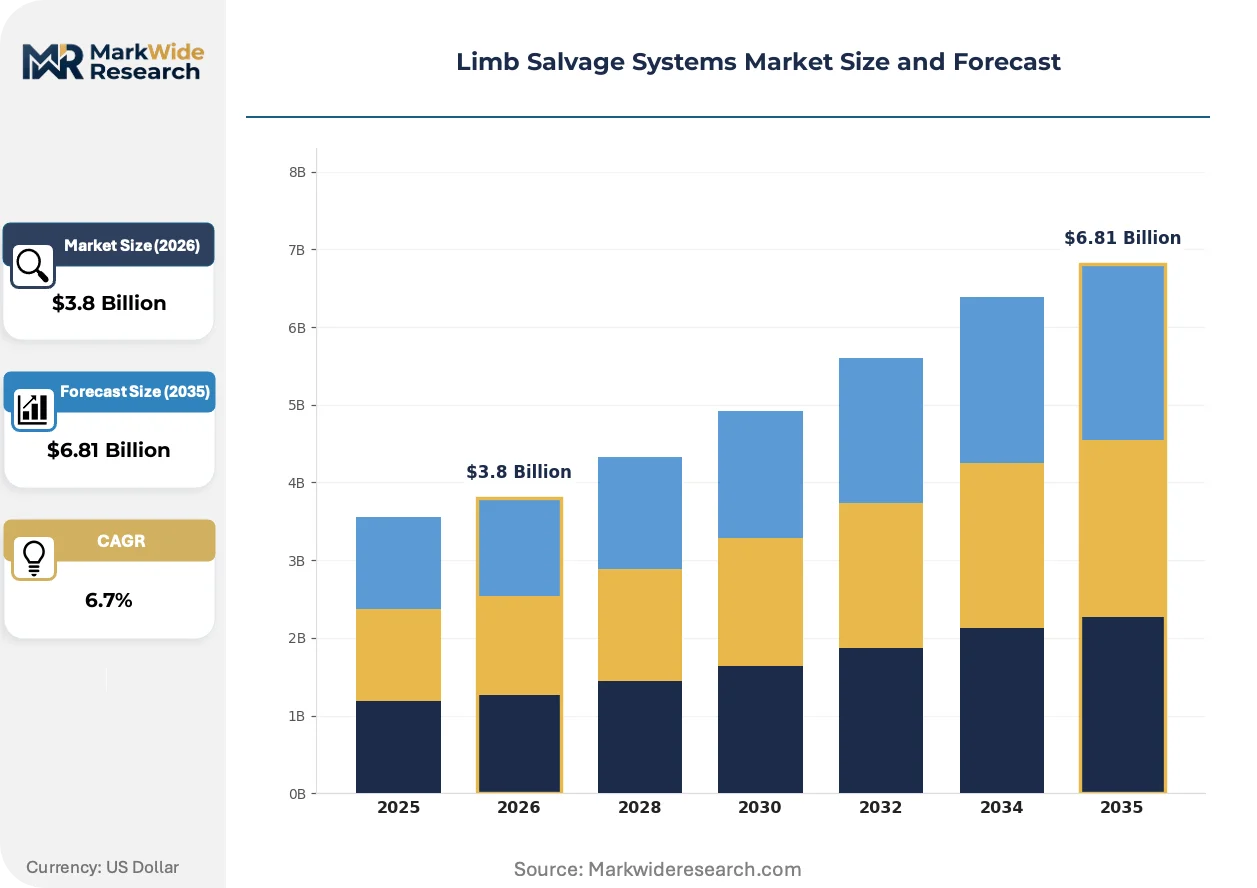
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: External Fixators, Bone Allografts, Implants, Orthoses Application: Trauma Management, Cancer Treatment, Diabetic Ulcers, Osteomyelitis End User: Hospitals, Rehabilitation Centers, Outpatient Clinics, Surgical Centers Technology: 3D Printing, Biomaterials, Robotics, Imaging Systems |
| Companies Covered | Stryker Corporation, Zimmer Biomet Holdings, Inc., Onkos Surgical, Inc., Wright Medical Group N.V., Implantcast GmbH, Stanmore Implants Worldwide Ltd, LimaCorporate S.p.A., Smith & Nephew plc, Orthofix Medical Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Limb Salvage Systems Market Strategic Shifts
Digital manufacturing workflows are displacing conventional forging and machining across implant production, while regulatory convergence between FDA and EU MDR frameworks is harmonizing quality management expectations for multinational suppliers.
Patient-specific instrumentation derived from preoperative CT segmentation is digitizing surgical planning workflows for complex tumor resections. Academic medical centers in the United States are adopting these digital templates at accelerating rates. The technology is digitizing case preparation by compressing operative time and reducing intraoperative decision variability.
EU Medical Device Regulation Class III implantable requirements are mandating systematic post-market clinical follow-up for all permanent limb salvage devices. Manufacturers must now maintain active surveillance registries capturing long-term implant survival data. Modular tumor endoprostheses face the steepest compliance burden given their extended intended-use lifespans and revision-intensive follow-up requirements.
Hospital purchasing committees are consolidating vendor relationships around full-procedure solutions rather than discrete implant procurement. Integrated limb preservation centers in the United States now negotiate bundled contracts spanning navigation systems, patient-matched instrumentation, and implant hardware. This behavioral shift concentrates purchasing power at flagship academic institutions while marginalizing smaller community hospital suppliers.
Limb Salvage Systems Market Segmentation
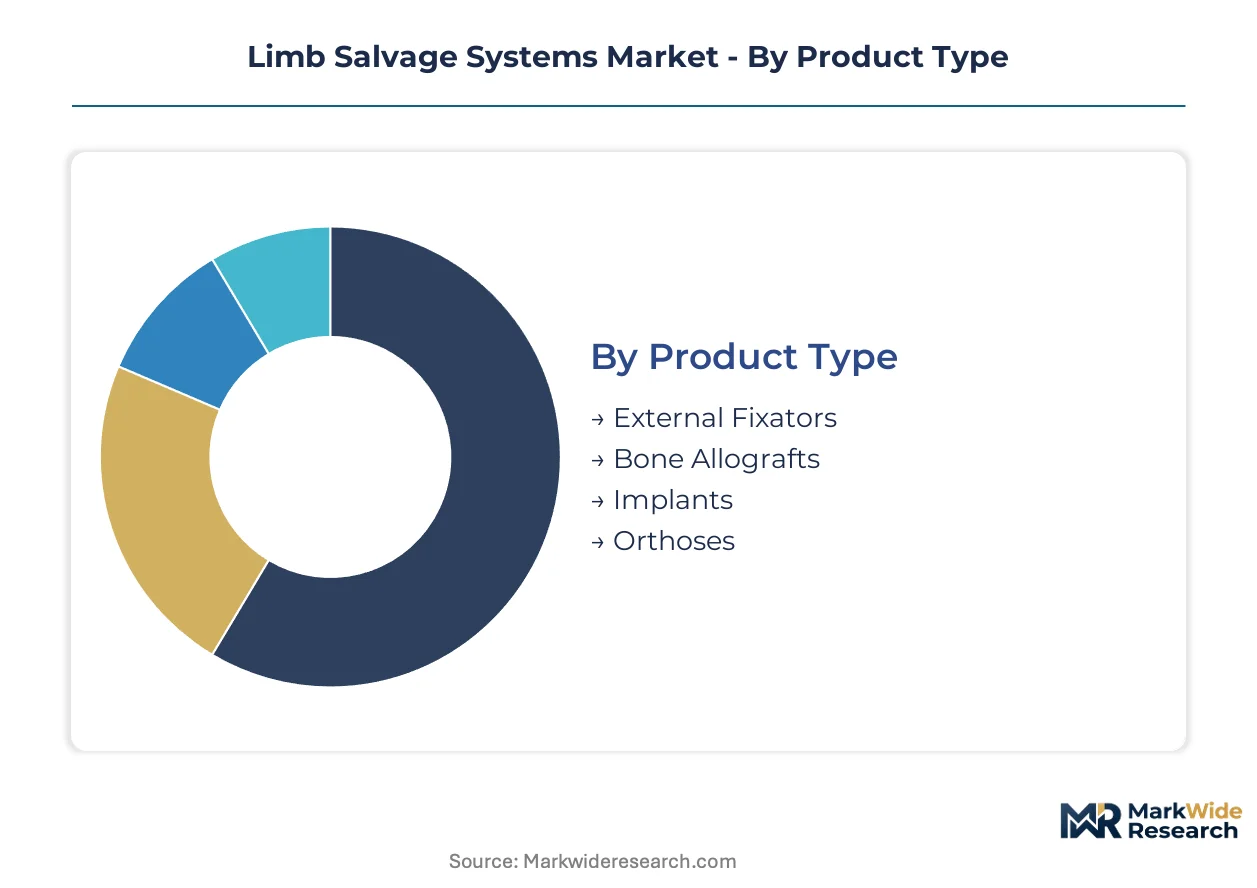
Limb salvage systems span implantable hardware, biological grafts, and external stabilization devices, each with distinct procurement pathways and clinical decision criteria. Segmentation reveals how technology maturity and reimbursement economics reshape competitive priorities across product categories.
Product Type:
Mature forged-metal implants coexist with emerging additive-manufactured constructs across the maturity spectrum.
- Implants:Modular tumor endoprostheses and revision stems command premium pricing through cobalt-chrome and titanium porous structures. Tertiary referral centers in the United States concentrate demand for navigation-assisted implantation workflows. Recurring revision cycles sustain manufacturer revenue predictability despite elevated upfront capital requirements.
- External Fixators:Ring and rail-based systems stabilize compromised limbs through percutaneous pin fixation. German orthopedic hospitals favor these devices for temporary limb preservation ahead of definitive reconstruction. Lower reimbursement thresholds constrain pricing power compared to permanent implants.
- Bone Allografts:Cadaveric structural grafts restore segmental bone loss in oncologic resections.
- Orthoses:Custom-fabricated braces and splints maintain postoperative alignment during osseointegration.
Implants retain volume leadership; 3D-printed porous titanium constructs hold the steepest expansion curve.
Application:
Cost tier stratification separates high-complexity oncologic procedures from routine infectious management.
- Cancer Treatment:Musculoskeletal tumor resections require modular endoprostheses with expandable components for pediatric patients. Academic medical centers in the United States generate concentrated case volumes through multidisciplinary sarcoma programs. Post-market clinical follow-up mandates under EU MDR impose surveillance registry costs that favor incumbent manufacturers.
- Trauma Management:High-energy fractures with segmental bone loss demand immediate stabilization and staged reconstruction. Level I trauma centers prioritize integrated fixation systems that convert external to internal constructs. Reimbursement through diagnosis-related groups creates pressure to minimize implant costs per episode.
- Diabetic Ulcers:Vascular surgery departments in Germany are expanding limb preservation protocols for neuropathic foot complications.
- Osteomyelitis:Antibiotic-loaded cement spacers compete with definitive implants in infectious destruction cases.
Cancer treatment commands the highest revenue per procedure; diabetic ulcers are climbing the fastest as vascular surgery integrates reconstructive capabilities.
End User:
Customer type determines procurement sophistication and capital equipment bundling requirements.
- Hospitals:Integrated limb preservation centers consolidate complex reconstructive workflows across oncology, orthopedics, and vascular surgery. These institutions negotiate bundled contracts spanning navigation systems, patient-matched instrumentation, and implant hardware. Purchasing committees now favor full-procedure solutions over discrete component procurement.
- Surgical Centers:Ambulatory facilities handle lower-acuity external fixation and soft-tissue procedures. Medicare site-of-service differentials incentivize migration of appropriate cases from hospital outpatient departments.
- Rehabilitation Centers:Post-acute facilities manage orthotic fitting and gait training following definitive reconstruction.
- Outpatient Clinics:Wound care centers initiate limb preservation protocols for diabetic and vascular patients.
Hospitals retain volume leadership; surgical centers are gaining share fastest through site-of-service economics.
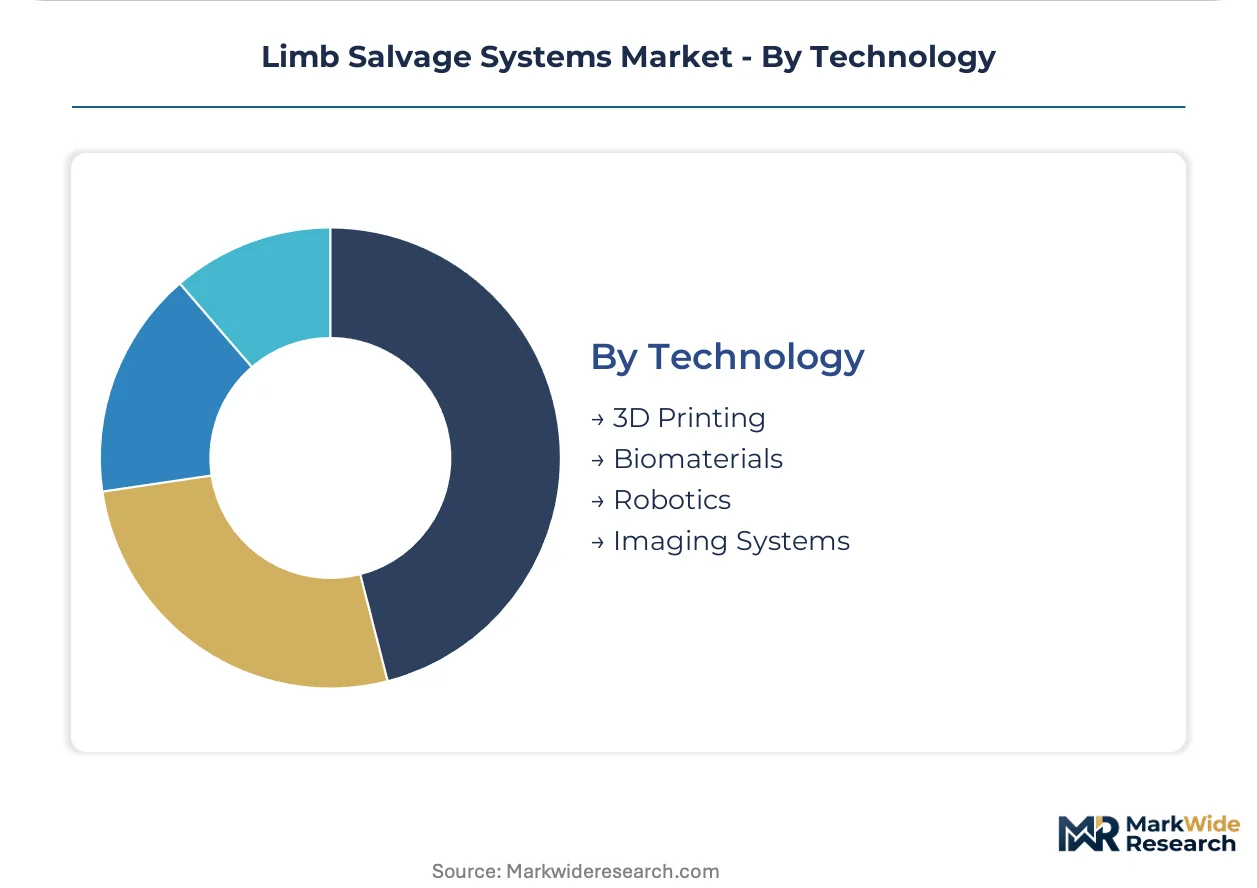
Technology:
Supply concentration in additive manufacturing equipment shapes competitive access to patient-specific production.
- 3D Printing:Electron beam melting and selective laser sintering enable anatomically matched porous titanium scaffolds with superior osseointegration. Tertiary centers in the United States adopt these constructs for complex pelvic and shoulder reconstructions. Equipment vendor lock-in creates switching costs that concentrate production capabilities at select manufacturing sites.
- Imaging Systems:Intraoperative CT and fluoroscopy integrate with navigation platforms to reduce surgical variability. Academic medical centers standardize these workflows for tumor resections requiring precise margin assessment.
- Biomaterials:Antibiotic-loaded cements and osteoinductive coatings modify implant surfaces for infection control.
- Robotics:Positioning systems assist with complex osteotomies and implant alignment.
3D printing retains technology leadership; imaging systems integration holds the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA premarket approval pathways anchor the United States as the dominant geography for limb salvage system commercialization, while EU MDR compliance costs reshape competitive positioning across European markets. The analysis spans five countries where regulatory frameworks and clinical infrastructure concentrate demand.
United States
Integrated limb preservation centers in Boston, Houston, and Chicago consolidate complex reconstructive referrals from community hospitals. FDA Center for Devices and Radiological Health enforces extended PMA review cycles for permanent implantables. Academic medical centers in the Southeast are standardizing navigation-assisted surgical workflows for pelvic tumor resections.
Germany
Orthopedic hospitals in Bavaria and North Rhine-Westphalia are expanding reconstructive surgery programs for diabetic foot complications. EU Medical Device Regulation mandates notified body conformity assessments and post-market clinical follow-up for Class III implantables. Precision implant fabrication clusters around Stuttgart and Munich are narrowing the manufacturing capacity gap through targeted capital investments.
India
Private hospital chains in Mumbai and Delhi are building dedicated musculoskeletal oncology units to capture rising case volumes. CDSCO regulatory pathways offer faster market access than FDA or EMA routes for qualified manufacturers. Tertiary referral centers in Karnataka and Tamil Nadu are adopting 3D-printed patient-specific instrumentation for complex tumor surgeries.
Japan
PMDA marketing authorization requirements for permanent implantables maintain rigorous clinical evidence standards comparable to FDA benchmarks. METI industrial policy supports domestic additive manufacturing capabilities for medical-grade titanium porous structures. Osaka-based orthopedic centers are integrating intraoperative imaging with robotic positioning systems for shoulder reconstructions.
United Kingdom
NHS specialized commissioning frameworks concentrate limb salvage procedures at designated sarcoma centers in London, Manchester, and Birmingham. MHRA post-Brexit regulatory alignment with EU MDR maintains CE marking requirements for implantable devices. Academic medical centers in Scotland are expanding patient-matched instrumentation programs for pediatric expandable endoprostheses.
Limb Salvage Systems Market Competitive Environment
Capability concentration sits with integrated surgical technology conglomerates; scale advantage sits with specialized orthopedic manufacturers. The market structure organizes around three tiers: diversified medtech conglomerates with navigation system portfolios, dedicated orthopedic implant specialists with modular tumor prosthesis expertise, and emerging additive manufacturing-native firms with patient-specific production capabilities. Dominant competitive moves include strategic partnerships between implant manufacturers and 3D printing equipment vendors, plus backward integration into cobalt-chrome alloy supply chains to mitigate feedstock price volatility.
Among diversified technology conglomerates, Stryker Corporation and Smith & Nephew plc exemplify the integrated surgical systems archetype, bundling navigation platforms with implant hardware. Zimmer Biomet Holdings, Inc. occupies a position within the specialized orthopedic tier, anchoring European market presence through oncologic prosthesis development. Onkos Surgical, Inc. represents the patient-specific instrumentation specialist archetype, differentiating through musculoskeletal tumor surgery applications.
| Leading Market Players |
|---|
| Stryker Corporation |
| Zimmer Biomet Holdings, Inc. |
| Onkos Surgical, Inc. |
| Wright Medical Group N.V. |
| Implantcast GmbH |
| Stanmore Implants Worldwide Ltd |
| LimaCorporate S.p.A. |
| Smith & Nephew plc |
| Orthofix Medical Inc. |
| Others |
Value Chain & Pricing Dynamics
Cobalt feedstock price volatility concentrates pricing power at European and East Asian smelters, compressing margins for forged implant manufacturers while widening spreads between premium porous titanium constructs and standard cobalt-chrome stems. This commodity exposure forces tiered procurement strategies across German orthopedic hospitals and American limb preservation centers, with buyers bundling navigation systems to offset raw material risk.
Pricing Analysis
Price spreads between the United States and Germany exceed those within either market due to FDA PMA pathway costs and EU MDR surveillance burdens. Three-tier pricing structure across premium, standard, and economy levels separates navigation-integrated tumor endoprostheses from conventional modular stems and temporary cement spacers. Pricing pressure stems from antibiotic-loaded spacer substitution in infectious destruction cases. Community hospitals exhibit highest price sensitivity; integrated academic centers prioritize outcome predictability over unit cost.
Supply Chain Analysis
Single-source dependency on German and Belgian cobalt-chrome alloy smelters dominates supply risk for forged implant manufacturers. Medical-grade titanium sponge feeds from Japanese and Kazakhstani refiners, while electron beam melting equipment concentrates among Dutch and German additive manufacturing vendors. Distribution runs through GPO contracts at American hospital systems and direct procurement at European orthopedic centers. Tariff exposure between the United States and EU threatens cross-Atlantic component flows for patient-specific instrumentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity sits with diabetic limb preservation protocols, as vascular surgery departments in Germany and the United States build reconstructive capabilities faster than incumbent orthopedic suppliers can adapt portfolios. This demand-side specialization creates niches for additive manufacturing-native firms and biological graft specialists.
For Market Incumbents: Build regulatory data moats through EU MDR post-market clinical follow-up registries capturing long-term modular endoprosthesis survival. Incumbents should anchor backward integration into cobalt-chrome supply chains to neutralize feedstock volatility, while deploying navigation system bundling to lock out emerging additive manufacturing competitors from academic medical center contracts. For New Entrants and Emerging Players: Pursue CDSCO regulatory pathways for 3D-printed porous titanium scaffolds in Indian private hospital chains, where musculoskeletal oncology unit expansion outpaces domestic manufacturing capacity. New entrants should target diabetic foot reconstruction applications in German vascular surgery departments, leveraging patient-specific instrumentation partnerships with Mumbai-based tertiary centers as reference sites. For Investors and Strategic Acquirers: EU MDR Class III implantable surveillance mandates reshape the acquisition landscape by devaluing development-stage assets lacking longitudinal clinical data. Investors should frame five-to-ten year viability around notified body relationship depth and active registry maintenance capabilities. The signal to watch is CDSCO accelerated approval designations for additive-manufactured constructs, which would validate Indian market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Post-Market Clinical Follow-Up Registry | Longitudinal implant survival data satisfies notified body surveillance mandates for Class III devices. |
| Navigation System Bundling Contract | Integrated limb preservation centers in Boston and Houston consolidate vendor relationships around full-procedure solutions. |
| CDSCO Regulatory Pathway Investment | Faster marketing authorization in India than FDA or EMA routes enables early revenue in expanding oncology units. |
| Patient-Specific Instrumentation Partnership | Preoperative CT segmentation workflows digitize surgical planning for complex pelvic tumor resections. |
| Cobalt-Chrome Alloy Supply Integration | Captive smelter relationships neutralize price volatility from concentrated European feedstock sources. |
Study Parameters
Initial hypotheses were tested against primary input from orthopedic surgeons, hospital purchasing committee directors, biomedical engineers at tertiary referral centers, and regulatory affairs leads at implant manufacturers, then refined through secondary validation against FDA PMA filings, EU MDR notified body guidance documents, CMS Medicare reimbursement databases, and hospital procurement contract records. Bottom-up procedure volume estimates triangulated with top-down manufacturer revenue allocations.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling segmentation dimensions including product type maturity, application complexity tier, end-user capital equipment bundling requirements, and technology adoption patterns by geographic regulatory cluster. CAGRs derived from procedure volume growth trajectories, pricing elasticity coefficients, and revision cycle frequency assumptions specific to modular tumor endoprostheses versus external fixation systems.
The forecast holds incumbent behavior within observed patterns; aggressive moves by additive manufacturing-native entrants or cobalt alloy supply consolidators would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Spinal Implants and Devices Market
Orthopedic Devices
Orthopedic Pedicle Screw Market
Orthopedic Devices
Global Joint Replacement Market
Orthopedic Devices
Revision Knee Replacement Market
Orthopedic Devices
Middle East and Africa Knee Cartilage Repair Market
Orthopedic Devices
Global Orthopedic Bone Cement Market
Orthopedic Devices
Global Veterinary Orthopedics Market
Orthopedic Devices
Global Shoulder Replacement Market
Orthopedic Devices
Wrist Replacement Orthopedic Devices Market
Orthopedic Devices
Global Orthopedic Splints Market
Orthopedic Devices
GCC Orthopedic Braces and Supports Market
Orthopedic Devices
Pediatrics Orthotics Market
Orthopedic Devices
Global Patient Positioning Devices Market
Orthopedic Devices
Orthopedic Extremity Market
Orthopedic Devices
Orthotic Devices Orthotic Splints and Orthopedic Braces and Support Market
Orthopedic Devices
Global Orthopedic Digit Implants Market