
 Orthopedic Trauma Devices Market | 2026-2036
Orthopedic Trauma Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Orthopedic Trauma Devices Market Outlook
The premium-commodity split in orthopedic trauma devices is repositioning around material science and surgical workflow integration. Stryker Corporation leverages its robotics and navigation platforms to command higher pricing in image-guided fracture repair. Zimmer Biomet Holdings anchors its portfolio through broad hospital contracts and legacy surgeon training programs. Smith & Nephew plc differentiates via its advanced wound management adjacencies that tie into post-trauma recovery protocols.
Orthopedic trauma devices comprise metallic and bioresorbable implants engineered to stabilize bone fractures, reconstruct limbs, and enable fusion through mechanical fixation and biological integration. These products typically employ titanium alloys, stainless steel, or polyetheretherketone substrates manufactured to precise ASTM and ISO dimensional tolerances, with surface treatments that promote osseointegration. Plates and screws remain the volume backbone due to universal applicability across fracture types, while intramedullary nails capture premium margins in long-bone trauma where load-bearing performance is critical. Robotics and image-guided surgery represent the fastest-expanding technology dimension, though traditional open techniques still dominate procedure counts in emerging hospital systems.
The FDA's 510(k) premarket notification framework and the European Union's Medical Device Regulation impose stringent biocompatibility and clinical evidence requirements that filter market entrants and extend product development cycles. ASTM F138 and ISO 5832 material standards govern implant metallurgy, creating compliance moats around established manufacturers. Stakeholders must monitor how FDA digital health guidance and EU MDR notified body capacity constraints reshape competitive timelines for next-generation trauma platforms.
Market Dynamics
The orthopedic trauma devices market is undergoing a fundamental reconfiguration as patient-specific 3D-printed implants and robotic-assisted surgical platforms compress traditional open-procedure economics while elevating outcomes-based reimbursement thresholds.
Growth Catalysts
- Aging Demographics in China:The country's 60-plus population expansion generates sustained demand for hip and femoral fracture fixation devices across tier-one hospital networks.
- FDA Breakthrough Device Designation:Expedited review pathways for patient-matched implants accelerate commercialization timelines for additive-manufactured trauma plates.
- Trauma Center Certification Mandates:State-level emergency medical service requirements in the United States drive capital equipment procurement for Level I and II trauma facilities.
Market Restraints
- Titanium Alloy Price Volatility:Aerospace and defense sector competition for Ti-6Al-4V feedstock compresses implant manufacturing margins during supply tightness.
- Notified Body Capacity Constraints: EU MDR technical documentation review backlogs extend product launch timelines by 12-18 months for mid-tier manufacturers.
- Bioresorbable Polymer Degradation Uncertainty:PLLA and PGA composite screws face clinical skepticism regarding predictable mechanical strength loss curves in load-bearing applications.
Strategic Opportunities
- Outpatient Surgery Center Expansion:Ambulatory surgical facilities in Germany and the United States seek compact, image-guided trauma systems for same-day fracture stabilization.
- AI-Enabled Preoperative Planning:Machine learning algorithms for fracture classification and implant sizing converge with cloud-based surgical workflow platforms.
- India's PLI Scheme for Medical Devices:Production-linked incentives for domestic manufacturing of high-value orthopedic implants reduce import dependency in price-sensitive segments.
Industry Challenges
- Orthopedic Trauma Surgeon Training Gaps:Fellowship programs produce insufficient volumes of surgeons proficient in minimally invasive nailing techniques and robotic platform operation.
- Legacy Hospital Information System Integration:Surgical navigation and planning software requires costly middleware development to interface with entrenched electronic health record architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Orthopedic Trauma Devices Market |
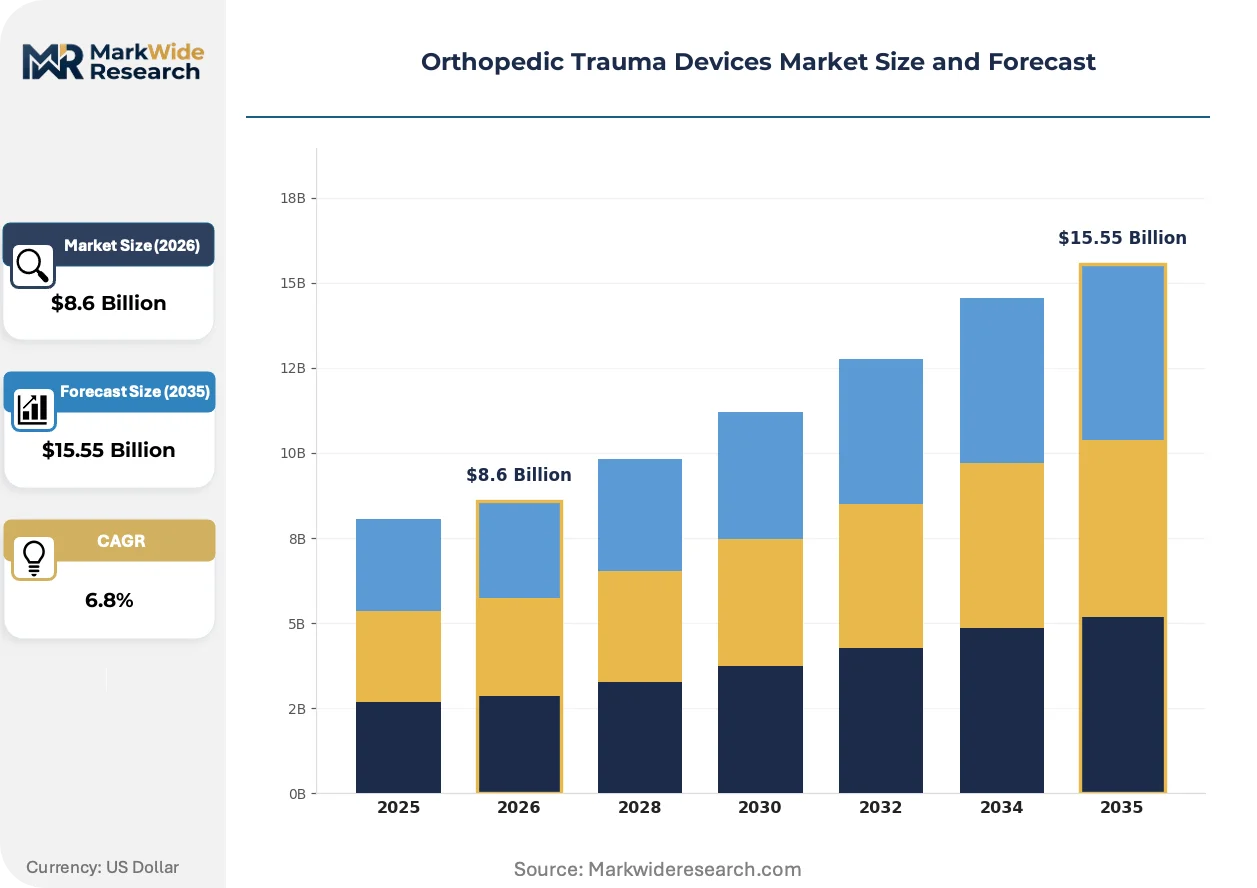
| Market Size in 2026 | $8.6 Billion |
| Market Size in 2035 | $15.55 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plates, Screws, Intramedullary Nails, Bone Grafts End User: Hospitals, Orthopedic Clinics, Rehabilitation Centers, Private Practices Application: Fracture Repair, Limb Reconstruction, Osteotomy, Fusion Procedures Technology: Minimally Invasive Techniques, Traditional Surgery, Image-Guided Surgery, Robotics |
| Companies Covered | Smith & Nephew plc, Enovis Corporation, DePuy Synthes, Inc., Medacta International SA, MicroPort Scientific Corporation, Stryker Corporation, Arthrex, Inc., CONMED Corporation, Zimmer Biomet Holdings, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orthopedic Trauma Devices Market Strategic Shifts
Digital surgical ecosystems are redefining competitive advantage in trauma care, with connectivity, personalization, and point-of-care manufacturing displacing conventional implant commoditization.
Patient-specific 3D-printed titanium implants is overtaking standard anatomical plate inventory in complex pelvic and acetabular fracture reconstruction. Academic medical centers and specialized trauma hubs in Germany and the United States are adopting these implants for 15-20% of complex cases. This technology is overtaking the traditional implant stocking model by enabling just-in-time manufacturing that eliminates sterilization logistics and reduces operative time.
EU MDR Article 10 clinical evidence requirements are intensifying post-market surveillance obligations for legacy implant portfolios. Manufacturers must now generate prospective clinical data or systematic literature reviews for devices previously cleared under the Medical Devices Directive. Long-bone intramedullary nail systems face the steepest compliance burden, with several mid-tier suppliers withdrawing SKUs rather than funding clinical follow-up studies.
Hospital procurement committees are consolidating vendor relationships into multi-year, enterprise-wide contracts that bundle implants with robotics, navigation, and training services. Independent distributors and regional implant suppliers are losing shelf space as integrated delivery networks in the United States and hospital chains in China centralize purchasing authority. This concentration is most visible in the United States, where three national GPOs control 80% of acute care orthopedic device spend and demand outcome guarantees from suppliers.
Orthopedic Trauma Devices Market Segmentation
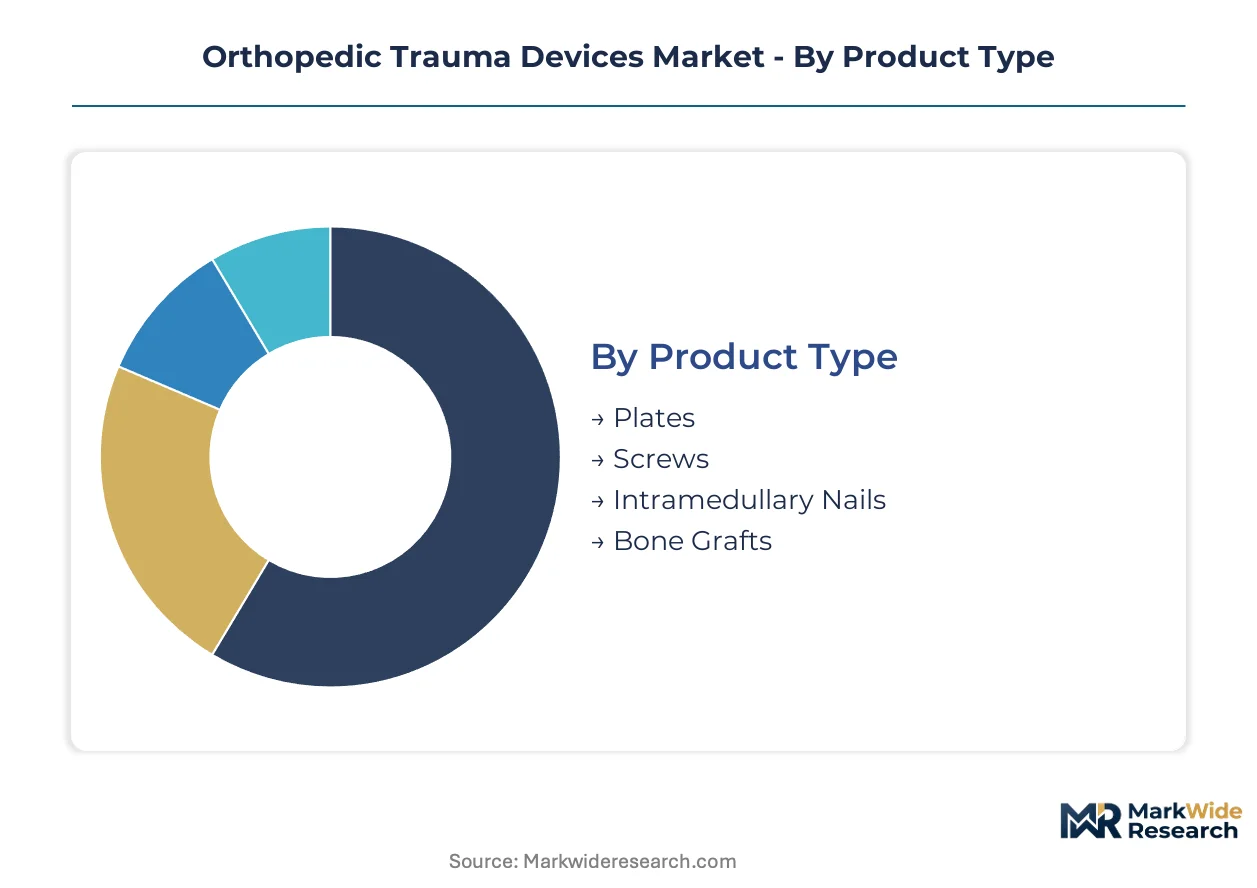
Orthopedic trauma device segmentation reveals how capital deployment, regulatory pathways, and surgical workflow integration create divergent margin profiles across product categories. Understanding these fault lines enables manufacturers to prioritize R&D investment and distribution partnerships.
Product Type:
Capital intensity varies dramatically across implant categories, with forging and precision machining requirements dictating facility investment thresholds.
- Plates:Titanium alloy and stainless steel plates require multi-axis CNC machining and surface treatment lines. Demand clusters in United States Level I trauma centers and German university hospitals managing high-volume polytrauma. These facilities prioritize locking compression plate systems with anatomically contoured designs.
- Intramedullary Nails:These load-bearing implants demand closed-die forging and gamma sterilization infrastructure. Chinese tier-one hospitals and United States academic medical centers drive procurement for femoral and tibial nailing systems, particularly as minimally invasive insertion techniques expand.
- Screws:Cortical and cancellous bone screws utilize standardized thread geometries with lower per-unit capital requirements than plates or nails.
- Bone Grafts:Synthetic and allograft materials involve biologics processing capabilities distinct from metallic implant manufacturing.
Plates absorb the bulk of installed capacity; intramedullary nails are expanding most quickly.
End User:
Purchasing authority and procurement sophistication create distinct customer tiers with varying contract structures and outcome expectations.
- Hospitals:Acute care facilities with emergency departments command the highest implant volumes and negotiate enterprise-wide agreements bundling trauma devices with robotics platforms. United States integrated delivery networks and Chinese provincial hospital chains centralize purchasing through dedicated orthopedic procurement committees.
- Orthopedic Clinics:Specialized ambulatory surgery centers in Germany and the United States seek compact fixation systems for same-day fracture stabilization, driving demand for streamlined instrument sets.
- Rehabilitation Centers:Post-acute facilities focus on external fixation and wound management adjacencies rather than permanent implant procurement.
- Private Practices:Independent orthopedic surgeons in suburban United States markets and select European private healthcare systems maintain limited inventory for minor trauma procedures.
Hospitals concentrate procurement volume; orthopedic clinics are gaining share fastest as ambulatory migration accelerates.
Application:
Procedure complexity and reimbursement coding influence device selection and pricing power across surgical indications.
- Fracture Repair:Diaphyseal and metaphyseal fracture fixation constitutes the foundational application, with United States trauma centers and Chinese emergency departments generating sustained demand for plates, screws, and nails across anatomical sites.
- Limb Reconstruction:Complex deformity correction and bone transport procedures require specialized external fixation and gradual lengthening systems, concentrating in German and United States academic referral centers.
- Osteotomy:Elective bone realignment procedures for post-traumatic deformity or joint preservation utilize wedge plates and guided cutting systems.
- Fusion Procedures:Arthrodesis for post-traumatic arthritis bridges trauma and spine device categories with distinct regulatory and reimbursement frameworks.
Fracture repair dominates procedure counts; limb reconstruction commands the steepest pricing premium.
Technology:
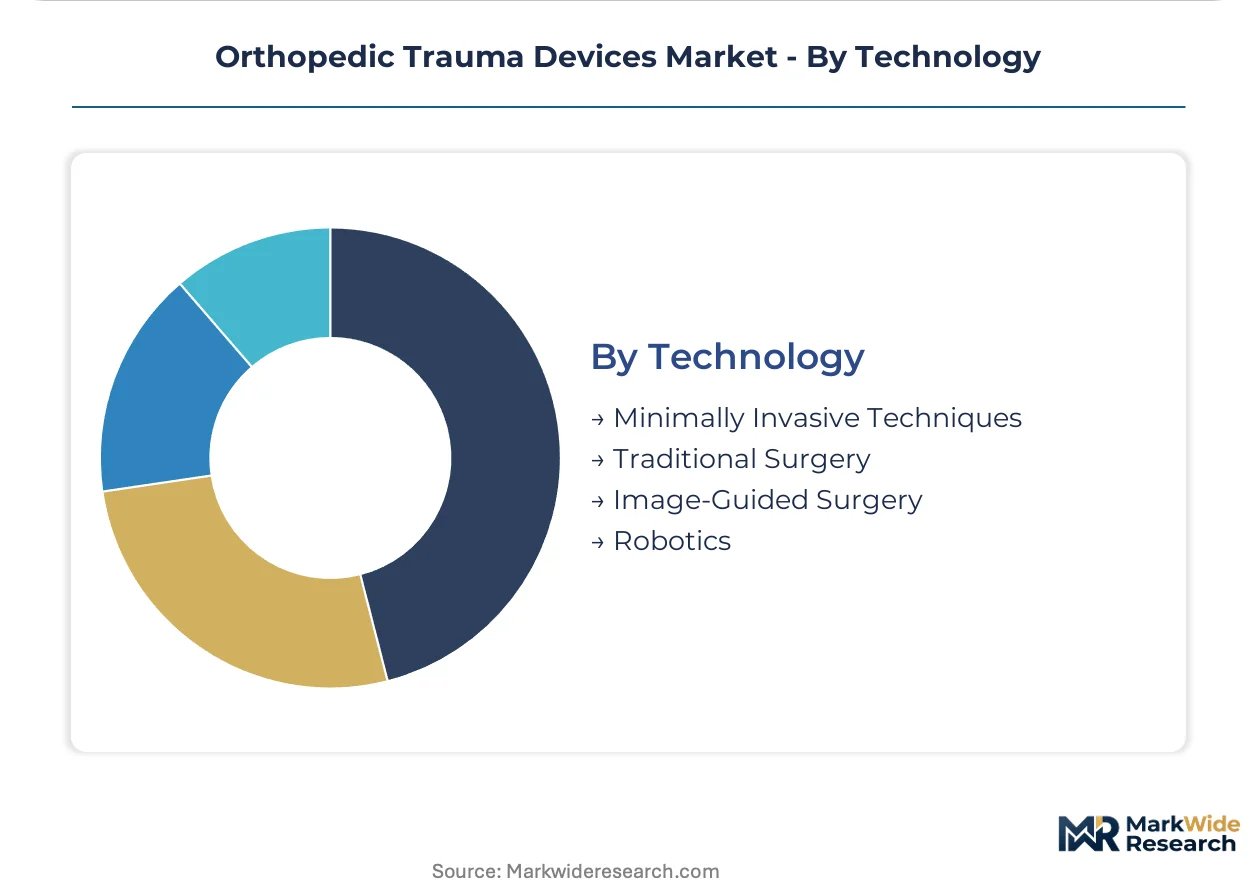
Platform investment requirements separate incumbent suppliers from emerging competitors, with software and capital equipment integration creating new barriers to entry.
- Robotics:Computer-assisted fracture reduction and implant positioning systems demand substantial development investment in haptic feedback and intraoperative imaging registration. United States academic centers and German trauma hubs lead adoption as they integrate these platforms with existing navigation infrastructure.
- Image-Guided Surgery:Fluoroscopy-integrated drilling and targeting systems reduce radiation exposure and improve implant placement accuracy. Chinese tier-one hospitals and United States Level I trauma centers prioritize these technologies for complex pelvic and acetabular cases.
- Minimally Invasive Techniques:Percutaneous plating and intramedullary nailing through small incisions require specialized instrument sets and surgeon training programs.
- Traditional Surgery:Open reduction and internal fixation with standard anatomical plates remains prevalent in cost-constrained settings and emerging hospital systems.
Traditional surgery retains the largest installed base; robotics is climbing the fastest as platform economics reshape capital allocation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Warsaw's emerging medical device corridor concentrates Central European trauma manufacturing capabilities as domestic hospitals expand orthopedic surgery capacity. Distribution networks radiate from this cluster into neighboring markets.
United States
Level I trauma centers in Baltimore and Houston drive procurement of robotic-assisted fracture repair systems as patient volumes surge. The FDA's 510(k) pathway shapes product development timelines for domestic manufacturers. The Midwest industrial belt around Warsaw, Indiana anchors metallic implant forging and precision machining operations for national distribution.
Germany
University hospitals in Munich and Berlin generate sustained demand for patient-matched 3D-printed titanium plates in complex pelvic reconstruction. The EU MDR's clinical evidence requirements filter market entrants and extend certification timelines. The Baden-Württemberg medical technology cluster around Tübingen concentrates surgical navigation platform development.
China
Tier-one hospitals in Beijing and Shanghai absorb growing volumes of intramedullary nails as road accident trauma loads intensify. The NMPA's streamlined Class III device review accelerates market access for domestic innovators. The Yangtze River Delta manufacturing corridor near Suzhou scales titanium alloy processing for both domestic consumption and export markets.
India
Provincial hospital chains in Maharashtra and Karnataka expand orthopedic device procurement as surgical infrastructure modernizes. The PLI scheme for medical devices incentivizes domestic production of high-value trauma implants. The Gujarat pharmaceutical-industrial corridor near Ahmedabad attracts contract manufacturing investments from multinational suppliers.
Japan
Academic medical centers in Tokyo and Osaka prioritize minimally invasive nailing techniques for aging femoral fracture patients. The PMDA's SAKIGAKE designation accelerates regulatory review for innovative trauma platforms. The Kobe medical device cluster advances bioresorbable polymer research for next-generation fixation systems.
Orthopedic Trauma Devices Market Competitive Environment
Premium-margin players sit above commodity-margin players across technology integration and surgeon training depth. The vendor base concentrates around integrated device-robotics platforms and standalone implant portfolios. Three archetypes dominate: diversified orthopedic conglomerates with navigation ecosystems, mid-scale specialists in trauma-specific fixation, and emerging Asian manufacturers leveraging cost-optimized production. Consolidation through strategic acquisitions and exclusive hospital contracting represent the primary competitive vectors reshaping market share distribution.
Among diversified orthopedic conglomerates, Stryker Corporation and Zimmer Biomet Holdings exemplify the premium-tier archetype through bundled device-platform offerings. Smith & Nephew plc occupies a distinct position linking trauma fixation with adjacent wound management capabilities. These three anchors illustrate how competitive positioning increasingly depends on workflow integration rather than implant commoditization alone.
| Leading Market Players |
|---|
| Smith & Nephew plc |
| Enovis Corporation |
| DePuy Synthes, Inc. |
| Medacta International SA |
| MicroPort Scientific Corporation |
| Stryker Corporation |
| Arthrex, Inc. |
| CONMED Corporation |
| Zimmer Biomet Holdings, Inc. |
| Others |
Value Chain & Pricing Dynamics
Captive titanium alloy forging operations in the United States, Germany, and China anchor both supply security and pricing power for implant manufacturers serving Level I trauma centers. This backward integration into Ti-6Al-4V feedstock processing insulates premium-tier suppliers from aerospace sector competition while enabling outcome-based contract structures with integrated delivery networks.
Pricing Analysis
Outcome guarantees tied to surgical workflow integration anchor pricing structures for robotic-assisted trauma platforms. Three-tier pricing stratification separates image-guided navigation bundles from standard anatomical plate systems and economy-grade stainless steel fixation. Pricing pressure stems from hospital procurement committee consolidation around enterprise-wide vendor contracts. Ambulatory surgery centers in Germany and the United States exhibit the highest price sensitivity, while United States academic medical centers prioritize throughput metrics over per-unit cost.
Supply Chain Analysis
Regional distribution centers in Warsaw, Indiana, Tübingen, and Suzhou coordinate hub-and-spoke fulfillment to hospital networks across North America, Europe, and Asia-Pacific. Manufacturing concentration in the United States Midwest, Germany's Baden-Württemberg cluster, and China's Yangtze River Delta feeds from titanium sponge processing and precision machining inputs. Single-source vulnerability in gamma sterilization capacity poses structural risk. Distribution runs through exclusive distributor relationships with GPO-affiliated logistics partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR notified body capacity constraints and titanium alloy feedstock competition from aerospace procurement create supply bottlenecks that prop pricing for qualified manufacturers across the analysis window.
For Market Incumbents: Anchor market position through exclusive multi-year contracts bundling implants with robotics platforms and surgeon training programs. Deepen backward integration into titanium alloy forging capacity in the United States Midwest to defend against aerospace sector feedstock competition. Prioritize FDA Breakthrough Device Designation pathways for patient-matched 3D-printed implants to extend regulatory moats. For New Entrants and Emerging Players: Launch via compact image-guided systems targeting ambulatory surgery centers in Germany and the United States seeking same-day fracture stabilization capabilities. India's PLI scheme for medical devices offers the most penetrable entry point for cost-optimized trauma plates. Pursue cloud-based surgical planning software partnerships to bypass capital-intensive robotics development. For Investors and Strategic Acquirers: Exit pathways concentrate in platform-integrated trauma specialists with FDA-cleared navigation ecosystems and established hospital GPO relationships. Long-term viability hinges on reimbursement strategy execution for outpatient migration. Watch for FDA digital health guidance finalization as inflection signal for software-enabled trauma platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Expedited review compresses commercialization timelines for patient-matched additive-manufactured trauma plates. |
| CE Marking Pathway under EU MDR | Article 10 clinical evidence requirements filter mid-tier competitors from legacy implant portfolios. |
| Hospital System Partnership | Enterprise-wide contracts with United States integrated delivery networks consolidate procurement authority. |
| Software Companion Development | AI-enabled preoperative planning platforms integrate with cloud-based surgical workflow systems. |
| Reimbursement Strategy | CPT code optimization for robotic-assisted fracture repair secures favorable outpatient payment rates. |
Study Parameters
FDA 510(k) clearance databases, EU MDR notified body technical documentation filings, and hospital procurement contract registries formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with orthopedic trauma surgeons, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers validated demand assumptions and pricing dynamics. Bottom-up implant volume modeling and top-down healthcare expenditure allocation triangulated market estimates.
Bottom-up segmentation across product type, end user, application, and technology dimensions anchored the analytical framework across the projection horizon. CAGRs derived from procedure volume growth, pricing trajectory assumptions, and technology adoption curves modeled through logistic diffusion functions. Forecast inputs incorporated aging demographic projections, road accident trauma incidence patterns, and regulatory pathway timelines.
Titanium alloy price volatility, EU MDR notified body capacity expansion delays, and bioresorbable polymer clinical evidence generation are the dominant revision risks to modeled outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
UAE Spinal Surgery Devices Market
Orthopedic Devices
Orthopedic Consumables Market
Orthopedic Devices
Europe Orthopedic Braces and Support Market
Orthopedic Devices
Global Joint Replacement Market
Orthopedic Devices
Orthopaedic Cushions Market
Orthopedic Devices
Closed Heel Nursing Shoes Market
Orthopedic Devices
3D Orthopedic Scanning System Market
Orthopedic Devices
South Africa Spinal Surgery Devices Market
Orthopedic Devices
Global Animal Ortho-Prosthetics Market
Orthopedic Devices
Europe Knee Cartilage Repair Market
Orthopedic Devices
Femoral Head Prostheses Market
Orthopedic Devices
Small Bone and Joint Orthopedic Devices Market
Orthopedic Devices
North America Spinal Surgery Market
Orthopedic Devices
Spinal Surgery Devices Market
Orthopedic Devices
Orthopedic Joint Reconstruction Market
Orthopedic Devices
Europe Orthopedic Devices Market