
 Total Wrist Prosthesis Market | 2026-2036
Total Wrist Prosthesis Market Size, Share, and Industry Trends Forecast 2026-2036
Total Wrist Prosthesis Market Analytics
Market Context
A capital-intensity divergence between integrated manufacturers and component assemblers is reorganizing competitive tiers in total wrist prosthesis supply. Zimmer Biomet leverages captive forging capacity for cobalt-chrome carpal components, while Stryker sustains R&D intensity through its dedicated extremities division. Johnson & Johnson competes via DePuy Synthes with broad orthopedic portfolios that cross-subsidize wrist-specific development.
Technical Definition and Segment Structure
Total wrist prosthesis denotes an artificial joint system replacing the radiocarpal and intercarpal articulations, typically comprising a radial metal component, carpal plate, and polyethylene bearing surface designed to restore flexion-extension arc and radial-ulnar deviation. The device serves patients with post-traumatic arthritis, rheumatoid destruction, or scapholunate advanced collapse where conservative management fails. Modular systems command premium positioning against fixed designs due to intraoperative adaptability and reduced revision rates. Ceramic bearings occupy a nascent but technically differentiated tier where wear debris concerns drive surgeon preference. Hospital procurement dominates volume, though orthopedic clinics represent the fastest-growing end-user channel as ambulatory surgical capacity expands.
Regulatory Environment
FDA 510(k) substantial equivalence reviews and EU MDR technical documentation requirements impose divergent compliance burdens on manufacturers seeking dual-market access. ISO 5832 standards for implant alloys and ASTM F2077 testing protocols govern material qualification and fatigue performance. Stakeholders must monitor evolving CMS reimbursement determinations for total wrist arthroplasty codes and parallel health technology assessment processes in Germany and Japan.
Market Dynamics
EU MDR technical documentation requirements and FDA 510(k) substantial equivalence pathways are compressing product development timelines while forcing manufacturers to prioritize modular implant architectures over fixed designs.
Growth Catalysts
- Ambulatory surgical center expansion:Orthopedic clinics in the United States are building dedicated wrist arthroplasty capacity, diverting volume from inpatient settings and accelerating procedural throughput.
- ISO 5832 alloy standardization:Unified material qualification protocols reduce supplier qualification burden and enable faster cobalt-chrome component sourcing across dual-market manufacturers.
- Rheumatoid arthritis prevalence clustering:Patient concentration in Germany and Japan creates predictable demand corridors that justify dedicated sales force deployment and inventory pre-positioning.
Market Restraints
- Cobalt-chrome price volatility:Raw material input costs for carpal plates fluctuate with aerospace sector demand, compressing margin stability for component assemblers without captive forging.
- Revision surgery complexity:Polyethylene bearing wear debris triggers osteolysis that complicates secondary procedures, limiting initial implant selection to surgeons with advanced soft-tissue management training.
- EU MDR notified body capacity:Technical documentation review queues extend CE marking timelines by 12-18 months, delaying market access for ceramic bearing innovations.
Strategic Opportunities
- Japan's super-aging prefectures:Rural regions with 35%+ population over 65 present concentrated demand for motion-preserving alternatives to wrist arthrodesis.
- Ceramic-polyethylene hybrid bearings:Material convergence reduces wear rates while maintaining surgeon familiarity with existing instrumentation and surgical technique.
- Direct-to-clinic distribution:Bypassing hospital procurement committees enables faster implant turnover and specialized inventory matching to surgeon preference cards.
Industry Challenges
- Extremities-specialized surgical training:Wrist arthroplasty volume remains insufficient to sustain dedicated fellowship pipelines, creating talent scarcity for complex revision cases.
- Legacy arthrodesis technique inertia:Established surgeons with decades of fusion experience require proctored conversion programs to adopt total wrist replacement protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Total Wrist Prosthesis Market |
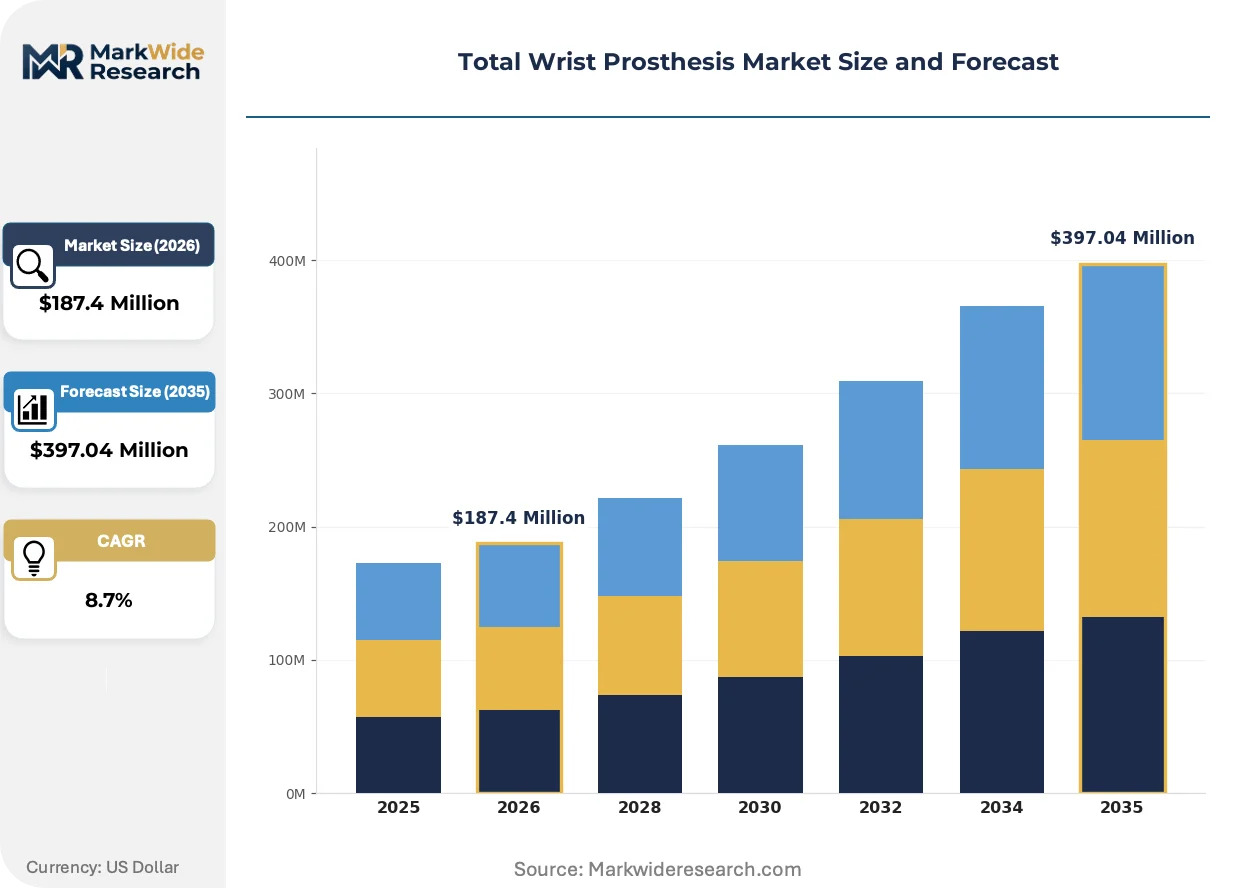
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed, Adjustable, Flexible, Modular Material: Metal, Ceramic, Polymer, Composite End User: Hospitals, Orthopedic Clinics, Rehabilitation Centers, Home Care Distribution Channel: Direct Sales, E-commerce, Wholesalers, Distributors |
| Companies Covered | Zimmer Biomet, Stryker, Johnson & Johnson, Smith+Nephew, DePuy Synthes, Arthrex, Integra LifeSciences, Acumed, Enovis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Total Wrist Prosthesis Market Evolving Landscape
Implant design philosophy is pivoting from maximal constraint toward adaptive kinematics, with bearing surface engineering and instrumentation ergonomics converging to expand the treatable patient pool beyond traditional rheumatoid indications.
Patient-specific instrumentation derived from preoperative CT is miniaturizing surgical exposure requirements and reducing soft-tissue dissection. Ambulatory surgery centers in the United States are adopting these systems fastest, compressing operative time and enabling same-day discharge protocols that hospital outpatient departments struggle to replicate.
EU MDR Article 10 technical documentation mandates now require clinical evaluation reports with post-market surveillance data, forcing manufacturers to maintain active implant registries. German notified bodies are enforcing this most strictly, causing smaller component assemblers to abandon CE marking rather than absorb compliance infrastructure costs.
Hospital procurement committees are unbundling implant pricing from instrumentation and surgical support, shifting vendor selection toward component-level cost transparency. This behavior is most pronounced in United States integrated delivery networks, where value analysis committees now dominate total wrist arthroplasty contract negotiations previously managed by individual surgeons.
Total Wrist Prosthesis Market Segmentation
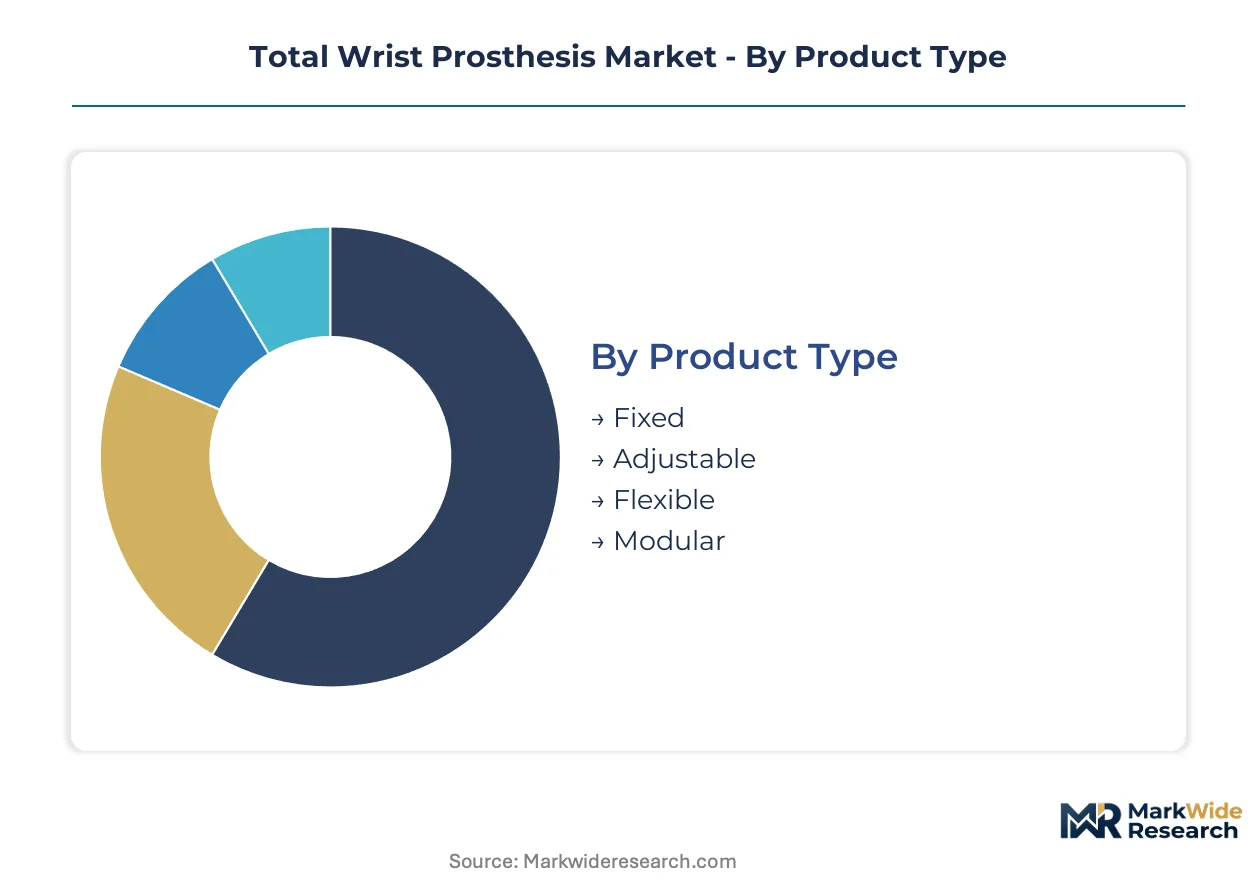
Total wrist prosthesis procurement patterns diverge sharply by clinical setting and material specification, with regulatory pathways governing reimbursement eligibility for each configuration. Surgeons select implant architectures based on bone stock quality, soft-tissue integrity, and anticipated activity demands rather than cost alone.
Product Type:
FDA 510(k) substantial equivalence reviews and EU MDR clinical evaluation requirements favor modular designs with established predicate devices, compressing approval timelines for adjustable configurations while fixed designs face heightened scrutiny for wear debris profiles.
- Fixed:Non-adjustable implant geometry with predetermined radial inclination and carpal height. Demand concentrates in Germany's statutory health insurance system where standardized reimbursement codes favor proven designs with decade-long surveillance data.
- Adjustable:Intraoperative tensioning mechanisms permit soft-tissue balancing without component exchange. United States ambulatory surgery centers are adopting these systems fastest, driven by same-day discharge protocols that demand predictable operative time.
- Flexible:Constrained motion patterns via elastic bearing elements. Japanese orthopedic clinics favor this architecture for low-demand rheumatoid patients.
- Modular:Interchangeable radial stems, carpal plates, and bearing inserts enable intraoperative customization. Hospital procurement committees in integrated delivery networks prioritize this tier for inventory consolidation across multiple surgeons.
Established volume favors Fixed; emerging adoption favors Modular.
Material:
Cost tier differentiation separates premium ceramic bearings from standard cobalt-chrome configurations, with polymer composites occupying a mid-tier position where wear performance justifies moderate price elevation.
- Metal:Cobalt-chrome alloys per ISO 5832-4 dominate radial components and carpal plates. German notified bodies enforce strict fatigue testing documentation, extending CE marking timelines for forged versus cast variants.
- Ceramic:Alumina or zirconia bearing surfaces reduce osteolysis risk from polyethylene debris. Japan's PMDA has cleared two ceramic-on-polyethylene systems, creating concentrated demand in Tokyo and Osaka academic medical centers.
- Polymer:Ultra-high molecular weight polyethylene articulating surfaces remain standard for cost-sensitive procurement.
- Composite:Carbon fiber-reinforced polymers for carpal plates in revision scenarios with compromised bone stock.
Metal retains dominant share; Ceramic climbs the fastest on longevity claims.
End User:
Customer type determines service intensity, with hospitals demanding comprehensive surgical support while orthopedic clinics prioritize instrument turnover speed and direct technical assistance.
- Hospitals:Inpatient and outpatient departments with 24-hour implant availability and revision surgery capability. United States academic medical centers in Boston and Baltimore maintain the highest procedural volumes for complex post-traumatic reconstructions.
- Orthopedic Clinics:Ambulatory facilities with dedicated hand surgery suites. These settings are expanding fastest in Florida and Arizona where aging populations and favorable payer mixes coincide.
- Rehabilitation Centers:Post-acute facilities managing conservative care and preoperative optimization.
- Home Care:Post-discharge monitoring and remote physical therapy protocols.
Hospitals anchor current volume; Orthopedic Clinics gain share fastest on site-of-service migration.
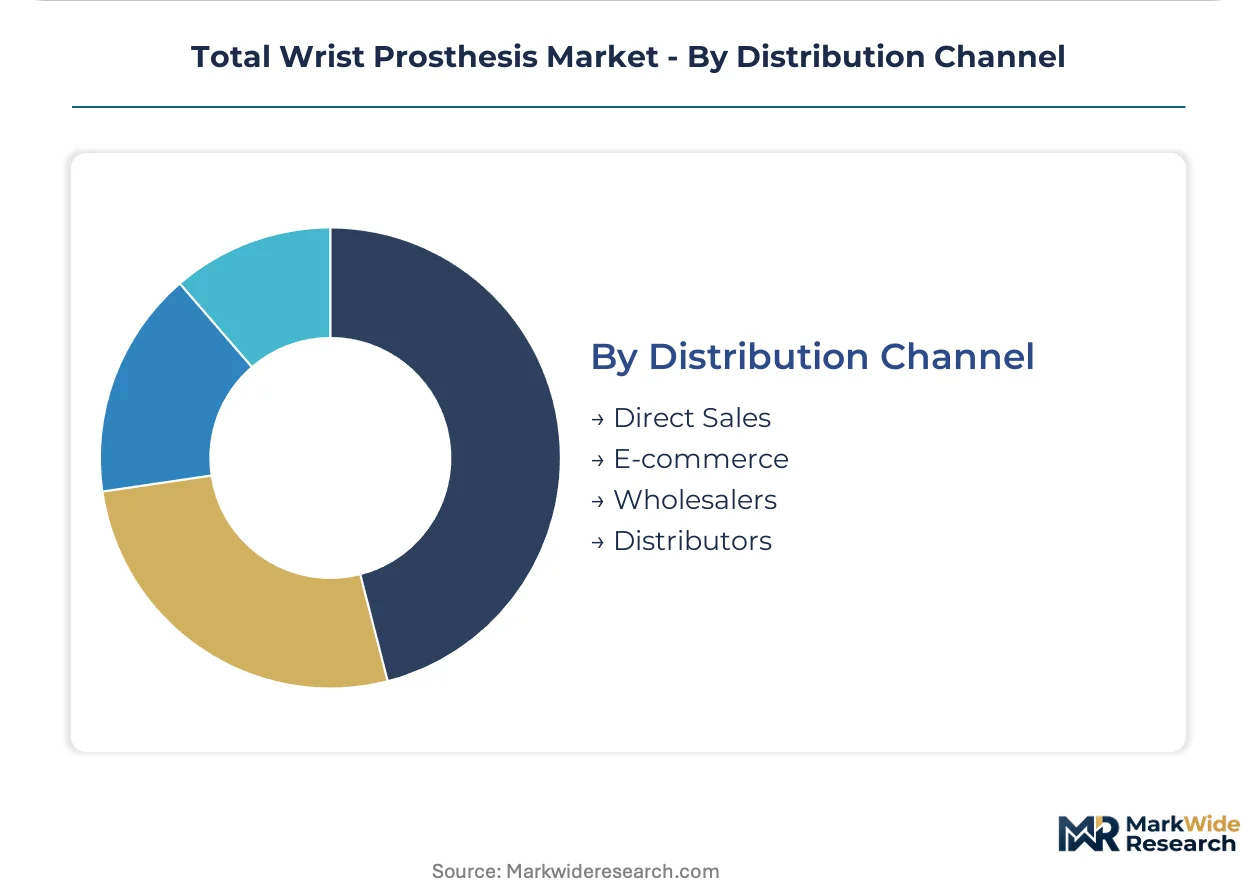
Distribution Channel:
Supply concentration dictates margin capture, with direct sales preserving manufacturer pricing power while distributor networks extend geographic reach at compressed economics.
- Direct Sales:Manufacturer-employed representatives managing surgeon relationships and case coverage. Stryker and Zimmer Biomet deploy this model exclusively for high-volume United States metropolitan markets.
- E-commerce:Digital procurement platforms for consumables and instrument accessories. German hospital purchasing cooperatives have piloted centralized ordering portals for standard implant configurations.
- Wholesalers:Regional inventory aggregation for mid-tier manufacturers without dedicated sales infrastructure.
- Distributors:Independent agents covering rural Japan and secondary United States markets where procedural volume cannot support direct representation.
Direct Sales commands premium positioning; E-commerce shows steepest expansion trajectory on procurement automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's statutory health insurance system, where standardized reimbursement codes reward decade-long surveillance data, while United States ambulatory surgery centers compete on operative time compression and same-day discharge economics.
United States
Orthopedic clinics in Florida and Arizona are building dedicated wrist arthroplasty capacity where aging populations and favorable payer mixes coincide. FDA 510(k) substantial equivalence pathways favor modular designs with established predicate devices. Academic medical centers in Boston and Baltimore maintain the highest procedural volumes for complex post-traumatic reconstructions.
Germany
German notified bodies enforce EU MDR Article 10 technical documentation mandates most strictly, extending CE marking timelines by 12-18 months for ceramic bearing innovations. Statutory health insurance reimbursement codes concentrate demand in fixed implant configurations with proven longevity data. The statutory health insurance system rewards standardized designs over adjustable systems.
Japan
Rural prefectures with 35%+ population over 65 present concentrated demand for motion-preserving alternatives to wrist arthrodesis. Japan's PMDA has cleared two ceramic-on-polyethylene systems, creating demand concentration in Tokyo and Osaka academic medical centers. Super-aging demographics in Kyushu and Tohoku regions justify dedicated sales force deployment.
United Kingdom
NHS procurement frameworks unbundle implant pricing from instrumentation, shifting vendor selection toward component-level cost transparency. Value analysis committees now dominate contract negotiations previously managed by individual surgeons. London teaching hospitals maintain revision surgery capability that anchors regional referral patterns.
Switzerland
Swissmedic enforces ISO 5832 alloy documentation requirements that extend approval timelines for forged versus cast cobalt-chrome variants. Premium pricing tolerance supports ceramic bearing adoption where wear debris concerns drive surgeon preference. Zurich and Geneva academic centers anchor demand for patient-specific instrumentation derived from preoperative CT.
Total Wrist Prosthesis Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated manufacturers commanding premium positioning through captive forging capacity while component assemblers compete on procurement automation and distributor reach. The vendor base organizes around three strategic archetypes: diversified orthopedic conglomerates with extremities divisions, specialized hand surgery device firms, and regional component suppliers without direct sales infrastructure. Dominant competitive moves include backward integration into cobalt-chrome forging and direct-to-clinic distribution bypassing hospital procurement committees.
Among diversified orthopedic conglomerates, Zimmer Biomet, Stryker, and Johnson & Johnson occupy positions that exemplify scale-driven competitive dynamics. Zimmer Biomet represents the integrated manufacturing archetype with in-house production capabilities. Stryker exemplifies R&D intensity sustained through dedicated divisional structures. Johnson & Johnson, operating through DePuy Synthes, anchors the broad portfolio archetype where cross-subsidization supports wrist-specific development. These three entities collectively represent the premium-tier positioning that hospital procurement committees and integrated delivery networks prioritize for inventory consolidation.
| Leading Market Players |
|---|
| Zimmer Biomet |
| Stryker |
| Johnson & Johnson |
| Smith+Nephew |
| DePuy Synthes |
| Arthrex |
| Integra LifeSciences |
| Acumed |
| Enovis |
| Others |
Value Network & Pricing Analysis
Cobalt-chrome forging capacity utilization at integrated manufacturers shapes both supply concentration and price floors for carpal components, compressing margins for assemblers without captive metalworking while sustaining premium positioning for Zimmer Biomet and Stryker in hospital procurement negotiations.
Pricing Analysis
The customization-premium spread separates modular system pricing from fixed implant configurations, with intraoperative adjustability commanding substantial premiums over standardized geometries. Pricing stratifies across premium ceramic bearings, standard cobalt-chrome modular systems, and economy fixed designs where statutory reimbursement codes cap recoverable costs. Cost compression in fixed implant tiers is intensifying because German statutory health insurance rewards decade-long surveillance data over technical innovation. Orthopedic clinics in United States ambulatory settings exhibit highest price sensitivity due to same-day discharge economics, while academic medical centers in Boston and Baltimore prioritize longevity claims over unit cost.
Supply Chain Analysis
Inbound logistics costs for cobalt-chrome alloy feedstock fluctuate with aerospace sector demand cycles, exposing component assemblers to margin volatility when Rotterdam or Hamburg port congestion delays forged billet delivery. Supply concentrates in Germany for precision forging, Switzerland for ceramic bearing finishing, and United States for polyethylene machining. Raw material dependencies center on cobalt-chrome alloys per ISO 5832-4, alumina ceramic substrates, and ultra-high molecular weight polyethylene resin. Single-source vulnerability pervades precision forging capacity for carpal plates. Distribution runs through direct sales representatives in metropolitan United States markets, with independent distributors covering rural Japan and secondary European regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward hospital procurement committees and integrated delivery networks, consolidating vendor selection authority previously held by individual surgeons and compressing pricing leverage for manufacturers without scale-backed contract negotiation resources.
For Market Incumbents: Fortify backward integration into cobalt-chrome forging to defend margin stability against aerospace-driven input volatility, while deepening direct-to-clinic distribution relationships that bypass hospital value analysis committees. Threat substitution from patient-specific instrumentation and 3D-printed implants demands accelerated R&D in CT-derived surgical planning tools. Capacity addition in Germany's notified body corridor reduces EU MDR approval timeline exposure. For New Entrants and Emerging Players: Lead with ceramic-on-polyethylene hybrid bearings targeting Japan's super-aging prefectures where wear debris concerns and PMDA clearance pathways create accessible entry points. The most penetrable segment spans rural orthopedic clinics in Kyushu and Tohoku regions underserved by direct sales infrastructure. A go-to-market angle anchored in proctored surgeon training programs addresses the talent scarcity barrier for complex revision cases. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors component assemblers with forged cobalt-chrome supply agreements and pending EU MDR technical documentation, as ceramic bearing innovations face 12-18 month CE marking delays that compress near-term revenue recognition. Long-term viability across the analysis window hinges on ambulatory surgery center site-of-service migration and motion-preserving indication expansion beyond rheumatoid arthritis. The acquisition target archetype combines precision forging capability with direct clinic relationships. The signal to watch is FDA 510(k) clearance velocity for modular systems with patient-specific instrumentation compatibility, indicating which platforms will capture ambulatory throughput growth.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Accelerates CE marking timelines for ceramic bearing innovations in German notified body corridors. |
| Direct-to-Clinic Distribution Buildout | Bypasses hospital procurement committees in United States integrated delivery networks. |
| Patient-Specific Instrumentation Development | Compresses operative time for ambulatory surgery centers adopting same-day discharge protocols. |
| Cobalt-Chrome Forging Backward Integration | Insulates margin stability from aerospace sector demand-driven raw material volatility. |
| Japan Rural Sales Force Deployment | Captures concentrated demand in super-aging prefectures with 35%+ population over 65. |
Research Methodology
The analysis maps fixed, adjustable, flexible, and modular implant architectures, each validated through hand surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, CMS Medicare reimbursement determinations, and hospital procurement contract records. Bottom-up procedure volume estimates and top-down manufacturer revenue triangulation anchored market sizing.
Consistency checks validated volume and value outputs against external benchmarks across the modeling period. The analytical framework modeled segmentation dimensions including implant architecture, bearing material specification, end-user clinical setting, and geographic regulatory cluster. CAGRs derived from procedure volume elasticity to aging demographic penetration and reimbursement code expansion. Industry-specific forecast inputs incorporated EU MDR notified body queue duration and ambulatory surgery center capacity buildout rates.
Forecasts assume regulatory continuity in FDA 510(k) substantial equivalence pathways and EU MDR Article 10 technical documentation mandates; material policy shifts would require re-modeling. Specific risk factors that could revise forecasts include cobalt-chrome price spikes, notified body capacity constraints extending CE marking timelines, and CMS reimbursement determination changes for total wrist arthroplasty codes. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Vertebroplasty Needles Market
Orthopedic Devices
Kyphoplasty Market
Orthopedic Devices
Europe Kyphoplasty Market
Orthopedic Devices
Orthopedic Joint Reconstruction Market
Orthopedic Devices
Spinal Implants and Devices Market
Orthopedic Devices
Shoulder Arthroplasty Market
Orthopedic Devices
France Neurology Devices Market
Orthopedic Devices
Global Joint Replacement Market
Orthopedic Devices
Patient Lifts Market
Orthopedic Devices
Orthopedic Pedicle Screw Market
Orthopedic Devices
Knee Implants Market
Orthopedic Devices
Non-Operative Spine Care Market
Orthopedic Devices
Small Bone and Joint Orthopedic Devices Market
Orthopedic Devices
Europe Knee Cartilage Repair Market
Orthopedic Devices
Bone Void Fillers Market
Orthopedic Devices
Orthopaedic Cushions Market