
 Antibiotic-Loaded Bone Cement Market | 2026-2036
Antibiotic-Loaded Bone Cement Market Size, Share, and Industry Trends Forecast 2026-2036
Antibiotic-Loaded Bone Cement Market Analysis
Preventive maintenance contracts and software-enabled inventory tracking is restructuring how orthopedic cement portfolios are sold to hospital systems. Stryker leverages its integrated trauma and reconstruction platforms to bundle cement with implant systems. Zimmer Biomet anchors its position through specialized delivery devices that pair with antibiotic-loaded formulations. Heraeus Medical differentiates via deep expertise in polymethyl methacrylate chemistry and European manufacturing scale.
Antibiotic-loaded bone cement consists of a polymer matrix—typically polymethyl methacrylate—impregnated with heat-stable antibiotics such as gentamicin or tobramycin, which elute locally at surgical sites to prevent prosthetic joint infection. The material cures in situ through an exothermic polymerization reaction, achieving compressive strengths exceeding 70 MPa while maintaining elution kinetics over 72 hours post-implantation. Polymethyl methacrylate formulations dominate current revenue owing to decades of clinical validation and established reimbursement pathways, though hydroxyapatite composites are gaining traction in spine applications where osteointegration properties matter. Orthopedic surgery remains the largest application segment by volume, while trauma surgery represents the fastest-growing indication as open fracture protocols increasingly mandate antibiotic prophylaxis at the fixation site.
FDA 510(k) requirements and the EU Medical Device Regulation impose distinct compliance burdens on manufacturers seeking dual-market access, with the MDR's enhanced clinical evidence standards lengthening conformity assessment timelines for antibiotic-eluting devices. The EPA monitors volatile methyl methacrylate monomer emissions from manufacturing facilities, particularly affecting production economics at US-based plants. Stakeholders must monitor how evolving FDA guidance on combination products reclassifies certain high-dose antibiotic cements, as this determination will reshape competitive positioning and capital allocation across the sector.
Market Dynamics
Orthopedic cement manufacturers face escalating pressure from the FDA's evolving combination product classification framework, which threatens to reclassify high-antibiotic-load formulations as drug-device combinations requiring premarket approval rather than 510(k) clearance.
Growth Catalysts
- Revision Surgery Volumes:Aging primary joint replacements in the United States are generating sustained demand for infection-prophylactic cement in revision arthroplasty procedures.
- EU MDR Clinical Evidence Standards:Enhanced post-market surveillance requirements under the Medical Device Regulation are consolidating market share among established manufacturers with robust clinical portfolios.
- Gentamicin Elution Kinetics:Optimized polymerization chemistry now sustains therapeutic antibiotic concentrations at surgical sites for 72-hour windows, expanding prophylactic indications.
Market Restraints
- Methyl Methacrylate Monomer Volatility:EPA emissions monitoring at US production facilities elevates compliance costs and constrains domestic manufacturing capacity expansion.
- Heat-Stable Antibiotic Supply Concentration:Gentamicin and tobramycin API sourcing concentrates among Asian pharmaceutical manufacturers, exposing formulators to input cost fluctuations.
- Mechanical Strength Trade-offs:Elevated antibiotic loading above 2 grams per 40-gram cement unit compromises compressive strength below orthopedic load-bearing thresholds.
Strategic Opportunities
- Spine Fusion Applications:Hydroxyapatite-composite cements with osteointegration properties are penetrating cervical and lumbar interbody fusion procedures previously served by allograft.
- Trauma Fixation Protocols:Open fracture management guidelines increasingly mandate local antibiotic delivery at the fixation site, expanding addressable volume beyond joint reconstruction.
- Preventive Maintenance Contracting:Software-enabled inventory tracking systems enable cement bundling with implant systems through consignment-based hospital supply arrangements.
Industry Challenges
- Polymerization Chemistry Expertise Gap:Formulation scientists capable of balancing elution kinetics with mechanical performance remain scarce relative to expansion targets.
- Dual 510(k) and PMA Pathway Complexity:Manufacturers face capital allocation uncertainty as FDA deliberates combination product classification thresholds for next-generation high-load formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antibiotic-Loaded Bone Cement Market |
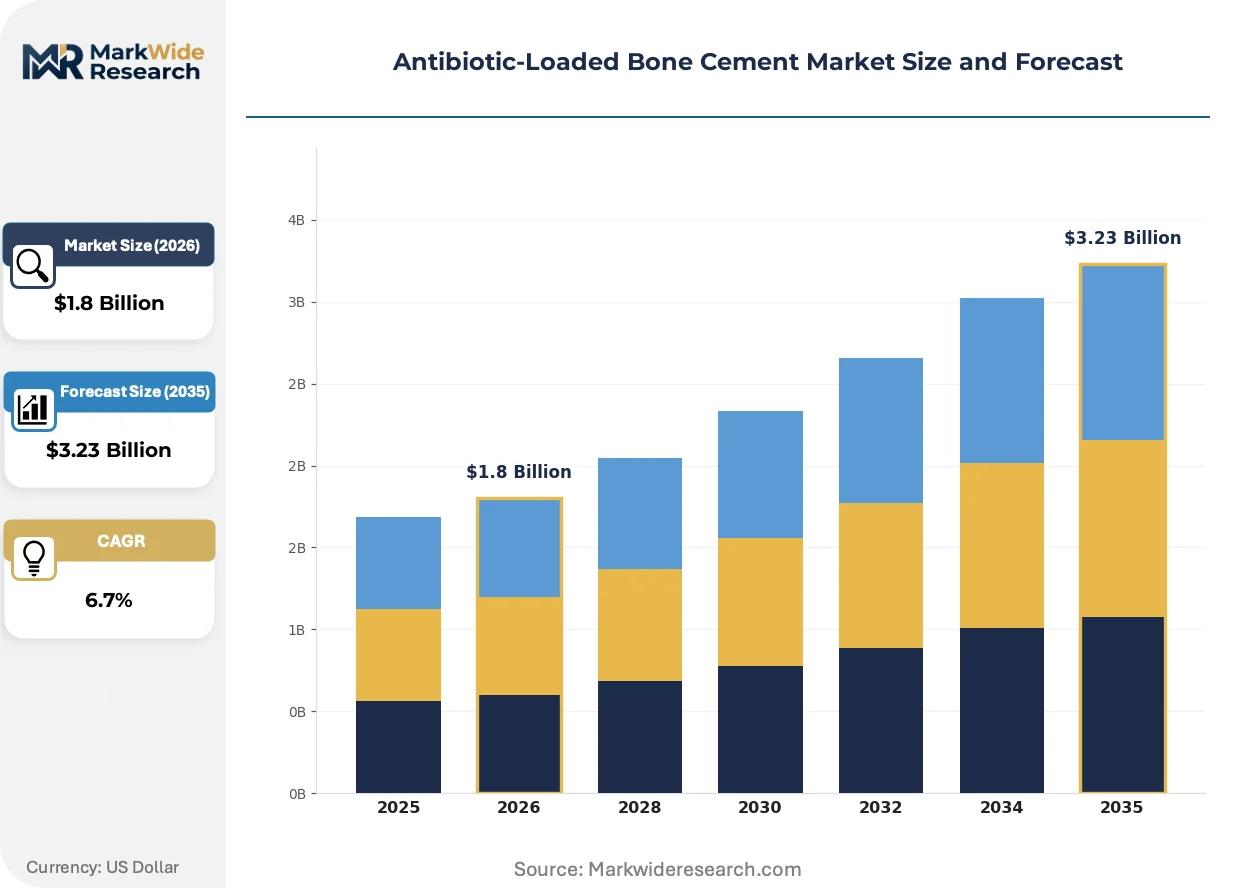
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymethyl Methacrylate, Calcium Sulfate, Hydroxyapatite, Others Application: Orthopedic Surgery, Trauma Surgery, Spine Surgery, Dental Surgery End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions Distribution Channel: Direct Sales, Medical Distributors, Online Platforms, Wholesalers |
| Companies Covered | Stryker, Zimmer Biomet, Heraeus Medical, DePuy Synthes, Smith+Nephew, DJO Global, Tecres, G21, Exactech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antibiotic-Loaded Bone Cement Market Emerging Trajectories
Antibiotic-loaded bone cement is undergoing material science evolution as manufacturers balance elution performance against mechanical integrity, while regulatory frameworks on both sides of the Atlantic impose divergent evidentiary burdens.
Copal bone cement with gentamicin and clindamycin dual-antibiotic loading is absorbing demand from single-agent formulations in revision knee and hip arthroplasty. European orthopedic departments are adopting these enhanced-elution systems for high-risk patient cohorts. The technology is absorbing market share previously held by systemic prophylaxis protocols, compressing the addressable window for intravenous antibiotic regimens.
REACH authorization requirements for methyl methacrylate monomer are tightening substance volume tracking across EU manufacturing facilities. German and French producers must now submit comprehensive exposure assessments to ECHA as a condition of continued production authorization. Medium-scale formulators without dedicated regulatory affairs infrastructure are consolidating or exiting rather than absorbing compliance costs.
Hospital procurement departments are consolidating orthopedic cement purchasing through integrated delivery network contracts that bundle cement with reconstruction implants and trauma hardware. Independent distributors are losing shelf space as Stryker and Zimmer Biomet deploy direct-to-OR consignment models with real-time usage tracking. This channel compression is most advanced in United States metropolitan hospital systems with centralized supply chain governance.
Antibiotic-Loaded Bone Cement Market Segmentation
Antibiotic-loaded bone cement exhibits divergent manufacturing economics across material chemistries, while surgical application requirements reshape procurement patterns among end users. Understanding these segment boundaries clarifies where formulation investments concentrate and which delivery channels capture margin.
Product Type:
Capital intensity varies sharply by chemistry, with polymerization infrastructure and regulatory validation timelines determining which formulations attract sustained manufacturer investment.
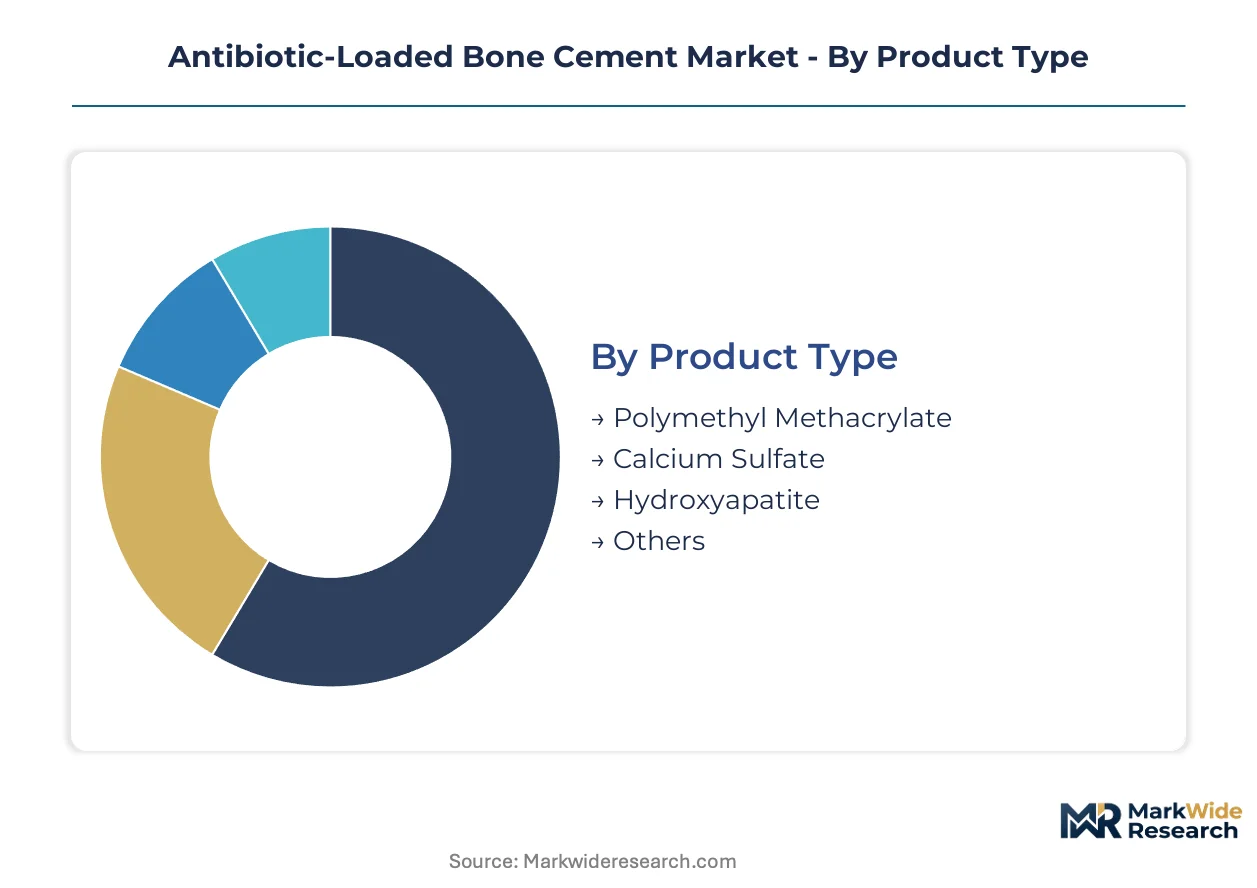
- Polymethyl Methacrylate:The exothermic polymerization of methyl methacrylate monomer yields compressive strengths exceeding 70 MPa, with gentamicin elution sustained over 72-hour therapeutic windows. Demand concentrates in United States tertiary hospitals performing revision knee and hip arthroplasty, where FDA 510(k) clearance pathways and established reimbursement codes reduce commercial friction. This chemistry absorbs the bulk of installed capacity; Hydroxyapatite is expanding most quickly.
- Hydroxyapatite:Calcium phosphate composites integrate osteoconductive mineral phases with antibiotic delivery, enabling direct bone apposition without fibrous encapsulation. Spine fusion procedures in German and French orthopedic departments are absorbing volume as ECHA REACH authorization requirements for methyl methacrylate monomer elevate compliance costs for conventional alternatives.
- Calcium Sulfate:Resorbable matrices provide rapid antibiotic release with complete dissolution within 4-6 weeks, suited to temporary void filling in trauma applications.
- Others:Bioactive glass and collagen-based carriers occupy niche indications where resorption kinetics or handling properties override mechanical load-bearing requirements.
Polymethyl Methacrylate absorbs the bulk of installed capacity; Hydroxyapatite is expanding most quickly.
Application:
Surgical volume distribution follows procedure reimbursement economics and infection risk profiles, with revision arthroplasty commanding premium cement formulations.
- Orthopedic Surgery:Primary and revision joint replacement procedures utilize antibiotic-loaded cement for prosthetic fixation and local infection prophylaxis. United States Medicare reimbursement for diagnosis-related groups 470-471 sustains demand for high-antibiotic-load formulations in knee and hip arthroplasty. Orthopedic Surgery absorbs the bulk of installed capacity; Trauma Surgery is climbing the fastest.
- Trauma Surgery:Open fracture management protocols increasingly mandate local antibiotic delivery at fixation sites, with the AO Foundation's guidelines driving adoption in Level I trauma centers. German and Austrian emergency departments are expanding use in compound tibial fractures where systemic prophylaxis proves insufficient.
- Spine Surgery:Interbody fusion cages and pedicle screw augmentation employ hydroxyapatite-composite cements to enhance osteointegration while preventing deep surgical site infection.
- Dental Surgery:Periodontal defect filling and implant site preparation utilize lower-volume antibiotic cement applications with distinct regulatory pathways through dental device classifications.
Orthopedic Surgery absorbs the bulk of installed capacity; Trauma Surgery is climbing the fastest.
End User:
Procurement sophistication and inventory management capabilities segment the customer base, with integrated delivery networks capturing volume through consignment arrangements.
- Hospitals:Tertiary medical centers with centralized supply chain governance negotiate bundled contracts cementing reconstruction implants with antibiotic-loaded formulations. United States metropolitan health systems with orthopedic service line management deploy real-time usage tracking to optimize consignment inventory. Hospitals absorb the bulk of installed capacity; Ambulatory Surgical Centers are gaining share fastest.
- Ambulatory Surgical Centers:Outpatient joint replacement growth in United States Medicare-certified facilities is driving demand for pre-mixed, single-dose cement presentations that minimize waste and simplify storage.
- Specialty Clinics:Orthopedic-focused ambulatory practices in Germany and Switzerland purchase through regional medical distributors with specialized cold-chain logistics for temperature-sensitive formulations.
- Research Institutions:Academic medical centers with biomechanical testing facilities evaluate next-generation elution kinetics and polymerization chemistry for manufacturer-sponsored clinical trials.
Hospitals absorb the bulk of installed capacity; Ambulatory Surgical Centers are gaining share fastest.
Distribution Channel:
Channel economics reflect inventory carrying costs and the technical service requirements of cement handling and mixing protocols.
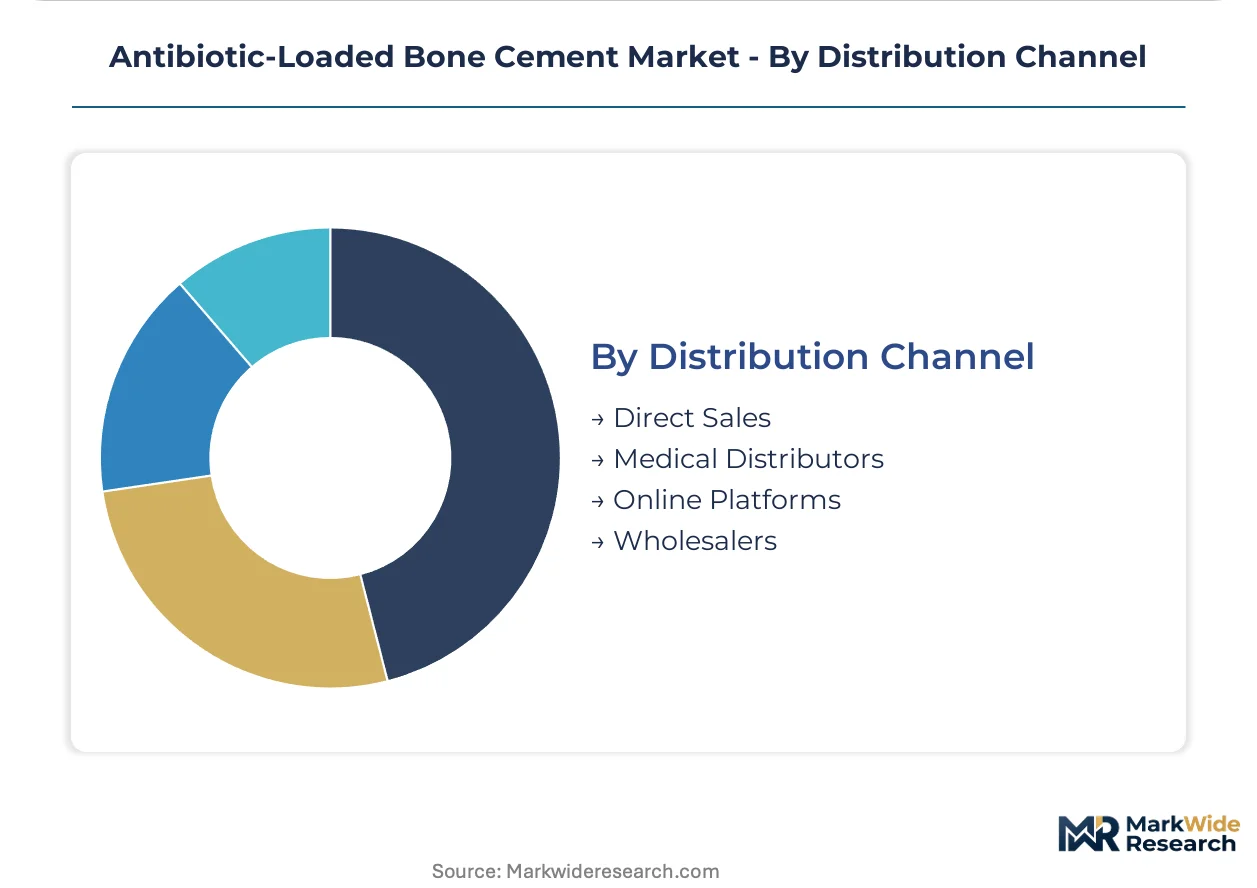
- Direct Sales:Manufacturer field representatives provide on-site technical support for mixing systems and delivery devices, capturing premium pricing in high-volume United States hospital systems with exclusive vendor agreements. Direct Sales absorbs the bulk of installed capacity; Online Platforms are expanding most rapidly.
- Medical Distributors:Regional specialists with orthopedic implant logistics expertise serve mid-tier hospitals and ambulatory surgical centers lacking dedicated supply chain infrastructure.
- Online Platforms:E-procurement portals are penetrating European hospital purchasing consortia seeking price transparency and consolidated invoicing across multiple cement SKUs.
- Wholesalers:Broad-line distributors handle commoditized, low-antibiotic-load formulations for smaller clinics with intermittent demand patterns.
Direct Sales absorbs the bulk of installed capacity; Online Platforms are expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Germany and the United States, while consumption tilts toward aging populations in Western Europe and North America. Manufacturing economics favor established polymethyl methacrylate chemistry hubs with integrated regulatory affairs infrastructure.
United States
Medicare reimbursement for diagnosis-related groups 470-471 sustains demand for high-antibiotic-load formulations in knee and hip arthroplasty. The FDA's evolving combination product classification framework threatens to reclassify certain formulations as drug-device combinations requiring premarket approval. Tertiary hospital systems in metropolitan areas deploy real-time usage tracking to optimize consignment inventory.
Germany
REACH authorization requirements for methyl methacrylate monomer tighten substance volume tracking across manufacturing facilities. German producers submit comprehensive exposure assessments to ECHA as a condition of continued production authorization. Orthopedic departments in university hospitals adopt dual-antibiotic loading systems for high-risk revision cohorts.
France
ANSM post-market surveillance requirements align with EU MDR enhanced clinical evidence standards, consolidating procurement toward established manufacturers. French emergency departments expand antibiotic-loaded cement use in compound tibial fractures per AO Foundation protocols. The Paris and Lyon hospital clusters drive standardization of delivery device specifications.
United Kingdom
NICE guidelines on prosthetic joint infection prophylaxis influence cement selection in NHS Trust orthopedic units. The Medicines and Healthcare products Regulatory Agency monitors combination product classifications alongside FDA developments. Greater Manchester and London teaching hospitals pilot software-enabled inventory tracking for implant-cement bundles.
Japan
PMDA consultation procedures for drug-device combination products create parallel regulatory complexity to FDA pathways. Japan's aging demographic generates revision surgery volumes comparable to Western markets. The Kansai region's medical device manufacturing corridor supplies regional orthopedic centers with specialized delivery systems.
Antibiotic-Loaded Bone Cement Market Vendor Landscape
Top-tier vendors anchor integrated trauma and reconstruction platforms, while mid-scale European specialists concentrate on polymethyl methacrylate chemistry depth. The vendor base stratifies across three archetypes: diversified orthopedic conglomerates with bundling capabilities, regional cement specialists with formulation expertise, and implant manufacturers seeking backward integration into cement supply. Competitive moves center on consignment-based hospital supply arrangements and dual-antibiotic formulation differentiation.
Within the diversified orthopedic tier, Stryker and Zimmer Biomet occupy positions exemplifying platform bundling strategies. Heraeus Medical represents the European specialist archetype with deep polymerization chemistry capabilities. These three anchors demonstrate how competitive positioning diverges between scale-driven integrated systems and focused formulation expertise.
| Leading Market Players |
|---|
| Stryker |
| Zimmer Biomet |
| Heraeus Medical |
| DePuy Synthes |
| Smith+Nephew |
| DJO Global |
| Tecres |
| G21 |
| Exactech |
| Others |
Supply Flow & Price Mechanics
Methyl methacrylate monomer spot price volatility cascades through antibiotic-loaded bone cement supply chains, compressing margins for formulators lacking backward integration into polymer feedstock while amplifying pricing power for integrated manufacturers with captive monomer supply.
Pricing Analysis
Cost-down pressure on standard-grade formulations accelerates because Asian API concentration exposes non-integrated manufacturers to gentamicin and tobramycin price swings. Three-tier pricing structure across premium dual-antibiotic, standard single-agent, and economy low-load levels separates formulations by elution duration and mechanical certification. Price differentiation hinges on FDA 510(k) clearance tier and ECHA REACH compliance status. Ambulatory surgical centers exhibit acute price sensitivity versus tertiary hospital systems with consignment-based procurement.
Supply Chain Analysis
Domestic-content mandates in United States defense-proximate healthcare procurement are reshaping sourcing toward North American methyl methacrylate producers. Manufacturing gravity centers on Germany, the United States, and Japan, with each hub feeding regional demand clusters. Formulation draws from heat-stable antibiotic APIs concentrated among Asian pharmaceutical manufacturers, methyl methacrylate monomer from petrochemical corridors, and hydroxyapatite from mineral processing facilities. Single-source vulnerability in gentamicin API supply exposes blenders to input disruption. Distribution runs through direct manufacturer-to-hospital consignment models with real-time inventory tracking.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Antibiotic-loaded bone cement is becoming a vertical-integration race as manufacturers pursue captive control over polymethyl methacrylate polymerization chemistry to defend margin structure against API cost volatility.
For Market Incumbents: Deepen backward integration into methyl methacrylate monomer production or secure long-term offtake agreements with German and United States petrochemical suppliers to insulate against feedstock price spikes. Expand high-load dual-antibiotic formulation capacity ahead of potential FDA reclassification that would disadvantage non-integrated competitors unable to absorb PMA pathway costs. For New Entrants and Emerging Players: Begin with hydroxyapatite-composite spine applications in German and French university hospitals where ECHA REACH compliance costs are displacing conventional polymethyl methacrylate suppliers. Target trauma fixation protocols in Level I centers adopting AO Foundation open fracture guidelines, leveraging resorbable calcium sulfate matrices as a differentiated entry point with lower regulatory burden. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale European cement specialists with validated polymerization chemistry and ECHA authorization infrastructure in Germany and France. Watch FDA combination product classification deliberations as the inflection signal determining whether high-load formulations require PMA investment or remain 510(k)-eligible.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Antibiotic Formulation Development | Copal cement with gentamicin-clindamycin loading captures revision arthroplasty volume from single-agent alternatives. |
| Consignment Inventory Systems | Software-enabled usage tracking binds hospital systems to integrated implant-cement bundles with exclusive vendor terms. |
| ECHA REACH Authorization Investment | Comprehensive exposure assessment submission preserves production authorization for methyl methacrylate facilities in Germany and France. |
| Trauma Fixation Protocol Expansion | AO Foundation guideline alignment opens compound fracture applications beyond traditional joint reconstruction markets. |
| Hydroxyapatite Composite Scale-Up | Osteoconductive mineral phase integration addresses spine fusion demand as REACH costs disadvantage conventional alternatives. |
Methodological Framework
Document review covered FDA 510(k) filings, EMA MDR technical documentation, ECHA REACH authorization records, and hospital procurement database extracts, complemented by interviews with orthopedic surgeons, biomedical engineers, hospital GPO contracts managers, and cement formulation scientists. Secondary validation drew from CMS Medicare reimbursement schedules, AO Foundation clinical guidelines, and SEC manufacturer disclosures. Bottom-up procedure volume estimates and top-down manufacturer revenue analysis were triangulated to constrain segment sizing.
Unit demand and revenue projections across the analysis window reflect modeled segmentation by material chemistry, surgical application, end-user facility type, and distribution channel structure. CAGRs were derived from orthopedic procedure growth trajectories, revision surgery incidence curves, and antibiotic cement penetration rate assumptions. Forecast inputs incorporated FDA combination product classification scenarios, EU MDR post-market surveillance cost burdens, and ECHA methyl methacrylate authorization timelines.
FDA regulatory reclassification, ECHA substance restriction expansion, and gentamicin API supply disruption are the dominant revision risks that could compress or extend manufacturer revenue trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
North America Single-Use Medical Device Reprocessing Market
Medical Devices
In Vitro Fertilization Monitoring System Market
Medical Devices
Transcatheter Bioprosthesis Market
Medical Devices
Nerve Locator Stimulator Market
Medical Devices
Allografts Market
Medical Devices
Global Nebuliser Market
Medical Devices
Medical Device Films Market
Medical Devices
North America Refractive Surgery Devices Market
Medical Devices
Medical Injection Molding Machine Market
Medical Devices
Global Peripheral Vascular Devices and Accessories Market
Medical Devices
Clinical Trinocular Microscopes Market
Medical Devices
Cardiac Resynchronization Therapy (CRT) Devices Market
Medical Devices
Global Holter ECG Market
Medical Devices
Electrosurgery Devices Market
Medical Devices
Ocular Implants Market
Medical Devices
Lung Preservation Systems Market