
 Hip Resurfacing Implants Market | 2026-2036
Hip Resurfacing Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Hip Resurfacing Implants Market Intelligence
The EU Green Deal's push for sustainable medical device manufacturing is broadening procurement criteria across European hospital systems. Smith & Nephew leverages its Birmingham Hip Resurfacing legacy to sustain brand recognition among orthopedic surgeons. Zimmer Biomet anchors its competitive stance through integrated digital surgical planning platforms that complement implant placement.
Hip resurfacing implants are cobalt-chrome or ceramic femoral components that cap rather than replace the femoral head, preserving proximal bone stock for potential future revision. The devices typically feature diameters of 36–58 mm and require precision reaming of the native femoral head to achieve cemented or cementless fixation. Cementless fixation dominates European product mixes due to demonstrated long-term osseointegration outcomes in registries. Ceramic-on-ceramic technology commands premium positioning for its wear resistance and reduced metal ion release concerns. Osteoarthritis treatment remains the largest application segment, though avascular necrosis therapy represents a faster-growing niche where bone preservation drives clinical preference.
EMA oversight of high-risk implantable devices, combined with national registry mandates from entities such as the UK's National Joint Registry and Germany's Endoprothesenregister, shapes product development priorities and post-market surveillance obligations. The EU MDR's strengthened clinical evaluation requirements are filtering out devices with limited long-term follow-up data. Stakeholders must monitor registry survival curves and revision-rate differentials against total hip arthroplasty benchmarks to justify continued investment in resurfacing technology.
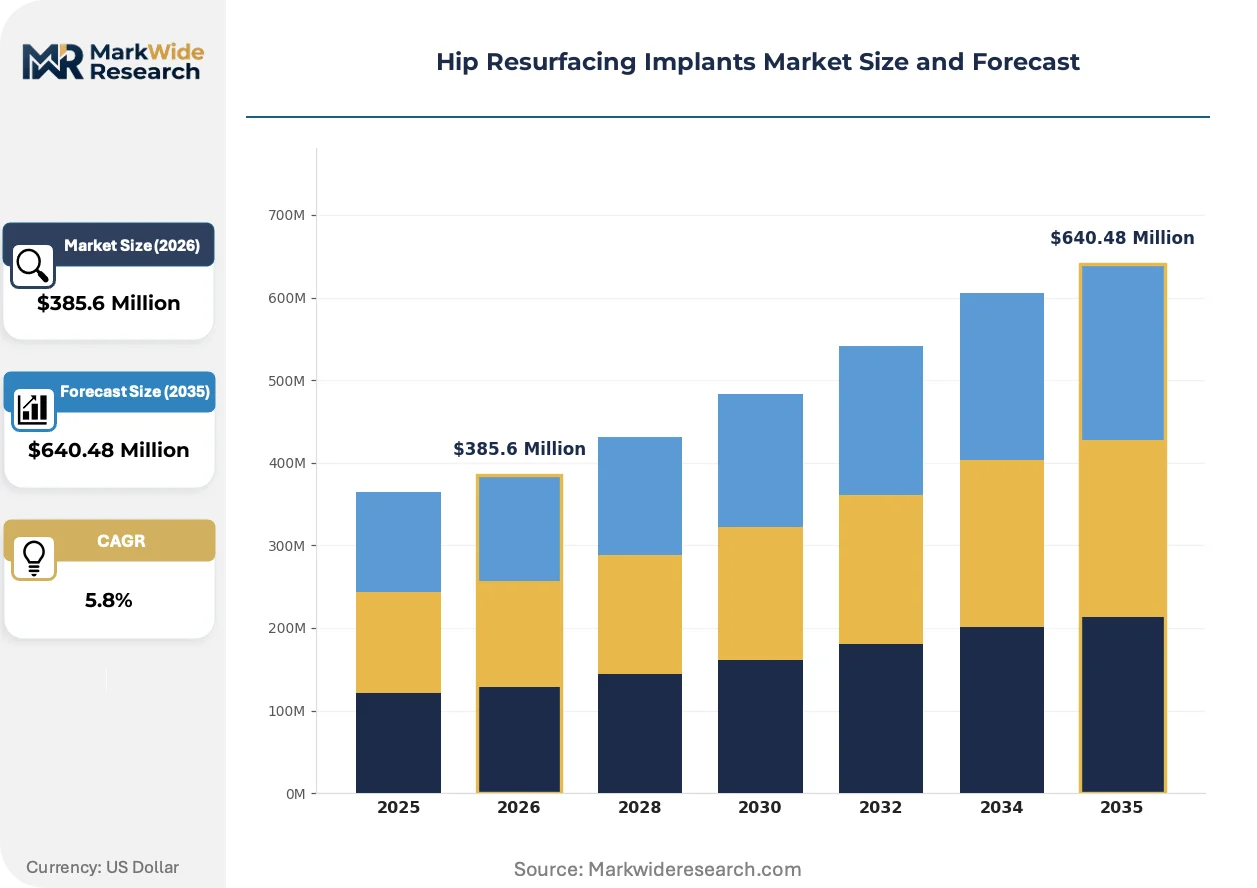
Market Dynamics
The EU MDR's tightened clinical evidence requirements are filtering manufacturer portfolios and elevating registry-linked survival data as the primary competitive currency across European orthopedic markets.
Growth Catalysts
- Younger Patient Demographics:Orthopedic clinics in Germany and the United Kingdom are expanding bone-conserving arthroplasty for active patients under 60 seeking joint preservation options.
- EU Green Deal Procurement Criteria:Sustainable medical device manufacturing standards are broadening hospital system tender requirements and favoring suppliers with verified environmental footprints.
- Ceramic-on-Ceramic Technology:Wear-resistant bearing surfaces with reduced metal ion release are commanding premium positioning in revision-sensitive patient segments.
Market Restraints
- Cobalt-Chrome Supply Concentration:Dependence on specialized alloy foundries creates input cost volatility and geographic supply risk for femoral component manufacturing.
- Technical Precision Requirements:Femoral head reaming tolerances of 0.5 mm demand specialized surgical training and limit addressable surgeon populations.
- Total Hip Arthroplasty Substitution:Established THA procedures with broader indications and simpler technique curves compete for younger patient referrals.
Strategic Opportunities
- Avascular Necrosis Therapy:Bone preservation indications in femoral head collapse cases represent faster-growing clinical preference segments versus osteoarthritis applications.
- Digital Surgical Planning Convergence:Integration of preoperative templating software with robotic-assisted reaming systems is opening precision-placement service models.
- Swissmedic Fast-Track Pathways:Switzerland's streamlined high-risk device evaluation offers accelerated market access for registry-validated implant systems.
Industry Challenges
- Long-Term Registry Data Generation:Fifteen-year survival curves required for MDR compliance demand sustained post-market surveillance infrastructure and patient tracking systems.
- Surgeon Retraining Requirements:Cementless fixation technique mastery and bearing selection protocols require dedicated proctorship programs and cadaveric certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hip Resurfacing Implants Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $640.48 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cemented, Cementless, Hybrid, Modular, Custom-Fitted Technology: Metal-on-Metal, Ceramic-on-Ceramic, Polyethylene Liner, Ceramic-on-Polyethylene, Crosslinked Polyethylene Application: Osteoarthritis Treatment, Rheumatoid Arthritis Management, Traumatic Injury Repair, Avascular Necrosis Therapy, Femoral Head Preservation End User: Orthopedic Clinics, Specialty Surgery Centers, Rehabilitation Facilities, Private Hospitals, Ambulatory Surgical Centers |
| Companies Covered | Smith & Nephew, Zimmer Biomet, DePuy Synthes, Stryker, Corin Group, Wright Medical, Exactech, B. Braun, Arthrex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hip Resurfacing Implants Market Strategic Shifts & Innovations
Ceramic bearing surfaces and digital planning platforms are displacing conventional metal-on-metal systems and freehand surgical techniques across European resurfacing practice.
Ceramic-on-ceramic femoral cap technology is consolidating market positioning for manufacturers seeking differentiation through wear resistance and biocompatibility profiles. Academic medical centers in the Netherlands and Belgium are adopting these systems at accelerated procurement cycles. The technology is consolidating premium pricing tiers and compressing residual demand for metal-on-metal legacy designs.
The EU Medical Device Regulation's strengthened clinical evaluation requirements are mandating fifteen-year implant survival data for continued CE marking. This regulatory pressure is elevating registry participation costs and filtering out devices with limited longitudinal follow-up. High-volume orthopedic centers in Germany and the United Kingdom are responding by concentrating procurement on established registry-tracked suppliers.
Hospital purchasing consortia are consolidating vendor contracts around integrated implant-plus-planning platform bundles. Independent distributors in France and Italy are losing share to manufacturer-direct service models with embedded surgical support. The Benelux region exhibits the most visible concentration of procurement authority within centralized hospital group purchasing organizations.
Hip Resurfacing Implants Market Segmentation
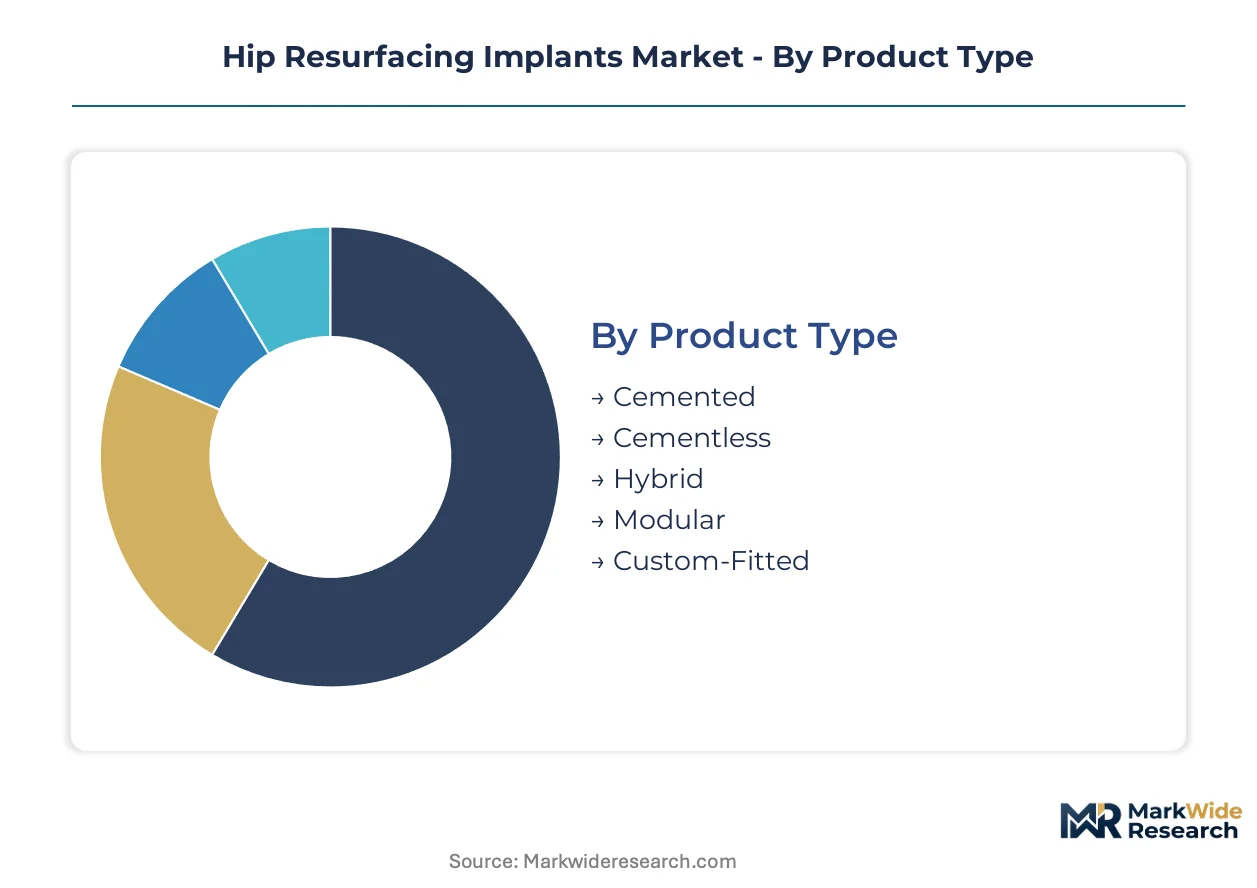
Segmentation in hip resurfacing implants reveals how fixation methods, bearing surfaces, and clinical settings concentrate procurement decisions. Manufacturers align R&D investment and distribution capacity against these dimensions to defend registry-tracked market positions.
Product Type:
Supply concentration for femoral component manufacturing clusters around cementless fixation expertise, with specialized foundries in Germany and the United Kingdom dominating cobalt-chrome casting capacity for porous-coated implants.
- Cemented:Polymethylmethacrylate bone cement achieves immediate fixation through mechanical interlock with cancellous bone. Demand concentrates in French orthopedic clinics where surgeon training programs emphasize cement technique mastery for older patients with compromised bone quality.
- Cementless:Porous-coated cobalt-chrome or titanium constructs achieve biological osseointegration without cement. German and UK registries demonstrate superior long-term survival curves, driving procurement concentration among high-volume academic centers seeking MDR-compliant fifteen-year data.
- Hybrid:Combines cemented femoral cap with cementless acetabular shell for selective fixation optimization.
- Modular:Adjustable neck-shaft angle configurations accommodate anatomical variation in dysplastic hips.
- Custom-Fitted:Patient-specific implants from CT-derived geometries address complex revision scenarios.
Cementless fixation absorbs the bulk of installed capacity; custom-fitted implants are expanding most quickly in revision-sensitive tertiary centers.
Technology:
Cost tier stratification separates premium ceramic bearing systems from standard metal-on-metal and economy polyethylene alternatives, with reimbursement differentials across Benelux hospital systems reinforcing this hierarchy.
- Metal-on-Metal:Cobalt-chrome articulating surfaces deliver durability but face regulatory headwinds from ion release concerns. Netherlands orthopedic centers have phased procurement toward alternative bearings following EMA safety communications.
- Ceramic-on-Ceramic:Alumina or zirconia-toughened alumina bearing pairs minimize wear debris and eliminate metal ion release. Belgian academic hospitals command premium pricing tiers for these systems in active patients under fifty-five.
- Polyethylene Liner:Conventional ultra-high molecular weight polyethylene offers cost-accessible articulation for budget-constrained procurement.
- Ceramic-on-Polyethylene:Hybrid bearing combines ceramic femoral head with polyethylene acetabular liner for intermediate wear performance.
- Crosslinked Polyethylene:Radiation-treated liner material reduces oxidative degradation and wear rates versus conventional polyethylene.
Ceramic-on-ceramic systems command the highest margin tier; crosslinked polyethylene is climbing the fastest as a cost-optimized alternative in volume-driven markets.
Application:
Volume concentration in osteoarthritis treatment creates manufacturing scale advantages, while niche indications in avascular necrosis and femoral head preservation attract specialized product development.
- Osteoarthritis Treatment:Degenerative joint disease in weight-bearing hips constitutes the primary surgical indication. German orthopedic clinics generate the highest procedure volumes, with statutory health insurance reimbursement favoring joint preservation in pre-retirement age cohorts.
- Avascular Necrosis Therapy:Femoral head collapse from vascular compromise demands bone-preserving intervention before subchondral fracture. UK tertiary centers concentrate expertise in this indication, leveraging resurfacing to delay or avoid total hip arthroplasty conversion.
- Rheumatoid Arthritis Management:Inflammatory arthropathy with systemic bone involvement requires careful patient selection.
- Traumatic Injury Repair:Acetabular fracture sequelae or femoral head impaction injuries in younger trauma patients.
- Femoral Head Preservation:Prophylactic resurfacing in developmental dysplasia or pre-collapse avascular necrosis stages.
Osteoarthritis treatment dominates manufacturing throughput; avascular necrosis therapy shows the steepest expansion trajectory as bone preservation protocols gain clinical traction.
End User:
Customer type maturity separates established orthopedic clinics with registry participation infrastructure from emerging ambulatory settings seeking simplified procurement pathways.
- Orthopedic Clinics:Dedicated arthroplasty units with fellowship-trained surgeons and longitudinal patient tracking systems. United Kingdom orthopedic clinics anchor European registry data generation, with National Joint Registry mandates creating high barriers to supplier entry.
- Specialty Surgery Centers:Focused orthopedic facilities with streamlined case volume and standardized implant protocols. Swiss specialty centers leverage Swissmedic fast-track pathways to accelerate adoption of registry-validated systems.
- Rehabilitation Facilities:Post-acute care settings with limited direct implant procurement authority.
- Private Hospitals:Commercial payor environments with flexibility in premium technology selection.
- Ambulatory Surgical Centers:Same-day discharge models requiring simplified instrumentation and rapid recovery protocols.
Orthopedic clinics concentrate the majority of high-complexity resurfacing volume; specialty surgery centers are gaining share fastest through procedure consolidation and direct manufacturer contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Warsaw's orthopedic surgery corridor concentrates Central European demand for bone-conserving arthroplasty, with academic medical centers driving procurement of MDR-compliant implant systems across the continent.
Germany
Endoprothesenregister mandates shape procurement decisions at Berlin and Hamburg academic centers. The Federal Institute for Drugs and Medical Devices enforces fifteen-year survival data requirements for CE marking renewal. Bavarian orthopedic clinics concentrate the highest resurfacing volumes, with statutory health insurance reimbursing joint preservation procedures for pre-retirement cohorts.
United Kingdom
National Joint Registry participation requirements filter supplier entry at London and Birmingham arthroplasty units. The Medicines and Healthcare products Regulatory Agency aligns post-market surveillance with EU MDR transition timelines. Oxford and Cambridge medical centers generate longitudinal survival data that anchors European registry benchmarks.
Netherlands
Academic hospitals in Rotterdam and Utrecht accelerated ceramic-on-ceramic adoption following EMA safety communications on metal ion release. The Healthcare Inspectorate integrates registry outcomes into hospital accreditation criteria. Eindhoven's medical technology cluster supports surgical planning software integration with implant procurement.
Switzerland
Swissmedic fast-track pathways attract registry-validated systems to Zurich and Geneva specialty centers. The Federal Office of Public Health maintains parallel surveillance to EU registries while streamlining high-risk device evaluation. Basel's orthopedic institutes concentrate revision surgery expertise for complex resurfacing indications.
Belgium
Federal Agency for Medicines and Health Products requires implant traceability systems at Leuven and Brussels university hospitals. Belgian academic centers command premium pricing tiers for ceramic bearing systems in patients under fifty-five. Flanders' hospital networks consolidate procurement through centralized group purchasing organizations.
Hip Resurfacing Implants Market Key Industry Players
The competitive structure tilts toward diversified orthopedic conglomerates with registry-tracked legacy portfolios. Market concentration favors manufacturers with fifteen-year survival data and integrated digital surgical planning capabilities. Two strategic archetypes dominate: established arthroplasty specialists with Birmingham Hip Resurfacing heritage, and diversified implant conglomerates leveraging robotic-assisted platform ecosystems. Competitive moves center on M&A consolidation of specialized foundry capacity and strategic partnerships with academic medical centers for post-market surveillance data generation.
Among diversified orthopedic manufacturers, Smith & Nephew and Zimmer Biomet occupy positions shaped by registry participation infrastructure and digital planning integration. Smith & Nephew represents the heritage-driven archetype with established surgeon training networks. Zimmer Biomet exemplifies the platform-integrated approach, anchoring competitive stance through surgical planning software convergence. DePuy Synthes sits within the consolidated conglomerate tier, reflecting Johnson & Johnson's broader orthopedic portfolio scale.
| Leading Market Players |
|---|
| Smith & Nephew |
| Zimmer Biomet |
| DePuy Synthes |
| Stryker |
| Corin Group |
| Wright Medical |
| Exactech |
| B. Braun |
| Arthrex |
| Others |
Cost & Logistics Intelligence
MDR-mandated fifteen-year survival data requirements from orthopedic clinics in Germany and the United Kingdom are forcing manufacturers to absorb elevated registry participation costs, compressing margins on legacy metal-on-metal systems while amplifying pricing power for ceramic-bearing suppliers with validated longitudinal outcomes.
Pricing Analysis
Registry-tracked survival outcomes anchor value-based pricing tiers across European hip resurfacing markets. Pricing stratifies across premium ceramic-on-ceramic, standard metal-on-metal, and economy polyethylene bearing tiers, with certification grade and volume scale as primary differentiation drivers. Cost compression in metal-on-metal segments is intensifying because EMA safety communications have eroded clinician confidence. Ambulatory surgical centers exhibit highest price sensitivity; academic medical centers in Belgium and the Netherlands command lowest sensitivity due to outcome-based procurement mandates.
Supply Chain Analysis
Single-source vulnerability sits with specialized cobalt-chrome foundry capacity concentrated in Germany and the United Kingdom. Raw material dependencies include medical-grade cobalt-chrome alloy, porous titanium coatings, and alumina ceramic blanks. Tariff exposure on specialty alloy imports from non-EU sources amplifies input cost volatility. Distribution runs through manufacturer-direct service models with embedded surgical support, displacing independent distributors in France and Italy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market occupies a technology-transition phase where ceramic-on-ceramic bearing surfaces are displacing metal-on-metal legacy systems, rewarding manufacturers with validated biocompatibility profiles and punishing those dependent on outdated metallurgy.
For Market Incumbents: Extend registry data generation infrastructure to maintain CE marking compliance under EU MDR timelines. Cementless fixation expertise and porous-coating foundry capacity represent defensible moats against emerging competitors lacking fifteen-year survival curves. Backward integration into ceramic bearing manufacturing secures supply continuity as metal-on-metal demand collapses.
For New Entrants and Emerging Players: The gap between premium ceramic-on-ceramic pricing and economy polyethylene tiers creates white-space opportunity in mid-market hybrid bearings. Avascular necrosis therapy applications in UK tertiary centers offer the most penetrable entry point. A go-to-market angle anchored to digital surgical planning platform partnerships bypasses incumbent surgeon training network advantages.
For Investors and Strategic Acquirers: The window for entry favors specialized foundry operators with medical-grade cobalt-chrome casting capabilities and existing porous-coating IP. Long-term viability hinges on ceramic technology transition completion and MDR compliance infrastructure. The signal to watch is National Joint Registry survival curve divergence between ceramic and metal-bearing cohorts.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance anchors market access for registry-validated implant systems. |
| Hospital System Partnership | Academic medical centers in Germany generate longitudinal survival data benchmarks. |
| Software Companion Development | Preoperative templating integration differentiates precision-placement service models. |
| Reimbursement Strategy | Statutory health insurance alignment in Bavaria shapes joint preservation procedure economics. |
| Backward Integration | Captive ceramic bearing production insulates against metal-on-metal demand collapse. |
Research Approach
Independent corroboration across orthopedic surgeon interviews, hospital procurement committee discussions, and regulatory affairs consultations underwrites the qualitative findings. Primary fieldwork engaged arthroplasty specialists, biomedical engineers, GPO contracts managers, and EMA notified body representatives. Secondary validation drew from National Joint Registry datasets, Endoprothesenregister survival curves, EU MDR guidance documents, and hospital procurement database extracts. Bottom-up procedure volume estimates triangulated against top-down implant manufacturer capacity disclosures.
Rate-of-change decomposition separated volume effects from pricing effects across the projection horizon. Segmentation dimensions modeled include fixation method, bearing surface technology, clinical application, and end-user facility type. CAGRs were derived from registry-reported procedure growth rates and implant survival curve extrapolations. Forecast inputs incorporated MDR transition timelines, ceramic technology adoption curves, and Swissmedic fast-track pathway utilization rates.
Underlying measurement precision varies by segment; ceramic-on-ceramic and cementless fixation categories carry tighter precision than legacy metal-on-metal and cemented alternatives due to concentrated registry participation. Forecasts reflect assumptions regarding EU MDR enforcement consistency, cobalt-chrome supply stability, and surgeon retraining program completion rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Orthopedic Prosthetic Devices Market
Orthopedic Devices
US Tendon Repair Market
Orthopedic Devices
Japan Spinal Surgery Devices Market
Orthopedic Devices
Orthopedic Trauma Fixation Devices Market
Orthopedic Devices
Orthopedic Artificial Bone Defect Repair Materials Market
Orthopedic Devices
India Orthopedic Braces and Supports Market
Orthopedic Devices
Pediatrics Orthotics Market
Orthopedic Devices
France Neurology Devices Market
Orthopedic Devices
Middle East and Africa Knee Cartilage Repair Market
Orthopedic Devices
Global Shockwave Therapy Market
Orthopedic Devices
Distal Compression Plates Market
Orthopedic Devices
Small Bone and Joint Orthopedic Devices Market
Orthopedic Devices
Humeral Implant Market
Orthopedic Devices
Bone Void Fillers Market
Orthopedic Devices
Scoliosis Treatment Market
Orthopedic Devices
Physiotherapy Devices Market