
 Global Hip Replacement Implants Market | 2026-2036
Global Hip Replacement Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hip Replacement Implants Market Foresight
Ceramic composite bearing surfaces is pivoting away from conventional metal-on-polyethylene constructs in hip replacement implants, reducing wear debris and extending implant longevity. Zimmer Biomet Holdings leverages its integrated manufacturing network to control costs across titanium alloy and ceramic component lines. Stryker Corporation dominates the robotic-assisted surgical navigation ecosystem that now accompanies implant placement. Smith & Nephew differentiates through its ceramic-on-ceramic portfolio targeting younger, more active patient cohorts.
Hip replacement implants are prosthetic devices designed to replace damaged hip joint structures, typically comprising femoral stems, acetabular cups, and bearing surfaces engineered from titanium alloys, cobalt-chromium alloys, or ceramic composites with tolerances measured in micrometers to ensure proper biomechanical load distribution and osseointegration. Their primary purpose is to restore mobility and alleviate pain in patients with degenerative joint disease or traumatic injury. Cementless implants lead volume due to biological fixation advantages in younger patients, while revision surgery commands premium pricing as complexity and component customization escalate. Ceramic composites represent the fastest-growing material segment as bearing surface innovation shifts toward reduced wear rates and enhanced biocompatibility.
FDA premarket notification pathways and EU MDR conformity assessment requirements shape product development timelines and market access conditions for manufacturers targeting the United States and European markets. ISO 5832 material standards and ASTM F2068 specifications govern titanium alloy chemistry and mechanical properties, creating compliance barriers for new entrants. Japan's PMDA and China's NMPA maintain distinct clinical evidence requirements that fragment regulatory strategy across Asia-Pacific jurisdictions. Stakeholders must monitor ceramic fracture risk data and bearing surface litigation trends as material innovation outpaces long-term clinical validation.
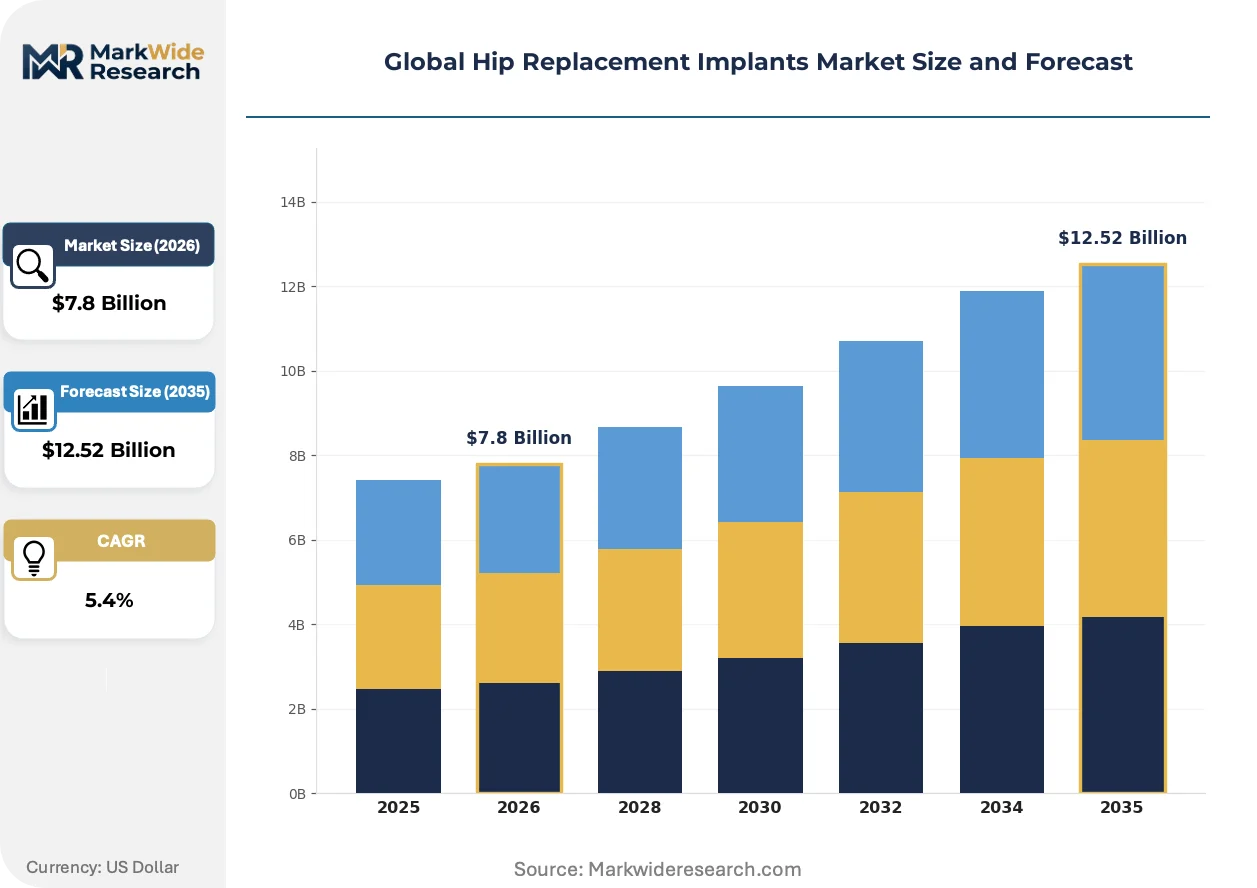
Market Dynamics
Ceramic composite bearing surfaces are consolidating clinical preference as surgeons prioritize implant longevity over initial cost containment, compressing margins for metal-on-polyethylene suppliers while elevating technical barriers for new entrants.
Growth Catalysts
- Japan's PMDA reimbursement clarity:The regulator's streamlined approval pathways for ceramic-on-ceramic constructs accelerate hospital procurement cycles and reduce administrative friction for manufacturers targeting the Japanese market.
- Same-day joint replacement protocols:Ambulatory surgery centers across the United States are expanding adoption of outpatient hip arthroplasty, creating demand for cementless fixation systems optimized for rapid discharge.
- Additive manufacturing of titanium porous structures:3D-printed acetabular shells with engineered osseointegration surfaces are reducing revision rates in younger patient cohorts and expanding addressable demographics.
Market Restraints
- Cobalt-chromium supply concentration:Primary smelting capacity for orthopedic-grade alloys clusters in a limited number of European and Asian suppliers, exposing manufacturers to input volatility and geopolitical disruption.
- Ceramic fracture risk database gaps:Long-term clinical validation for fourth-generation ceramic composites remains incomplete, creating liability exposure and slowing hospital committee approvals.
- EU MDR conformity assessment bottlenecks:Notified body capacity constraints extend product recertification timelines for legacy implants, freezing portfolio refresh cycles and elevating compliance costs.
Strategic Opportunities
- Robotic-assisted surgical navigation convergence:Integration of preoperative planning software with intraoperative implant positioning systems creates bundled service revenue streams and locks in hospital purchasing loyalty.
- India's underpenetrated tertiary care expansion:Private hospital chains in Mumbai, Delhi, and Bangalore are building dedicated arthroplasty centers as medical tourism infrastructure matures.
- Extended reality surgical training mandates:VR-based credentialing requirements for orthopedic residents create aftermarket content and hardware licensing opportunities for implant manufacturers.
Industry Challenges
- Biomechanical engineer talent scarcity:Specialized expertise in tribology and wear simulation remains concentrated at a handful of academic medical centers, constraining R&D velocity for mid-tier competitors.
- Legacy hospital information system integration:Implant tracking and outcomes registry connectivity requires costly middleware development to bridge proprietary EHR architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hip Replacement Implants Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.52 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cemented Implants, Cementless Implants, Hybrid Implants, Modular Implants, Custom Implants Material: Titanium Alloys, Cobalt-Chromium Alloys, Stainless Steel, Polyethylene, Ceramic Composites Application: Osteoarthritis Treatment, Rheumatoid Arthritis Management, Hip Fracture Repair, Avascular Necrosis Therapy, Revision Surgery End User: Orthopedic Clinics, Specialized Surgery Centers, Rehabilitation Facilities, Academic Medical Institutions, Ambulatory Surgery Centers |
| Companies Covered | Zimmer Biomet Holdings, Stryker Corporation, DePuy Synthes, Smith & Nephew, Johnson & Johnson Services, Exactech, MicroPort Scientific Corporation, B. Braun Melsungen, Medacta, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hip Replacement Implants Market Shifts & Advancements
Digital surgical ecosystems are reconfiguring how hip replacement implants are selected, positioned, and monitored, shifting value capture from hardware margins to software-enabled outcome guarantees and longitudinal patient management contracts.
Machine learning algorithms embedded in preoperative planning platforms are automating implant sizing recommendations and predicting optimal bearing surface selection based on patient activity profiles and bone quality metrics. Academic medical centers in Germany and the United States are piloting these systems at scale. The technology is automating what had been surgeon-dependent variability, compressing operative time and reducing revision risk.
The EU MDR's enhanced post-market surveillance requirements are mandating systematic implant registry participation and proactive adverse event reporting across all bearing surface categories. Manufacturers must now maintain dedicated clinical affairs teams in Brussels to manage notified body relationships. Revision surgery components face the steepest compliance burden due to smaller patient cohorts and fragmented long-term data.
Hospital purchasing committees are consolidating vendor relationships around single-source outcome guarantees that bundle implant cost with revision liability coverage. Integrated delivery networks in the United States are leading this transition away from transactional procurement. The shift is most pronounced in Medicare Advantage contracts where capitated reimbursement aligns stakeholder incentives around durability metrics.
Global Hip Replacement Implants Market Segmentation
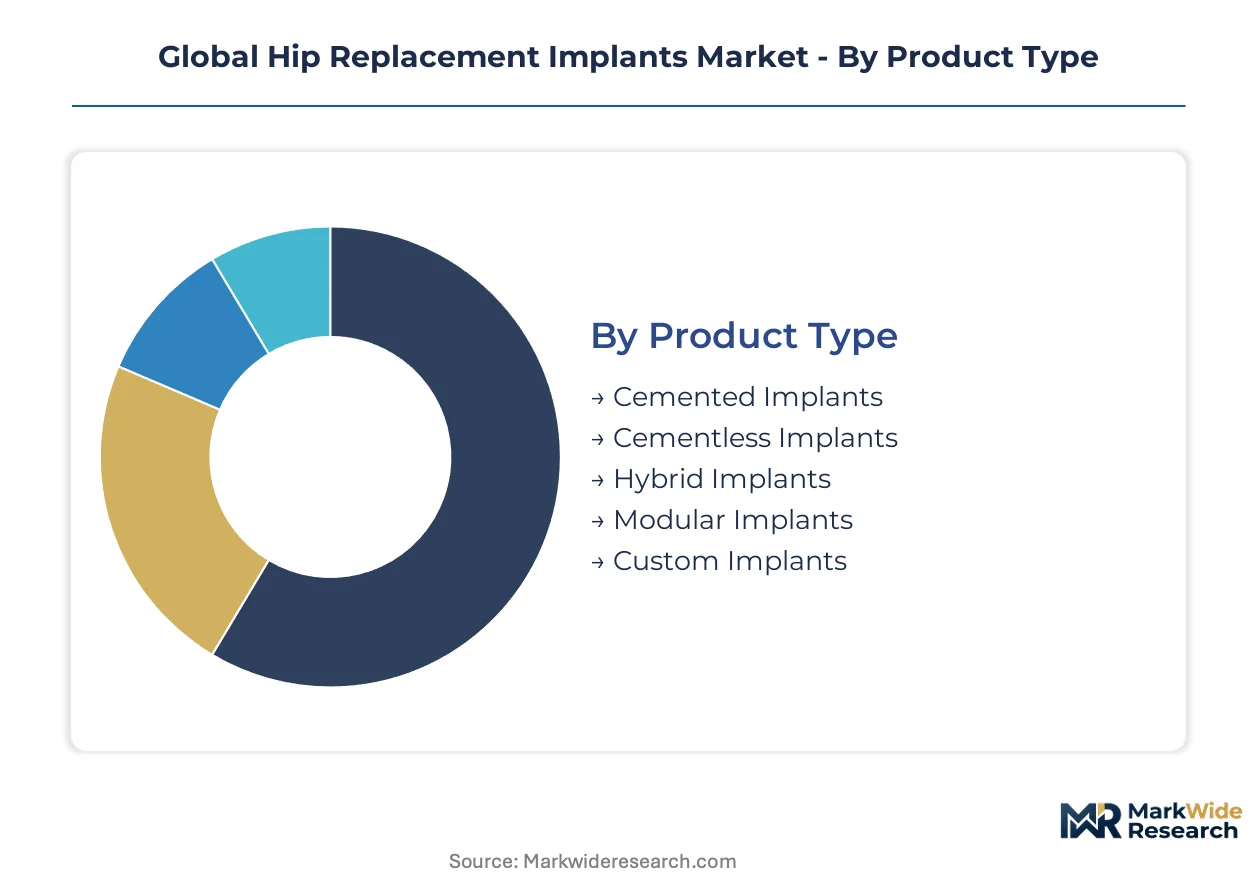
Segmentation in hip replacement implants reflects divergent clinical priorities across patient age, bone quality, and surgical setting. Procurement committees weight initial implant cost against projected revision probability when allocating budget across product categories.
Product Type:
Surgeon preference for fixation method drives hospital formulary decisions and inventory investment levels.
- Cementless Implants:Biological fixation through porous titanium surfaces eliminates cement-related complications and supports faster weight-bearing protocols. Demand concentrates in United States ambulatory surgery centers where same-day discharge protocols favor rapid osseointegration.
- Cemented Implants:Polymethylmethacrylate bone cement provides immediate mechanical stability in osteoporotic bone and elderly patient cohorts. German orthopedic clinics maintain strong procurement volumes given the country's aging demographic profile and established cemented technique training pathways.
- Hybrid Implants:Combines cemented femoral stems with cementless acetabular cups for tailored fixation strategies.
- Modular Implants:Interchangeable neck and head components enable intraoperative flexibility for leg length and offset adjustment.
- Custom Implants:Patient-specific geometries derived from CT imaging address complex anatomical deformities and revision scenarios.
Cementless implants lead on scale; custom implants lead on momentum.
Material:
Material selection determines wear characteristics, biocompatibility profiles, and long-term revision risk calculations.
- Ceramic Composites:Fourth-generation alumina-zirconia blends achieve wear rates below 0.1 millimeters per year with minimal particulate debris generation. Japanese PMDA reimbursement clarity accelerates hospital adoption in Tokyo and Osaka metropolitan surgical networks.
- Titanium Alloys:Ti-6Al-4V ELI chemistry balances strength-to-weight ratios with proven osseointegration performance across porous surface architectures. United States academic medical centers specify titanium for cementless applications requiring extensive bone ingrowth.
- Cobalt-Chromium Alloys:Superior hardness supports bearing surface applications in metal-on-polyethylene constructs.
- Stainless Steel:Cost-effective option for temporary implants and specific revision components.
- Polyethylene:Cross-linked ultra-high molecular weight formulations remain standard for acetabular liners in cost-sensitive procurement tiers.
Titanium alloys dominate current volume; ceramic composites are climbing the fastest.
Application:
Clinical indication shapes implant complexity, bearing surface selection, and anticipated functional lifespan requirements.
- Osteoarthritis Treatment:Primary degenerative joint disease represents the volume foundation with standard total hip arthroplasty protocols. United States Medicare reimbursement rates stabilize demand across community hospital systems and integrated delivery networks.
- Revision Surgery:Component removal and reconstruction demands specialized stems, augments, and porous metal solutions for bone deficiency management. German orthopedic centers command premium pricing given procedural complexity and extended operative time requirements.
- Rheumatoid Arthritis Management:Inflammatory joint destruction requires careful bone quality assessment and cemented fixation strategies.
- Hip Fracture Repair:Trauma-focused hemiarthroplasty and total hip replacement address femoral neck and intertrochanteric fractures.
- Avascular Necrosis Therapy:Younger patient demographics drive ceramic-on-ceramic bearing selection for longevity.
Osteoarthritis treatment leads on scale; revision surgery leads on momentum.
End User:
Facility type determines case volume concentration, technology investment capacity, and outcome tracking sophistication.
- Ambulatory Surgery Centers:Outpatient hip arthroplasty protocols demand streamlined implant systems with predictable discharge trajectories. United States same-day joint replacement expansion concentrates procurement power in ASC networks across Florida, Texas, and California.
- Academic Medical Institutions:Research mandates and resident training programs sustain demand for robotic navigation systems and advanced bearing technologies. Japanese university hospitals in Kyoto and Kobe pilot ceramic composite innovations with longitudinal registry participation.
- Orthopedic Clinics:High-volume specialty practices optimize for operative efficiency and standardized component selection.
- Specialized Surgery Centers:Dedicated arthroplasty facilities achieve economies through procedure focus and vendor consolidation.
- Rehabilitation Facilities:Post-acute settings influence implant selection through outcomes data feedback and patient-reported metrics.
Orthopedic clinics lead on scale; ambulatory surgery centers lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Warsaw's orthopedic manufacturing corridor anchors European production of hip replacement implants, with specialized foundries supplying titanium alloy components to surgical device manufacturers across the continent. Regulatory frameworks and aging demographics drive divergent growth trajectories across national markets.
United States
Medicare Advantage capitation models incentivize implant durability in Florida and Texas ambulatory surgery centers. FDA premarket notification pathways for ceramic-on-ceramic bearings streamline 510(k) clearance timelines. Greater Boston's academic medical consortium pilots machine learning algorithms for preoperative planning.
Germany
Cemented fixation techniques dominate elderly patient protocols in Bavarian orthopedic clinics. EU MDR conformity assessment requirements extend recertification timelines for legacy metal-on-polyethylene portfolios. North Rhine-Westphalia's Ruhr Valley hosts concentrated cobalt-chromium smelting capacity serving continental manufacturers.
Japan
PMDA reimbursement clarity accelerates ceramic composite adoption in Tokyo metropolitan surgical networks. METI industrial policy supports domestic titanium alloy processing for cementless implant production. Osaka-Kobe's university hospital alliance maintains longitudinal registries tracking fourth-generation bearing surface performance.
India
Private hospital chains in Mumbai and Delhi build dedicated arthroplasty centers targeting medical tourism flows. CDSCO medical device regulations harmonize with ISO 5832 material standards for import substitution. Karnataka's Bangalore medical device cluster attracts contract manufacturing for global OEMs.
China
NMPA clinical evidence requirements fragment regulatory strategy for ceramic bearing imports. Dual carbon goals drive domestic titanium sponge production expansion in Sichuan-Chongqing industrial zones. Yangtze River Delta hospitals concentrate robotic-assisted surgical navigation deployment.
Global Hip Replacement Implants Market Competitive Landscape
Global majors compete with regional champions across regulatory access and bearing surface innovation, producing a tiered structure where integrated manufacturers control premium ceramic composite supply while mid-scale fabricators specialize in cemented construct refurbishment. Three archetypes dominate: full-line orthopedic conglomerates with robotic navigation ecosystems; ceramic-focused specialists targeting younger patient longevity requirements; and contract manufacturers supplying porous titanium acetabular shells to branded OEMs. M&A activity concentrates on additive manufacturing capabilities and outpatient surgery center distribution networks.
Within the integrated orthopedic tier, Zimmer Biomet Holdings and Stryker Corporation occupy positions spanning fixation systems to surgical navigation software. Smith & Nephew exemplifies the ceramic-specialist archetype with concentrated bearing surface portfolios. B. Braun Melsungen and MicroPort Scientific Corporation represent regional-scale manufacturers with differentiated geographic footprints in European and Asia-Pacific markets respectively.
| Leading Market Players |
|---|
| Zimmer Biomet Holdings |
| Stryker Corporation |
| DePuy Synthes |
| Smith & Nephew |
| Johnson & Johnson Services |
| Exactech |
| MicroPort Scientific Corporation |
| B. Braun Melsungen |
| Medacta |
| Others |
Supply & Pricing Matrix
Ceramic-on-ceramic bearing certification tiers bifurcate procurement economics, with PMDA-cleared constructs in Japan commanding material premiums over legacy metal-on-polyethylene systems while cobalt-chromium feedstock concentration in European smelters compresses margins for undifferentiated suppliers. This divergence manifests in hospital formulary decisions that weight long-term revision liability against upfront implant cost, reshaping supplier relationships around outcome guarantees rather than unit pricing.
Pricing Analysis
Input-cost pass-through from titanium sponge and orthopedic-grade cobalt-chromium alloys drives pricing stratification across premium, standard, and economy tiers. Price differentiation rests on FDA 510(k) clearance tier and ceramic fracture risk database completeness, with Japanese academic medical centers showing lowest sensitivity due to reimbursement clarity. Pricing pressure stems from ambulatory surgery center procurement consolidation in Florida and Texas, where Medicare Advantage capitation compresses allowable implant spend. Community hospital systems exhibit highest price sensitivity, deferring to GPO contracts for metal-on-polyethylene constructs.
Supply Chain Analysis
Freight cost escalation for titanium alloy ingots and ceramic powder precursors amplifies landed cost volatility for manufacturers dependent on Japanese and German raw material streams. Supply concentrates in Sichuan-Chongqing titanium sponge facilities, North Rhine-Westphalia cobalt-chromium smelters, and Osaka ceramic processing plants. Raw material dependencies include Ti-6Al-4V ELI titanium alloy, alumina-zirconia ceramic composites, and cross-linked polyethylene liners. Single-source vulnerability in orthopedic-grade cobalt-chromium exposes manufacturers to geopolitical disruption. Distribution runs through integrated delivery networks and specialized orthopedic distributors serving ambulatory surgery center networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities concentrate in India's underpenetrated arthroplasty infrastructure, where CDSCO regulatory harmonization with ISO 5832 standards reduces import substitution cost versus established United States and German markets.
For Market Incumbents: To counter robotic-assisted surgical navigation ecosystem lock-in by integrated orthopedic conglomerates, cementless fixation specialists should deepen backward integration into additive manufacturing of porous titanium acetabular shells and secure exclusive GPO contracts with Florida and Texas ambulatory surgery center networks. Ceramic composite portfolio expansion with PMDA pre-clearance investment protects Japanese market share against reimbursement-driven procurement consolidation. For New Entrants and Emerging Players: Underserved mid-tier orthopedic clinics in India's Mumbai-Delhi corridor present white-space entry points, with CDSCO regulatory pathways offering faster market access than FDA 510(k) timelines. Medical tourism infrastructure at Bangalore arthroplasty centers creates reference site opportunities for ceramic-on-ceramic bearing validation. Go-to-market positioning should emphasize value-based outcome guarantees bundled with extended reality surgical training content for resident credentialing programs. For Investors and Strategic Acquirers: Consolidation pressure builds where additive manufacturing capabilities and outpatient surgery center distribution networks remain fragmented among mid-scale fabricators. Long-term viability over the projection horizon favors targets with robotic navigation software integration and ceramic bearing surface IP portfolios. The signal to watch is PMDA reimbursement clarity expansion to additional ceramic composite constructs, which would validate premium pricing durability and trigger hospital procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Composite Bearing Development | PMDA reimbursement clarity in Tokyo metropolitan networks accelerates hospital adoption timelines. |
| Robotic Navigation Ecosystem Integration | Stryker's surgical positioning systems lock in hospital purchasing loyalty through bundled software contracts. |
| Additive Manufacturing Scale-Up | 3D-printed porous titanium shells reduce revision rates in United States ambulatory surgery centers. |
| Hospital System Partnership | Medicare Advantage capitation models in Florida align incentives around implant durability metrics. |
| Reimbursement Strategy | Japan's streamlined PMDA pathways compress administrative friction for ceramic-on-ceramic procurement cycles. |
Research Methodology
Multiple input streams — primary interviews with orthopedic surgeons and hospital purchasing committees, GPO contract database analysis, and FDA 510(k) filing review — were reconciled against secondary validation from CMS Medicare reimbursement data, ISO 5832 material standard documentation, and PMDA approval pathway records. Bottom-up triangulation across cementless implant volume estimates and top-down ceramic composite revenue segmentation ensured cross-verification of market sizing assumptions.
Data-stream reconciliation anchored volume and value outputs across product type, material chemistry, application indication, and end-user facility tier dimensions. CAGRs were derived from surgical procedure volume trajectories, aging demographic projections, and reimbursement policy evolution across the analysis window. Industry-specific forecast inputs included ceramic fracture risk database completion timelines and ambulatory surgery center same-day discharge protocol adoption curves.
Inputs from PMDA reimbursement bulletins and EU MDR notified body capacity reports were available through the study window; gaps in fourth-generation ceramic composite long-term clinical validation introduce uncertainty bands around revision rate assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Personalized Orthopaedic Implant Market
Orthopedic Devices
Global Minimally Invasive Spine Surgery Market
Orthopedic Devices
Spinal Pumps Market
Orthopedic Devices
Vertebroplasty Needles Market
Orthopedic Devices
Veterinary Prosthetics and Orthotics Market
Orthopedic Devices
Spinal Surgery Devices Market
Orthopedic Devices
India Spinal Surgery Devices Market
Orthopedic Devices
3D Orthopedic Scanning System Market
Orthopedic Devices
Chondroplasty Market
Orthopedic Devices
Spinal Devices Market
Orthopedic Devices
Patient Lifts Market
Orthopedic Devices
Closed Heel Nursing Shoes Market
Orthopedic Devices
Orthopedic Pedicle Screw Market
Orthopedic Devices
Global Orthopedic Navigation Systems Market
Orthopedic Devices
Global Patient Positioning Devices Market
Orthopedic Devices
Orthopedic Consumables Market