
 Orthopaedic Cushions Market | 2026-2036
Orthopaedic Cushions Market Size, Share, and Industry Trends Forecast 2026-2036
Orthopaedic Cushions Market Analytics
Multi-source material procurement is decoupling from traditional foam-supplier lock-in across the orthopaedic cushion supply base. Tempur-Pedic International leverages captive memory-foam formulation capabilities to sustain margin control over premium sleep and clinical positioning products. Medline Industries anchors institutional purchasing power through direct hospital contracts that dominate North American distribution. ROHO, Inc. specializes in air-cell pressure-relief technology for wheelchair and long-term care applications, competing on clinical outcomes rather than commodity pricing.
Orthopaedic cushions are engineered support surfaces constructed from viscoelastic polymers, gel composites, or pneumatic cell matrices, designed to redistribute pressure and maintain spinal or joint alignment during seated or recumbent use. Memory foam variants dominate product-type revenue due to established consumer familiarity and manufacturing scale, while gel segments command premium positioning in post-surgical and bariatric applications where thermal regulation matters. Application demand concentrates in seat cushioning and back support categories, with rehabilitation centers and home-care end users representing the fastest-growing channel as post-acute care shifts outside hospital walls.
The U.S. FDA regulates orthopaedic cushions as Class I or II medical devices depending on therapeutic claims, while the EU MDR imposes stricter clinical evidence and post-market surveillance requirements on cushion manufacturers seeking CE marking. ISO 13485 quality management certification has become a baseline market-access filter rather than a differentiator. Stakeholders must monitor how reimbursement code changes in Medicare and national health systems alter the economics of home-care versus institutional procurement.
Market Dynamics
The EU Medical Device Regulation (MDR) is compressing certification timelines for patient-contact products while aging demographics across Germany, Japan, and the United States concentrate demand for post-acute home-care solutions. This regulatory-demographic intersection is restructuring competitive positioning around clinical evidence and reimbursement navigation rather than commodity manufacturing scale.
Growth Catalysts
- EU MDR compliance mandates:Stricter biocompatibility documentation is filtering out marginal foam converters and elevating certified manufacturers with ISO 13485 quality systems already embedded.
- Post-surgical home-care protocols:Discharge acceleration policies in German and US hospital systems are expanding cushion prescriptions for pressure-ulcer prevention outside institutional settings.
- Gel-foam hybrid formulations:Thermal-regulating composites are penetrating bariatric and wound-care applications where temperature management directly affects healing outcomes.
Market Restraints
- Petrochemical input volatility:Polyurethane precursor costs fluctuate with crude-oil derivatives, compressing margins for foam-dependent manufacturers without backward integration into chemical supply.
- Supplier concentration in East Asian polymer feedstock:Memory-foam raw material production clusters in China and South Korea create geographic risk exposure for Western cushion assemblers.
- Reimbursement code fragmentation:Medicare HCPCS coding inconsistencies across US states complicate patient access and delay institutional purchasing decisions.
Strategic Opportunities
- Underpenetrated Indian home-care segment:PLI scheme incentives for medical device manufacturing are lowering import barriers for pressure-relief cushion categories previously dominated by unorganized local production.
- Remote patient monitoring integration:Sensor-embedded cushions transmitting pressure-distribution data to telehealth platforms are opening subscription revenue models in long-term care facilities.
- Brazilian ANVISA fast-track pathway:Streamlined registration for Class II pressure-management devices is accelerating market entry timelines versus traditional South American regulatory routes.
Industry Challenges
- Biomedical engineering talent scarcity:Cross-functional expertise combining foam chemistry, ergonomics, and clinical validation is concentrated among a small pool of specialists in Germany and the United States.
- Legacy ERP integration with track-and-trace systems:EU MDR unique device identification requirements are forcing mid-size manufacturers to replace inventory management infrastructure ahead of depreciation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Orthopaedic Cushions Market |
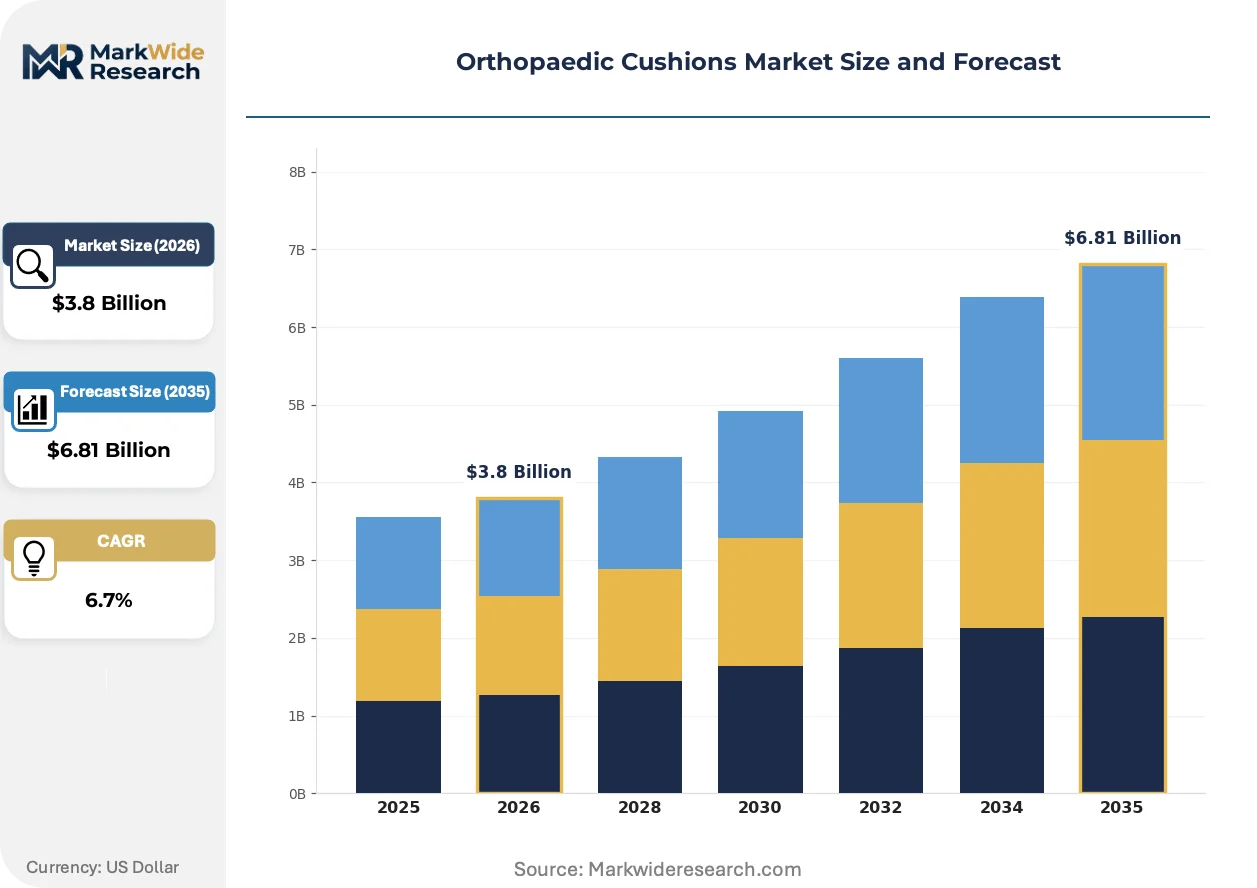
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Memory Foam, Gel, Air, Rubber Application: Post-Surgery, Back Support, Knee Support, Seat Cushioning End User: Hospitals, Rehabilitation Centers, Home Care, Athletic Facilities Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Pharmacies |
| Companies Covered | Tempur-Pedic International, Inc., Medline Industries, Inc., Drive DeVilbiss Healthcare, Invacare Corporation, Graham-Field Health Products, Inc., ROHO, Inc., Putnams Health, CosyCo, Supracor, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orthopaedic Cushions Market Evolving Landscape
Material science convergence with digital health infrastructure is redefining how pressure-management surfaces are specified, reimbursed, and monitored across acute and post-acute care environments.
Air-cell pneumatic matrices are expanding into remote patient monitoring architectures. These systems redistribute seated pressure through adjustable cell inflation, enabling real-time pressure mapping. Rehabilitation centers in the United States are piloting connected ROHO-style configurations that transmit alert thresholds to nursing stations, compressing response times for pressure-ulcer prevention and shifting liability models toward technology-enabled care protocols.
REACH substance restrictions on persistent organic pollutants are forcing reformulation of legacy flame-retardant additives in viscoelastic foams. Manufacturers serving EU markets must substitute halogenated compounds with phosphorus-based alternatives, extending R&D cycles by 12-18 months. German hospital procurement departments are now requiring full material disclosure documentation ahead of contract renewal, privileging suppliers with pre-validated chemical registries.
Direct-to-patient subscription models are disrupting traditional durable medical equipment distribution. Patients recovering from spinal surgery in California and Texas are bypassing brick-and-mortar retailers to lease premium positioning cushions with home-delivery and telehealth coaching bundles. This channel compression eliminates distributor markups while capturing recurring revenue streams that institutional bulk purchasing previously obscured.
Orthopaedic Cushions Market Segmentation
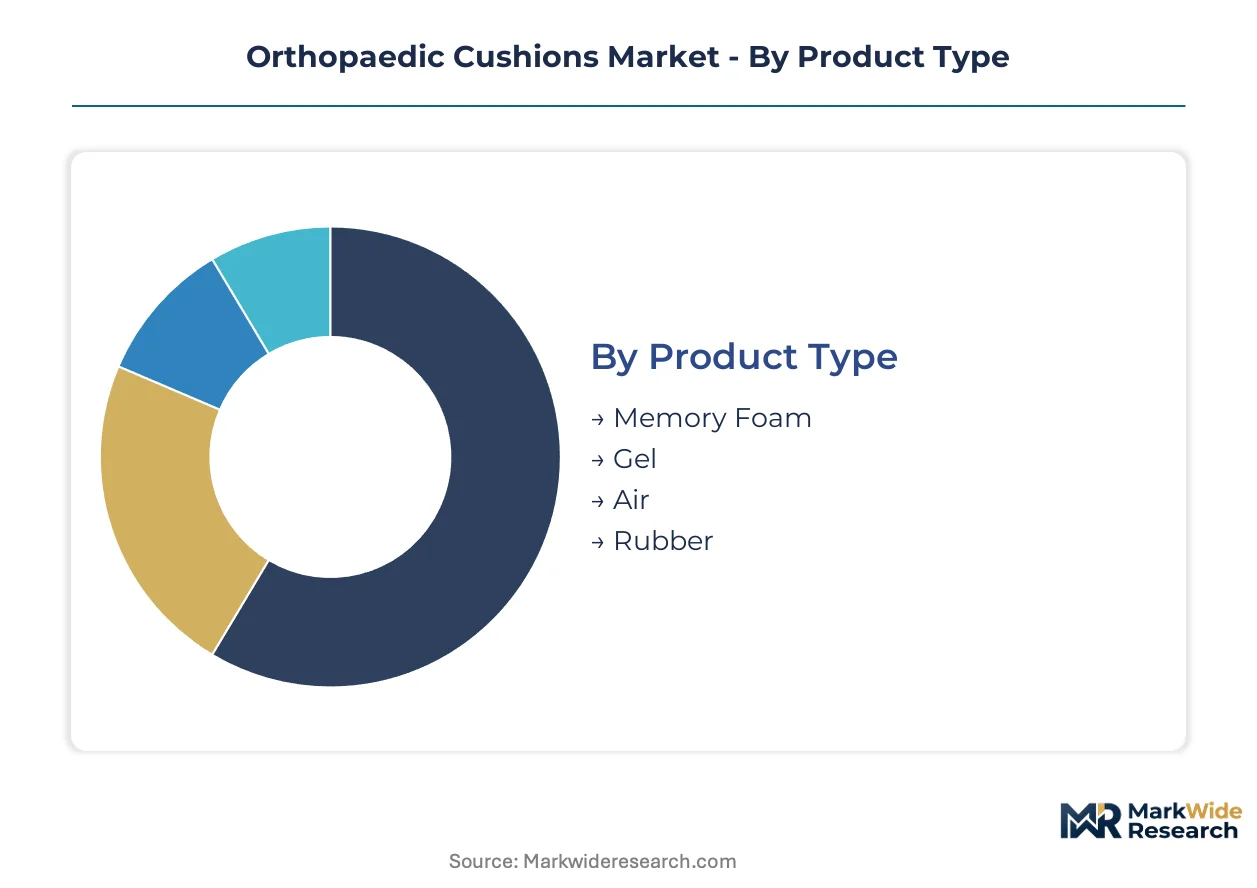
Orthopaedic cushion purchasing decisions split between standardized institutional procurement and customized patient-specific prescriptions. Material composition, clinical setting, and reimbursement pathway determine which segmentation axis dominates volume flows in any given geography.
Product Type:
Customization intensity varies sharply across material platforms, with formulation chemistry dictating both manufacturing flexibility and clinical specification range.
- Memory Foam:Viscoelastic polyurethane formulations dominate manufacturing scale due to established molding infrastructure and consumer familiarity. Demand concentrates in German home-care channels where statutory health insurance reimbursement covers pressure-ulcer prevention cushions for ambulatory patients.
- Gel:Thermally conductive silicone or polymer composites redistribute body heat while maintaining pressure distribution. Post-surgical applications in US bariatric wards drive premium positioning where temperature regulation accelerates wound healing protocols.
- Air:Pneumatic cell matrices enable real-time pressure adjustment through inflation control. Long-term care facilities pilot connected configurations transmitting alert thresholds to nursing stations.
- Rubber:Latex and synthetic elastomer cores deliver durability in high-use athletic and institutional settings. Southeast Asian manufacturing clusters supply cost-sensitive bulk procurement.
Most installed capacity flows through Memory Foam. Expansion is steepest in Gel.
Application:
Clinical outcome requirements stratify across anatomical targets, with spinal alignment applications commanding stricter biomechanical validation than peripheral joint support.
- Post-Surgery:Positioning surfaces for spinal, hip, and knee procedures require ISO 13485-validated pressure redistribution metrics. German hospital discharge acceleration policies are expanding prescription volumes for home-recovery protocols.
- Back Support:Lumbar cushions for seated occupational health compete on ergonomic certification rather than clinical reimbursement codes. Corporate wellness programs in California and Texas represent emerging volume concentrations.
- Knee Support:Anatomically contoured surfaces for post-arthroscopy recovery or chronic osteoarthritis management. Rehabilitation centers specify modular designs accommodating range-of-motion progression.
- Seat Cushioning:General pressure relief for wheelchair users and extended sitting applications. Medicare HCPCS coding inconsistencies across US states fragment procurement economics.
Reimbursement eligibility concentrates volume in Post-Surgery. Seat Cushioning climbs the fastest as remote work normalizes ergonomic home investments.
End User:
Procurement authority and patient proximity determine specification complexity, with acute care institutions demanding traceable clinical evidence that home settings rarely require.
- Hospitals:Centralized purchasing departments mandate CE marking under EU MDR and FDA 510(k) clearance for pressure-management claims. Biocompatibility documentation filters out uncertified foam converters.
- Rehabilitation Centers:Post-acute facilities balance clinical outcomes with capital equipment budgets. Sensor-embedded cushions transmitting pressure data to telehealth platforms are gaining trial adoption.
- Home Care:Patient or caregiver-directed purchasing bypasses institutional procurement controls. Direct-to-patient subscription models in California and Texas capture recurring revenue through home-delivery bundles.
- Athletic Facilities:Performance recovery and injury prevention applications prioritize durability and moisture resistance over clinical reimbursement pathways.
Contract concentration anchors volume in Hospitals. Home Care gains share fastest as post-acute care shifts outside institutional walls.
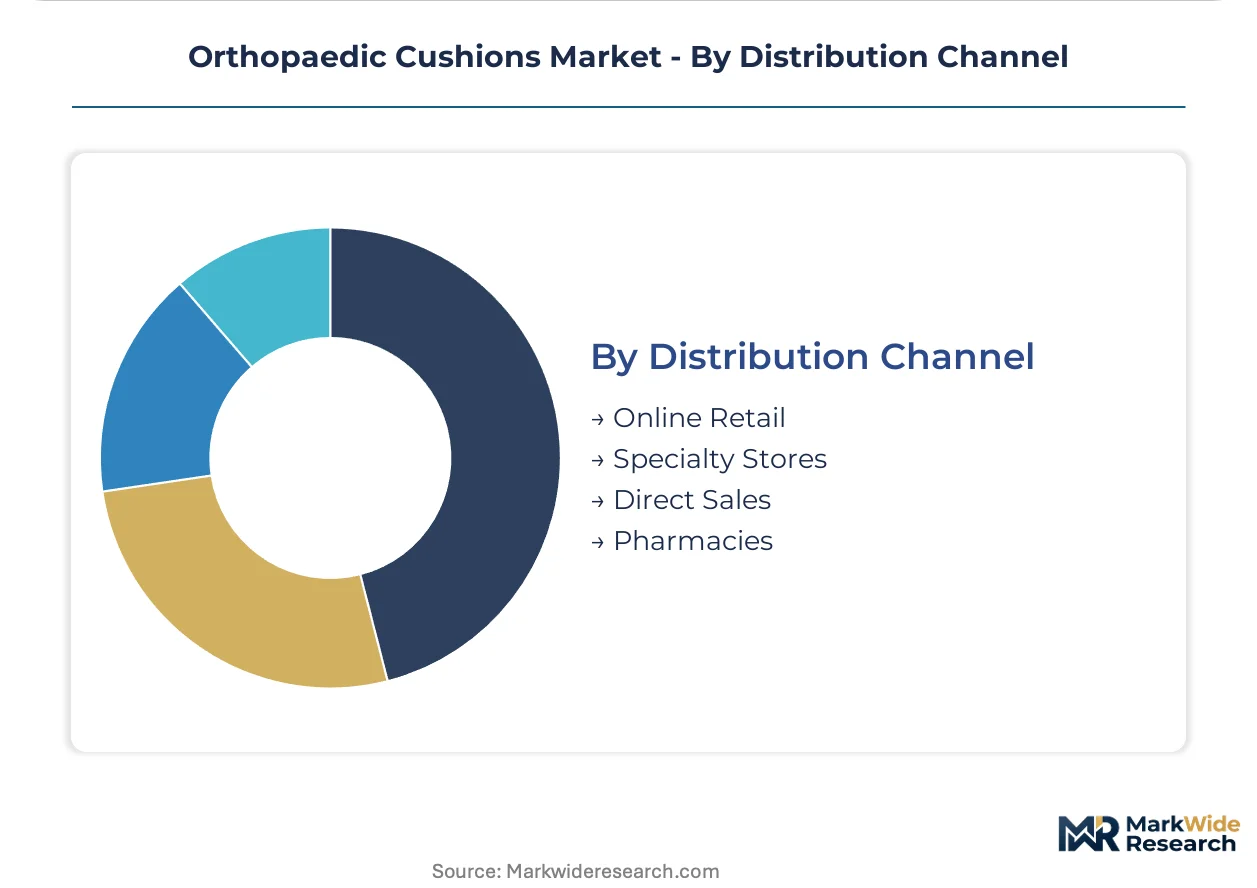
Distribution Channel:
Channel selection determines margin capture and patient access speed, with institutional direct contracts diverging sharply from consumer-facing retail economics.
- Online Retail:E-commerce platforms aggregate consumer search behavior and enable comparison shopping on density specifications. California and Texas spinal surgery patients increasingly lease premium positioning cushions through subscription portals.
- Specialty Stores:Brick-and-mortar durable medical equipment retailers provide fitting services and insurance claim assistance. Foot traffic dependency creates geographic coverage gaps in rural markets.
- Direct Sales:Manufacturer-to-institution contracts eliminate distributor markups and enable volume pricing for hospital systems. Medline Industries anchors North American procurement through exclusive supply agreements.
- Pharmacies:Retail pharmacy chains leverage prescription foot traffic for impulse cushion purchases. Limited clinical consultation capability restricts attachment to standardized product ranges.
Institutional procurement flows through Direct Sales. Online Retail expands most quickly as channel compression eliminates intermediary economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The German industrial corridor dominates orthopaedic cushion manufacturing infrastructure, with aging demographics and statutory reimbursement frameworks concentrating demand across Western Europe. Regulatory convergence around EU MDR compliance is filtering supply bases while post-acute care decentralization accelerates home-care channel expansion.
United States
Medicare HCPCS coding inconsistencies fragment procurement economics across state lines, delaying institutional purchasing decisions. FDA Class II device clearance requirements for pressure-management claims elevate documentation burdens. California and Texas spinal surgery patients increasingly access premium positioning cushions through direct-to-patient subscription portals.
Germany
Statutory health insurance reimbursement for ambulatory pressure-ulcer prevention cushions drives memory foam volume through home-care channels. EU MDR biocompatibility documentation mandates filter out uncertified foam converters. The Baden-Württemberg medical device cluster hosts ISO 13485-validated manufacturers serving hospital discharge acceleration protocols.
Japan
Super-aging demographics concentrate demand for post-surgical home-care solutions as METI promotes telehealth-integrated medical devices. PMDA quality management requirements align with global ISO standards. The Kansai manufacturing belt supplies pressure-relief surfaces to long-term care facilities adapting to reimbursement code reforms.
India
PLI scheme incentives for medical device manufacturing lower import barriers for pressure-relief cushion categories. CDSCO registration pathways for Class I devices streamline market access versus historical routes. Maharashtra and Gujarat industrial zones attract contract manufacturing for gel-foam hybrid formulations targeting bariatric applications.
Brazil
ANVISA fast-track registration for Class II pressure-management devices compresses entry timelines versus traditional South American regulatory routes. Private health insurance expansion in São Paulo and Rio de Janeiro metro areas drives premium product adoption. Local assembly operations in Minas Gerais serve price-sensitive institutional procurement.
Orthopaedic Cushions Market Competitive Landscape
Global majors compete with regional champions across certification depth and reimbursement navigation capabilities. The vendor base stratifies between integrated foam formulators, institutional distributors, and clinical-outcome specialists. Three archetypes dominate: captive polymer chemists, hospital-contract aggregators, and pneumatic technology innovators. Competitive moves concentrate on M&A for manufacturing scale and strategic partnerships for telehealth platform integration.
Among North American fabricators, Tempur-Pedic International exemplifies the captive formulation archetype through in-house memory-foam chemistry control. Medline Industries anchors institutional procurement aggregation through direct hospital system contracts. ROHO, Inc. occupies the pneumatic specialization tier, representing air-cell pressure-relief technology developed for wheelchair and long-term care configurations.
| Leading Market Players |
|---|
| Tempur-Pedic International, Inc. |
| Medline Industries, Inc. |
| Drive DeVilbiss Healthcare |
| Invacare Corporation |
| Graham-Field Health Products, Inc. |
| ROHO, Inc. |
| Putnams Health |
| CosyCo |
| Supracor, Inc. |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap foam converters in Germany's Baden-Württemberg corridor anchor supply-side discipline through generational ownership structures that resist short-term margin compression. Their captive polymer chemistry expertise sustains pricing power against commodity importers while EU MDR compliance investments filter price-tendering competitors from hospital procurement pools.
Pricing Analysis
Polyurethane precursor volatility passes through to cushion ASPs on 6-12 month lags, compressing margins for non-integrated assemblers. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-validated clinical grades from consumer wellness SKUs. Pricing pressure stems from Medicare HCPCS coding fragmentation that delays institutional purchasing decisions. Home-care patients show highest price sensitivity; bariatric wards demonstrate lowest.
Supply Chain Analysis
Direct-to-hospital channels handle institutional volume through GPO-negotiated contracts, while specialty medical distributors serve rehabilitation centers. Memory-foam raw material production clusters in China and South Korea, with gel composite feedstock sourcing from German chemical specialists. Supply chain risk centers on single-source vulnerability for viscoelastic polymer formulations. Distribution runs through Medline's North American institutional network and regional durable medical equipment retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Orthopaedic cushions function as a stable compounder anchored by irreversible demographic aging across developed economies. Post-acute care decentralization sustains replacement demand regardless of macroeconomic cycles.
For Market Incumbents: Cement ISO 13485-validated manufacturing scale as the primary defensive moat against Asian commodity importers. Deepen backward integration into polyurethane formulation chemistry to offset petrochemical input volatility. Prioritize EU MDR technical documentation superiority to capture German statutory reimbursement flows.
For New Entrants and Emerging Players: Telehealth platform partnerships represent the most penetrable channel for sensor-embedded cushion categories bypassing traditional durable medical equipment distribution. Target Indian home-care segments where PLI scheme incentives lower import barriers against unorganized local production. Pursue direct-to-patient subscription models in California and Texas spinal surgery recovery markets.
For Investors and Strategic Acquirers: Valuations sit cheapest among pneumatic technology specialists with connected-device roadmaps but unmonetized data assets. Five-to-ten year viability hinges on reimbursement code consolidation favoring clinical-outcome demonstrators over commodity positioning. Watch for Medicare HCPCS harmonization signals as inflection indicator for institutional procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | CE marking under MDR filters uncertified competitors from German hospital procurement. |
| Sensor-Embedded Cushion Development | Pressure-mapping telemetry enables subscription revenue in US long-term care facilities. |
| Backward Integration into Polymer Chemistry | Captive foam formulation insulates margins from crude-derivative volatility. |
| Direct-to-Patient Subscription Launch | Home-delivery bundles bypass distributor markups in California spinal surgery markets. |
| Indian PLI Scheme Manufacturing Entry | Domestic production lowers CDSCO registration barriers for bariatric gel-foam hybrids. |
Research Methodology
Coverage spans North America, Western Europe, and Asia-Pacific, with primary inputs from each region triangulated against secondary validation. Interviews with biomedical engineers, hospital purchasing committees, GPO contracts managers, and foam chemistry R&D directors informed supply-side and demand-side dynamics. Secondary sources include FDA 510(k) filings, EU MDR technical documentation databases, CMS Medicare reimbursement code repositories, and hospital procurement contract disclosures. Bottom-up volume modeling and top-down value reconciliation cross-validated segment-level outputs.
Rate-of-change decomposition isolates volume drivers from price-mix effects across the projection horizon. Segmentation dimensions modeled include material platform, clinical application, end-user setting, and reimbursement pathway. CAGRs derive from logistic adoption curves fitted to historical penetration data and elasticity-adjusted price trajectories. Forecast inputs incorporate EU MDR compliance timeline assumptions and Medicare HCPCS code consolidation probabilities.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to petrochemical price volatility and reimbursement policy shifts. Analysis reflects assumptions regarding discharge acceleration protocol permanence and telehealth platform integration adoption rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Orthopedic Contract Manufacturing Market
Orthopedic Devices
Orthopedic Support Systems Market
Orthopedic Devices
Global Elbow Replacement Market
Orthopedic Devices
Saudi Arabia Spinal Surgery Devices Market
Orthopedic Devices
Global Shockwave Therapy Market
Orthopedic Devices
Intramedullary Nails Market
Orthopedic Devices
Knee Implants Market
Orthopedic Devices
North America Spinal Surgery Market
Orthopedic Devices
Orthobiologics Market
Orthopedic Devices
Keyhole Orthopaedic Surgery Market
Orthopedic Devices
Unicompartmental Knee Prosthesis Market
Orthopedic Devices
Orthopedic Braces Market
Orthopedic Devices
Orthopedic Wire Pin Driver Market
Orthopedic Devices
Hip Replacement Market
Orthopedic Devices
North America Knee Cartilage Repair Market
Orthopedic Devices
Podiatry Laser Market