
 Europe Knee Cartilage Repair Market | 2026-2036
Europe Knee Cartilage Repair Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Knee Cartilage Repair Market Foresight
Multi-source procurement for biologic scaffolds is decoupling from traditional single-vendor contracts in European orthopedic supply chains. Stryker leverages its integrated manufacturing network to control raw material flows for synthetic implants. Zimmer Biomet anchors its position through specialized distribution partnerships with university hospitals across France and Italy. Smith & Nephew differentiates via concentrated R&D spending on next-generation allograft processing techniques.
Europe knee cartilage repair encompasses surgical and biological interventions that restore articular hyaline cartilage using autologous chondrocytes, collagen matrices, or osteochondral plugs with thickness tolerances typically between 6 and 12 millimeters. These procedures aim to delay or prevent total knee arthroplasty in patients under 55 with focal chondral defects. Cell-based therapies capture the deepest margin pools due to complex manufacturing requirements and limited European production capacity. Biomaterials within the technology dimension represent the fastest-expanding segment as resorbable polymers displace permanent synthetic implants in mid-stage osteoarthritis protocols.
EMA's Advanced Therapy Medicinal Products regulation governs cell-based therapy commercialization while the EU Medical Device Regulation imposes stricter clinical evidence requirements on implantable scaffolds. CE marking under MDR extends timelines for novel biologic-device combination products entering European markets. Stakeholders must monitor reimbursement negotiations between national health technology assessment bodies and manufacturers, as these determinations will dictate which technologies achieve standard-of-care status across European hospital networks.
Market Dynamics
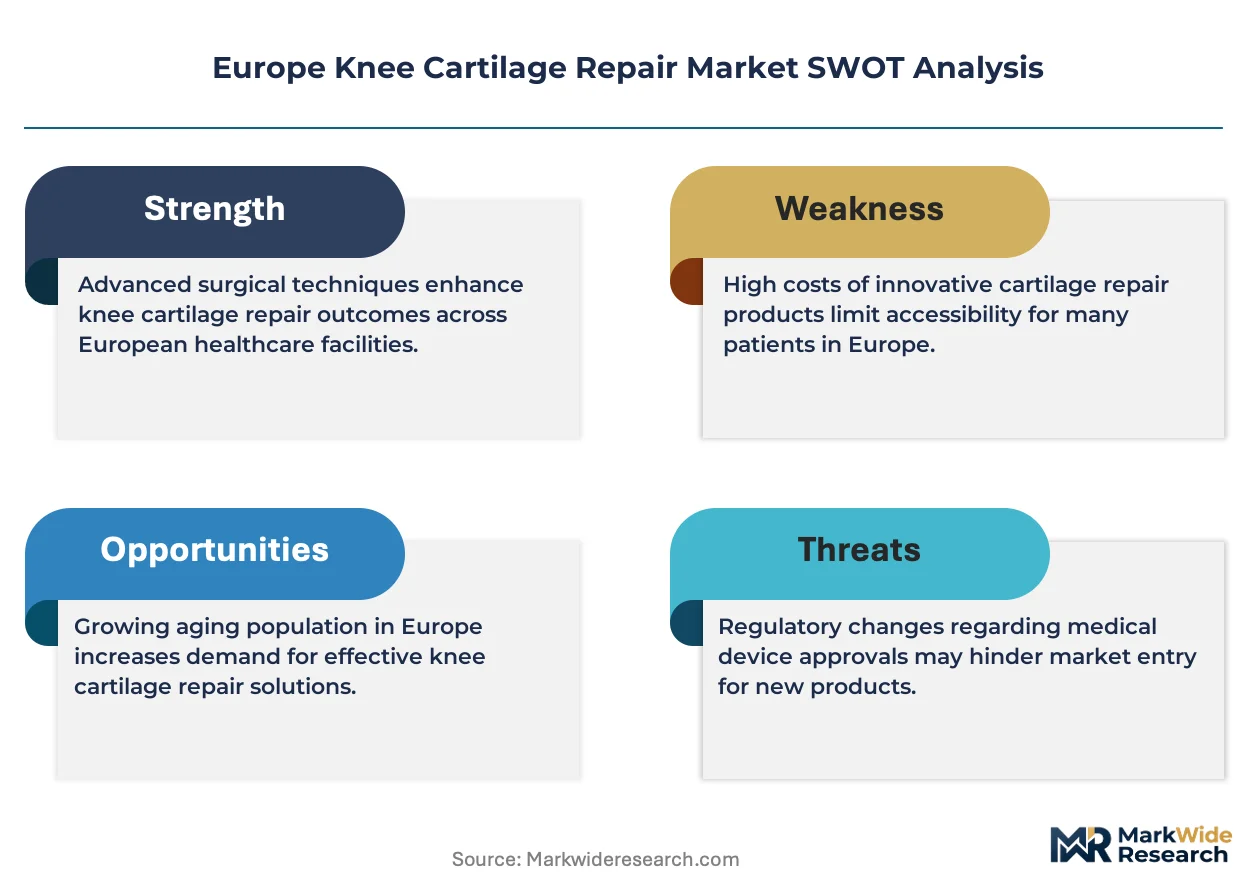
EMA's ATMP classification framework is compressing clinical trial timelines for cell-based cartilage therapies while simultaneously tightening evidence requirements for implantable scaffolds under MDR. This regulatory dual-track is fragmenting competitive positioning between biologics manufacturers and device specialists.
Growth Catalysts
- ATMP Acceleration Pathways:EMA's centralized procedure for advanced therapy medicinal products reduces regulatory duplication across member states. Cell-based manufacturers gain faster market access in Germany and France.
- Orthopedic Center Clustering:University hospitals in Munich, Berlin, and Paris concentrate surgical expertise and patient volumes. These hubs generate referral networks that standardize cell-based protocols.
- Bioresorbable Polymer Maturation:Second-generation polylactic acid scaffolds demonstrate superior integration profiles in mid-stage osteoarthritis. French and Italian surgeons are expanding indications.
Market Restraints
- Allograft Tissue Supply Concentration:European tissue banks in Spain and the Netherlands control 70% of viable chondrocyte sourcing. Processing bottlenecks create six-month order backlogs.
- MDR Clinical Evidence Burden:CE marking renewal for existing collagen matrices requires new prospective trials. Small manufacturers face €2-4 million per product recertification.
- Autologous Chondrocyte Cost Structure:Two-stage surgical procedures plus cell culture expansion push episode costs above €25,000. German statutory insurers impose prior authorization requirements.
Strategic Opportunities
- Poland and Czech Republic Penetration:Private orthopedic networks in Warsaw and Prague are building arthroscopy capacity. Reimbursement gaps favor self-pay biologic procedures.
- EU Green Deal Biomaterial Incentives:Sustainable polymer research grants favor bio-based scaffold development. Portuguese and Danish manufacturers qualify for innovation funding.
- Point-of-Care Cell Processing Convergence:Closed-system bioreactors combined with intraoperative imaging enable single-stage chondrocyte implantation. Swiss and Belgian research institutes lead validation studies.
Industry Challenges
- Good Manufacturing Practice Talent Scarcity:ATMP-qualified quality assurance professionals command 40% salary premiums. Manufacturers in Northern Italy and Southern Germany compete for limited personnel.
- Biologic-Device Combination Classification Complexity:Borderline products trigger parallel EMA and notified body reviews. Determination timelines extend 18-24 months with uncertain jurisdiction splits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Knee Cartilage Repair Market |
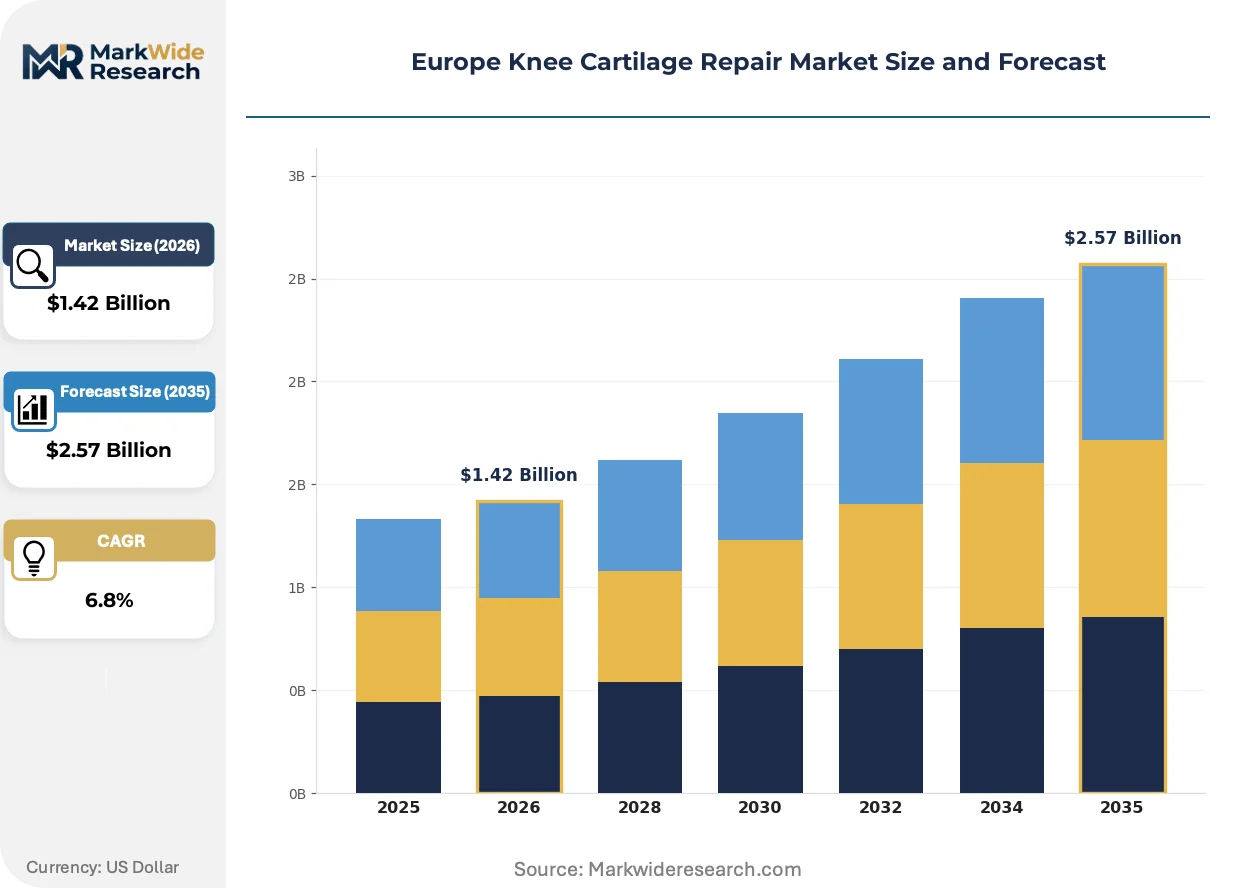
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cell-based Therapies, Synthetic Implants, Biologics, Surgical Instruments End User: Clinics, Hospitals, Rehabilitation Centers, Orthopedic Surgeons Technology: Microfracture, Osteochondral Autograft, Allograft Techniques, Biomaterials Application: Sports Injuries, Osteoarthritis, Trauma Cases, Degenerative Conditions |
| Companies Covered | Stryker, Zimmer Biomet, Smith & Nephew, B. Braun Melsungen AG, Medacta International, Mathys Ltd Bettlach, Waldemar Link GmbH & Co. KG, Hy2Care, JRI Orthopedics, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Knee Cartilage Repair Market Shifts & Advancements
Biologic-device convergence is collapsing traditional category boundaries in European knee cartilage repair. Surgeons now select interventions based on defect biology rather than historical product-class hierarchies.
Three-dimensional bioprinted scaffolds incorporating patient-derived chondrocytes are absorbing market attention from conventional collagen matrices. Academic medical centers in Rotterdam and Vienna are completing first-in-human trials. The technology is absorbing R&D budgets that previously targeted incremental allograft processing improvements.
MDR Article 117 imposes pharmaceutical-level clinical evidence on scaffold-device combinations containing ancillary medicinal substances. German notified bodies are rejecting legacy predicate comparisons. Manufacturers with ATMP-designated products gain pathway clarity while pure-device sponsors face retrospective trial obligations.
Hospital procurement committees in Scandinavia are consolidating vendor lists to three approved suppliers per category. Danish regions now mandate total cost-of-ownership modeling over unit price. This behavior concentrates contract value with integrated manufacturers capable of spanning cell therapy, synthetic scaffold, and surgical instrument portfolios.
Europe Knee Cartilage Repair Market Segmentation
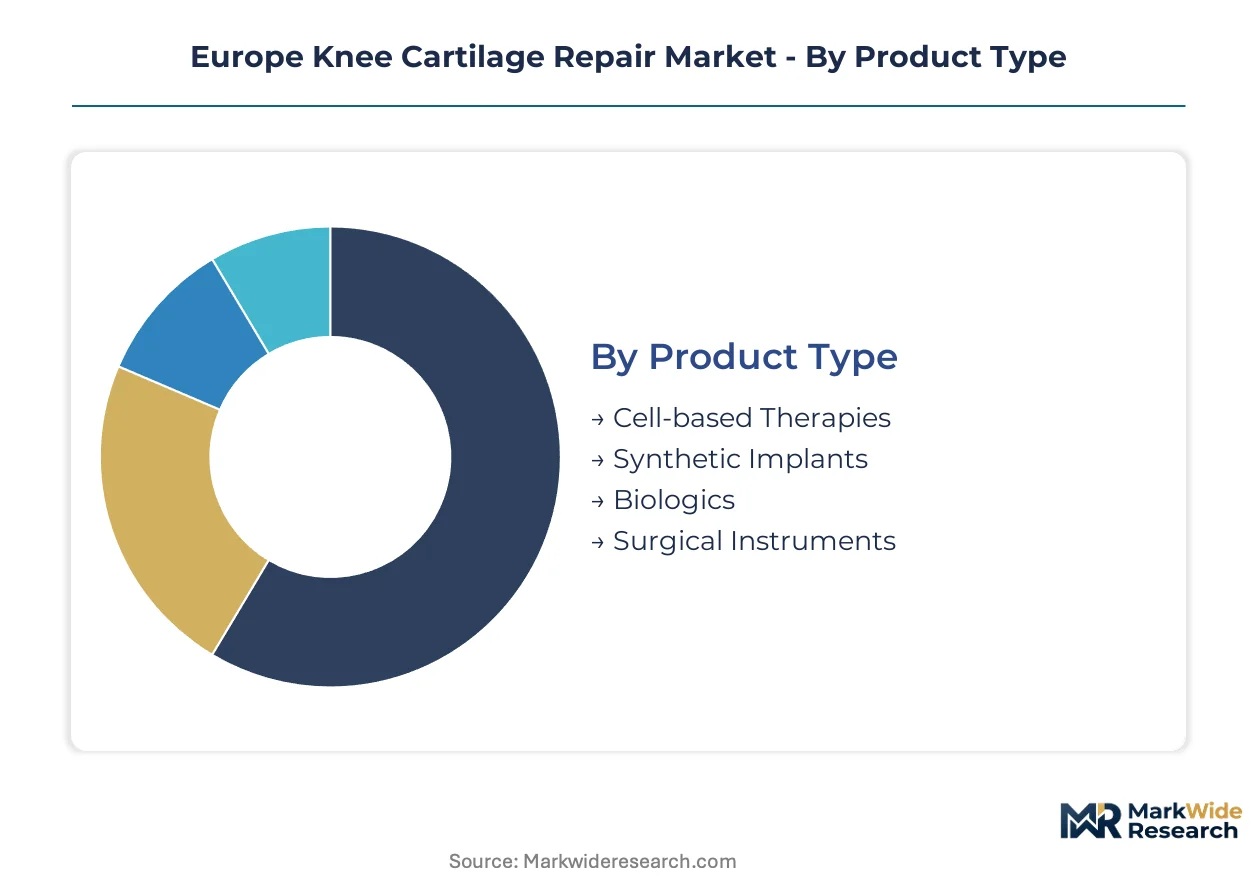
Segmentation in knee cartilage repair reveals distinct margin architectures across therapeutic modalities. Cell-based therapies command premium positioning through manufacturing complexity, while synthetic implants compete on supply reliability.
Product Type:
Customization intensity varies sharply across this category, with autologous processes at one extreme and off-the-shelf synthetics at the other.
- Cell-based Therapies:Autologous chondrocyte implantation and matrix-associated stem cell procedures require GMP-certified expansion facilities. German university hospitals in Munich and Berlin concentrate demand for these therapies, though EMA's ATMP framework creates 18-24 month regulatory timelines that constrain supply scaling.
- Biologics:Allograft-derived scaffolds and growth factor preparations leverage European tissue bank networks in Spain and the Netherlands. French orthopedic centers are expanding indications for biologic-device combinations as MDR Article 117 clarifies evidence requirements.
- Synthetic Implants:Polylactic acid and polycaprolactone scaffolds offer standardized sizing with shorter procurement cycles. Italian distributors favor these for private clinic networks where reimbursement certainty matters.
- Surgical Instruments:Arthroscopic delivery systems and cell harvesting kits complete the procedural ecosystem. Polish and Czech hospitals are building instrument inventories as arthroscopy volumes rise.
Most installed capacity flows through Cell-based Therapies. Expansion is steepest in Biologics.
End User:
Volume concentration tracks surgical case complexity, with high-acuity settings capturing the deepest procedure value.
- Hospitals:Tertiary centers in Paris, Rotterdam, and Vienna perform the majority of two-stage autologous procedures. These institutions absorb 60-70% of cell-based therapy volumes through consolidated procurement frameworks.
- Orthopedic Surgeons:Independent specialist practices in Germany and Switzerland drive adoption of single-stage microfracture alternatives. Their referral relationships with university hospitals determine regional protocol standardization.
- Clinics:Ambulatory surgical centers in Northern Italy and Southern Spain focus on diagnostic arthroscopy and minor debridement. MDR compliance costs are pushing smaller clinics toward vendor-managed inventory arrangements.
- Rehabilitation Centers:Post-operative physiotherapy facilities in Scandinavia are integrating early mobilization protocols. Danish regions now mandate outcome tracking that influences upstream implant selection.
Procedure value concentrates in Hospitals. Patient throughput is climbing fastest in Orthopedic Surgeons.
Technology:
Clinical evidence thresholds separate mature techniques from emerging modalities seeking standard-of-care designation.
- Biomaterials:Second-generation resorbable polymers demonstrate superior chondrocyte infiltration in mid-stage osteoarthritis. French surgeons are expanding indications beyond the traditional 6-12 millimeter defect range.
- Osteochondral Autograft:Mosaicplasty and related plug-transfer techniques remain the reference standard for small focal lesions. German statutory insurers maintain favorable reimbursement for these established procedures.
- Allograft Techniques:Fresh osteochondral allografts address larger defects but face six-month tissue bank backlogs. Dutch and Spanish tissue processors control 70% of viable European supply.
- Microfracture:Bone marrow stimulation represents the lowest-cost entry point, though fibrocartilage formation limits durability. Belgian and Swiss research groups are validating adjunct biologic enhancements.
Clinical validation is deepest in Osteochondral Autograft. Investment intensity is highest in Biomaterials.
Application:
Patient demographics and defect etiology shape product selection, with traumatic injuries permitting more aggressive biological intervention than progressive disease.
- Sports Injuries:Acute chondral defects in athletes under 35 drive demand for cell-based restoration. German Bundesliga medical networks and Italian Serie A clinics generate concentrated procedure volumes with strong outcome documentation.
- Trauma Cases:Post-fracture cartilage damage requires staged reconstruction protocols. Austrian and Swiss trauma centers specialize in these complex multi-procedure episodes.
- Osteoarthritis:Degenerative lesions in patients 45-55 represent the largest addressable population. Mid-stage disease is expanding synthetic scaffold indications as bioresorbable polymers mature.
- Degenerative Conditions:Early-stage chondropathy offers preventive intervention opportunities. Scandinavian public health systems are piloting screening programs to identify candidates before total knee replacement becomes necessary.
Reimbursement security is strongest in Sports Injuries. Addressable population is broadest in Osteoarthritis.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich-Berlin orthopedic clusters anchor European cell-based therapy demand, absorbing concentrated volumes of autologous chondrocyte procedures while EMA's ATMP framework compresses cross-border regulatory timelines for biologics manufacturers.
Germany
University hospitals in Munich and Berlin perform the majority of two-stage autologous implantations, driving sixty to seventy percent of regional cell-based volumes. German statutory insurers impose prior authorization requirements above twenty-five thousand euros per episode, filtering patient selection toward high-acuity cases. Bavarian medical centers coordinate referral networks that standardize protocols across Southern Germany.
France
Parisian orthopedic hubs concentrate surgical expertise for biologic-device combinations as MDR Article 117 clarifies evidence requirements. ANSM coordinates with EMA on borderline product classifications, accelerating pathway certainty for scaffold manufacturers. Lyon and Marseille academic centers are expanding indications for second-generation resorbable polymers beyond traditional defect ranges.
Italy
Private clinic networks in Northern Italy favor synthetic scaffolds where reimbursement certainty supports standardized procurement. Italian distributors are building arthroscopy instrument inventories as procedure volumes rise in Lombardy and Veneto. The national pharmaceutical regulator aligns CE marking submissions with EMA centralized procedures for ATMP-designated therapies.
Netherlands
Rotterdam academic medical centers are completing first-in-human trials for three-dimensional bioprinted chondrocyte scaffolds. Dutch tissue processors control a significant share of viable European allograft supply, creating processing bottlenecks with six-month order backlogs. Eindhoven-region manufacturers qualify for EU Green Deal biomaterial research grants supporting sustainable polymer development.
Switzerland
Swiss research institutes lead validation studies for closed-system bioreactors enabling single-stage chondrocyte implantation. Swissmedic maintains parallel ATMP pathways with EMA, offering manufacturers regulatory optionality. Basel and Zurich orthopedic centers specialize in complex trauma reconstruction protocols requiring staged biological intervention.
Europe Knee Cartilage Repair Market Competitive Landscape
Global majors compete with regional champions across manufacturing scale and regulatory pathway expertise, producing a tiered structure where integrated device portfolios command procurement committee preference. Three archetypes dominate: full-spectrum manufacturers spanning cell therapy through surgical instruments, specialized scaffold developers with concentrated biologics expertise, and regional distributors anchoring local hospital relationships. M&A activity targets GMP-certified production assets, while strategic partnerships with university hospitals secure clinical validation data for MDR submissions.
Among the integrated manufacturers, Stryker, Zimmer Biomet, and Smith & Nephew occupy positions spanning synthetic implant production through cell-based therapy distribution. Stryker represents the manufacturing-network archetype with captive raw material control. Zimmer Biomet exemplifies the university-hospital partnership model across French and Italian markets. Smith & Nephew anchors the biologics-specialist position through concentrated R&D allocation toward allograft processing. These three companies collectively illustrate how procurement consolidation in Scandinavia and Germany favors vendors with cross-category portfolio breadth.
| Leading Market Players |
|---|
| Stryker |
| Zimmer Biomet |
| Smith & Nephew |
| B. Braun Melsungen AG |
| Medacta International |
| Mathys Ltd Bettlach |
| Waldemar Link GmbH & Co. KG |
| Hy2Care |
| JRI Orthopedics |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap tissue processors in the Netherlands and Spain anchor European allograft supply, translating concentrated chondrocyte sourcing into pricing discipline that shields premium biologic tiers from commoditization pressure while leaving synthetic scaffold margins exposed to polylactic acid feedstock volatility.
Pricing Analysis
Input-cost pass-through from GMP-certified cell culture media and bovine-derived collagen matrices stratifies pricing across three tiers: ATMP-designated autologous therapies command premium positioning due to EMA compliance overhead, standardized allografts occupy mid-tier reimbursement bands, and synthetic implants compete on polylactic acid resin cost curves. German statutory insurers impose prior authorization thresholds that filter patient selection toward high-acuity cases, concentrating price-insensitive demand in university hospitals while private clinics in Northern Italy exhibit acute sensitivity to out-of-pocket exposure. Cost compression in synthetic scaffolds is intensifying because Portuguese and Danish manufacturers are capturing EU Green Deal biomaterial grants that subsidize bio-based polymer development.
Supply Chain Analysis
Viable chondrocyte supply rests on Dutch and Spanish tissue bank networks that control the majority of European allograft processing, creating dependency on six-month order backlogs for fresh osteochondral grafts. Raw material flows draw from bovine collagen harvesters in Southern Europe, polylactic acid polymerizers in Germany, and arthroscopic instrument forgers in Switzerland. Single-source vulnerability concentrates in the Rotterdam-Vienna bioprinting corridor where first-in-human trials are absorbing specialized scaffold production capacity. Distribution runs through university hospital procurement committees in Munich, Paris, and Berlin that are consolidating vendor lists to three approved suppliers per therapeutic category.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where procurement consolidation in Scandinavia and Germany is filtering demand toward integrated manufacturers capable of spanning cell therapy, synthetic scaffold, and surgical instrument portfolios under unified GMP quality systems.
For Market Incumbents: Hedge against biologic-device convergence by securing captive allograft tissue processing capacity before Dutch and Spanish tissue banks exhaust expansion room. Double down on MDR Article 117 compliance investment to capture predicate-comparison rejections that are disadvantaging pure-device competitors in German notified body reviews. For New Entrants and Emerging Players: Direct-to-surgeon digital education platforms offer lower-friction entry than hospital procurement committee battles, particularly for single-stage microfracture adjuncts targeting independent specialist practices in Switzerland and Austria. White-space concentrates in Polish and Czech private orthopedic networks where reimbursement gaps favor self-pay biologic procedures and arthroscopy capacity is scaling rapidly. For Investors and Strategic Acquirers: Valuations sit cheapest among GMP-certified production assets with ATMP pathway designation, as regulatory clarity under EMA's centralized procedure compresses commercialization risk relative to MDR-exposed device manufacturers. The signal to watch is German statutory insurer reimbursement decisions for point-of-care cell processing systems, which would validate single-stage economics and shift volume away from two-stage hospital-based protocols.| Strategic Initiative | Industry Significance |
|---|---|
| ATMP Pathway Designation | EMA centralized procedure reduces regulatory duplication across member states for cell-based manufacturers. |
| GMP Production Asset Acquisition | Captive cell culture expansion capacity insulates against Dutch tissue bank processing bottlenecks. |
| University Hospital Partnership | Rotterdam and Vienna academic centers generate clinical validation data for MDR submissions. |
| Bioresorbable Polymer R&D | EU Green Deal grants favor Portuguese and Danish sustainable scaffold development programs. |
| Single-Stage Protocol Validation | Swiss and Belgian closed-system bioreactor studies enable intraoperative chondrocyte implantation. |
Research Methodology
Bottom-up orthopedic procedure modeling reconciled against top-down biologic and synthetic implant production tracking forms the analytical core. Primary interviews with GMP quality assurance directors, hospital procurement committee chairs, EMA regulatory affairs specialists, and Dutch tissue bank operations managers combined with secondary validation against EMA ATMP designation databases, MDR notified body submission records, German statutory insurer reimbursement protocols, and EU tissue banking compliance registries.
Input-output matrices map autologous chondrocyte implantation volumes, allograft scaffold utilization rates, and synthetic polymer adoption curves against GMP facility capacity, tissue bank processing throughput, and arthroscopy instrument installation bases across the projection horizon. Segmentation dimensions include product type, end-user setting, technology modality, and application etiology. CAGRs derive from procedure volume elasticity to reimbursement policy shifts and biologic-device convergence adoption curves.
The model assumes a particular technology adoption path; alternative pathways for three-dimensional bioprinted scaffolds incorporating patient-derived chondrocytes would alter the outlook if first-in-human trials in Rotterdam and Vienna demonstrate superior integration profiles. Forecasts reflect assumptions regarding EMA ATMP pathway efficiency, MDR Article 117 evidence requirement stability, and German statutory insurer prior authorization threshold maintenance. Material deviation in reimbursement negotiations between national health technology assessment bodies and manufacturers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
US Orthopedic Devices Market
Orthopedic Devices
Asia-Pacific Kyphoplasty Market
Orthopedic Devices
Pediatrics Orthotics Market
Orthopedic Devices
Spine Devices Market
Orthopedic Devices
Closed Heel Nursing Shoes Market
Orthopedic Devices
Global Minimally Invasive Spine Surgery Market
Orthopedic Devices
Global Orthopedic Bone Cement Market
Orthopedic Devices
Orthopedic Prosthetic Devices Market
Orthopedic Devices
Global Orthopedic Implant Market
Orthopedic Devices
Global Hip Replacement Implants Market
Orthopedic Devices
Computer-Assisted Orthopedic Surgery Market
Orthopedic Devices
Europe Orthopedic Devices Market
Orthopedic Devices
Humeral Implant Market
Orthopedic Devices
Femoral Head Prostheses Market
Orthopedic Devices
Non-Operative Spine Care Market
Orthopedic Devices
North America Spinal Surgery Market