
 Non-Operative Spine Care Market | 2026-2036
Non-Operative Spine Care Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Operative Spine Care Market Analytics
Physical therapist workforce shortages across major metropolitan areas is collapsing access to conservative spine protocols in key markets. Medtronic leverages its neuromodulation portfolio to sustain relevance in pain management adjacent to non-operative pathways. Stryker Corporation anchors its position through rehabilitation equipment and outpatient clinic infrastructure. Johnson & Johnson competes via DePuy Synthes with motion preservation devices that bridge operative and conservative treatment boundaries.
Non-operative spine care encompasses evidence-based interventions including manual therapy, targeted pharmacologic regimens, epidural steroid injections, and structured exercise protocols designed to alleviate spinal pathology without surgical incision. These modalities rely on precise diagnostic imaging to localize pathology and monitor functional improvement over standardized treatment courses. Injection therapy dominates current revenue pools due to physician reimbursement structures, while physical therapy represents the fastest-growing segment as value-based care contracts expand. Geriatric patient demographics command disproportionate clinical attention given age-related degenerative disc disease prevalence and surgical risk stratification protocols.
FDA oversight of spinal biologics and neuromodulation devices shapes product development timelines and clinical evidence requirements for manufacturers seeking non-operative indications. The Centers for Medicare & Medicaid Services reimbursement policies directly determine outpatient clinic viability and patient access to conservative treatment protocols. Physical therapy licensure boards and state scope-of-practice regulations further fragment market access across jurisdictions. Stakeholders must monitor evolving payer policies on prior authorization requirements and episode-based payment bundles that will determine which treatment settings capture patient volume.
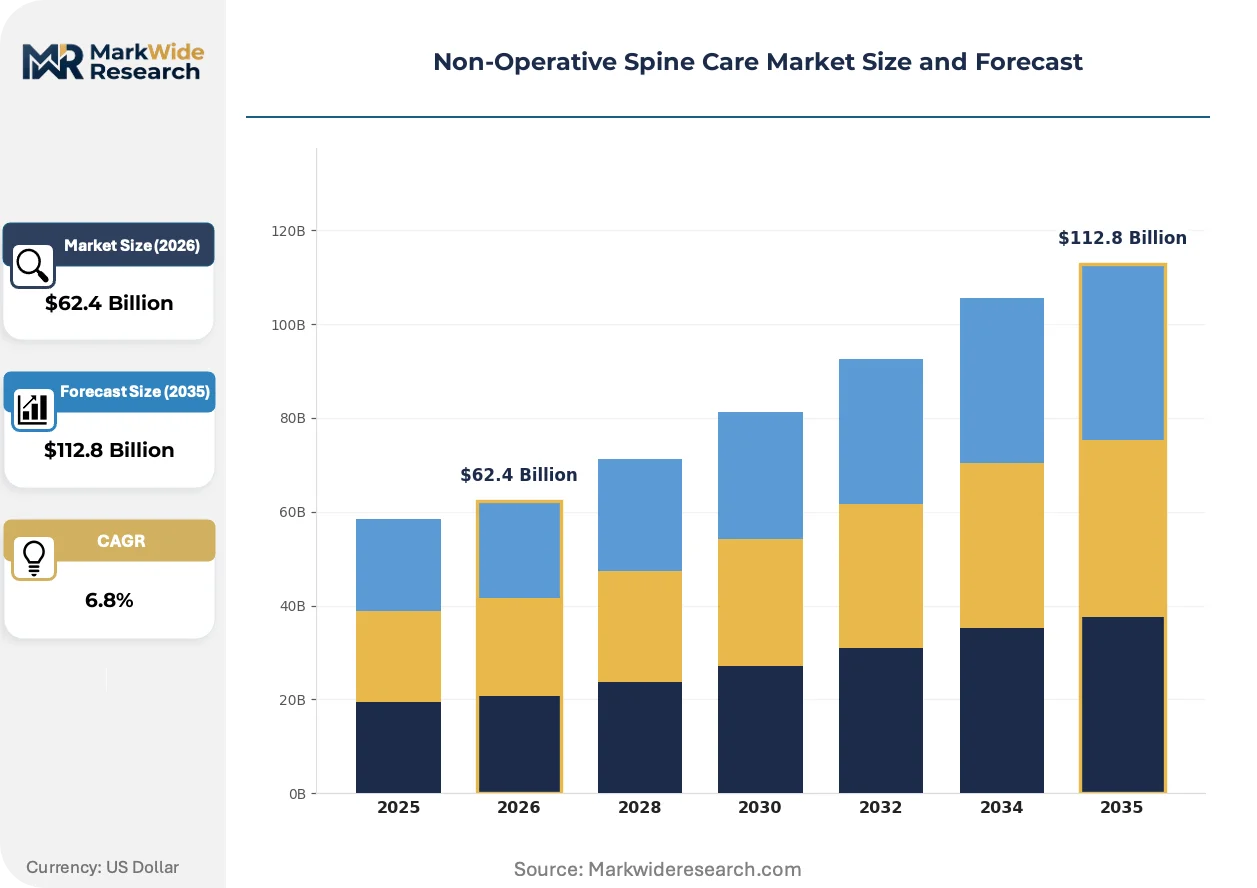
Market Dynamics
The Non-Operative Spine Care Market pivots on CMS reimbursement recalibration that is redirecting patient volume toward outpatient conservative protocols and away from surgical centers. This structural force compresses treatment timelines while expanding physical therapy and injection therapy access across Medicare Advantage networks.
Growth Catalysts
- IRA Hospital Price Transparency Rules:United States facilities now disclose negotiated rates, enabling patients to compare non-operative spine care costs and select conservative options.
- Artificial Intelligence:Machine learning algorithms embedded in diagnostic imaging accelerate pathology localization and treatment personalization for physical therapists.
- Geriatric Concentration:Florida, Arizona, and California retirement corridors generate disproportionate demand for age-appropriate conservative interventions.
Market Restraints
- Specialist Workforce Scarcity:Orthopedic physical therapist vacancies exceed 18% in metropolitan Texas and California markets, capping clinic expansion.
- Biologics Approval Friction:FDA 510(k) pathway modifications for spinal biologics extend development timelines and elevate clinical evidence burdens.
- Pharmacologic Substitution:Oral analgesic protocols and topical NSAID formulations capture mild-to-moderate pain cases that might otherwise proceed to injection therapy.
Strategic Opportunities
- Telehealth Integration:Remote therapeutic monitoring reimbursement codes enable virtual physical therapy delivery into rural United States counties.
- Value-Based Bundles:CMS accountable care organization contracts reward episode-based spine care outcomes, favoring integrated conservative treatment networks.
- Neuromodulation Convergence:Spinal cord stimulation systems paired with biofeedback applications create hybrid non-operative pain management protocols.
Industry Challenges
- Interoperability Friction:Electronic health record fragmentation between hospital systems and independent physical therapy clinics obstructs care coordination.
- Credentialing Bottlenecks:State physical therapy licensure boards impose variable continuing education requirements that complicate multi-state practice expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Operative Spine Care Market |
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $112.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Physical Therapy, Chiropractic Care, Medication, Injection Therapy Patient Demographic: Geriatric, Adult, Adolescent, Pediatric Condition Type: Herniated Disc, Spinal Stenosis, Degenerative Disc Disease, Muscle Strain Treatment Setting: Outpatient Clinic, Home Care, Rehabilitation Center, Wellness Center |
| Companies Covered | Medtronic, Stryker Corporation, Johnson & Johnson (DePuy Synthes), Zimmer Biomet Holdings, Inc., NuVasive, Inc., Globus Medical, Inc., B. Braun Melsungen AG, Orthofix Medical Inc., RTI Surgical, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Operative Spine Care Market Evolving Landscape
Digital health infrastructure is compressing diagnostic-to-treatment intervals while wearable biosensors enable remote monitoring of spinal mobility metrics. These shifts are restructuring how conservative care protocols are prescribed, delivered, and reimbursed across outpatient networks.
Portable neuromodulation devices for home-based pain management is miniaturizing previously clinic-bound technology. Medicare Advantage plans in Florida and Arizona are covering these units for chronic low back pain patients. The form factor reduction is collapsing the boundary between supervised and self-administered conservative care.
CMS is expanding prior authorization requirements for epidural steroid injections in lumbar spinal stenosis cases. This administrative burden is redirecting physician attention toward physical therapy-first protocols. United States pain management practices are hiring dedicated authorization staff to navigate documentation complexity.
Employer-sponsored health plans are unbundling physical therapy from bundled surgical episodes. Large self-insured employers in manufacturing and logistics verticals are contracting directly with outpatient spine clinics. Texas and Ohio industrial corridors exhibit the strongest concentration of this direct-to-employer contracting activity.
Non-Operative Spine Care Market Segmentation
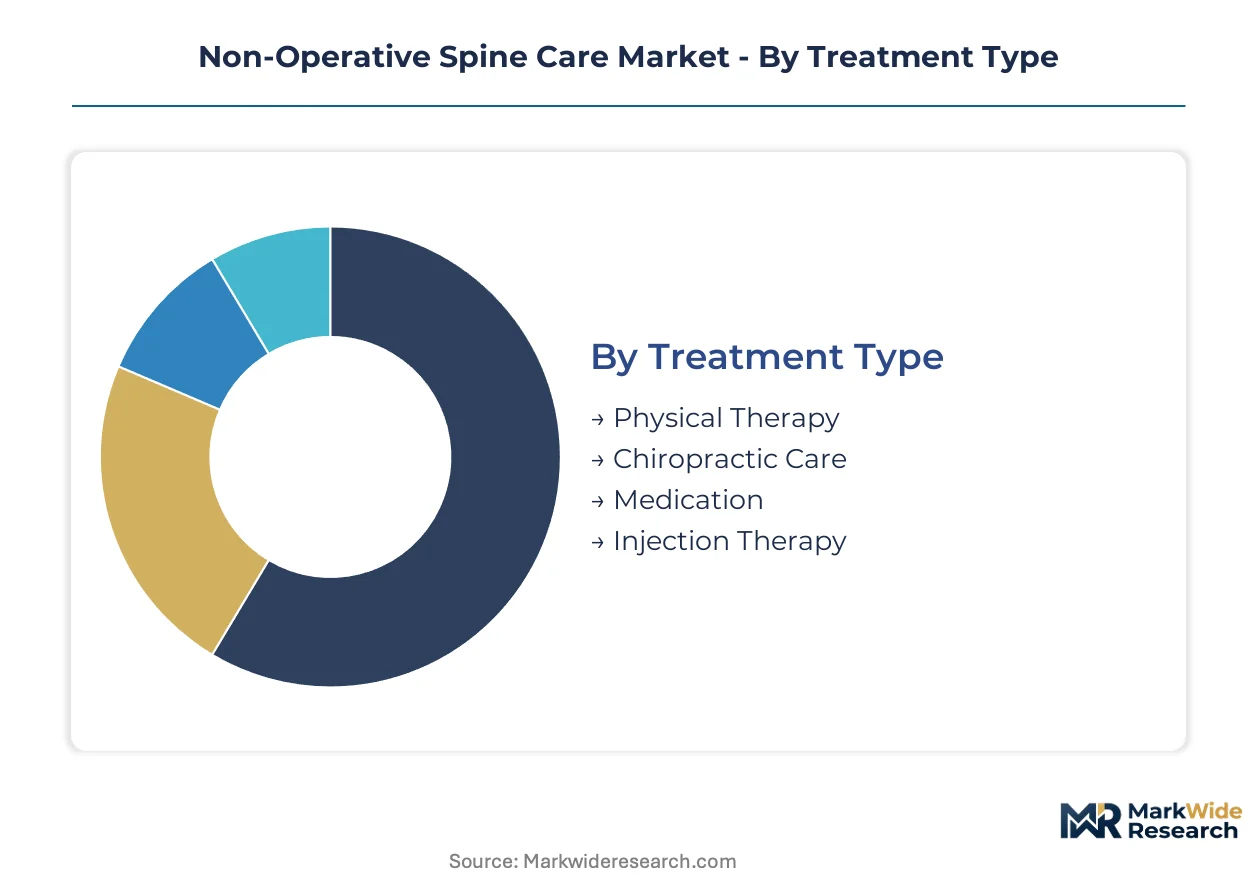
Non-operative spine care segmentation reveals how reimbursement structures, patient risk profiles, and care delivery settings fragment commercial opportunity. Treatment modality selection, patient age stratification, pathology type, and site of service each command distinct regulatory pathways and margin structures.
Treatment Type:
FDA 510(k) clearance requirements for spinal biologics and neuromodulation devices create divergent competitive moats across conservative intervention categories.
- Physical Therapy:Structured exercise protocols, manual therapy, and neuromuscular re-education delivered by licensed practitioners. CMS remote therapeutic monitoring codes now reimburse virtual delivery into rural United States counties, expanding Medicare Advantage network penetration.
- Injection Therapy:Epidural steroid injections, facet joint blocks, and nerve root injections performed under fluoroscopic guidance. Prior authorization requirements from CMS for lumbar spinal stenosis cases are compressing volume in United States pain management practices while elevating documentation burdens.
- Chiropractic Care:Spinal manipulation and mobilization techniques administered by licensed chiropractors. Scope-of-practice variations across state licensure boards fragment multi-state clinic expansion.
- Medication:Oral analgesics, muscle relaxants, and topical NSAID formulations prescribed for symptom management. Pharmacologic substitution captures mild-to-moderate pain cases that might otherwise proceed to interventional procedures.
Established volume favors injection therapy; emerging adoption favors physical therapy.
Patient Demographic:
Cost tier stratification aligns with surgical risk stratification protocols and reimbursement intensity.
- Geriatric:Patients aged 65 and older presenting age-related degenerative disc disease and spinal stenosis. Florida, Arizona, and California retirement corridors generate disproportionate demand for age-appropriate conservative interventions under Medicare Advantage structures.
- Adult:Working-age population with occupational and post-traumatic spinal conditions. Large self-insured employers in Texas and Ohio manufacturing verticals contract directly with outpatient spine clinics for this cohort.
- Adolescent:Young patients with sports-related injuries and early-onset scoliosis. School-based athletic programs and pediatric orthopedic networks concentrate demand.
- Pediatric:Children requiring developmental spinal assessment and congenital anomaly management. Specialized pediatric rehabilitation centers and children's hospital networks capture this low-incidence, high-complexity segment.
Reimbursement intensity peaks with geriatric patients; commercial margin concentrates with adult employer-sponsored populations.
Condition Type:
Application urgency and progression risk determine treatment setting and modality selection.
- Degenerative Disc Disease:Age-related disc dehydration and height loss causing axial back pain. Longitudinal management protocols favor physical therapy-first approaches with injection therapy reserved for acute flare-ups.
- Spinal Stenosis:Neural foraminal narrowing producing neurogenic claudication. CMS prior authorization requirements for epidural steroid injections are redirecting physician attention toward conservative protocols in United States Medicare populations.
- Herniated Disc:Nucleus pulposus extrusion with radiculopathy. Diagnostic imaging localization enables targeted injection therapy or surgical triage based on neurological deficit severity.
- Muscle Strain:Soft tissue injury without structural spinal pathology. Self-limiting condition captured by primary care and urgent care channels with minimal specialist referral.
Chronic condition management favors degenerative disc disease; acute intervention volume concentrates with herniated disc presentations.
Treatment Setting:
Supply concentration in outpatient infrastructure is reshaping site-of-service economics.
- Outpatient Clinic:Physician-owned and hospital-affiliated ambulatory facilities delivering injection therapy and physical therapy. United States facility price transparency rules enable patient cost comparison and conservative option selection.
- Rehabilitation Center:Post-acute facilities providing intensive multidisciplinary spine programs. Episode-based payment bundles from CMS accountable care organizations reward integrated conservative treatment networks.
- Home Care:Portable neuromodulation devices and remote therapeutic monitoring for self-administered pain management. Medicare Advantage plans in Florida and Arizona cover home-based units for chronic low back pain patients.
- Wellness Center:Corporate and commercial fitness-integrated prevention programs. Direct-to-employer contracting in manufacturing and logistics verticals concentrates demand in Texas and Ohio industrial corridors.
Reimbursement stability anchors outpatient clinic volume; growth trajectory steepest in home care delivery models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands premium pricing for non-operative spine protocols while India operates on compressed cost structures serving comparable patient volumes. This asymmetry redirects medical tourism flows and shapes cross-border equipment procurement patterns.
United States
Medicare Advantage expansion and direct-to-employer contracting by self-insured manufacturers drive volume concentration. FDA 510(k) pathway modifications for spinal biologics extend development timelines and elevate clinical evidence burdens. Texas and Ohio industrial corridors exhibit the strongest concentration of employer-direct spine clinic contracting.
Germany
Aging demographics and statutory health insurance reimbursement stability sustain outpatient physical therapy demand. EMA oversight of neuromodulation devices shapes product registration requirements for conservative pain management technologies. Bavaria and North Rhine-Westphalia anchor rehabilitation center networks serving cross-border Austrian and Dutch patients.
Japan
Super-aged population concentration and long-term care insurance expansion accelerate geriatric conservative care adoption. PMDA regulatory frameworks for home-use medical devices enable portable neuromodulation market entry. The Kanto region surrounding Tokyo concentrates specialized spine rehabilitation facilities.
India
Post-traumatic occupational spine conditions in manufacturing and logistics sectors drive working-age patient volume. CDSCO medical device classification rules determine import pathway complexity for conservative care equipment. Maharashtra and Gujarat urban clusters concentrate corporate hospital outpatient spine centers.
Australia
Medicare Benefits Schedule revisions redirect lumbar spinal stenosis cases toward physical therapy-first protocols. TGA approval requirements for spinal biologics influence product launch sequencing. New South Wales and Victoria metropolitan areas concentrate private practice pain management clinics.
Non-Operative Spine Care Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the non-operative spine care market. Consolidated medical device conglomerates with neuromodulation portfolios compete against fragmented physical therapy clinic networks and independent rehabilitation equipment fabricators. Three archetypes dominate: diversified spine technology conglomerates, specialized conservative care equipment manufacturers, and vertically integrated outpatient clinic operators. M&A activity concentrates around digital health platforms and remote therapeutic monitoring capabilities, while geographic expansion targets Medicare Advantage-dense retirement corridors.
Among diversified spine technology conglomerates, Medtronic, Stryker Corporation, and Johnson & Johnson occupy positions that exemplify the technology-intensive archetype. Medtronic represents the neuromodulation-centered approach to pain management adjacent to conservative pathways. Stryker Corporation anchors the rehabilitation equipment and outpatient infrastructure vector. Johnson & Johnson through DePuy Synthes sits within the motion preservation device segment that bridges operative and non-operative treatment boundaries.
| Leading Market Players |
|---|
| Medtronic |
| Stryker Corporation |
| Johnson & Johnson (DePuy Synthes) |
| Zimmer Biomet Holdings, Inc. |
| NuVasive, Inc. |
| Globus Medical, Inc. |
| B. Braun Melsungen AG |
| Orthofix Medical Inc. |
| RTI Surgical, Inc. |
| Others |
Value Network & Pricing Analysis
Equipment utilization rates in outpatient clinic networks anchor cost structures across injection therapy and physical therapy delivery, concentrating margin leverage with multi-site operators while compressing price floors for independent practices competing on CMS reimbursement schedules.
Pricing Analysis
Configured-to-order pricing for customized neuromodulation devices commands spreads of 40-60% above standard catalog configurations, with FDA 510(k) clearance tier and software integration depth as primary differentiation drivers. Subscription-based remote therapeutic monitoring is displacing per-session physical therapy billing, though price erosion runs through injection therapy as prior authorization requirements expand. Employer-sponsored populations exhibit lowest price sensitivity; Medicare Advantage networks face highest cost compression.
Supply Chain Analysis
Port congestion at Los Angeles-Long Beach and container availability constraints on Asia-Pacific trade lanes are elevating inbound logistics costs for neuromodulation device components and rehabilitation equipment assemblies. Manufacturing concentrates in the United States, Germany, and China, with semiconductor inputs for biofeedback systems and medical-grade polymers for injection catheters as critical dependencies. Single-source vulnerability in spinal cord stimulation chipsets presents structural risk. Distribution runs through GPO-contracted hospital systems and direct-to-clinic arrangements with outpatient networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized orthopedic physical therapist shortages in Texas and California retirement corridors constrain clinic expansion velocity, creating a capability-scarcity environment where workforce access determines competitive position more than equipment or technology.
For Market Incumbents: Compound neuromodulation portfolio depth with remote therapeutic monitoring platform acquisitions to defend against digital health entrants capturing Medicare Advantage reimbursement codes. Expand physical therapy clinic density in Florida and Arizona retirement corridors ahead of workforce competition. Prioritize backward integration into injection therapy consumables manufacturing to protect margin from supply cost volatility.
For New Entrants and Emerging Players: Rural county virtual physical therapy delivery represents the most penetrable service-layer gap, as CMS remote therapeutic monitoring codes enable reimbursement parity with urban clinic visits without brick-and-mortar overhead. Target direct-to-employer contracting in Ohio and Texas manufacturing verticals, positioning home-based portable neuromodulation units as surgical avoidance solutions under value-based care contracts.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated outpatient clinic operators with captive physical therapy and injection therapy capabilities under single tax identification. Long-term viability hinges on Medicare Advantage network penetration depth and prior authorization navigation infrastructure. Monitor FDA 510(k) clearance velocity for spinal biologics as inflection indicator for conservative modality investment returns.
| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy Development | CMS remote therapeutic monitoring code capture determines Medicare Advantage network viability and rural market access. |
| Hospital System Partnership | Integrated delivery network contracts secure patient volume referrals and episode-based payment bundle participation. |
| Software Companion Development | Biofeedback-enabled neuromodulation applications differentiate home-based devices from clinic-bound competitors. |
| CE Marking Pathway | EMA clearance for portable neuromodulation devices enables German statutory insurance reimbursement and cross-border Austrian patient flows. |
| Acquisition of Specialist Firm | Digital health platforms with AI-enabled diagnostic imaging accelerate pathology localization and treatment personalization. |
Research Methodology
Cross-validation between hospital purchasing committee interviews and CMS Medicare claims data anchors the qualitative findings on reimbursement pathway viability and patient volume distribution. Primary discussions with pain management physicians, physical therapy clinic operators, biomedical engineers, and GPO contracts managers combined with secondary sources including FDA 510(k) filings, hospital procurement databases, and Medicare Advantage plan formulary documents. Bottom-up clinic capacity modeling and top-down spending flow analysis provided triangulation.
Sensitivity analysis around CMS reimbursement recalibration scenarios and physical therapist workforce growth assumptions shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include treatment modality, patient age stratification, pathology type, and site of service, with regional regulatory cluster as an additional healthcare-specific dimension. CAGRs derived from historical volume trajectories and elasticity-adjusted demand curves, incorporating geriatric demographic projections and Medicare Advantage penetration curves as spine-specific inputs.
Underlying assumptions cover stable FDA oversight frameworks for spinal biologics and neuromodulation devices, with deviation risk concentrated in prior authorization requirement expansion and state physical therapy licensure board scope-of-practice modifications. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Orthopedic Fracture Repairing Implants for Osteoporosis Market
Orthopedic Devices
Bone Void Fillers Market
Orthopedic Devices
UAE Spinal Surgery Devices Market
Orthopedic Devices
Orthopedic Trauma Fixation Devices Market
Orthopedic Devices
Global Minimally Invasive Spine Surgery Market
Orthopedic Devices
Podiatry Laser Market
Orthopedic Devices
Saudi Arabia Spinal Surgery Devices Market
Orthopedic Devices
Europe Orthopedic Devices Market
Orthopedic Devices
Global Personalized 3D Printed Orthopedic Implants Market
Orthopedic Devices
Orthopedic Artificial Bone Defect Repair Materials Market
Orthopedic Devices
Wrist Replacement Orthopedic Devices Market
Orthopedic Devices
Hip Resurfacing Implants Market
Orthopedic Devices
Animal External Fixation Market
Orthopedic Devices
Closed Heel Nursing Shoes Market
Orthopedic Devices
Global Orthopedic Implant Market
Orthopedic Devices
Cartilage Repair Market