
 Global Bone Tumor Ablation Devices Market | 2026-2036
Global Bone Tumor Ablation Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bone Tumor Ablation Devices Market Foresight
A shortage of interventional radiologists trained in percutaneous ablation techniques is collapsing procedure throughput at mid-tier hospitals. Medtronic Plc leverages its integrated navigation and energy platforms to sustain premium positioning across academic medical centers. Boston Scientific Corporation anchors its competitiveness through specialized radiofrequency electrode portfolios designed for osseous tissue.
Bone tumor ablation devices deliver thermal or cryogenic energy through percutaneously placed probes to destroy neoplastic tissue while preserving structural integrity, typically operating at temperatures between 50°C and 150°C for thermal modalities or minus 40°C for cryoablation. These systems serve primarily to palliate painful metastatic lesions and definitively treat benign tumors such as osteoid osteoma. Radiofrequency ablation dominates installed base metrics due to decades of clinical validation and favorable reimbursement coding, while microwave ablation represents the fastest-expanding technology segment owing to faster heating profiles and reduced susceptibility to heat-sink effects from adjacent vasculature. Deployment through ambulatory surgical centers is capturing disproportionate margin pools as payors shift site-of-service incentives away from inpatient stays.
FDA 510(k) premarket notification requirements govern device clearance in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence standards for thermal ablation systems marketed in Europe. Japan's PMDA maintains distinct technical documentation requirements that delay market entry relative to Western timelines. Stakeholders must monitor evolving site-of-service reimbursement decisions and interventional radiology fellowship graduation rates to calibrate capacity investments against procedural demand trajectories.
Market Dynamics
The migration of bone tumor ablation procedures from inpatient oncology wards to ambulatory surgical centers is compressing capital equipment cycles and forcing manufacturers to redesign systems for portable, same-day deployment.
Growth Catalysts
- Favorable Reimbursement Coding:CMS procedural codes in the United States now explicitly cover percutaneous ablation for metastatic bone lesions, accelerating hospital procurement cycles and expanding addressable procedure volumes.
- Microwave Technology Maturation:Faster heating profiles and reduced heat-sink susceptibility are pulling interventional radiologists away from radiofrequency systems in high-throughput academic settings.
- Japan's Aging Demographics:PMDA streamlined technical documentation for thermal ablation devices targeting osteoid osteoma, creating regulatory precedent for faster market entry.
Market Restraints
- Supply Concentration in Electrosurgical Components:Precision RF generators and microwave magnetrons source predominantly from German and Japanese component houses, exposing device assemblers to single-source fragility.
- MDR Clinical Evidence Burden:The EU Medical Device Regulation now demands prospective clinical data for thermal ablation systems, extending CE marking timelines by 18-24 months relative to prior Medical Device Directive pathways.
- Consolidated Buyer Power:Integrated delivery networks in the United States now negotiate enterprise-wide ablation device contracts, compressing realized pricing for standalone equipment purchases.
Strategic Opportunities
- India's Underserved Tertiary Network:CDSCO regulatory harmonization with IMDRF standards is reducing import clearance friction for cryoablation systems targeting private oncology chains in Mumbai and Delhi.
- Navigation-Convergence:Real-time CT-fluoroscopy fusion with electromagnetic tracking is enabling single-operator bone lesion targeting previously requiring dual-physician teams.
- ASC Channel Expansion:Site-of-service payment differentials are pulling capital equipment purchases into physician-owned surgical centers previously served only by hospital outpatient departments.
Industry Challenges
- Interventional Radiology Fellowship Pipeline:ACGME-accredited training positions in percutaneous ablation techniques are growing at half the rate of procedural demand, creating throughput ceilings at mid-tier hospitals.
- Legacy PACS Integration:Ablation planning software from competing vendors employs proprietary DICOM extensions, forcing hospitals into costly middleware development or single-vendor lock-in.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bone Tumor Ablation Devices Market |
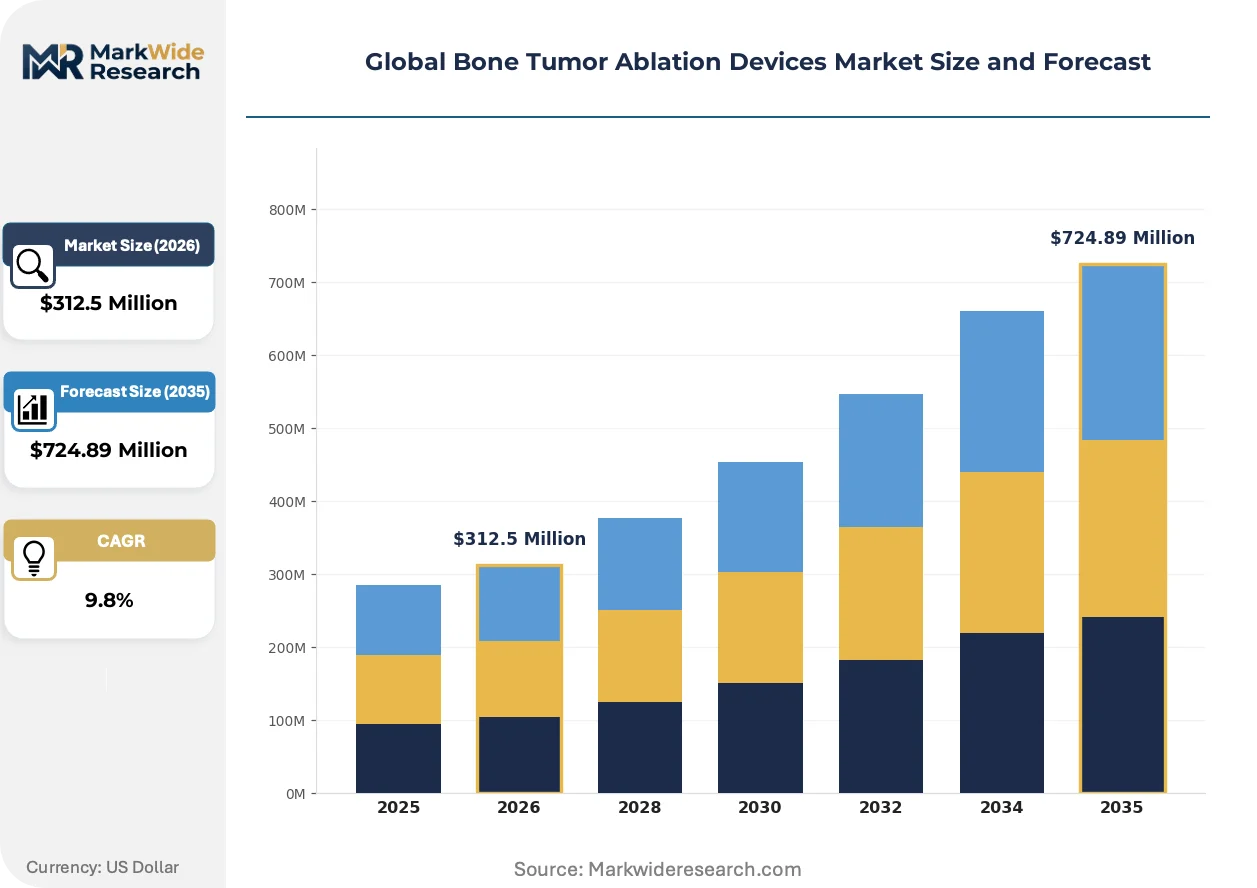
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $724.89 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Radiofrequency Ablation, Cryoablation, Microwave Ablation, Laser Ablation, Ultrasound Ablation Application: Primary Bone Tumors, Metastatic Lesions, Osteoid Osteoma, Chondroblastoma, Giant Cell Tumors End User: Orthopedic Surgeons, Oncologists, Interventional Radiologists, Specialty Clinics, Research Institutes Deployment Model: Hospital Settings, Ambulatory Surgical Centers, Private Clinics, Academic Medical Centers, Diagnostic Centers |
| Companies Covered | Medtronic Plc, Boston Scientific Corporation, AngioDynamics Inc., B. Braun Melsungen AG, Merit Medical Systems Inc., Olympus Corporation, Varian Medical Systems Inc., MedWaves Inc., Mermaid Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bone Tumor Ablation Devices Market Shifts & Advancements
Energy delivery modalities and procedural settings are undergoing simultaneous transformation as thermal physics advances collide with payment reform and workforce constraints.
Microwave ablation systems operating at 915 MHz and 2.45 GHz are displacing conventional radiofrequency platforms in academic medical centers managing high volumes of spinal metastases. Interventional radiology departments at tertiary centers in Germany and the United States are prioritizing microwave acquisition for its insensitivity to char formation and superior performance near vascular structures. The technology is displacing RF-only capital budgets and compressing replacement cycles for installed base equipment.
The EU Medical Device Regulation's post-market surveillance requirements are mandating systematic collection of real-world performance data for Class IIb thermal ablation devices. Manufacturers must now maintain post-market clinical follow-up registries as a condition of CE certificate renewal, fundamentally restructuring quality management system resource allocation. European notified bodies are prioritizing audit capacity for active implantable and thermal ablation categories, creating inspection queue bottlenecks that delay new product introductions.
Hospital procurement committees are unbundling capital equipment from disposable electrode contracts that previously locked buyers into multi-year supply agreements. Independent purchasing cooperatives in the United States are negotiating electrode sourcing separately from generator platforms, fragmenting vendor commercial relationships. This pattern is most pronounced in Texas and Florida health systems where physician employment models create divergent incentives between proceduralists and supply chain administrators.
Global Bone Tumor Ablation Devices Market Segmentation
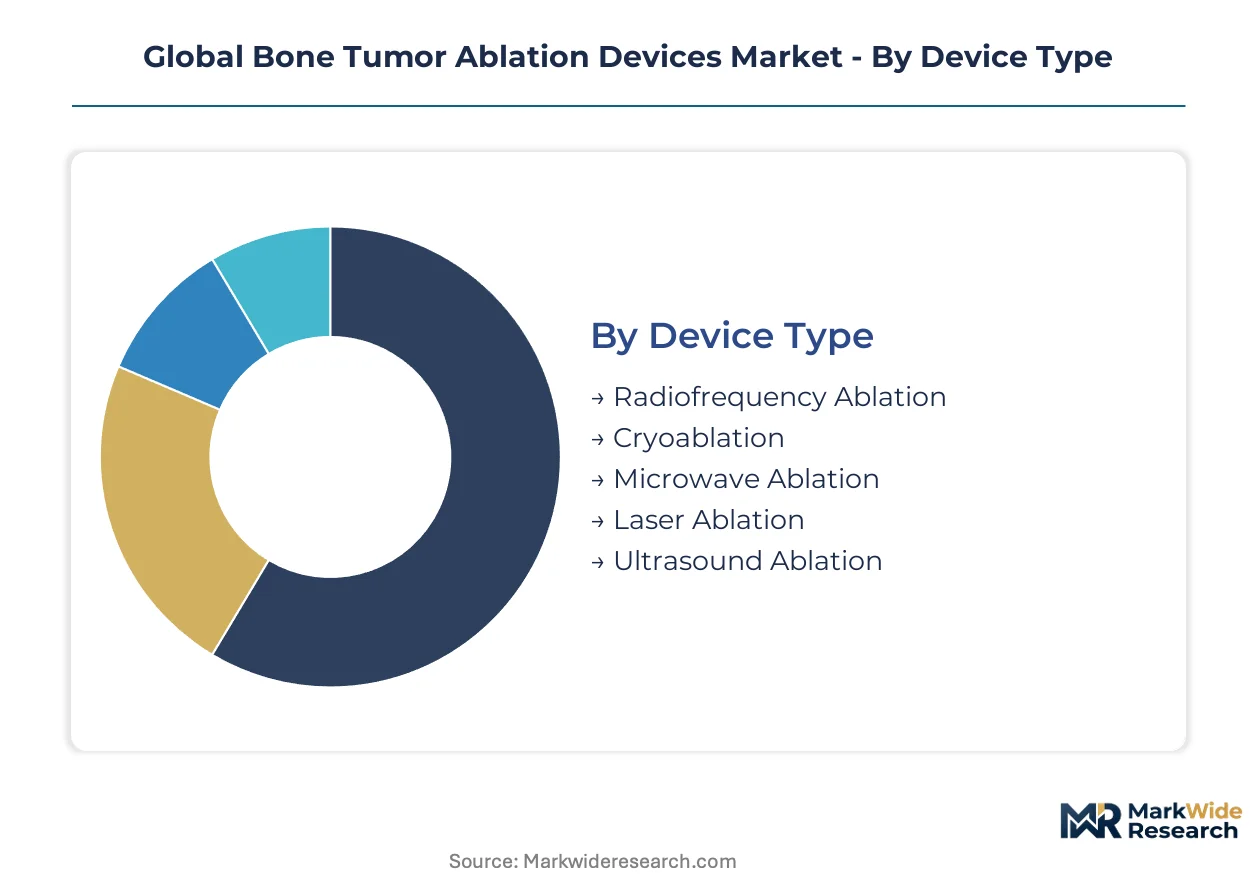
Segmentation reveals how thermal physics, reimbursement pathways, and operator training constraints fragment demand across device modalities and care settings. Understanding these divisions exposes where capital budgets concentrate and which customer cohorts drive replacement cycles.
Device Type:
Domestic demand in the United States and Germany concentrates on radiofrequency and microwave platforms with established CPT reimbursement, while cryoablation and laser systems serve export markets where tissue-preserving iceball visualization commands premium positioning.
- Radiofrequency Ablation:Electromagnetic energy at 460-480 kHz generates frictional heating through ionic agitation, with impedance-monitoring algorithms preventing collateral thermal damage. Demand clusters in United States community hospitals where Medicare reimbursement for metastatic bone lesions has stabilized procurement budgets.
- Microwave Ablation:Electromagnetic radiation at 915 MHz or 2.45 GHz produces rapid volumetric heating through dielectric hysteresis, eliminating dependence on tissue conductivity. Academic medical centers in Germany and Japan are prioritizing these systems for spinal metastases near critical vasculature.
- Cryoablation:Joule-Thomson expansion of argon gas creates minus 40°C iceballs with CT-visible margins, enabling real-time treatment monitoring. Private oncology chains in India and Brazil favor this modality for osteoid osteoma in pediatric populations.
- Laser Ablation:Nd:YAG or diode lasers deliver precise thermal necrosis through fiberoptic probes, requiring smaller access tracts than RF electrodes. Research institutes in Switzerland and the Netherlands deploy these systems for preclinical dosimetry studies.
- Ultrasound Ablation:High-intensity focused ultrasound generates mechanical and thermal tissue destruction without percutaneous instrumentation. Japanese regulatory pathways for this non-invasive modality are creating precedent for PMDA approval timelines.
Radiofrequency Ablation holds the largest share; momentum sits with Microwave Ablation.
Application:
Cost tier stratification separates palliative metastatic procedures reimbursed under bundled payment models from definitive benign tumor treatments commanding out-of-pocket premium pricing in private settings.
- Primary Bone Tumors:Chondrosarcoma and osteosarcoma ablation requires wide margins and adjuvant systemic therapy coordination. Tertiary sarcoma centers in Milan and Houston maintain dedicated multidisciplinary protocols for these complex cases.
- Metastatic Lesions:Percutaneous thermal destruction of spinal and pelvic metastases from lung, breast, and prostate primaries dominates procedure volumes. United States ASC site-of-service differentials are accelerating same-day discharge protocols for these patients.
- Osteoid Osteoma:Radiofrequency ablation has displaced surgical en-bloc resection as the definitive standard for this benign but painful lesion. Pediatric orthopedic departments in Paris and Tokyo report 95% pain resolution at 12-month follow-up.
- Chondroblastoma:Epiphyseal location in young patients demands precise thermal control to preserve growth plates. Academic centers with navigation-integrated systems in Boston and Heidelberg capture disproportionate case referrals.
- Giant Cell Tumors:Denosumab pre-treatment followed by curettage and adjuvant ablation represents evolving practice patterns. Orthopedic oncology units in Sydney and Singapore are standardizing this combined-modality approach.
Metastatic Lesions command the highest procedure volume; steepest expansion trajectory belongs to Osteoid Osteoma as pediatric referral networks mature.
End User:
Customer type fragmentation reflects divergent training pathways—surgical residencies versus interventional radiology fellowships—creating distinct purchasing committees with incompatible evaluation criteria.
- Orthopedic Surgeons:Surgical oncologists prioritize mechanical stability and post-ablation structural assessment, favoring systems with integrated navigation. University hospitals in Madrid and Chicago anchor demand for these combined platforms.
- Oncologists:Medical oncology departments coordinate ablation within systemic therapy sequences, requiring scheduling flexibility and multidisciplinary tumor board integration. Cancer centers in London and Melbourne emphasize workflow interoperability.
- Interventional Radiologists:Percutaneous specialists drive volume growth through image-guided expertise, with ACGME fellowship expansion lagging procedural demand across United States mid-tier markets.
- Specialty Clinics:Physician-owned musculoskeletal practices in Texas and Florida are acquiring compact RF generators for office-based lesion treatment, bypassing hospital outpatient department scheduling constraints.
- Research Institutes:Preclinical and clinical trial centers in Rotterdam and Shanghai evaluate next-generation energy modalities, generating early efficacy data for regulatory submissions.
Interventional Radiologists hold the largest share; momentum concentrates with Specialty Clinics as ASC channel incentives deepen.
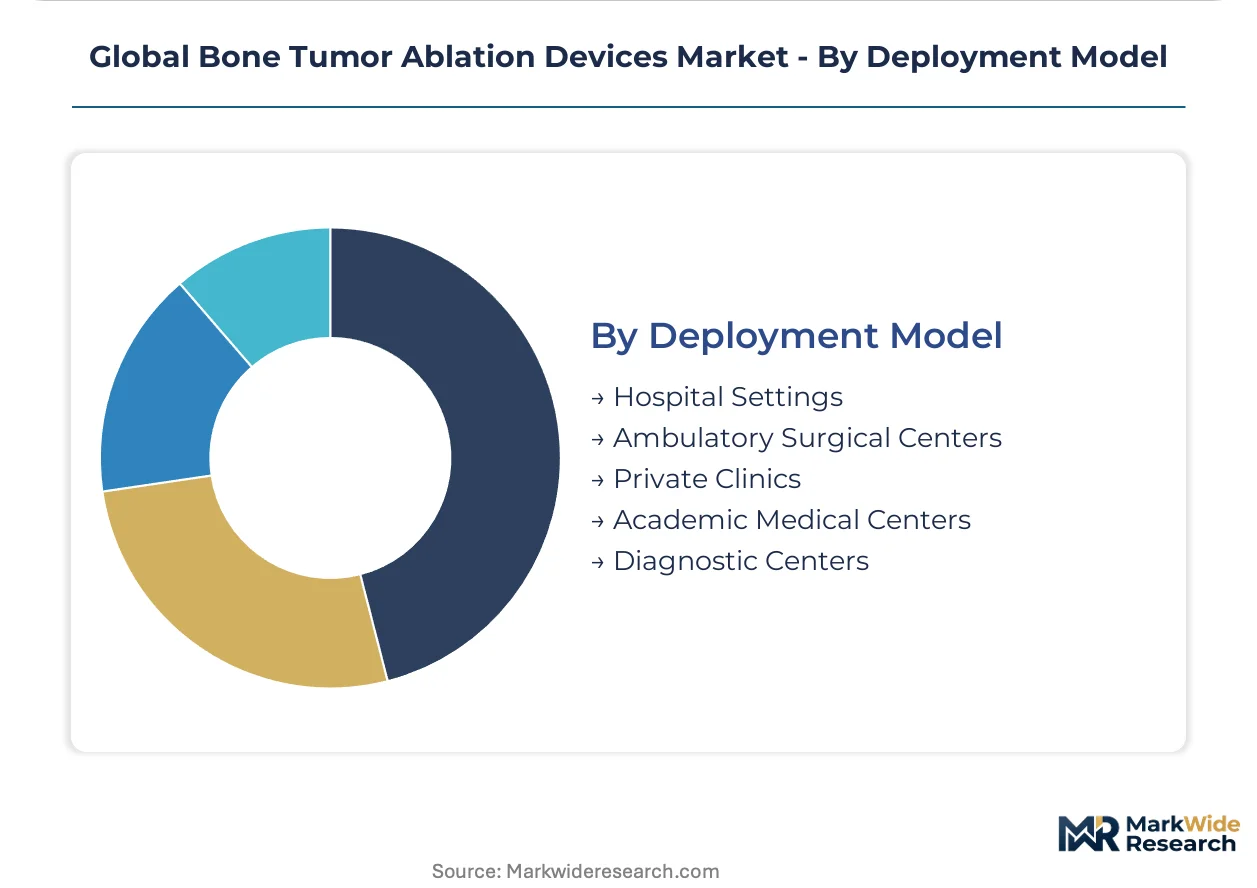
Deployment Model:
Supply concentration in generator manufacturing favors high-volume hospital purchasers, while portable system design enables ambulatory and private clinic penetration previously blocked by capital intensity barriers.
- Hospital Settings:Inpatient oncology wards maintain backup capabilities for complex cases requiring overnight observation, though procedure volume is migrating to outpatient alternatives.
- Ambulatory Surgical Centers:Same-day discharge protocols for metastatic bone lesion ablation capture favorable Medicare site-of-service differentials. United States ASCs in Arizona and Pennsylvania are expanding interventional radiology service lines aggressively.
- Private Clinics:Independent musculoskeletal practices in São Paulo and Mumbai deploy compact cryoablation systems for osteoid osteoma, leveraging direct patient payment models outside public reimbursement frameworks.
- Academic Medical Centers:Teaching hospitals in Berlin and Kyoto train the interventional radiology workforce while evaluating microwave and navigation-convergent technologies for protocol standardization.
- Diagnostic Centers:Imaging facilities in Dubai and Bangkok are adding therapeutic capabilities to existing CT and MRI infrastructure, converting diagnostic relationships into procedural revenue streams.
Hospital Settings retain the largest installed base; Ambulatory Surgical Centers are gaining share fastest as payment reform accelerates site-of-service migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Japanese tertiary oncology networks where bundled reimbursement for metastatic bone procedures exceeds United States Medicare rates by substantial margins. Emerging private oncology chains in India and Brazil capture premium out-of-pocket payments for cryoablation outside public reimbursement frameworks. Regulatory divergence across FDA, MDR, and PMDA pathways fragments commercialization timelines and creates arbitrage opportunities for region-specific product configurations.
United States
CMS procedural codes for percutaneous bone tumor ablation stabilize hospital procurement budgets and accelerate same-day discharge protocols at ambulatory surgical centers. FDA 510(k) clearance pathways maintain predictable premarket notification timelines for thermal ablation systems. Interventional radiology departments in Houston and Chicago anchor demand for navigation-integrated microwave platforms.
Germany
Academic medical centers in Heidelberg and Berlin prioritize microwave acquisition for spinal metastases near critical vasculature. MDR CE marking demands prospective clinical evidence that extends certification timelines relative to prior Medical Device Directive pathways. Notified bodies concentrate audit capacity on thermal ablation categories, creating inspection queue bottlenecks.
Japan
PMDA streamlined technical documentation for thermal ablation devices targeting osteoid osteoma, establishing regulatory precedent for faster market entry. Aging demographics expand the addressable patient pool for palliative metastatic procedures. Tertiary centers in Tokyo and Kyoto train the interventional radiology workforce while evaluating next-generation energy modalities.
India
CDSCO regulatory harmonization with IMDRF standards reduces import clearance friction for cryoablation systems. Private oncology chains in Mumbai and Delhi deploy compact generators for osteoid osteoma under direct patient payment models. Diagnostic centers in Bangalore add therapeutic capabilities to existing imaging infrastructure.
Brazil
ANVISA registration pathways for thermal ablation devices lag FDA and MDR timelines, favoring established multinational suppliers with regulatory affairs infrastructure. Private musculoskeletal practices in São Paulo acquire portable RF systems for office-based lesion treatment. Out-of-pocket payment concentration in southeastern states creates pricing stratification versus public hospital procurement.
Global Bone Tumor Ablation Devices Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated navigation platforms commanding premium positioning while standardized RF generators compete on electrode pricing. The vendor base clusters around three strategic tiers: diversified medical technology conglomerates with enterprise-wide hospital contracts, interventional oncology specialists with focused energy portfolios, and regional component assemblers serving price-sensitive private clinic channels. Dominant competitive moves include M&A for navigation software capabilities and strategic partnerships to secure electrosurgical component supply.
Among diversified medical technology conglomerates, Medtronic Plc and Boston Scientific Corporation occupy positions exemplifying the integrated platform archetype. Medtronic leverages navigation and energy convergence to sustain premium positioning across academic medical centers. Boston Scientific anchors competitiveness through specialized electrode portfolios designed for osseous tissue. Merit Medical Systems Inc. represents the interventional oncology specialist tier with focused capital equipment and disposable sourcing. These three companies illustrate how scale-driven conglomerates and focused specialists coexist through differentiated channel access and reimbursement positioning.
| Leading Market Players |
|---|
| Medtronic Plc |
| Boston Scientific Corporation |
| AngioDynamics Inc. |
| B. Braun Melsungen AG |
| Merit Medical Systems Inc. |
| Olympus Corporation |
| Varian Medical Systems Inc. |
| MedWaves Inc. |
| Mermaid Medical |
| Others |
Supply & Pricing Matrix
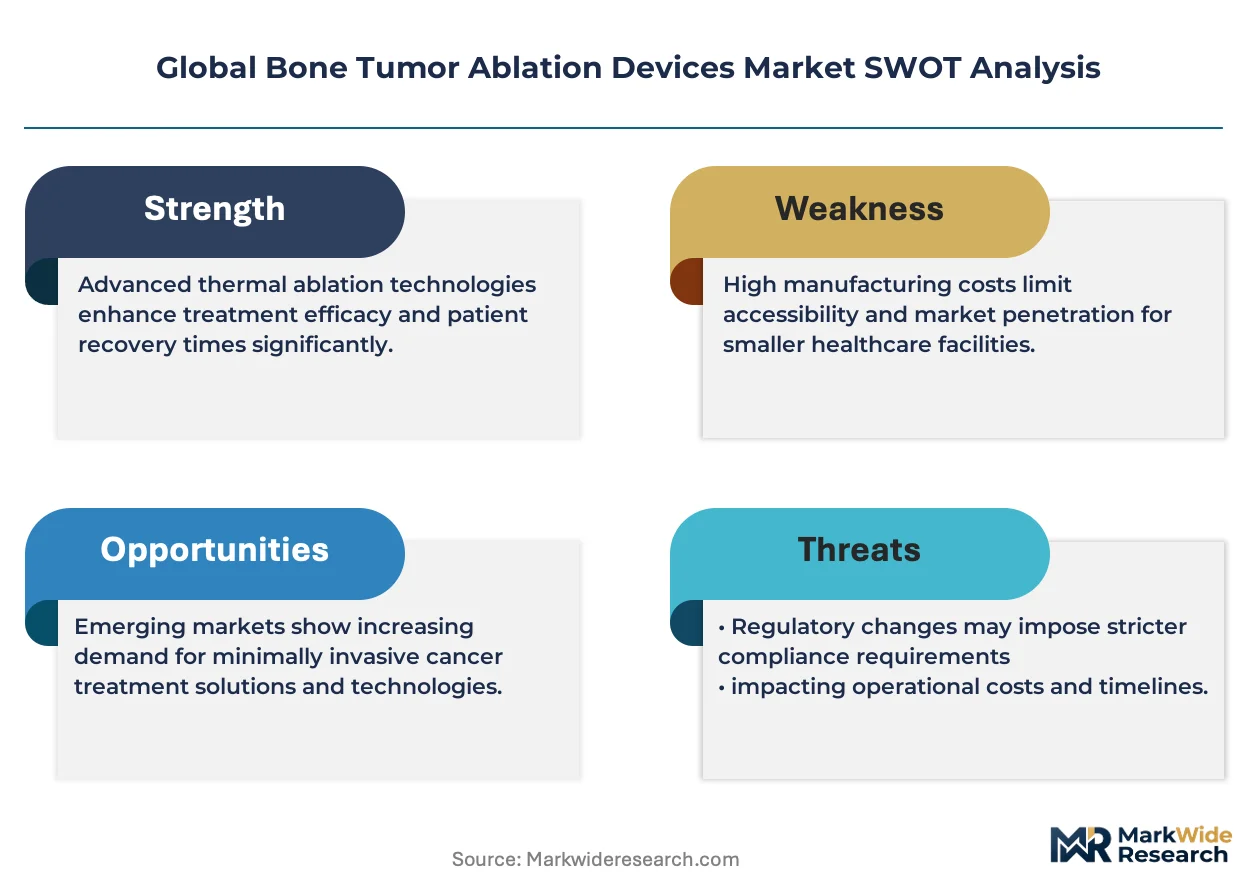
FDA 510(k) clearance pathways and MDR CE marking regimes gate both supply qualification and price differentiation simultaneously, compressing margins for non-certified assemblers while enabling premium capture for integrated platform vendors with established regulatory affairs infrastructure. Buyers in academic medical centers and ambulatory surgical centers face divergent total-cost-of-ownership calculations that fragment pricing power across deployment settings.
Pricing Analysis
German and Japanese tertiary oncology networks command substantial premiums over United States Medicare reimbursement rates for bundled metastatic bone procedures, creating geographic price spreads exceeding standard procurement differentials. Three-tier pricing structure across premium navigation-integrated platforms, standard RF generators, and economy electrode bundles dominates capital equipment transactions, with certification grade and volume scale as primary differentiation drivers. Cost compression in the electrode tier intensifies as independent purchasing cooperatives unbundle disposable contracts from generator platforms. Community hospitals in United States mid-tier markets exhibit highest price sensitivity; academic medical centers with enterprise-wide contracts show least.
Supply Chain Analysis
Inventory cycles for precision RF generators and microwave magnetrons stretch 16-24 weeks, constraining OEM responsiveness to hospital procurement surges. Component sourcing concentrates in Germany and Japan for electrosurgical subsystems, with final device assembly distributed across United States, Ireland, and Singapore manufacturing footprints. Raw material dependencies include tantalum capacitors, ceramic insulators, and argon gas delivery systems. Single-source vulnerability in magnetron supply from Japanese component houses exposes assemblers to production disruption. Distribution runs through hospital purchasing cooperatives and GPO contracts in developed markets, direct-to-clinic channels in private-pay emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are inflecting as navigation-software convergence collapses the dual-physician team model into single-operator workflows, creating winner-take-most dynamics for vendors controlling electromagnetic tracking and CT-fluoroscopy fusion ecosystems.
For Market Incumbents: Secure electrode supply agreements with German and Japanese component houses before magnetron allocation constraints tighten, insulating against single-source fragility that could cripple microwave platform rollout. Defend installed base positions by embedding proprietary DICOM extensions into ablation planning software, raising switching costs for hospital customers confronting legacy PACS integration challenges. Capacity addition in Singapore and Ireland manufacturing footprints addresses MDR audit queue bottlenecks compressing European product introduction timelines. For New Entrants and Emerging Players: PMDA streamlined documentation pathways for osteoid osteoma thermal ablation devices create regulatory fast-track opportunities for compact cryoablation systems targeting Japan's aging demographic expansion. Private oncology chains in Mumbai and Delhi represent the most penetrable geography, with CDSCO harmonization reducing import clearance friction against ANVISA lag in Brazil. Direct-to-clinic sales models bypassing hospital purchasing committees offer the clearest go-to-market angle for price-disruptive portable generators. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across portable RF and cryoablation system categories as semiconductor integration reduces generator footprint and power requirements, enabling physician-owned clinic channel penetration previously blocked by capital barriers. Acquisition target archetype: interventional oncology specialists with focused energy portfolios and established reimbursement strategy capabilities, vulnerable to navigation-convergence disruption from diversified conglomerates. Interventional radiology fellowship graduation rates versus procedural demand trajectories serve as the critical inflection indicator for capacity investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Navigation-Convergence Development | Real-time CT-fluoroscopy fusion with electromagnetic tracking collapses dual-physician teams into single-operator workflows at academic centers. |
| CE Marking Pathway Investment | MDR prospective clinical evidence requirements extend certification timelines, favoring early movers with quality management system infrastructure. |
| Ambulatory Surgical Center Partnership | Site-of-service payment differentials pull capital equipment purchases into physician-owned centers bypassing hospital procurement. |
| Electrode Supply Agreement | Long-term contracts with German and Japanese component houses insulate against magnetron single-source fragility. |
| Software Companion Development | Proprietary DICOM extensions in ablation planning software raise hospital switching costs and defend installed base positions. |
Research Methodology
A spread of perspectives from interventional radiologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers converged on the working assumptions underlying demand trajectories and pricing dynamics. Primary interview insights combined with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and MDR notified body audit disclosures. Bottom-up procedure volume estimates triangulated against top-down capital equipment shipment data from generator manufacturers and electrode suppliers.
Segmentation dimensions modeled span device type, application lesion category, end-user specialty, and deployment setting across the projection horizon. Analytical framework derived CAGRs from installed base replacement cycles, reimbursement code expansion trajectories, and interventional radiology workforce pipeline constraints. Forecast inputs incorporated site-of-service migration rates from inpatient to ambulatory settings and microwave technology displacement curves against radiofrequency installed base.
Decision-makers should treat outputs as directional under assumptions of stable CMS reimbursement coding and ACGME fellowship expansion rates; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Large Volume Nebulizers Market
Medical Devices
Wearable Breast Pumps Market
Medical Devices
Medical Device Complaint Management Market
Medical Devices
Next Generation Implants (NGI) Market
Medical Devices
SPG Microstimulator System Market
Medical Devices
Cystic Fibrosis Devices Market
Medical Devices
Nasal Packing Devices Market
Medical Devices
Upper Limb Prosthetics Market
Medical Devices
Biodegradable Stents Market
Medical Devices
MRI Safe Biopsy Needle Market
Medical Devices
Ventricular Restoration Systems Market
Medical Devices
Canada Ultrasound Devices Market
Medical Devices
Global Wearable Injectors Market
Medical Devices
Small Bowel Enteroscopes Market
Medical Devices
Global Dermatoscope Market
Medical Devices
Asia-Pacific Interventional Cardiology and Peripheral Vascular Devices Market