
 Ultrasound Stimulator Market | 2026-2036
Ultrasound Stimulator Market Size, Share, and Industry Trends Forecast 2026-2036
Ultrasound Stimulator Market Insights
Clinical-grade therapeutic output specifications is collapsing the gap between professional rehabilitation equipment and consumer-grade alternatives. Zimmer MedizinSysteme GmbH leverages its German engineering heritage to dominate hospital procurement channels across Western Europe. Fujifilm Sonosite anchors its position through portable system miniaturization that extends point-of-care accessibility. Esaote competes on specialized musculoskeletal imaging integration with therapeutic delivery modules.
An ultrasound stimulator generates acoustic waves typically between 1-3 MHz frequency to produce thermal and non-thermal biological effects in soft tissue, employing piezoelectric crystal transducers for energy conversion and delivery. These devices serve primarily to accelerate tissue repair, modulate pain signaling, and enhance drug penetration in clinical rehabilitation settings. Portable stimulators now capture expanding share in home-based care models where physiotherapy clinics and sports medicine centers drive recurring revenue through rental and lease arrangements. Combination therapy systems integrating pulsed ultrasound with electrical stimulation represent the fastest-growing technology segment, as dual-modality reimbursement codes improve clinical economics. High-intensity focused ultrasound remains concentrated in aesthetic treatments where margin pools exceed standard therapeutic applications.
The FDA's 510(k) premarket notification framework governs therapeutic ultrasound device commercialization in the United States, while the EU Medical Device Regulation (MDR) imposes strengthened clinical evidence requirements for CE marking across European markets. Japan's Ministry of Health, Labour and Welfare (MHLW) and Pharmaceuticals and Medical Devices Agency (PMDA) enforce distinct quality management system certifications that create non-trivial entry barriers for Western manufacturers. Stakeholders must monitor evolving reimbursement classifications for combination therapy modalities, as payor acceptance determines whether clinical adoption translates into sustainable revenue capture across outpatient and institutional channels.
Market Dynamics
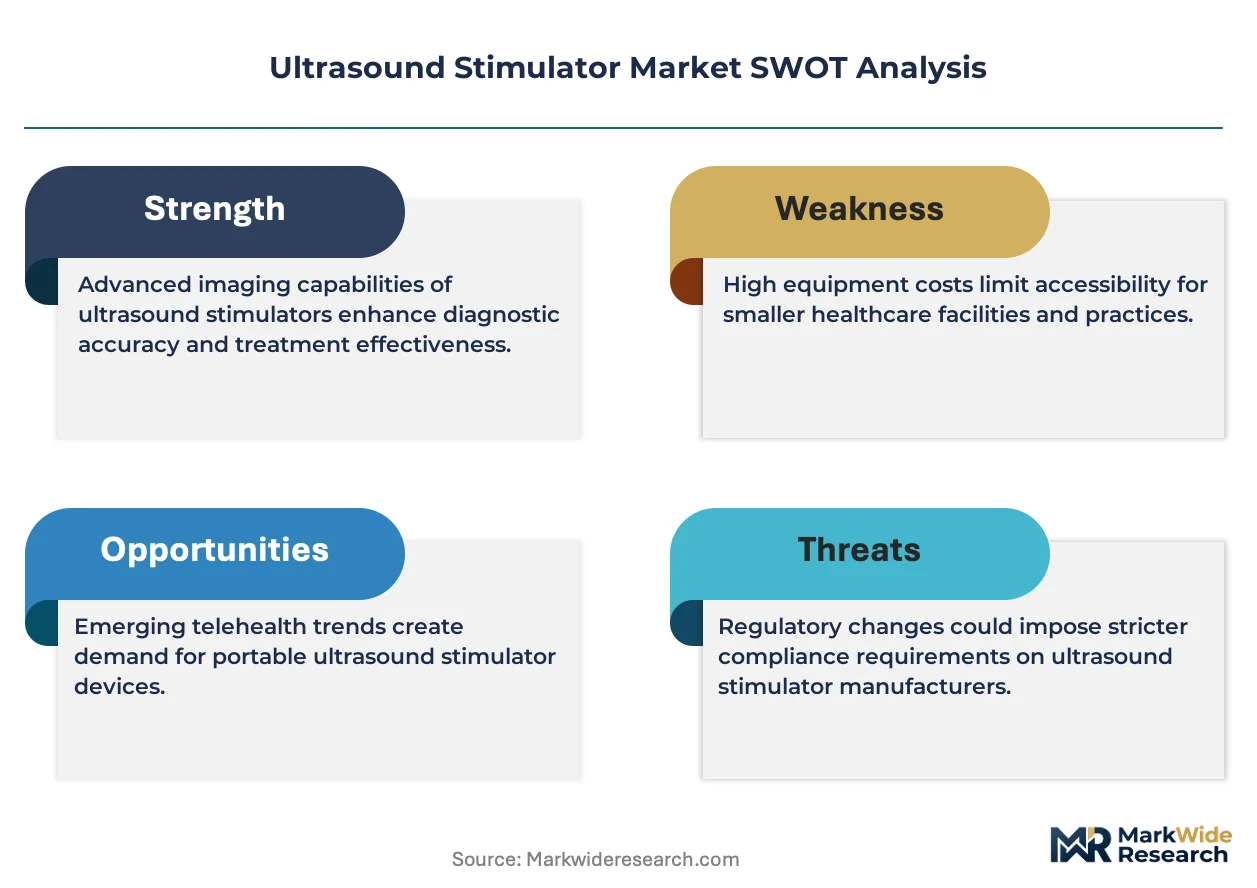
The FDA's 510(k) clearance pathway is compressing product development timelines while simultaneously fragmenting competitive positioning between established rehabilitation equipment manufacturers and emerging portable device specialists. This regulatory acceleration is reshaping how therapeutic ultrasound platforms reach clinical and home-care settings.
Growth Catalysts
- Combination therapy reimbursement codes:Dual-modality billing classifications in outpatient rehabilitation settings are pulling capital investment toward integrated ultrasound-electrical stimulation systems. Physical therapy clinics now prioritize platforms that unlock multiple revenue streams per patient visit.
- Aging demographics in Japan and Germany:Expanding geriatric populations in these markets are amplifying demand for non-invasive pain management modalities. Hospital procurement channels in both countries are expanding therapeutic ultrasound fleet sizes to address chronic musculoskeletal conditions.
- Piezoelectric crystal efficiency gains:Advances in transducer material science are reducing device footprint while maintaining therapeutic output specifications. This technical progression is enabling home-based care models previously restricted to clinical environments.
Market Restraints
- EU MDR clinical evidence requirements:Strengthened documentation mandates for CE marking are extending time-to-market for new therapeutic ultrasound platforms. Smaller manufacturers face disproportionate compliance cost burdens relative to revenue base.
- Substitution by low-frequency TENS devices:Transcutaneous electrical nerve stimulators at lower price points are capturing budget-constrained segments of the pain management market. Patient self-administration preferences favor these simpler alternatives.
- Supply concentration in rare earth elements:Piezoelectric crystal production depends on concentrated sourcing of specific mineral inputs. Geopolitical friction affecting these supply corridors creates input cost volatility.
Strategic Opportunities
- Home-based rental channel expansion:Post-acute care providers in the United States are piloting subscription-based device access models. This channel innovation reduces patient acquisition costs while generating recurring revenue streams.
- High-intensity focused ultrasound aesthetic pivot:Margin pools in cosmetic applications exceed standard therapeutic rehabilitation. Manufacturers with thermal control expertise can redirect R&D toward dermatology and body contouring segments.
- Japan PMDA quality management alignment:Western manufacturers achieving PMDA certification gain preferential access to hospital procurement networks. This regulatory tailwind rewards upfront investment in documentation and manufacturing process rigor.
Industry Challenges
- Biomedical engineer talent scarcity:Specialized expertise integrating acoustic physics with clinical efficacy validation is concentrated among a limited pool of professionals. Recruitment friction delays product iteration cycles.
- Legacy electronic health record integration:Therapeutic ultrasound platforms must interface with institutional documentation systems that lack standardized APIs. Custom integration work inflates deployment costs and extends sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultrasound Stimulator Market |
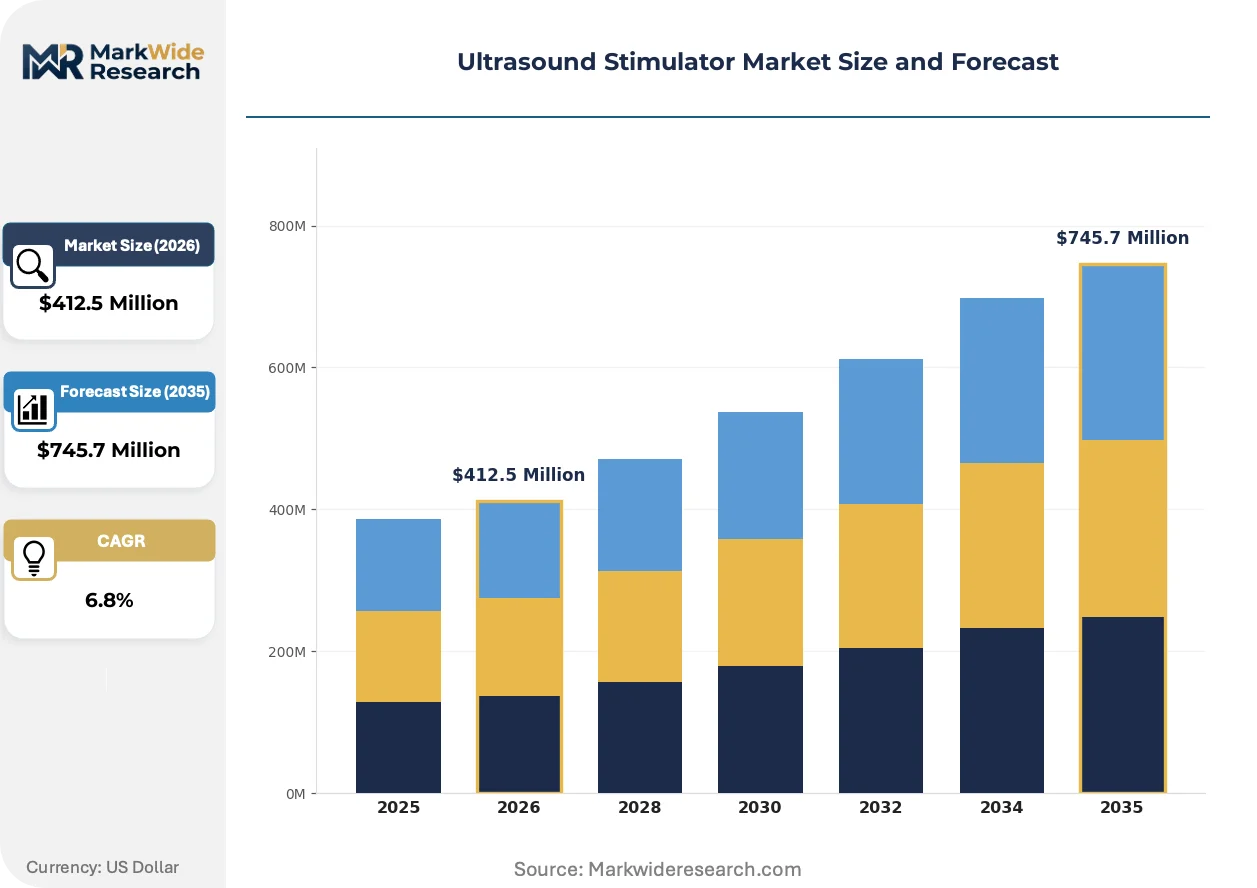
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Stimulators, Therapeutic Devices, High-Intensity Focused Ultrasound, Ultrasound Imaging Systems Application: Physical Therapy, Pain Management, Rehabilitation, Aesthetic Treatments End User: Healthcare Facilities, Physiotherapy Clinics, Sports Medicine Centers, Research Institutions Technology: Pulsed Ultrasound, Continuous Ultrasound, Combination Therapy, Digital Ultrasound |
| Companies Covered | Zimmer MedizinSysteme GmbH, Gbo Medizintechnik AG, Astar, GymnaUniphy N.V., Enraf-Nonius B.V., Mettler Electronics Corp., Fujifilm Sonosite, Esaote, Mindray Medical International Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultrasound Stimulator Market Trends and Innovations
Portable system miniaturization is collapsing the boundary between clinical-grade therapeutic output and consumer-accessible form factors. This technical trajectory is enabling new care delivery models while pressuring traditional equipment rental economics.
MEMS-based transducer arrays are displacing conventional piezoelectric crystal assemblies in next-generation portable stimulators. Sports medicine centers and mobile physiotherapy services are adopting these platforms at accelerating velocity. The technology is displacing stationary cart-based systems in outpatient settings where space constraints and patient throughput priorities dominate capital allocation decisions.
Japan's PMDA enforcement of distinct quality management system certifications is tightening market entry requirements for therapeutic ultrasound devices. Manufacturers must demonstrate manufacturing process controls that exceed ISO 13485 baselines. Western suppliers targeting Japanese hospital procurement channels are responding by establishing local technical service partnerships and dedicated regulatory affairs staffing.
After-sales service unbundling is fragmenting traditional equipment procurement bundles in German rehabilitation markets. Hospital buyers now separately negotiate maintenance contracts, training packages, and software update subscriptions. This behavioral shift is most visible among university-affiliated medical centers where value-analysis committees scrutinize total cost of ownership across extended depreciation horizons.
Ultrasound Stimulator Market Segmentation
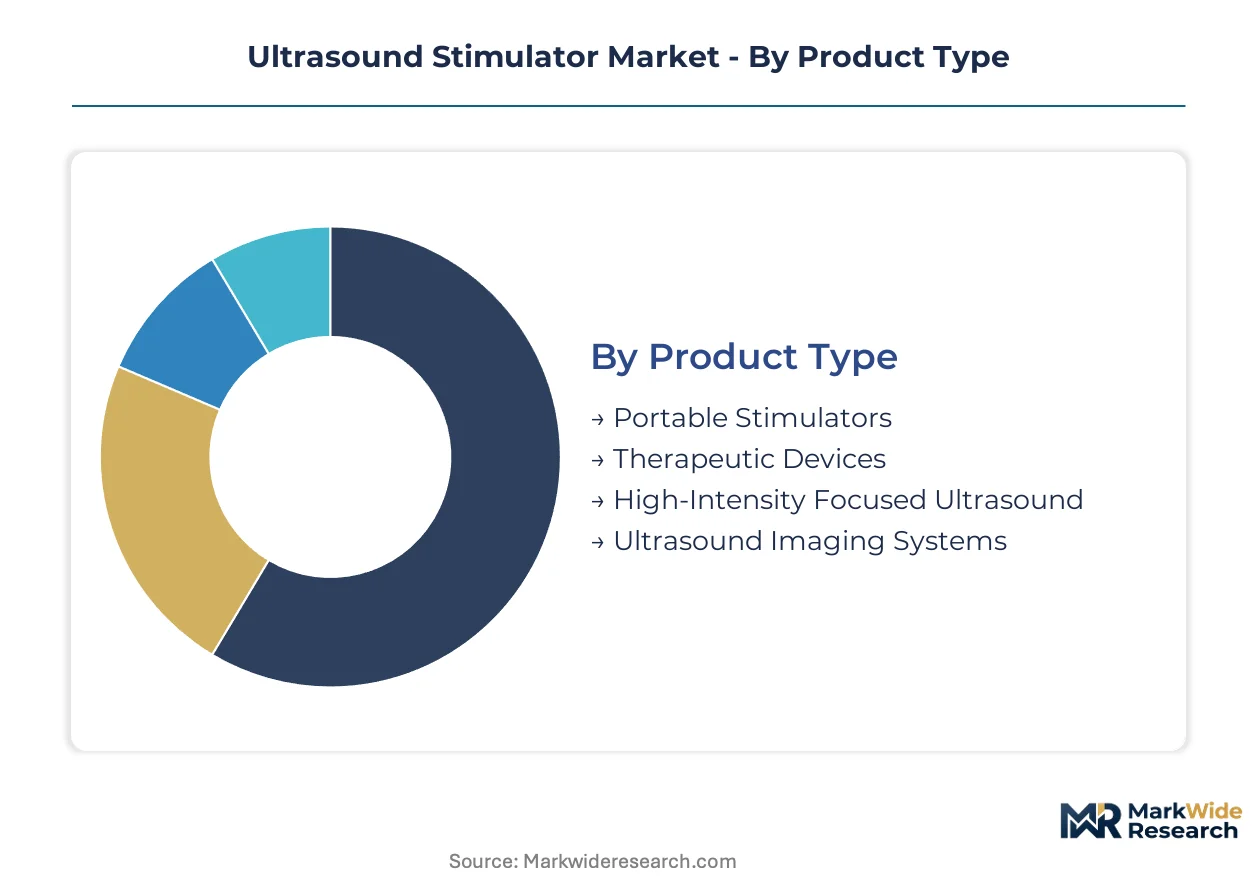
Ultrasound stimulator segmentation reveals distinct regulatory pathways governing each product category. FDA 510(k) clearances cluster differently across portable versus stationary platforms, while reimbursement codes fragment demand by clinical setting.
Product Type:
FDA 510(k) submissions for therapeutic ultrasound devices vary substantially in documentation burden by product classification, with portable systems facing streamlined review compared to high-intensity platforms requiring clinical efficacy dossiers.
- Portable Stimulators:Battery-operated units employing MEMS-based transducer arrays deliver 1-3 MHz output in handheld form factors. Demand concentrates in United States home-based care models where post-acute providers pilot subscription rental channels to reduce patient acquisition costs.
- Therapeutic Devices:Clinical-grade cart-based systems maintain continuous wave output for deep tissue heating applications. German hospital procurement channels expand fleet sizes for chronic musculoskeletal conditions among aging patient populations.
- High-Intensity Focused Ultrasound:Concentrated acoustic energy platforms for aesthetic applications.
- Ultrasound Imaging Systems:Combined diagnostic-therapeutic platforms with integrated transducer modules.
Portable Stimulators handles the majority of throughput; High-Intensity Focused Ultrasound is expanding most quickly on share.
Application:
Cost tier differentiation separates institutional reimbursement from out-of-pocket aesthetic spending, with clinical applications constrained by payor acceptance while cosmetic procedures command premium pricing.
- Physical Therapy:Outpatient rehabilitation protocols leverage ultrasound for tissue repair acceleration and range-of-motion restoration. United States physical therapy clinics prioritize combination therapy platforms that unlock multiple revenue streams per patient visit under dual-modality billing codes.
- Pain Management:Non-invasive neuromodulation through thermal and cavitation effects targets chronic conditions. Japanese hospital procurement networks favor devices with PMDA quality management certification for integration into geriatric care pathways.
- Rehabilitation:Post-surgical and injury recovery protocols in institutional settings.
- Aesthetic Treatments:Body contouring and dermatology applications with superior margin profiles.
Physical Therapy commands the largest installed base; Aesthetic Treatments climbs the fastest on margin capture.
End User:
Customer type determines purchasing authority structure, with hospital value-analysis committees imposing extended evaluation cycles compared to independent clinic decision-making.
- Healthcare Facilities:Acute care hospitals and integrated delivery networks with centralized capital allocation. German university-affiliated medical centers unbundle after-sales service contracts from equipment procurement to scrutinize total cost of ownership.
- Physiotherapy Clinics:Independent outpatient practices with direct patient relationship economics. These United States clinics drive recurring revenue through rental and lease arrangements for portable systems.
- Sports Medicine Centers:Specialized facilities serving athletic populations with throughput priorities.
- Research Institutions:Academic medical centers conducting clinical efficacy validation studies.
Healthcare Facilities absorb the bulk of capital expenditure; Physiotherapy Clinics is gaining share fastest on rental model adoption.
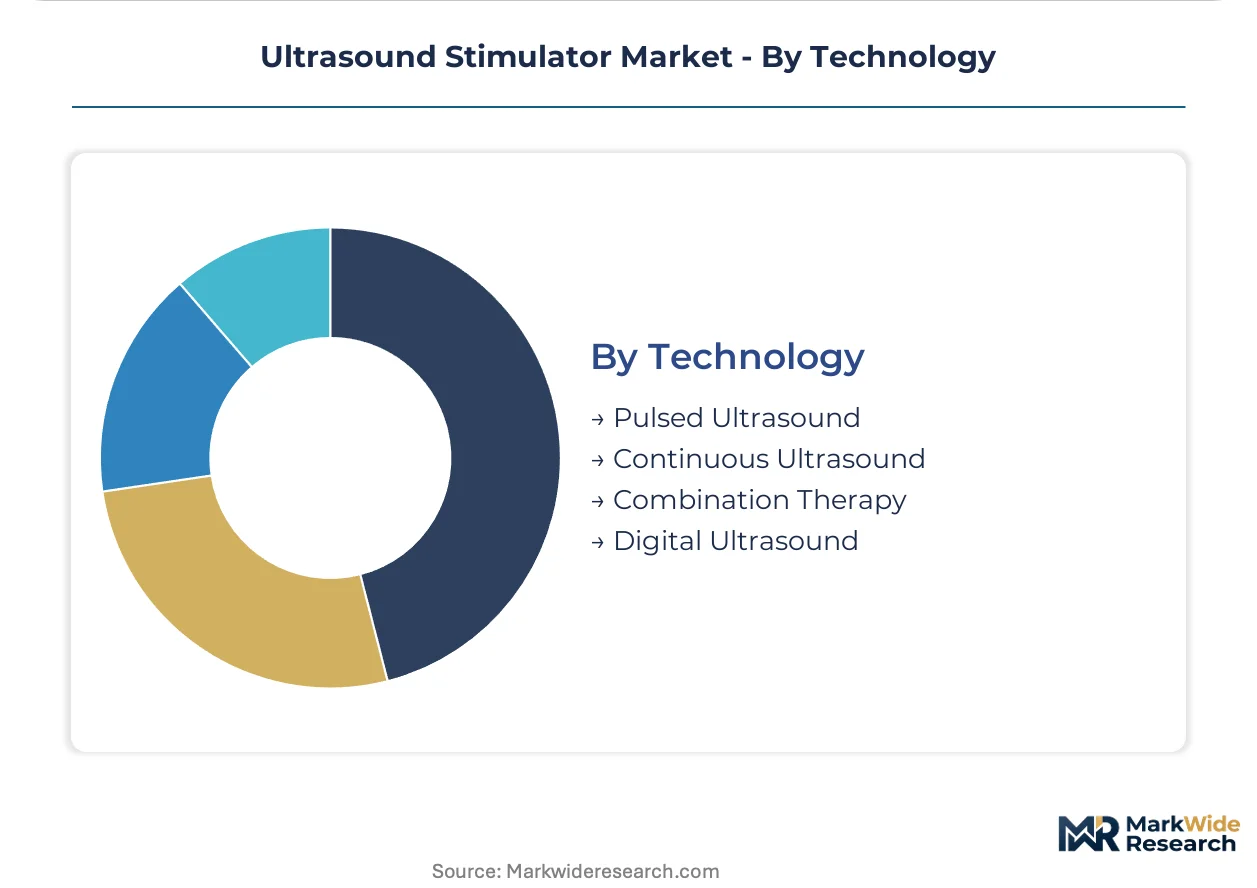
Technology:
Supply concentration in piezoelectric crystal sourcing creates input cost volatility that differentially impacts transducer-dependent technology segments.
- Combination Therapy:Integrated ultrasound-electrical stimulation platforms with synchronized output modulation. Dual-modality reimbursement classifications in United States outpatient settings pull capital investment toward these systems.
- Pulsed Ultrasound:Non-thermal mechanical effects for acute injury protocols with reduced tissue heating risk. Japanese MHLW reimbursement frameworks favor these platforms for early-intervention musculoskeletal programs.
- Continuous Ultrasound:Sustained thermal delivery for chronic condition management.
- Digital Ultrasound:Software-defined waveform control with embedded treatment protocols.
Combination Therapy dominates new platform investment; Digital Ultrasound shows the steepest expansion trajectory on miniaturization enablement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in therapeutic ultrasound equipment tilt toward net importing positions in aging economies while manufacturing concentrates in Germany, Japan, and the United States. Export competitiveness hinges on regulatory certification breadth and piezoelectric component sourcing security.
United States
Post-acute care providers and independent physiotherapy clinics drive portable stimulator uptake through subscription rental models. The FDA's 510(k) premarket notification framework compresses clearance timelines for handheld devices compared to stationary platforms. Minneapolis-St. Paul anchors device distribution networks serving the Upper Midwest rehabilitation corridor.
Germany
Hospital procurement channels expand therapeutic ultrasound fleet sizes to address chronic musculoskeletal conditions among aging patient populations. The EU Medical Device Regulation imposes strengthened clinical evidence requirements for CE marking that extend time-to-market for new platforms. Berlin-Brandenburg hosts value-analysis committees at university-affiliated medical centers unbundling after-sales service contracts from equipment procurement.
Japan
Geriatric care pathways integrate therapeutic ultrasound for non-invasive pain management in institutional settings. The Ministry of Health, Labour and Welfare and Pharmaceuticals and Medical Devices Agency enforce quality management system certifications exceeding ISO 13485 baselines. Osaka-Kansai manufacturers maintain captive piezoelectric crystal production for transducer assembly.
China
Domestic hospital networks accelerate procurement of combination therapy systems as dual-modality reimbursement codes mature in pilot provinces. The National Medical Products Administration governs therapeutic device registration with clinical trial requirements tightening for imported platforms. Shenzhen-Pearl River Delta assembles portable stimulators for Southeast Asian export markets.
South Korea
Sports medicine centers and mobile physiotherapy services adopt MEMS-based transducer platforms for patient throughput optimization. The Ministry of Food and Drug Safety aligns quality management certifications with PMDA standards to facilitate Japan market access. Seoul Capital Area clusters medical device engineering talent for acoustic physics integration.
Ultrasound Stimulator Market Competitive Landscape
Concentration sits with diversified rehabilitation equipment manufacturers possessing hospital procurement relationships and dedicated regulatory affairs staffing. Mid-tier specialists compete on portable form factors and home-care channel innovation. Two strategic archetypes dominate: German-engineered stationary systems for institutional settings and miniaturized portable platforms for outpatient and rental economics. Competitive moves center on PMDA certification achievement for Japan market entry and MEMS transducer technology licensing for footprint reduction.
Within the diversified manufacturer tier, Zimmer MedizinSysteme GmbH and Fujifilm Sonosite exemplify contrasting geographic and structural positioning. Zimmer MedizinSysteme GmbH occupies a position reflecting German engineering heritage in hospital procurement channels. Fujifilm Sonosite represents Japanese-origin miniaturization expertise extending point-of-care accessibility. Esaote sits within the specialized imaging-therapy integration archetype, anchoring musculoskeletal application development.
| Leading Market Players |
|---|
| Zimmer MedizinSysteme GmbH |
| Gbo Medizintechnik AG |
| Astar |
| GymnaUniphy N.V. |
| Enraf-Nonius B.V. |
| Mettler Electronics Corp. |
| Fujifilm Sonosite |
| Esaote |
| Mindray Medical International Limited |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation contracts with Japanese piezoelectric crystal producers lock in transducer supply visibility while insulating device manufacturers from rare earth price volatility. These arrangements tether procurement economics to Osaka-Kansi manufacturing clusters where captive crystal production anchors tiered pricing structures across portable and stationary platform categories.
Pricing Analysis
Hospital procurement committees anchor three-tier pricing structure across premium, standard, and economy levels in therapeutic ultrasound equipment. Price differentiation rests on FDA 510(k) clearance tier, after-sales service bundling, and MEMS transducer integration depth. Cost compression in economy-grade portable stimulators is intensifying because low-frequency TENS devices capture budget-constrained pain management segments. Independent physiotherapy clinics exhibit highest price sensitivity; German university-affiliated medical centers demonstrate lowest sensitivity due to extended depreciation horizons.
Supply Chain Analysis
Japan and Germany anchor piezoelectric crystal fabrication and precision transducer assembly for therapeutic ultrasound platforms. Raw material flows draw from concentrated rare earth element deposits and specialized ceramic substrate production. Single-source vulnerability in piezoelectric component sourcing creates exposure to geopolitical friction affecting mineral supply corridors. Distribution runs through hospital procurement networks in aging economies and subscription rental channels in United States post-acute care markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MEMS-based transducer miniaturization and dual-modality reimbursement code expansion are reshaping competitive economics across clinical and home-care settings. This technological-regulatory inflection compresses product development timelines while fragmenting positioning between institutional equipment manufacturers and portable device specialists.
For Market Incumbents: Secure PMDA quality management certification ahead of competitors to lock in Japanese hospital procurement channel access. Deepen backward integration into piezoelectric crystal production to reduce rare earth supply volatility exposure. Prioritize software companion development for legacy EHR integration to defend against emerging portable specialists. For New Entrants and Emerging Players: Post-acute rental service gaps in United States home-based care models offer immediate white-space penetration. Target independent physiotherapy clinics with subscription-based device access models that reduce patient acquisition costs. Pursue MEMS transducer technology licensing agreements to collapse form factors and unlock outpatient channel economics. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier specialists possessing MEMS transducer IP and established regulatory dossiers across FDA and CE marking pathways. Long-term viability favors platforms with demonstrated reimbursement strategy execution in combination therapy modalities. Watch for dual-modality billing code expansion in additional United States states as inflection signal for clinical adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Certification Achievement | Unlocks preferential access to Japanese hospital procurement networks exceeding ISO 13485 baselines. |
| MEMS Transducer Technology Licensing | Enables footprint reduction for portable platforms targeting outpatient throughput optimization. |
| Combination Therapy Platform Development | Captures dual-modality reimbursement codes that improve clinical economics per patient visit. |
| Home-Based Rental Channel Expansion | Generates recurring revenue streams while reducing patient acquisition costs for post-acute providers. |
| Software Companion Development | Addresses legacy EHR integration friction that inflates deployment costs and extends sales cycles. |
Research Methodology
A standing panel of biomedical engineers, hospital purchasing committee members, GPO contracts managers, and post-acute care operations directors provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) clearance databases, CMS Medicare reimbursement classifications, and Japanese MHLW device registration records. Bottom-up unit economics triangulated against top-down market sizing across portable stimulator, therapeutic device, and high-intensity focused ultrasound categories.
Consistency checks validated volume and value outputs against external benchmarks including hospital procurement database trends and trade flow analysis. The analytical framework modeled product type, application, end user, and technology segments across the projection horizon. CAGRs were derived from segment-level growth trajectory analysis incorporating piezoelectric crystal efficiency gains, reimbursement code expansion patterns, and aging demographic demand curves.
Forecasts assume regulatory continuity in FDA 510(k) pathways, EU MDR enforcement, and Japanese PMDA quality management regimes; material policy shifts would require re-modeling. Specific risk factors include substitution acceleration by low-frequency TENS devices and rare earth supply corridor disruptions. Recalibration cycles align with material shifts in dual-modality reimbursement adoption and MEMS transducer manufacturing yield improvements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Near Vision Devices Market
Medical Devices
High Flow Oxygen Therapy Devices Market
Medical Devices
Global Medical Suction Devices Market
Medical Devices
Canada Varicose Vein Treatment Devices Market
Medical Devices
Pressure Ulcer Detection Devices Market
Medical Devices
MRI Guided Drug Delivery Market
Medical Devices
Polyp Trap Devices Market
Medical Devices
US Medical Device Outsourcing Market
Medical Devices
Asia-Pacific Smart Medical Devices Market
Medical Devices
Transilluminators Market
Medical Devices
Specimen Retrieval Nets Market
Medical Devices
Printed Electronics in Healthcare Market
Medical Devices
Australia Spinal Surgery Devices Market
Medical Devices
Infusion Management Market
Medical Devices
Small Bone and Joint Devices Market
Medical Devices
Infant Radiant Warmer Market