
 Self-Injections Market | 2026-2036
Self-Injections Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Injections Market Analysis
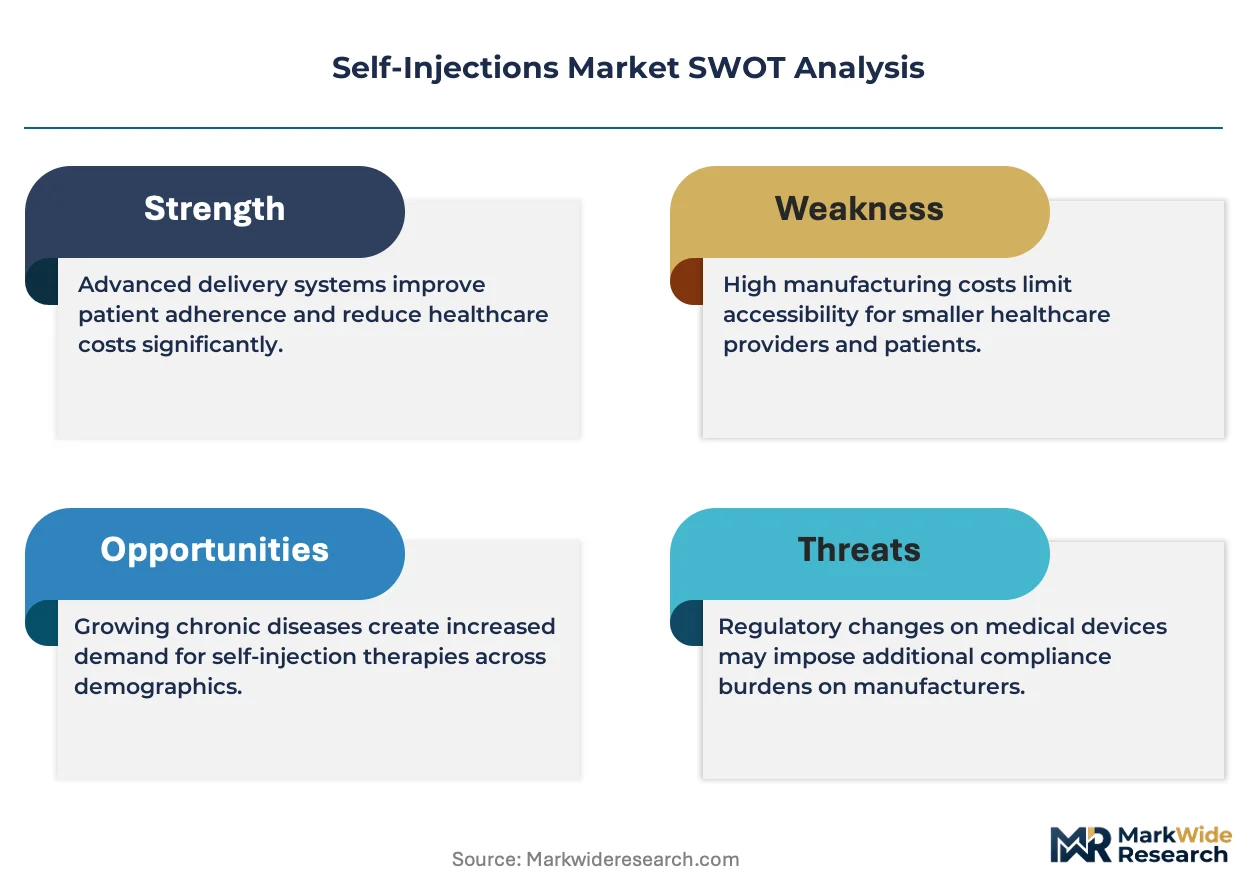
Connected device ecosystems is fragmenting legacy hardware-centric business models across the self-injections landscape. Becton Dickinson and Company leverages its integrated manufacturing scale to dominate disposable pen-needle supply chains. Ypsomed Holding AG anchors European distribution through its proprietary autoinjector platforms. AbbVie Inc. differentiates via therapeutic-area-specific delivery partnerships that lock in biologic compatibility requirements.
Self-injections encompass drug delivery systems enabling patients or caregivers to administer parenteral therapies outside clinical settings, typically incorporating spring-driven or electromechanical mechanisms with dose-precision tolerances of plus or minus five percent. Pens command the largest product-type position due to insulin dependence and repeat-dosing protocols, while wearable pump devices represent the fastest-growing delivery format as patch-based systems displace conventional syringes for hormone therapy. Subcutaneous delivery holds the broadest application footprint across diabetes and autoimmune indications, though intramuscular formats retain margin concentration in biologic administration where viscosity handling demands specialized needle geometries.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape device commercialization timelines and clinical evidence burdens for manufacturers seeking dual-territory approval. ISO 11608 needle-based injection system standards govern dose accuracy and sterility assurance, creating compliance moats that favor incumbents with established quality management systems. Stakeholders must monitor evolving pharmacovigilance obligations for combination products as regulators increasingly scrutinize device-drug interaction failures rather than isolating component-level performance.
Market Dynamics
The self-injections market is being fundamentally restructured by the convergence of biologic drug pipelines with electromechanical delivery platforms, as chronic disease management migrates from hospital infusion centers to patient-controlled home environments.
Growth Catalysts
- EU MDR Conformity Pathways:The Medical Device Regulation's enhanced clinical evidence requirements for combination products is accelerating investment in integrated device-drug development programs across European pharmaceutical portfolios.
- Diabetes Home Therapy Protocols:Endocrinology practices in the United States are standardizing continuous glucose monitor-linked insulin delivery systems, creating installed base expansion for interoperable injection platforms.
- Subcutaneous Biologic Formulations:Monoclonal antibody developers are engineering lower-viscosity concentrates specifically for patient-administered delivery, bypassing infusion center capacity constraints.
Market Restraints
- Spring Steel and Precision Molding Concentration:Disposable autoinjector mechanical subassemblies depend on Swiss and German specialty component suppliers, creating single-source vulnerability for pen-needle and drive mechanism production.
- FDA 510(k) Clinical Evidence Burden:Predicate device comparisons for novel delivery formats require human factors validation studies that extend commercialization timelines by eighteen to thirty-six months.
- Oral Biologic Substitutes:Intestinal permeation technologies for peptide therapeutics threaten subcutaneous injection volumes in diabetes and obesity management categories.
Strategic Opportunities
- Brazil ANVISA Harmonization:The national health surveillance agency's accelerated review pathway for combination products with prior FDA or EMA approval is opening Latin America's largest chronic disease market to pre-cleared device platforms.
- Wearable Patch Pump Convergence:Integration of microneedle arrays with flexible electronics is enabling hormone therapy delivery formats that displace conventional syringe-based protocols in fertility and endocrine applications.
- Japan PMDA Real-World Evidence Framework:The Pharmaceuticals and Medical Devices Agency's post-market surveillance data acceptance for device modifications reduces recertification costs for iterative platform improvements.
Industry Challenges
- Human Factors Engineering Talent Scarcity:Combination product development requires specialized usability validation expertise that outpaces university program output in the United States and Germany.
- ISO 11608-1 Dose Accuracy Certification:Needle-based injection system standard compliance testing for electromechanical devices requires capital-intensive metrology infrastructure that fragments mid-tier manufacturer participation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Injections Market |
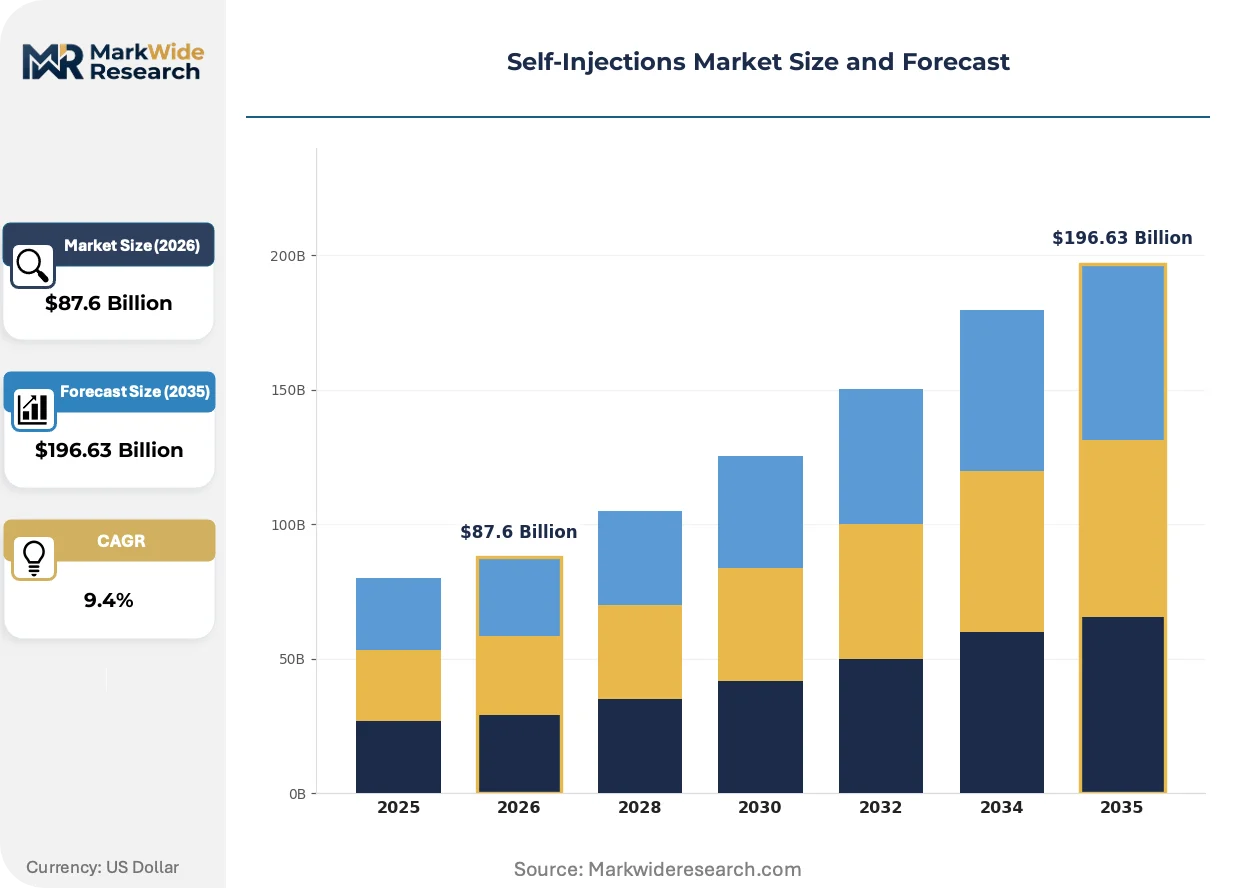
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $196.63 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pens, Syringes, Devices, Kits End User: Patients, Healthcare Providers, Homecare, Clinics Application: Diabetes, Autoimmune Disorders, Hormone Therapy, Pain Management Delivery Method: Subcutaneous, Intramuscular, Intravenous, Intra-articular |
| Companies Covered | Becton Dickinson and Company, Ypsomed Holding AG, AbbVie Inc., SHL Medical AG, Gerresheimer AG, West Pharmaceutical Services Inc., Owen Mumford Limited, Insulet Corporation, Antares Pharma Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Injections Market Emerging Trajectories
Connected device architectures are dissolving the boundary between drug delivery hardware and digital therapeutics, forcing manufacturers to build software competency alongside mechanical engineering capabilities.
Electromechanical autoinjector platforms are hybridizing spring-driven reliability with Bluetooth-enabled dose tracking and adherence monitoring. Rheumatology and gastroenterology patient cohorts in Germany and the United States are adopting these systems at replacement-cycle rates exceeding traditional disposable formats. This convergence is compressing the addressable market for non-connected legacy devices while expanding recurring revenue streams through software subscription attach rates.
EU MDR Article 117 technical documentation requirements for drug-device combination products are mandating device-specific clinical evidence rather than drug-centric bridging studies. Manufacturers seeking CE marking must now generate standalone usability and performance data, extending development budgets and favoring incumbents with established notified body relationships. The regulation is most acutely affecting biologic license holders that historically outsourced delivery device development to third-party specialists.
Home infusion training models are displacing clinic-based injection education as the standard of care for biologic initiation. Specialty pharmacy channels in the United States are absorbing nurse educator functions previously performed at hospital infusion centers, altering device manufacturer support service obligations and field team deployment. This channel migration is most visible in inflammatory disease categories where patient self-efficacy protocols now dominate therapy onboarding.
Self-Injections Market Segmentation
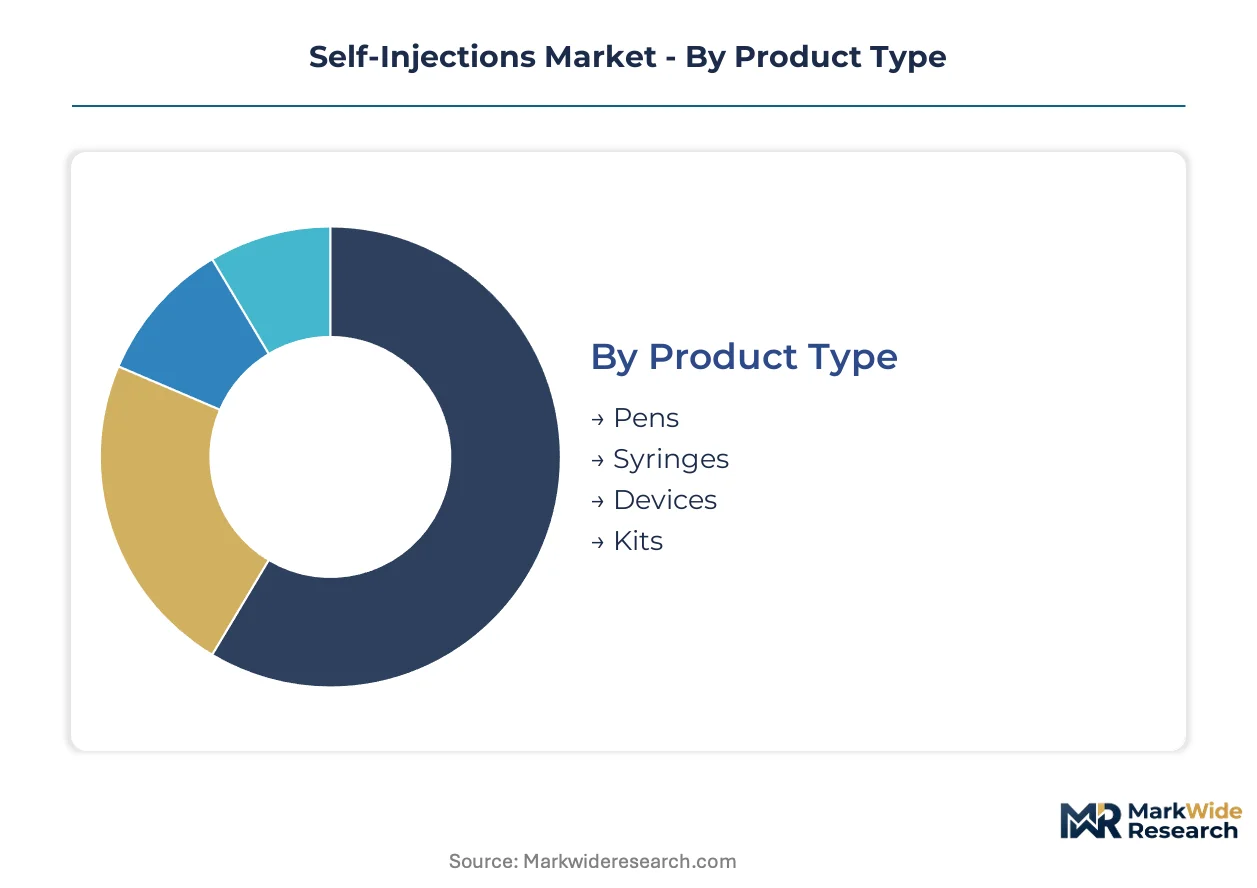
Self-injection platforms fragment across four interdependent dimensions that determine device design specifications, regulatory pathways, and commercial support requirements. Each segmentation layer imposes distinct constraints on dose precision, user interface complexity, and aftermarket service intensity.
Product Type:
After-sales-service intensity varies sharply across product categories, with electromechanical devices demanding firmware updates and calibration protocols that disposable formats avoid entirely.
- Pens:Spring-driven or dial-based mechanical systems engineered for insulin and GLP-1 receptor agonist delivery with fixed or variable dose settings. Demand concentrates in the United States and Germany where diabetes prevalence and reimbursement density align, though spring steel supply constraints from Swiss component manufacturers create procurement vulnerability.
- Devices:Electromechanical autoinjectors and wearable pump systems incorporating Bluetooth connectivity, dose logging, and adherence monitoring capabilities. United States rheumatology practices are standardizing these platforms for biologic initiation protocols, compressing replacement cycles for legacy disposable formats.
- Syringes:Conventional barrel-and-plunger designs for single-use parenteral administration, predominating in cost-sensitive markets and emergency settings where device complexity introduces training burden.
- Kits:Integrated packaging combining drug vials, needles, and disposal containers for specialty pharmacy distribution, common in fertility and hormone therapy categories where protocol adherence requires component bundling.
By volume, pens lead. By growth pace, devices are ahead.
End User:
Cost tier stratification separates institutional procurement from direct-to-patient channels, with reimbursement eligibility determining device sophistication thresholds.
- Patients:Individuals administering therapy in residential settings without clinical supervision, driving demand for human-factors-optimized interfaces and error-prevention mechanisms. United States specialty pharmacy networks now absorb nurse educator functions, shifting training burden to device manufacturers.
- Healthcare Providers:Hospital and infusion center staff performing supervised injections during therapy initiation or acute episodes, requiring rapid-dose adjustment capabilities and multi-patient sterilization protocols.
- Homecare:Skilled nursing services delivering parenteral therapy in patient residences, typically for populations with manual dexterity limitations or complex polypharmacy regimens.
- Clinics:Outpatient endocrinology and rheumatology practices managing chronic disease cohorts, increasingly delegating injection training to device manufacturer field teams as infusion center capacity contracts.
Patient-directed administration commands the largest installed base. Healthcare provider adoption is climbing the fastest as biologic pipelines expand.
Application:
Volume concentration in diabetes creates procurement scale effects that subsidize development costs for smaller therapeutic categories.
- Diabetes:Insulin and GLP-1 agonist delivery dominating pen-based consumption, with continuous glucose monitor interoperability now a baseline requirement for new platform approvals.
- Autoimmune Disorders:Rheumatoid arthritis, psoriasis, and inflammatory bowel disease biologics driving electromechanical autoinjector adoption as subcutaneous formulations displace infusion center dependence.
- Hormone Therapy:Fertility protocols and endocrine replacement requiring precise micro-dose titration, where wearable patch pumps are displacing conventional syringe-based administration.
- Pain Management:Opioid antagonist and local anesthetic delivery in palliative and post-surgical settings, constrained by controlled-substance diversion concerns that limit device automation.
Diabetes generates the highest absolute unit volumes. Autoimmune applications are gaining share fastest as biologic pipelines mature.
Delivery Method:
Margin structure inverts across delivery depths, with intravenous formats commanding premium pricing despite smaller addressable populations.
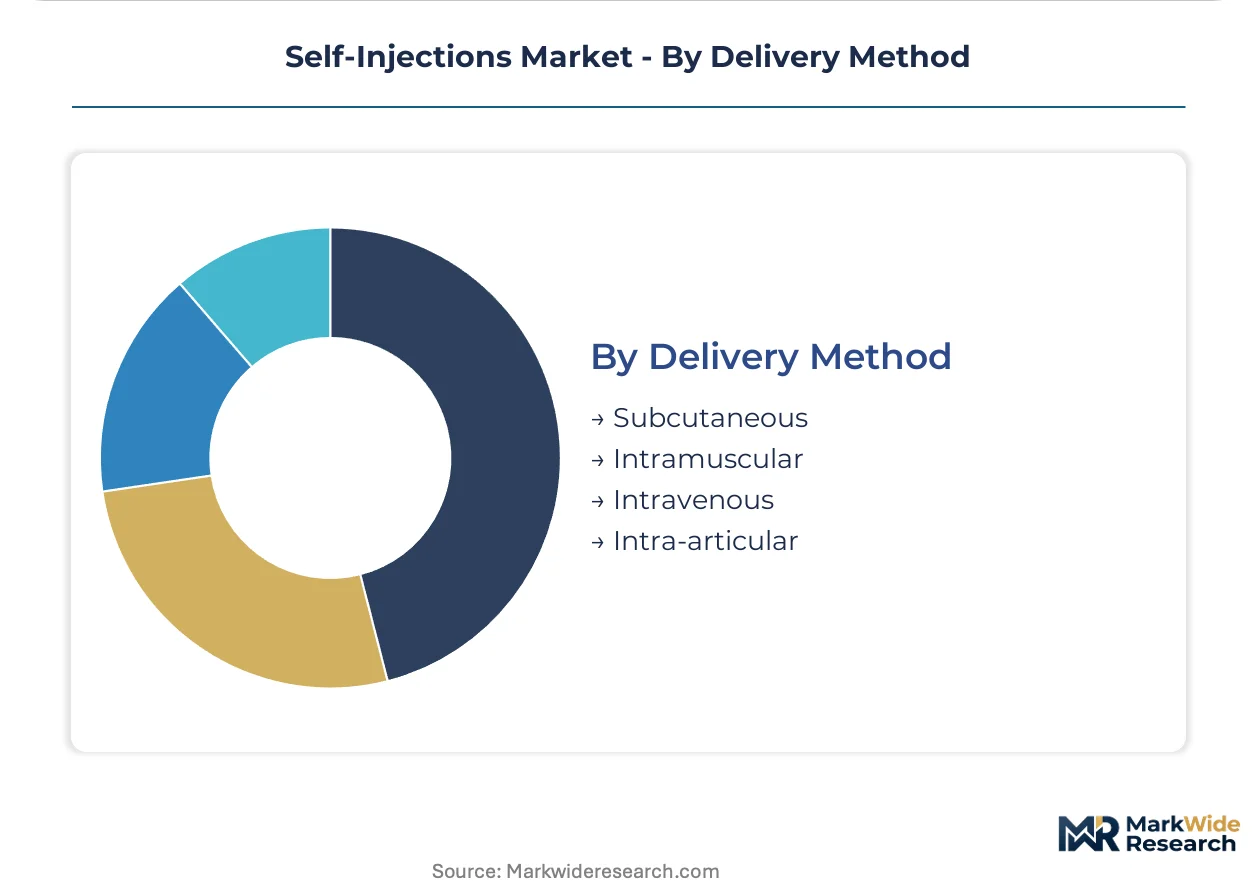
- Subcutaneous:Tissue injection into the fat layer beneath the dermis, accommodating the broadest drug viscosity range and enabling patient self-administration for diabetes and autoimmune indications.
- Intramuscular:Deeper tissue deposition requiring longer needle geometries and aspiration protocols, retaining importance for biologic administration where absorption kinetics demand vascular proximity.
- Intravenous:Direct vascular access for high-volume or vesicant drug delivery, predominantly hospital-administered though portable infusion pumps are enabling selected home protocols.
- Intra-articular:Joint space injection for localized anti-inflammatory delivery in osteoarthritis and rheumatoid arthritis, requiring specialized needle curvature and imaging guidance compatibility.
Subcutaneous delivery leads by procedure volume. Intravenous formats show the steepest expansion trajectory as oncology and immunology pipelines advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in self-injection devices tilt heavily toward net-import positions across major chronic disease markets, with specialized component manufacturing concentrated in Swiss and German supply bases while finished device assembly gravitates toward patient-proximate distribution hubs.
United States
Diabetes prevalence and specialty pharmacy channel density drive the largest absolute demand for pen-based and connected autoinjector platforms. FDA 510(k) clearance pathways shape commercialization timelines, with human factors validation requirements extending market entry by eighteen to thirty-six months for novel formats. The Greater Boston corridor hosts biologic-device combination product development clusters where pharmaceutical firms co-locate with delivery technology specialists.
Germany
Rheumatology and gastroenterology practices standardize electromechanical autoinjectors for biologic initiation, compressing replacement cycles for legacy disposable formats. EU MDR conformity assessments mandate standalone device-specific clinical evidence rather than drug-centric bridging studies, favoring incumbents with established notified body relationships. The Baden-Württemberg region concentrates precision molding and spring steel component fabrication for pen-needle mechanical subassemblies.
Japan
Aging demographics and endocrinology patient volumes sustain demand for human-factors-optimized injection platforms with error-prevention mechanisms. PMDA real-world evidence frameworks reduce recertification costs for iterative device modifications, accelerating platform improvement cycles. The Kanto region around Tokyo anchors pharmaceutical-device partnership development for hormone therapy and autoimmune indications.
Switzerland
Specialty component supply chains for autoinjector mechanical subassemblies create export dominance in spring steel and precision-molded drive mechanisms. Swissmedic regulatory alignment with EU MDR streamlines dual-territory approval pathways for combination products. The Jura Arc industrial cluster spans northwestern Switzerland and neighboring French territories, concentrating micromechanical fabrication for disposable injection devices.
Brazil
Chronic disease prevalence in Latin America's largest market attracts pre-cleared device platforms seeking expanded installed bases. ANVISA accelerated review pathways for combination products with prior FDA or EMA approval reduce commercialization friction for foreign manufacturers. São Paulo state anchors specialty pharmacy distribution networks that absorb nurse educator functions for home therapy onboarding.
Self-Injections Market Vendor Landscape
On the supply side, the industry is consolidating around integrated device-drug development programs as EU MDR technical documentation requirements raise barriers for third-party component sourcing. Three archetypes dominate: pharmaceutical license holders building captive delivery capabilities, specialized autoinjector platform developers, and disposable component manufacturers with precision molding scale. Competitive moves center on backward integration into specialty component supply and strategic partnerships locking in biologic compatibility requirements.
Among Swiss and German-based fabrication specialists, Ypsomed Holding AG and SHL Medical AG exemplify the platform-developer archetype with proprietary autoinjector ecosystems. Becton Dickinson and Company anchors the scale-driven disposable supply tier with integrated manufacturing across pen-needle value chains. These three occupy positions that reflect the industry's structural shift toward combination product integration and regulatory compliance moats.
| Leading Market Players |
|---|
| Becton Dickinson and Company |
| Ypsomed Holding AG |
| AbbVie Inc. |
| SHL Medical AG |
| Gerresheimer AG |
| West Pharmaceutical Services Inc. |
| Owen Mumford Limited |
| Insulet Corporation |
| Antares Pharma Inc. |
| Others |
Supply Flow & Price Mechanics
The Jura Arc industrial cluster spanning northwestern Switzerland and neighboring French territories anchors global capacity for micromechanical fabrication and precision-molded drive mechanisms, translating concentrated component supply into asymmetric pricing power for disposable autoinjector subassemblies. Swiss and German specialty suppliers command premium positioning through ISO 11608-1 certification moats, while downstream device assemblers absorb cost volatility through long-term offtake commitments.
Pricing Analysis
Current-generation electromechanical autoinjectors command substantial premiums over spring-driven mechanical pens and legacy syringe formats, while next-generation wearable patch pumps with integrated connectivity modules occupy emerging premium tiers. Three-tier pricing structure across premium, standard, and economy levels separates connected device platforms with Bluetooth-enabled adherence monitoring from basic disposable formats and commodity syringe supplies. Pricing pressure stems from specialty pharmacy channel consolidation in the United States, where formulary managers extract volume discounts for insulin pen-needle contracts. Healthcare provider procurement committees demonstrate highest price sensitivity for routine diabetes supplies, while biologic license holders show lowest sensitivity when device-drug compatibility locks in platform selection.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Swiss and German component manufacturers enable working capital flexibility for mid-tier device assemblers competing against integrated multinationals. Geographic supply concentration centers on Switzerland, Germany, and the United States for spring steel drive mechanisms, precision-molded needle hubs, and electromechanical assembly. Raw material dependencies include medical-grade stainless steel, engineering polymers, and lithium-ion cell formats for connected platforms. Single-source vulnerability for Swiss spring steel suppliers creates structural risk exposure. Distribution runs through specialty pharmacy networks and hospital procurement committees in major chronic disease markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The self-injections market represents a high-growth disruption as EU MDR Article 117 mandates standalone device-specific clinical evidence for combination products, forcing pharmaceutical license holders to internalize delivery platform development. This regulatory inflection compresses timelines for third-party device specialists while rewarding integrated device-drug programs.
For Market Incumbents: Build regulatory compliance moats through notified body relationship investment and captive ISO 11608-1 metrology infrastructure. Pharmaceutical license holders should acquire or deepen partnerships with autoinjector platform developers to secure biologic compatibility lock-in against emerging electromechanical substitutes. Capacity addition in Baden-Württemberg precision molding clusters defends component supply security against Swiss single-source concentration. For New Entrants and Emerging Players: Wearable patch pump convergence in hormone therapy applications represents the most penetrable entry point, as fertility protocols and endocrine replacement lack incumbent platform saturation. Brazil ANVISA accelerated review pathways for pre-cleared FDA or EMA combination products offer geographic white-space with reduced regulatory friction. Go-to-market execution should target specialty pharmacy distribution networks absorbing nurse educator functions for home therapy onboarding. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform developers with proprietary autoinjector ecosystems and established pharmaceutical partnerships over commodity disposable component manufacturers. Long-term viability across the analysis window hinges on software competency integration alongside mechanical engineering capabilities. Acquisition target archetypes include electromechanical autoinjector specialists with Bluetooth-enabled dose tracking and European notified body relationships. The signal to watch is FDA 510(k) clearance velocity for novel connected formats as predicate device comparisons extend commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU MDR Article 117 compliance accelerates device-drug combination product approvals for European pharmaceutical portfolios. |
| Hospital System Partnership | Rheumatology and gastroenterology practice standardization locks in electromechanical autoinjector installed bases for biologic initiation. |
| Software Companion Development | Bluetooth-enabled dose tracking and adherence monitoring creates recurring revenue streams beyond hardware replacement cycles. |
| Reimbursement Strategy Execution | Specialty pharmacy network integration captures nurse educator functions and secures formulary positioning for connected platforms. |
| FDA Submission Advancement | Human factors validation studies for novel delivery formats compress eighteen-to-thirty-six month commercialization timeline risks. |
Methodological Framework
Cross-validation between primary interviews with industry stakeholders and secondary regulatory filings anchors the qualitative findings for this study. Conversations with regulatory affairs leads at combination product developers, biomedical engineers at notified bodies, GPO contracts managers at United States specialty pharmacy networks, and formulary directors at hospital systems informed device-drug integration dynamics. Secondary validation drew from FDA 510(k) clearance databases, EU MDR technical documentation guidance, ISO 11608-1 certification records, and pharmaceutical pipeline disclosures. Bottom-up demand modeling across patient cohorts and top-down supply capacity assessment triangulate market sizing.
Calibration against historical approval timelines and installed base expansion rates validates projection assumptions across the analysis window. Segmentation dimensions modeled include product type, end user archetype, therapeutic application, delivery method, and regional regulatory cluster. CAGRs derive from patient population growth, biologic pipeline maturation, and replacement cycle compression for legacy formats. Forecast inputs incorporate diabetes prevalence trajectories, EU MDR implementation pace, and continuous glucose monitor interoperability requirements.
Macroeconomic conditions sit as an overlay; deviation in reimbursement policy, specialty pharmacy channel consolidation, or spring steel supply disruption would shift the trajectory. Forecasts reflect documented assumptions about regulatory harmonization and biologic formulation advancement. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Digital X-Ray Devices Market
Medical Devices
Ablation Devices Market
Medical Devices
Testicular Implants (Prosthesis) Market
Medical Devices
Australia Clear Aligner Market
Medical Devices
US Surgical Microscopes Market
Medical Devices
Medical Device Technologies Market
Medical Devices
Next Generation Implants (NGI) Market
Medical Devices
India Minimally Invasive Surgery Devices Market
Medical Devices
C-Arms Devices Market
Medical Devices
Absorbable Antibacterial Envelope Market
Medical Devices
Global Wearable Injectors Market
Medical Devices
Foot and Ankle Allograft Market
Medical Devices
Disposable Lancets Market
Medical Devices
Ultrasound Transducers Market
Medical Devices
Pressure-Volume Loop Systems Market
Medical Devices
Urinary Collection Device Market