
 Cerebral Oximetry Monitoring Market | 2026-2036
Cerebral Oximetry Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Cerebral Oximetry Monitoring Market Analysis
Near-infrared spectroscopy integration with multi-parameter patient monitoring platforms is narrowing the gap between standalone cerebral oximetry and comprehensive perioperative brain monitoring. Masimo leverages its signal processing algorithms to sustain premium positioning across hospital networks. Edwards Lifesciences Corporation anchors its portfolio in cardiac surgery workflows where cerebral desaturation events carry acute clinical stakes. Nonin Medical competes through portable device specialization that extends monitoring into ambulatory and transport settings.
Cerebral oximetry monitoring employs near-infrared light wavelengths between 700 and 1000 nanometers to measure regional oxygen saturation in cerebral tissue, typically reporting absolute values or trended baselines with sampling rates exceeding one hertz for real-time surgical guidance. The technology serves primarily to detect and alert clinicians to cerebral hypoxia during procedures where general anesthesia, cardiopulmonary bypass, or patient positioning compromises cerebral perfusion. Stationary monitors occupy the dominant revenue position in high-volume surgical centers where capital equipment depreciation aligns with utilization economics, while wearable devices represent the fastest-expanding category as manufacturers miniaturize optode arrays and wireless telemetry for postoperative surveillance. Near-infrared spectroscopy leads technology deployment due to its established optical pathlength correction methods and broad clinician familiarity, though electromagnetic sensors are gaining traction in research configurations that demand deeper tissue penetration.
FDA 510(k) clearance requirements and ISO 80601-2-56 electrical safety standards govern device commercialization in the United States, while the EU Medical Device Regulation imposes strengthened clinical evidence obligations for Class IIa and IIb monitoring equipment across European markets. These frameworks elevate barriers for new entrants without established quality management systems or predicate device portfolios. Stakeholders must monitor evolving reimbursement codes for perioperative brain monitoring as payors scrutinize outcome differentiation against standard pulse oximetry alone.
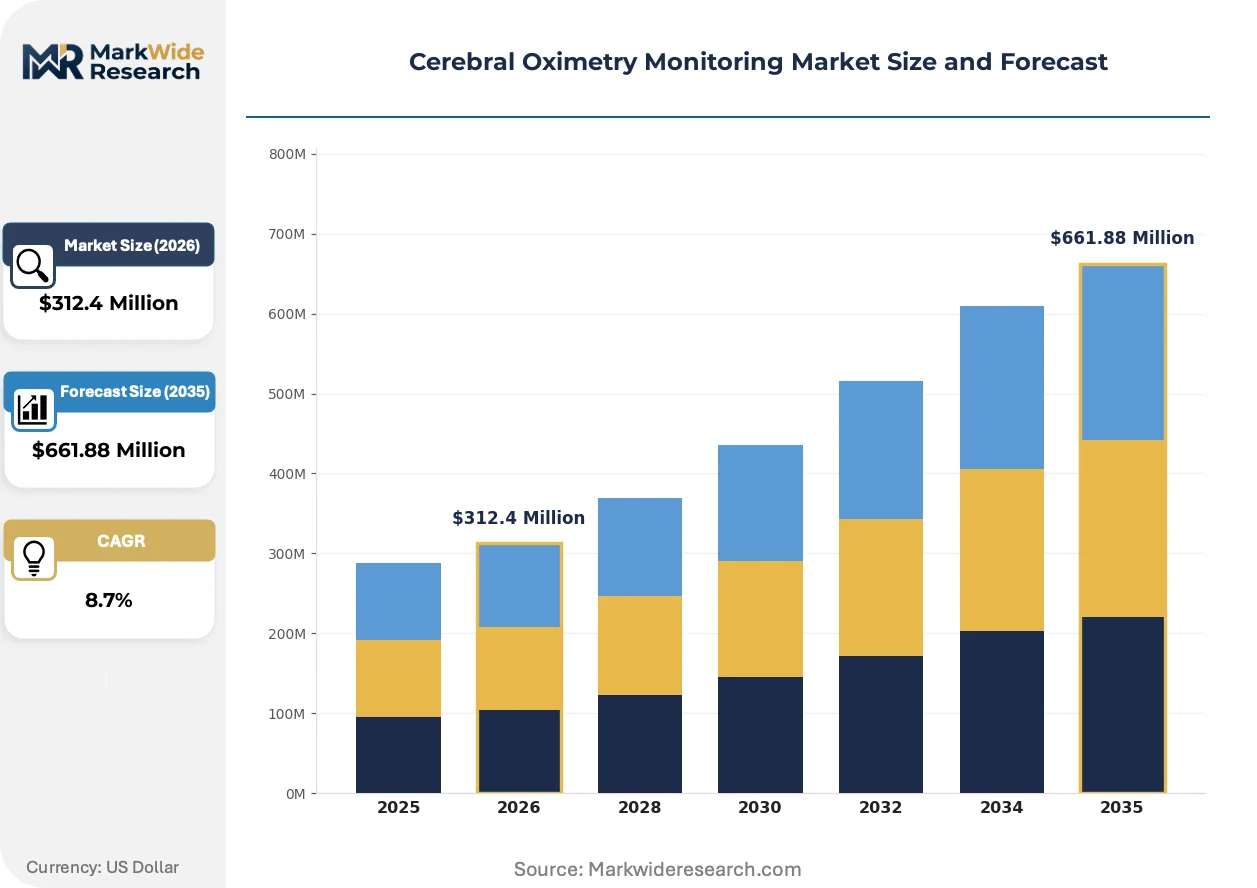
Market Dynamics
Near-infrared spectroscopy miniaturization is compressing hardware footprints while expanding deployment settings from operating rooms into post-anesthesia care units and transport corridors, fundamentally altering capital allocation patterns among hospital procurement committees.
Growth Catalysts
- ISO 80601-2-56 electrical safety standards:Harmonized international benchmarks reduce regulatory friction for multi-market device launches, accelerating clearance timelines for manufacturers with established quality systems.
- Cardiac surgery workflow integration:Cardiopulmonary bypass protocols increasingly mandate cerebral oxygen surveillance as standard-of-care, embedding monitors into perfusionist checklists across tertiary surgical centers.
- Japan's surgical aging demographic:Patients over 65 now constitute the majority of complex cardiac and neurosurgical procedures, elevating hypoxia risk profiles and monitoring intensity requirements.
Market Restraints
- Optode array manufacturing concentration:Precision photodetector fabrication clusters in specialized German and Japanese component suppliers, creating single-source vulnerability for device assemblers.
- Pulse oximetry substitution threat:Low-cost finger-probe alternatives capture budget-constrained settings despite inferior cerebral specificity, pressuring premium positioning.
- EU MDR clinical evidence burdens:Strengthened post-market surveillance obligations for Class IIb monitoring equipment extend recertification cycles and inflate regulatory compliance headcount.
Strategic Opportunities
- Postoperative surveillance expansion:Wearable optode arrays with wireless telemetry enable continuous monitoring in step-down units, addressing the 48-hour window when delayed hypoxic events frequently manifest.
- India's tertiary hospital buildout:Greenfield medical cities in Hyderabad and Chennai seek differentiated technology suites to attract medical tourism, creating first-mover positioning for cerebral oximetry vendors.
- Artificial intelligence signal processing convergence:Machine learning artifact rejection algorithms reduce false-positive alerts, improving clinician trust and device utilization rates in high-stakes surgical environments.
Industry Challenges
- Biomedical optics specialization scarcity:PhD-level expertise in near-infrared tissue spectroscopy remains concentrated in academic medical centers, constraining R&D expansion for commercial device developers.
- Legacy patient monitor integration complexity:Proprietary data protocols from entrenched multi-parameter platform vendors obstruct seamless cerebral oximetry module incorporation, forcing costly interface engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cerebral Oximetry Monitoring Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Monitors, Stationary Monitors, Multi-parameter Monitors, Wearable Devices Technology: Infrared Spectroscopy, Near-Infrared Spectroscopy, Optical Sensors, Electromagnetic Sensors End User: Hospitals, Clinics, Academic Research Institutions, Home Care Application: Neurosurgery, Cardiovascular Surgery, Anesthesia Monitoring, Critical Care |
| Companies Covered | Masimo, Medtronic, Edwards Lifesciences Corporation, Nonin Medical, ISS, Hamamatsu Photonics K.K., GE Healthcare, Philips Healthcare, Mindray Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cerebral Oximetry Monitoring Market Emerging Trajectories
Device architecture is bifurcating between high-fidelity operating room installations and disposable, single-use sensors for ambulatory monitoring, with software-defined signal processing bridging performance gaps between tiers.
Miniaturized silicon photomultiplier arrays are replacing traditional photodiode detectors in next-generation optode designs, enabling deeper tissue penetration at reduced source power. Cardiac surgery departments at university-affiliated hospitals in Germany and the United States are piloting these configurations for low-perfusion states. The shift is rendering obsolete bulkier benchtop monitors that required dedicated electrical isolation and cooling subsystems.
EU Medical Device Regulation Article 10 clinical evaluation requirements are mandating prospective outcome studies for Class IIb cerebral monitors, not merely predicate equivalence demonstrations. Manufacturers must now sponsor randomized trials demonstrating hypoxia detection sensitivity against neurological outcome markers. The cardiac surgery segment bears the heaviest compliance burden, with several vendors delaying European launches pending data maturation.
Hospital procurement committees are unbundling monitoring hardware from disposable sensor contracts, reversing the historical razor-and-blade model that locked institutions into single-vendor ecosystems. Group purchasing organizations in the United States are negotiating sensor-only supply agreements with secondary manufacturers, pressuring original equipment suppliers to open proprietary connector specifications. This disintermediation is most visible in integrated delivery networks across Texas and Florida, where standardization mandates span dozens of surgical suites.
Cerebral Oximetry Monitoring Market Segmentation
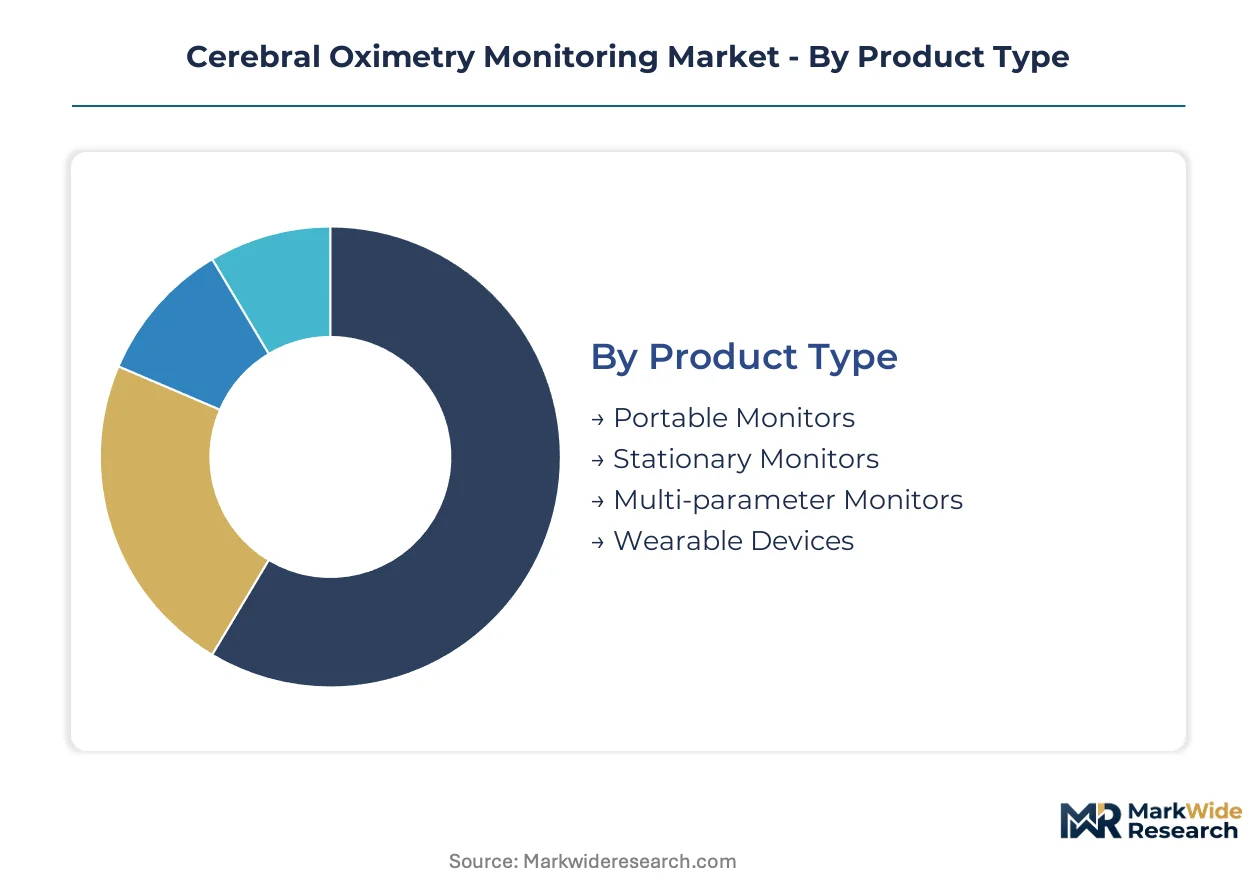
Cerebral oximetry monitoring segments diverge sharply in service intensity, with stationary installations demanding multi-year calibration contracts while portable units require rapid sensor replacement logistics. Hospital procurement committees weight these lifecycle costs against capital depreciation schedules when allocating budgets across surgical departments.
Product Type:
After-sales service intensity varies dramatically across product tiers, with stationary monitors requiring embedded biomedical engineering support and wearable devices demanding cloud-based telemetry maintenance.
- Stationary Monitors:Fixed-installation systems integrate isolated electrical subsystems and liquid cooling loops for high-fidelity photodetector arrays. Tertiary cardiac surgery centers in the United States and Germany anchor demand, driven by perfusionist protocol mandates that embed cerebral oxygen surveillance into cardiopulmonary bypass checklists.
- Portable Monitors:Battery-powered units with detachable optode arrays enable intra-hospital transport from operating rooms to post-anesthesia care units. Demand concentrates in Japanese surgical networks where aging patient demographics elevate hypoxia risk profiles across dispersed facility footprints.
- Multi-parameter Monitors:Modular platforms that integrate cerebral oximetry alongside pulse oximetry and hemodynamic tracking.
- Wearable Devices:Miniaturized wireless sensors for ambulatory and step-down unit surveillance.
By volume, stationary monitors lead. By growth pace, wearable devices are ahead.
Technology:
Technology selection determines optical pathlength correction complexity and regulatory clearance pathways, with established methods commanding premium pricing against experimental configurations.
- Near-Infrared Spectroscopy:Dominant wavelength-based approach employing 700-1000 nanometer light with validated Beer-Lambert law adaptations for tissue scattering compensation. United States and German hospital networks drive replacement demand as ISO 80601-2-56 electrical safety standards tighten validation requirements for predicate device submissions.
- Infrared Spectroscopy:Broader spectral range configurations for research applications requiring deeper tissue penetration. Academic medical centers in Japan pilot these systems for low-perfusion state investigation, constrained by FDA and PMDA evidentiary burdens for clinical translation.
- Optical Sensors:Silicon photomultiplier arrays replacing traditional photodiodes in next-generation optode designs.
- Electromagnetic Sensors:Experimental configurations for subcortical monitoring in specialized research settings.
Near-infrared spectroscopy commands the installed base. Optical sensors are climbing the fastest.
End User:
End-user category shapes reimbursement capture and capital cycle timing, with hospitals amortizing equipment over five-to-seven-year depreciation schedules against clinic rental models.
- Hospitals:Integrated delivery networks across Texas and Florida unbundle hardware from disposable sensor contracts, reversing historical razor-and-blade vendor lock-in. Group purchasing organizations negotiate sensor-only supply agreements, pressuring original equipment manufacturers to open proprietary connector specifications.
- Academic Research Institutions:University-affiliated hospitals in Germany and the United States pilot silicon photomultiplier configurations for cardiac surgery departments. EU MDR Article 10 clinical evaluation requirements mandate prospective outcome studies, delaying several vendor European launches pending data maturation.
- Clinics:Outpatient surgical centers with limited perfusionist staffing.
- Home Care:Emerging ambulatory monitoring for high-risk postoperative patients.
Hospitals dominate capital expenditure. Academic research institutions are expanding most quickly.
Application:
Application segmentation reflects procedural risk gradients and anesthesia complexity, with cardiac and neurosurgical workflows commanding distinct monitoring intensities.
- Cardiovascular Surgery:Cardiopulmonary bypass protocols increasingly mandate cerebral oxygen surveillance as standard-of-care. Edwards Lifesciences anchors portfolio positioning here, embedding monitors into perfusionist workflows where desaturation events carry acute neurological stakes.
- Neurosurgery:Tertiary hospital suites in the United States and Japan expand non-invasive brain oxygen monitoring adoption. Masimo leverages signal processing algorithms to sustain premium positioning across these networks.
- Anesthesia Monitoring:General anesthesia cases where patient positioning compromises cerebral perfusion.
- Critical Care:Step-down and intensive care unit surveillance for delayed hypoxic event detection.
Cardiovascular surgery leads by revenue concentration. Neurosurgery is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in tertiary cardiac surgery centers concentrate capital expenditure across the United States, Germany, and Japan, where aging surgical populations and reimbursement clarity sustain device deployment.
United States
Integrated delivery networks in Texas and Florida unbundle monitoring hardware from disposable sensor contracts, reversing historical vendor lock-in. FDA 510(k) clearance pathways govern commercialization timelines. The Greater Boston medical cluster pilots silicon photomultiplier configurations for low-perfusion state investigation.
Germany
University-affiliated hospitals anchor European demand for high-fidelity operating room installations. EU Medical Device Regulation Article 10 mandates prospective outcome studies for Class IIb cerebral monitors, extending recertification cycles. Precision photodetector fabrication concentrates in specialized Bavarian component suppliers.
Japan
Patients over 65 constitute the majority of complex cardiac and neurosurgical procedures, elevating hypoxia risk profiles. PMDA evidentiary burdens constrain clinical translation of experimental infrared spectroscopy configurations. Tokyo and Osaka surgical networks drive portable monitor demand across dispersed facility footprints.
India
Greenfield medical cities in Hyderabad and Chennai seek differentiated technology suites to attract medical tourism. CDSCO device registration requirements shape market entry sequencing. Tertiary hospital buildouts in Maharashtra and Karnataka create first-mover positioning opportunities for cerebral oximetry vendors.
United Kingdom
NHS procurement frameworks emphasize outcome-based contracting for perioperative monitoring equipment. MHRA post-market surveillance aligns with strengthened EU MDR obligations for Class IIa and IIb devices. The Oxford-Cambridge-London research triangle hosts pilot programs for artificial intelligence signal processing convergence.
Cerebral Oximetry Monitoring Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. Consolidation pressure intensifies as group purchasing organizations negotiate sensor-only supply agreements, fragmenting historical razor-and-blade ecosystems. Three archetypes dominate: diversified medical technology conglomerates with multi-parameter platform integration capabilities, cardiac surgery workflow specialists with perfusionist protocol anchoring, and portable device manufacturers extending monitoring into transport and ambulatory settings. Dominant competitive moves include strategic partnerships for proprietary data protocol access and portfolio diversification through disposable sensor miniaturization.
Among diversified technology conglomerates, GE Healthcare and Philips Healthcare occupy positions spanning hospital capital equipment procurement channels. Masimo and Edwards Lifesciences Corporation exemplify contrasting specialization strategies—signal processing algorithm development versus cardiac surgery workflow integration. Nonin Medical represents the portable device archetype, with geography-agnostic naming suggesting ambulatory market positioning. Medtronic and Mindray Medical sit within the scale-driven tier, leveraging established quality management systems for multi-market regulatory clearance. Hamamatsu Photonics K.K. anchors Japanese-origin photodetector supply relationships, while ISS occupies research-oriented market segments.
| Leading Market Players |
|---|
| Masimo |
| Medtronic |
| Edwards Lifesciences Corporation |
| Nonin Medical |
| ISS |
| Hamamatsu Photonics K.K. |
| GE Healthcare |
| Philips Healthcare |
| Mindray Medical |
| Others |
Supply Flow & Price Mechanics
Precision photodetector fabrication clusters in specialized Bavarian and Japanese component suppliers concentrate upstream margin capture, while downstream pricing power fragments across hospital procurement committees unbundling hardware from sensor contracts. This bifurcation compresses assembler margins even as ISO 80601-2-56 validation costs escalate predicate device submission expenses.
Pricing Analysis
Cost-plus contracts with semiconductor indexation dominate optode array procurement, insulating German and Japanese suppliers from raw material volatility while transferring price risk to device assemblers. Three-tier pricing structure across premium, standard, and economy levels differentiates by FDA 510(k) clearance tier and after-sales calibration bundling. Pricing pressure stems from group purchasing organizations negotiating sensor-only supply agreements, eroding razor-and-blade lock-in. Budget-constrained outpatient surgical centers exhibit highest price sensitivity, while tertiary cardiac surgery centers prioritize hypoxia detection sensitivity over unit economics.
Supply Chain Analysis
Tariff exposure between German component suppliers and United States device assemblers dominates supply chain risk calculus, compounded by single-source vulnerability in silicon photomultiplier arrays. Manufacturing concentration rests on Germany, Japan, and the United States for precision photodetectors, with China and South Korea supplying downstream PCB assembly and battery subsystems. Raw material dependencies include indium gallium arsenide photodiodes, medical-grade silicone for optode housings, and lithium-ion cells for portable units. Distribution runs through group purchasing organizations and integrated delivery networks, bypassing traditional distributor markups in Texas and Florida hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where FDA 510(k) predicate device portfolios and ISO 80601-2-56 quality system certifications create years-long barriers against unqualified entrants.
For Market Incumbents: Entrench position through backward integration into silicon photomultiplier design and captive supply of precision photodetectors, neutralizing single-source vulnerability from Bavarian and Japanese component suppliers. Deepen hospital system partnerships by opening proprietary data protocols to multi-parameter platform vendors, preempting interface engineering costs that obstruct competitor module incorporation. Priority lever sits with reimbursement strategy investment, securing favorable perioperative brain monitoring codes before payor scrutiny intensifies against standard pulse oximetry substitution. For New Entrants and Emerging Players: Build out portable device specialization targeting Japanese surgical networks with dispersed facility footprints and aging patient demographics, where transport corridor monitoring remains underserved by stationary incumbents. Capture white-space in Indian greenfield medical cities across Hyderabad and Chennai, leveraging CDSCO registration sequencing to establish first-mover positioning before tertiary hospital buildouts in Maharashtra and Karnataka mature. Go-to-market angle emphasizes disposable single-use sensor miniaturization for ambulatory postoperative surveillance, bypassing capital equipment procurement committee gatekeeping. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across wearable device sub-segments as silicon photomultiplier arrays displace bulkier benchtop configurations, improving return thresholds for software-defined signal processing plays. Long-term viability favors diversified medical technology conglomerates with established quality management systems and multi-parameter platform integration capabilities. Acquisition target archetype: portable device manufacturers with wireless telemetry IP and ambulatory monitoring regulatory clearances. Signal to watch: PMDA evidentiary burden relaxation for experimental infrared spectroscopy configurations, which would unlock clinical translation and expand addressable monitoring depth.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Premarket submission predicates on established signal processing algorithms accelerate commercialization timelines for next-generation optode designs. |
| CE Marking Pathway | EU MDR Article 10 prospective outcome study mandates elevate clinical evidence burdens, favoring sponsors with randomized trial infrastructure. |
| Hospital System Partnership | Integrated delivery network standardization mandates across Texas and Florida surgical suites lock in multi-year disposable sensor commitments. |
| Software Companion Development | Machine learning artifact rejection algorithms reduce false-positive alerts, improving clinician trust and device utilization in cardiac surgery workflows. |
| Reimbursement Strategy | Favorable perioperative brain monitoring code capture insulates premium positioning against pulse oximetry substitution in budget-constrained settings. |
Methodological Framework
Initial hypotheses were tested against primary input from perfusionists, biomedical engineers, hospital purchasing committee members, and GPO contracts managers, and refined through secondary validation against FDA 510(k) filings, ISO 80601-2-56 standard documentation, hospital procurement databases, and CMS Medicare reimbursement codes. Bottom-up demand modeling across product type, technology, end user, and application segments triangulated with top-down market sizing from capital equipment depreciation schedules and disposable sensor replacement rates.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning stationary versus portable device architecture, near-infrared versus emerging optical sensor technology, hospital versus academic research institution end use, and cardiovascular versus neurosurgical application. CAGRs derived from surgical procedure volume projections, aging demographic hypoxia risk profiles, and reimbursement clarity evolution. Industry-specific forecast inputs included perfusionist protocol mandate adoption curves and EU MDR recertification cycle extensions.
Practitioners should monitor FDA premarket clearance timeline shifts, ISO 80601-2-56 revision schedules, and payer code bundling decisions for early signals of forecast deviation. Macroeconomic contraction affecting hospital capital expenditure, regulatory harmonization failure between FDA and EU MDR frameworks, or breakthrough pulse oximetry algorithm advances would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
North America Wearable Ambulatory Monitoring Devices Market
Patient Monitoring
Respiratory Monitoring Devices Market
Patient Monitoring
Global Ambulatory Blood Pressure Monitoring (ABPM) Devices Market
Patient Monitoring
Fetal Heart Rate Monitoring Devices Market
Patient Monitoring
Wearable Heart Monitoring Devices Market
Patient Monitoring
Germany Patient Monitoring Market
Patient Monitoring
Cardiac Rhythm Remote Monitoring Devices Market
Patient Monitoring
South America Body Temperature Monitoring Market
Patient Monitoring
Real-Time Location System (RTLS) in Healthcare Market
Patient Monitoring
Middle East and Africa Fetal and Neonatal Monitoring Market
Patient Monitoring
Real Time Health Monitoring Devices Market
Patient Monitoring
UAE Patient Monitoring Equipment Market
Patient Monitoring
Patient Monitoring Systems Market
Patient Monitoring
Saudi Arabia Patient Monitoring Market
Patient Monitoring
Respiratory Gas Monitors Market
Patient Monitoring
Middle East and Africa Cardiac Monitoring Market